
 United Kingdom Continuous Glucose Monitoring Market | 2026-2036
United Kingdom Continuous Glucose Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Continuous Glucose Monitoring Market Insights
Market Context
Ireland's sensor component manufacturing base is rewriting supply dynamics for UK-bound glucose monitoring hardware. Abbott Diabetes Care leverages its vertically integrated sensor production to sustain pricing power across NHS procurement frameworks. Dexcom Inc. competes through algorithm-intensive real-time platforms that dominate hospital-based continuous monitoring protocols. Medtronic PLC anchors its position via deep clinical trial partnerships with English NHS trusts.
Technical Definition and Segment Structure
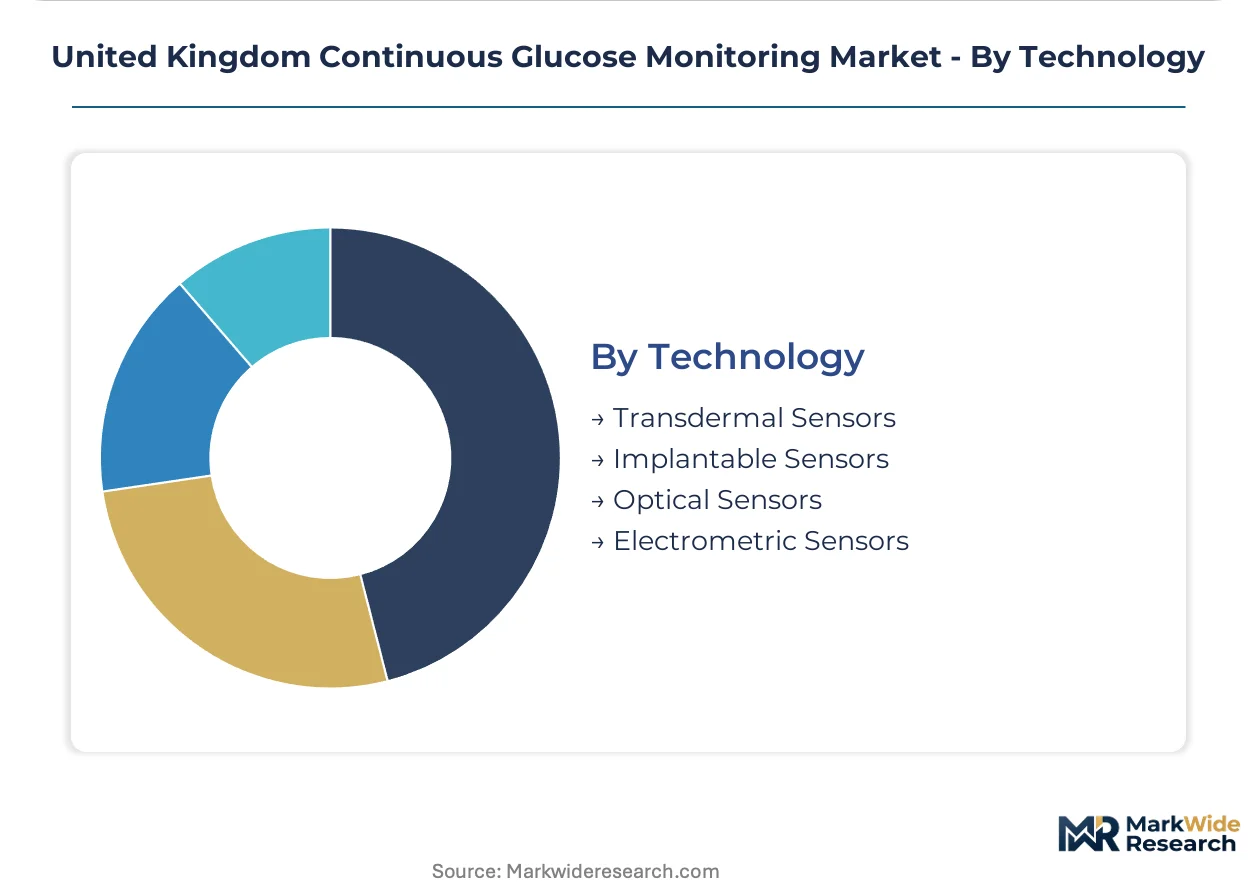
Continuous glucose monitoring comprises wearable electrochemical sensor systems that measure interstitial glucose concentrations at intervals of one to fifteen minutes, transmitting data to receivers or smartphones for real-time glycaemic management. Flash glucose monitoring occupies the largest installed base among product types due to NHS cost-effectiveness thresholds, while smartphone-compatible devices represent the fastest structural expansion as patient self-management preferences shift. Transdermal sensors lead technology adoption for non-invasive glucose tracking, whereas implantable sensors capture concentrated margin pools from long-duration monitoring protocols in Type 1 diabetes management.
Regulatory Framework
The Medicines and Healthcare products Regulatory Agency enforces UKCA marking requirements that shape device approval timelines and post-market surveillance obligations for all glucose monitoring manufacturers. NHS England's Technology Appraisal Guidance and National Institute for Health and Care Excellence recommendations directly determine reimbursement eligibility and channel access across hospitals and diabetes clinics. Stakeholders must monitor evolving MHRA recognition agreements with European notified bodies, as divergence from EU MDR harmonisation threatens market entry pathways for emerging sensor technologies.
Market Dynamics
NHS England's reimbursement expansion for Type 1 diabetes patients is compressing adoption timelines across hospital trusts and primary care networks. The policy shift toward ambulatory glucose profiling is forcing device manufacturers to recalibrate supply chains for just-in-time sensor replenishment.
Growth Catalysts
- NICE Technology Appraisal Guidance:Updated recommendations for real-time continuous glucose monitoring in Type 1 diabetes expand eligibility criteria, pulling new patient cohorts into reimbursed coverage.
- Smartphone-integrated platforms:Bluetooth-enabled data transmission eliminates dedicated receiver hardware, reducing total cost of ownership for NHS procurement frameworks.
- Greater London specialist clusters:Concentrated endocrinology services in the South East generate referral density that accelerates device penetration among newly diagnosed patients.
Market Restraints
- Sensor substrate cost volatility:Platinum and conductive polymer input prices fluctuate with electronics supply chain disruptions, squeezing gross margins on disposable components.
- Irish manufacturing concentration:Single-source sensor fabrication facilities in County Galway create geographic vulnerability for UK-bound hardware shipments.
- MHRA-MDR divergence friction:Post-Brexit regulatory misalignment with EU notified bodies extends approval timelines for next-generation transdermal platforms.
Strategic Opportunities
- Wales and Northern England coverage gaps:Underpenetrated regions outside the South East specialist corridor offer whitespace for community diabetes service expansion.
- Type 2 diabetes ambulatory monitoring:Emerging application in insulin-treated Type 2 populations awaits NICE cost-effectiveness threshold recalibration.
- Integrated insulin pump convergence:Closed-loop algorithm development creates bundling potential with automated delivery systems in tertiary care centers.
Industry Challenges
- Biofouling mitigation expertise:Sensor membrane engineering talent scarcity constrains R&D velocity for extended-wear platforms.
- UKCA certification backlog:Post-market surveillance documentation requirements delay product launches by 8-14 months relative to pre-2021 timelines.
- Legacy EHR integration complexity:Hospital trust electronic health record fragmentation forces bespoke API development for each NHS IT system deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Continuous Glucose Monitoring Market |
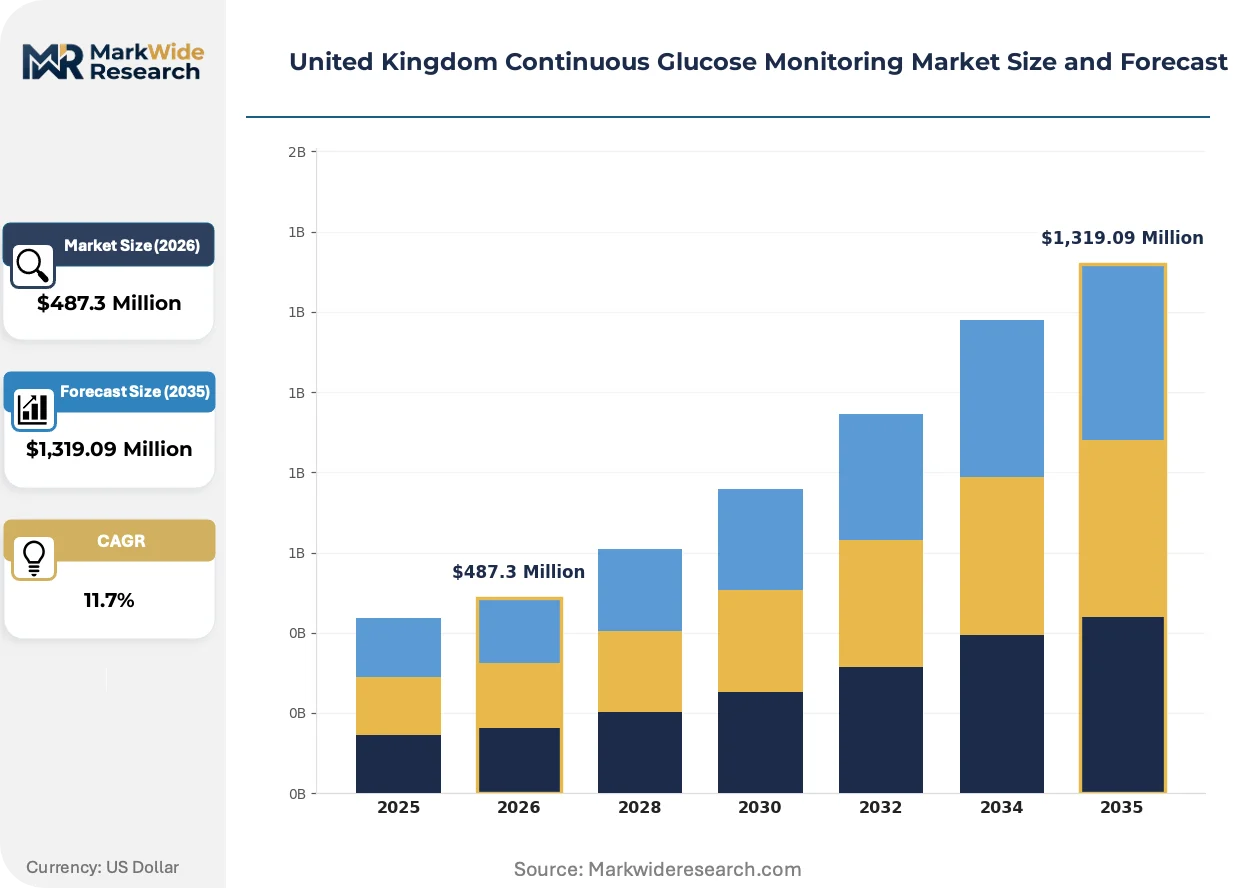
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flash Glucose Monitoring, Real-Time Continuous Monitoring, Smartphone-Compatible Devices, Wearable Sensors Application: Type 1 Diabetes Management, Type 2 Diabetes Management, Clinical Research, Home Monitoring End User: Hospitals, Diabetes Clinics, Individual Consumers, Healthcare Providers Technology: Transdermal Sensors, Implantable Sensors, Optical Sensors, Electrometric Sensors |
| Companies Covered | Abbott Diabetes Care, Dexcom Inc., Medtronic PLC, Ascensia Diabetes Care, Senseonics, Roche Diagnostics, GlySens, GlucoRx, Nemaura Medical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Continuous Glucose Monitoring Market Trends and Innovations
Algorithm-augmented glucose prediction is displacing threshold-based alerting across NHS diabetes pathways. The convergence of machine learning with electrochemical sensing is compressing hypoglycaemia detection windows while expanding patient self-management autonomy.
Non-invasive optical sensing is hybridizing with minimally invasive electrochemical platforms in hybrid glucose monitoring architectures. Research consortia at Oxford and Cambridge are piloting near-infrared spectroscopy combined with interstitial validation for reduced calibration burden. NHS Innovation Accelerator programmes are fast-tracking these dual-modality devices into real-world evidence collection protocols. The structural consequence is a compression of the invasive-non-invasive performance gap, forcing incumbents to defend sensor accuracy claims through head-to-head clinical trials.
NHS England's MedTech Funding Mandate is mandating real-world evidence generation for all new glucose monitoring procurements above specified volume thresholds. The policy requires manufacturers to submit patient-reported outcome measures alongside traditional glycaemic control endpoints. Flash glucose monitoring systems face heightened evidentiary requirements for Type 2 diabetes indications. Hospital trusts are responding by consolidating procurement through regional collaborative hubs that aggregate post-market surveillance data.
Patient-generated health data monetisation is reshaping commercial relationships between device manufacturers and data analytics platforms. NHS Digital's secure data environments are enabling secondary use of aggregated glucose trajectories for population health modelling. Diabetes clinics in the South East are piloting subscription-based remote monitoring services that unbundle hardware from clinical interpretation. This shift is most visible in Greater London integrated care systems where capitated budgets incentivise preventative glycaemic management.
United Kingdom Continuous Glucose Monitoring Market Segmentation
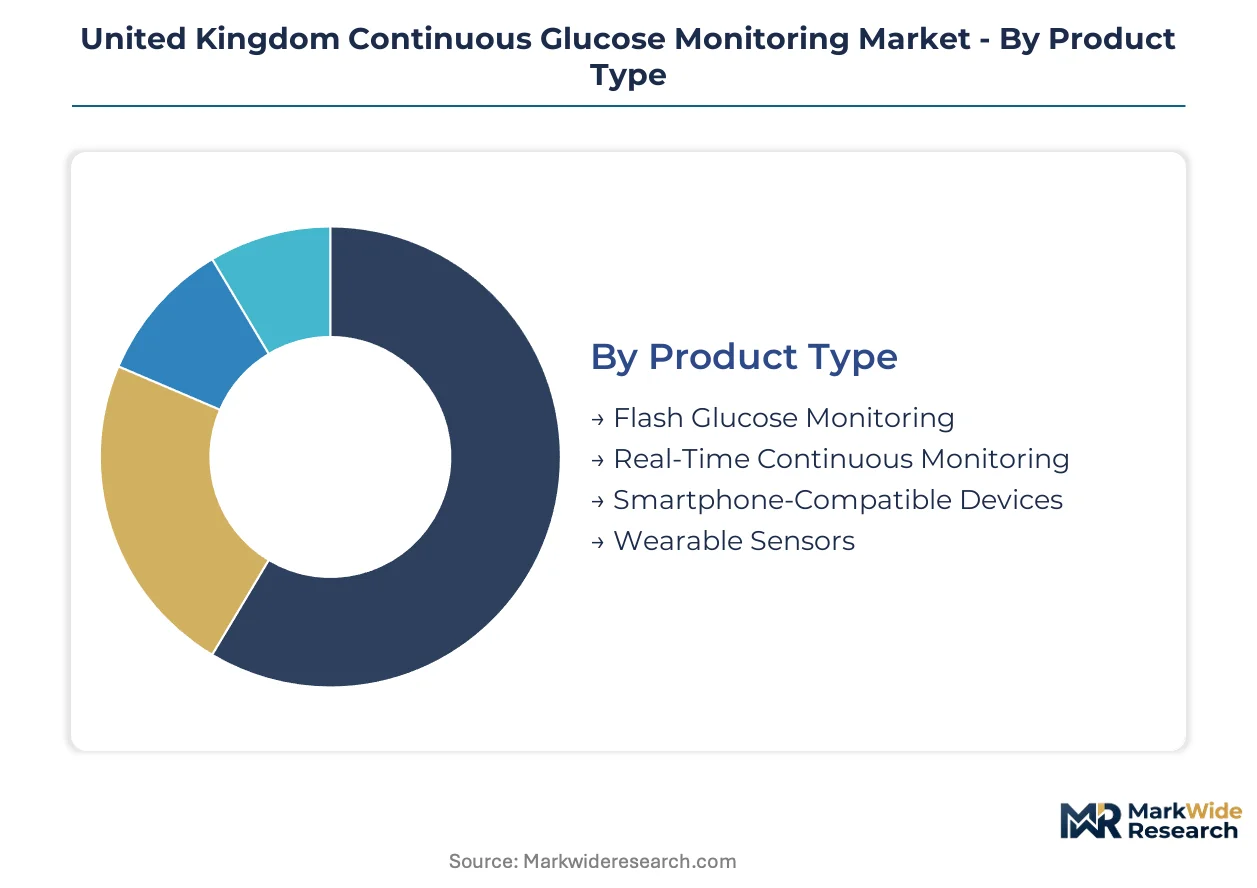
Segmentation in UK continuous glucose monitoring reveals how reimbursement pathways, clinical workflows, and patient self-management preferences split demand across hardware configurations. NHS procurement frameworks amplify certain technology combinations while constraining others, creating distinct competitive arenas within the same national market.
Product Type:
After-sales service intensity varies sharply across product architectures, with sensor replacement logistics and software update obligations driving manufacturer operational commitments.
- Flash Glucose Monitoring:Factory-calibrated electrochemical sensors eliminate fingerstick calibration, reducing clinical support burden. NHS hospital trusts in Greater London deploy these systems for ambulatory glucose profiling in Type 1 cohorts, constrained by cost-effectiveness thresholds that favor disposable economics over capital-intensive hardware.
- Real-Time Continuous Monitoring:Algorithm-intensive platforms transmit glucose readings every 1-5 minutes to dedicated receivers or smartphones. Specialist endocrinology services in the South East cluster around these devices for hypoglycaemia prediction in insulin-treated patients, pulled by NICE Technology Appraisal Guidance reimbursement expansion.
- Smartphone-Compatible Devices:Bluetooth-enabled data transmission architectures reduce total cost of ownership by eliminating dedicated receiver hardware.
- Wearable Sensors:Skin-adhesive form factors prioritize patient discretion and extended wear duration in community diabetes settings.
Flash glucose monitoring holds the largest share; momentum sits with smartphone-compatible devices.
Application:
Volume concentration tracks reimbursement eligibility boundaries, with NICE cost-effectiveness determinations creating tiered access across patient populations.
- Type 1 Diabetes Management:Intensive insulin therapy protocols demand continuous glucose visibility for safe dosing decisions. NHS England's expanded coverage criteria are pulling newly diagnosed patients into reimbursed monitoring programs across hospital trusts and primary care networks.
- Type 2 Diabetes Management:Insulin-treated Type 2 populations represent emerging demand as ambulatory monitoring protocols extend beyond traditional Type 1 boundaries. Wales and Northern England integrated care systems pilot these applications where capitated budgets incentivise preventative glycaemic management.
- Clinical Research:Real-world evidence generation requirements under NHS England's MedTech Funding Mandate drive sensor deployment in academic medical centers.
- Home Monitoring:Patient-generated health data platforms enable remote clinical interpretation outside traditional clinic visits.
Type 1 diabetes management dominates volume; Type 2 applications are climbing the fastest.
End User:
Customer procurement sophistication determines pricing tolerance, with institutional buyers extracting volume discounts unavailable to individual purchasers.
- Hospitals:Tertiary care centers with closed-loop insulin pump programs require algorithm-integrated monitoring for automated delivery convergence. English NHS trusts aggregate procurement through regional collaborative hubs that standardize device selection and post-market surveillance data collection.
- Diabetes Clinics:Specialist endocrinology services in Greater London generate referral density that accelerates device penetration among newly diagnosed patients.
- Individual Consumers:Self-funded purchases outside NHS reimbursement create margin pools for premium feature sets.
- Healthcare Providers:Community nursing services and general practitioners deliver monitoring hardware through prescription pathways.
Hospitals command the largest procurement volumes; diabetes clinics show the steepest expansion trajectory.
Technology:
Margin structure correlates with manufacturing complexity and sensor longevity, with implantable platforms capturing concentrated value from extended-wear protocols.
- Transdermal Sensors:Minimally invasive electrochemical platforms penetrate the stratum corneum for interstitial glucose measurement. These devices lead NHS adoption for non-invasive glucose tracking, though biofouling mitigation challenges constrain R&D velocity for wear extensions beyond 14 days.
- Implantable Sensors:Subcutaneous sensor architectures enable 90-180 day monitoring durations with reduced calibration burden. Long-duration Type 1 diabetes management protocols in English NHS trusts concentrate demand here, justified by total cost-of-ownership calculations across extended replacement cycles.
- Optical Sensors:Near-infrared spectroscopy approaches hybridize with electrochemical validation in research consortia at Oxford and Cambridge.
- Electrometric Sensors:Impedance-based measurement techniques offer alternative transduction mechanisms for glucose quantification.
Transdermal sensors retain dominant installed base position; implantable platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the United Kingdom diverge sharply between specialist-intensive southern corridors and community-care-dependent northern regions, with reimbursement density rather than disease prevalence determining device penetration rates.
Greater London
Specialist endocrinology services cluster densely in London's tertiary hospital network, driving concentrated demand for algorithm-intensive real-time monitoring platforms. NHS England's Technology Appraisal Guidance implementation reaches highest fidelity here, with integrated care systems deploying capitated budgets for preventative glycaemic management. The South East specialist corridor accelerates referral velocity for newly diagnosed Type 1 patients.
Midlands
Community diabetes services in Birmingham and Leicester manage substantial Type 2 insulin-treated populations awaiting NICE cost-effectiveness threshold recalibration for continuous monitoring eligibility. The Medicines and Healthcare products Regulatory Agency's UKCA marking requirements shape procurement timelines for regional hospital trusts. Manufacturing supply chains for sensor components route through Irish fabrication facilities before reaching Midlands distribution hubs.
North England
Underpenetrated regions including Yorkshire and the North East present whitespace for ambulatory monitoring expansion as NHS England pushes coverage beyond traditional specialist corridors. Primary care networks here lack the referral density of southern counterparts, compressing device penetration rates. Manchester's emerging health innovation cluster pilots remote monitoring subscription models unbundling hardware from clinical interpretation.
Scotland
NHS Scotland operates distinct procurement frameworks from English structures, creating parallel reimbursement pathways for glucose monitoring devices. Edinburgh and Glasgow academic medical centers generate real-world evidence requirements under divergent health board mandates. Scottish integrated care systems experiment with closed-loop algorithm development in tertiary care settings.
Wales
Community nursing services in Cardiff and Swansea deliver monitoring hardware through prescription pathways with limited specialist endocrinology backup. Welsh health boards pilot capitated budget models for insulin-treated Type 2 populations, testing ambulatory monitoring protocols outside traditional Type 1 boundaries. Regulatory alignment with MHRA requirements proceeds through distinct Welsh Government health technology assessment processes.
United Kingdom Continuous Glucose Monitoring Market Competitive Landscape
Capability concentration sits with algorithm-intensive platform developers; scale advantage sits with vertically integrated sensor manufacturers. The market structures around three tiers: multinational device conglomerates with deep NHS clinical trial partnerships, mid-cap specialists in extended-wear sensor architectures, and emerging optical sensing challengers from academic spin-outs. Consolidation pressure runs through bundled procurement frameworks while differentiation shifts toward predictive algorithm performance and EHR integration depth.
Within the multinational tier, Abbott Diabetes Care, Dexcom Inc., and Medtronic PLC occupy anchor positions shaped by divergent strategic postures. Abbott's vertically integrated sensor production in Irish facilities exemplifies supply-side control for cost-positioning within NHS frameworks. Dexcom represents the algorithm-intensive real-time platform archetype dominating hospital-based protocols. Medtronic anchors the integrated insulin pump convergence vector through deep clinical trial partnerships with English NHS trusts.
| Leading Market Players |
|---|
| Abbott Diabetes Care |
| Dexcom Inc. |
| Medtronic PLC |
| Ascensia Diabetes Care |
| Senseonics |
| Roche Diagnostics |
| GlySens |
| GlucoRx |
| Nemaura Medical |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Irish sensor fabrication facilities is compressing supplier margins while amplifying pricing leverage for vertically integrated manufacturers serving NHS procurement frameworks. This utilization squeeze forces contract manufacturers to prioritize volume commitments from Abbott Diabetes Care and Dexcom Inc., reshaping cost structures across disposable electrochemical sensor platforms.
Pricing Analysis
Long-term offtake agreements dominate NHS procurement frameworks, with three-year bundled contracts for sensor replenishment locking in volume discounts unavailable to spot-market purchasers. Price differentiation separates algorithm-intensive real-time platforms from factory-calibrated flash systems, with the latter facing intensifying cost compression due to conductive polymer input volatility. Hospital trusts extract maximum concession through regional collaborative hubs, while individual consumers in self-funded channels show lowest price sensitivity. Margins are tightening in standard-tier disposable sensors as platinum electrode costs fluctuate with electronics supply chain disruptions.
Supply Chain Analysis
Contract manufacturing concentration sits with Irish sensor fabrication facilities in County Galway and specialized electrochemical foundries in Germany and the Netherlands. Raw material dependencies draw from South African platinum suppliers, German conductive polymer producers, and Taiwanese microelectronics packaging operations. Single-source vulnerability in Irish sensor substrate production creates geographic concentration risk for UK-bound hardware shipments. Distribution runs through regional NHS distribution hubs before reaching hospital trusts and diabetes clinics.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through NHS England's regional procurement hubs, with aggregated purchasing volume tilting negotiation leverage toward institutional purchasers and compressing vendor margin pools.
For Market Incumbents: Pre-empt algorithm commoditization by deepening predictive analytics capabilities and securing exclusive EHR integration partnerships with dominant hospital trust IT systems. Threats from optical sensing challengers at Oxford and Cambridge research consortia demand accelerated real-world evidence generation under NHS England's MedTech Funding Mandate. Priority lever: captive sensor membrane engineering talent acquisition to extend wear duration beyond 14-day thresholds. For New Entrants and Emerging Players: Community diabetes services in Wales and Northern England represent the most penetrable entry point for ambulatory monitoring expansion outside saturated South East specialist corridors. Type 2 insulin-treated populations awaiting NICE cost-effectiveness recalibration offer whitespace before reimbursement formalization. Go-to-market angle: subscription-based remote monitoring services unbundling hardware from clinical interpretation, piloted in Manchester's health innovation cluster. For Investors and Strategic Acquirers: Capital is best deployed toward algorithm-intensive platform developers with demonstrated NHS clinical trial partnerships and closed-loop insulin pump convergence roadmaps. Long-term viability hinges on predictive glucose accuracy differentiation as electrochemical sensing commoditizes. Acquisition target archetype: mid-cap specialists in extended-wear implantable sensor architectures. Signal to watch: MHRA recognition agreement negotiations with European notified bodies as regulatory divergence friction indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Algorithm Development | Automated insulin delivery convergence with Medtronic PLC's NHS trust partnerships creates bundling moats. |
| UKCA Certification Fast-Track | Accelerated MHRA approval timelines compress 8-14 month backlog for next-generation transdermal platforms. |
| Regional Collaborative Hub Engagement | Aggregated procurement through NHS England hubs standardizes device selection and surveillance data collection. |
| EHR Integration Partnership | Bespoke API development for fragmented hospital trust IT systems locks in switching costs for incumbent vendors. |
| Real-World Evidence Generation | NHS MedTech Funding Mandate compliance requires patient-reported outcome measures alongside glycaemic endpoints. |
Research Methodology
Operator-level perspectives from NHS procurement managers, specialist endocrinologists, biomedical engineers at hospital trusts, and diabetes clinic nursing directors anchored the qualitative base. Secondary validation drew from MHRA device registration databases, NICE Technology Appraisal Guidance documents, NHS England procurement disclosure records, and hospital trust electronic health record system specifications. Bottom-up sensor shipment estimates triangulated against top-down NHS reimbursement expenditure data.
Scenario-bracketing framed the analytical approach across the projection horizon, with sensitivity testing on NICE cost-effectiveness threshold adjustments and MHRA-MDR divergence scenarios. Segmentation dimensions modeled include product architecture, diabetes type application, end-user procurement sophistication, and sensor technology platform. CAGRs derived from installed base growth trajectories and replacement cycle economics, with algorithm adoption curves and smartphone-compatible device penetration as key forecast inputs.
Practitioners should monitor MHRA recognition agreement developments, NHS England coverage expansion announcements, and conductive polymer commodity price movements for early signals of forecast revision. Quarterly review of NICE Technology Appraisal Guidance updates and regional procurement hub consolidation patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Self-Monitoring Blood Glucose Strips Market
Diabetes Care
Gestational Diabetes Market
Diabetes Care
Mexico Diabetes Medication Market
Diabetes Care
SGLT2 Inhibitors Treatment Market
Diabetes Care
Brazil Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Italy Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Middle East and Africa Diabetes Care Devices Market
Diabetes Care
OTC Glucose Monitors Market
Diabetes Care
Italy Continuous Glucose Monitoring Devices Market
Diabetes Care
France Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Type 2 Diabetes Mellitus Treatment Market
Diabetes Care
South Korea Insulin Infusion Pump Market
Diabetes Care
Thailand Oral Antidiabetic Drug Market
Diabetes Care
France Oral Anti-Diabetic Drug Market
Diabetes Care
Global Continuous Glucose Monitoring Systems Market