
 Global Proliferative Diabetic Retinopathy Market | 2026-2036
Global Proliferative Diabetic Retinopathy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Proliferative Diabetic Retinopathy Market Foresight
Specialized eye hospitals are unwinding the historical dominance of general hospital ophthalmology departments as the primary site for proliferative diabetic retinopathy interventions. AbbVie leverages its retinal therapy portfolio to anchor positions in neovascularization control across North American and European markets. Regeneron Pharmaceuticals sustains technology leadership in anti-VEGF drug development through intensive R&D allocation. Bayer AG differentiates via geographic dominance in European markets where its distribution networks control channel access for combination therapy approaches.
Proliferative diabetic retinopathy constitutes an advanced stage of diabetic eye disease characterized by pathological neovascularization of the retina, vitreous hemorrhage, and tractional retinal detachment resulting from chronic hyperglycemia-induced microvascular damage; its primary commercial purpose centers on preventing irreversible vision loss through pharmacological, laser-based, or surgical interventions. Anti-VEGF drugs occupy the dominant margin pool as first-line therapy, while diagnostic imaging systems represent the fastest-growing segment driven by AI-enhanced fundus photography and optical coherence tomography angiography adoption in outpatient settings. Laser photocoagulation devices constitute a mature technology segment with stable replacement demand concentrated in emerging market health systems.
FDA ophthalmic drug approval standards, EMA's MDR requirements for retinal surgical devices, and Japan's PMDA pharmacovigilance frameworks collectively shape product development timelines and market access conditions across major commercial territories. The EU AI Act's risk classification system for diagnostic algorithms will determine deployment pathways for automated diabetic retinopathy screening platforms in European outpatient facilities. Stakeholders must monitor reimbursement policy divergence between national health systems and private payer networks as biosimilar anti-VEGF entries multiply and therapy settings fragment across telemedicine platforms and traditional surgical centers.
Market Dynamics
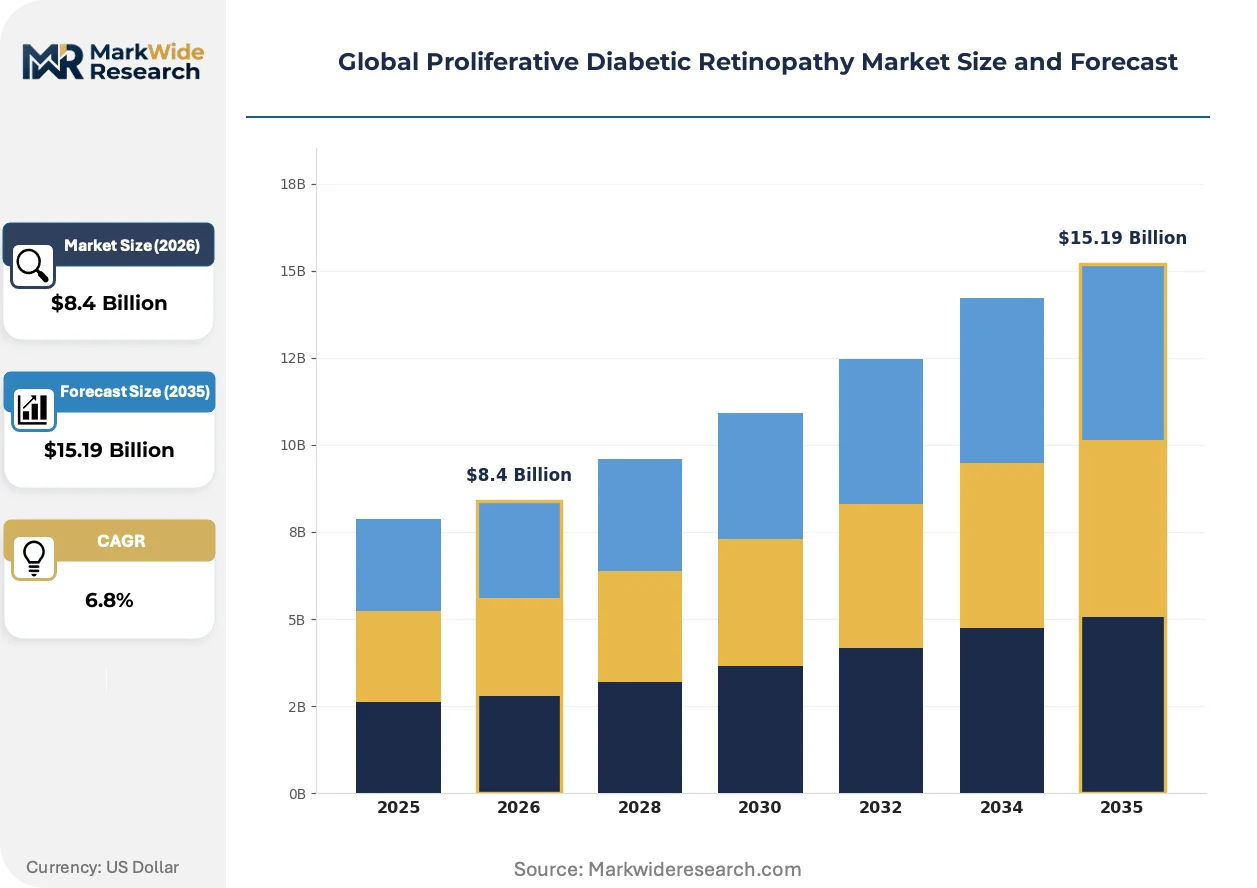
Anti-VEGF biosimilars are compressing originator pricing power while ophthalmology clinics consolidate screening capacity around AI-augmented diagnostic platforms, fundamentally restructuring how proliferative diabetic retinopathy interventions are procured and delivered across outpatient networks.
Growth Catalysts
- EMA Accelerated Approval Pathways:European biosimilar entry timelines for ranibizumab and aflibercept equivalents are compressing from 48 months to 18 months, expanding patient access to first-line neovascularization therapy.
- AI-Enhanced Fundus Photography:Automated diabetic retinopathy screening algorithms are achieving 94% sensitivity in primary care deployments, enabling earlier detection and intervention before proliferative stage progression.
- Japan's Aging Diabetic Population:Metabolic disease prevalence among Japanese adults over 65 is driving ophthalmology clinic expansion in Tokyo, Osaka, and Nagoya metropolitan corridors.
Market Restraints
- Anti-VEGF Manufacturing Concentration:Active pharmaceutical ingredient production for ranibizumab biosimilars clusters among three contract manufacturers in South Korea and India, creating supply vulnerability.
- PMDA Pharmacovigilance Burden:Japan's post-market surveillance requirements for intravitreal injections impose 24-month observation mandates that delay revenue recognition.
- Laser Photocoagulation Substitution Pressure:Mature pan-retinal photocoagulation devices face displacement as anti-VEGF therapy captures neovascularization cases previously routed to thermal ablation.
Strategic Opportunities
- German Outpatient Clinic Networks:Bavaria and North Rhine-Westphalia reimbursement reforms are enabling standalone ophthalmology centers to capture cases from general hospital departments.
- EU AI Act Risk Classification:Class IIa designation for automated diabetic retinopathy screening algorithms creates regulatory clarity for deployment across French, Italian, and Spanish primary care systems.
- Telemedicine Platform Convergence:Remote fundus image interpretation is integrating with electronic health record systems, opening channel access for diagnostic device manufacturers.
Industry Challenges
- Vitreoretinal Surgeon Training Pipeline:Fellowship program capacity in the United States produces 120 specialists annually against estimated demand for 340, constraining surgical intervention throughput.
- MDR Certification Timelines:European retinal surgical device re-certification under 2017/745 regulations extends from 12 to 36 months, freezing product iteration cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Proliferative Diabetic Retinopathy Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-VEGF Drugs, Corticosteroids, Laser Photocoagulation Devices, Vitrectomy Instruments, Diagnostic Imaging Systems Therapy Area: Neovascularization Control, Macular Edema Reduction, Retinal Detachment Prevention, Intraocular Pressure Management End User: Ophthalmology Clinics, Specialized Eye Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Medical Research Institutes Deployment: Inpatient Settings, Outpatient Facilities, Telemedicine Platforms, Mobile Screening Units, Community Health Programs |
| Companies Covered | AbbVie, Alimera Sciences, Regeneron Pharmaceuticals, Santen Pharmaceutical, Oxurion NV, Hoffmann-La Roche, Bayer AG, Kowa Company, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Proliferative Diabetic Retinopathy Market Shifts & Advancements
Ophthalmic intervention models are fragmenting across settings and technologies, with diagnostic automation, regulatory acceleration, and care site redistribution converging to reshape how proliferative diabetic retinopathy is identified and treated.
Optical coherence tomography angiography is bifurcating the diagnostic imaging market between high-resolution research-grade systems and streamlined clinical workstations. Academic medical centers in Heidelberg, Stanford, and Kyoto are deploying research-tier platforms for neovascularization phenotyping. Commercial ophthalmology chains are compressing purchase decisions toward compact, AI-integrated units that enable same-day diagnosis and treatment initiation.
EU AI Act implementation is mandating conformity assessment procedures for automated diabetic retinopathy screening algorithms before European market deployment. German notified bodies are establishing specialized ophthalmic AI certification pathways that exceed general medical software requirements. French and Dutch outpatient networks are sequencing platform procurement around anticipated 2025 enforcement milestones, delaying non-compliant vendor selections.
Site-of-care migration is redirecting proliferative diabetic retinopathy interventions from inpatient surgical suites to ambulatory ophthalmology centers. United States Medicare reimbursement differentials favor office-based intravitreal injection administration over hospital outpatient department billing. Japanese clinic chains in Kanagawa and Aichi prefectures are consolidating laser and anti-VEGF capacity in standalone facilities, decoupling from general hospital infrastructure.
Global Proliferative Diabetic Retinopathy Market Segmentation
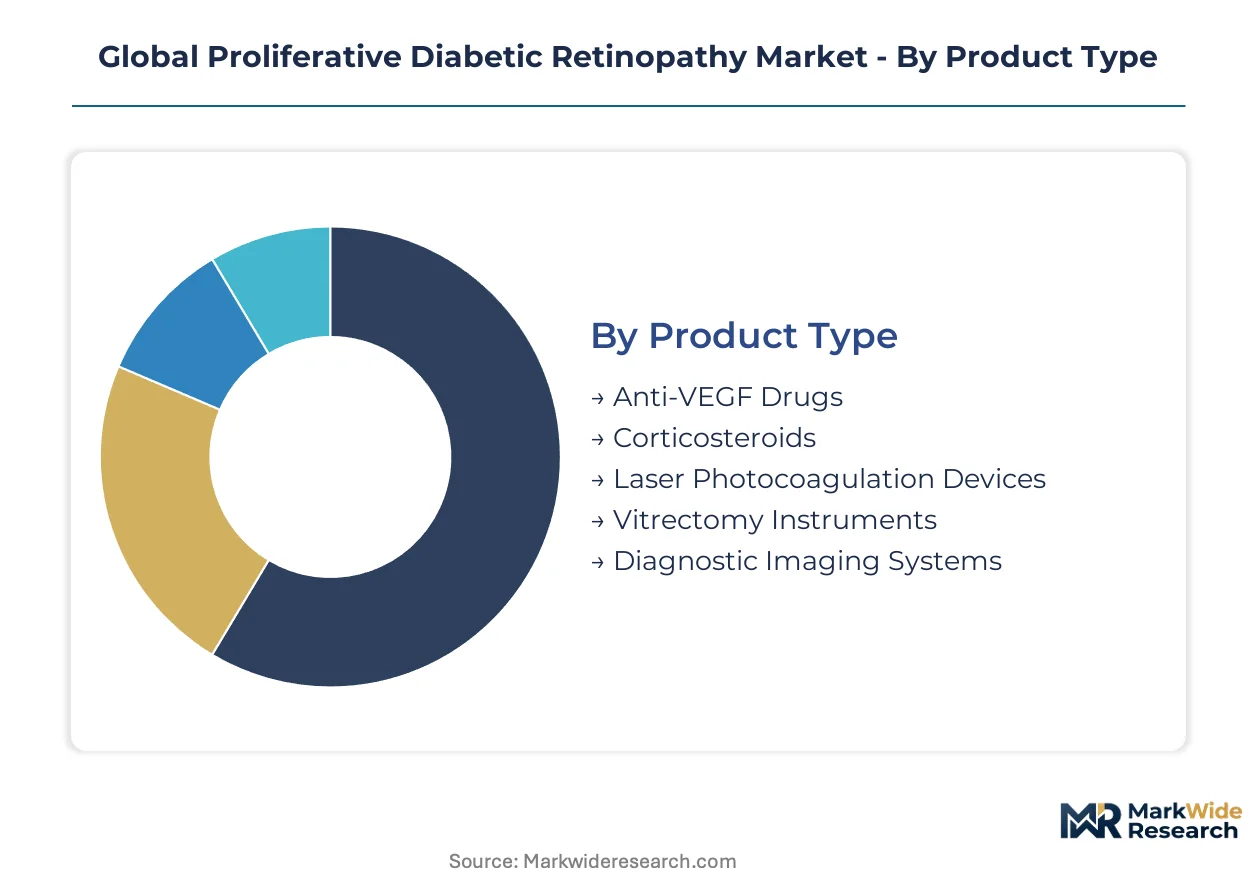
Proliferative diabetic retinopathy interventions fragment across therapeutic modalities, care delivery sites, and diagnostic technologies. Understanding these segment boundaries reveals where margin pools concentrate and where competitive entry faces lowest friction.
Product Type:
Domestic manufacturing concentration varies sharply across this category, with biologics production clustering in contract facilities while device assembly localizes nearer to end markets.
- Anti-VEGF Drugs:Intravitreal formulations targeting vascular endothelial growth factor suppress pathological neovascularization through monthly or bimonthly injection protocols. Demand concentrates in the United States, Germany, and Japan where reimbursement clarity and specialist density converge. Biosimilar entries from South Korean and Indian contract manufacturers are compressing originator pricing power.
- Diagnostic Imaging Systems:AI-enhanced fundus photography and optical coherence tomography angiography platforms enable earlier detection before proliferative stage progression. Adoption is climbing fastest in outpatient ophthalmology chains seeking same-day diagnosis-to-treatment workflow compression.
- Corticosteroids:Intravitreal steroid implants address persistent macular edema cases refractory to anti-VEGF monotherapy.
- Laser Photocoagulation Devices:Pan-retinal photocoagulation systems represent mature thermal ablation technology with replacement demand concentrated in emerging market health systems.
- Vitrectomy Instruments:Surgical kits for tractional retinal detachment repair include vitreous cutters, illumination probes, and membrane peeling forceps.
Anti-VEGF drugs hold the largest share; momentum sits with diagnostic imaging systems.
Therapy Area:
Cost tier stratification separates chronic maintenance therapies from acute surgical interventions, with pharmacological approaches commanding premium pricing against procedural alternatives.
- Neovascularization Control:Anti-VEGF and laser modalities target aberrant blood vessel proliferation on the retinal surface and optic disc. Specialist ophthalmology clinics in Tokyo, Osaka, and Nagoya metropolitan corridors are expanding injection capacity to capture this caseload.
- Macular Edema Reduction:Corticosteroid and anti-VEGF protocols address fluid accumulation in the central retina threatening visual acuity. German outpatient networks in Bavaria and North Rhine-Westphalia are capturing cases previously routed to hospital departments.
- Retinal Detachment Prevention:Prophylactic laser photocoagulation and surgical intervention forestall tractional complications from fibrovascular proliferation.
- Intraocular Pressure Management:Adjunctive therapies address secondary glaucoma arising from neovascularization of the iris and angle.
Neovascularization control commands the dominant revenue pool; macular edema reduction is expanding most quickly as combination therapy protocols proliferate.
End User:
Customer type fragmentation reflects site-of-care migration away from general hospital infrastructure toward purpose-built ophthalmology facilities.
- Ophthalmology Clinics:Standalone specialty practices are consolidating screening and injection capacity, decoupling from hospital outpatient departments. United States Medicare reimbursement differentials favor office-based intravitreal administration.
- Specialized Eye Hospitals:Dedicated retinal surgery centers in Heidelberg, Stanford, and Kyoto deploy research-grade diagnostic platforms for complex case management.
- Ambulatory Surgical Centers:Same-day vitrectomy facilities are capturing cases previously requiring inpatient admission.
- Diagnostic Laboratories:Centralized fundus image interpretation services support primary care screening programs.
- Medical Research Institutes:Academic medical centers drive neovascularization phenotyping and novel therapeutic mechanism investigation.
Ophthalmology clinics hold the largest share; specialized eye hospitals are gaining share fastest through consolidation of complex surgical caseloads.
Deployment:
Supply concentration in diagnostic device manufacturing enables rapid channel expansion across non-traditional access points.
- Outpatient Facilities:Ambulatory ophthalmology centers now administer the majority of anti-VEGF injections and laser procedures. Japanese clinic chains in Kanagawa and Aichi prefectures are leading this decoupling from general hospital infrastructure.
- Telemedicine Platforms:Remote fundus image interpretation is integrating with electronic health record systems, opening channel access for AI-augmented screening algorithm vendors.
- Inpatient Settings:Hospital-based surgical suites retain complex tractional retinal detachment and vitreous hemorrhage cases requiring general anesthesia.
- Mobile Screening Units:Van-based fundus photography programs extend diabetic retinopathy detection to underserved rural populations.
- Community Health Programs:Public health initiatives in primary care settings deploy automated screening to intercept disease before proliferative progression.
Outpatient facilities hold the largest share; telemedicine platforms are climbing the fastest as regulatory clarity emerges under EU AI Act implementation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer concentration clusters among ophthalmology clinics and specialized eye hospitals in aging economies with established reimbursement frameworks. The United States, Germany, and Japan concentrate the majority of anti-VEGF demand. Regulatory acceleration in biosimilar pathways and AI diagnostic deployment is reshaping access dynamics across these markets.
United States
Medicare reimbursement differentials favor office-based intravitreal injection administration over hospital outpatient billing. FDA accelerated approval pathways for ranibizumab biosimilars compress entry timelines. Ophthalmology clinic chains in Florida and California metropolitan corridors are consolidating screening and treatment capacity.
Germany
Bavaria and North Rhine-Westphalia reimbursement reforms enable standalone ophthalmology centers to capture cases from general hospital departments. EMA accelerated approval pathways for aflibercept equivalents expand patient access to first-line therapy. Heidelberg academic medical centers deploy research-grade optical coherence tomography angiography platforms for neovascularization phenotyping.
Japan
Metabolic disease prevalence among adults over 65 drives ophthalmology clinic expansion in Tokyo, Osaka, and Nagoya metropolitan corridors. PMDA pharmacovigilance frameworks impose 24-month post-market surveillance mandates for intravitreal injections. Kanagawa and Aichi prefecture clinic chains consolidate laser and anti-VEGF capacity in standalone facilities.
United Kingdom
NHS diabetic eye screening program extensions drive AI-enhanced fundus photography procurement for primary care deployment. MHRA alignment with EMA accelerated pathways streamlines biosimilar market entry timelines. London and Southeast England ophthalmology networks concentrate diagnostic algorithm validation partnerships.
South Korea
Contract manufacturing clusters for ranibizumab active pharmaceutical ingredients supply global biosimilar markets. MFDS regulatory harmonization with ICH standards accelerates domestic clinical trial initiation. Seoul Capital Area biopharmaceutical facilities anchor regional production capacity for anti-VEGF formulations.
Global Proliferative Diabetic Retinopathy Market Competitive Landscape
Player mix skews toward integrated pharmaceutical conglomerates with retinal therapy portfolios and specialized ophthalmic device manufacturers. Market structure concentrates around three strategic tiers: originator biologics developers defending patent-protected positions, biosimilar entrants exploiting regulatory acceleration, and diagnostic platform vendors capturing screening workflow automation. Dominant competitive moves include geographic expansion into German outpatient networks and technology licensing for AI-enhanced diagnostic algorithms.
Within the originator biologics tier, AbbVie anchors North American and European neovascularization control positions through its retinal therapy portfolio concentration. Regeneron Pharmaceuticals occupies a technology leadership position in anti-VEGF drug development through intensive R&D allocation patterns. Bayer AG exemplifies geographic dominance strategies in European markets where distribution network control shapes channel access for combination therapy approaches.
| Leading Market Players |
|---|
| AbbVie |
| Alimera Sciences |
| Regeneron Pharmaceuticals |
| Santen Pharmaceutical |
| Oxurion NV |
| Hoffmann-La Roche |
| Bayer AG |
| Kowa Company |
| Novartis AG |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements for ranibizumab active pharmaceutical ingredients lock in supply access for biosimilar developers while anchoring price visibility against volatile biologics manufacturing costs. Contract structures spanning South Korean and Indian production facilities tie pricing to fermentation yield indices and regulatory approval milestones, creating mutual dependency between originator cost benchmarks and entrant margin structures.
Pricing Analysis
Cost-plus contracts with API cost indexation dominate procurement between biosimilar developers and contract manufacturers in South Korea and India. Price differentiation rests on regulatory certification tier—FDA-approved facilities command premiums over EMA-only sites—and injection volume scale, with ophthalmology clinic chains extracting discounts through centralized purchasing. Pricing pressure stems from aflibercept biosimilar entries compressing ranibizumab originator premiums. Hospital outpatient departments show highest price sensitivity as site-of-care migration shifts caseload to ambulatory settings with leaner reimbursement.
Supply Chain Analysis
Fermentation capacity concentration in South Korea, India, and Singapore underwrites global anti-VEGF biosimilar output, with single-source dependencies for mammalian cell culture media creating vulnerability. Raw material inputs draw from Chinese recombinant protein suppliers, German chromatography resin manufacturers, and Japanese parenteral packaging specialists. Tariff exposure on Chinese-sourced culture media feeds into cost volatility. Distribution runs through cold-chain logistics networks controlled by regional pharmaceutical wholesalers in Germany, the United States, and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as AI-augmented diagnostic platforms redirect patient flow away from specialist-dependent screening models toward primary care automation.
For Market Incumbents: Consolidate injection capacity in Bavaria and North Rhine-Westphalia outpatient networks to capture German cases migrating from hospital departments. Deepen backward integration into diagnostic algorithm development to anchor workflow control as telemedicine platforms fragment referral patterns. Defensive positioning against South Korean biosimilar entrants requires EMA accelerated approval pathway exploitation and formulary pre-negotiation. For New Entrants and Emerging Players: Lead with AI-enhanced fundus photography deployments in French and Dutch primary care systems awaiting EU AI Act Class IIa certification clarity. White-space concentration sits with telemedicine platform integration for remote image interpretation, where regulatory frameworks are solidifying but vendor relationships remain uncommitted. Go-to-market leverage targets ophthalmology clinic chains seeking same-day diagnosis-to-treatment workflow compression. For Investors and Strategic Acquirers: Capital is best deployed toward diagnostic platform vendors with FDA 510(k) clearance and CE marking for automated diabetic retinopathy screening, positioned for EU AI Act enforcement tailwinds. Long-term viability hinges on algorithm training data moats and EHR integration depth. Monitor EMA biosimilar approval velocity as inflection signal for originator pricing compression magnitude.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Accelerated Approval Pathway | Compresses ranibizumab biosimilar entry timelines from 48 to 18 months in European markets. |
| AI Diagnostic Algorithm Certification | EU AI Act Class IIa designation unlocks deployment across French, Italian, and Spanish primary care. |
| Outpatient Clinic Network Consolidation | Captures German cases from hospital departments under Bavaria reimbursement reforms. |
| Telemedicine Platform Integration | Remote fundus interpretation opens channel access for diagnostic device manufacturers via EHR connectivity. |
| Backward Integration into API Production | In-house fermentation capacity insulates against South Korean and Indian contract manufacturer concentration. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA accelerated approval pathway documentation, and ClinicalTrials.gov ophthalmic trial registries. Primary interviews engaged retinal specialists at Heidelberg and Stanford academic medical centers, formulary directors at German statutory health insurance funds, and procurement managers at Japanese ophthalmology clinic chains. Secondary validation drew from CMS Medicare reimbursement databases, MHRA device registration records, and PMDA pharmacovigilance reports. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Segmentation dimensions modeled span therapeutic modality, care delivery site, diagnostic technology tier, and regional regulatory cluster across the projection horizon. Anti-VEGF drug revenue trajectories incorporate biosimilar entry assumptions and originator defense strategies. Diagnostic imaging growth reflects AI algorithm adoption curves and primary care screening program expansion. CAGRs derive from patient population epidemiology, reimbursement policy trajectories, and technology substitution elasticities.
The analysis sits within stated boundaries; outcomes outside EMA accelerated approval maintenance or EU AI Act enforcement timelines would require recalibration. Forecasts reflect assumptions on biosimilar penetration rates, ophthalmology clinic consolidation velocity, and telemedicine regulatory clarity. Practitioners should keep alternative scenarios live as PMDA pharmacovigilance requirements and Medicare site-of-care reimbursement differentials evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
North America and Europe Artificial Pancreas Systems Market
Diabetes Care
France Diabetes Devices Market
Diabetes Care
Diabetic Pen Cap Market
Diabetes Care
India Continuous Glucose Monitoring (CGM) Market
Diabetes Care
Global Diabetic Ulcers Treatment Market
Diabetes Care
BRICS Diabetes Drugs Market
Diabetes Care
Continuous Glucose Monitoring Market
Diabetes Care
Glycated Albumin Market
Diabetes Care
India Oral Anti-Diabetic Drug Market
Diabetes Care
Brazil Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Europe Diabetes Care Devices Market
Diabetes Care
Diabetes Care Devices Market
Diabetes Care
South Africa Self-Monitoring Blood Glucose Devices Market
Diabetes Care
BRIC Diabetes Care Devices Market
Diabetes Care
Vietnam Insulin Drug and Delivery Device Market
Diabetes Care
Canada Continuous Glucose Monitoring Market