
 Alternatives for Injectable Diabetes Care Market | 2026-2036
Alternatives for Injectable Diabetes Care Market Size, Share, and Industry Trends Forecast 2026-2036
Alternatives for Injectable Diabetes Care Market Outlook
Subscription-based software layers for insulin dose optimization are pivoting device economics from hardware sales to recurring revenue models. Medtronic Plc leverages its MiniMed ecosystem to anchor patient retention through predictive algorithm updates. Dexcom competes on sensor accuracy and direct-to-consumer channel control, while Abbott Laboratories sustains manufacturing scale across FreeStyle Libre production lines.
Alternatives for injectable diabetes care encompass non-needle delivery systems, continuous glucose sensors, and automated insulin administration devices designed to maintain glycemic control without conventional syringe-based injection. These systems typically employ subcutaneous electrochemical sensors with 10-14 day wear periods, paired with algorithm-driven pump modulation or inhaled insulin powder formulations to reduce injection burden. Continuous glucose monitors lead product type segments due to established reimbursement and expanding non-insulin user populations, while smart devices within the technology dimension capture expanding margin pools through software-enabled personalization. Non-injectable medications represent the fastest-growing delivery mode category as pharmaceutical developers advance oral GLP-1 formulations and transdermal peptide patches.
FDA premarket approval requirements for closed-loop systems and EMA MDR compliance for wearable sensors shape product development timelines and market access costs for manufacturers. The EU AI Act and HIPAA data governance standards further constrain how patient glucose data flows between devices, cloud platforms, and healthcare providers. Stakeholders must monitor evolving payer evidence requirements for digital health integration as regulators tighten cybersecurity mandates for connected diabetes devices.
Market Dynamics
The shift from hardware-centric insulin delivery toward algorithm-driven, software-updatable systems is restructuring competitive economics and patient retention models across diabetes care.
Growth Catalysts
- Home care migration:Patient preference for self-administered glycemic management is accelerating uptake of connected delivery systems in residential settings, reducing clinical dependency.
- EMA MDR compliance pathways:Accelerated device approval timelines for closed-loop artificial pancreas systems in Germany are compressing market access barriers for wearable sensor manufacturers.
- Digital therapeutic reimbursement:Early payer integration of connected diabetes devices in the United States is expanding addressable patient populations beyond traditional insulin users.
Market Restraints
- Electrochemical sensor substrate costs:Palladium and platinum price volatility in 10-14 day continuous glucose monitor manufacturing is squeezing hardware margins.
- FDA premarket approval timelines:Extended clinical evidence requirements for closed-loop systems delay commercialization by 18-36 months relative to sensor-only devices.
- Inhaled insulin substitution:Oral GLP-1 formulation advances from pharmaceutical developers threaten to displace pump-dependent patient segments.
Strategic Opportunities
- Non-insulin user expansion:Type 2 diabetes populations in India represent underpenetrated demand for continuous glucose monitoring without pump pairing.
- EU AI Act compliance:Algorithm transparency mandates create first-mover advantage for manufacturers with pre-validated glucose prediction models.
- Direct-to-consumer channel control:Bypassing durable medical equipment distributors via pharmacy and e-commerce platforms captures margin previously lost to intermediaries.
Industry Challenges
- Biocompatibility engineering talent scarcity:Shortage of specialists in subcutaneous electrochemical sensor design constrains R&D throughput.
- HIPAA cloud architecture retrofit:Legacy glucose data platforms require expensive re-engineering to meet tightened cybersecurity mandates for connected devices.
- Interoperability certification delays:Fragmented standards between pump, sensor, and mobile app ecosystems prolong integration testing cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alternatives for Injectable Diabetes Care Market |
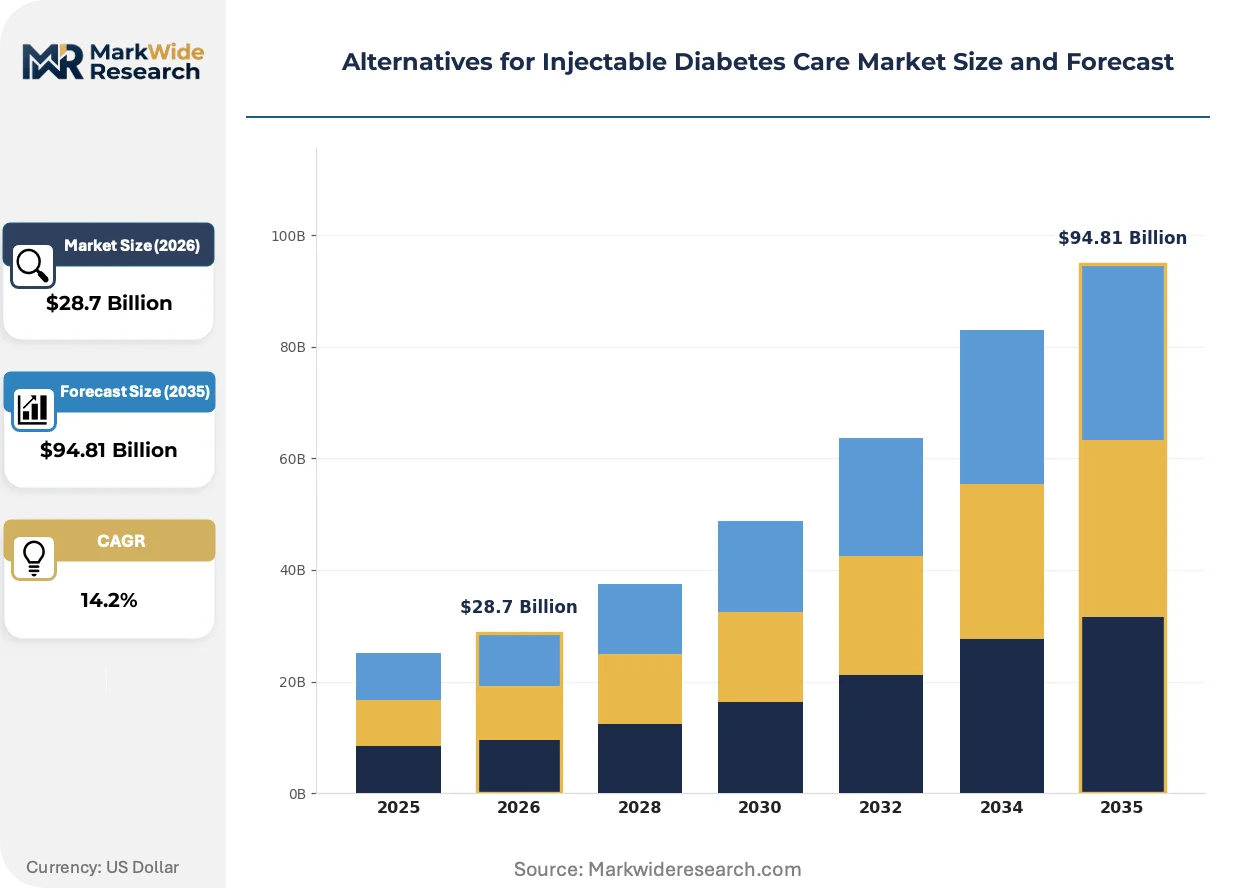
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $94.81 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pens, Continuous Glucose Monitors, Insulin Pumps, Non-Injectable Medications Delivery Mode: Oral, Transdermal, Inhalable, Depot Injection End User: Home Care, Hospitals, Diagnostic Centers, Pharmacies Technology: Smart Devices, Wearable Sensors, Mobile Apps, Biometric Devices |
| Companies Covered | Medtronic Plc, Insulet Corporation, Dexcom, Abbott Laboratories, F Hoffmann-La Roche AG, Animas Corporation, Valeritas, Tandem Diabetes Care, MannKind Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alternatives for Injectable Diabetes Care Market Strategic Shifts
Algorithmic personalization and data sovereignty requirements are simultaneously elevating software value capture and complicating cross-border device deployment in diabetes management systems.
Closed-loop artificial pancreas systems that integrate continuous glucose sensors with predictive insulin dosing algorithms is rewriting competitive positioning in automated diabetes care. Pediatric endocrinology departments and high-acuity adult patients are adopting these systems faster than standard pump upgrades, compressing the addressable market for standalone sensor or pump hardware vendors.
The EU AI Act's risk-classification framework for medical device algorithms is tightening documentation requirements for glucose prediction models. Manufacturers must now maintain algorithm version logs and performance audit trails, increasing compliance costs most severely for mid-tier device makers without established quality management systems.
Subscription-based software layers for insulin dose optimization are displacing perpetual hardware sales in patient acquisition economics. Endocrinology practices in the United States are unbundling device procurement from algorithm access, shifting vendor relationships toward recurring revenue models and compressing upfront capital requirements for patient onboarding.
Alternatives for Injectable Diabetes Care Market Segmentation
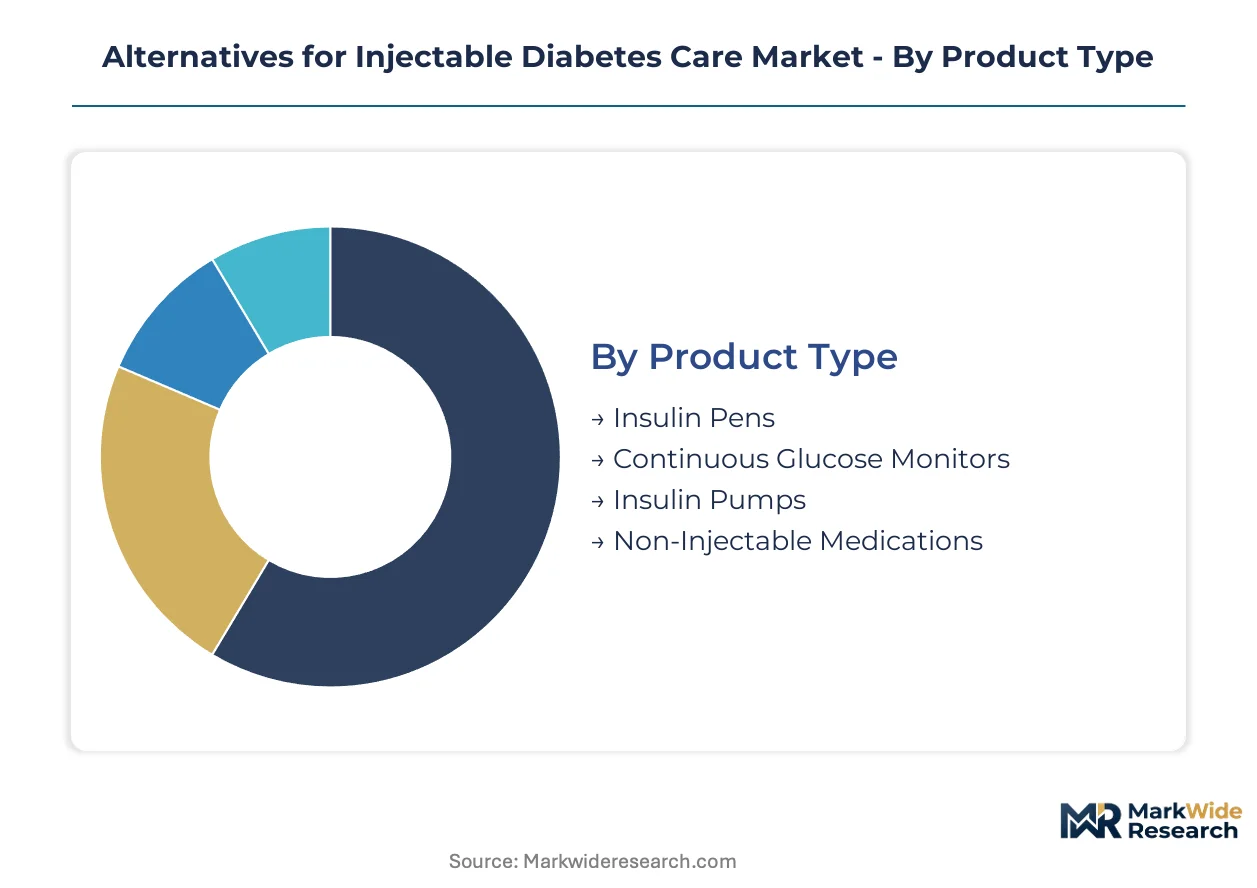
Segmentation in diabetes alternatives reveals how patient preference, reimbursement pathways, and technology maturity fragment addressable demand across distinct commercial battlegrounds. Manufacturers must align hardware portfolios, software roadmaps, and channel strategies to specific segment economics rather than pursuing uniform market penetration.
Product Type:
Customization intensity spans single-use disposables at one extreme to algorithm-updatable systems at the other, with reimbursement density clustering toward sensor-augmented platforms.
- Continuous Glucose Monitors:Subcutaneous electrochemical sensors with 10-14 day wear periods paired with real-time data transmission. Demand concentrates in United States home care settings where CMS reimbursement codes and early payer integration of digital therapeutics expand access beyond insulin-dependent populations.
- Insulin Pumps:Programmable reservoir devices with basal-bolus delivery capability, increasingly paired with closed-loop algorithm integration. United States pediatric endocrinology departments and high-acuity adult patients in Germany drive replacement cycles faster than standard hardware upgrades, compressing addressable volume for standalone pump vendors.
- Insulin Pens:Disposable and reusable injection devices with dose memory features. United States pharmacy channels and European retail networks sustain volume through accessibility and lower upfront cost barriers.
- Non-Injectable Medications:Oral GLP-1 formulations, transdermal peptide patches, and inhaled insulin powder systems. Pharmaceutical developers in India and United States advance oral peptide stability technologies, threatening to displace pump-dependent segments.
Leading the category by volume: Continuous Glucose Monitors. Expanding most quickly: Non-Injectable Medications.
Delivery Mode:
Cost tier stratification separates premium biologic-compatible platforms from commodity-compatible alternatives, with manufacturing scale determining competitive viability.
- Oral:Enteric-coated peptide formulations and small-molecule enhancers enabling gastrointestinal absorption of GLP-1 analogues. United States and India represent focal markets where pharmaceutical developers target Type 2 diabetes populations with needle-free alternatives.
- Transdermal:Microneedle arrays and iontophoretic patches for peptide delivery through stratum corneum. European EMA MDR compliance pathways and Germany's accelerated device approval timelines favor manufacturers with validated biocompatibility data.
- Inhalable:Dry powder insulin formulations delivered via breath-actuated devices. United States FDA premarket approval requirements and pulmonary safety evidence standards constrain commercialization timelines relative to other modes.
- Depot Injection:Long-acting subcutaneous formulations with weekly or monthly dosing intervals. Hospital and diagnostic center procurement in United States sustains volume despite patient preference for fully non-injectable alternatives.
Highest reimbursement capture: Oral. Steepest regulatory complexity: Inhalable.
End User:
Application context determines device connectivity requirements, with acute care settings demanding EMR integration and residential settings prioritizing standalone usability.
- Home Care:Self-administered glycemic management with patient-controlled data sharing. United States dominates addressable population due to reimbursement density and direct-to-consumer channel expansion through pharmacy and e-commerce platforms.
- Hospitals:Inpatient glycemic control with centralized monitoring and nurse-administered dosing. United States health system procurement and Germany's hospital digitization mandates drive demand for interoperable device ecosystems.
- Diagnostic Centers:Point-of-care glucose testing and device trial programs. India represents underpenetrated expansion opportunity for continuous glucose monitoring without pump pairing.
- Pharmacies:Retail device dispensing and patient education services. United States pharmacy benefit managers increasingly control access to connected delivery systems through formulary placement.
Fastest channel margin expansion: Home Care. Highest procurement concentration: Hospitals.
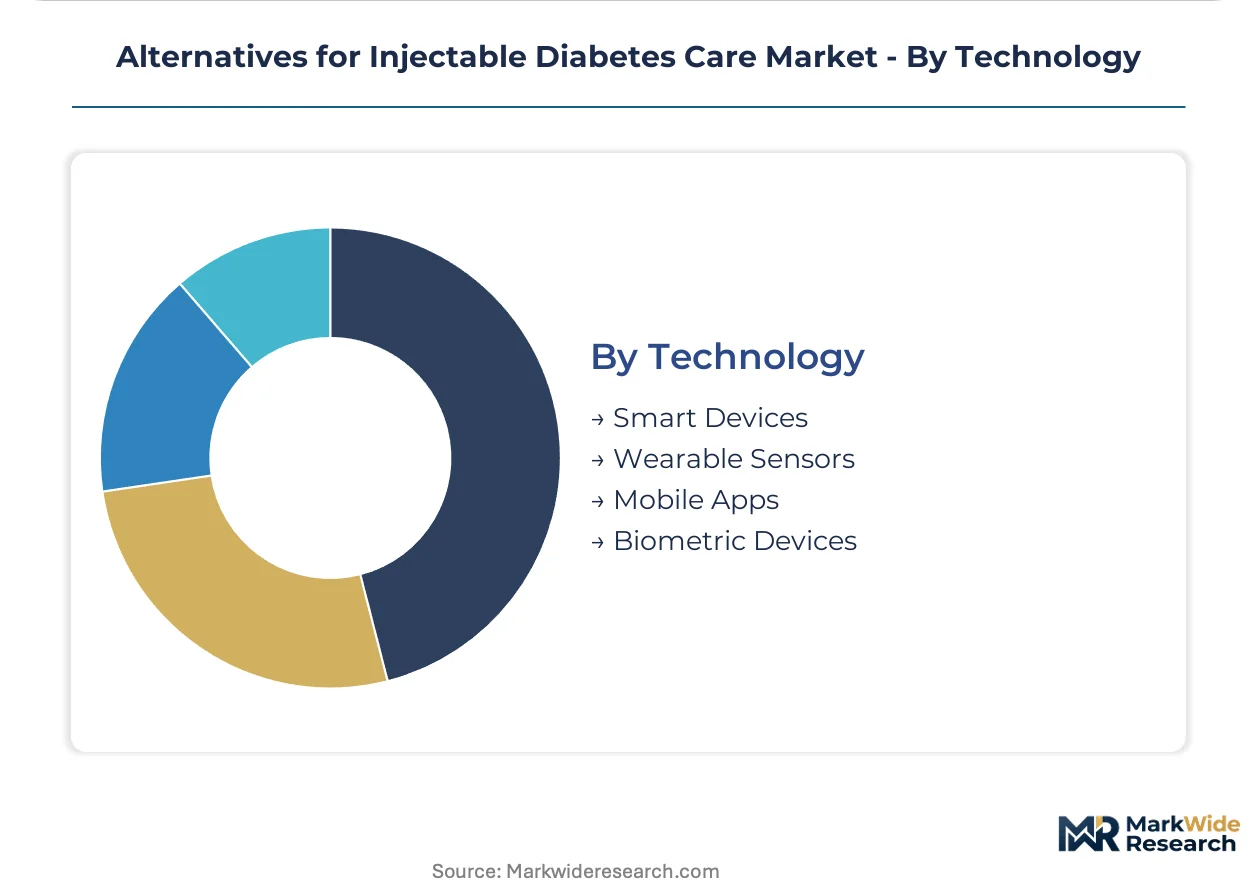
Technology:
Supply concentration in sensor substrate manufacturing and algorithm development talent creates asymmetric competitive advantages for vertically integrated platforms.
- Smart Devices:Closed-loop artificial pancreas systems integrating sensor input with predictive insulin dosing. FDA and EMA regulatory pathways for algorithm-driven devices accelerate approvals in United States and Germany while EU AI Act compliance mandates reshape documentation requirements.
- Wearable Sensors:Subcutaneous electrochemical monitors with wireless data transmission. Palladium and platinum price volatility in 10-14 day continuous glucose monitor manufacturing squeezes hardware margins for non-integrated vendors.
- Mobile Apps:Patient-facing dose optimization and data visualization platforms. HIPAA cloud architecture retrofit requirements and tightened cybersecurity mandates for connected devices impose compliance costs on legacy platform operators.
- Biometric Devices:Non-invasive glucose monitoring through optical or thermal sensing. Technical validation challenges and clinical evidence requirements delay commercialization relative to electrochemical alternatives.
Deepest margin pools: Smart Devices. Longest validation runway: Biometric Devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing concentrates in Germany and the United States while patient adoption scales fastest in India and China where diabetes prevalence outpaces reimbursement infrastructure.
United States
CMS reimbursement codes and early payer integration of digital therapeutics expand continuous glucose monitor access beyond insulin-dependent populations. FDA premarket approval pathways for closed-loop systems compress commercialization timelines relative to other geographies. The Minneapolis medical device corridor anchors sensor manufacturing and algorithm development clusters.
Germany
EMA MDR compliance pathways accelerate device approvals for closed-loop artificial pancreas systems. Hospital digitization mandates drive demand for interoperable device ecosystems in inpatient glycemic control. The Baden-Württemberg precision engineering cluster supports electrochemical sensor substrate fabrication.
India
Type 2 diabetes populations represent underpenetrated demand for continuous glucose monitoring without pump pairing. CDSCO regulatory frameworks for wearable medical devices are evolving to accommodate software-updatable systems. The Maharashtra pharmaceutical corridor advances oral GLP-1 formulation stability technologies.
China
NMPA approval timelines for continuous glucose monitors are compressing as domestic manufacturers scale electrochemical sensor production. The country's national pharmaceutical regulator is tightening biocompatibility documentation requirements for subcutaneous devices. The Yangtze River Delta medical device manufacturing belt concentrates wearable sensor assembly capacity.
Japan
PMDA regulatory pathways favor incremental device improvements over novel closed-loop system approvals. METI industrial policy supports domestic production of precision glucose sensors for export markets. The Kanto region Tokyo-Osaka corridor hosts pediatric endocrinology departments adopting algorithm-driven insulin delivery.
Alternatives for Injectable Diabetes Care Market Competitive Environment
Top-tier vendors anchor integrated closed-loop ecosystems, while mid-tier specialists concentrate on single-modality hardware. The vendor base stratifies across three tiers: diversified medical device conglomerates with algorithm platforms, sensor-focused manufacturers competing on accuracy specifications, and pharmaceutical developers advancing non-injectable peptide formulations. Dominant competitive moves include strategic partnerships between sensor and pump manufacturers and geographic licensing agreements for algorithm distribution rights.
Within the diversified medical device tier, Medtronic Plc and Abbott Laboratories exemplify vertically integrated platform strategies spanning sensors, pumps, and data infrastructure. Dexcom occupies a position as a sensor-specialist archetype competing on accuracy metrics and direct-to-consumer channel control. Insulet Corporation represents the patch-pump specialization vector targeting patient populations seeking reduced device footprint.
| Leading Market Players |
|---|
| Medtronic Plc |
| Insulet Corporation |
| Dexcom |
| Abbott Laboratories |
| F Hoffmann-La Roche AG |
| Animas Corporation |
| Valeritas |
| Tandem Diabetes Care |
| MannKind Corporation |
| Others |
Value Chain & Pricing Dynamics
Palladium and platinum substrate costs flow from South African mining operations through German electrochemical sensor fabricators to United States pump manufacturers, compressing hardware margins at each tier while subscription software layers capture expanding margin pools downstream.
Pricing Analysis
Margin tightening in continuous glucose monitor hardware reflects palladium price volatility and platinum supply constraints from concentrated mining jurisdictions. Three-tier pricing structure across premium closed-loop systems, standard sensor-augmented pumps, and economy insulin pens separates reimbursement-rich United States pediatric segments from cash-pay diagnostic center volumes in India. Cost-down pressure on wearable sensor assemblies accelerates because electrochemical substrate suppliers pass through commodity volatility without long-term offtake contracts. Hospital procurement committees demonstrate lowest price sensitivity due to bundled reimbursement codes, while pharmacy direct-to-consumer channels face highest patient out-of-pocket resistance.
Supply Chain Analysis
Domestic-content mandates in China's NMPA framework and India's PLI scheme for medical devices are reshaping sourcing patterns for subcutaneous sensor assembly. Manufacturing concentrates in Germany's Baden-Württemberg precision engineering cluster, the United States Minneapolis medical device corridor, and China's Yangtze River Delta assembly belt. Raw material dependencies center on South African platinum group metals, Taiwanese semiconductor substrates for wireless transmission modules, and Japanese precision polymers for biocompatible housing. Single-source vulnerability in palladium refining exposes non-integrated vendors to supply interruption. Distribution runs through United States durable medical equipment distributors, European hospital procurement consortia, and Indian pharmacy retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around algorithm-integrated platforms as FDA premarket approval timelines and EU AI Act compliance costs force mid-tier sensor-only vendors toward acquisition or exit.
For Market Incumbents: Deepen backward integration into electrochemical sensor substrate fabrication to insulate margin from South African platinum group metal volatility. Anchor patient retention through predictive algorithm update subscriptions that displace perpetual hardware sales. Defend against oral GLP-1 formulation advances by accelerating closed-loop artificial pancreas approvals in United States pediatric endocrinology departments. For New Entrants and Emerging Players: The price-point gap between premium closed-loop systems and economy insulin pens creates entry space for algorithm-agnostic continuous glucose monitors targeting India's Type 2 diabetes populations without pump pairing. Penetrate diagnostic center channels in Maharashtra and Karnataka where reimbursement infrastructure lags device readiness. Deploy direct-to-consumer pharmacy and e-commerce platforms to bypass entrenched durable medical equipment distributor relationships. For Investors and Strategic Acquirers: EU AI Act algorithm transparency mandates clearing through EMA MDR pathways is the leading indicator that mid-tier device makers without established quality management systems face existential compliance cost burdens. Position acquisition screening toward sensor-specialist vendors with validated glucose prediction models and pre-audited documentation trails. Watch for CDSCO regulatory framework evolution in India as the signal for software-updatable system market access liberalization.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for Closed-Loop Systems | Premarket approval pathways in the United States compress commercialization timelines relative to sensor-only devices. |
| CE Marking Pathway under EU AI Act | Algorithm transparency mandates reshape documentation requirements for glucose prediction models in European markets. |
| Hospital System Partnership | United States health system procurement and Germany's hospital digitization mandates drive demand for interoperable device ecosystems. |
| Software Companion Development | Subscription-based insulin dose optimization layers pivot device economics from hardware sales to recurring revenue models. |
| Reimbursement Strategy | Early payer integration of digital therapeutics in the United States expands addressable populations beyond traditional insulin users. |
Study Parameters
FDA 510(k) filings, EMA MDR submission databases, and CMS reimbursement code records formed the secondary backbone, cross-referenced against primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and endocrinology practice administrators. Bottom-up patient population estimates by diabetes type and insulin dependency status were triangulated against top-down manufacturer shipment data from United States, German, and Indian trade sources.
Historical trendline analysis of continuous glucose monitor adoption curves and insulin pump replacement cycles informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, delivery mode, end user setting, and technology tier with geographic regulatory cluster overlays. CAGRs were derived from fitted growth curves applied to validated base-year estimates, incorporating oral GLP-1 formulation pipeline progression and closed-loop system approval velocity as industry-specific demand modifiers.
Inputs from FDA premarket notification databases and EMA MDR approval registers were available through the study window; gaps in real-time manufacturer shipment disclosures from Chinese NMPA filings introduce uncertainty bands around Asia-Pacific volume estimates. Forecasts reflect assumptions regarding reimbursement code expansion timelines and algorithm regulatory classification stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
North America Diabetes Care Devices Market
Diabetes Care
Diabetic Shoes Market
Diabetes Care
China Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Canada Diabetes Care Drugs and Devices Market
Diabetes Care
Diabetic Lancing Devices Market
Diabetes Care
New Zealand Oral Anti-Diabetic Drug Market
Diabetes Care
United States Blood Glucose Monitoring Market
Diabetes Care
France Diabetes Devices Market
Diabetes Care
Egypt Diabetes Care Devices Market
Diabetes Care
Middle East and Africa Insulin Infusion Pumps Market
Diabetes Care
Vietnam Insulin Infusion Pump Market
Diabetes Care
Asia-Pacific Diabetes Care Devices Market
Diabetes Care
Latin America Oral Anti-Diabetic Drug Market
Diabetes Care
Asia Pacific Diabetes Pen Market
Diabetes Care
India Continuous Glucose Monitoring (CGM) Market
Diabetes Care
Italy Self-Monitoring Blood Glucose Devices Market