
 Australia Self-Monitoring Blood Glucose Market | 2026-2036
Australia Self-Monitoring Blood Glucose Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Self-Monitoring Blood Glucose Market Analysis
Australia is rewriting its domestic medtech manufacturing roadmap through targeted biomedical precinct investments in Melbourne and Sydney. Abbott Diabetes Care leverages extensive pharmacy distribution networks across Australian capital cities. Roche Diabetes Care anchors hospital and pathology channel relationships that sustain institutional test strip volumes. LifeScan competes through brand recognition among type 2 diabetes patients managing therapy independently.
Self-monitoring blood glucose encompasses portable electrochemical biosensor systems that quantify capillary glucose concentration via enzyme-mediated reactions on disposable test strips, primarily enabling real-time metabolic management for insulin-dependent and non-insulin-dependent diabetes patients. Standard meters retain volume leadership in Australian retail pharmacy channels due to reimbursement familiarity, while continuous glucose monitors represent the fastest-growing product type as endocrinologists expand CGM prescribing for type 1 and intensive type 2 cohorts. Smart meters and wireless technology segments capture margin concentration through subscription-linked data platforms that integrate with telehealth workflows.
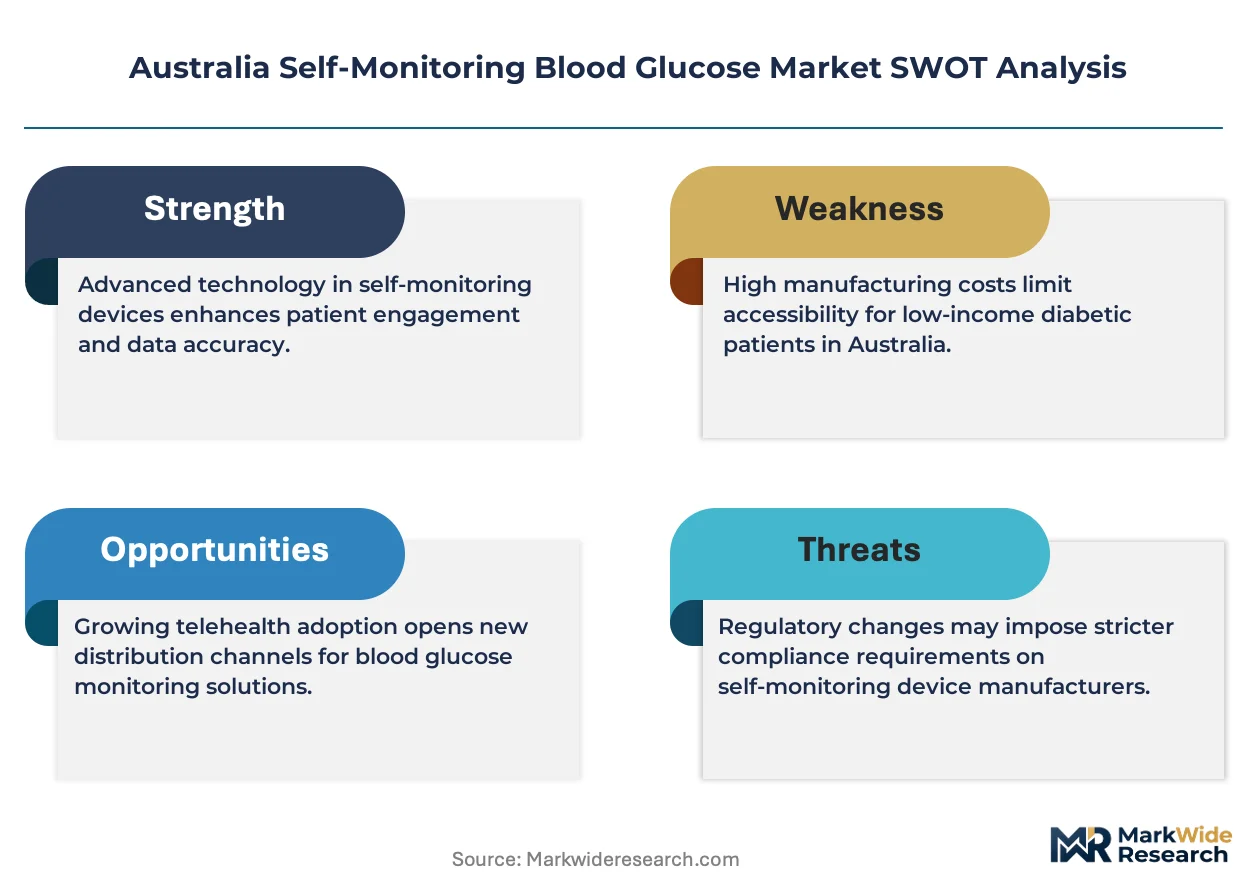
TGA medical device frameworks govern premarket conformity assessment for glucose monitoring systems, while ISO 15197 accuracy standards define analytical performance thresholds that manufacturers must validate. The Therapeutic Goods Administration's post-market vigilance requirements for adverse event reporting shape product liability exposure and design control investments. Stakeholders must monitor reimbursement policy evolution under the National Diabetes Services Scheme as continuous monitoring eligibility criteria expand beyond traditional patient categories.
Market Dynamics
The National Diabetes Services Scheme reimbursement expansion for continuous glucose monitors is compressing traditional test strip volumes while accelerating device upgrade cycles across Australian diabetes care pathways.
Growth Catalysts
- NDSS Subsidy Expansion:The Therapeutic Goods Administration's streamlined approval pathways for integrated CGM systems are pulling intensive type 2 patients toward continuous monitoring protocols previously restricted to type 1 cohorts.
- Telehealth Infrastructure:Medicare's permanent telehealth item numbers for endocrinology consultations are embedding remote glucose data sharing into standard care workflows across rural and metropolitan Australia.
- Aged Care Integration:Residential aged care facilities in Victoria and New South Wales are deploying centralized glucose monitoring stations to reduce hospitalization events among insulin-dependent residents.
Market Restraints
- Reimbursement Ceiling Pressure:The Pharmaceutical Benefits Scheme's fixed price schedules for test strips are constraining manufacturer margin recovery despite enzyme and electrode raw material volatility.
- Import Dependency:Over 80% of electrochemical biosensor substrates enter through Port Melbourne from concentrated Asian manufacturing clusters, exposing distributors to maritime freight rate fluctuations.
- Accuracy Standard Escalation:ISO 15197:2013's tightened error margin requirements are forcing redesign investments that delay product launches for mid-tier meter manufacturers.
Strategic Opportunities
- Tasmanian Rural Penetration:The island state's dispersed population and limited endocrinology clinic presence create whitespace for pharmacy-led diabetes educator programs paired with cellular-connected smart meters.
- Insulin Pump Convergence:Bluetooth-enabled meter-to-pump data bridges are opening subscription revenue streams as TGA clears automated insulin delivery interoperability standards.
- My Health Record Integration:The Australian Digital Health Agency's API expansion for consumer-controlled data sharing is enabling platform plays that aggregate glucose histories across multiple device brands.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Melbourne's biomedical precincts are competing for firmware developers capable of embedded glucose algorithm validation, compressing recruitment timelines for device startups.
- Post-Market Surveillance Burden:TGA's mandatory adverse event reporting for class IIa glucose monitors requires dedicated regulatory affairs headcount that strains mid-market player operating models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Self-Monitoring Blood Glucose Market |
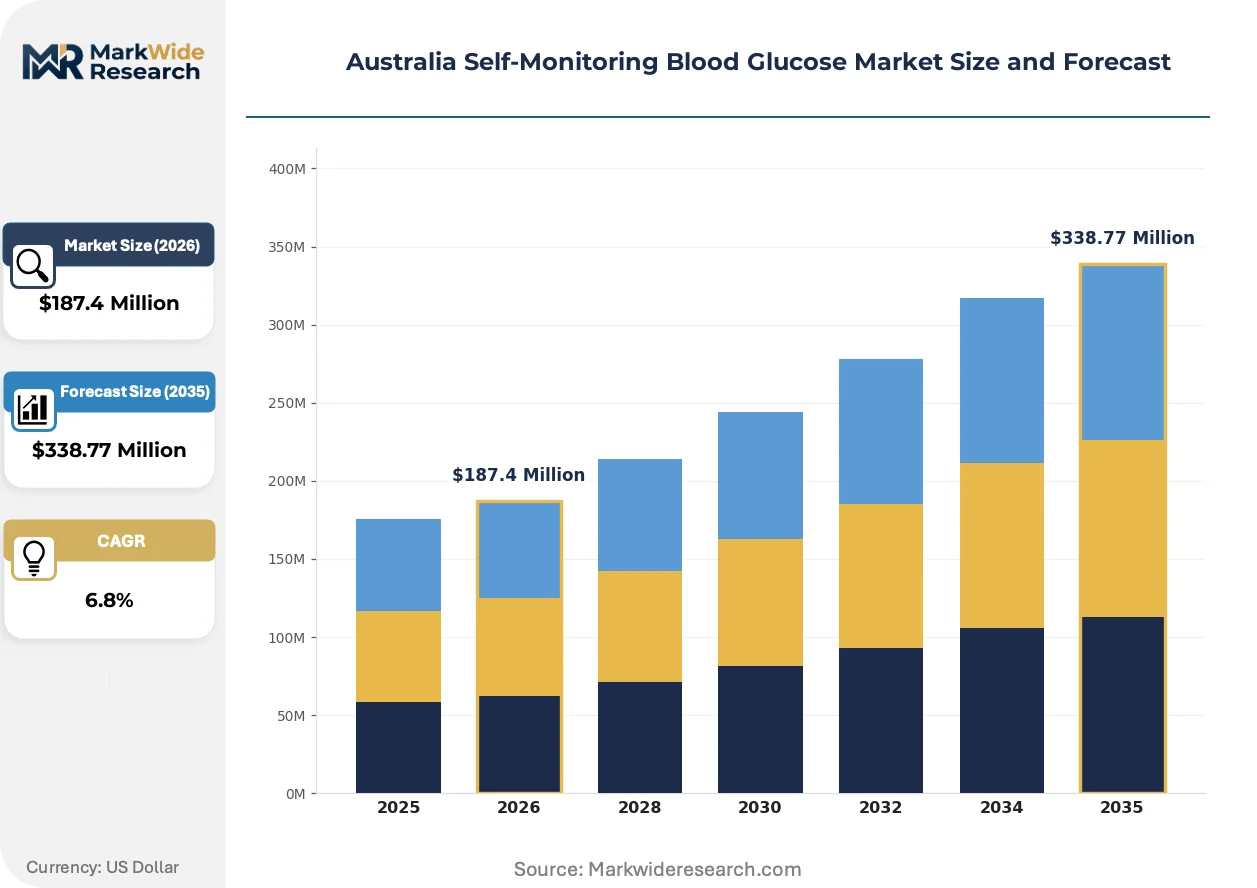
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucose Meters, Test Strips, Lancing Devices, Continuous Glucose Monitors End User: Home Users, Healthcare Providers, Pharmacies, Hospitals Technology: Standard Meters, Smart Meters, Wireless Technology, Mobile Apps Distribution Channel: Online Stores, Retail Pharmacies, Direct Sales, Medical Distributors |
| Companies Covered | Abbott Diabetes Care, Roche Diabetes Care, LifeScan, Ascensia Diabetes Care, Arkray Inc, Trividia Health, Acon Laboratories Inc, Bionime Corporation, Agamatrix Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Self-Monitoring Blood Glucose Market Emerging Trajectories
Electrochemical sensing architectures are yielding to optical and minimally invasive alternatives while reimbursement policy actively selects for connected, data-generating device formats over standalone meters.
Factory-calibrated continuous glucose monitors utilizing fluorescent glucose-binding proteins are collapsing the traditional fingerstick calibration ritual that has defined patient compliance for three decades. Endocrinology practices in Sydney and Melbourne are prescribing these systems to insulin-naive type 2 patients within six months of diagnosis. The elimination of calibration strips is compressing retail pharmacy foot traffic and redirecting margin toward subscription-based sensor shipments.
TGA's 2024 guidance on software-as-a-medical-device classification is redefining which glucose data analytics platforms require full conformity assessment. Smartphone applications that aggregate meter readings and generate insulin dose recommendations now face premarket scrutiny previously reserved for hardware. Australian digital health startups are responding by embedding their algorithms within TGA-registered meter firmware rather than standalone app deployments.
Pharmacy diabetes educators are displacing general practitioner clinics as the primary initiation point for new glucose monitoring patients. Chemist Warehouse and Priceline Pharmacy networks in Queensland and Western Australia are deploying certified educators who configure devices and enroll patients in NDSS subsidy programs during single visits. This channel shift is most visible in Perth's outer metropolitan zones where GP appointment availability constrains traditional care pathways.
Australia Self-Monitoring Blood Glucose Market Segmentation
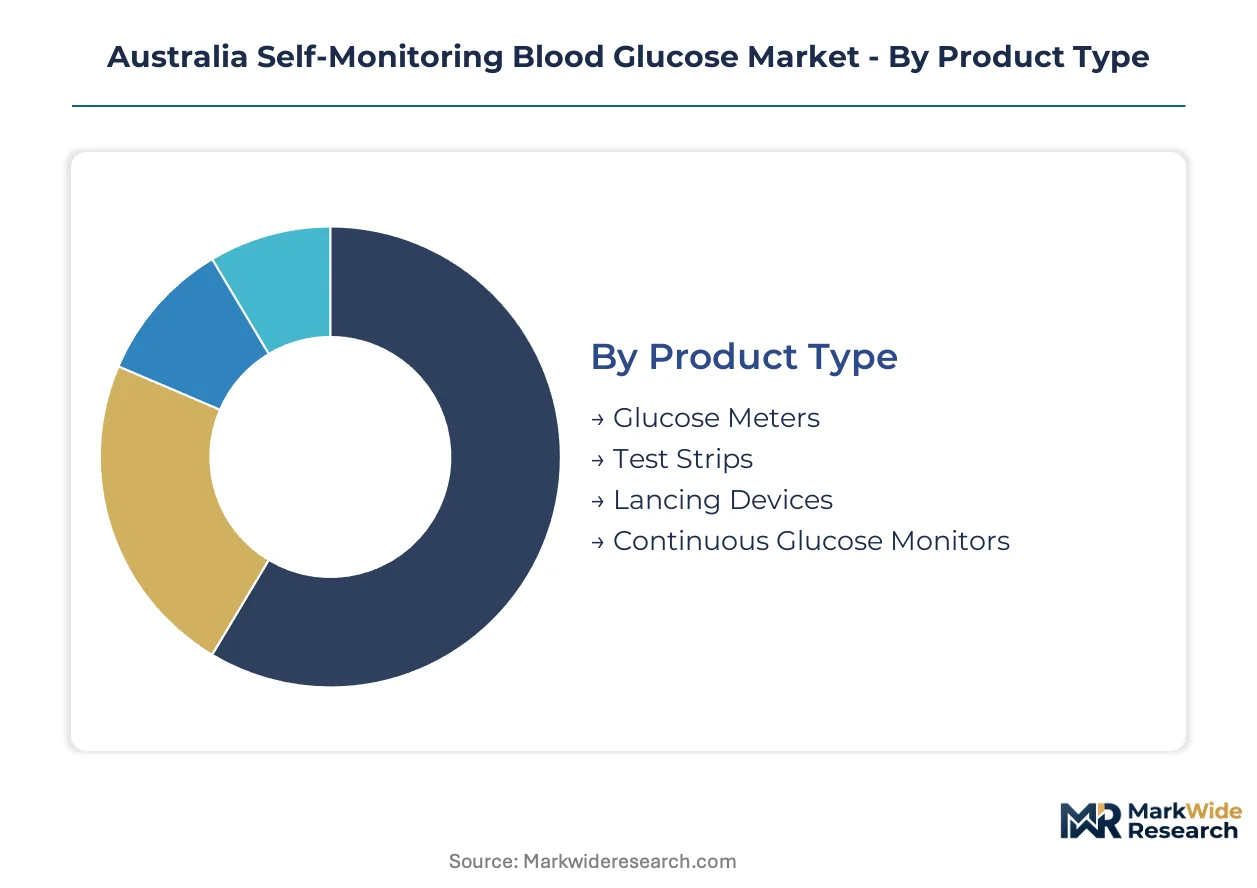
Segmentation in the Australian self-monitoring blood glucose market reveals distinct replacement cycles and reimbursement dependencies that shape inventory planning and channel strategy. Each dimension carries implications for TGA compliance pathways and NDSS subsidy eligibility that vendors must navigate simultaneously.
Product Type:
Replacement velocity varies dramatically across this category, with consumables turning over in weeks while capital equipment persists for years.
- Glucose Meters:Handheld electrochemical analyzers process enzyme-mediated reactions on disposable strips, delivering capillary glucose readings within seconds. Demand clusters among type 2 patients in Queensland and Western Australia where pharmacy educator networks have displaced GP clinics as initiation points.
- Test Strips:Single-use biosensor substrates containing glucose oxidase or dehydrogenase enzymes constitute the highest-volume revenue stream despite margin compression under PBS fixed pricing. Victorian and New South Wales hospitals maintain institutional contracts that sustain volume even as CGM adoption accelerates.
- Lancing Devices:Spring-loaded penetration instruments for capillary blood sampling, typically bundled with meter kits or sold as replacements through retail pharmacy channels.
- Continuous Glucose Monitors:Factory-calibrated fluorescent sensor systems eliminating fingerstick calibration, now reimbursable under expanded NDSS criteria for intensive type 2 cohorts.
Test strips dominate installed base volumes. Continuous glucose monitors are where expansion concentrates most steeply.
End User:
Cost tier stratification separates subsidized patient segments from institutional procurement with distinct pricing elasticity profiles.
- Home Users:Individual diabetes patients managing therapy independently, representing the price-sensitive mass market reached through pharmacy retail and NDSS subsidy enrollment.
- Healthcare Providers:General practitioner and endocrinology clinics prescribing and configuring devices, concentrated in Sydney and Melbourne metropolitan corridors with highest specialist density.
- Pharmacies:Chemist Warehouse and Priceline networks in Queensland and Western Australia now employing certified diabetes educators who handle device configuration and subsidy enrollment.
- Hospitals:Public and private acute care facilities in Victoria and New South Wales deploying centralized monitoring stations for insulin-dependent inpatients and aged care transitions.
Home users anchor volume demand. Healthcare providers are where prescription influence and reimbursement authorization concentrate.
Technology:
Application sophistication separates basic metabolic logging from integrated insulin dosing workflows that command subscription premiums.
- Standard Meters:Conventional electrochemical devices with onboard memory and no connectivity, retaining volume leadership through reimbursement familiarity and lowest patient out-of-pocket cost.
- Smart Meters:Bluetooth-enabled devices transmitting readings to smartphone applications, capturing margin concentration through data platform subscriptions that integrate with telehealth workflows.
- Wireless Technology:Cellular-connected systems enabling remote monitoring by caregivers and clinicians, penetrating Tasmanian rural markets where endocrinology access is most constrained.
- Mobile Apps:Software platforms aggregating multi-device glucose histories, now subject to TGA software-as-a-medical-device classification requiring premarket conformity assessment.
Standard meters retain the broadest installed base. Smart meters and wireless systems are climbing the fastest as telehealth infrastructure matures.
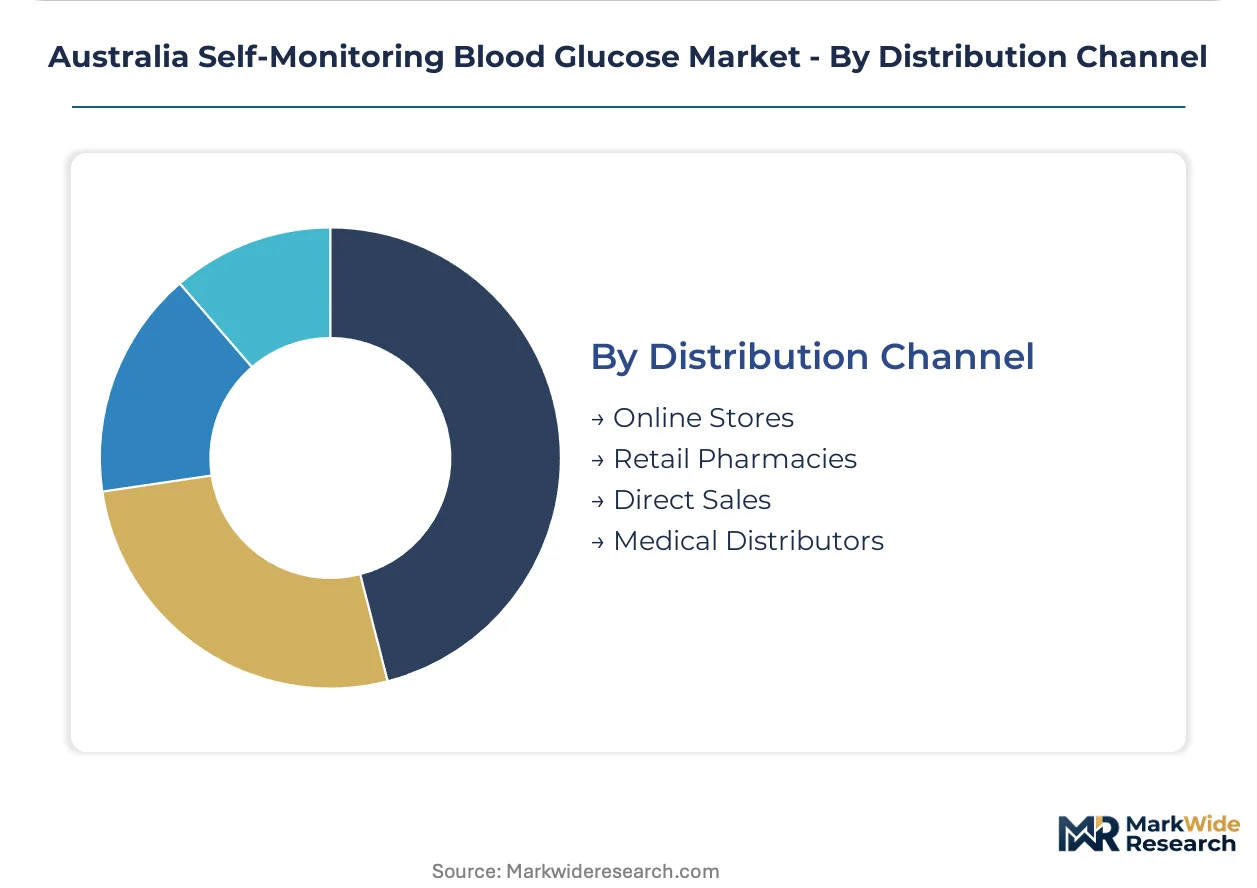
Distribution Channel:
Supply concentration in Port Melbourne import corridors shapes fulfillment economics and inventory risk exposure across channel types.
- Online Stores:Direct-to-consumer e-commerce platforms bypassing pharmacy markup, gaining traction among tech-comfortable type 1 patients seeking CGM subscription renewals.
- Retail Pharmacies:Chemist Warehouse, Priceline and independent pharmacy networks dominating test strip and meter sales through NDSS subsidy processing and educator-staffed consultation.
- Direct Sales:Manufacturer field forces targeting hospital procurement departments and pathology laboratories with volume contract negotiations.
- Medical Distributors:Specialized logistics providers managing temperature-sensitive CGM sensor shipments and institutional inventory for aged care facility deployments.
Retail pharmacies control patient-facing volume. Online stores are gaining share fastest among continuous monitoring subscription renewals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Port Melbourne's container terminal infrastructure processes over 80% of Australia's electrochemical biosensor imports, underwriting the national distribution network for glucose monitoring consumables and capital equipment.
New South Wales
Sydney's endocrinology corridor concentrates the highest specialist density nationally, driving CGM prescription volumes through Royal Prince Alfred Hospital and associated private clinics. The state's Clinical Excellence Commission mandates glycemic control protocols that embed continuous monitoring into insulin-dependent patient pathways. Westmead's biomedical research precinct hosts firmware validation labs serving TGA-registered device manufacturers.
Victoria
Melbourne anchors Australia's medical device manufacturing revival through the Parkville biomedical precinct and Monash Technology Precinct partnerships. The Victorian government's MedTech Manufacturing Voucher program subsidizes local glucose sensor substrate production to reduce import dependency. Clayton's manufacturing corridor houses electrochemical electrode assembly operations supplying domestic meter producers.
Queensland
Brisbane's northern suburbs and Gold Coast corridors exhibit the fastest pharmacy-led diabetes educator penetration, with Chemist Warehouse networks displacing GP clinics as device initiation points. The state's Hospital and Health Services procurement consolidation drives volume contracts for institutional test strip supply. Townsville's rural health districts deploy cellular-connected smart meters to bridge endocrinology access gaps.
Western Australia
Perth's outer metropolitan zones face GP appointment scarcity that accelerates pharmacy educator channel capture for glucose monitoring initiation. The WA Department of Health's chronic disease management framework reimburses telehealth-integrated devices for remote Indigenous community deployment. Fremantle's port facilities handle CGM sensor shipments for distribution across the state's vast geography.
Australia Self-Monitoring Blood Glucose Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in electrode substrates and enzyme formulations. The Australian market exhibits moderate consolidation around four multinational device manufacturers with established TGA registrations and NDSS subsidy pathways, while mid-tier Asian manufacturers compete on test strip cost through parallel import channels. Two strategic archetypes dominate: vertically integrated multinationals controlling sensor-to-software stacks, and regional component suppliers feeding white-label meter assembly. Competitive moves concentrate on TGA approval velocity for integrated CGM systems and pharmacy educator network exclusivity arrangements.
Among the multinational platform tier, Abbott Diabetes Care, Roche Diabetes Care, and LifeScan exemplify contrasting channel strategies. Abbott leverages extensive pharmacy distribution networks across Australian capital cities. Roche anchors hospital and pathology channel relationships that sustain institutional test strip volumes. LifeScan competes through brand recognition among type 2 diabetes patients managing therapy independently.
| Leading Market Players |
|---|
| Abbott Diabetes Care |
| Roche Diabetes Care |
| LifeScan |
| Ascensia Diabetes Care |
| Arkray Inc |
| Trividia Health |
| Acon Laboratories Inc |
| Bionime Corporation |
| Agamatrix Inc |
| Others |
Supply Flow & Price Mechanics
Asian electrochemical biosensor substrate manufacturing clusters feed over 80% of Australian glucose monitoring consumables through Port Melbourne, concentrating margin capture with distributors who control import logistics and NDSS subsidy processing networks.
Pricing Analysis
The Pharmaceutical Benefits Scheme dictates the pricing tier structure for test strips through fixed reimbursement schedules that compress manufacturer margins despite raw material volatility. Three-tier pricing structure across premium CGM subscriptions, standard smart meters, and economy standalone devices separates subscription-linked data platforms from transactional strip sales. Cost compression in the test strip tier is intensifying because PBS price ceilings lag enzyme and electrode input cost movements. Home users managing type 2 diabetes independently exhibit highest price sensitivity, while intensive insulin-dependent cohorts accessing NDSS-subsidized continuous monitoring show lowest elasticity.
Supply Chain Analysis
Extended payment terms from 90 to 120 days characterize distributor-manufacturer arrangements as working capital pressure mounts through the import corridor. Supply draws from concentrated manufacturing bases in China, South Korea, and Taiwan for electrochemical electrodes, enzyme formulations, and plastic molding components. Single-source vulnerability sits with the Port Melbourne container terminal chokepoint that processes the majority of temperature-sensitive CGM sensor shipments. Distribution runs through pharmacy retail networks that double as NDSS enrollment points, consolidating patient-facing fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australian self-monitoring blood glucose market sits at an inflection where TGA software-as-a-medical-device classification and NDSS continuous monitor expansion are collapsing traditional test strip economics while elevating platform-integrated device architectures.
For Market Incumbents: Harden pharmacy educator network exclusivity through certified training program investments that lock Chemist Warehouse and Priceline channels against emerging CGM competitors. Deepen backward integration into electrode substrate production via Melbourne biomedical precinct partnerships to offset import dependency exposure. Anchor hospital pathology contracts with volume guarantees that sustain institutional test strip flows despite continuous monitoring substitution. For New Entrants and Emerging Players: Tasmanian rural health districts with dispersed populations and constrained endocrinology access represent the most penetrable entry point for cellular-connected smart meter deployments paired with telehealth integration. Western Australian outer metropolitan zones facing GP appointment scarcity offer secondary whitespace for pharmacy-led device initiation programs. Pursue TGA software-as-a-medical-device premarket clearance for glucose data analytics platforms embedded within registered meter firmware rather than standalone applications. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-tier Asian test strip manufacturers supplying parallel import channels under price pressure from PBS reimbursement compression. Long-term viability across the analysis window favors platform-integrated device developers with recurring sensor subscription revenue over transactional strip economics. Monitor TGA approval velocity for automated insulin delivery interoperability standards as signal for pump-convergence investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| TGA Software-as-a-Medical-Device Clearance | Smartphone glucose analytics platforms face premarket scrutiny previously reserved for hardware devices. |
| NDSS Continuous Monitor Eligibility Expansion | Intensive type 2 patient access to factory-calibrated CGM systems redirects margin from strips to subscriptions. |
| Pharmacy Diabetes Educator Network Deployment | Chemist Warehouse and Priceline certification programs displace GP clinics as device initiation points. |
| Melbourne Biomedical Precinct Manufacturing Investment | Local electrode substrate production reduces Port Melbourne import dependency for domestic meter assembly. |
| My Health Record API Integration Development | Australian Digital Health Agency data sharing expansion enables multi-device glucose history aggregation platforms. |
Methodological Framework
Desk research of TGA medical device registration databases, NDSS subsidy policy documents, and hospital procurement contract disclosures preceded structured interviews with endocrinology practice managers, pharmacy diabetes educators, biomedical firmware engineers, and medical device regulatory affairs specialists. Primary fieldwork with Melbourne biomedical precinct manufacturing partners and Port Melbourne logistics operators validated import corridor economics. Secondary sources included Therapeutic Goods Administration adverse event reporting systems, Pharmaceutical Benefits Scheme pricing schedules, and Australian Digital Health Agency interoperability frameworks. Bottom-up patient population modeling and top-down reimbursement expenditure analysis were triangulated against device shipment data.
Assumptions held fixed across the modeling period include TGA regulatory pathway stability, NDSS subsidy eligibility criteria evolution toward continuous monitoring, and telehealth infrastructure permanence under Medicare item numbers. Segmentation dimensions modeled encompass product type replacement cycles, technology connectivity tiers, end-user cost stratification, and distribution channel reimbursement processing capabilities. CAGRs were derived from installed base turnover rates and upgrade cycle compression under expanded CGM access. Forecast inputs incorporated enzyme raw material cost trajectories and maritime freight rate volatility through the Port Melbourne corridor.
Macroeconomic conditions sit as an overlay; deviation in Australian dollar exchange rates against Asian manufacturing currencies or maritime shipping cost indices would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway timelines and reimbursement policy continuity. Technological disruption from non-invasive optical sensing alternatives or regulatory restriction on software-as-a-medical-device classification would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Japan Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Global Diabetes Pen Market
Diabetes Care
South Korea Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Digital Diabetes Care Market
Diabetes Care
Oman Diabetes Drugs Market
Diabetes Care
Continuous Glucose Monitoring Device Market
Diabetes Care
United Kingdom Blood Glucose Monitoring Market
Diabetes Care
Wearable Glucometers Market
Diabetes Care
Global Smart Insulin Pens Market
Diabetes Care
Germany Insulin Infusion Pump Market
Diabetes Care
Egypt Diabetes Care Devices Market
Diabetes Care
Asia Pacific Blood Glucose Test Strip Market
Diabetes Care
Mexico Diabetes Medication Market
Diabetes Care
Asia-Pacific Insulin Delivery Devices Market
Diabetes Care
Hyperinsulinemia Hypoglycaemia Treatment Market
Diabetes Care
Vietnam Diabetes Care Devices Market