
 Ambulatory Healthcare Service Market | 2026-2036
Ambulatory Healthcare Service Market Size, Share, and Industry Trends Forecast 2026-2036
Ambulatory Healthcare Service Market Analysis
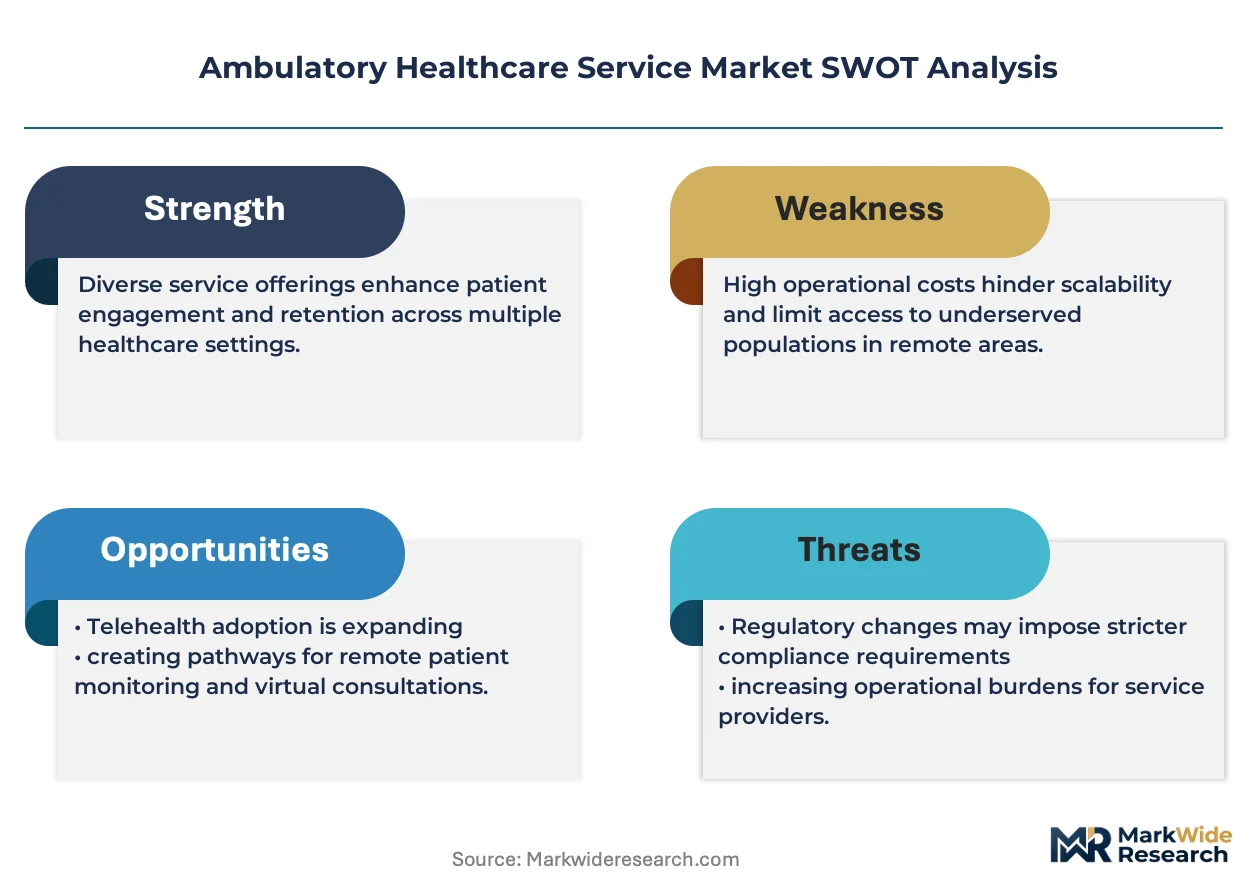
The gap between premium multi-specialty ambulatory networks and commodity single-service clinics is restructuring competitive economics in outpatient care. HCA Healthcare leverages its scale across hundreds of freestanding emergency rooms and surgery centers to sustain geographic density that community hospitals struggle to match. Tenet Healthcare anchors its ambulatory strategy through United Surgical Partners International, which operates one of the largest networks of outpatient facilities in the United States. Surgery Partners competes on procedural focus, concentrating on high-volume orthopedic and gastrointestinal services that generate predictable throughput.
Ambulatory healthcare services encompass outpatient medical care delivered in non-hospital settings, including diagnosis, treatment, surgical intervention, and rehabilitation administered through facilities designed for same-day discharge and reduced infection exposure. These services employ standardized clinical protocols, electronic health record integration, and lean staffing models to achieve cost structures typically 40-60% below equivalent inpatient procedures. Specialty care and urgent care segments lead volume expansion as patient preferences shift toward convenience-accessible delivery models, while value-based care and bundled payment service models capture disproportionate margin pools by aligning provider incentives with outcome efficiency. Telemedicine infrastructure within the technology segment supports hybrid virtual-physical workflows that extend reach into underserved catchment areas.
The Centers for Medicare and Medicaid Services (CMS) in the United States drives site-neutral payment policies that compress reimbursement differentials between hospital outpatient departments and independent ambulatory centers, accelerating capital migration toward freestanding models. FDA oversight of ambulatory surgical equipment and OSHA workplace safety standards for clinical staff shape operational compliance burdens that favor scaled operators with dedicated regulatory infrastructure. State-level certificate-of-need requirements in approximately two-thirds of US jurisdictions create localized barriers to entry that incumbent networks exploit to defend market position. Stakeholders must monitor whether Medicare's continued expansion of approved procedures for ambulatory settings outpaces workforce supply constraints in nursing and anesthesia specialties.
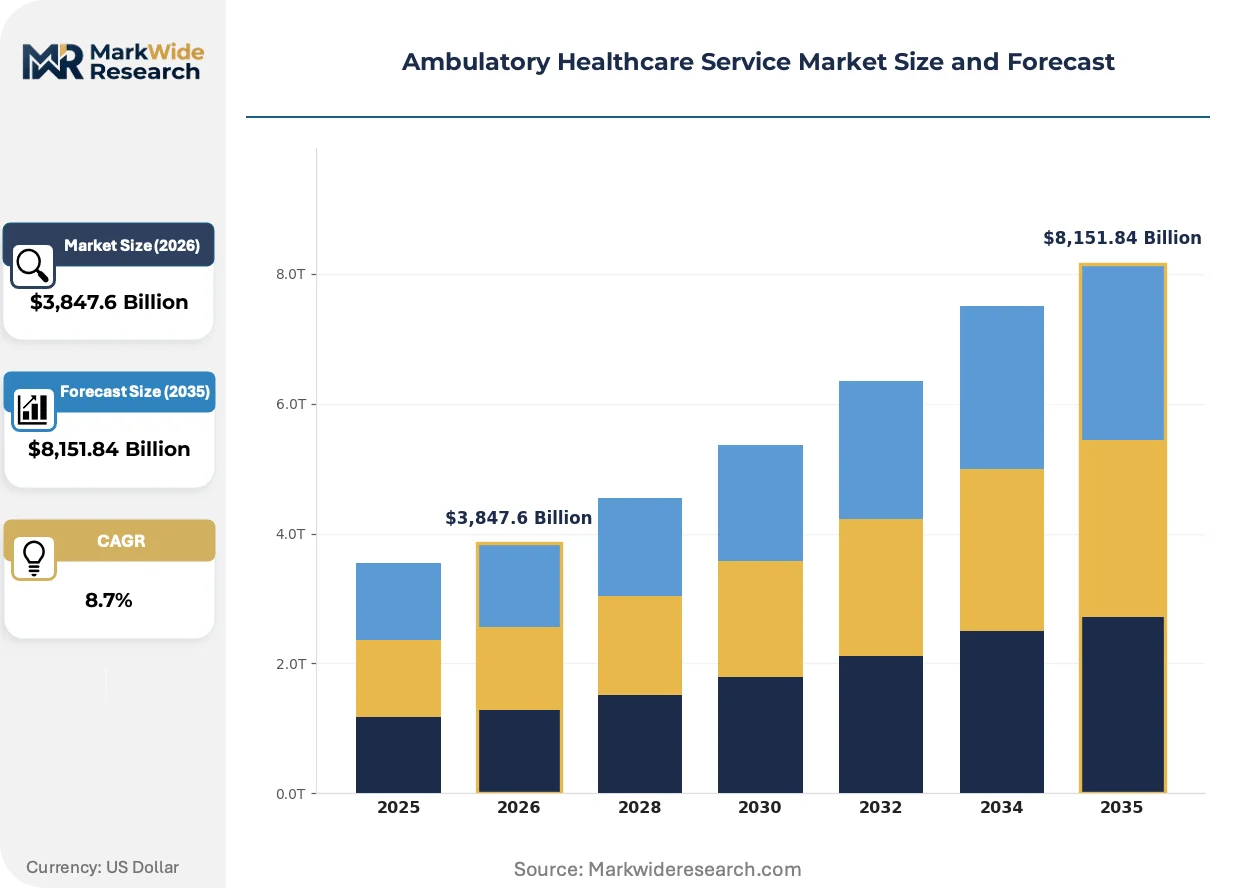
Market Dynamics
Medicare's site-neutral payment policies are compressing reimbursement differentials between hospital outpatient departments and independent ambulatory centers, redirecting capital flows and patient volumes toward freestanding facilities.
Growth Catalysts
- CMS Site-Neutral Reimbursement:Payment parity between hospital outpatient departments and independent ambulatory centers eliminates financial incentives for inpatient settings, accelerating facility migration.
- Aging Demographics:Elderly patients require higher-frequency chronic disease management and elective procedures suited to same-day discharge protocols.
- Minimally Invasive Surgical Techniques:Laparoscopic and endoscopic innovations expand procedure eligibility for ambulatory settings previously requiring overnight observation.
Market Restraints
- Certificate-of-Need Requirements:Approximately two-thirds of US jurisdictions maintain CON laws that restrict new facility entry and protect incumbent geographic monopolies.
- Anesthesia Workforce Constraints:Limited CRNA and anesthesiologist supply creates bottlenecks for procedure expansion in high-growth markets.
- Capital Intensity of Accreditation:AAAHC and Joint Commission certification requirements demand sustained infrastructure investment that disadvantages smaller operators.
Strategic Opportunities
- Rural Underserved Catchments:Telemedicine-integrated micro-hospitals and freestanding emergency rooms extend specialist access to communities beyond hospital network reach.
- Bundled Payment Pilots:CMS voluntary bundled payment models for orthopedic and cardiac episodes align provider incentives with outcome efficiency, capturing margin pools.
- Hybrid Virtual-Physical Workflows:Remote patient monitoring platforms combined with in-person procedural sites create continuous care models for chronic disease populations.
Industry Challenges
- EHR Interoperability Friction:Integration between ambulatory-specific systems and hospital-based electronic health records creates data continuity risks across care transitions.
- Nursing Supply Compression:Preoperative and recovery staffing shortages constrain throughput expansion despite physical capacity availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ambulatory Healthcare Service Market |
| Market Size in 2026 | $3,847.6 Billion |
| Market Size in 2035 | $8,151.84 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Urgent Care, Primary Care, Specialty Care, Rehabilitation End User: Outpatients, Elderly Patients, Rehabilitation Patients, Pediatric Patients Technology: Telemedicine, Mobile Health Solutions, Remote Monitoring, Electronic Health Records Service Model: Fee-for-Service, Value-Based Care, Bundled Payments, Capitation |
| Companies Covered | HCA Healthcare, Tenet Healthcare, Surgery Partners, Surgical Care Affiliates, United Surgical Partners International, AmSurg, UnitedHealth Group, Community Health Systems, DaVita, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ambulatory Healthcare Service Market Emerging Trajectories
Workflow digitization and regulatory payment reform are restructuring how ambulatory services are delivered, measured, and reimbursed. Three distinct movements are reshaping competitive positioning.
Robotic-assisted surgical platforms are overtaking conventional laparoscopic equipment in high-volume orthopedic and gastrointestinal procedures. Ambulatory surgery centers with capital access are deploying these systems to attract surgeon loyalty and justify premium facility fees. The technology is overtaking manual techniques as the standard of care for joint replacement and hernia repair, compressing recovery timelines and expanding same-day discharge eligibility.
CMS site-neutral payment policies eliminate reimbursement premiums previously attached to hospital outpatient department procedures. The industrial consequence is accelerated capital migration toward independent ambulatory facilities with leaner cost structures. United States-based multi-specialty networks are responding by consolidating independent surgery centers to capture volume displaced from hospital settings.
Patients are selecting providers based on transparent episode pricing and convenience metrics rather than institutional brand recognition. Direct-to-employer contracting and reference-based pricing models are displacing traditional payer network arrangements in self-insured populations. This behavioral shift is most visible in Texas and Florida, where large employer coalitions negotiate directly with ambulatory networks for bundled surgical episodes.
Ambulatory Healthcare Service Market Segmentation
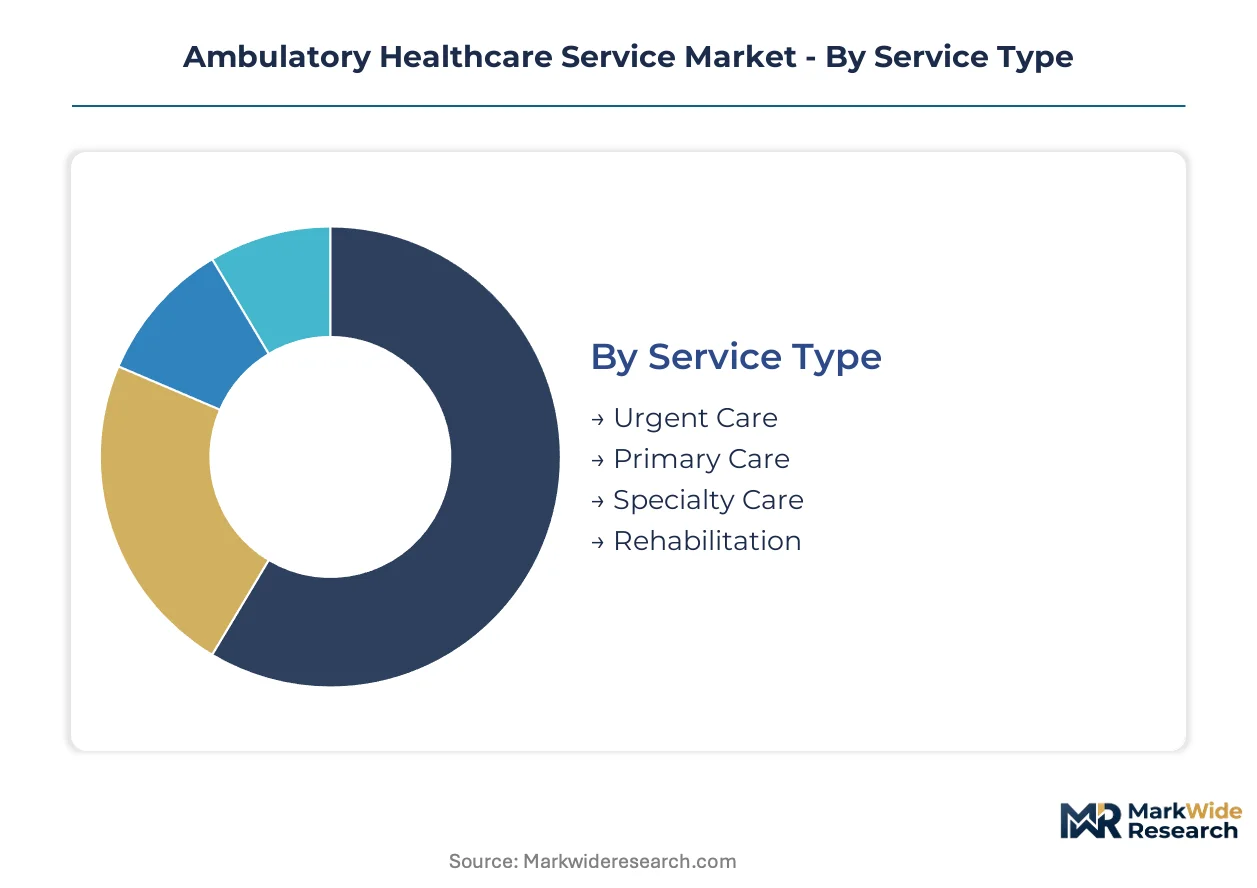
Ambulatory healthcare services fragment across multiple operational dimensions that determine reimbursement mechanics, capital requirements, and patient throughput economics. Service type and technology infrastructure together shape which operators capture margin pools versus commodity positioning.
Service Type:
Clinical intensity and procedural complexity define the technology and staffing specifications for each service category.
- Specialty Care:Concentrates advanced procedures—orthopedic, gastrointestinal, ophthalmologic—that leverage minimally invasive surgical platforms and same-day discharge protocols. Demand clusters in metropolitan United States corridors where surgeon density supports high-volume centers and CMS site-neutral policies redirect cases from hospital outpatient departments.
- Urgent Care:Delivers episodic treatment for acute non-life-threatening conditions through standardized triage protocols and point-of-care diagnostics. Volume concentrates in suburban United States markets with employer-sponsored populations seeking after-hours access outside emergency room cost structures.
- Primary Care:Manages chronic disease prevention and routine health maintenance through scheduled encounters.
- Rehabilitation:Provides post-acute physical, occupational, and speech therapy services.
Specialty Care leads on scale; Urgent Care leads on momentum.
End User:
Patient acuity and demographic profile drive utilization patterns and reimbursement rate differentials across ambulatory settings.
- Elderly Patients:Generate highest-frequency utilization for chronic disease management, elective procedures, and post-acute transitions. Medicare enrollment expansion and aging United States demographics concentrate demand in cardiology, orthopedics, and pain management services suited to ambulatory protocols.
- Outpatients:Encompass the broad commercially insured and Medicare Advantage populations seeking scheduled elective procedures. United States employer-sponsored plans increasingly steer volume toward ambulatory surgery centers through narrow network designs and reference-based pricing arrangements.
- Rehabilitation Patients:Require coordinated post-surgical or post-acute therapy regimens.
- Pediatric Patients:Demand specialized clinical environments and family-centered care models.
Elderly Patients anchor volume concentration; Outpatients drive commercial rate capture.
Technology:
Digital infrastructure maturity separates high-throughput operators from capacity-constrained competitors.
- Telemedicine:Enables synchronous virtual consultations, specialist triage, and remote preoperative assessments that extend geographic reach beyond physical facility footprints. United States rural health clinics and micro-hospital networks deploy telemedicine to maintain specialist access without full-time staffing costs.
- Remote Monitoring:Captures continuous physiologic data from implantable devices and wearable sensors to flag deterioration before acute events. Cardiac and orthopedic ambulatory programs in the United States integrate remote monitoring to satisfy CMS bundled payment quality thresholds and reduce readmission penalties.
- Mobile Health Solutions:Delivers asynchronous patient engagement and medication adherence tools.
- Electronic Health Records:Underpins clinical documentation, billing accuracy, and interoperability with hospital systems.
Telemedicine commands installed base; Remote Monitoring climbs the fastest.
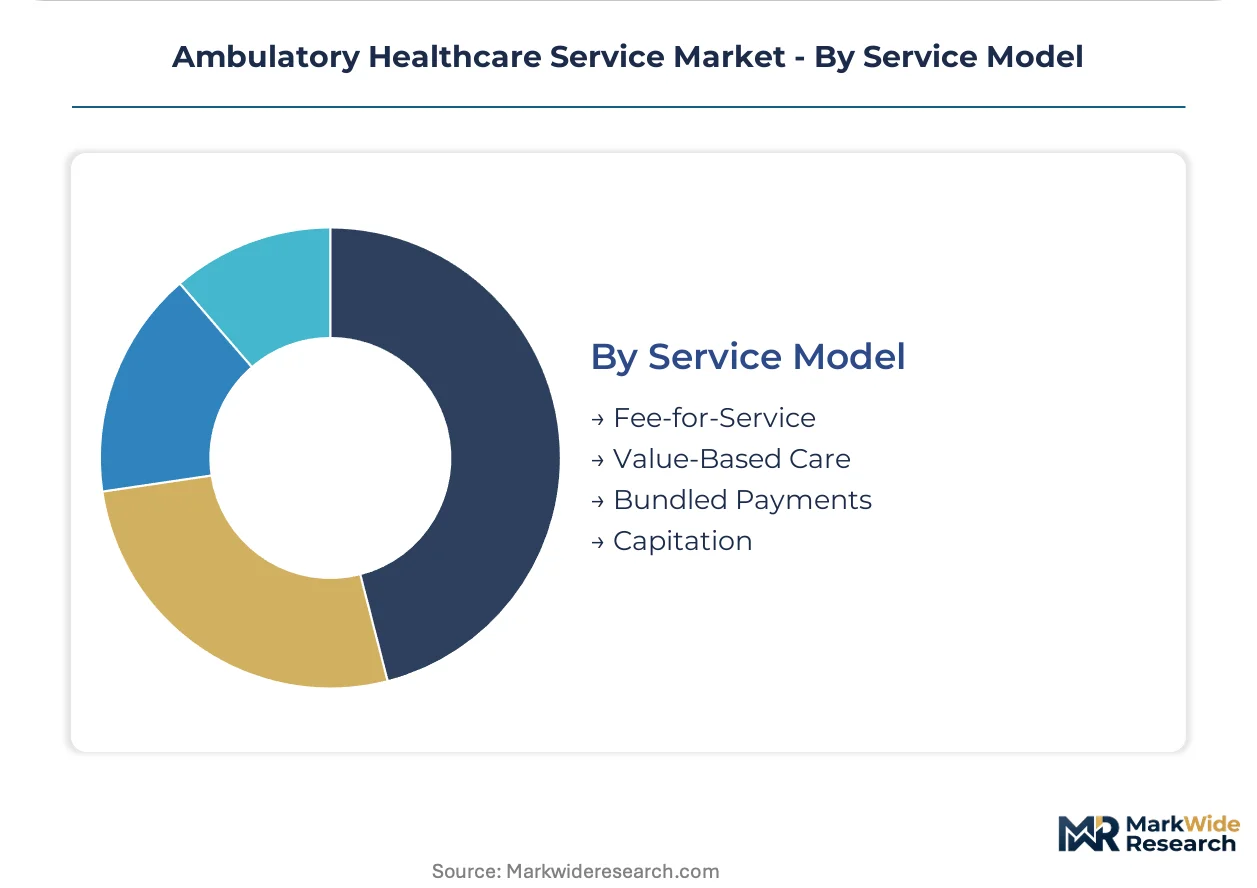
Service Model:
Reimbursement mechanism determines risk allocation between payer and provider, shaping capital deployment and operational design.
- Value-Based Care:Ties reimbursement to quality metrics, patient outcomes, and total cost of episode management. United States Medicare Advantage contracts and commercial ACO arrangements reward ambulatory networks that reduce avoidable utilization through care coordination and preventive intervention.
- Bundled Payments:Packages all services—surgical, anesthesia, facility, post-acute—into single prospective rates for defined episodes. CMS voluntary pilot programs for orthopedic and cardiac procedures in the United States favor ambulatory centers with lean cost structures and predictable throughput.
- Fee-for-Service:Compensates each discrete service encounter at negotiated rates.
- Capitation:Assigns fixed per-member-per-month payments for comprehensive care responsibility.
Value-Based Care captures margin expansion; Bundled Payments gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands the largest ambulatory healthcare footprint globally, while Germany and Japan are accelerating facility expansion to manage aging populations. Regulatory payment reforms in each market are redirecting surgical volumes from inpatient to outpatient settings.
United States
Medicare site-neutral policies and employer-sponsored narrow networks concentrate demand in freestanding surgery centers across Texas and Florida. CMS continues expanding approved procedure lists for ambulatory settings while certificate-of-need laws in two-thirds of states protect incumbent geographic positions. The Dallas-Fort Worth corridor hosts dense multi-specialty networks competing on bundled episode pricing for orthopedic and gastrointestinal procedures.
Germany
Outpatient surgery reimbursement parity and statutory health insurance cost pressures are accelerating ambulatory facility investment in Bavaria and North Rhine-Westphalia. The EMA's streamlined medical device approvals enable faster adoption of minimally invasive surgical platforms in independent centers. Munich's ambulatory surgery clusters attract cross-border patients from Austria and Switzerland seeking reduced wait times for elective joint replacement.
Japan
Revised fee schedules under universal health coverage are elevating same-day surgery eligibility for cataract and endoscopic procedures in Kanto and Kansai regions. METI's healthcare productivity initiatives support digital infrastructure deployment in outpatient clinics facing nursing workforce constraints. Tokyo's specialty ambulatory networks integrate remote monitoring to manage post-operative cardiac patients outside hospital settings.
United Kingdom
NHS England's elective recovery program targets 75% of surgical procedures for same-day discharge by 2028, redirecting capital toward independent sector treatment centers. CQC accreditation standards and procurement frameworks favor scaled operators with integrated electronic health record systems. London's independent ambulatory networks contract directly with NHS trusts to clear procedural backlogs in ophthalmology and orthopedics.
Canada
Provincial health authority outsourcing of elective procedures is expanding independent ambulatory surgery capacity in Ontario and British Columbia. Health Canada's streamlined medical device licensing supports faster deployment of robotic-assisted surgical platforms in outpatient settings. Toronto's ambulatory networks leverage proximity to academic medical centers for anesthesia coverage and emergency backup protocols.
Ambulatory Healthcare Service Market Vendor Landscape
Top-tier vendors anchor multi-specialty networks with geographic density advantages, while mid-tier operators compete on procedural focus and regional concentration. The market structure stratifies across three archetypes: scaled hospital-affiliated platforms, independent surgery center consolidators, and single-specialty focused operators. Dominant competitive moves include facility network consolidation through acquisition and direct-to-employer contracting for bundled surgical episodes.
Within the hospital-affiliated tier, HCA Healthcare exemplifies geographic density strategy across freestanding emergency and surgical assets, while Tenet Healthcare occupies a position through United Surgical Partners International's outpatient facility network. Surgery Partners represents the procedural focus archetype, anchoring high-volume orthopedic and gastrointestinal service lines that generate predictable throughput metrics. These three operators collectively illustrate how scale, affiliation structure, and service concentration define competitive positioning in site-neutral reimbursement environments.
| Leading Market Players |
|---|
| HCA Healthcare |
| Tenet Healthcare |
| Surgery Partners |
| Surgical Care Affiliates |
| United Surgical Partners International |
| AmSurg |
| UnitedHealth Group |
| Community Health Systems |
| DaVita |
| Others |
Supply Flow & Price Mechanics
Self-insured employer coalitions in Texas and Florida concentrate purchasing power around bundled episode pricing, forcing ambulatory networks to compete on transparent cost-per-procedure metrics rather than institutional brand premiums. This buyer concentration rewards operators with lean cost structures and penalizes hospital-affiliated outpatient departments facing site-neutral reimbursement compression.
Pricing Analysis
Bundled payment pilots for orthopedic and cardiac episodes now compete against traditional fee-for-service arrangements across United States ambulatory markets. Price differentiation hinges on Joint Commission accreditation tier and geographic proximity to metropolitan surgical clusters. Cost compression in single-specialty clinics intensifies as UnitedHealth Group and other payers narrow network designs to capture reference-based pricing savings. Commercially insured outpatients exhibit highest price sensitivity, while Medicare Advantage populations prioritize access convenience over episode cost.
Supply Chain Analysis
Regional distribution centers for surgical equipment and implantable devices follow hub-and-spoke patterns anchored in Dallas-Fort Worth, Munich, and Tokyo metropolitan clusters. Supply concentration centers on United States, Germany, and Japan for robotic-assisted surgical platforms and minimally invasive instrument sets. Raw material dependencies include titanium alloys for orthopedic implants, specialized polymers for endoscopic devices, and semiconductor components for navigation systems. Single-source vulnerability in CRNA staffing agencies creates anesthesia coverage bottlenecks. Distribution runs through manufacturer-direct channels to ambulatory surgery centers, bypassing traditional hospital procurement intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ambulatory healthcare service market functions as a geographic-arbitrage play where site-neutral Medicare reimbursement in the United States creates cost advantages against hospital outpatient departments, while Germany's statutory health insurance pressures accelerate independent facility investment relative to neighboring European markets.
For Market Incumbents: Hedge against anesthesia workforce constraints by securing exclusive CRNA staffing contracts and deploying telemedicine preoperative assessments to extend specialist reach without full-time hiring. Consolidate independent surgery centers in certificate-of-need states to defend geographic monopolies against new entrants. Backward integration into remote patient monitoring platforms captures CMS bundled payment quality bonuses and reduces readmission penalties. For New Entrants and Emerging Players: The price-point gap between premium multi-specialty networks and commodity urgent care clinics creates entry space for mid-tier procedural focus operators. Rural underserved catchments in certificate-of-need states offer protected expansion zones where telemedicine-integrated micro-hospitals bypass incumbent hospital network reach. Target direct-to-employer contracting in self-insured Texas and Florida markets as the primary go-to-market channel. For Investors and Strategic Acquirers: Private equity firms specializing in healthcare services are the most active acquirer in this space, drawn by predictable cash flows and reimbursement tailwinds. The long-term viability window favors platforms with demonstrated bundled payment execution and EHR interoperability infrastructure. Acquisition target archetypes include single-specialty orthopedic or gastrointestinal centers with surgeon equity participation. Watch CMS expansion of ambulatory-approved procedure lists as the inflection signal for volume migration acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CMS Bundled Payment Participation | Aligns provider incentives with outcome efficiency and captures margin pools in orthopedic episodes. |
| Telemedicine Infrastructure Deployment | Extends specialist access into rural catchments beyond hospital network geographic density. |
| Certificate-of-Need State Consolidation | Exploits regulatory barriers to defend market position against new facility entry. |
| Surgeon Equity Partnership Structures | Locks procedural volume through ownership alignment and reduces competitive poaching risk. |
| Remote Patient Monitoring Integration | Satisfies CMS quality thresholds and reduces readmission penalties in cardiac programs. |
Methodological Framework
Bottom-up patient volume modeling reconciled against top-down facility capacity tracking forms the analytical core of this study. Primary interviews with ambulatory surgery center administrators, hospital outpatient department directors, GPO contracts managers, and CMS policy specialists were combined with secondary validation from CMS Medicare cost reports, state certificate-of-need filings, and hospital procurement databases. Triangulation across stakeholder perspectives and data sources ensures cross-verified demand and supply estimates.
Input-output matrices map procedure volume by service type against staffing capacity, equipment utilization rates, and reimbursement rate differentials across the projection horizon. Segmentation dimensions include clinical intensity tier, technology infrastructure maturity, payer mix composition, and geographic regulatory cluster. CAGRs were derived from procedure volume growth trajectories and site-neutral policy implementation timelines. Forecast inputs incorporate minimally invasive surgical platform adoption curves and anesthesia workforce supply projections.
The model assumes a particular technology adoption path; alternative pathways for robotic-assisted surgical platforms would alter the outlook if capital constraints delay deployment in mid-tier facilities. Forecasts reflect documented assumptions around CMS reimbursement expansion and state-level regulatory stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Australia Senior Living Market
Healthcare Services
Healthcare Staffing Market
Healthcare Services
Sterilization Services Market
Healthcare Services
Medical Peer & External Physician Review Services Market
Healthcare Services
Global Infusion Pharmacy Management Market
Healthcare Services
IVD Contract Manufacturing Services Market
Healthcare Services
Inhaled and Intranasal Products Contract Service Providers Market
Healthcare Services
Biopharmaceutical Third Party Logistics (3PL) Market
Healthcare Services
Vaccine Logistics Market
Healthcare Services
Healthcare CMO Market
Healthcare Services
Assisted Living Market
Healthcare Services
Hospital Workforce Management Market
Healthcare Services
Hair Transplant Services Market
Healthcare Services
Primary Care Physicians Market
Healthcare Services
Packaging and Labeling (Healthcare) Services Market
Healthcare Services
Retail Clinics Market