
 Venous Reservoirs Market | 2026-2036
Venous Reservoirs Market Size, Share, and Industry Trends Forecast 2026-2036
Venous Reservoirs Market Analytics
MDR is realigning the cost-of-entry calculus for venous reservoir manufacturers serving European cardiac surgery centers. Medtronic plc leverages its integrated perfusion portfolio to sustain premium positioning across major hospital systems. LivaNova PLC anchors its competitive stance through specialized cardiac reservoir designs that dominate high-volume bypass procedures. Getinge AB differentiates via manufacturing scale and channel control in the mechanical technology segment.
Venous reservoirs are sterile, blood-contacting containers typically constructed from medical-grade polycarbonate or polyvinyl chloride, engineered to store and filter venous blood during cardiopulmonary bypass procedures while maintaining precise volume monitoring and air elimination. These devices integrate with oxygenators and pumps to ensure uninterrupted extracorporeal circulation, with functional parameters including prime volumes ranging from 800 mL to 4000 mL and filtration thresholds of 20-40 microns. Cannulation reservoirs occupy the largest share of the product type landscape due to their ubiquity in routine bypass surgeries, while automated technology represents the fastest-expanding segment as perfusionists seek reduced manual intervention and enhanced safety algorithms. Single-use delivery mode commands the dominant volume position, though reusable configurations retain niche appeal in cost-constrained surgical centers where sterilization infrastructure supports circular workflows.
FDA 510(k) clearance pathways and ISO 10993 biocompatibility standards govern market access for US and international manufacturers, with the former dictating clinical validation requirements and the latter defining material cytotoxicity and hemocompatibility benchmarks. The EU MDR intensifies post-market surveillance obligations, forcing reservoir producers to maintain exhaustive clinical follow-up data and updated technical documentation. Stakeholders must monitor evolving automated perfusion protocols and decide whether to invest in electronic sensor integration or preserve mechanical simplicity for emerging market penetration.
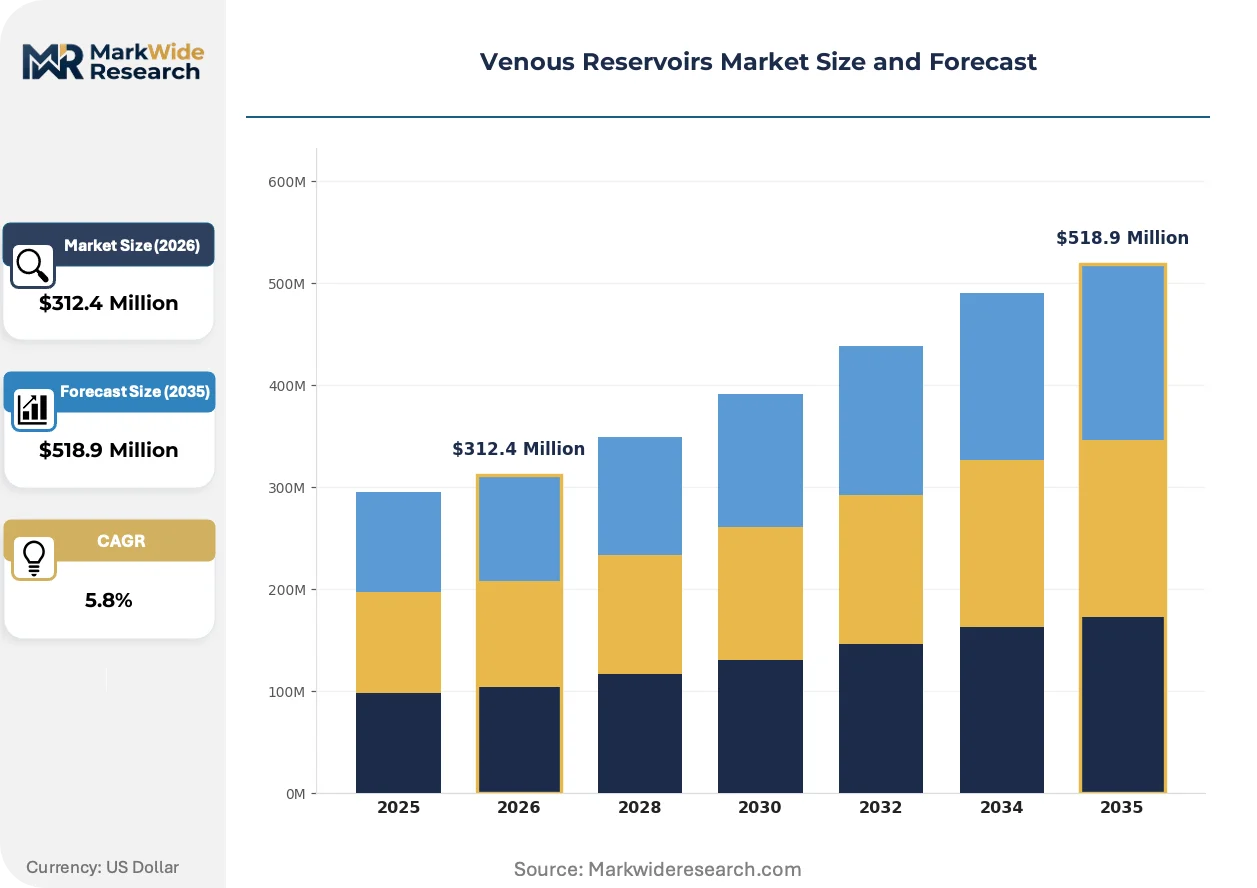
Market Dynamics
The EU MDR's intensified biocompatibility surveillance is forcing venous reservoir manufacturers to rebuild their clinical evidence portfolios and technical documentation from the ground up, compressing margins for mid-tier suppliers while favoring integrated perfusion system vendors with established regulatory infrastructure.
Growth Catalysts
- Automated Perfusion Protocols:Perfusionists at high-volume cardiac centers are demanding reservoirs with embedded electronic sensors and safety algorithms that reduce manual air-handling interventions during bypass procedures.
- EU MDR Compliance:The regulation's expanded post-market surveillance requirements are accelerating consolidation toward manufacturers with dedicated clinical affairs teams and robust technical file management systems.
- German Cardiac Center Modernization:Specialized centers in Munich, Berlin, and Heidelberg are replacing legacy mechanical reservoirs with integrated systems that support minimally invasive cardiac surgery workflows.
Market Restraints
- Medical-Grade Polymer Cost Volatility:Polycarbonate and polyvinyl chloride feedstock prices fluctuate with petrochemical markets, squeezing margins for single-use disposable producers without long-term supply agreements.
- Concentrated Component Sourcing:Precision filtration membranes and specialized venous ports rely on a limited supplier base concentrated in Southern Germany and Northern Italy, creating vulnerability to regional logistics disruptions.
- Reusable System Substitution:Cost-constrained surgical centers in Eastern European markets retain sterilizable reservoir configurations, limiting addressable market expansion for premium single-use technologies.
Strategic Opportunities
- Pediatric Perfusion Expansion:Neonatal and infant cardiac surgery programs in Poland and the Czech Republic lack appropriately sized reservoirs with sub-800 mL prime volumes, creating white space for specialized product development.
- Sensor-Oxygenator Convergence:Integration of real-time hematocrit and venous oxygen saturation monitoring into reservoir housings is unifying two discrete device categories into single-platform solutions.
- Green Procurement Mandates:The EU Green Deal's medical device sustainability criteria are creating preference for manufacturers with validated recycling pathways for polycarbonate components.
Industry Challenges
- Perfusionist Talent Scarcity:The specialized training required for automated system operation is outpacing certification program output in several EU member states, limiting technology adoption velocity.
- Legacy System Integration Friction:Tertiary hospitals with decade-old oxygenator-pump configurations face substantial capital and workflow reconfiguration costs when upgrading to integrated reservoir platforms.
- MDR Technical Documentation Burden:The regulation's requirement for continuous clinical follow-up data is extending product lifecycle management costs across the 10-15 year commercialization horizon.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Venous Reservoirs Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cannulation Reservoirs, Cardiac Reservoirs, Dialysis Reservoirs, Surgery Reservoirs Technology: Mechanical, Electronic, Automated, Hybrid End User: Hospitals, Surgical Centers, Dialysis Clinics, Emergency Units Delivery Mode: Single-Use, Reusable, Portable, Integrated |
| Companies Covered | Medtronic plc, LivaNova PLC, Getinge AB, Terumo Corporation, MicroPort Scientific Corporation, Braile Biomédica, Nipro Corporation, OriGen Biomedical, Inc., Abbott, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Venous Reservoirs Market Evolving Landscape
Perfusion technology is converging around platforms that embed intelligence directly into blood-contacting components, compressing the traditional separation between passive reservoirs and active monitoring systems.
Integrated sensor arrays are unifying volume measurement, air detection, and blood parameter monitoring within single reservoir housings. German cardiac surgery centers are adopting these platforms fastest, driven by MDR-mandated risk management documentation that favors closed-loop systems with automated alarm protocols. This convergence is compressing demand for standalone mechanical reservoirs and favoring suppliers with embedded software development capabilities.
The EU MDR's biocompatibility testing expansion is requiring reservoir manufacturers to submit exhaustive ISO 10993-5 cytotoxicity and hemocompatibility data for every material change. This regulatory burden is forcing mid-tier producers to abandon incremental product iterations and concentrate resources on platform-level redesigns. High-volume bypass procedure segments are responding by consolidating supplier relationships toward vendors with dedicated regulatory affairs infrastructure.
Hospital procurement departments are unbundling after-sales service contracts from device purchases, shifting toward third-party perfusion equipment maintenance providers. This channel disruption is most visible in France and the Netherlands, where group purchasing organizations now specify service-level agreements separately from hardware acquisition. Reservoir manufacturers must now compete on standalone product value rather than bundled support packages.
Venous Reservoirs Market Segmentation
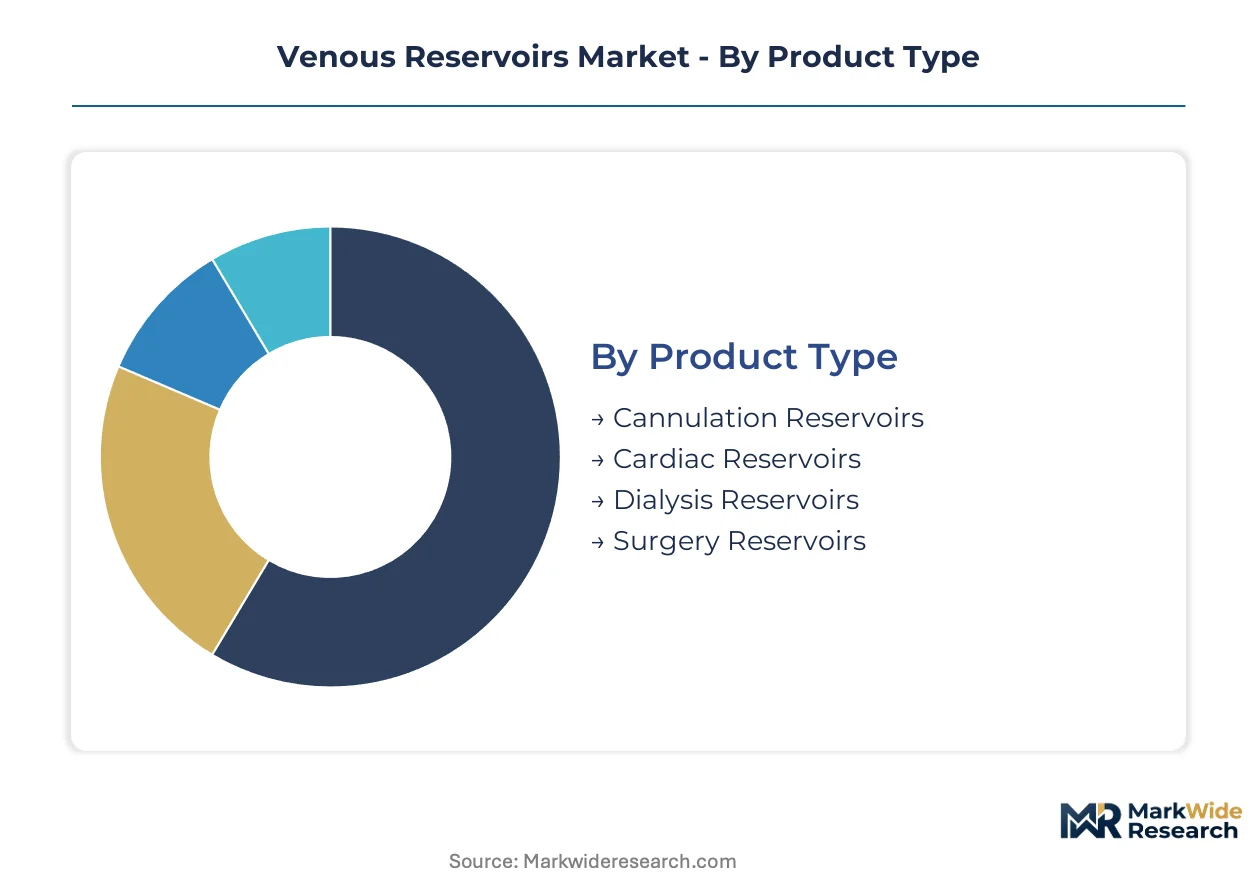
Venous reservoir segmentation reveals how integration depth varies across clinical workflows. Product architecture and delivery economics determine whether reservoirs function as standalone disposables or embed within comprehensive perfusion platforms.
Product Type:
Standalone reservoirs dominate routine procedures, while embedded configurations gain traction in complex cardiac workflows requiring seamless oxygenator-pump coordination.
- Cannulation Reservoirs:Medical-grade polycarbonate containers with 20-40 micron filtration and 800-4000 mL prime volumes serve as the workhorse configuration for standard bypass procedures. Demand concentrates in German tertiary cardiac centers upgrading to integrated perfusion infrastructure under MDR compliance timelines.
- Cardiac Reservoirs:Specialized designs with enhanced air-handling capabilities and reduced prime volumes address high-complexity procedures including minimally invasive valve repairs. Munich and Heidelberg surgical programs are replacing legacy mechanical units with sensor-embedded variants that support automated safety protocols.
- Dialysis Reservoirs:Configured for extracorporeal blood purification with biocompatible membranes meeting ISO 10993 hemocompatibility standards.
- Surgery Reservoirs:General-purpose designs adaptable across multiple open-chest procedures without specialized cardiac optimization.
Volume placements concentrate in Cannulation Reservoirs; the faster expansion belongs to Cardiac Reservoirs.
Technology:
Cost tier stratification separates premium electronic platforms from economy mechanical alternatives, with automation commanding substantial price premiums.
- Automated:Embedded electronic sensors and safety algorithms reduce manual air-handling interventions during bypass, commanding premium positioning. Polish and Czech pediatric programs lack appropriately scaled automated systems, creating development white space for sub-800 mL prime configurations.
- Mechanical:Passive gravity-dependent designs with manual volume monitoring retain dominance in cost-constrained Eastern European surgical centers where sterilization infrastructure supports reusable workflows.
- Electronic:Sensor arrays enabling real-time hematocrit and venous oxygen saturation monitoring without full automation capability.
- Hybrid:Modular architectures allowing perfusionists to toggle between manual and assisted operation modes based on procedural complexity.
Mechanical technology sustains the highest placement volumes; Automated systems are climbing the fastest as MDR documentation favors closed-loop configurations.
End User:
Customer type determines procurement sophistication, with consolidated hospital systems driving integrated platform adoption against fragmented clinic purchasing.
- Hospitals:Tertiary cardiac centers in Berlin and Munich command the most advanced integrated perfusion ecosystems, unbundling after-sales service from device purchases. Group purchasing organizations in France and the Netherlands now specify standalone product value over bundled support packages.
- Surgical Centers:Specialized cardiac facilities concentrate demand for premium single-use technologies with validated recycling pathways under EU Green Deal sustainability criteria.
- Dialysis Clinics:High-volume blood purification operations requiring continuous reservoir availability with standardized disposable economics.
- Emergency Units:Rapid-deployment configurations for acute resuscitation scenarios with minimal setup time requirements.
Hospitals account for the dominant placement base; Surgical Centers are gaining share fastest as outpatient cardiac volumes expand.
Delivery Mode:
Supply concentration in Southern Germany and Northern Italy for precision filtration components shapes procurement vulnerability across disposable and reusable categories.
- Single-Use:Dominant volume position driven by MDR-mandated biocompatibility documentation that favors fresh sterile supply chains. Petrochemical feedstock volatility for polycarbonate and polyvinyl chloride squeezes margins for producers without long-term supply agreements.
- Reusable:Sterilizable configurations retain niche appeal in cost-constrained Eastern European markets where capital equipment infrastructure supports circular workflows. Legacy system integration friction limits upgrade velocity at decade-old oxygenator-pump installations.
- Portable:Compact designs for field deployment and inter-hospital patient transport with reduced prime volume requirements.
- Integrated:Reservoir-oxygenator-pump convergence platforms eliminating discrete component interfaces.
Single-Use delivery commands the highest placement volumes; Integrated configurations are expanding most quickly as sensor-oxygenator convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's concentration of specialized cardiac economic zones concentrates venous reservoir demand through tax-advantaged medical technology clusters in Bavaria and Baden-Württemberg.
Germany
Tertiary cardiac centers in Munich, Berlin, and Heidelberg are replacing legacy mechanical reservoirs with integrated perfusion systems. The EU MDR's expanded post-market surveillance requirements favor manufacturers with dedicated clinical affairs infrastructure. The Bavarian medical technology corridor anchors production scale for precision filtration membranes serving German and Austrian surgical centers.
United States
FDA 510(k) clearance pathways govern market access for polycarbonate reservoir configurations across high-volume bypass programs. The agency's intensified scrutiny of biocompatibility documentation under ISO 10993 standards is compressing timelines for mid-tier suppliers. The Minneapolis-St. Paul medical device cluster concentrates perfusion system engineering talent and regulatory expertise.
Poland
Neonatal and infant cardiac surgery programs in Warsaw and Kraków lack appropriately sized reservoirs with sub-800 mL prime volumes. The country's national pharmaceutical regulator aligns pediatric device submissions with EMA guidance for extrapolation of adult clinical data. The Lower Silesian medical technology zone near Wrocław is attracting contract manufacturers serving Central European pediatric centers.
Japan
PMDA's streamlined approval pathways for second-generation perfusion devices are accelerating automated reservoir adoption in Tokyo and Osaka cardiac centers. METI's medical device export promotion program subsidizes domestic manufacturers seeking ASEAN market entry. The Kansai biomedical manufacturing belt concentrates polymer processing capabilities for blood-contacting components.
France
Group purchasing organizations in Paris and Lyon now specify standalone product value over bundled after-sales service packages. ANSM's vigilance reporting requirements for cardiopulmonary bypass incidents are tightening post-market documentation obligations. The Île-de-France medical technology cluster hosts specialized sterilization validation services for reusable reservoir configurations.
Venous Reservoirs Market Competitive Landscape
German producers anchor the premium integrated-system tier; Japanese and American specialists hold positions in sensor-embedded and mechanical segments respectively. The vendor base concentrates around three strategic archetypes: diversified cardiovascular conglomerates with full perfusion portfolios, dedicated extracorporeal device specialists, and regional contract manufacturers serving cost-constrained markets. Consolidation is accelerating through strategic partnerships between reservoir producers and oxygenator manufacturers, while capacity expansion concentrates in polymer processing hubs with validated MDR technical documentation infrastructure.
Among diversified cardiovascular conglomerates, Medtronic plc and LivaNova PLC exemplify the integrated-perfusion-system archetype, occupying positions that span reservoir-oxygenator-pump convergence platforms. Getinge AB sits within the manufacturing-scale tier, representing channel-control strategies in mechanical technology segments. These three anchors demonstrate how regulatory infrastructure investment separates sustainable competitors from mid-tier suppliers facing MDR documentation burdens.
| Leading Market Players |
|---|
| Medtronic plc |
| LivaNova PLC |
| Getinge AB |
| Terumo Corporation |
| MicroPort Scientific Corporation |
| Braile Biomédica |
| Nipro Corporation |
| OriGen Biomedical, Inc. |
| Abbott |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up specialists in precision filtration components anchor supply discipline across Southern Germany and Northern Italy, translating concentrated component sourcing into pricing power that resists commoditization despite polycarbonate feedstock volatility.
Pricing Analysis
Short lead-time premiums of fifteen to thirty percent over contract pricing reward manufacturers with regional distribution center proximity to Munich and Berlin cardiac centers. Three-tier pricing structure across premium sensor-embedded, standard automated, and economy mechanical configurations separates MDR-compliant integrated systems from Eastern European reusable alternatives. Cost compression in mechanical tiers is intensifying because Polish and Czech procurement committees prioritize sterilization infrastructure over disposable conversion. Pediatric perfusion programs exhibit the highest price sensitivity due to constrained national health budgets, while German tertiary centers demonstrate lowest sensitivity when automated safety protocols reduce perfusionist labor intensity.
Supply Chain Analysis
Regional distribution centers in Bavaria and Baden-Württemberg operate hub-and-spoke patterns feeding Austrian and Swiss cardiac surgery networks with twenty-four-hour replenishment cycles. Manufacturing gravity draws from Germany, Italy, and Japan for precision filtration membranes, polycarbonate resin, and electronic sensor arrays respectively. Single-source vulnerability concentrates in Southern German membrane suppliers serving ISO 10993 hemocompatibility requirements. Distribution runs through specialized medical device logistics providers with validated cold-chain and sterile-handling protocols rather than general freight networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polycarbonate polymerization capacity constraints at European petrochemical complexes prop pricing discipline by limiting feedstock availability for mid-tier disposable producers seeking MDR compliance.
For Market Incumbents: Hedge against Eastern European reusable system substitution by acquiring sterilization validation services in Poland and the Czech Republic. Backward integration into precision filtration membrane production in Bavaria reduces exposure to Southern German supplier concentration. MDR technical documentation burdens favor consolidation toward manufacturers with captive clinical affairs infrastructure. For New Entrants and Emerging Players: EU MDR in Germany opens a window for pediatric-specific reservoir development targeting sub-800 mL prime volume gaps in Warsaw and Kraków surgical programs. Polish neonatal cardiac centers represent the most penetrable segment due to extrapolation-friendly regulatory pathways and unmet automated perfusion demand. Partner with Lower Silesian contract manufacturers to bypass established German supply relationships. For Investors and Strategic Acquirers: Perfusionist certification program expansion velocity across EU member states is the leading indicator that automated system adoption will accelerate or stall. Five-to-ten year viability favors diversified cardiovascular conglomerates with reservoir-oxygenator-pump convergence platforms over standalone disposable specialists. Monitor German hospital procurement database trends for unbundling of after-sales service contracts as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | Accelerates consolidation toward manufacturers with dedicated clinical affairs teams in Germany. |
| Sensor-Oxygenator Platform Integration | Unifies discrete device categories into single-platform solutions favored by Munich cardiac centers. |
| Pediatric Reservoir Development Program | Addresses sub-800 mL prime volume gaps in Polish and Czech neonatal surgery programs. |
| Sterilization Validation Service Acquisition | Captures reusable system economics in cost-constrained Eastern European markets. |
| Green Procurement Certification Pathway | Aligns with EU Green Deal sustainability criteria for polycarbonate component recycling. |
Research Methodology
Multi-period observation of hospital procurement database trends, GPO contract unbundling patterns, and MDR compliance timelines anchored the trend analysis, supplemented by interviews with perfusionists, biomedical engineers, hospital purchasing committee chairs, and GPO contracts managers. Secondary validation drew from FDA 510(k) clearance databases, EUDAMED vigilance reports, ISO 10993 biocompatibility filings, and German hospital equipment replacement schedules. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Input-output matrices mapped product type, technology tier, delivery mode, and end-user category against regional regulatory cluster variations. CAGRs derived from segmented volume trajectory analysis incorporating MDR implementation phase impacts and pediatric program expansion rates. Forecast inputs included perfusionist certification program output projections and polycarbonate feedstock price elasticity assumptions.
The model assumes a particular technology adoption path; alternative pathways for fully closed-loop automated perfusion would alter the outlook if regulatory validation timelines compress unexpectedly. Forecasts reflect documented assumptions regarding MDR enforcement consistency and Eastern European health budget trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Atherectomy Devices Market
Cardiovascular Devices
Fractional Flow Reserve-Computed Tomography (FFR-CT) Market
Cardiovascular Devices
Global Artificial Heart Market
Cardiovascular Devices
Global Heart Valve Repair and Replacement Market
Cardiovascular Devices
Drug Eluting Balloon Market
Cardiovascular Devices
Stent-Assisted Coiling Market
Cardiovascular Devices
Global Vascular Injury Treatment Market
Cardiovascular Devices
Cardiovascular CT Systems Market
Cardiovascular Devices
US Ventricular Assist Devices Market
Cardiovascular Devices
Canada Cardiovascular Devices Market
Cardiovascular Devices
Cardiovascular and Soft Tissue Repair Patches Market
Cardiovascular Devices
Global Non-Vascular Stents Market
Cardiovascular Devices
Wearable Artificial Organs Market
Cardiovascular Devices
Vascular Access Catheters Market
Cardiovascular Devices
Saudi Arabia Cardiovascular Devices Market
Cardiovascular Devices
Ambulatory Cardiac Monitoring Devices Market