
 Mobile Applications for Melanoma Detection Market | 2026-2036
Mobile Applications for Melanoma Detection Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Applications for Melanoma Detection Market Outlook
Platform licensing revenue is fragmenting between standalone consumer apps and enterprise-integrated clinical tools. SkinVision anchors the direct-to-consumer channel with risk-assessment algorithms designed for patient self-monitoring. iDoc24 competes through teledermatology infrastructure that connects users to licensed dermatologists for remote consultation. DermaCompare specializes in longitudinal image comparison, sustaining recurring engagement through mole-tracking subscriptions.
Mobile applications for melanoma detection deploy convolutional neural networks trained on dermoscopic image datasets to classify pigmented lesions across risk categories from benign nevi to suspected melanoma. These systems achieve diagnostic sensitivity comparable to trained dermatologists in controlled validation studies, with primary commercial purpose centered on triaging patients toward timely specialist referral. Image analysis applications currently occupy the largest deployment share, while teledermatology platforms represent the fastest-expanding segment as health systems integrate asynchronous consultation into primary care workflows. Artificial intelligence and machine learning technologies dominate current development pipelines, though computer vision architectures specifically optimized for mobile inference are displacing cloud-dependent processing in low-bandwidth clinical settings.
FDA software-as-medical-device oversight and the EU AI Act's high-risk system requirements constrain market entry for unvalidated algorithms, directly shaping R&D investment toward prospective clinical trials and post-market surveillance infrastructure. Health Canada and Australia's TGA maintain parallel pre-market assessment pathways that similarly demand algorithmic transparency and performance benchmarking across diverse skin phototypes. Stakeholders must monitor evolving equivalence agreements between these regulatory frameworks to anticipate where multi-jurisdictional approval strategies will compress time-to-market or fragment compliance costs.
Market Dynamics
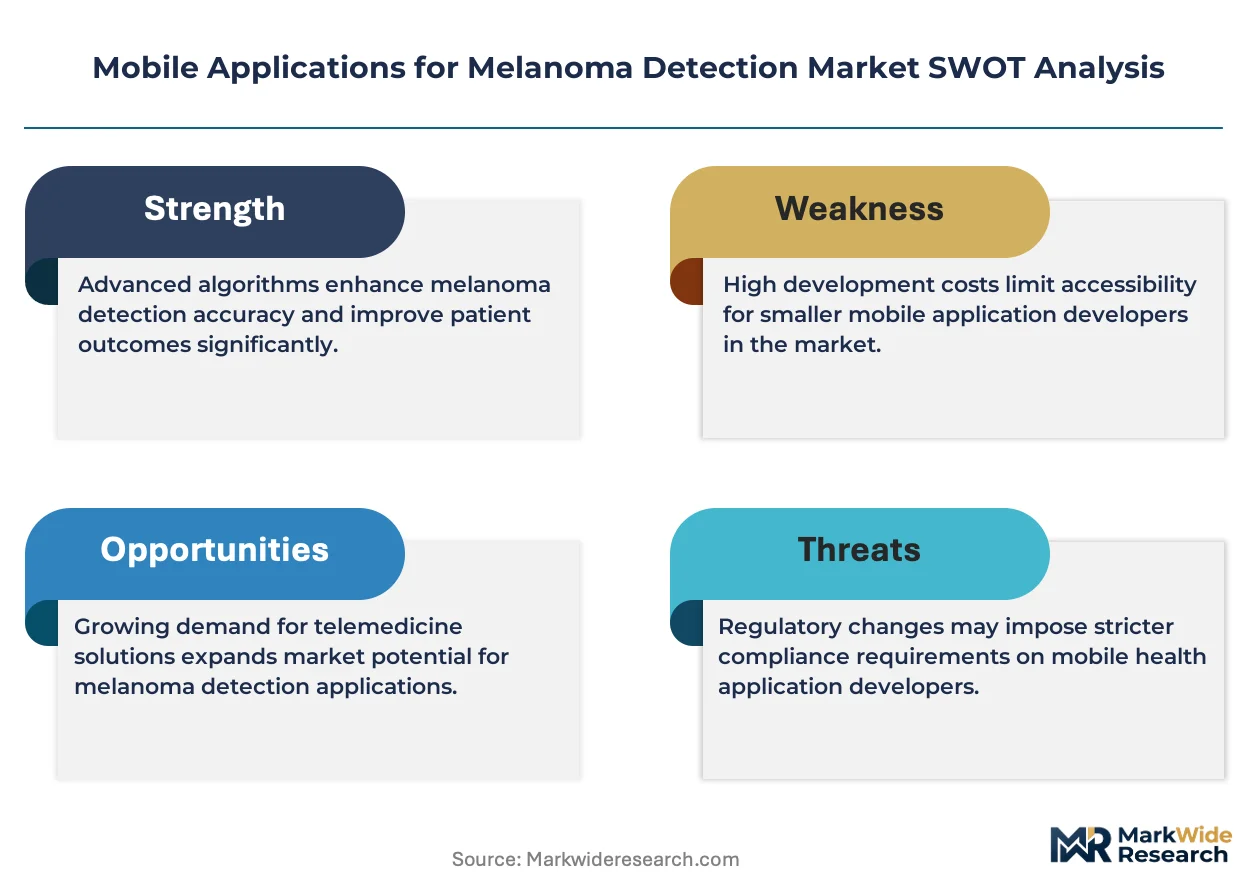
FDA software-as-medical-device guidance and the EU AI Act's risk classification framework are compressing validation timelines while elevating clinical evidence requirements for algorithm developers.
Growth Catalysts
- Teledermatology reimbursement expansion:Germany's statutory health insurance funds now cover asynchronous dermatology consultations, accelerating enterprise adoption of integrated screening platforms.
- Convolutional neural network optimization:On-device inference architectures trained on dermoscopic datasets eliminate cloud latency for rural primary care deployments.
- Australia's TGA streamlined pathway:The regulator's priority review track for AI-diagnostic software compresses pre-market assessment from 255 to 90 days for qualified melanoma detection algorithms.
Market Restraints
- Algorithmic bias liability exposure:Performance degradation across darker skin phototypes exposes developers to product liability claims under EU AI Act high-risk system accountability provisions.
- Specialist dermatologist supply concentration:Australia and Germany face acute dermatologist shortages, constraining teledermatology platform scaling regardless of software availability.
- Smartphone camera hardware heterogeneity:Variable optical quality across device tiers degrades lesion image standardization, complicating universal algorithm deployment.
Strategic Opportunities
- Primary care workflow integration:United States federally qualified health centers seek embedded screening tools to reduce specialist referral backlogs, creating enterprise licensing demand.
- Longitudinal mole-tracking subscriptions:Automated interval photography comparison sustains recurring revenue models beyond initial risk assessment transactions.
- Health Canada equivalency recognition:Mutual reliance agreements with FDA and TGA validation data reduce redundant clinical trials for North American market entry.
Industry Challenges
- Prospective clinical trial recruitment:Melanoma's low population incidence necessitates multi-site, multi-year validation studies to achieve statistically significant sensitivity benchmarks.
- Post-market surveillance infrastructure:Real-world performance monitoring across diverse skin types demands continuous data collection systems that strain developer operational capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Applications for Melanoma Detection Market |
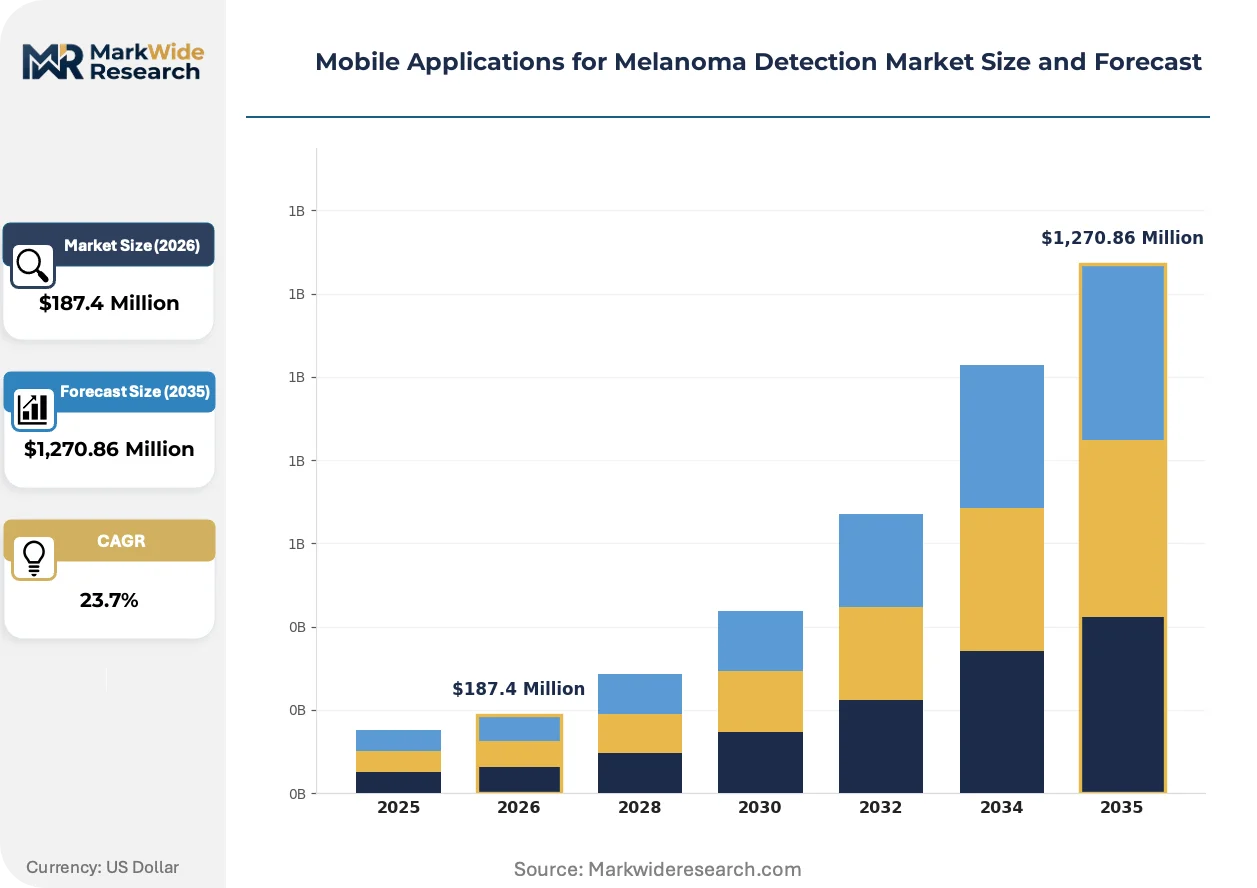
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,270.86 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Image Analysis, Risk Assessment, Patient Education, Teledermatology End User: Dermatologists, General Practitioners, Patients, Medical Researchers Technology: Artificial Intelligence, Machine Learning, Computer Vision, Augmented Reality Deployment Model: Cloud-Based, On-Premises, Hybrid, Mobile-Only |
| Companies Covered | SkinVision, DermaCompare, Dermatology Planet, DermLink.MD, FotoSkin, iDoc24, iSkin, LoveMySkin, MoleQuest, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Applications for Melanoma Detection Market Strategic Shifts
Edge-computing architectures and asynchronous care models are redistributing diagnostic activity from centralized dermatology departments toward distributed primary care and consumer endpoints.
On-device convolutional neural networks optimized for mobile inference are virtualizing lesion classification workflows previously tethered to cloud infrastructure. Rural clinics in bandwidth-constrained regions adopt these architectures to maintain diagnostic continuity during connectivity interruptions. This virtualization compresses the cost structure for screening deployment while eliminating latency-dependent user experience degradation.
The EU AI Act's high-risk system classification mandates algorithmic transparency documentation and human oversight protocols for melanoma detection software. Developers must now maintain technical files demonstrating performance consistency across demographic subgroups. Dermatology clinics in Germany and France restructure procurement criteria to prioritize vendors with completed conformity assessments.
Asynchronous store-and-forward teledermatology is displacing synchronous video consultation as the dominant remote care modality. Primary care networks in Australia and the United States integrate image-based screening into standardized referral pathways. This behavioral shift concentrates platform selection authority with health system IT procurement functions rather than individual clinician preference.
Mobile Applications for Melanoma Detection Market Segmentation
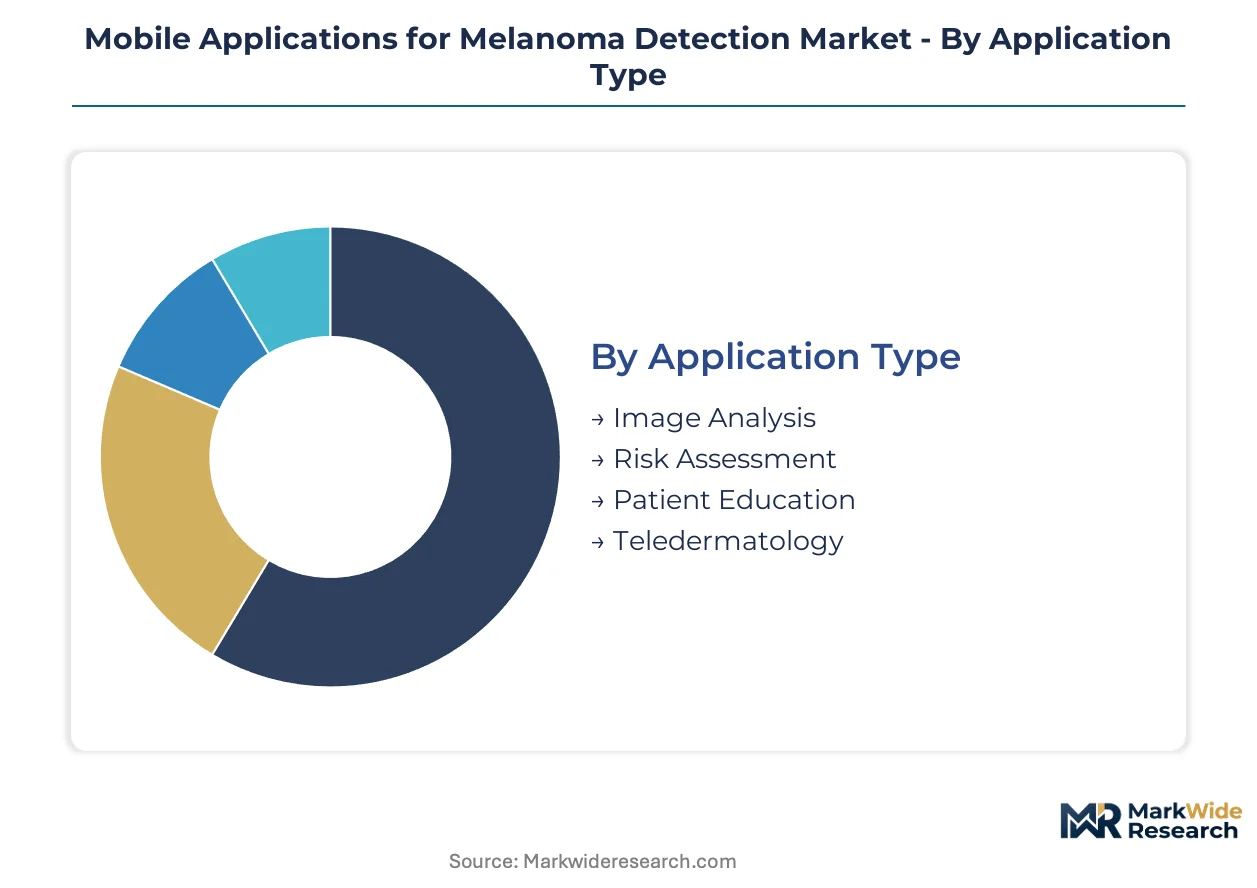
Segmentation in melanoma detection apps reveals how clinical utility, user sophistication, and infrastructure constraints fragment commercial opportunity. Each dimension shapes pricing power, regulatory pathway, and customer acquisition cost differently.
Application Type:
Clinical workflows span from immediate diagnostic assistance to longitudinal patient engagement, with reimbursement eligibility varying sharply across use cases.
- Image Analysis:Convolutional neural networks classify dermoscopic images into risk categories at the point of capture. Dermatology clinics in Germany and Australia embed these tools into electronic health records to triage urgent referrals.
- Teledermatology:Asynchronous store-and-forward platforms connect primary care physicians to dermatologists for remote consultation. United States federally qualified health centers deploy these systems to reduce specialist backlogs in underserved counties.
- Risk Assessment:Self-monitoring algorithms guide patient decisions on seeking professional evaluation.
- Patient Education:Interactive modules improve skin self-examination technique and sun protection compliance.
The dominant share belongs to Image Analysis, while Teledermatology is closing the gap fastest.
End User:
Adoption depth correlates with clinical authority and liability exposure, concentrating enterprise investment where diagnostic responsibility sits.
- Dermatologists:Specialists demand FDA-cleared and EU MDR-compliant algorithms with transparent performance benchmarking across skin phototypes. Academic medical centers in the United States prioritize tools with prospective validation data.
- General Practitioners:Primary care networks seek low-friction integration into existing workflows. Australia's rural health clinics adopt on-device inference to maintain screening continuity during connectivity outages.
- Patients:Direct-to-consumer users drive volume but generate lower per-account revenue.
- Medical Researchers:Institutional buyers fund algorithm development and validation studies.
Dermatologists command the highest licensing fees, though General Practitioners are expanding most quickly as gatekeeper models spread.
Technology:
Architectural choices determine latency, offline capability, and regulatory classification burden.
- Artificial Intelligence:Deep learning systems trained on multi-institutional dermoscopic datasets achieve sensitivity benchmarks matching trained clinicians. Developers face EU AI Act high-risk system documentation requirements.
- Computer Vision:Optimized mobile inference engines process lesion classification without cloud dependency. Bandwidth-constrained deployments in rural Australia favor these architectures.
- Machine Learning:Traditional classifiers persist in resource-constrained environments.
- Augmented Reality:Overlay guidance assists patient self-examination technique.
Artificial Intelligence anchors current R&D expenditure, while Computer Vision is gaining share fastest through edge-computing optimization.
Deployment Model:
Infrastructure strategy shapes data sovereignty, recurring cost structure, and vulnerability to connectivity disruption.
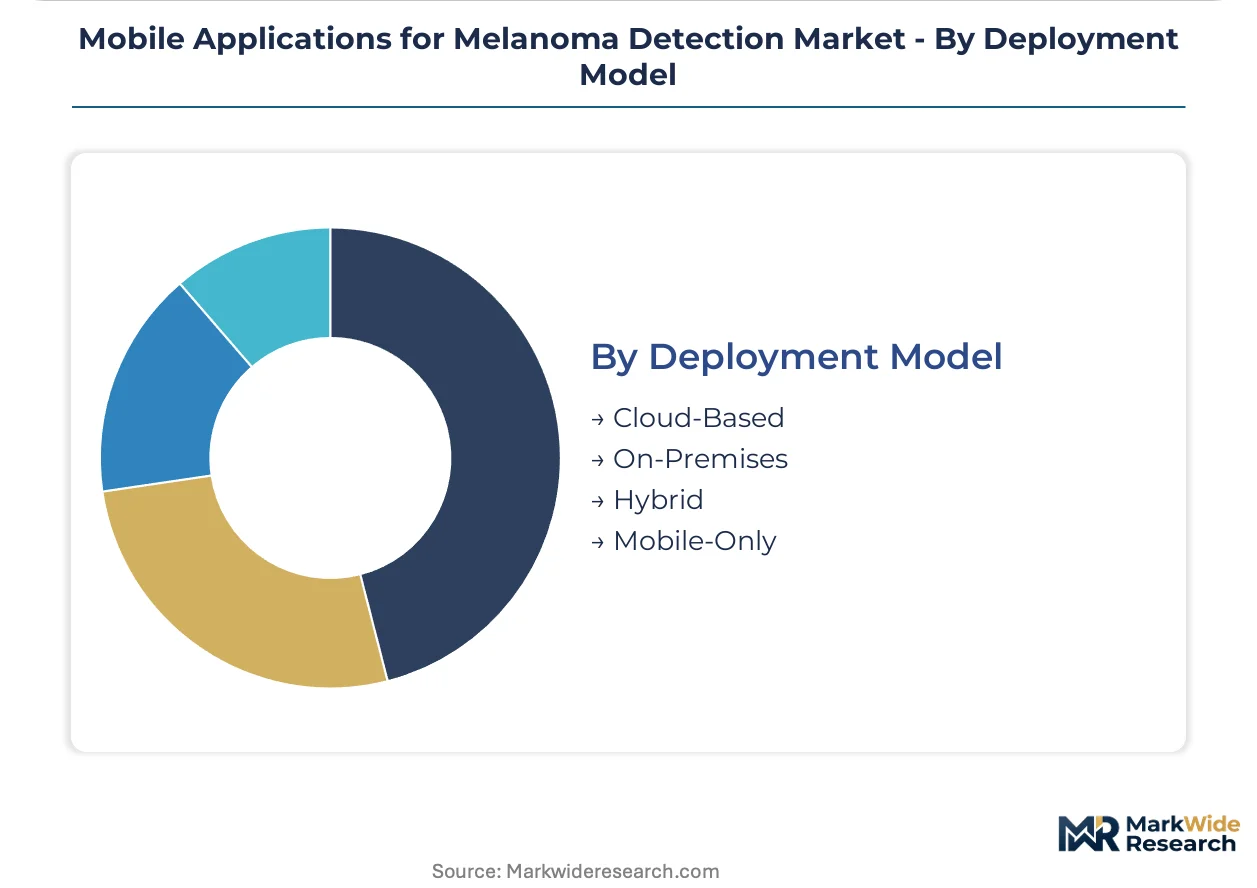
- Cloud-Based:Centralized processing enables model updates without client-side deployment. German dermatology networks favor this model for multi-site standardization.
- Mobile-Only:Fully on-device execution eliminates latency and data transmission privacy concerns. Australia's TGA fast-track pathway accelerates approval for qualified standalone algorithms.
- On-Premises:Hospital-controlled servers satisfy stringent data residency requirements.
- Hybrid:Split architectures balance local inference with cloud-based model refinement.
Cloud-Based deployments hold the largest installed base, while Mobile-Only configurations are climbing the fastest on privacy and bandwidth advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across markets. German dermatology clinics absorb premium licensing fees for validated algorithms, while direct-to-consumer users in India and Brazil gravitate toward freemium risk-assessment tiers. The United States occupies the middle ground, where reimbursement pathways determine enterprise willingness-to-pay.
United States
Federally qualified health centers in rural counties drive demand for asynchronous teledermatology platforms that reduce specialist referral backlogs. FDA software-as-medical-device guidance mandates prospective clinical trials for diagnostic algorithms, elevating compliance costs for market entrants. The Boston-Cambridge corridor concentrates AI-healthcare venture activity, with academic medical centers prioritizing tools with transparent performance benchmarking across diverse skin phototypes.
Germany
Statutory health insurance funds now reimburse asynchronous dermatology consultations, accelerating enterprise adoption of integrated screening platforms. EU AI Act high-risk system classification requires algorithmic transparency documentation and human oversight protocols for melanoma detection software. Berlin and Munich host procurement decision-makers at dermatology clinic networks, which restructure vendor selection criteria to prioritize completed conformity assessments.
Australia
Elevated melanoma incidence rates intersect with acute dermatologist shortages in rural regions, creating demand for on-device inference solutions. TGA's priority review track compresses pre-market assessment from 255 to 90 days for qualified AI-diagnostic software. Queensland and Western Australia deploy mobile-only screening tools in bandwidth-constrained primary care clinics to maintain diagnostic continuity during connectivity interruptions.
United Kingdom
NHS long-term plan targets reduction in dermatology waiting times through teledermatology integration into primary care workflows. MHRA recognition of FDA and TGA validation data reduces redundant clinical trials for algorithm developers seeking UK market entry. London and Manchester academic health science networks fund multi-site validation studies to achieve statistically significant sensitivity benchmarks for convolutional neural network classifiers.
India
Smartphone penetration exceeds dermatologist density by orders of magnitude, positioning direct-to-consumer risk-assessment apps as first-line screening tools. CDSCO regulatory framework for software-as-medical-device remains under development, creating uncertainty for algorithm developers. Bangalore and Hyderabad host health-tech startups optimizing mobile inference architectures for low-bandwidth deployment in tier-2 and tier-3 cities.
Mobile Applications for Melanoma Detection Market Competitive Environment
Capability concentration sits with specialized AI developers holding validated clinical evidence; scale advantage sits with platform integrators embedding screening tools into enterprise electronic health record workflows. The vendor base stratifies across three tiers: standalone consumer applications, clinical workflow integrators, and longitudinal mole-tracking subscription services. Strategic moves concentrate on regulatory pre-clearance accumulation and health system procurement contract capture.
Within the direct-to-consumer tier, SkinVision and iDoc24 exemplify divergent positioning archetypes. SkinVision anchors risk-assessment algorithms designed for patient self-monitoring without clinical oversight. iDoc24 occupies a position bridging consumer accessibility and clinical credibility through teledermatology infrastructure connecting users to licensed dermatologists. DermaCompare represents the longitudinal engagement archetype, sustaining recurring revenue through automated interval photography comparison rather than transactional risk assessment.
| Leading Market Players |
|---|
| SkinVision |
| DermaCompare |
| Dermatology Planet |
| DermLink.MD |
| FotoSkin |
| iDoc24 |
| iSkin |
| LoveMySkin |
| MoleQuest |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in cloud-based diagnostic processing is compressing margins for algorithm developers while simultaneously elevating pricing power for specialized edge-computing chip suppliers serving bandwidth-constrained deployments in rural Australia and India's tier-3 cities. This utilization asymmetry forces vendors to restructure cost allocation between subscription tiers and hardware-optimized licensing models.
Pricing Analysis
Longitudinal mole-tracking subscriptions drive lifetime value through automated interval photography comparison rather than transactional risk assessments. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared clinical algorithms from direct-to-consumer risk tools and basic educational modules. Price differentiation rests on certification grade—EU MDR conformity assessment completion commands 40-60% licensing premiums in German dermatology networks. Cost compression in the consumer tier intensifies as freemium apps proliferate in India and Brazil. General practitioners exhibit highest price sensitivity due to constrained procurement budgets, while academic medical centers absorb premium fees for transparent performance benchmarking across diverse skin phototypes.
Supply Chain Analysis
Extended payment terms from German statutory health insurance funds and supply-chain finance facilities at Australia's TGA priority review pathway are restructuring working capital requirements for algorithm developers. Geographic supply concentration centers on the United States for FDA-cleared training datasets, Germany for EU MDR technical documentation services, and Taiwan for mobile inference chip fabrication. Raw material dependencies include dermoscopic image repositories, convolutional neural network training infrastructure, and specialized mobile GPU components. Single-source vulnerability in FDA validation data providers exposes developers to approval timeline extension. Distribution runs through health system IT procurement functions rather than individual clinician channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where asynchronous teledermatology infrastructure is displacing synchronous consultation as the dominant interoperability standard, rewarding vendors who embed screening tools into electronic health record workflows ahead of ecosystem consolidation.
For Market Incumbents: Insulate installed base through backward integration into longitudinal image storage infrastructure and exclusive health system procurement contracts. The threat of on-device inference optimization by mobile-native entrants demands immediate capacity addition in edge-computing R&D. Certification investment in EU AI Act conformity assessment completion creates switching costs against latecomers.
For New Entrants and Emerging Players: Rural primary care networks in Australia's Queensland and Western Australia represent the most penetrable white-space target given acute dermatologist shortages and TGA fast-track eligibility. India's tier-2 cities offer volume expansion through low-bandwidth-optimized mobile inference architectures. Go-to-market execution should anchor on GPO contracts with United States federally qualified health centers seeking embedded screening tools.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among longitudinal mole-tracking subscription services with automated interval photography comparison rather than transactional risk assessment models. Long-term viability over the coming decade hinges on regulatory pre-clearance accumulation across FDA, EU MDR, and TGA pathways. The acquisition target archetype is specialized AI developers holding multi-jurisdictional validation data. Watch for FDA software-as-medical-device guidance expansion as the inflection signal compressing time-to-market for compliant algorithms.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Assessment Completion | Unlocks German statutory insurance reimbursement and procurement eligibility for high-risk AI systems. |
| On-Device Inference Optimization | Eliminates cloud latency for rural Australian deployments during connectivity interruptions. |
| Hospital System Partnership | Captures procurement authority shifting from individual clinicians to health system IT functions. |
| Longitudinal Image Storage Infrastructure | Sustains recurring revenue through automated mole-tracking subscriptions beyond initial transactions. |
| FDA Software-as-Medical-Device Submission | Mandates prospective clinical trials elevating compliance costs and barriers for unvalidated entrants. |
Study Parameters
Initial hypotheses were tested against primary input from dermatology clinic procurement managers, AI-healthcare venture capitalists, regulatory affairs specialists at FDA and TGA, biomedical engineers at academic medical centers, and teledermatology platform operators and refined through secondary validation against FDA software-as-medical-device guidance documents, EU AI Act technical standards, TGA priority review pathway determinations, hospital GPO contract databases, and dermoscopic image dataset licensing records. Bottom-up segmentation modeling triangulated with top-down epidemiological projections across skin cancer incidence patterns.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with convolutional neural network training capacity and dermatologist supply concentration serving as binding constraints. Segmentation dimensions modeled include application type, end-user clinical authority, technology architecture, and deployment model complexity alongside regional regulatory pathway clustering. CAGRs were derived from algorithmic adoption curves in comparable diagnostic AI markets adjusted for melanoma-specific incidence and reimbursement pathway maturation.
The forecast holds incumbent behavior within observed patterns; aggressive moves by mobile-native entrants with optimized edge-computing architectures would shift outcomes toward faster cloud displacement than modeled. Macroeconomic contraction affecting health system IT budgets, regulatory deviation in EU AI Act enforcement posture, or breakthroughs in non-imaging biomarker diagnostics would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Solutions
Near-Patient Molecular Solutions Market
Diagnostic Solutions
Protein Assays Market
Diagnostic Solutions
North America Lung Cancer Screening Software Market
Diagnostic Solutions
Europe Lung Cancer Screening Software Market
Diagnostic Solutions
Multiple Reaction Monitoring Assay Market
Diagnostic Solutions
Oral Screening Systems Market
Diagnostic Solutions
Global Upper Gastrointestinal (GI) Series Market
Diagnostic Solutions
Middle East and Africa Lung Cancer Screening Software Market
Diagnostic Solutions
Total Bile Acid Assay Kit Market
Diagnostic Solutions
Global Ioversol Market
Diagnostic Solutions
Global Lung Cancer Screening Software Market
Diagnostic Solutions
Hepatitis C Diagnosis and Treatment Market
Diagnostic Solutions
Protein Detection and Quantification Market
Diagnostic Solutions
Global Enzyme-Linked Immunosorbent Assay (ELISA) Market