
 Tubeless Insulin Pump Market | 2026-2036
Tubeless Insulin Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Tubeless Insulin Pump Market Analysis
China is tilting toward domestic manufacturing of miniaturized infusion components for wearable diabetes devices. Insulet Corporation leverages its proprietary Omnipod platform to sustain vertically integrated production of disposable patch pumps. Medtronic anchors its position through sensor-augmented pump systems that integrate continuous glucose monitoring with automated insulin delivery. Tandem Diabetes Care differentiates via touchscreen-controlled smart pumps that occupy the premium connected-device tier.
A tubeless insulin pump is a wearable, patch-based medical device that delivers subcutaneous insulin through a cannula without tethered tubing, typically operating with basal rates of 0.025 to 30 units per hour and reservoir volumes between 85 and 200 units. Its primary purpose is to reduce physical encumbrance and infection risk while enabling discreet, around-the-clock glycemic management for insulin-dependent diabetics. Patch pumps lead the product type category due to their disposable design and elimination of infusion sets, while connected systems represent the fastest-growing segment as Bluetooth-enabled smartphone integration becomes standard. Automated delivery modes command the highest margin pools because closed-loop algorithms require proprietary software validation and recurrent subscription revenue.
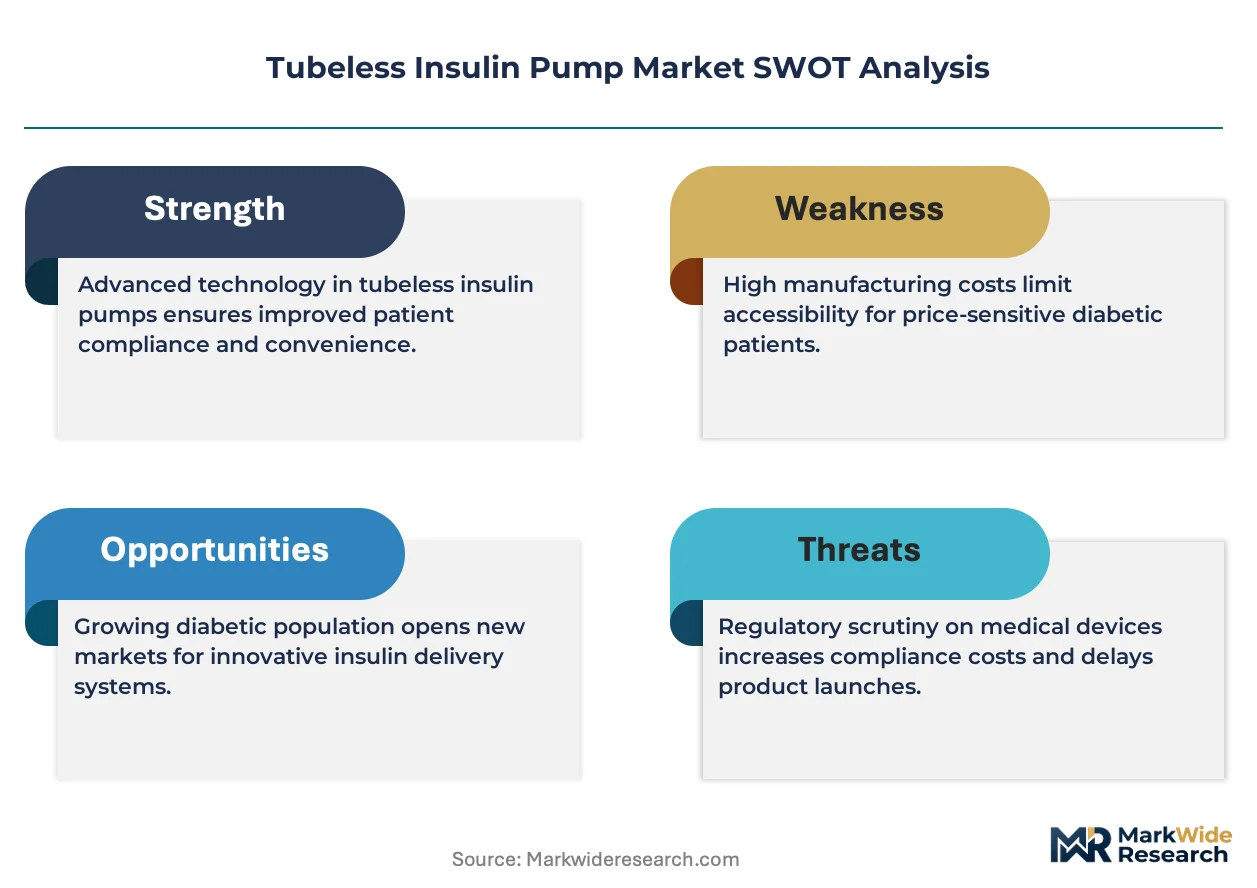
The FDA regulates tubeless pumps as Class II or Class III medical devices under 21 CFR 870.5860, requiring substantial equivalence or premarket approval that shapes development timelines and clinical trial investment. ISO 15197 and IEC 62304 standards govern glucose monitoring accuracy and software lifecycle processes, creating compliance barriers for new entrants. Reimbursement determinations by CMS and private payors directly influence patient access and manufacturer pricing power. Stakeholders must monitor evolving artificial-intelligence guidance documents from regulators and prepare for software-as-a-medical-device classification shifts that could reshape competitive requirements.
Market Dynamics
Home care migration is restructuring demand architecture for tubeless insulin pumps, as reimbursement frameworks in the United States and Germany now favor residential ambulatory delivery over clinical administration, compressing traditional hospital-based diabetes management channels.
Growth Catalysts
- FDA Breakthrough Device Designation:The pathway accelerates pre-market review timelines for patch pump innovations, reducing regulatory friction for algorithm-enabled closed-loop systems seeking 510(k) clearance.
- Bluetooth-enabled smartphone integration:Connected systems are capturing premium positioning as patients demand real-time glycemic data visibility through native mobile applications.
- Residential diabetes management:Home care patients are driving volume expansion as CMS reimbursement codes mature for wearable insulin delivery outside clinical settings.
Market Restraints
- ISO 15197 compliance costs:Glucose monitoring accuracy standards impose substantial validation burdens on new entrants, elevating R&D expenditure floors before commercialization.
- Disposable component supply concentration:Miniaturized infusion set manufacturing clusters in East Asia create single-source vulnerability for patch pump producers.
- Multiple daily injection persistence:Pen-based insulin delivery retains cost advantage in price-sensitive segments, limiting addressable market expansion.
Strategic Opportunities
- Software-as-a-medical-device classification:Evolving FDA guidance on AI-enabled dosing algorithms opens recurring revenue streams through subscription-based closed-loop software.
- Pediatric indication expansion:Underserved adolescent diabetic populations present white space for smaller-form-factor patch pumps with guardian oversight features.
- Direct-to-patient distribution:Pharmacy bypass models are emerging in the United States as manufacturers build proprietary fulfillment infrastructure.
Industry Challenges
- IEC 62304 software lifecycle expertise:Shortage of qualified medical device software engineers extends development timelines for algorithm validation.
- Legacy electronic health record integration:Closed-loop pump data interoperability with hospital IT systems requires costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tubeless Insulin Pump Market |
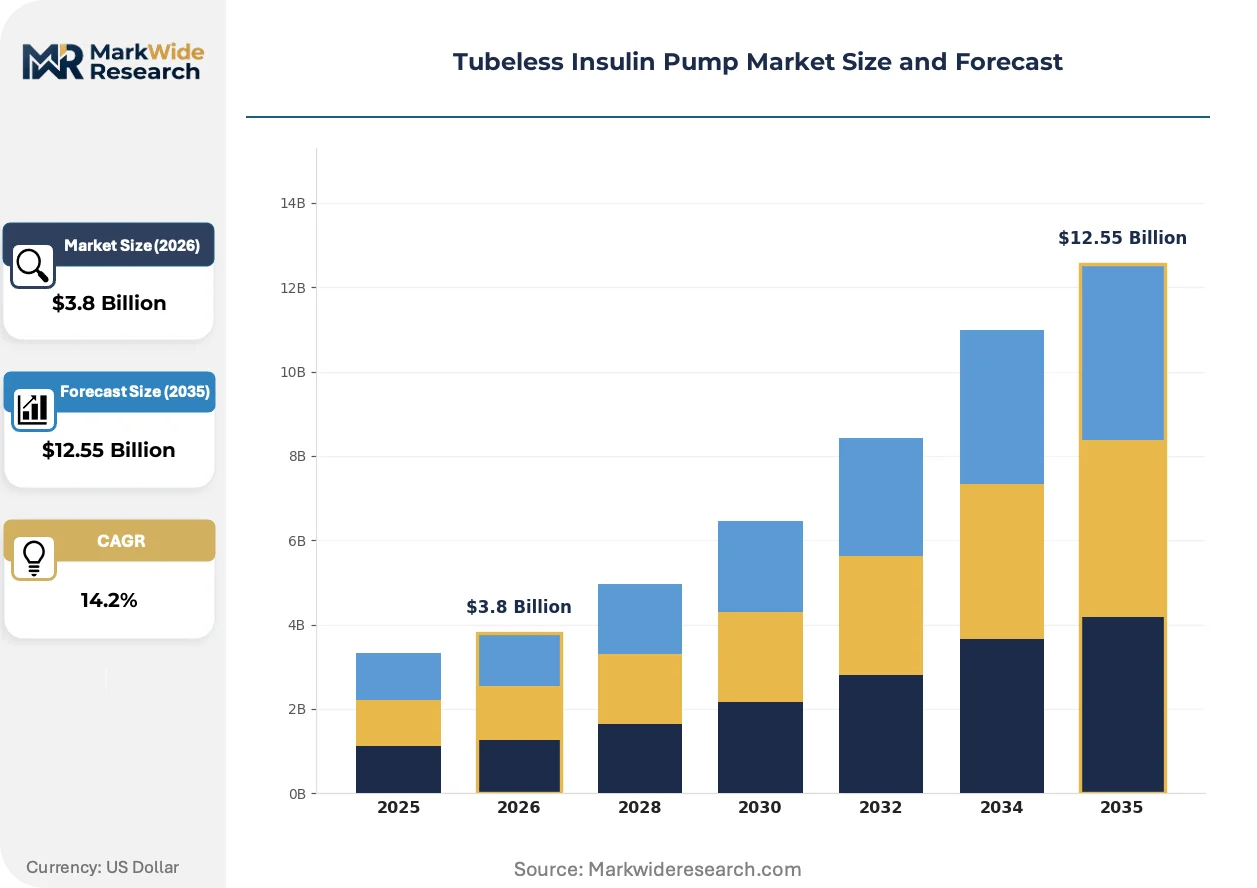
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patch Pumps, Smart Insulin Pumps, Wearable Devices, Connected Systems Delivery Mode: Continuous Delivery, On-demand Delivery, Automated Delivery, Manual Delivery End User: Diabetics, Healthcare Providers, Home Care Patients, Clinical Settings Technology: Micro Infusion Technology, Sensor-based Technology, Wireless Communication, Mobile App Integration |
| Companies Covered | Insulet Corporation, Tandem Diabetes Care, Medtronic, Roche Diabetes Care, Johnson & Johnson, Abbott, CeQur Corporation, Medtrum Technologies, Beta Bionics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tubeless Insulin Pump Market Emerging Trajectories
Algorithmic insulin dosing is compressing competitive differentiation around software sophistication rather than hardware mechanics, elevating the strategic importance of proprietary closed-loop architectures and data science capabilities.
Closed-loop artificial pancreas systems are rendering obsolete conventional basal-bolus programming that requires patient-initiated dose calculations. Adolescent and young adult diabetics are migrating fastest to these automated platforms, with pediatric endocrinology practices reporting accelerated switching cycles. The technology is rendering obsolete manual carbohydrate counting as the primary glycemic control interface, compressing margins for traditional pump makers lacking algorithmic assets.
The European Union's Medical Device Regulation (MDR) is tightening post-market surveillance requirements for active implantable and wearable drug delivery systems. Manufacturers must now maintain clinical evidence registries spanning the entire device lifecycle, elevating compliance infrastructure costs. Class III designation discussions for closed-loop pumps are forcing early-stage companies toward notified body partnerships in Germany and Ireland.
Patients are consolidating purchasing decisions through integrated diabetes management platforms rather than discrete device selection. Endocrinology practices are bundling pump procurement with continuous glucose monitor prescriptions and telehealth subscriptions, displacing standalone medical device distributors. This channel consolidation is most pronounced in the United States, where vertically integrated diabetes care networks are capturing patient lifetime value through multi-year service contracts.
Tubeless Insulin Pump Market Segmentation
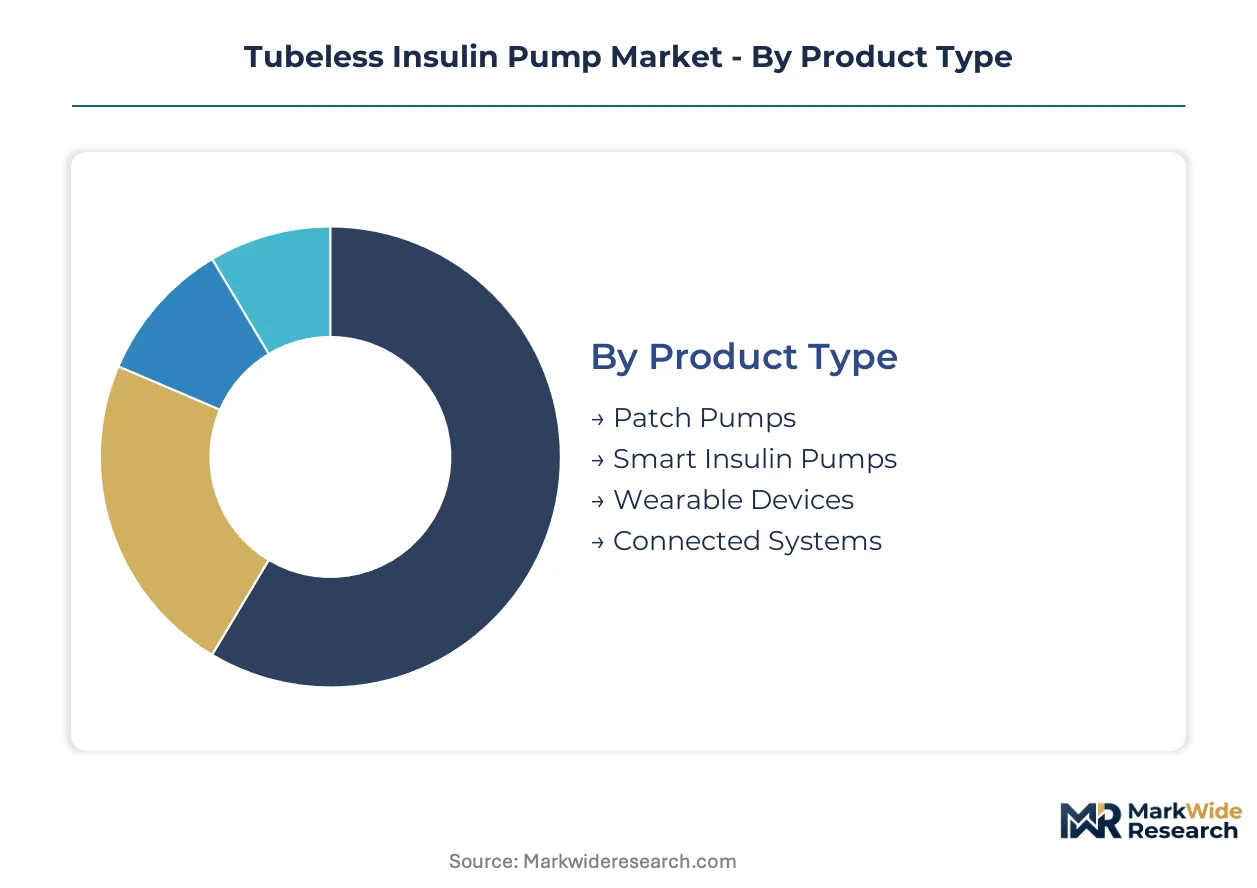
Tubeless insulin pump segmentation reveals how hardware miniaturization, algorithmic dosing, and care setting migration are fragmenting addressable demand across distinct technology tiers and patient workflows. Manufacturers must align R&D investment with the specific compliance burdens and reimbursement codes governing each category.
Product Type:
Use-case spectrum spans disposable patch-based wearables for cost-sensitive patients through premium connected systems for algorithm-dependent intensive insulin management.
- Patch Pumps:Self-contained disposable units integrate insulin reservoir, cannula, and pumping mechanism in a single adhesive pod worn directly on skin. Home care patients in the United States drive volume as CMS reimbursement codes mature for residential ambulatory delivery outside clinical settings.
- Connected Systems:Bluetooth-enabled platforms stream real-time glycemic data to smartphone applications, enabling remote monitoring and dose adjustment. Adolescent diabetics and their caregivers concentrate demand here, drawn by guardian oversight features and automated alerts that reduce hypoglycemic event frequency.
- Smart Insulin Pumps:Touchscreen-controlled devices with predictive low glucose suspend functionality occupy the premium device tier.
- Wearable Devices:Broader category encompassing non-pump continuous glucose monitors and hybrid closed-loop accessories.
The dominant share belongs to Patch Pumps, while Connected Systems is closing the gap fastest.
Delivery Mode:
Cost tier stratification separates subscription-supported automated algorithms from capital-efficient manual programming.
- Automated Delivery:Closed-loop algorithms modulate basal insulin rates based on continuous glucose monitor inputs without patient-initiated dosing. Pediatric endocrinology practices in Germany and the United States report accelerated switching cycles as families prioritize reduced cognitive burden over upfront device cost.
- Continuous Delivery:Steady basal insulin infusion mimics physiological pancreatic secretion patterns around the clock. Type 1 diabetics with established pump experience concentrate demand, particularly where private payor coverage limits access to newer automated platforms.
- On-demand Delivery:Patient-triggered bolus dosing for meal coverage and correction remains standard in price-sensitive segments.
- Manual Delivery:Simplified basal-bolus programming without predictive algorithms serves markets with limited reimbursement infrastructure.
Automated Delivery commands the highest margin pools, while Continuous Delivery retains volume leadership among established pump users.
End User:
Application concentration tracks the shift from hospital-based diabetes management toward residential self-care.
- Home Care Patients:Individuals managing insulin-dependent diabetes in residential settings without routine clinical supervision. Reimbursement frameworks in the United States and Germany now explicitly favor wearable insulin delivery outside hospital walls, compressing traditional clinical administration channels.
- Diabetics:The core patient population spans Type 1 and insulin-requiring Type 2 disease, with technology adoption varying by age, digital literacy, and comorbidity burden.
- Healthcare Providers:Endocrinology practices and diabetes educators influence device selection through bundled prescription workflows.
- Clinical Settings:Hospital inpatient and outpatient departments retain relevance for acute glycemic crisis management and pump initiation training.
Home Care Patients capture the steepest expansion trajectory, while Diabetics as a broad category maintains the largest installed base.
Technology:
Supply concentration for miniaturized components shapes competitive access to enabling hardware.
- Sensor-based Technology:Continuous glucose monitoring integration enables real-time glycemic feedback loops for closed-loop insulin modulation. FDA breakthrough device designation pathway accelerates pre-market review timelines for sensor-augmented patch pump innovations seeking 510(k) clearance.
- Mobile App Integration:Native smartphone applications display trend data, enable remote dosing authorization, and generate compliance reports for clinicians. Young adult diabetics in urban United States markets concentrate demand for these platforms, treating diabetes management as an extension of digital health tracking routines.
- Micro Infusion Technology:Precision micromechanical pumping mechanisms enable accurate sub-microliter insulin delivery in compact form factors.
- Wireless Communication:Bluetooth Low Energy and proprietary radio protocols enable device-to-device data exchange.
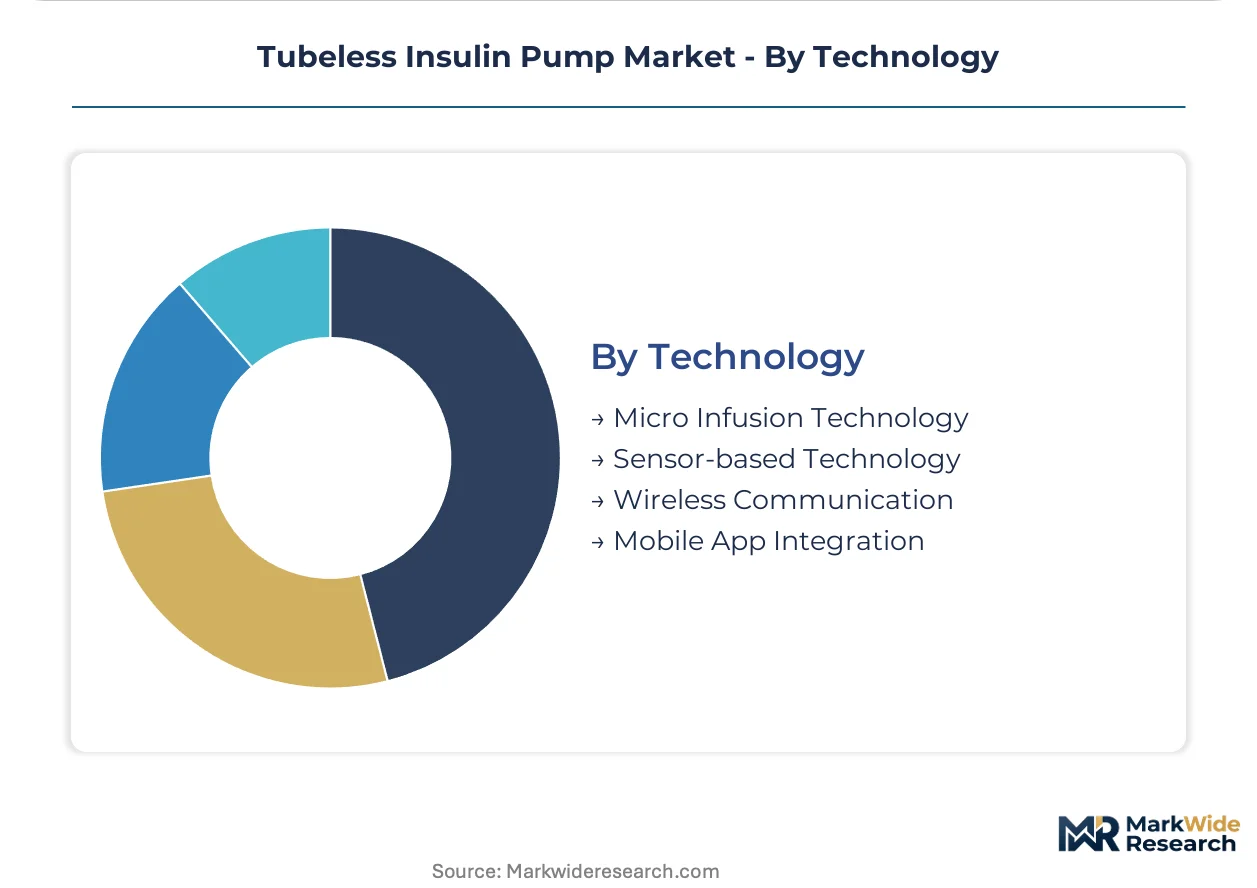
Sensor-based Technology anchors current competitive differentiation, while Mobile App Integration is expanding most quickly as smartphone-native patient cohorts age into insulin dependence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Miniaturized infusion component manufacturing clusters in East Asia, while algorithm development and regulatory clearance concentrate in the United States and Germany. These three countries anchor supply-side capability across hardware, software, and compliance validation.
United States
Home care patients and CMS reimbursement maturation drive residential ambulatory delivery demand. FDA breakthrough device designation accelerates pre-market review timelines for patch pump innovations. The Boston-Minneapolis corridor houses sensor-augmented pump development clusters.
Germany
Pediatric endocrinology practices report accelerated switching cycles to automated platforms. EU MDR post-market surveillance requirements elevate compliance infrastructure costs for notified body partnerships. The Baden-Württemberg region concentrates precision micromechanical manufacturing for compact form factors.
China
Domestic manufacturing of miniaturized infusion components expands for wearable diabetes devices. NMPA regulatory pathways shape development timelines for local market entry. The Yangtze River Delta hosts supply chain concentration for disposable patch pump production.
Japan
Type 1 diabetics with established pump experience concentrate demand for continuous delivery systems. PMDA software lifecycle validation extends timelines for algorithm-enabled devices. The Kanto region anchors medical device distribution networks.
United Kingdom
Young adult diabetics in urban markets demand mobile app integration for real-time glycemic visibility. MHRA alignment with EU MDR creates transitional compliance burdens for manufacturers. The Oxford-Cambridge corridor houses glucose monitoring accuracy research clusters.
Tubeless Insulin Pump Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying miniaturized infusion sets and precision pumping mechanisms. The vendor base stratifies into three tiers: vertically integrated device manufacturers with proprietary closed-loop algorithms, modular patch pump assemblers sourcing from East Asian component clusters, and software developers seeking SaMD classification for subscription revenue. Consolidation pressure runs through algorithm-enabled dosing systems as hardware margins compress. Strategic moves center on backward integration into disposable manufacturing and partnership structures with continuous glucose monitor producers.
Within the platform integrator tier, Insulet Corporation and Tandem Diabetes Care exemplify vertically integrated production architectures. Medtronic occupies a position bridging sensor-augmented hardware with automated insulin delivery software. These three anchors represent distinct competitive archetypes: disposable patch pump specialization, touchscreen-controlled premium connected devices, and sensor-pump integration systems. Each sits within a different margin pool—subscription-supported algorithms, capital-efficient hardware replacement cycles, or bundled device-service contracts.
| Leading Market Players |
|---|
| Insulet Corporation |
| Tandem Diabetes Care |
| Medtronic |
| Roche Diabetes Care |
| Johnson & Johnson |
| Abbott |
| CeQur Corporation |
| Medtrum Technologies |
| Beta Bionics |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta's expanding capacity for miniaturized infusion components is compressing margins for Western patch pump assemblers while amplifying pricing power for vertically integrated device manufacturers with captive supply chains. This geographic concentration of disposable manufacturing feeds directly into tiered pricing structures that separate algorithm-enabled closed-loop systems from commodity patch pump alternatives.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing structure across premium, standard, and economy levels in the tubeless insulin pump market. Subscription-supported automated delivery platforms command premium positioning against capital-efficient disposable patch pumps, with price differentiation resting on algorithmic sophistication and continuous glucose monitor integration. Cost compression in the manual delivery tier is intensifying because pen-based insulin delivery retains cost advantage in price-sensitive segments. Home care patients in the United States exhibit highest price sensitivity due to co-pay exposure, while pediatric endocrinology practices demonstrate lowest sensitivity where guardian oversight features justify premium expenditure.
Supply Chain Analysis
Export controls on precision micromechanical components and sensor technology limit flows from East Asian manufacturing hubs to Western device assemblers, creating supply friction for algorithm-enabled systems. Component sourcing draws from China, South Korea, and Germany for miniaturized infusion sets, precision pumping mechanisms, and glucose sensor substrates. Single-source vulnerability concentrates in East Asian disposable component manufacturing, with tariff exposure escalating for patch pump producers dependent on cross-border component flows. Distribution runs through vertically integrated diabetes care networks in the United States and hospital procurement systems in Germany, displacing standalone medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists across the tubeless insulin pump market as residential diabetes management shifts create distinct niches for algorithm-dependent intensive insulin management, cost-sensitive disposable wearables, and pediatric guardian-oversight platforms.
For Market Incumbents: Insulate algorithmic assets through proprietary closed-loop software validation and recurrent subscription revenue structures that lock in patient lifetime value. Backward integration into disposable patch pump manufacturing in the Yangtze River Delta or Baden-Württemberg regions reduces single-source vulnerability while capturing margin pools currently extracted by East Asian component suppliers. Prioritize IEC 62304 software lifecycle expertise acquisition to compress development timelines as regulatory scrutiny intensifies for AI-enabled dosing systems. For New Entrants and Emerging Players: Build out direct-to-patient distribution infrastructure in the United States pharmacy bypass channel, where vertically integrated fulfillment models are displacing traditional medical device distributors. Target adolescent diabetic populations in Germany and the United States with smaller-form-factor patch pumps featuring guardian oversight capabilities, as pediatric endocrinology practices report accelerated switching cycles to automated platforms. Pursue software-as-a-medical-device classification for subscription-based closed-loop algorithms rather than competing on hardware mechanics where incumbents hold manufacturing scale advantages. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because algorithmic insulin dosing is compressing competitive differentiation around software sophistication rather than hardware mechanics. Acquisition targets should emphasize proprietary data science capabilities and closed-loop architectures with FDA breakthrough device designation momentum. Monitor EU MDR Class III designation discussions for closed-loop pumps as an inflection indicator that would force early-stage companies toward costly notified body partnerships, creating distressed asset opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates pre-market review timelines for patch pump innovations seeking 510(k) clearance. |
| Software-as-a-Medical-Device Classification | Opens recurring revenue streams through subscription-based closed-loop algorithm platforms. |
| Pediatric Indication Expansion | Captures underserved adolescent diabetic populations with guardian oversight features. |
| Direct-to-Patient Distribution | Bypasses pharmacy intermediaries through proprietary fulfillment infrastructure in the United States. |
| Backward Integration into Disposable Manufacturing | Reduces single-source vulnerability for miniaturized infusion components from East Asian clusters. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interviews with endocrinologists, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and diabetes care network executives. Secondary validation drew from FDA 510(k) filings, CMS reimbursement code databases, EU MDR notified body guidance documents, and ISO 15197 glucose monitoring accuracy standards. Bottom-up patient population estimates triangulated against top-down manufacturer shipment data across the analysis window.
Calibration against historical adoption curves for continuous glucose monitors and insulin pump penetration rates anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled included product type, delivery mode, end user setting, and technology integration level, with CAGRs derived from algorithmic adoption velocity in pediatric versus adult populations and CMS reimbursement maturation trajectories. Industry-specific inputs encompassed FDA breakthrough device designation approval timelines and EU MDR post-market surveillance cost escalations.
Practitioners should monitor regulatory classification shifts for AI-enabled dosing algorithms and software-as-a-medical-device guidance evolution for early signals of competitive requirement changes. Forecasts reflect assumptions regarding CMS reimbursement code stability and EU MDR implementation consistency. Material shifts in FDA software lifecycle validation stringency or breakthrough device designation pathway access would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Specimen Retrieval Market
Medical Devices
Pocket Otoscope Market
Medical Devices
Global Coagulation-Hemostasis Analyzer Market
Medical Devices
Knotless Suture Anchors Market
Medical Devices
Supraglottic Airway Devices Market
Medical Devices
Bone Cement Mixers Market
Medical Devices
Infertility Devices Market
Medical Devices
Distal Embolic Filters Market
Medical Devices
Global Artificial Kidney Market
Medical Devices
Remote Magnetic Catheter Systems Market
Medical Devices
Arthroscopic Shaver Market
Medical Devices
Global Thermoelectric Devices in Medical and Laboratory Offering Market
Medical Devices
Global Implantable Loop Recorder Market
Medical Devices
Europe Surgical Visualization Products Market
Medical Devices
Global Non-Surgical Aesthetic Devices Market
Medical Devices
Oxygen Conserving Devices Market