
 Artery Compression Devices Market | 2026-2036
Artery Compression Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Artery Compression Devices Market Outlook
Chinese contract manufacturers of polymer-based medical textiles is expanding output of elastic compression components for vascular closure accessories. Abbott leverages its integrated vascular portfolio to sustain catheter lab placements across North American hospital networks. Merit Medical Systems anchors its position through direct sales teams that control procurement relationships with interventional cardiologists. Teleflex Incorporated differentiates via specialized radial artery compression bands that occupy the premium segment of post-procedure hemostasis.
Artery compression devices are mechanical or material-based systems designed to apply localized external pressure to a vascular access site, typically incorporating silicone pads, woven elastic fabrics, or calibrated mechanical arms with pressure indicators to achieve hemostasis following arterial puncture. These devices serve the primary commercial purpose of reducing time-to-hemostasis, minimizing bleeding complications, and enabling early ambulation after diagnostic or interventional cardiac procedures. Mechanical compressors lead product type demand in high-volume catheterization labs where standardized pressure application reduces nursing variability, while elastic bandages capture home care and lower-acuity settings where cost sensitivity shapes procurement. Silicone dominates material selection for skin-contact surfaces due to its biocompatibility profile and ease of sterilization, though fabric-based alternatives are gaining traction in disposable, single-use protocols.
FDA 510(k) clearance pathways govern market entry for mechanical compression devices in the United States, while the EU Medical Device Regulation requires notified body conformity assessment for radial artery compression bands distributed in European member states. Japan's PMDA enforces QMS inspections for foreign manufacturers seeking approval of Class II hemostasis devices, creating compliance barriers that favor established suppliers with in-country quality infrastructure. Stakeholders must monitor evolving reimbursement codes for same-day discharge after radial access procedures, as payer decisions will determine whether premium compression technologies achieve economic justification against manual compression protocols.
Market Dynamics
The radial-first access protocol is displacing femoral puncture techniques across interventional cardiology, concentrating demand for specialized compression systems designed for wrist-based hemostasis management. This procedural pivot is reshaping product development priorities and procurement specifications in catheterization labs.
Growth Catalysts
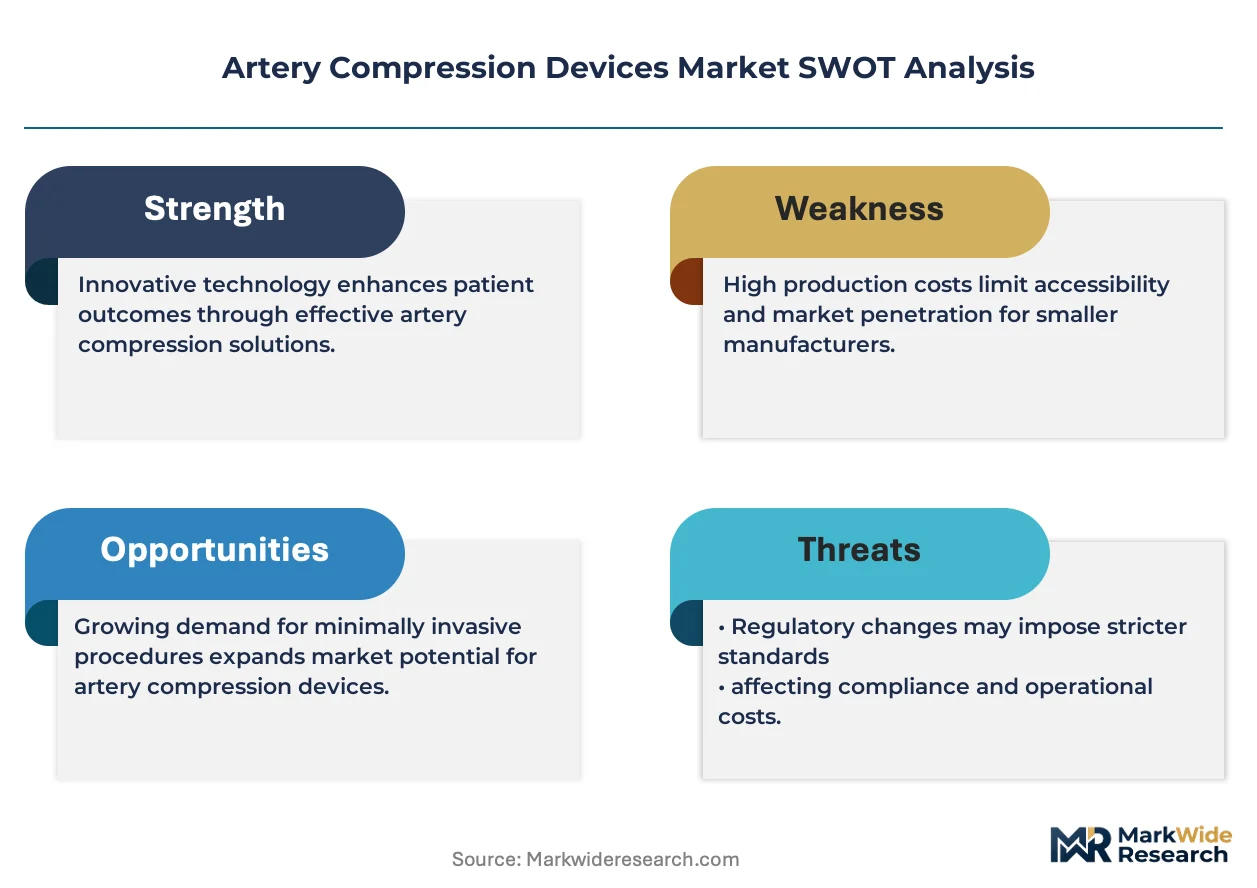
- Japan's PMDA QMS framework:The regulator's inspection requirements for foreign manufacturers create compliance moats that favor established suppliers with in-country quality infrastructure, reducing price competition.
- Silicone biocompatibility profile:The material's sterilization tolerance and skin-contact safety record drives specification lock-in for Class II hemostasis devices across tertiary hospital networks.
- Mechanical compression standardization:High-volume catheterization labs in the United States are adopting calibrated pressure systems to reduce nursing variability and accelerate patient throughput.
Market Restraints
- Polymer input cost volatility:Elastic compression components depend on petroleum-derived feedstocks, exposing contract manufacturers to raw material price swings that compress margin buffers.
- FDA 510(k) pathway friction:Updated Class II guidance for hemostasis management tightens validation requirements, extending time-to-market for new entrants without predicate device strategies.
- Manual compression substitution:Cost-sensitive ambulatory settings continue defaulting to nurse-applied pressure protocols, capping penetration in lower-acuity environments.
Strategic Opportunities
- Home care channel expansion:Post-procedure monitoring protocols are creating demand for disposable elastic bandages in Germany's expanding same-day discharge programs.
- EU MDR conformity acceleration:Notified body assessment requirements for radial artery compression bands favor suppliers with established technical documentation, creating acquisition targets for portfolio-builders.
- Wearable sensor convergence:Integration of pressure-monitoring electronics with mechanical compression arms enables real-time hemostasis verification, opening premium pricing tiers.
Industry Challenges
- ISO 13485 certification timelines:Quality management system audits for multi-site manufacturing create deployment bottlenecks that delay regional market entry.
- Interventional cardiologist training requirements:Radial access technique adoption demands procedural education investments that slow device pull-through in community hospital settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artery Compression Devices Market |
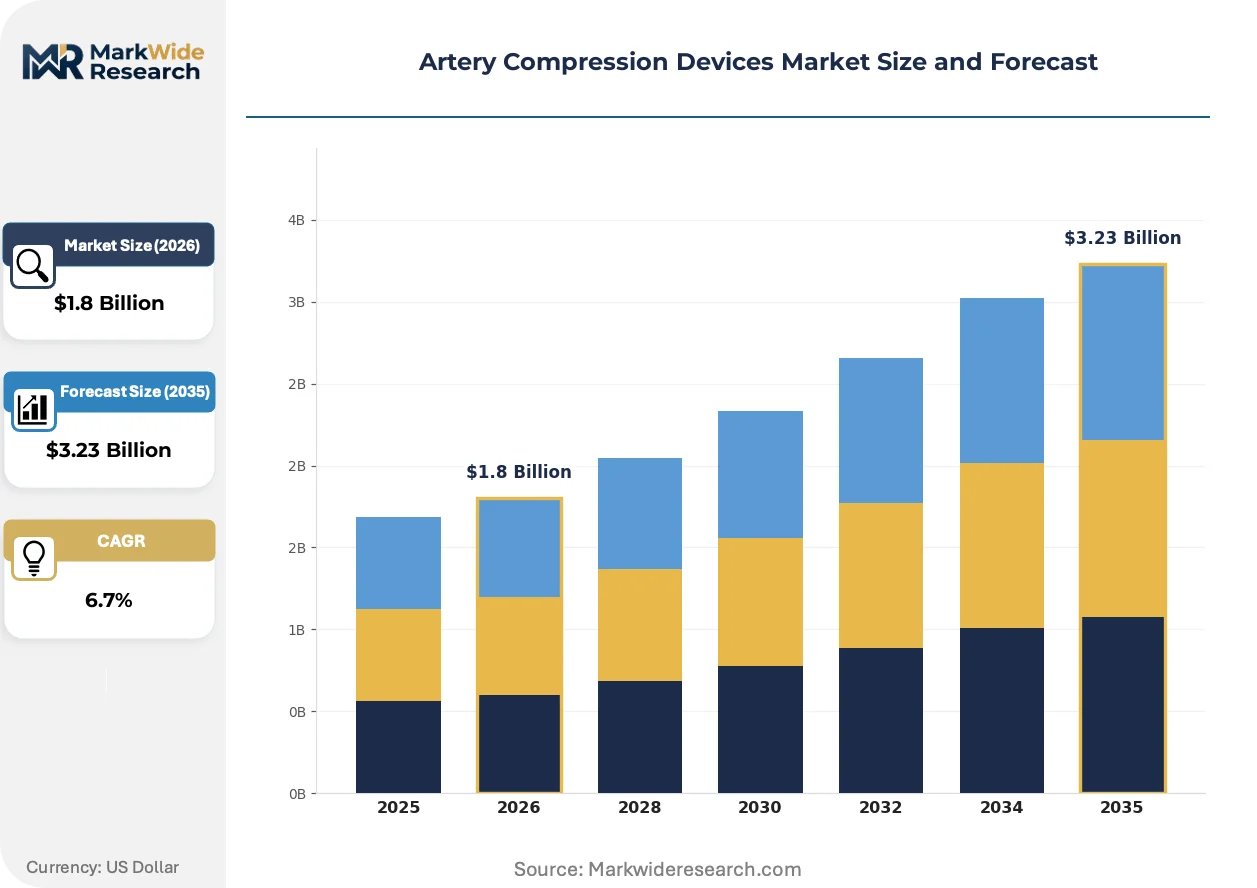
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Compressors, Elastic Bandages, Pressure Pads, Sutures Application: Interventional Procedures, Postoperative Care, Emergency Medicine, Trauma Management Material: Silicone, Foam, Fabric, Metal End User: Hospitals, Clinics, Home Care, Surgical Centers |
| Companies Covered | Terumo Corporation, Abbott, Teleflex Incorporated, Merit Medical Systems, Lepu Medical Technology, TZ Medical, Perouse Medical, Medtronic, AnsCare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artery Compression Devices Market Strategic Shifts
Disposable single-use protocols are displacing reusable mechanical systems across infection-conscious procurement committees. This shift is compressing product lifecycles and redirecting R&D investment toward material science rather than capital equipment durability.
Calibrated pressure indicators embedded in mechanical compression arms is decentralizing hemostasis management from specialized nursing staff to standardized protocols. Community hospitals in the United States are adopting these systems at accelerated rates to reduce training burden. The technology is compressing labor cost structures while enabling faster patient turnover in throughput-constrained labs.
The EU Medical Device Regulation's post-market surveillance requirements are tightening clinical evidence obligations for radial artery compression bands distributed in European member states. Manufacturers must now maintain systematic vigilance data that was previously voluntary. Class II hemostasis devices face the steepest compliance cost increases, favoring larger suppliers with dedicated regulatory affairs capacity.
Hospital procurement committees are unbundling after-sales service from device pricing, shifting toward component-only purchasing with in-house biomedical maintenance. This pattern is most visible in German hospital networks consolidating vendor relationships under centralized purchasing organizations. The disintermediation of technical support contracts is pressuring traditional direct-sales margins while creating openings for third-party service specialists.
Artery Compression Devices Market Segmentation
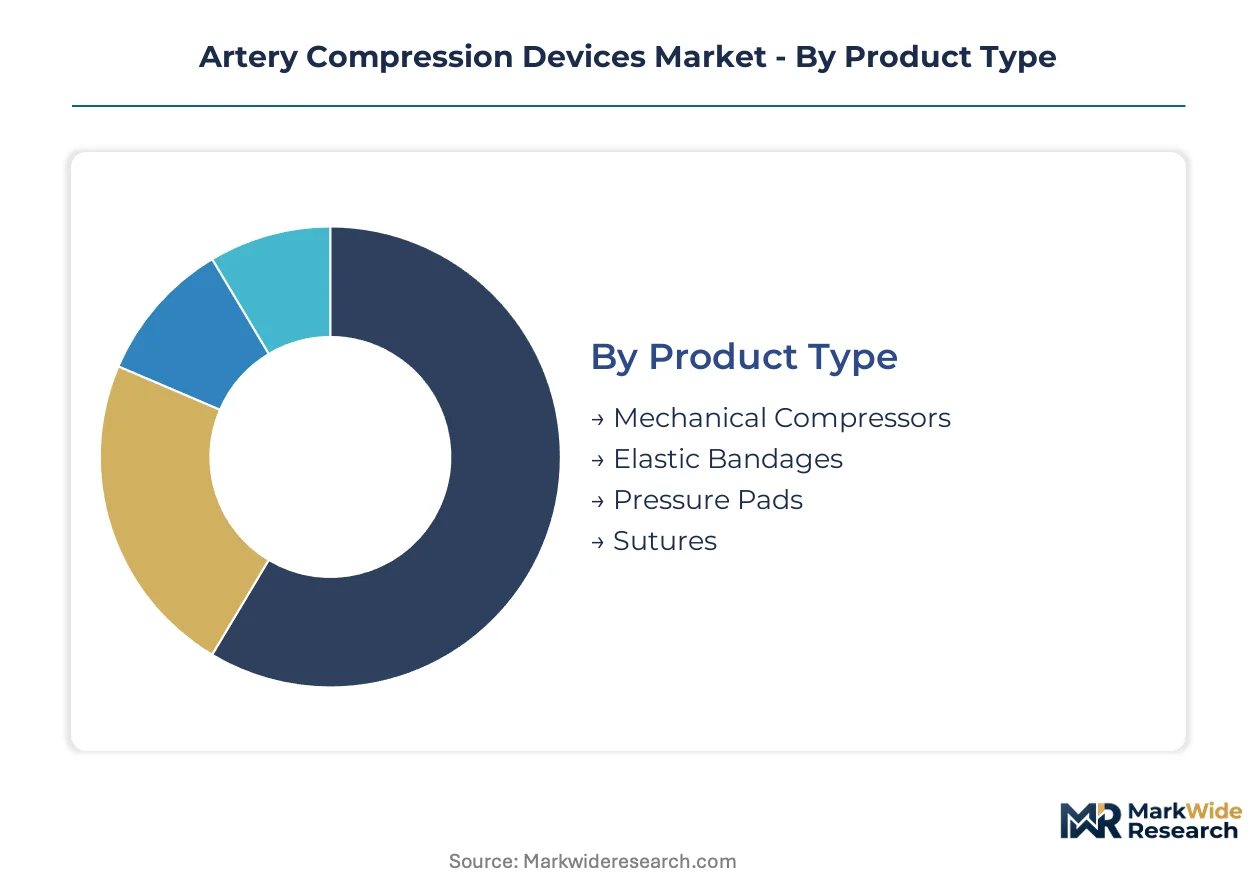
Artery compression devices fragment across four intersecting dimensions that determine procurement specifications, reimbursement pathways, and margin structures. Product type and material selection dominate technical differentiation, while application and end-user channels shape pricing power and competitive intensity.
Product Type:
Mechanical systems command premium positioning through calibrated pressure delivery, while elastic solutions capture volume through disposability and lower per-unit economics.
- Mechanical Compressors:Calibrated mechanical arms with integrated pressure indicators enable standardized hemostasis protocols. Demand concentrates in high-volume catheterization labs across the United States, Germany, and Japan where nursing standardization accelerates patient throughput and reduces complication variability.
- Elastic Bandages:Woven polymer-elastic fabrics with adjustable closure systems provide cost-effective radial artery compression. Adoption is climbing fastest in Germany's same-day discharge programs and Japan's expanding home care channels where cost sensitivity and disposability requirements dominate procurement specifications.
- Pressure Pads:Silicone or foam-backed adhesive pads deliver localized compression without mechanical adjustment.
- Sutures:Proprietary closure devices combining compression with vascular sealing for specific access site anatomies.
Today's leader: Mechanical Compressors. Tomorrow's challenger: Elastic Bandages.
Application:
Procedure complexity and reimbursement intensity determine device selection, with interventional cardiology representing the highest-value deployment environment.
- Interventional Procedures:Diagnostic and therapeutic cardiac catheterization demands precise hemostasis management to enable early ambulation. United States tertiary hospitals are expanding mechanical compressor placements as radial-first protocols displace femoral access techniques and reshape device specifications.
- Postoperative Care:Recovery unit monitoring of vascular access sites requires reliable compression during patient mobilization. Japanese hospital networks prioritize silicone-contact devices for extended wear comfort during post-procedure observation periods.
- Emergency Medicine:Rapid hemostasis in acute settings favors simple mechanical or elastic solutions.
- Trauma Management:External compression for hemorrhage control in field and transport environments.
Interventional Procedures anchor current revenue concentration. Postoperative Care offers the steepest expansion trajectory as same-day discharge protocols proliferate.
Material:
Biocompatibility certification and sterilization tolerance create specification lock-in for skin-contact surfaces, while structural materials determine device durability and cost positioning.
- Silicone:Medical-grade elastomers with established biocompatibility profiles and gamma sterilization tolerance. FDA Class II hemostasis device specifications and EU MDR technical documentation requirements reinforce silicone's specification dominance across tertiary hospital networks in the United States and Germany.
- Foam:Polyurethane or polyethylene foam cores with fabric or film encapsulation for pressure distribution. Chinese contract manufacturers are expanding output of foam-backed components for disposable single-use protocols targeting cost-sensitive procurement committees.
- Fabric:Woven elastic textiles for adjustable compression bandages.
- Metal:Stainless steel or aluminum structural elements in mechanical compression arms.
Silicone maintains incumbent advantage through regulatory validation heritage. Foam materials are gaining share fastest as infection-conscious procurement shifts toward disposability.
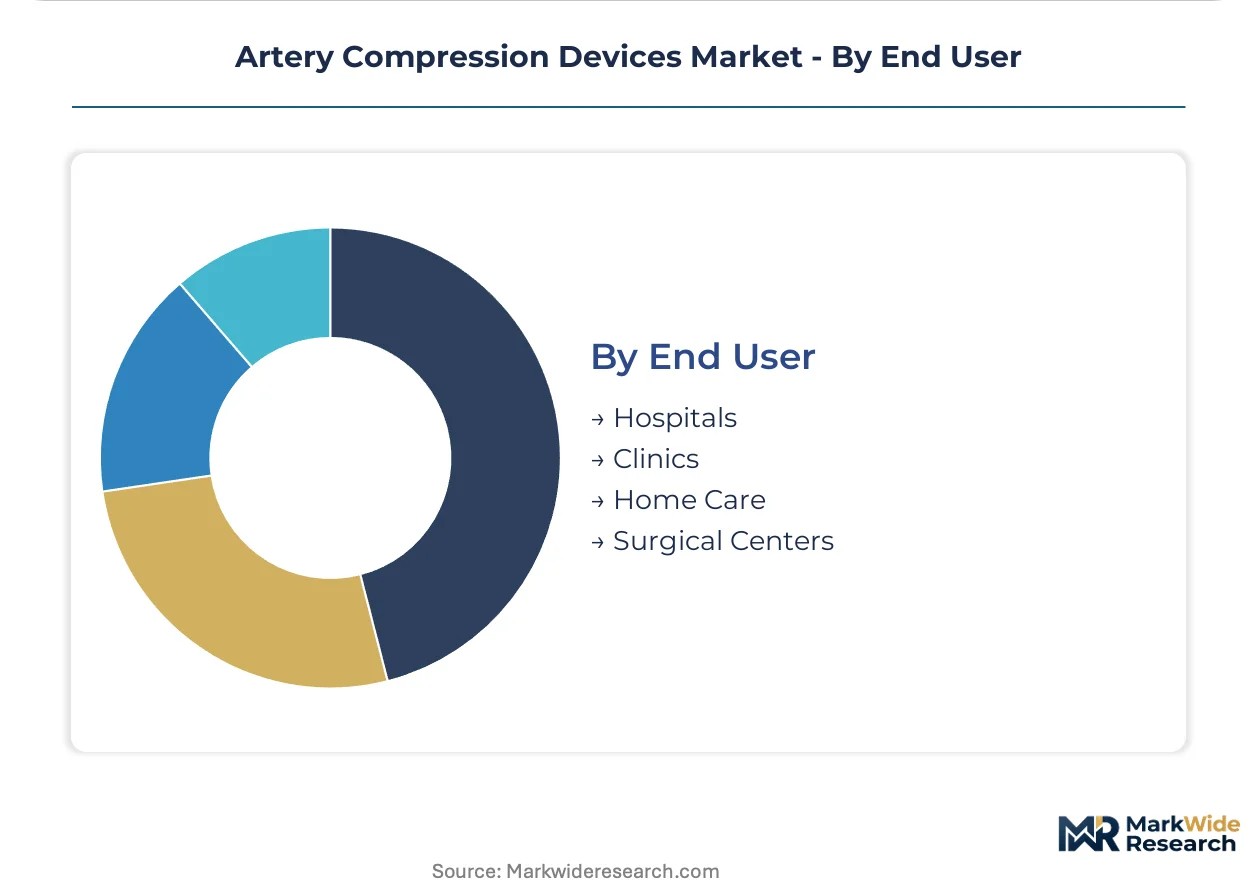
End User:
Channel economics and technical support requirements fragment competitive positioning, with hospital procurement demanding integrated service relationships while home care prioritizes unit cost minimization.
- Hospitals:Tertiary cardiac centers and catheterization labs with high procedural volumes and standardized protocols. German hospital networks are consolidating vendor relationships under centralized purchasing organizations that unbundle after-sales service from device pricing.
- Clinics:Outpatient diagnostic facilities with lower procedural volumes and greater price sensitivity.
- Home Care:Post-discharge patient self-management of hemostasis with remote monitoring support. Japan's aging demographic and expanding same-day discharge programs are creating demand for disposable elastic bandages with simplified application instructions.
- Surgical Centers:Ambulatory surgery facilities with focused procedural mixes and rapid turnover requirements.
Hospitals represent the most contested channel. Home Care is expanding most quickly as radial access enables earlier patient discharge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of elastic compression components is migrating toward Chinese contract manufacturers as cost-of-compliance gaps widen between established medical device hubs and emerging fabrication centers. FDA 510(k) pathway friction and Japan's PMDA QMS inspections create regulatory moats that favor incumbent suppliers with dedicated quality infrastructure in premium markets.
United States
Radial-first access protocol adoption in tertiary cardiac centers is accelerating mechanical compressor placements across high-volume catheterization labs. FDA's updated Class II guidance for hemostasis management tightens validation requirements, extending time-to-market for new entrants lacking predicate device strategies. The Greater Boston and Pacific Northwest clusters host concentrated interventional cardiology research infrastructure driving next-generation compression technology development.
Germany
Hospital networks are consolidating vendor relationships under centralized purchasing organizations that unbundle after-sales service from device pricing. EU Medical Device Regulation post-market surveillance requirements tighten clinical evidence obligations for radial artery compression bands distributed across member states. The Baden-Württemberg industrial corridor anchors precision manufacturing capabilities for calibrated mechanical compression systems serving European hospital procurement committees.
Japan
Aging demographics and expanding same-day discharge programs are creating demand for disposable elastic bandages with simplified patient application instructions. PMDA enforces QMS inspections for foreign manufacturers seeking approval of Class II hemostasis devices, creating compliance barriers that favor established suppliers with in-country quality infrastructure. The Kanto region surrounding Tokyo concentrates interventional cardiology infrastructure where radial access protocols displace femoral puncture techniques.
China
Contract manufacturers of polymer-based medical textiles are expanding output of elastic compression components for vascular closure accessories targeting global export markets. NMPA regulatory harmonization with international standards is gradually elevating domestic quality benchmarks for Class II hemostasis devices. The Yangtze River Delta manufacturing cluster specializes in disposable single-use protocol components serving infection-conscious procurement committees worldwide.
Artery Compression Devices Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in wearable sensor convergence and home care disposability. The vendor base stratifies across three tiers: integrated cardiovascular portfolios with catheter lab placement control, specialized radial compression specialists commanding premium positioning, and contract manufacturers capturing volume in elastic component supply. Dominant competitive moves include portfolio diversification into integrated vascular closure systems and geographic expansion through notified body conformity acceleration for EU MDR compliance.
Among Japan-based diversified medical technology groups, Terumo Corporation exemplifies the integrated cardiovascular portfolio archetype with established quality infrastructure spanning multiple regulatory jurisdictions. Abbott and Teleflex Incorporated represent North American-based specialists with differentiated positioning across the mechanical-to-elastic product spectrum, each anchoring distinct procurement relationship models with interventional cardiology departments. These three entities collectively illustrate how regulatory validation heritage and catheter lab placement density determine competitive positioning in hemostasis management.
| Leading Market Players |
|---|
| Terumo Corporation |
| Abbott |
| Teleflex Incorporated |
| Merit Medical Systems |
| Lepu Medical Technology |
| TZ Medical |
| Perouse Medical |
| Medtronic |
| AnsCare |
| Others |
Value Chain & Pricing Dynamics
EU MDR post-market surveillance mandates gate qualified supply for radial artery compression bands, restricting premium-tier pricing access to manufacturers with dedicated regulatory affairs capacity and systematic clinical vigilance infrastructure. This environmental compliance layer concentrates margin capture among established suppliers while elevating entry costs for new market participants.
Pricing Analysis
Direct-to-hospital contracting discounts dominate mechanical compressor transactions, with distributor margins compressed by centralized purchasing organizations in German hospital networks. Three-tier pricing structure across premium, standard, and economy levels differentiates by after-sales service bundling and ISO 13485 certification tier. Pricing pressure stems from unbundling of technical support contracts, with component-only procurement eroding traditional service-inclusive margins. Ambulatory surgical centers exhibit highest price sensitivity, while tertiary cardiac centers prioritize standardization over unit cost.
Supply Chain Analysis
ISO 13485 certification timelines gate supply chain participation, with quality management system audits creating bottlenecks for multi-site manufacturing deployment. Production concentrates in China, Germany, and the United States, with Chinese contract manufacturers expanding polymer-based medical textile output for elastic compression components. Raw material dependencies center on petroleum-derived polymer feedstocks, medical-grade silicone elastomers, and gamma-sterilization-compatible fabrics. Single-source vulnerability runs through specialized silicone suppliers serving Class II hemostasis device specifications. Distribution runs through direct sales teams controlling catheter lab procurement relationships and third-party service specialists filling technical support gaps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Japan's PMDA QMS inspection requirements and China's NMPA regulatory harmonization trajectory, with compliance cost differentials creating margin expansion opportunities for manufacturers with dual-territory quality infrastructure.
For Market Incumbents: Hedge against elastic bandage commoditization by deepening backward integration into medical-grade silicone production and accelerating wearable sensor convergence in mechanical compression arms. Threat substitution from disposable single-use protocols demands captive supply of gamma-sterilization-tolerant materials to defend margin position in premium tiers. For New Entrants and Emerging Players: Capture white-space in Japan's expanding home care channel and Germany's same-day discharge programs where simplified patient application instructions create differentiation openings. Postoperative care represents the most penetrable application segment. A direct-to-patient digital education platform paired with disposable elastic bandages offers viable go-to-market positioning. For Investors and Strategic Acquirers: Roll-up economics work for EU MDR-ready notified body assessment specialists because conformity acceleration requirements favor acquisition over organic technical documentation buildout. Five-to-ten year viability hinges on radial-first protocol permanence in interventional cardiology. Acquisition targets should demonstrate established PMDA quality infrastructure. The signal to watch is reimbursement code expansion for same-day discharge after radial access procedures.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Predicate device strategies accelerate clearance for mechanical compression systems targeting high-volume catheterization labs. |
| CE Marking Pathway | Notified body conformity assessment creates acquisition premiums for radial artery compression bands with established technical files. |
| Hospital System Partnership | Integrated vascular portfolio placements secure procurement relationships with interventional cardiology departments across North American networks. |
| Software Companion Development | Pressure-monitoring electronics integration enables real-time hemostasis verification and premium pricing tier capture. |
| Reimbursement Strategy | Payer decisions on same-day discharge codes determine economic justification for premium compression technologies against manual protocols. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and PMDA approval registries. Bottom-up segment sizing and top-down market triangulation cross-verified volume and value estimates.
Segment-weighting approaches distributed value across product type, material, application, and end-user dimensions, with interventional cardiology procedure volumes and radial access adoption rates serving as primary demand drivers throughout the projection horizon. CAGRs derived from fitted growth curves applied to base-year estimates, adjusted for regulatory pathway friction and procurement consolidation trends in German and Japanese hospital networks.
Regulatory timeline slippage, polymer input cost volatility, and reimbursement code revision are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding radial-first protocol permanence and Class II device validation requirements. A model refresh is warranted upon material change in FDA guidance for hemostasis management or PMDA QMS inspection intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Remote Endarterectomy Devices Market
Cardiovascular Devices
Balloon Catheters Market
Cardiovascular Devices
Atrial Fibrillation (AF) Ablation Market
Cardiovascular Devices
Extracorporeal Membrane Oxygenation (ECMO) Market
Cardiovascular Devices
Tricuspid Valve Repair Market
Cardiovascular Devices
Fluid Aspiration System Market
Cardiovascular Devices
Endovascular Stent Market
Cardiovascular Devices
Infusion Catheters Market
Cardiovascular Devices
Global Abdominal Aortic Aneurysm Treatment Market
Cardiovascular Devices
Cardiac Rhythm Management Devices Market
Cardiovascular Devices
Disposable Blood Pressure Cuffs Market
Cardiovascular Devices
Global Cardiac Output Monitoring Devices Market
Cardiovascular Devices
3D Cardiac Mapping Systems Market
Cardiovascular Devices
Global Coronary Stent Market
Cardiovascular Devices
United States Cardiovascular Devices Market
Cardiovascular Devices
India Cardiovascular Devices Market