
 Point of Care Glucose Testing Market | 2026-2036
Point of Care Glucose Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Point of Care Glucose Testing Market Intelligence
A shift towards individual patient monitoring in homecare settings is decoupling purchasing decisions from large institutional buyers like hospitals. Abbott leverages its extensive distribution network to reach consumers directly. F. Hoffmann-La Roche Ltd. differentiates through its focus on high-accuracy devices for both clinical and personal use. Nova Biomedical competes by specializing in integrated, hospital-grade point-of-care systems for critical care environments.
Point of care glucose testing involves devices that provide immediate blood glucose readings from a small sample, typically using electrochemical biosensors. These instruments are designed for use outside of a central laboratory, enabling rapid clinical decisions and patient self-management. While self-monitoring devices and their associated testing strips constitute a mature product category, continuous glucose monitors represent the fastest-growing segment. The hospital end-user segment commands significant volume due to critical care requirements.
Regulatory oversight from bodies like the US FDA, the European Medicines Agency (EMA), and China's NMPA is stringent. These agencies enforce strict accuracy standards, such as ISO 15197, and scrutinize data security for connected devices. The key decision for manufacturers will be how to integrate advanced connectivity and data analytics features while maintaining affordability for the expanding homecare segment.
Market Dynamics
The decentralization of diagnostics is the central force shaping the point of care glucose testing market. This structural shift moves testing from centralized hospital labs to homecare and outpatient settings, fundamentally altering device design requirements, distribution logistics, and data management strategies.
Growth Catalysts
- Non-Invasive Technologies:The development of advanced biosensors that can measure glucose through sweat, tears, or interstitial fluid is reducing the reliance on painful fingerpricks, which enhances patient adherence to testing protocols in homecare environments.
- Epidemiological Trends:A rising prevalence of diabetes and pre-diabetes, particularly in populous nations like China and the United States, creates a large, sustained patient base requiring regular glucose monitoring for disease management.
- Reimbursement Policies:Expanding insurance coverage and favorable reimbursement policies for continuous glucose monitors (CGMs) in several developed countries are making advanced monitoring technologies more accessible to a broader patient population, driving adoption.
Market Restraints
- Cost and Reimbursement Gaps:The high upfront cost of CGM systems and the recurring expense of disposable sensors remain significant barriers to adoption, particularly in markets without comprehensive public or private insurance coverage for these devices.
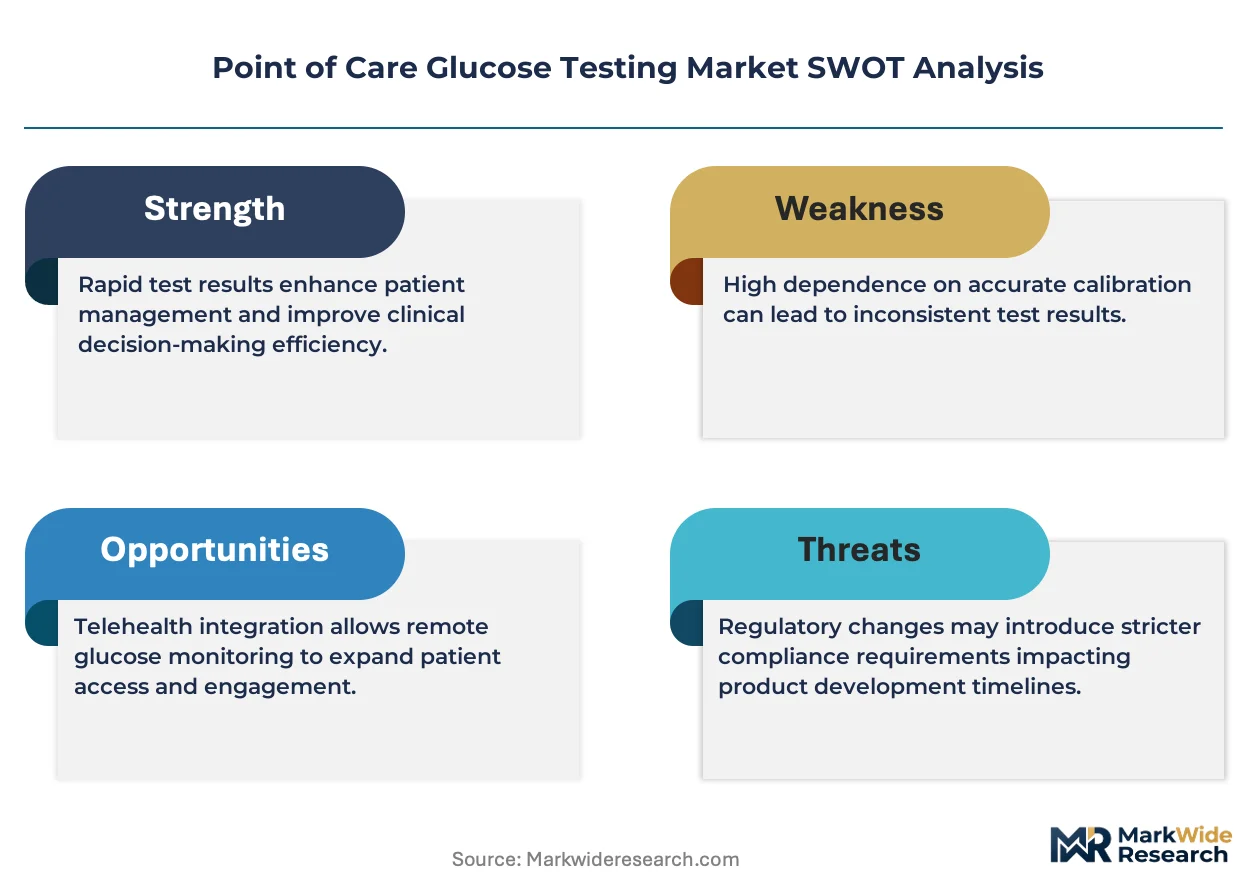
- Stringent Regulatory Hurdles:Compliance with rigorous accuracy standards, such as ISO 15197, and data security mandates for connected devices from bodies like the FDA and EMA creates long development timelines and high validation costs for manufacturers.
- Technical Limitations:Issues such as calibration requirements, sensor lifespan, and potential interference from certain medications can affect the reliability and user experience of some point-of-care devices, limiting user trust and consistent use.
Strategic Opportunities
- Emerging Market Penetration:Untapped demand in Latin American and Southeast Asian countries, where healthcare spending is increasing and awareness of diabetes management is growing, presents a significant geographic expansion opportunity for device manufacturers.
- Digital Health Integration:The convergence of glucose monitoring with digital health platforms, smartphone apps, and wearable technology enables the creation of comprehensive ecosystems for holistic chronic disease management, moving beyond simple data collection.
- Wellness and Metabolic Health:Expanding the application of CGM technology beyond diabetes to wellness-focused consumers, such as athletes and individuals interested in personalized nutrition, opens an entirely new, non-clinical market segment.
Industry Challenges
- Data Interoperability:Ensuring seamless and secure integration of data from a wide array of glucose monitoring devices into disparate electronic health record (EHR) systems remains a major operational challenge for healthcare providers and IT departments.
- Manufacturing and Quality Control:Scaling the production of highly sensitive electrochemical biosensors and CGM components to meet global demand, while maintaining stringent quality control and cost-efficiency, poses a significant manufacturing hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Point of Care Glucose Testing Market |
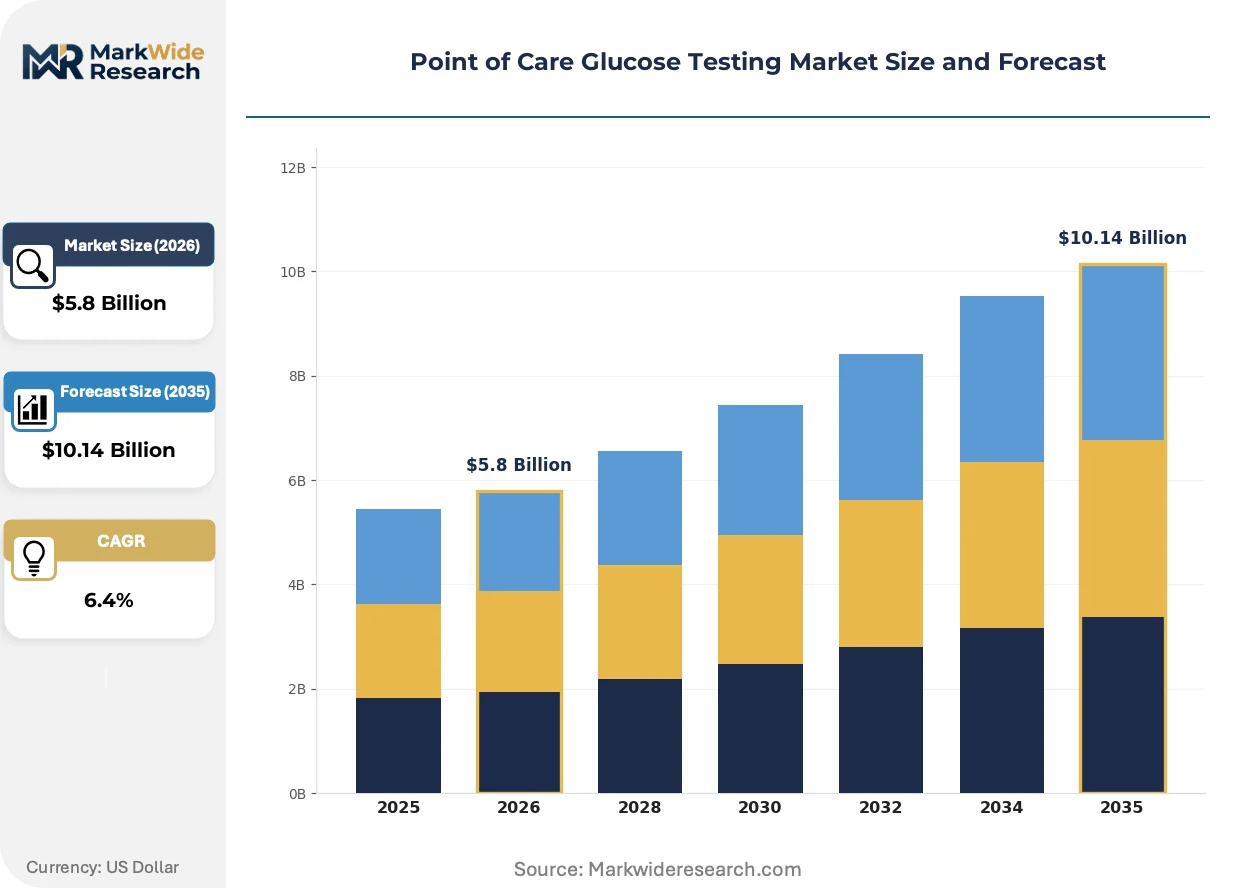
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Monitoring Devices, Continuous Glucose Monitors, Testing Strips, Lancets End User: Homecare, Hospitals, Diagnostic Laboratories, Pharmacies Technology: Lateral Flow, Electrochemical, Optical, Biosensors Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesale |
| Companies Covered | Abbott, F. Hoffmann-La Roche Ltd., Nova Biomedical, Nipro, Ascensia Diabetes Care Holdings AG, ACON Laboratories, Trividia Health, Prodigy Diabetes Care, Danaher, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Point of Care Glucose Testing Market Strategic Shifts & Innovations
The market's evolution is defined by the transition from discrete measurement to continuous, data-driven health management. This shift is powered by innovations in sensor technology, connectivity, and the analytical platforms that interpret glucose data, transforming it into actionable health intelligence for patients and clinicians.
Continuous glucose monitoring (CGM) technology provides real-time glucose readings from interstitial fluid, eliminating the need for routine fingerpricks. Its adoption is accelerating among patients with Type 1 diabetes and those with Type 2 diabetes on intensive insulin therapy. This technology is absorbing the market for traditional self-monitoring blood glucose (SMBG) by delivering trend data and predictive alerts, shifting the focus from isolated measurements to a complete glycemic profile.
Heightened regulatory focus on the cybersecurity of connected medical devices is coming from agencies like the US FDA and European authorities enforcing GDPR. This pressure compels manufacturers to implement robust data encryption, secure user authentication, and proactive vulnerability management across the device lifecycle. The homecare device segment is most impacted, requiring a careful balance between user-friendly connectivity and stringent security to protect patient data on personal networks.
A significant behavioral change is the direct purchase of glucose monitoring supplies through online pharmacies and direct-to-consumer subscription services. This model often bypasses traditional channels like physical pharmacies and some durable medical equipment (DME) suppliers. This consumer-driven shift is especially visible in the United States, where convenience and price transparency are increasingly influencing purchasing decisions for self-monitoring products.
Point of Care Glucose Testing Market Segmentation
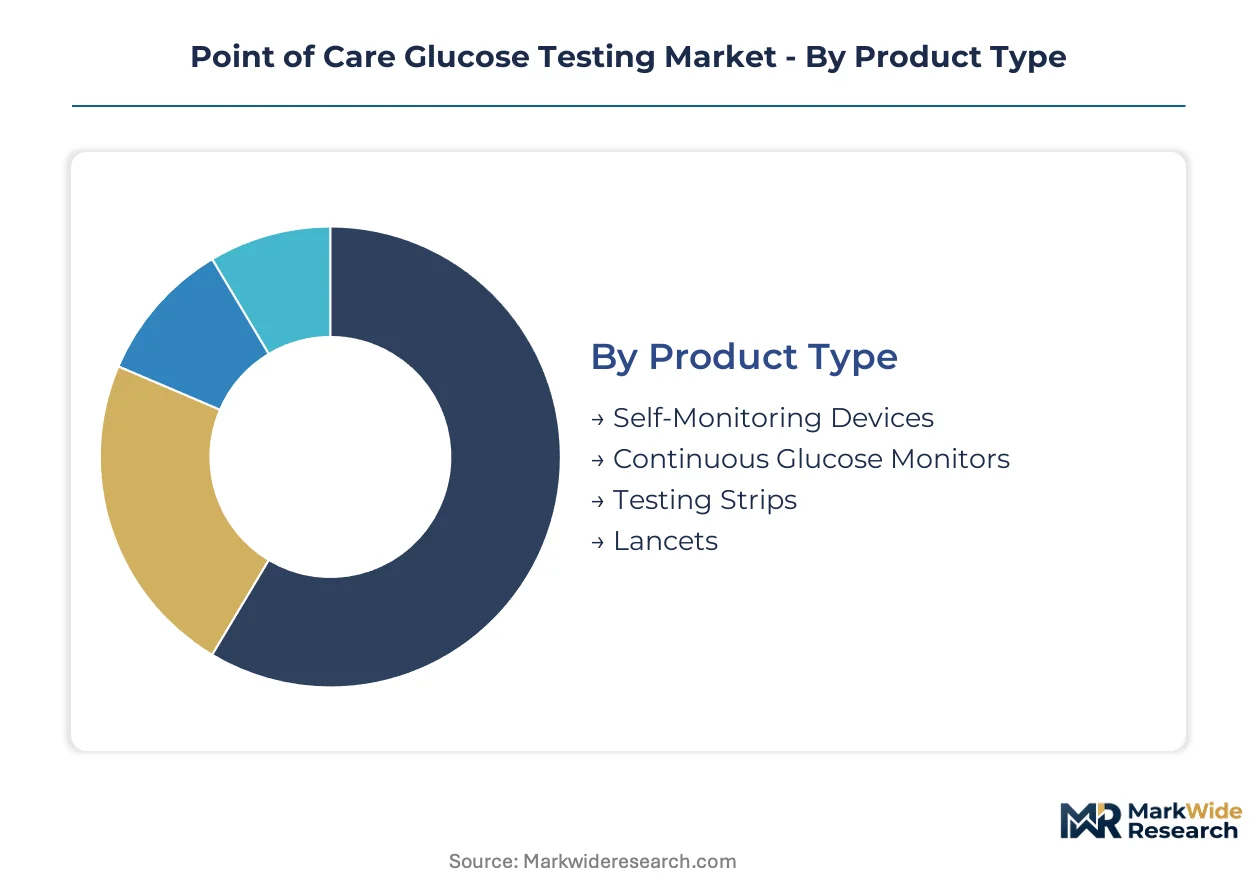
Segmentation provides a granular view of the Point of Care Glucose Testing Market, revealing distinct demand drivers, regulatory landscapes, and technological preferences across various categories. Understanding these divisions helps manufacturers tailor product development and market entry strategies effectively.
Product Type:
Regulatory bodies like the US FDA and European EMA impose distinct certification burdens on different product types, particularly for devices involved in continuous patient monitoring.
- Continuous Glucose Monitors:These advanced devices provide real-time glucose readings from interstitial fluid, eliminating routine fingerpricks. Demand concentrates in developed countries like the United States due to expanding insurance coverage and favorable reimbursement policies.
- Self-Monitoring Devices:Traditional blood glucose meters require a small blood sample for discrete, immediate readings. Patient self-management in homecare settings drives significant volume, particularly in populous nations like China.
- Testing Strips:These consumable components are essential for traditional self-monitoring devices, requiring precise chemical coatings for accurate readings.
- Lancets:Small, disposable needles facilitate blood sample collection for self-monitoring, emphasizing patient comfort and safety.
Testing Strips sit at the top of the volume ranking, with Continuous Glucose Monitors climbing the fastest.
End User:
Different end-user segments exhibit varying procurement patterns and demand characteristics for glucose testing solutions.
- Homecare:This segment includes individuals managing their diabetes at home, utilizing devices for self-monitoring and personal health management. Decentralization of diagnostics and patient self-management trends in countries like the United States are driving this segment's expansion.
- Hospitals:Hospitals require high-accuracy point-of-care systems for critical care environments and rapid clinical decision-making. Critical care requirements and emergency diagnostics contribute to significant volume consumption within institutional settings.
- Diagnostic Laboratories:These facilities use point-of-care devices for quick, preliminary screenings before sending samples for full lab analysis.
- Pharmacies:Pharmacies serve as accessible points for basic glucose testing services and direct sales of self-monitoring devices to consumers.
Homecare shows the steepest expansion trajectory, while Hospitals maintain consistent high volume.
Technology:
Technological innovation defines the competitive landscape, with established methods coexisting with advanced non-invasive approaches.
- Biosensors:These advanced sensors utilize biological components to detect glucose levels, often forming the core of continuous glucose monitors. Non-invasive technologies measuring glucose through interstitial fluid are a key technological enabler in this segment.
- Electrochemical:Electrochemical biosensors measure glucose concentration by detecting electrical current generated from enzymatic reactions. This technology forms the basis for most traditional self-monitoring blood glucose devices, ensuring widespread use.
- Optical:Optical technologies detect glucose levels through changes in light absorption or scattering, offering potential for non-invasive applications.
- Lateral Flow:Lateral flow assays provide rapid, qualitative or semi-quantitative results for glucose detection, typically used in simpler screening tests.
Biosensors are gaining share fastest, while Electrochemical remains the dominant underlying principle.
Distribution Channel:
Supply concentration varies significantly across distribution channels, influencing pricing and market reach for manufacturers.
- Online Retail:E-commerce platforms and direct-to-consumer subscription services facilitate convenient purchase of glucose monitoring supplies. This channel is experiencing significant growth in the United States, driven by consumer preference for convenience and price transparency.
- Direct Sales:Manufacturers engage directly with large institutional buyers like hospitals and healthcare systems for bulk procurement. This channel ensures specialized support and tailored solutions for critical care environments and complex integrated systems.
- Offline Retail:Traditional brick-and-mortar pharmacies and medical supply stores serve as primary access points for many self-monitoring products.
- Wholesale:Wholesalers procure devices and consumables in large volumes, distributing them to a network of smaller retailers and healthcare providers.
Online Retail is expanding most quickly, challenging traditional Offline Retail patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A concentration of specialized medical device engineers and researchers drives innovation across key global regions for point of care glucose testing. These areas benefit from established healthcare infrastructures and significant patient populations requiring continuous monitoring solutions. Regulatory frameworks also play a pivotal role in shaping market access and technology adoption across these diverse geographies.
United States
The United States exhibits strong demand for advanced continuous glucose monitors, driven by a large diabetic population and patient preference for self-management. The US FDA enforces rigorous accuracy standards, including ISO 15197, for all glucose monitoring devices, ensuring product reliability. Boston's MedTech corridor remains a hub for biosensor innovation, fostering the development of next-generation non-invasive technologies.
China
China's burgeoning diabetic population creates immense demand for both traditional self-monitoring devices and emerging continuous glucose monitors. China's NMPA actively regulates medical devices, focusing on local manufacturing and quality control to meet national health objectives. Shanghai's biomedical parks are rapidly expanding, supporting domestic companies in developing and producing glucose testing solutions.
Germany
Germany prioritizes high-accuracy point-of-care systems for both clinical and personal use, supported by a robust healthcare system and an aging demographic. The European Medicines Agency (EMA) and the Medical Device Regulation (MDR) ensure strict compliance for device safety and performance across the EU. Munich's medical technology hub contributes significantly to advanced sensor development and digital health integration.
Japan
Japan demonstrates a strong inclination towards technological adoption in healthcare, favoring precision diagnostics and user-friendly glucose monitoring devices. Japan's PMDA oversees medical device approvals, ensuring high standards for product efficacy and patient safety. Tokyo's research institutions lead efforts in non-invasive glucose monitoring, exploring optical and other advanced sensing methods.
India
India's burgeoning diabetic population and expanding healthcare infrastructure fuel demand for affordable and accessible glucose testing solutions. India's CDSCO regulates medical devices, working to standardize quality and promote local production to serve the vast market. Bengaluru's biotech sector is attracting investment for local device development, aiming to cater to diverse patient needs.
Point of Care Glucose Testing Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists in the point of care glucose testing market, creating a tiered competitive structure. This market features large multinational healthcare companies alongside agile innovators specializing in specific device types or technologies. Strategic partnerships and technology licensing agreements are prevalent competitive moves, allowing companies to expand their product portfolios and geographic reach.
Among the large diversified healthcare companies, Abbott and F. Hoffmann-La Roche Ltd. represent established players with extensive distribution networks and broad product offerings. Nova Biomedical occupies a position as a specialized manufacturer, focusing on high-accuracy, hospital-grade point-of-care systems for critical care environments. These companies anchor different segments of the market, from consumer-focused self-monitoring to clinical-grade diagnostics.
| Leading Market Players |
|---|
| Abbott |
| F. Hoffmann-La Roche Ltd. |
| Nova Biomedical |
| Nipro |
| Ascensia Diabetes Care Holdings AG |
| ACON Laboratories |
| Trividia Health |
| Prodigy Diabetes Care |
| Danaher |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps and venture-backed innovators influence supply behavior, impacting the pricing discipline for point of care glucose testing devices. This dynamic shapes affordability and market access for diverse end-users.
Pricing Analysis
The bundled-versus-unbundled service split significantly influences pricing strategies in point of care glucose testing. Per-unit transactional pricing dominates for self-monitoring devices, while continuous glucose monitors increasingly adopt subscription models for sensors. Price differentiation stems from accuracy certifications, such as ISO 15197, and the level of integrated digital health support. Pricing pressure stems from the rapid adoption of continuous glucose monitors displacing traditional self-monitoring blood glucose devices, with homecare consumers exhibiting the highest price sensitivity compared to hospitals.
Supply Chain Analysis
Logistics and freight costs significantly influence the global distribution of point of care glucose testing devices, with supply concentration for advanced biosensors and electrochemical components centering in China, the United States, and Germany. The market relies on specialized testing strip chemicals and microprocessors as key raw materials. Regulatory restrictions from bodies like China's NMPA and the US FDA present a structural supply chain risk, especially for complex integrated systems. Distribution runs through online retail for homecare and direct sales channels for institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The point of care glucose testing market presents a margin-expansion story, driven by the premium-tier shift towards continuous glucose monitors. Advanced biosensor technologies allow for higher value capture and improved patient outcomes.
For Market Incumbents: Anticipate the disruption from nimble digital health startups and emerging non-invasive technologies by deepening R&D into next-generation biosensors. Market incumbents should acquire specialized technology startups to integrate advanced data analytics platforms. Expanding direct-to-consumer subscription models will enhance channel control and customer loyalty. Investment in robust cybersecurity measures is crucial given heightened regulatory scrutiny from the US FDA and EMA.
For New Entrants and Emerging Players: Non-invasive biosensor technology offers a compelling wedge for new entrants to penetrate the point of care glucose testing market. Target the wellness and metabolic health segment by offering integrated digital health platforms and smartphone applications. Focus on underserved emerging markets in Latin America and Southeast Asia with affordable, user-friendly solutions. Direct-to-consumer online sales models will bypass traditional distribution challenges.
For Investors and Strategic Acquirers: Valuations sit cheapest among traditional self-monitoring device manufacturers facing CGM displacement. The long-term viability of this market remains strong, driven by chronic disease prevalence and continuous technological innovation over the next 5-10 years. Strategic acquirers should target specialized biosensor developers and digital health platform providers. Watch for expanding reimbursement policies for continuous glucose monitors in new developed and emerging markets as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Biosensor R&D | Drives non-invasive monitoring solutions, improving patient adherence and market differentiation. |
| Digital Health Platform Integration | Creates comprehensive chronic disease management ecosystems, enhancing patient engagement and data utility. |
| Emerging Market Entry | Captures untapped demand in populous nations with rising diabetes prevalence and increasing healthcare spending. |
| Direct-to-Consumer Channel Expansion | Bypasses traditional distribution, offering convenience and price transparency for homecare users. |
| Cybersecurity Protocol Enhancement | Ensures patient data security and regulatory compliance for connected medical devices under FDA and EMA scrutiny. |
Research Approach
Multiple input streams — primary interviews, secondary validation, and quantitative market data — were reconciled to build a robust understanding of the market. Primary research included discussions with clinicians, hospital purchasing committees, and biomedical engineers. Secondary data sources comprised regulatory filings with the US FDA and EMA, medical device registries, and academic literature. This approach ensured bottom-up and top-down triangulation of market sizing and trends.
Data-stream reconciliation formed the basis of the quantitative forecasting model across the analysis window. The framework modeled segmentation dimensions including product type, end-user, technology, and distribution channel, alongside regional regulatory clusters. Compound annual growth rates were derived from historical data and projected market dynamics. Key industry-specific forecast inputs included diabetes prevalence rates and insurance reimbursement trends for continuous glucose monitors.
The model holds under current epidemiological trends and regulatory frameworks; deviation in unforeseen regulatory changes or rapid non-invasive technology breakthroughs would shift market trajectories. Forecasts reflect assumptions regarding healthcare infrastructure development and patient adoption rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
South Africa Oral Antidiabetic Drug Market
Diabetes Care
Insulin Pen Needles Market
Diabetes Care
New Zealand Insulin Drugs and Devices Market
Diabetes Care
Vietnam Oral Anti-Diabetic Drug Market
Diabetes Care
South Korea Insulin Infusion Pump Market
Diabetes Care
India Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Mexico Continuous Glucose Monitoring Market
Diabetes Care
Egypt Diabetes Care Devices Market
Diabetes Care
Middle East and Africa Diabetes Care Devices Market
Diabetes Care
New Zealand Self-Monitoring Blood Glucose Market
Diabetes Care
Oman Diabetes Drugs Market
Diabetes Care
Australia Insulin Infusion Pump Market
Diabetes Care
United States Self-Monitoring Blood Glucose Market
Diabetes Care
BRIC Diabetes Care Devices Market
Diabetes Care
Middle-East and Africa Blood Glucose Monitoring Market
Diabetes Care
Disposable Insulin-Delivery Device Market