
 Diabetic Shoes Market | 2026-2036
Diabetic Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Diabetic Shoes Market Analysis
Medical-grade construction is rotating toward Medicare-certified therapeutic depth standards that require removable insoles and extra-width toe boxes. Apex Foot Health Industries leverages in-house orthotic manufacturing to control material consistency from plantar plate to heel counter. Propét USA Inc. anchors its position through extended sizing matrices that serve edema-progression stages. DJO Global Inc. (Dr. Comfort) dominates the direct-to-patient channel with podiatrist-partnered fitting protocols.
Diabetic shoes are biomechanical footwear engineered with pressure-mapping outsoles, seamless interiors, and heat-moldable midsoles to redistribute plantar pressure and prevent neuropathic ulceration in diabetic patients. Women's Shoes command volume leadership due to broader Medicare eligibility pathways for female beneficiaries with peripheral neuropathy, while Custom Shoes capture margin concentration through CAD-CAM orthotic integration and bilateral asymmetry correction. Distribution through Specialty Stores sustains higher average fittings per patient because certified pedorthists perform dynamic gait analysis during the purchase process.
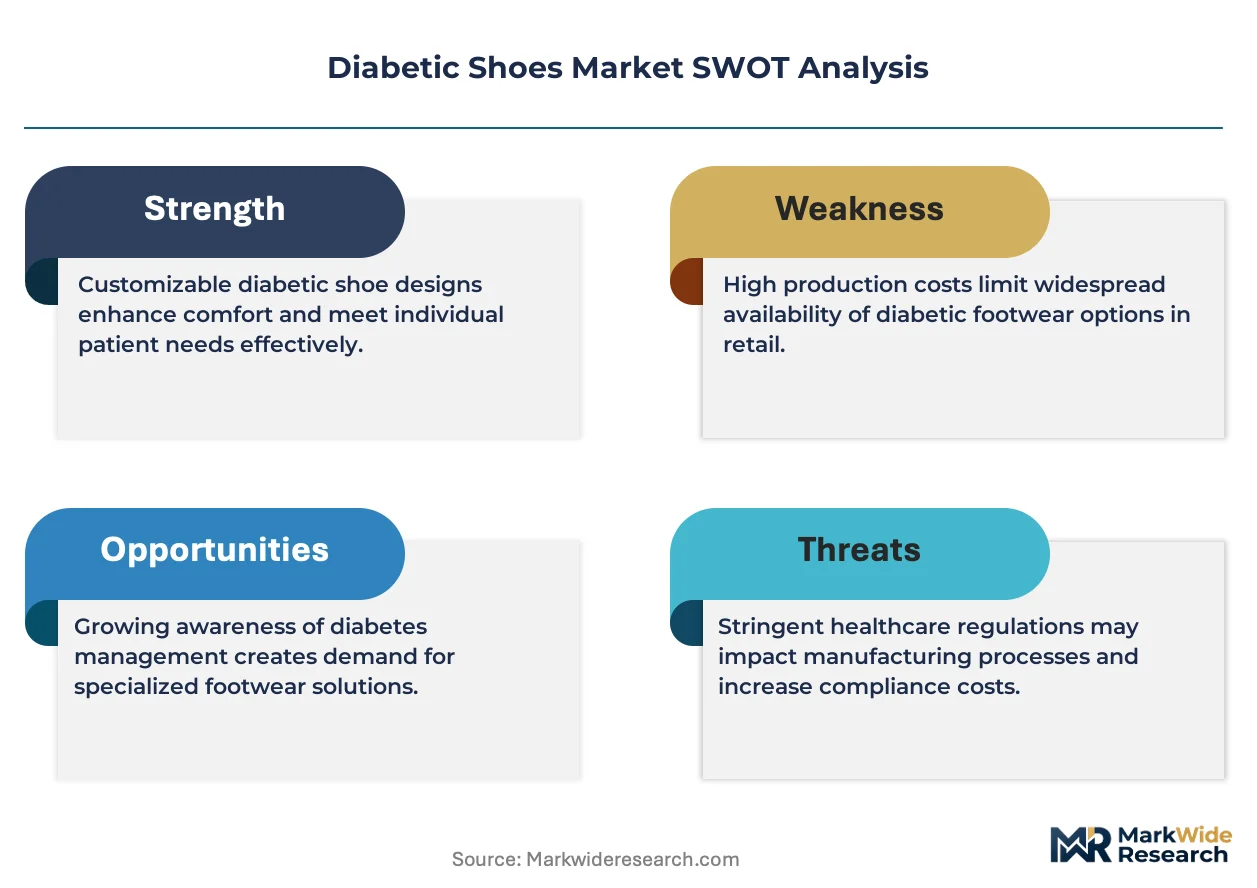
FDA 510(k) clearance pathways govern Class I therapeutic footwear claims in the United States, while Medicare's Therapeutic Shoes for Persons with Diabetes benefit (HCPCS codes A5500-A5501) directly structures reimbursement demand. Germany's DIN 4843 and the EU Medical Device Regulation (MDR) Class I rules enforce pressure-relief testing and biocompatibility documentation for market access. Stakeholders must monitor whether CMS narrows Local Coverage Determination criteria or expands telehealth fitting allowances, as either shift would restructure patient acquisition economics and inventory deployment across retail and clinical channels.
Market Dynamics
Medicare's Therapeutic Shoes for Persons with Diabetes benefit is restructuring demand economics by reimbursing one pair of depth-inlay shoes and three pairs of heat-moldable or extra-depth inserts annually, forcing manufacturers to certify production lines for HCPCS compliance while expanding podiatrist-partnered distribution networks.
Growth Catalysts
- Peripheral neuropathy prevalence:Rising diabetes incidence in the United States, Germany, and Japan is expanding the addressable patient base eligible for prescription footwear programs.
- HCPCS A5500-A5501 reimbursement:Medicare's structured benefit pathway removes price barriers for geriatric beneficiaries, converting clinical recommendations into reimbursed transactions.
- Seamless interior construction:Heat-moldable midsole technology enables point-of-care customization, reducing return rates and improving pressure-relief outcomes in podiatric clinics.
Market Restraints
- Ethylene-vinyl acetate price volatility:Midsole foam input costs fluctuate with petrochemical feedstock markets, compressing margin on economy-tier therapeutic footwear.
- Specialty pedorthist concentration:Certified fitting professionals cluster in urban United States markets, creating access deserts in rural counties and non-reimbursement regions.
- Biocompatibility documentation burden:EU MDR Class I rules require pressure-relief testing protocols that extend time-to-market for European entrants by 8-14 months.
Strategic Opportunities
- Telehealth fitting allowances:CMS pilot programs for remote gait assessment could unlock rural patient acquisition without brick-and-mortar podiatry presence.
- CAD-CAM bilateral asymmetry correction:Digital foot scanning integration enables mass-customization at standard-production cost curves, capturing premium margin in the custom shoe segment.
- Germany's DIN 4843 export halo:Manufacturers certified to German orthopedic standards gain automatic credibility in adjacent European markets lacking equivalent benchmarks.
Industry Challenges
- Certified pedorthist training pipelines:The United States produces fewer than 400 board-certified practitioners annually, constraining specialty store expansion and dynamic gait analysis capacity.
- Legacy inventory SKU complexity:Extended sizing matrices for edema-progression stages require working capital intensity that mid-tier distributors struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diabetic Shoes Market |
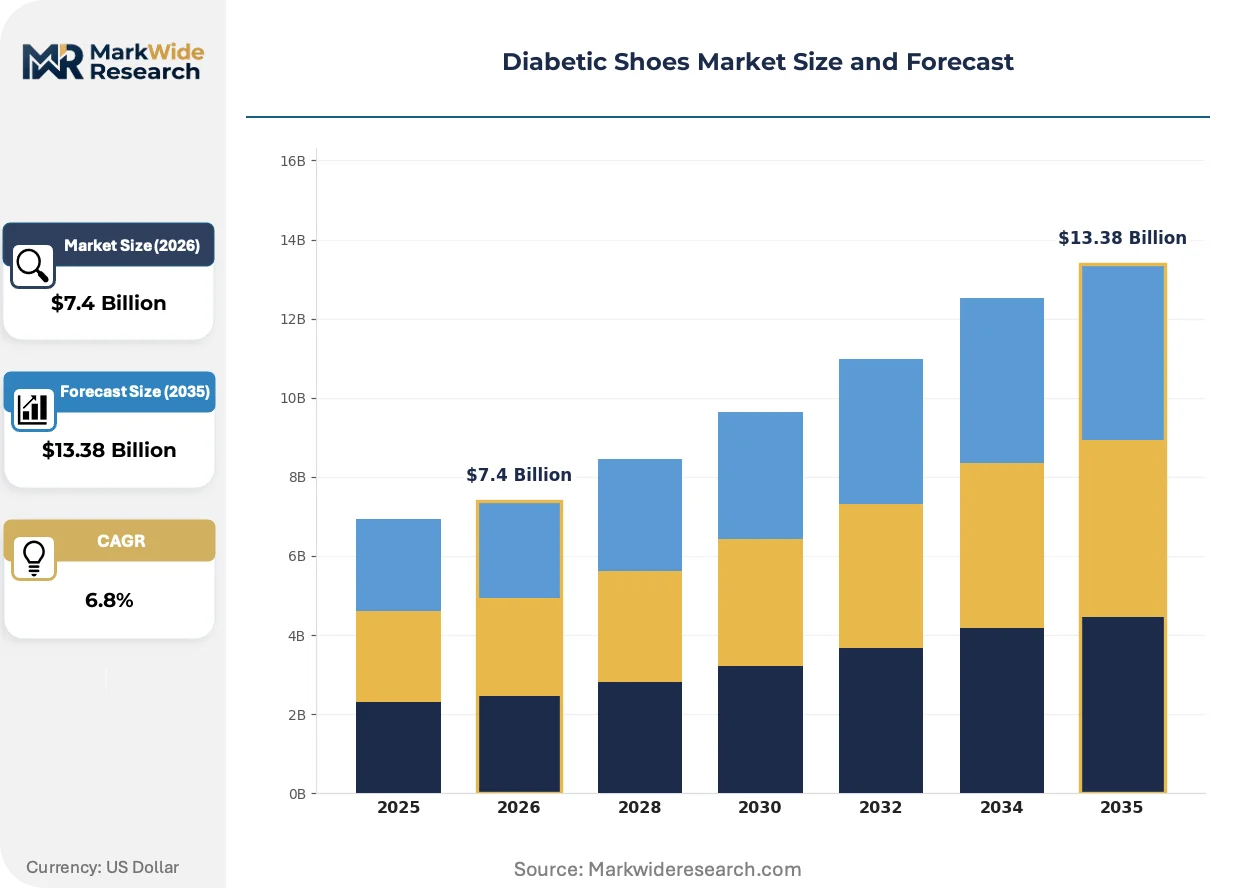
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $13.38 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Men's Shoes, Women's Shoes, Custom Shoes, Athletic Shoes Material: Leather, Synthetic, Mesh, Rubber Feature: Diabetic-Friendly, Shock Absorption, Breathability, Arch Support Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Direct Sales |
| Companies Covered | Apex Foot Health Industries, LLC, Propét USA Inc., Aetrex Worldwide, Inc., Podartis Srl, Drew Shoe Corporation, DJO Global Inc. (Dr. Comfort), DARCO International, Inc., Advanced Diabetic Solutions, Orthofeet Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diabetic Shoes Market Emerging Trajectories
Pressure-mapping technology is migrating from clinical diagnostic equipment into consumer-accessible footwear, while regulatory frameworks on both sides of the Atlantic tighten documentation requirements for therapeutic claims. These forces are compressing product development cycles and reshaping competitive advantage toward data-validated biomechanical performance.
Plantar pressure sensor integration is fragmenting the traditional prescription-customization model. Thin-film capacitive sensors embedded in removable insoles capture real-time gait data during daily wear. Podiatry clinics in the United States are adopting sensor-equipped trial shoes to refine orthotic prescriptions before final fabrication. This data feedback loop is fragmenting the historical reliance on static plaster casting and visual gait assessment, shifting competitive advantage toward manufacturers with embedded electronics partnerships.
EU MDR Class I enforcement is tightening biocompatibility and pressure-relief testing documentation for therapeutic footwear marketed in Europe. Manufacturers must now submit technical files demonstrating seam-free interior construction and heat-moldable midsole performance under standardized load conditions. German producers with pre-existing DIN 4843 certification are adapting existing quality systems to MDR requirements faster than new market entrants, consolidating position in the European therapeutic footwear segment.
Direct-to-patient channels are displacing traditional medical supply store distribution for initial diabetic shoe acquisition. Dr. Comfort's podiatrist-partnered fitting protocol enables prescription capture at point of diagnosis, bypassing durable medical equipment intermediaries. This channel compression is most visible in United States Medicare regions where Local Coverage Determination criteria have stabilized, allowing predictable reimbursement workflows that reward vertical integration between clinical assessment and fulfillment.
Diabetic Shoes Market Segmentation
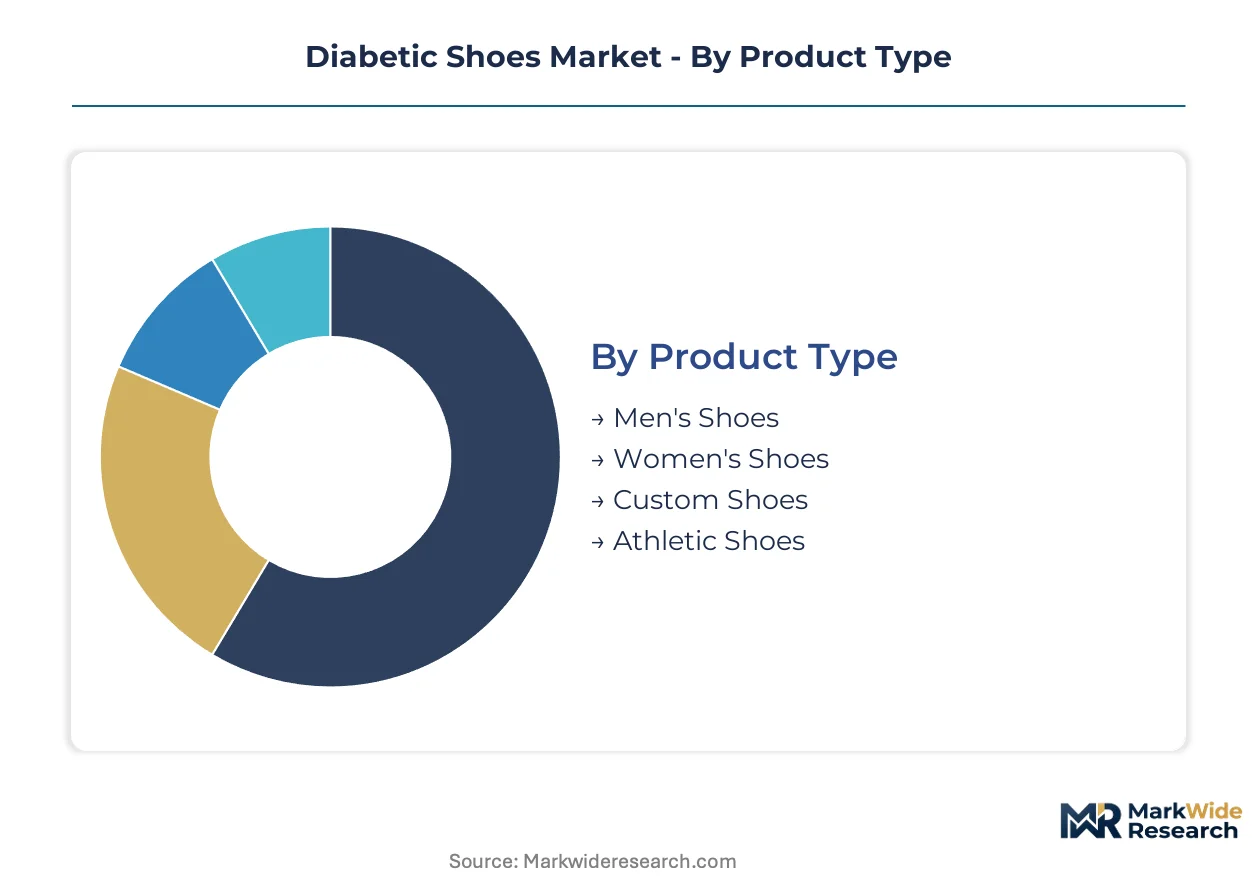
Segmentation in diabetic footwear reveals how Medicare reimbursement pathways, material certification standards, and distribution channel economics concentrate value capture across distinct patient need states and purchasing contexts.
Product Type:
Women's Shoes and Custom Shoes anchor domestic Medicare volume, while Men's Shoes and Athletic Shoes follow distinct reimbursement and retail pathways.
- Women's Shoes:Engineered with extra-width toe boxes and seamless interiors to accommodate peripheral neuropathy progression. Demand concentrates in United States Medicare regions where female beneficiaries show higher eligibility rates for therapeutic footwear benefits.
- Custom Shoes:CAD-CAM fabrication enables bilateral asymmetry correction for deformity cases. Podiatry clinics in Germany and Japan drive adoption through DIN 4843 and JIS-certified orthotic integration programs.
- Men's Shoes:Depth-inlay construction with removable heat-moldable insoles serves edema-progression stages in geriatric populations.
- Athletic Shoes:Pressure-mapping outsoles with biomechanical stability features target active diabetic patients outside standard Medicare reimbursement.
Women's Shoes holds the largest share; momentum sits with Custom Shoes.
Material:
Material selection stratifies across cost tiers from premium leather to economy synthetic, with mesh and rubber occupying mid-market functional positions.
- Leather:Full-grain construction with moisture-wicking linings meets DIN 4843 durability benchmarks. German orthopedic manufacturers specify vegetable-tanned hides for EU MDR Class I biocompatibility compliance.
- Synthetic:Polyurethane and microfiber blends reduce unit costs for economy-tier Medicare-reimbursed footwear. Ethylene-vinyl acetate price volatility compresses margins on high-volume production lines.
- Mesh:Engineered knit uppers enhance breathability for diabetic patients with thermoregulatory dysfunction.
- Rubber:Molded outsoles with Shore A durometer ratings optimize pressure redistribution on plantar surfaces.
Leather commands premium positioning; synthetic materials are expanding most quickly in reimbursed channels.
Feature:
Feature bundling reflects clinical validation requirements, with diabetic-friendly construction mandatory for reimbursement and shock absorption gaining traction in athletic applications.
- Diabetic-Friendly:Seamless interiors, extra depth, and removable insoles satisfy HCPCS A5500-A5501 certification. United States podiatrists require this feature set for Medicare documentation.
- Shock Absorption:Viscoelastic midsole polymers attenuate heel-strike forces during gait. Japanese METI-funded research programs validate pressure-relief performance for JIS-certified products.
- Breathability:Moisture management via perforated linings reduces fungal infection risk in neuropathic patients.
- Arch Support:Medial posting and custom-moldable footbeds address pes planus complications common in diabetic populations.
Diabetic-Friendly construction is mandatory for reimbursement capture; shock absorption shows steepest expansion trajectory in non-reimbursed athletic segments.
Distribution Channel:
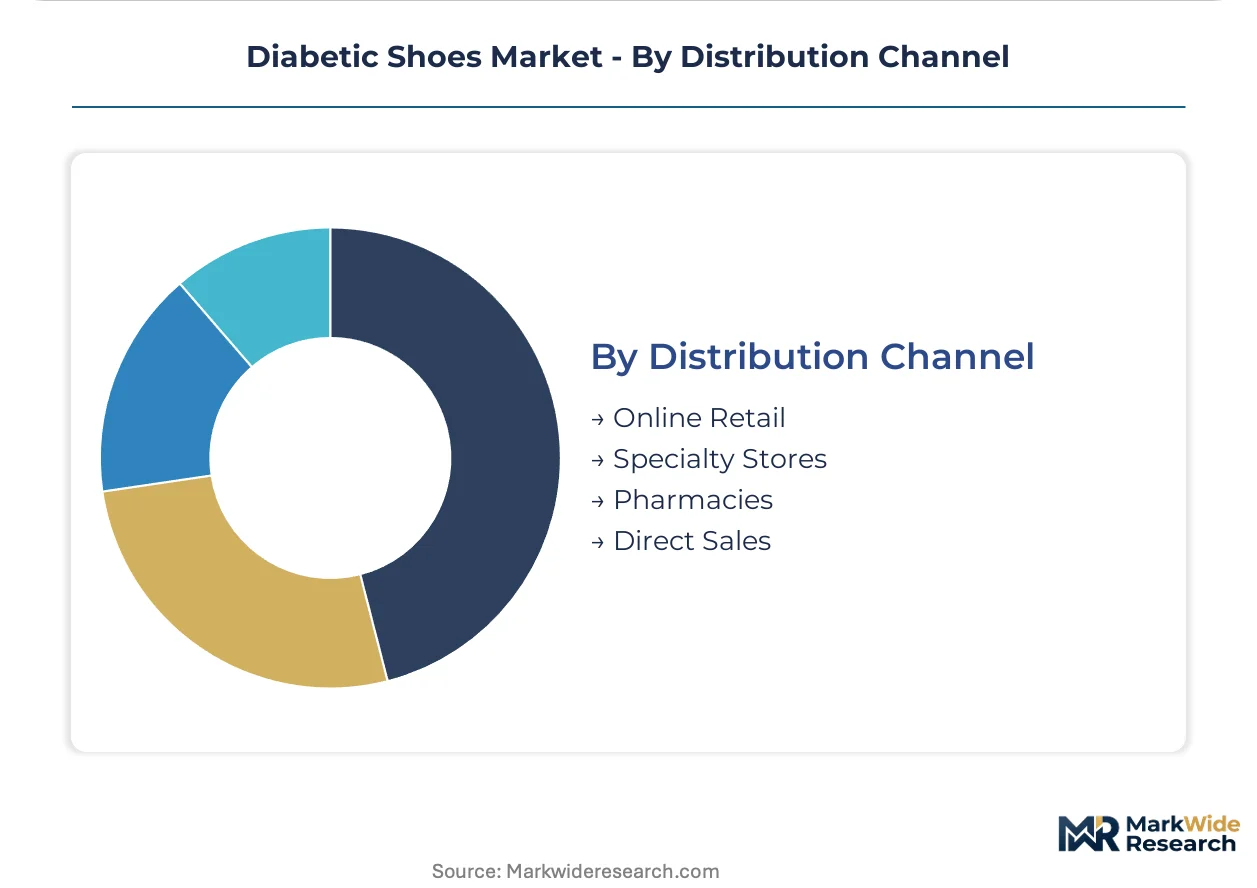
Channel economics separate reimbursed prescription flows from retail accessibility, with specialty stores and direct sales capturing higher-margin fitting services.
- Specialty Stores:Certified pedorthists perform dynamic gait analysis and HCPCS documentation. Urban United States markets concentrate fitting capacity, creating access deserts in rural counties.
- Direct Sales:Podiatrist-partnered protocols enable prescription capture at diagnosis. Dr. Comfort's vertical integration between clinical assessment and fulfillment exemplifies this channel compression.
- Online Retail:E-commerce platforms serve repeat purchasers with established size profiles, though initial fitting requires clinical intervention.
- Pharmacies:Retail pharmacy chains stock economy-tier depth shoes for cash-pay patients without podiatric referral.
Specialty Stores retain the highest average fittings per patient; Direct Sales is gaining share fastest through vertical integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for therapeutic footwear clusters where Medicare reimbursement, DIN certification, and JIS standards create regulatory gravity. Germany's orthopedic fabrication centers, United States podiatric supply chains, and Japanese precision-molding facilities anchor production networks serving diabetic populations.
United States
Medicare's HCPCS A5500-A5501 benefit pathway structures demand through podiatrist-certified prescriptions. FDA 510(k) clearance requirements govern Class I therapeutic footwear claims for pressure-relief and seamless construction. Urban clusters in Chicago, Boston, and Minneapolis concentrate certified pedorthist capacity, while rural access gaps persist in Mississippi Delta and Appalachian counties.
Germany
DIN 4843 orthopedic standards enforce material durability and biocompatibility benchmarks across EU member states. Germany's statutory health insurance funds reimburse custom-fabricated diabetic footwear through physician prescription networks. Industrial concentration in North Rhine-Westphalia and Bavaria houses precision-molding facilities serving adjacent European markets lacking equivalent certification infrastructure.
Japan
METI-funded research programs validate pressure-mapping technology for JIS-certified therapeutic footwear. Japan's aging demographic expands the addressable patient base for neuropathic ulcer prevention programs. Manufacturing clusters in Kansai and Chubu regions integrate CAD-CAM orthotic fabrication with traditional craftsmanship for bilateral asymmetry correction.
United Kingdom
NHS England's diabetic foot care pathways incorporate therapeutic footwear provision through podiatry referral networks. MHRA compliance with EU MDR Class I rules extends time-to-market for new market entrants. London and Manchester medical supply corridors distribute depth-inlay shoes through specialist orthotic clinics and hospital outpatient services.
Diabetic Shoes Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the diabetic footwear segment. The market structure separates Medicare-certified manufacturers with HCPCS-compliant production lines from economy-tier distributors serving cash-pay patients. Three strategic archetypes dominate: vertically integrated orthopedic fabricators controlling material consistency from insole to outsole; direct-to-patient marketers with podiatrist-partnered fitting protocols; and specialty retailers employing certified pedorthists for dynamic gait analysis. Competitive moves concentrate on backward integration into orthotic manufacturing and geographic expansion through telehealth fitting allowances.
Among United States-based manufacturers, Apex Foot Health Industries, LLC and Propét USA Inc. exemplify the vertically integrated archetype with in-house production capabilities. DJO Global Inc. (Dr. Comfort) anchors the direct-to-patient channel through clinical partnership networks. These three players represent distinct strategic positions: fabrication control, sizing matrix breadth, and vertical integration between diagnosis and fulfillment.
| Leading Market Players |
|---|
| Apex Foot Health Industries, LLC |
| Propét USA Inc. |
| Aetrex Worldwide, Inc. |
| Podartis Srl |
| Drew Shoe Corporation |
| DJO Global Inc. (Dr. Comfort) |
| DARCO International, Inc. |
| Advanced Diabetic Solutions |
| Orthofeet Inc. |
| Others |
Supply Flow & Price Mechanics
HCPCS A5500-A5501 certification throughput drives economies of scale that concentrate manufacturing among Medicare-certified producers in the United States and DIN 4843-compliant fabricators in Germany, creating price floors that exclude uncertified competitors from reimbursed channels while compressing margins on economy-tier synthetic footwear.
Pricing Analysis
Medicare's HCPCS A5500-A5501 reimbursement pathway dictates the pricing tier structure across the diabetic footwear landscape. Three-tier pricing structure across premium, standard, and economy levels separates CAD-CAM custom fabrications from depth-inlay Medicare-certified models and cash-pay pharmacy offerings. Price differentiation stems from certification grade and geographic delivery cost, with rural access premiums reflecting pedorthist scarcity. Cost compression in economy-tier synthetic lines is intensifying because ethylene-vinyl acetate feedstock volatility erodes producer margins. Cash-pay patients in pharmacy channels exhibit highest price sensitivity, while podiatry-directed Medicare beneficiaries show lowest sensitivity due to zero out-of-pocket reimbursement structures.
Supply Chain Analysis
Certified pedorthist training pipelines constitute the critical chokepoint constraining downstream distribution capacity across rural United States counties. Manufacturing draws from leather tanneries in Germany, ethylene-vinyl acetate foam producers in the United States, and precision-molding facilities in Japan. Raw material dependencies include full-grain vegetable-tanned hides, heat-moldable midsole polymers, and thin-film capacitive sensor components. Single-source vulnerability in certified pedorthist labor pools threatens specialty store expansion timelines. Distribution runs through podiatrist-partnered direct sales channels, specialty retail with certified fitting protocols, and pharmacy chains for cash-pay segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities proliferate as telehealth fitting allowances and CAD-CAM mass-customization fragment the traditional prescription-customization model, creating specialized niches for sensor-integrated footwear and rural patient acquisition platforms.
For Market Incumbents: Secure podiatrist network exclusivity through vertical integration of fitting protocols with fulfillment infrastructure. Incumbent producers must defend against direct-to-patient channel compression by capturing prescription flow at diagnosis point, while investing in backward integration into orthotic manufacturing to control material consistency from plantar plate to heel counter.
For New Entrants and Emerging Players: Anchor in rural United States counties where certified pedorthist deserts create reimbursement access gaps. New entrants should target telehealth-enabled patient acquisition platforms as the most penetrable segment, deploying remote gait assessment technologies to bypass brick-and-mortar podiatry presence requirements.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with embedded sensor partnerships and DIN 4843 certification halo for European export expansion. Long-term viability over the coming decade rests on data-validated biomechanical performance rather than static construction claims. Acquisition targets should demonstrate CMS reimbursement workflow integration. The signal to watch as inflection indicator is CMS telehealth fitting allowance expansion or contraction.
| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Fitting Platform Development | CMS pilot programs for remote gait assessment unlock rural patient acquisition without podiatry presence. |
| CAD-CAM Bilateral Asymmetry Integration | Digital foot scanning enables mass-customization at standard-production cost curves in custom shoe segment. |
| Sensor-Embedded Insole Partnership | Thin-film capacitive sensor integration captures real-time gait data for prescription refinement before fabrication. |
| DIN 4843 Certification Expansion | German orthopedic standards provide automatic credibility in adjacent European markets lacking equivalent benchmarks. |
| Podiatrist Network Vertical Integration | Direct-to-patient channel compression bypasses durable medical equipment intermediaries in stabilized Medicare regions. |
Methodological Framework
The analysis maps women's shoes, custom shoes, men's shoes, and athletic shoes segments, each validated through podiatrists, certified pedorthists, biomedical engineers, and GPO contracts managers. Primary interviews with these stakeholders combined with secondary validation against CMS Medicare reimbursement databases, FDA 510(k) clearance filings, DIN 4843 certification registries, and hospital procurement databases. Bottom-up patient eligibility modeling and top-down reimbursement flow analysis provided triangulation across data sources.
Consistency checks validated volume and value outputs against external reimbursement benchmarks and production capacity disclosures across the projection horizon. Segmentation dimensions modeled include product type, material grade, feature bundling, and distribution channel complexity. CAGRs were derived from patient population growth trajectories, reimbursement policy stability assumptions, and technology adoption curves for pressure-mapping and CAD-CAM fabrication.
Decision-makers should treat outputs as directional under stable Medicare Local Coverage Determination and EU MDR Class I enforcement assumptions; material deviation in reimbursement criteria or biocompatibility documentation requirements would warrant model refresh. Practitioners should keep alternative scenarios live as CMS telehealth policy and ethylene-vinyl acetate feedstock markets evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Digital Diabetes Management Market
Diabetes Care
South Africa Oral Antidiabetic Drug Market
Diabetes Care
Canada Diabetes Care Drugs and Devices Market
Diabetes Care
Glycated Albumin Market
Diabetes Care
Diabetes Injection Pens Market
Diabetes Care
Alternatives for Injectable Diabetes Care Market
Diabetes Care
North America Insulin Infusion Pumps Market
Diabetes Care
Type 2 Diabetes Mellitus Treatment Market
Diabetes Care
France Diabetes Devices Market
Diabetes Care
Point of Care Glucose Testing Market
Diabetes Care
France Insulin Infusion Pump Market
Diabetes Care
Middle East and Africa Diabetes Market
Diabetes Care
Egypt Diabetes Care Devices Market
Diabetes Care
Middle East and Africa Diabetes Pen Market
Diabetes Care
New Zealand Self-Monitoring Blood Glucose Market
Diabetes Care
Insulin Resistance Market