
 Middle East and Africa Blood Glucose Test Strip Market | 2026-2036
Middle East and Africa Blood Glucose Test Strip Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Blood Glucose Test Strip Market Foresight
Trained diabetes educator shortages across North African markets is redrawing competitive dynamics for manufacturers seeking scale. Abbott Laboratories leverages its established diagnostics infrastructure to sustain channel presence in Gulf Cooperation Council states. LifeScan competes through retail pharmacy partnerships that anchor last-mile distribution in urban Nigerian corridors. Ascensia Diabetes Care Holdings specializes in electrochemical platform compatibility, differentiating its strip portfolios for integrated meter ecosystems.
Blood glucose test strips are thin, disposable polymer substrates coated with enzyme reagents—typically glucose oxidase or glucose dehydrogenase—that catalyze electrochemical reactions quantifying glucose concentration in capillary blood samples, with results displayed on calibrated meters within five to fifteen seconds. The primary commercial purpose centers on enabling real-time glycemic monitoring for insulin-dosing decisions and long-term complication prevention. Single-use strips dominate volume throughput across retail channels, while multi-use strip configurations command margin premiums in hospital procurement frameworks. Electrochemical technology leads technology segmentation due to superior precision and minimal interference from hematocrit variation, whereas colorimetric platforms retain niche positions in resource-constrained settings with limited meter infrastructure.
South Africa's Health Products Regulatory Authority and Saudi Arabia's SFDA enforce ISO 15197 accuracy standards and lot-release testing protocols that determine market authorization timelines and reimbursement eligibility. Egypt's drug authority and the UAE's Ministry of Health and Prevention maintain import registration requirements that shape distributor selection and product labeling specifications. Stakeholders must monitor evolving national essential medicines list inclusions and tender consolidation patterns that will determine volume allocation across public procurement channels.
Market Dynamics
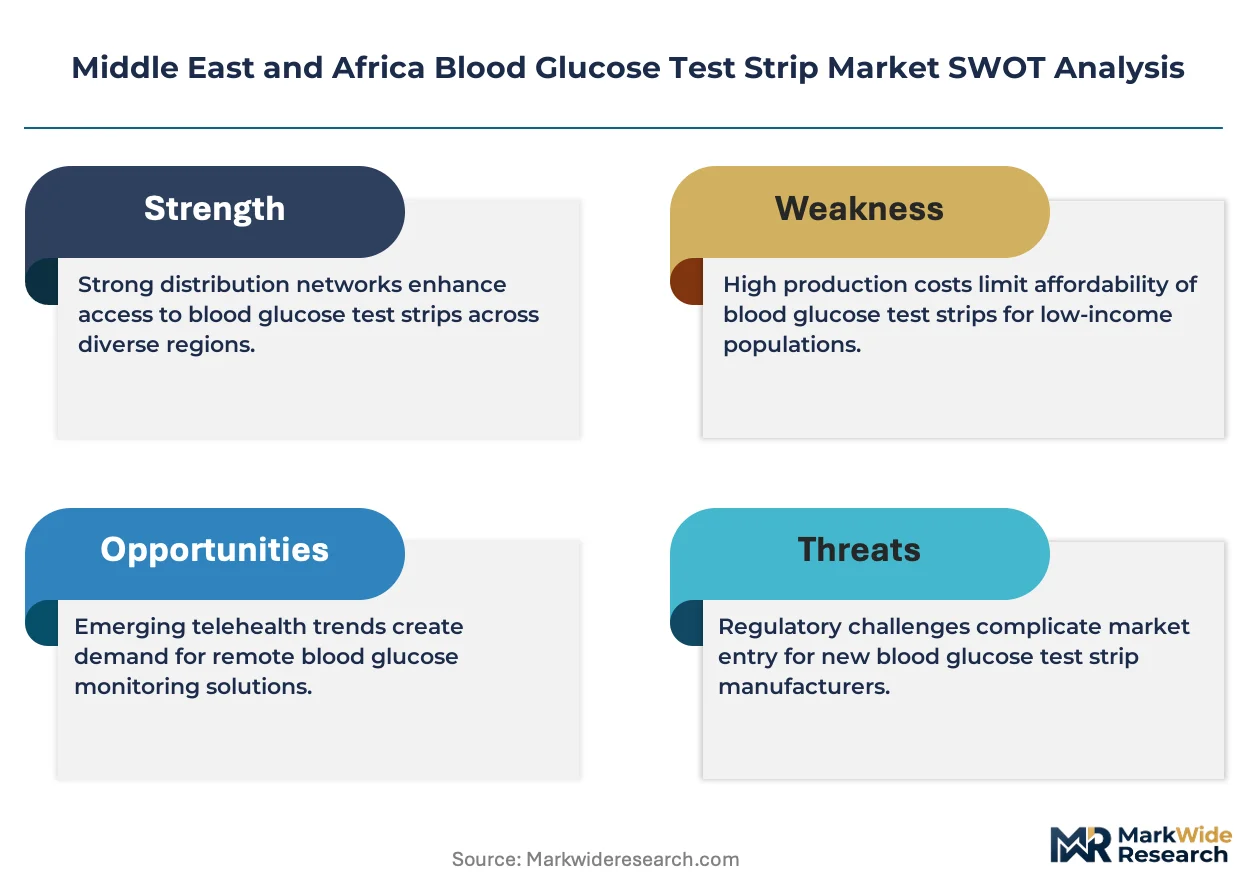
Homecare patient migration from clinical settings is compressing distribution layers and forcing strip manufacturers to reconfigure last-mile logistics around retail pharmacy networks across Gulf Cooperation Council states and North African corridors.
Growth Catalysts
- Egypt's NCD screening expansion:Government-mandated point-of-care testing infrastructure deployment is creating institutional demand anchors for electrochemical strip procurement through public tender channels.
- Self-monitoring protocol adoption:Trained diabetes educator shortages in Morocco and Algeria are pushing patients toward autonomous glucose management using consumer-grade meter-strip ecosystems.
- SFDA reimbursement alignment:Saudi Arabia's device coverage framework is reducing out-of-pocket burdens and accelerating household penetration of continuous monitoring supplies.
Market Restraints
- Enzyme reagent cost volatility:Glucose oxidase and glucose dehydrogenase precursor supply concentrates in South Asian chemical processing clusters, exposing strip converters to input price swings.
- Import registration friction:Egypt's drug authority maintains extended lot-release timelines that delay product launches and tie up working capital for distributor networks.
- Colorimetric platform substitution:Resource-constrained rural settings without reliable electricity access default to visual-read strips, capping electrochemical premium capture in these zones.
Strategic Opportunities
- Nigerian urban corridor penetration:Lagos and Abuja pharmacy chain consolidation creates concentrated buyer access points for brands establishing retail partnerships.
- Integrated meter ecosystem convergence:Bluetooth-enabled strips linking to mobile health applications are opening subscription-based recurring revenue models for device-agnostic consumable suppliers.
- South Africa HTA framework leverage:Health technology assessment pathways for diabetes management devices offer reimbursement fast-track potential for manufacturers meeting cost-effectiveness thresholds.
Industry Challenges
- ISO 15197 certification timeline compression:South Africa's Health Products Regulatory Authority and Saudi SFDA enforce accuracy standard verification that extends product registration cycles and delays revenue recognition.
- Distributor capability fragmentation:Cold chain maintenance for enzyme-stabilized inventory requires logistics partners with temperature-controlled warehousing, a scarce competency across secondary cities in the Horn of Africa.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Blood Glucose Test Strip Market |
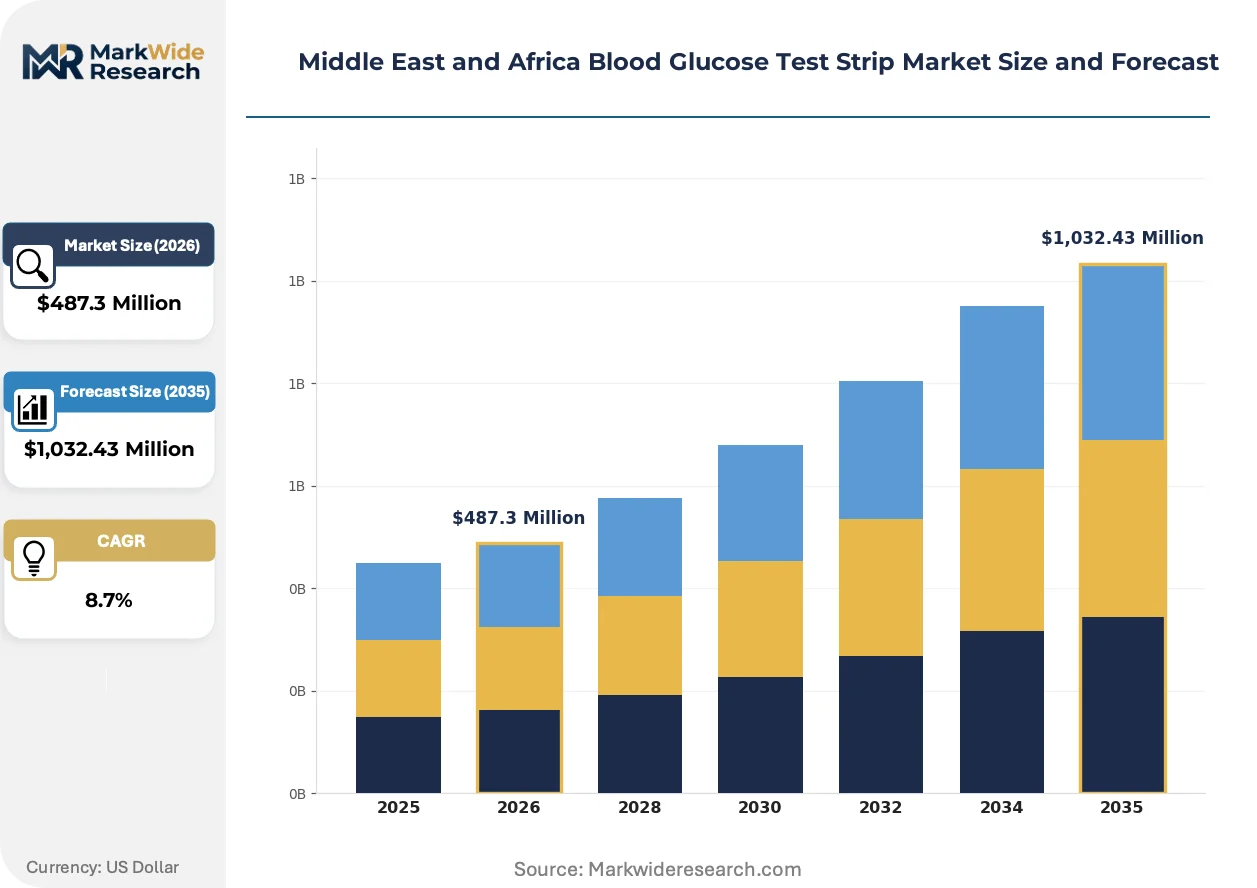
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-use Strips, Multi-use Strips, Test Kits, Control Solutions End User: Homecare Patients, Hospitals, Clinics, Diagnostic Labs Distribution Channel: Retail Pharmacies, Online Stores, Direct Sales, Wholesale Distributors Technology: Electrochemical Technology, Optical Technology, Photometric Technology, Colorimetric Technology |
| Companies Covered | LifeScan, Arkray, F. Hoffmann-La Roche, ACON Laboratories, AgaMatrix, Abbott Laboratories, Medtronic, Medisana, Ascensia Diabetes Care Holdings, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Blood Glucose Test Strip Market Shifts & Advancements
Electrochemical sensing architectures and connectivity integration are redefining strip value propositions, while regulatory convergence around accuracy standards is elevating manufacturing compliance burdens.
Continuous glucose monitoring patch technology is miniaturizing sensor form factors and extending wear duration beyond traditional fingerstick paradigms. Private endocrinology clinics in Dubai and Johannesburg are piloting these systems for Type 1 patient cohorts. This miniaturization is compressing the addressable market for conventional strip volumes in premium urban segments.
SFDA and South Africa's Health Products Regulatory Authority are harmonizing ISO 15197 accuracy thresholds with post-market surveillance requirements. Manufacturers now face mandatory lot-release testing documentation that extends authorization timelines. Hospital procurement frameworks in Riyadh and Cape Town are responding by consolidating supplier lists around vertically integrated producers with captive testing laboratories.
Retail pharmacy chains are unbundling after-sales calibration support from strip purchases, shifting technical service liability to manufacturer hotlines. This disintermediation reduces pharmacist training burdens but increases direct-to-consumer support costs for brands. The pattern is most visible in UAE's MOHAP-regulated pharmacy networks and Kenya's expanding urban drugstore franchises.
Middle East and Africa Blood Glucose Test Strip Market Segmentation
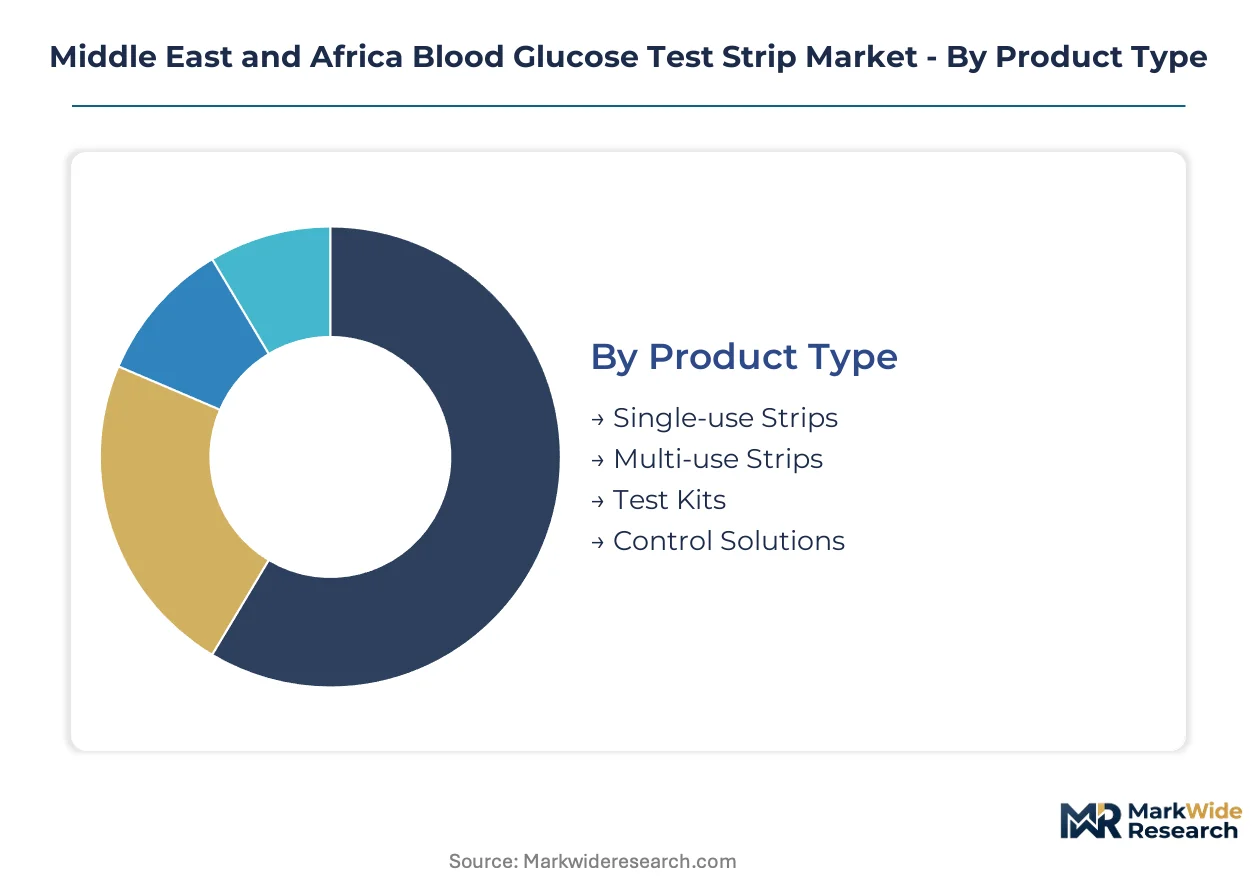
Strip configuration and channel access determine patient adherence and manufacturer margin capture across Middle East and Africa markets. Technology platform selection and distribution density shape competitive positioning in settings with uneven meter penetration and divergent reimbursement frameworks.
Product Type:
Single-use strips dominate procurement volumes across Gulf Cooperation Council public tenders and Egyptian ministry contracts, while multi-use configurations concentrate in South African hospital group purchasing. Export-led demand for test kits flows into Nigerian pharmacy consolidations and Kenyan diagnostic network expansions.
- Single-use Strips:Disposable polymer substrates coated with glucose oxidase or glucose dehydrogenase enzymes enable capillary blood testing with five-to-fifteen-second meter readouts. Demand concentrates in Saudi Arabia's SFDA-reimbursed homecare channels and Egypt's expanding point-of-care infrastructure, driven by government-mandated diabetes screening protocols that anchor institutional procurement volumes.
- Multi-use Strips:Reusable cartridge formats compatible with hospital-grade analyzers reduce per-test consumable costs for high-throughput clinical environments. Procurement clusters in South Africa's private hospital networks and Dubai's endocrinology clinics, where Health Products Regulatory Authority accuracy certifications and integrated meter ecosystems justify premium positioning.
- Test Kits:Bundled meter-strip combinations target first-time users in Morocco and Algeria where diabetes educator shortages push autonomous self-monitoring adoption.
- Control Solutions:Calibration reagents for meter verification support quality assurance in diagnostic labs across UAE's MOHAP-regulated networks.
Single-use strips hold the largest share; momentum sits with multi-use strips as hospital procurement consolidation accelerates.
End User:
Cost tier differentiation separates premium hospital contracts from retail-accessible homecare segments, with clinic channels capturing price-sensitive patients transitioning from acute care.
- Homecare Patients:Individual consumers purchasing through retail pharmacies or online platforms for daily glycemic self-monitoring. Volume growth concentrates in Saudi Arabia's SFDA-coverage expansion and Egypt's urban corridors, where reduced out-of-pocket burdens and pharmacy chain density accelerate household penetration.
- Hospitals:Acute care facilities and integrated delivery networks procuring through tender processes for inpatient glycemic management. Demand anchors in South Africa's Health Products Regulatory Authority-regulated procurement frameworks and Riyadh's ministry hospital systems, where ISO 15197 accuracy standards determine supplier qualification.
- Clinics:Outpatient settings in Lagos and Nairobi provide accessible testing for patients without hospital referrals.
- Diagnostic Labs:Centralized testing facilities in Casablanca and Johannesburg process high-volume screening samples.
Hospitals command the highest contract values; homecare patients are expanding most quickly as self-monitoring protocols displace clinic-dependent models.
Distribution Channel:
Channel maturity varies sharply across the region, with retail pharmacy density determining last-mile access in urban Nigeria and Gulf Cooperation Council states while direct sales sustain institutional relationships.
- Retail Pharmacies:Physical drugstore networks providing immediate access to strips and meter supplies. Procurement concentrates in UAE's MOHAP-regulated pharmacy chains and Kenya's expanding urban franchises, where disintermediation of calibration support shifts technical service liability to manufacturer hotlines.
- Online Stores:E-commerce platforms and direct-to-consumer channels reaching patients in secondary cities with limited pharmacy density. Growth clusters in South Africa's digital health expansion and Nigerian urban corridors, where pharmacy chain consolidation creates concentrated buyer access points.
- Direct Sales:Manufacturer field forces serving hospital procurement offices in Cairo and Johannesburg.
- Wholesale Distributors:Temperature-controlled logistics partners managing enzyme-stabilized inventory across Horn of Africa secondary cities.
Retail pharmacies retain volume leadership; online stores gain share fastest as digital payment infrastructure spreads.
Technology:
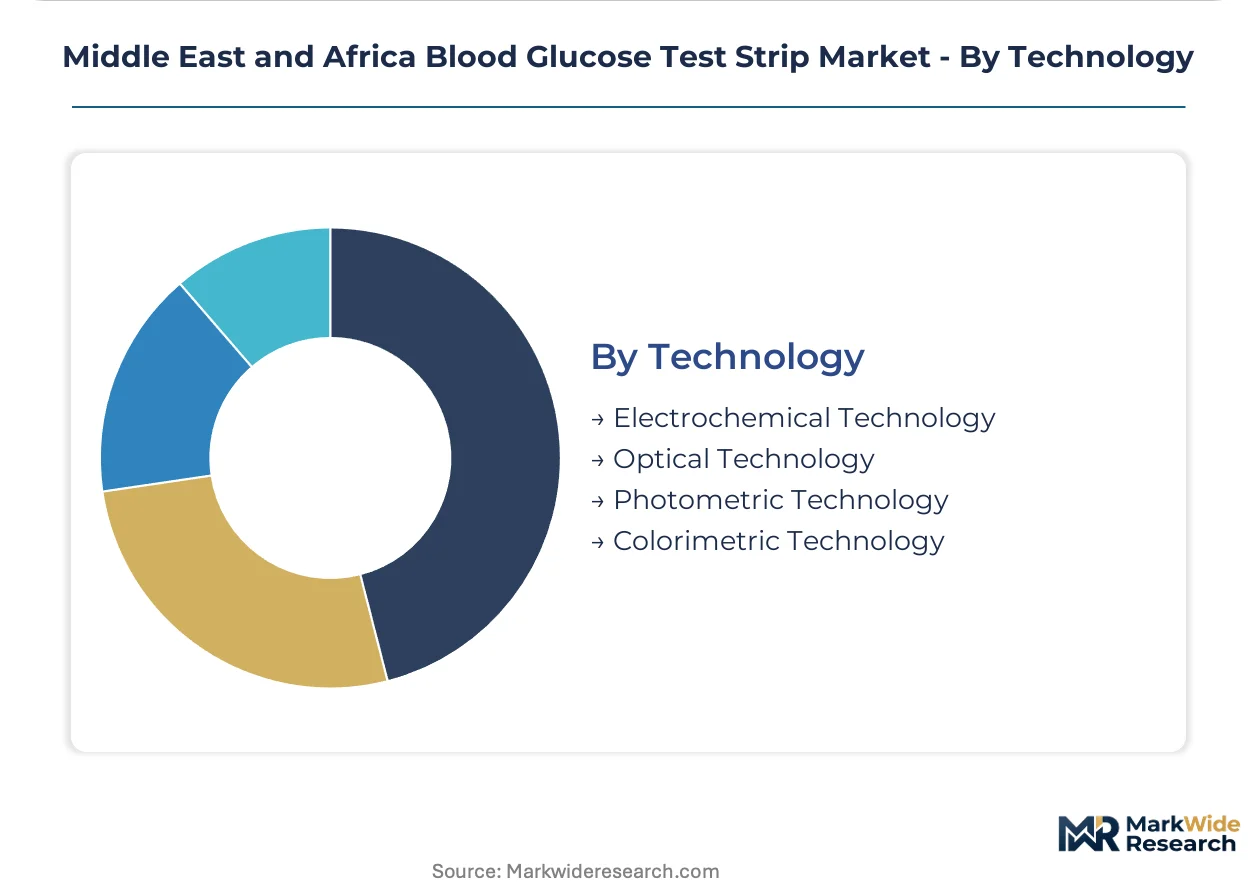
Supply concentration in electrochemical enzyme processing shapes platform economics, while optical alternatives serve electricity-constrained rural settings.
- Electrochemical Technology:Enzyme-catalyzed reactions quantifying glucose concentration with minimal hematocrit interference and superior precision. Procurement dominates Saudi SFDA and South African Health Products Regulatory Authority frameworks, where ISO 15197 accuracy standards and lot-release testing protocols mandate platform compliance.
- Colorimetric Technology:Visual-read strips requiring no electronic meter infrastructure for result interpretation. Demand persists in Horn of Africa rural zones and Egyptian Delta regions without reliable electricity access, where resource constraints cap premium electrochemical capture.
- Optical Technology:Light-based detection systems in specialized hospital analyzers.
- Photometric Technology:Laboratory-grade spectrophotometric methods for reference testing.
Electrochemical technology holds the largest share; Bluetooth-enabled connectivity integration is driving the steepest expansion trajectory for next-generation strip platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA reimbursement protocols in Saudi Arabia anchor the regional regulatory framework, with Egypt's point-of-care expansion and South Africa's health technology assessment pathways creating divergent demand centers across the Middle East and Africa blood glucose test strip market.
Saudi Arabia
Government-mandated device coverage frameworks reduce household out-of-pocket burdens for glucose monitoring supplies. SFDA enforces ISO 15197 accuracy standards and lot-release testing protocols that determine market authorization timelines. Riyadh's ministry hospital systems consolidate procurement around vertically integrated suppliers with captive testing laboratories.
Egypt
Non-communicable disease screening programs deploy point-of-care testing infrastructure through public health channels. The country's drug authority maintains extended import registration timelines that delay product launches and tie up distributor working capital. Cairo anchors institutional procurement volumes, while Delta regions without reliable electricity access default to visual-read colorimetric platforms.
South Africa
Health Products Regulatory Authority frameworks offer reimbursement fast-track potential for manufacturers meeting cost-effectiveness thresholds. Private hospital networks in Johannesburg and Cape Town concentrate procurement for multi-use strip configurations compatible with hospital-grade analyzers. Cape Town's endocrinology clinics pilot continuous glucose monitoring systems for Type 1 patient cohorts.
United Arab Emirates
MOHAP-regulated pharmacy networks disintermediate after-sales calibration support from strip purchases, shifting technical service liability to manufacturer hotlines. Dubai's private endocrinology clinics drive premium segment demand for Bluetooth-enabled strips linking to mobile health applications. Urban pharmacy chain density accelerates last-mile access in Abu Dhabi and Dubai corridors.
Nigeria
Retail pharmacy consolidation in Lagos and Abuja creates concentrated buyer access points for brands establishing distribution partnerships. Urban corridors face cold chain maintenance gaps for enzyme-stabilized inventory across secondary cities. Pharmacy chains in Lagos anchor volume throughput for bundled meter-strip combinations targeting first-time users.
Middle East and Africa Blood Glucose Test Strip Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the market structure consolidating around vertically integrated producers with captive testing laboratories and regional distribution networks. Multinational diagnostics conglomerates compete through established channel presence in Gulf Cooperation Council states, while mid-scale specialists differentiate through electrochemical platform compatibility and retail pharmacy partnerships. Strategic archetypes include integrated diagnostics leaders, electrochemical platform specialists, and retail-anchored distribution players. Competitive moves center on hospital procurement consolidation responses and subscription-based recurring revenue models for device-agnostic consumable suppliers.
Among the integrated diagnostics tier, Abbott Laboratories and LifeScan occupy positions shaped by channel infrastructure depth across Saudi Arabia and Nigeria respectively. Abbott leverages established diagnostics infrastructure to sustain presence in Gulf Cooperation Council states, while LifeScan competes through retail pharmacy partnerships anchoring last-mile distribution in urban Nigerian corridors. Ascensia Diabetes Care Holdings sits within the electrochemical platform specialist archetype, with its strip portfolios differentiated for integrated meter ecosystems.
| Leading Market Players |
|---|
| LifeScan |
| Arkray |
| F. Hoffmann-La Roche |
| ACON Laboratories |
| AgaMatrix |
| Abbott Laboratories |
| Medtronic |
| Medisana |
| Ascensia Diabetes Care Holdings |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between South Asian enzyme processors and Gulf Cooperation Council distributors lock in glucose oxidase supply access while capping raw material price visibility for strip converters across the Middle East and Africa blood glucose test strip market. These arrangements transfer commodity risk downstream to manufacturers while securing volume commitments for public tender participation in Saudi Arabia and Egypt.
Pricing Analysis
Gulf Cooperation Council states command 15-25% premiums over North African corridors due to SFDA-mandated accuracy certification costs and cold chain logistics overhead. Pricing stratifies across ISO 15197-certified premium tiers, standard hospital procurement grades, and economy visual-read strips for electricity-constrained zones. Cost compression in the standard tier intensifies as Egyptian ministry tenders consolidate volume around fewer suppliers. Homecare patients in Morocco and Algeria exhibit highest price sensitivity, while South African private hospital networks absorb premium positioning for multi-use cartridge systems.
Supply Chain Analysis
Strait of Hormuz transit underwrites enzyme reagent flows from Indian and Chinese chemical processing clusters to regional strip converters in Saudi Arabia and the UAE. Manufacturing draws from glucose oxidase precursors, polymer substrate films, and electrochemical sensor components. Single-source vulnerability concentrates in South Asian enzyme suppliers, exposing converters to input disruption. Distribution runs through temperature-controlled wholesale networks serving retail pharmacy chains, with direct sales forces managing hospital procurement relationships in Cairo and Johannesburg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated retail pharmacy chains in Lagos and Nairobi, fragmenting distributor margins while concentrating volume access for brands with direct pharmacy partnerships.
For Market Incumbents: Fortify ISO 15197 certification pipelines to defend South African Health Products Regulatory Authority and Saudi SFDA positioning against emerging electrochemical platform specialists. Deepen backward integration into enzyme stabilization capabilities to offset raw material volatility from South Asian suppliers. Anchor channel control through exclusive meter-strip ecosystem bundling that raises switching costs for homecare patients. For New Entrants and Emerging Players: After-sales calibration support gaps in UAE's MOHAP-regulated pharmacy networks offer service-layer differentiation where incumbents have disintermediated technical liability to manufacturer hotlines. Target Nigerian urban corridor pharmacy consolidations with white-label test kit bundles for first-time users. Pursue direct-to-clinic go-to-market angles in Kenya's expanding diagnostic networks bypassing established wholesale hierarchies. For Investors and Strategic Acquirers: Regional distributors with captive cold chain capabilities across Horn of Africa secondary cities represent acquisition targets with scarce logistics competencies. Long-term viability hinges on continuous glucose monitoring substitution timelines compressing conventional strip addressable markets in premium urban segments. Watch SFDA post-market surveillance requirement harmonization as inflection signal for regulatory compliance cost escalation favoring scaled manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Bluetooth-Enabled Strip Development | Opens subscription revenue models for device-agnostic consumable suppliers targeting UAE's digital health expansion. |
| SFDA Accuracy Certification Investment | Secures reimbursement eligibility and hospital procurement qualification in Saudi Arabia's consolidated supplier framework. |
| Retail Pharmacy Partnership Expansion | Captures last-mile density in Lagos and Abuja corridors where chain consolidation concentrates buyer access points. |
| Enzyme Stabilization Backward Integration | Reduces exposure to South Asian precursor volatility while improving lot-release timeline predictability for Egyptian drug authority submissions. |
| Continuous Glonitoring Monitoring Pilot Programs | Positions incumbents for platform transition in Johannesburg and Dubai endocrinology clinics ahead of strip volume compression. |
Research Methodology
Desk research of SFDA regulatory filings, Egyptian drug authority registration databases, and South African Health Products Regulatory Authority approval records preceded structured interviews with hospital procurement managers, retail pharmacy chain category buyers, biomedical engineers at diagnostic networks, and distributor logistics directors across Gulf Cooperation Council states and North African corridors. Secondary validation drew from trade customs data, hospital tender documentation, and GPO contract disclosures. Bottom-up patient population modeling and top-down manufacturer revenue triangulation anchored volume estimates.
Variance decomposition across product type, end-user segment, technology platform, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate synthesis weighted by base-year revenue contribution. Forecast inputs incorporated diabetes prevalence trajectories, SFDA reimbursement expansion schedules, and pharmacy chain consolidation velocity.
Material uncertainties — enzyme reagent supply disruptions, Egyptian import registration timeline extensions, and continuous glucose monitoring substitution rates — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory harmonization and distributor capability evolution. Practitioners should keep alternative scenarios live as SFDA post-market surveillance requirements and South African HTA framework adjustments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Saudi Arabia Diabetes Care Devices Market
Diabetes Care
Global Smart Insulin Pens Market
Diabetes Care
Egypt Diabetes Care Devices Market
Diabetes Care
Russia Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Oman Insulin Drugs and Delivery Devices Market
Diabetes Care
Hyperinsulinemia Hypoglycaemia Treatment Market
Diabetes Care
Mexico Diabetes Care Devices Market
Diabetes Care
Latin America Diabetes Care Devices Market
Diabetes Care
Germany Insulin Infusion Pump Market
Diabetes Care
India Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Disposable Insulin-Delivery Device Market
Diabetes Care
New Zealand Oral Anti-Diabetic Drug Market
Diabetes Care
Malaysia Diabetes Care Devices Market
Diabetes Care
Saudi Arabia Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Hyperglycemia Treatment Market
Diabetes Care
Diabetic Lancing Devices Market