
 Instrument Transformers Market | 2026-2036
Instrument Transformers Market Size, Share, and Industry Trends Forecast 2026-2036
Instrument Transformers Market Analysis
Utility capital planners are bifurcating from industrial buyers as the dominant procurement archetype in instrument transformers. Schneider Electric SE leverages its digital substation portfolio to capture utility upgrade cycles across Europe. Siemens Energy AG anchors high-voltage direct current projects with specialized current transformer designs. ABB Ltd. competes through integrated protection relay systems that bundle voltage transformers with control electronics.
Instrument transformers are electromagnetic devices that scale high primary currents and voltages to standardized secondary levels, typically 1 A or 5 A for current and 110 V or 120 V for voltage, enabling safe measurement and protection in power networks. They isolate metering equipment from live conductors while maintaining accuracy classes defined by IEEE C57.13 and IEC 61869. Current transformers dominate product type revenue due to mandatory replacement cycles in aging switchgear installations. Digital technology segments expand fastest as utilities deploy optical current sensors and merging units for process bus architectures. Hybrid analog-digital designs occupy the margin pool where retrofit compatibility commands pricing premiums over full optical replacements.
The US Federal Energy Regulatory Commission mandates transmission reliability standards that require synchronized phasor measurement units, driving precision instrument transformer upgrades. IEC 61850 and IEEE 2030 smart grid interoperability frameworks reshape supplier qualification criteria across procurement tenders. India's Central Electricity Authority enforces grid code revisions that specify accuracy limits for metering transformers in renewable integration zones. Stakeholders must monitor how digital substation standardization redefines aftermarket service contracts and spare parts compatibility.
Market Dynamics
Digital substation architectures are fragmenting procurement authority between traditional utility engineering departments and newly formed IT-security governance structures, forcing suppliers to recertify products against dual technical standards.
Growth Catalysts
- Grid modernization mandates:India's Central Electricity Authority enforces revised grid codes requiring accuracy-class upgrades for metering transformers in renewable integration zones, compelling distribution utilities to accelerate replacement schedules.
- Optical sensing convergence:Fiber-optic current sensors merged with IEC 61850-9-2LE process bus protocols enable non-conventional instrument transformer deployments in 765 kV transmission corridors.
- Phasor measurement synchronization:The US Federal Energy Regulatory Commission mandates transmission reliability standards requiring synchronized PMU installations, driving precision instrument transformer upgrades across interconnection zones.
Market Restraints
- Raw material concentration:Electrical-grade grain-oriented silicon steel production concentrates in China and Japan, exposing transformer core manufacturing to supply disruptions and price volatility.
- Optical sensor cost barriers:Non-conventional instrument transformers using Faraday-effect optical current sensors carry capital premiums exceeding 40 percent versus electromagnetic equivalents, constraining adoption in cost-sensitive distribution networks.
- Dual certification burdens:Suppliers must maintain parallel IEEE C57.13 and IEC 61869 compliance testing programs, inflating R&D overhead for products serving multinational utility portfolios.
Strategic Opportunities
- Retrofit hybrid architectures:Analog-digital merging units that preserve existing electromagnetic transformer cores while adding optical digital outputs capture margin pools in European brownfield substation upgrades.
- Offshore wind integration:High-voltage direct current converter platforms require specialized DC-current instrument transformers, creating white space for suppliers with high-voltage insulation expertise.
- Service contract unbundling:Digital substation standardization enables third-party firmware update services, allowing aftermarket specialists to capture recurring revenue from calibration and cybersecurity patching.
Industry Challenges
- Cross-functional talent scarcity:Utilities struggle to recruit engineers fluent in both power system protection and IT cybersecurity protocols, slowing digital substation commissioning timelines.
- Legacy asset integration:Electromechanical protection relays in 40-year-old switchgear installations resist seamless integration with IEC 61850 process bus architectures, forcing costly parallel metering systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instrument Transformers Market |
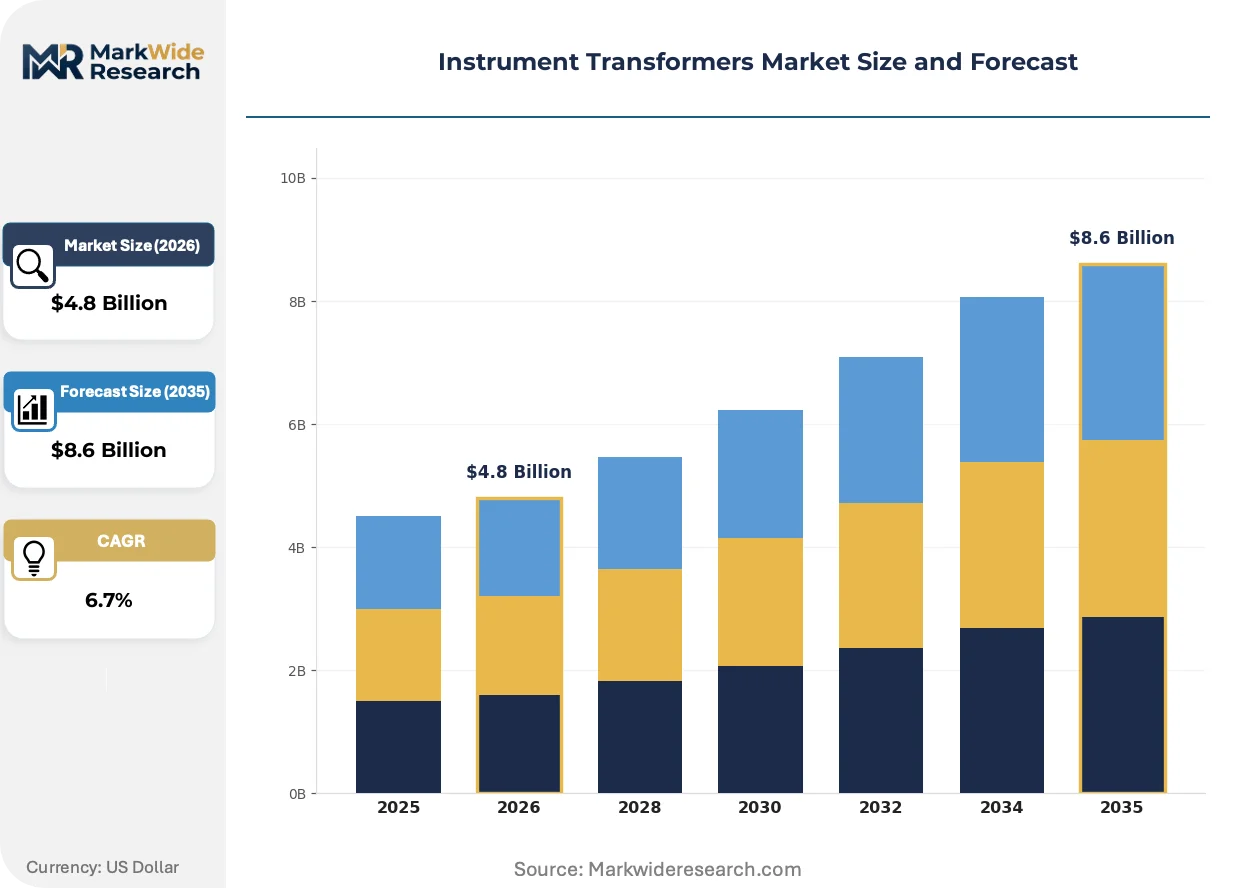
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Current Transformer, Voltage Transformer, Potential Transformer, Metering Transformer Technology: Optical, Digital, Analog, Hybrid End User: Utilities, Industrial, Infrastructure, Commercial Application: Power System Monitoring, Protection Relay Systems, Energy Management, Data Acquisition |
| Companies Covered | Schneider Electric SE, Mitsubishi Electric Corporation, ABB Ltd., Eaton Corporation plc, Toshiba Corporation, Siemens Energy AG, Arteche Group, RITZ Instrument Transformers GmbH, General Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instrument Transformers Market Emerging Trajectories
Process bus architectures are dissolving the physical boundaries between switchyard equipment and control room systems, compressing installation footprints while introducing cybersecurity vulnerabilities that reshape supplier qualification criteria.
Optical current transducers utilizing Faraday rotation in flint glass fibers are decomposing the traditional iron-core current transformer value chain. Transmission utilities in Germany and Texas deploy these sensors in 400 kV gas-insulated substations where electromagnetic saturation risks compromise protection coordination. The technology is decomposing legacy manufacturing competencies centered on laminated steel cores and copper windings, compressing incumbent supplier margins while elevating photonics specialists.
The European Union's F-Gas Regulation imposes phasedown schedules for sulfur hexafluoride insulation in switchgear, accelerating instrument transformer redesigns toward vacuum or dry-air insulation systems. Manufacturers serving European utilities must requalify products under MDR-equivalent pressure equipment directives. High-voltage instrument transformer suppliers with SF6-dependent portfolios face compressed order pipelines in Germany, France, and the Netherlands as procurement specifications harden.
Utility procurement departments are consolidating vendor panels from fifteen-plus suppliers to four-to-six strategic partners, demanding decade-long framework agreements with embedded cybersecurity update commitments. This concentration displaces regional transformer specialists who lack dedicated firmware engineering teams. The pattern is most visible in United Kingdom distribution network operator tenders, where National Grid ESO and ScottishPower have executed consolidated procurement frameworks.
Instrument Transformers Market Segmentation
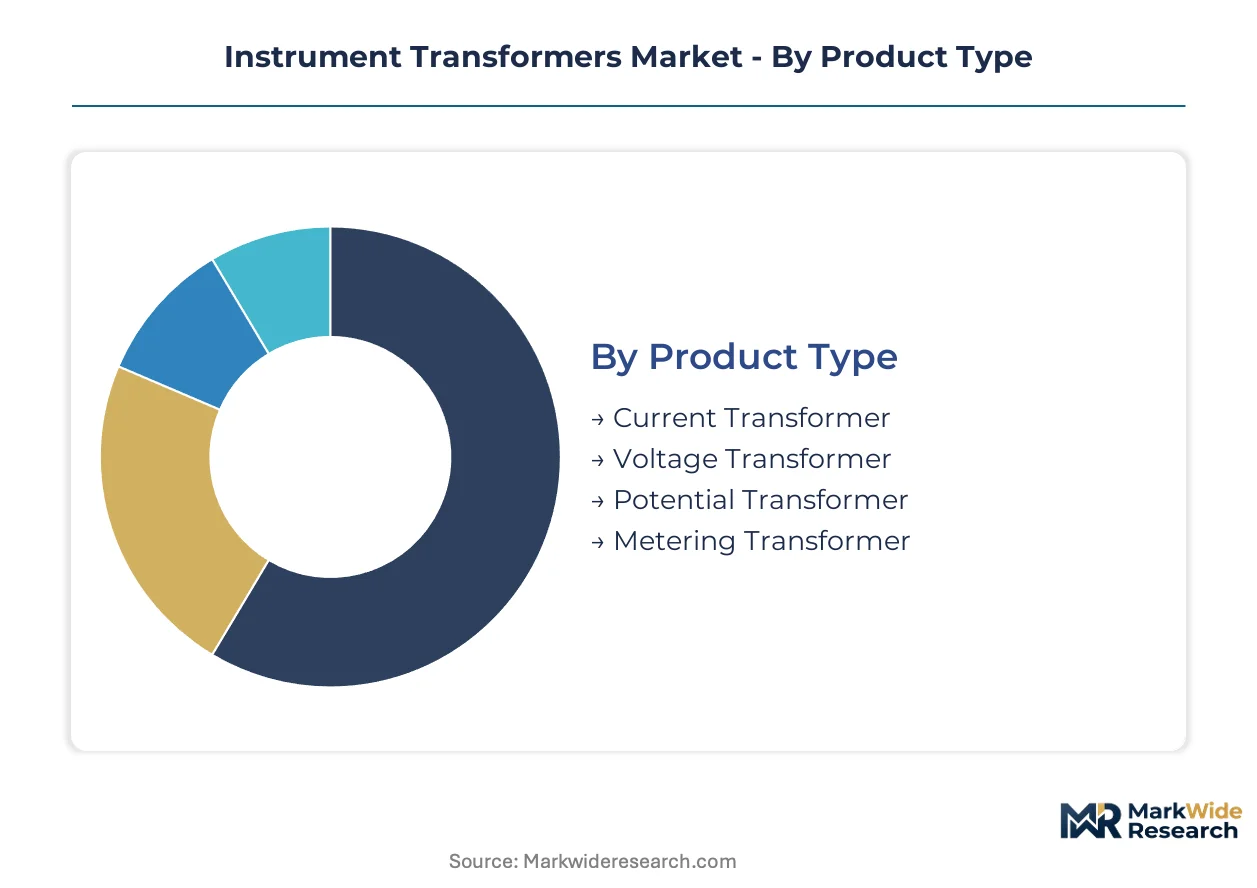
Segmentation in instrument transformers reveals how procurement authority splits between legacy electromagnetic specifications and emerging digital architectures. Suppliers must calibrate R&D portfolios across four distinct category hierarchies where technology choices increasingly override traditional product type distinctions.
Product Type:
Margin pools concentrate in current transformers due to mandatory replacement cycles in aging switchgear, while voltage transformer profitability depends on accuracy class premiums in utility metering applications.
- Current Transformer:Electromagnetic devices that scale high primary currents to standardized 1 A or 5 A secondary levels using laminated silicon steel cores and copper windings. Demand clusters in China's State Grid transmission expansion and India's renewable integration zones where IEC 61869 accuracy upgrades are compulsory. Distribution utilities face compressed replacement timelines as 40-year-old installations reach end-of-life.
- Voltage Transformer:Instrument transformers that step down primary voltages to 110 V or 120 V secondary levels for metering and protection isolation. Procurement concentrates in European digital substation retrofits where brownfield compatibility commands pricing premiums over full optical replacements.
- Potential Transformer:Specialized voltage transformers engineered for protective relaying applications requiring transient response stability. German and Japanese manufacturers dominate high-voltage insulation expertise for 765 kV corridors.
- Metering Transformer:Accuracy-class optimized designs for revenue-grade energy measurement meeting IEEE C57.13 and IEC 61869 standards. India's CEA grid code revisions specify strict accuracy limits for renewable integration zones.
Current transformers hold installed capacity. Voltage transformers are rotating up the share rankings as digital substation architectures elevate precision requirements.
Technology:
Technology segmentation tracks how procurement specifications are bifurcating between electromagnetic legacy and optical-digital convergence, with hybrid architectures capturing intermediate margin pools.
- Optical:Faraday-effect current sensors using flint glass fibers that eliminate magnetic saturation risks in 400 kV gas-insulated substations. Texas and German transmission utilities deploy these in process bus architectures despite capital premiums exceeding electromagnetic equivalents.
- Digital:IEC 61850-9-2LE compliant merging units with sampled value outputs for substation automation systems. Demand accelerates in UK distribution network operator tenders where National Grid ESO mandates embedded cybersecurity update commitments.
- Analog:Conventional electromagnetic designs with copper windings and laminated steel cores. Cost-sensitive distribution networks in India and Southeast Asia sustain procurement volumes despite digital migration pressure.
- Hybrid:Analog-digital merging units preserving existing transformer cores while adding optical digital outputs. European brownfield upgrades favor this architecture where full replacement economics are prohibitive.
Optical technology is climbing the fastest as transmission voltage levels rise. Hybrid architectures defend share in retrofit-dominant geographies.
End User:
End user segmentation exposes how utility capital planners have displaced industrial buyers as the dominant procurement archetype, concentrating vendor panel consolidation effects.
- Utilities:Transmission and distribution operators driving grid modernization mandates across China, India, and the United States. FERC synchronized phasor measurement requirements and India's CEA grid code revisions compel precision instrument transformer upgrades.
- Industrial:Manufacturing facilities and process industries with captive substation requirements. Demand fragments across steel, chemical, and mining sectors where protection coordination reliability outweighs digital sophistication.
- Infrastructure:Rail electrification, airport power systems, and data center substations. European rail operators specify compact gas-insulated designs with SF6-alternative insulation under F-Gas Regulation phasedown schedules.
- Commercial:Large building complexes and campus microgrids with distributed energy integration. Procurement prioritizes cost minimization over accuracy class premiums.
Utilities dominate absolute demand volume. Industrial end users are gaining procurement sophistication as captive generation expands.
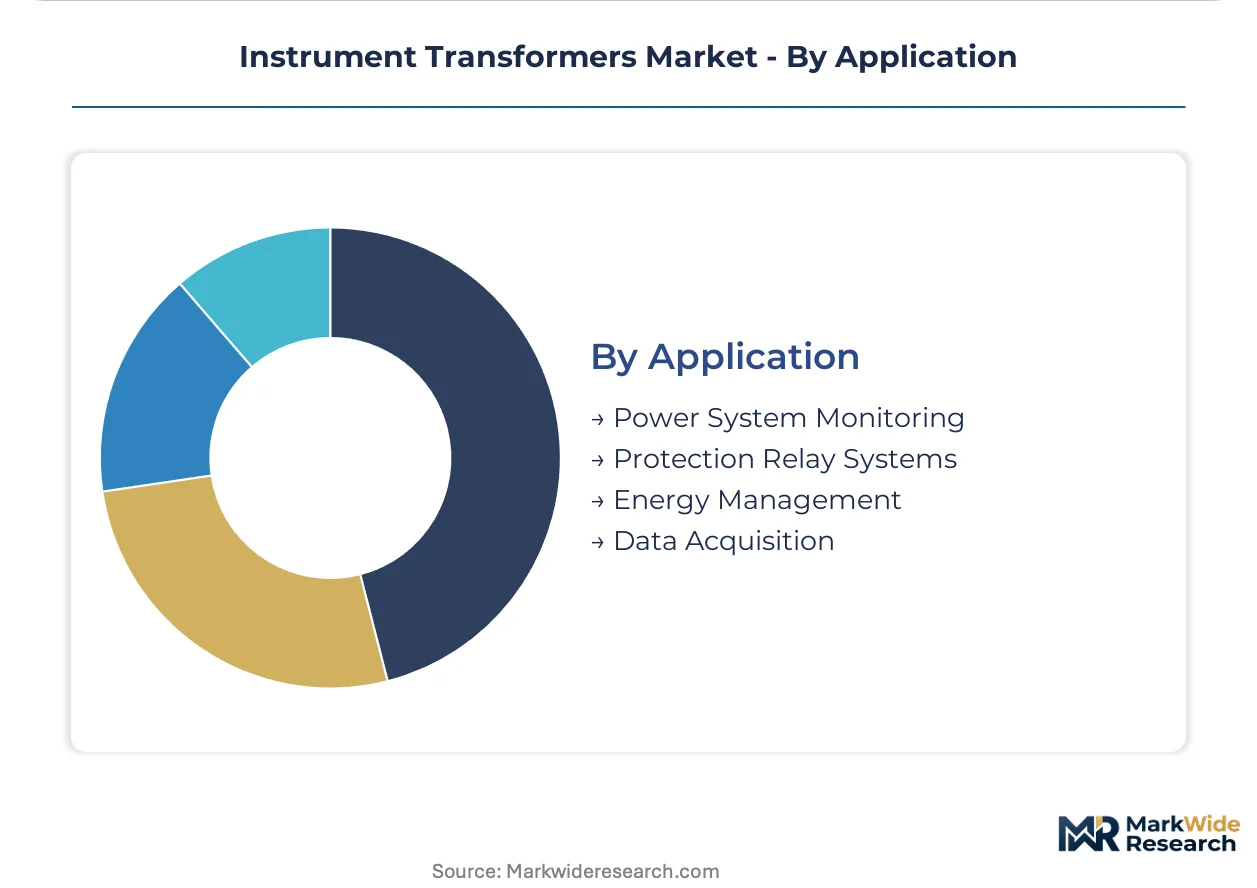
Application:
Application segmentation maps how digital substation architectures are dissolving functional boundaries between measurement, protection, and control systems.
- Power System Monitoring:Wide-area measurement systems requiring synchronized phasor data from precision instrument transformers. US interconnection zones deploy these under FERC Order 693 reliability standards.
- Protection Relay Systems:Fault detection and isolation circuits demanding transient response stability. ABB Ltd. and Siemens Energy AG compete through integrated relay-transformer bundles.
- Energy Management:Revenue metering and load profiling applications where accuracy class certification determines procurement eligibility. India's renewable integration zones enforce CEA-mandated accuracy upgrades.
- Data Acquisition:Process bus architectures with IEC 61850-9-2LE sampled value streams for substation automation. Cybersecurity vulnerabilities in merging units reshape supplier qualification criteria.
Protection relay systems anchor installed base. Power system monitoring is expanding most quickly as wide-area measurement deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese manufacturers dominate high-voltage insulation exports to transmission utilities across the Middle East and Southeast Asia. Trade corridors from China's silicon steel mills feed transformer core fabrication clusters in India and Brazil.
United States
FERC Order 693 mandates synchronized phasor measurement unit deployment across interconnection zones. The Federal Energy Regulatory Commission enforces transmission reliability standards requiring precision instrument transformer upgrades. Texas transmission utilities deploy optical current sensors in 400 kV corridors near Houston and Dallas-Fort Worth.
China
State Grid Corporation accelerates transmission expansion in western provinces with ultra-high voltage direct current projects. The National Energy Administration enforces dual carbon goals that reshape substation procurement specifications. Xi'an and Shenyang anchor manufacturing clusters where domestic suppliers capture utility framework agreements.
Germany
The F-Gas Regulation imposes sulfur hexafluoride phasedown schedules that force vacuum insulation redesigns. Transmission system operators specify IEC 61850 process bus architectures in brownfield digital substation retrofits. Siemens Energy AG and RITZ Instrument Transformers GmbH anchor high-voltage expertise in Bavaria and Lower Saxony.
India
The Central Electricity Authority enforces grid code revisions requiring accuracy-class upgrades for metering transformers in renewable integration zones. State distribution utilities in Gujarat and Maharashtra face compressed replacement timelines. Bangalore and Chennai clusters concentrate digital substation integration engineering talent.
Japan
METI drives smart grid interoperability frameworks that reshape supplier qualification criteria. Domestic utilities prioritize hybrid analog-digital architectures for earthquake-resilient substations. Osaka and Nagoya house precision instrument transformer manufacturing for 765 kV transmission corridors.
Instrument Transformers Market Vendor Landscape
Player mix skews toward integrated electrical equipment conglomerates with dedicated high-voltage divisions. Market structure concentrates around six-to-eight strategic partners per major utility procurement panel, displacing regional specialists. Two archetypes dominate: full-portfolio suppliers bundling transformers with protection relays, and precision-focused specialists in optical sensing. Competitive moves center on cybersecurity certification investments and decade-long service contract frameworks.
Within the integrated conglomerate tier, Schneider Electric SE, Siemens Energy AG, and ABB Ltd. exemplify positioning around digital substation portfolios. Schneider Electric SE leverages French engineering heritage in utility automation systems. Siemens Energy AG anchors German high-voltage direct current project expertise. ABB Ltd. represents Swiss-Swedish positioning across protection relay integration. These three occupy positions where IEC 61850 compliance and firmware engineering capabilities determine procurement eligibility.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Mitsubishi Electric Corporation |
| ABB Ltd. |
| Eaton Corporation plc |
| Toshiba Corporation |
| Siemens Energy AG |
| Arteche Group |
| RITZ Instrument Transformers GmbH |
| General Electric Company |
| Others |
Supply Flow & Price Mechanics
Silicon steel substitution for amorphous metal cores is redrawing procurement maps from China's Baosteel mills to Japanese specialty alloy foundries while compressing transformer core pricing premiums. This material transition simultaneously elevates logistics costs for grain-oriented electrical steel and creates tiered sourcing strategies among European and Indian manufacturers.
Pricing Analysis
Three-generation pricing spreads separate optical current sensors from electromagnetic legacy designs and emerging hybrid merging units. Three-tier pricing structure across premium optical, standard electromagnetic, and economy analog tiers reflects certification complexity under IEC 61869 and IEEE C57.13. Cost compression in the electromagnetic tier is intensifying because Indian distribution utilities enforce accelerated replacement schedules. State-owned transmission operators in China and India exhibit lowest price sensitivity, while Southeast Asian commercial microgrid developers drive hardest bargaining.
Supply Chain Analysis
Strategic stockpiling of grain-oriented silicon steel dominates procurement behavior among Japanese and German transformer manufacturers facing China's export quota uncertainties. Electrical-grade silicon steel production concentrates in China and Japan, with copper winding supply anchored in Chile and Zambia. Supply chain risk centers on single-source vulnerability for 0.23mm-thick core laminations. Distribution runs through utility framework agreements with embedded decade-long service commitments rather than spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around IEC 61850 certification creates formidable defensive moats for established suppliers. Switching costs escalate as utilities consolidate vendor panels and embed firmware-dependent service contracts.
For Market Incumbents: Consolidate cybersecurity engineering capabilities to defend against optical sensor specialists encroaching on digital substation tenders. Acquire merging unit firmware teams in Bangalore or Chennai to preempt talent scarcity. Lock in decade-long framework agreements with National Grid ESO and State Grid Corporation before procurement panels close to new entrants. For New Entrants and Emerging Players: Differentiate on hybrid analog-digital architectures targeting European brownfield retrofits where full optical replacement economics fail. Penetrate India's renewable integration zones with CEA-compliant metering transformers before accuracy-class mandates harden. Partner with German transmission system operators seeking SF6-alternative insulation redesigns under F-Gas Regulation phasedown schedules. For Investors and Strategic Acquirers: F-Gas Regulation implementation reshapes the acquisition landscape toward vacuum insulation specialists with MDR-equivalent pressure equipment qualifications. Five-to-ten year viability favors precision optical sensing engineers over laminated core manufacturers. Watch for IEC 61850-9-2LE process bus deployment rates in UK distribution network operator tenders as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | Firmware update capabilities determine eligibility in National Grid ESO consolidated tenders. |
| Backward Integration into Silicon Steel | Captive core lamination supply insulates margins from China's export quota volatility. |
| Hybrid Architecture Product Launch | Analog-digital merging units capture European brownfield upgrade margin pools. |
| SF6-Alternative Insulation Redesign | Vacuum insulation qualifications unlock German, French, and Dutch procurement pipelines. |
| Long-Term Service Contract Framework | Embedded cybersecurity patching commitments secure recurring revenue from utility panels. |
Methodological Framework
Cross-validation between utility procurement officer interviews and IEC standard committee documentation anchors the qualitative findings. Primary fieldwork engaged transmission planning engineers, substation automation architects, protection relay specialists, and high-voltage insulation designers across China, Germany, India, Japan, and the United States. Secondary sources included FERC Order 693 filings, CEA grid code revisions, State Grid Corporation tender databases, and METI smart grid interoperability frameworks. Bottom-up unit deployment estimates triangulate against top-down transmission infrastructure investment forecasts.
Sensitivity analysis around optical sensor cost curves and electromagnetic replacement cycles informs the analytical framework across the projection horizon. Segmentation dimensions span product type, technology generation, end-user archetype, and application function. CAGRs derive from installed base depreciation schedules, grid modernization mandate timelines, and digital substation adoption velocity. Forecast inputs incorporate silicon steel price indices and IEC 61850 certification lag times.
The analysis sits within stated boundaries; outcomes outside sustained utility capital expenditure commitments or accelerated F-Gas Regulation enforcement would require recalibration. Forecasts reflect assumptions about standardization timelines and raw material supply continuity. Revision becomes warranted when optical sensor capital premiums fall below twenty percent of electromagnetic equivalents or when China's silicon steel export controls tighten beyond historical ranges.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Battery Charger Market
Electrical Power Equipment
Global Low Voltage Electric Drives Market
Electrical Power Equipment
AC Residential Switchgear Market
Electrical Power Equipment
Domestic Hot Water (DHW) Tanks Market
Electrical Power Equipment
3rd Rail Current Collector Market
Electrical Power Equipment
Global Electric Power Substation Automation Market
Electrical Power Equipment
Power Over Ethernet Lighting Market
Electrical Power Equipment
Substation Market
Electrical Power Equipment
South America Medium Voltage Switchgear Market
Electrical Power Equipment
Bio-Based Transformer Oil Market
Electrical Power Equipment
Overhead Power Cables Market
Electrical Power Equipment
Power Line Carrier System Market
Electrical Power Equipment
South America Gas Insulated Switchgear Market
Electrical Power Equipment
Frameless Brushless DC Motors Market
Electrical Power Equipment
Electric Submersible Pump Cable Market
Electrical Power Equipment
High Voltage Ionising Air Gun Market