
 Europe Smart Transformers Market | 2026-2036
Europe Smart Transformers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Smart Transformers Market Foresight
Renewable energy facilities are rotating into the dominant buyer archetype as European utilities phase out fossil-linked infrastructure. Siemens AG leverages deep manufacturing scale across German production hubs to anchor regional supply. Schneider Electric SE differentiates through IoT-integrated transformer platforms that enable real-time grid diagnostics. Hitachi Energy Ltd sustains technology leadership in high-voltage digital control systems for substation applications.
Europe smart transformers are power conversion devices rated typically from 10 kVA to 500 MVA, incorporating solid-state switching, embedded sensors, and bidirectional power flow capability to stabilize variable renewable injection. Their primary purpose is voltage regulation with millisecond response times while enabling decentralized grid management. Step-down transformers occupy the largest installed base across distribution networks, though isolation transformers command premium pricing in offshore wind interconnection projects. IoT integration represents the fastest-expanding technology segment as utilities deploy cloud-connected thermal monitoring and predictive maintenance algorithms.
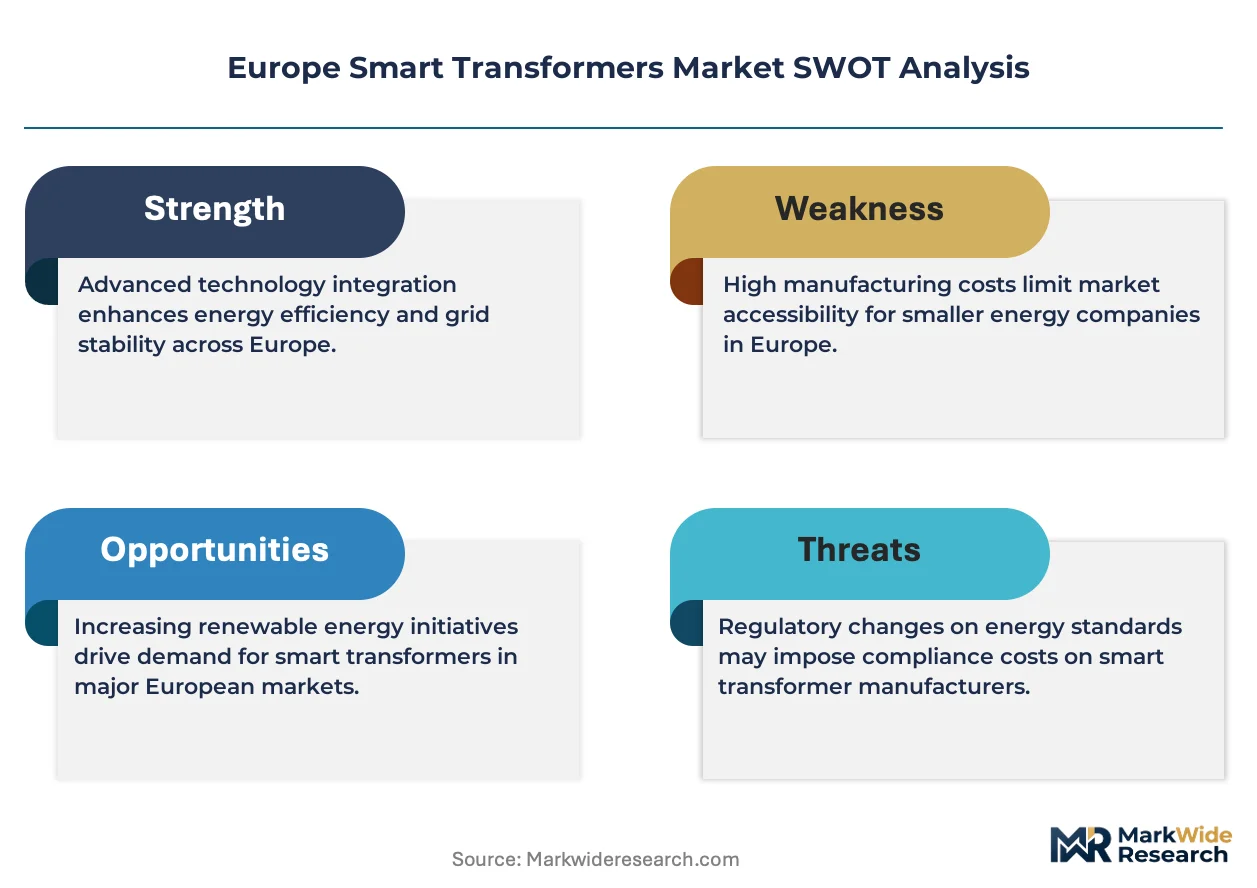
The EU Green Deal, F-Gas Regulation, and CE marking requirements under the EU AI Act collectively mandate efficiency thresholds and cybersecurity certification for grid-connected assets. ECHA chemical compliance and national regulators in Germany, France, and Italy enforce material traceability that shapes supplier qualification timelines. Stakeholders must monitor how the CSRD disclosure framework will compel utilities to document embodied carbon in transformer procurement decisions.
Market Dynamics
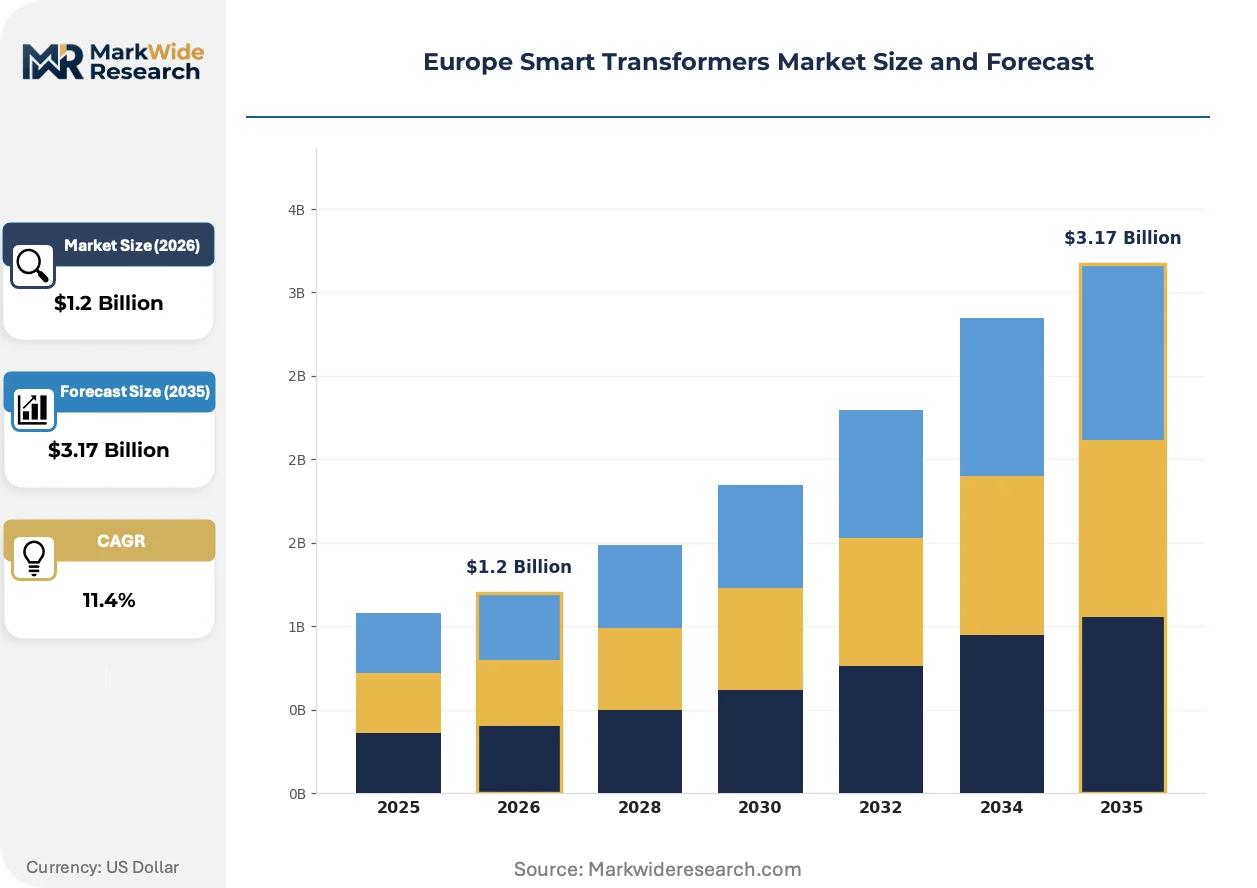
The EU Green Deal and F-Gas Regulation are compressing procurement timelines for digitally monitored grid assets as utilities face binding efficiency mandates and carbon disclosure requirements across member states.
Growth Catalysts
- EU Green Deal efficiency mandates:Binding carbon reduction targets are forcing utilities to accelerate replacement of conventional transformers with sensor-equipped alternatives that enable real-time grid optimization.
- Offshore wind interconnection surge:North Sea and Baltic projects require bidirectional power flow capability that only solid-state switching architectures can deliver at scale.
- CE marking cybersecurity requirements:The EU AI Act's grid-connected asset certification is creating compliant product demand that favors established European manufacturers with testing infrastructure.
Market Restraints
- Rare earth magnet supply concentration:Solid-state transformer cores depend on neodymium and dysprosium where processing capacity clusters in China, exposing European fabricators to input volatility and export restriction risk.
- ECHA material traceability compliance:REACH substance restrictions on insulating oils and flame retardants extend supplier qualification timelines by 12-18 months for non-EU component sources.
- Silicon carbide wafer technical limitation:High-voltage power modules above 3.3 kV face yield constraints that limit production scale for utility-grade installations.
Strategic Opportunities
- Polish and Romanian distribution grid underpenetration:These member states lag Germany and France in smart meter deployment, creating first-mover advantage for integrated transformer-communication platform vendors.
- CSRD embodied carbon disclosure:The Corporate Sustainability Reporting Directive compels utilities to document supply chain emissions, favoring regional manufacturers with auditable production footprints.
- IoT-thermal monitoring convergence:Cloud-connected predictive maintenance algorithms are opening recurring revenue streams beyond hardware sales for asset management service providers.
Industry Challenges
- Power electronics firmware certification timelines:Grid code compliance testing for bidirectional control algorithms requires 8-14 months of national regulator validation in Germany, France, and Italy.
- Legacy SCADA integration complexity:Utilities operate heterogeneous communication protocols that demand custom middleware development for each deployment.
- High-voltage testing facility scarcity:Continental Europe maintains only six laboratories capable of full-load validation for 400 kV class smart transformers, creating queue bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Smart Transformers Market |
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $3.17 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Step-Up Transformers, Step-Down Transformers, Isolation Transformers, Autotransformers Technology: Digital Control, IoT Integration, Cloud-based Solutions, Automation Systems End User: Utility Companies, Industrial Users, Commercial Buildings, Renewable Energy Facilities Installation Type: Indoor Installations, Outdoor Installations, Pole-Mounted Units, Substation Applications |
| Companies Covered | Hitachi Energy Ltd, Siemens AG, Eaton Corporation PLC, Schneider Electric SE, General Electric Company, ABB Ltd., SGB-SMIT, Westrafo SRL, Societa Elettromeccanica Arzignanese SpA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Smart Transformers Market Shifts & Advancements
Digital twin architecture is compressing development cycles for grid assets while regulatory pressure on fluorinated gases accelerates material substitution in insulation systems.
Solid-state transformer topology is displacing conventional electromagnetic designs in medium-voltage distribution applications. German and French utilities are piloting 10-40 MVA silicon carbide-based units for urban substations. This displacement is compressing the 30-year replacement cycle toward 15-year technology refresh intervals as efficiency gains compound.
The F-Gas Regulation's phasedown of sulfur hexafluoride and perfluorocarbon insulating media is forcing reformulation of transformer dielectric systems. Manufacturers are accelerating biodegradable ester fluid and dry-type resin casting adoption to maintain CE marking eligibility. Offshore wind transformer platforms in the North Sea corridor face the most acute compliance pressure given their sealed-environment maintenance constraints.
Outcome-based asset performance contracts are fragmenting traditional equipment procurement patterns. Nordic utilities are unbundling hardware purchase from 15-year availability guarantees, transferring operational risk to OEM service organizations. This reconfiguration is most advanced in Denmark and Sweden where district heating-coupled grid operators prioritize thermal efficiency over capital expenditure minimization.
Europe Smart Transformers Market Segmentation
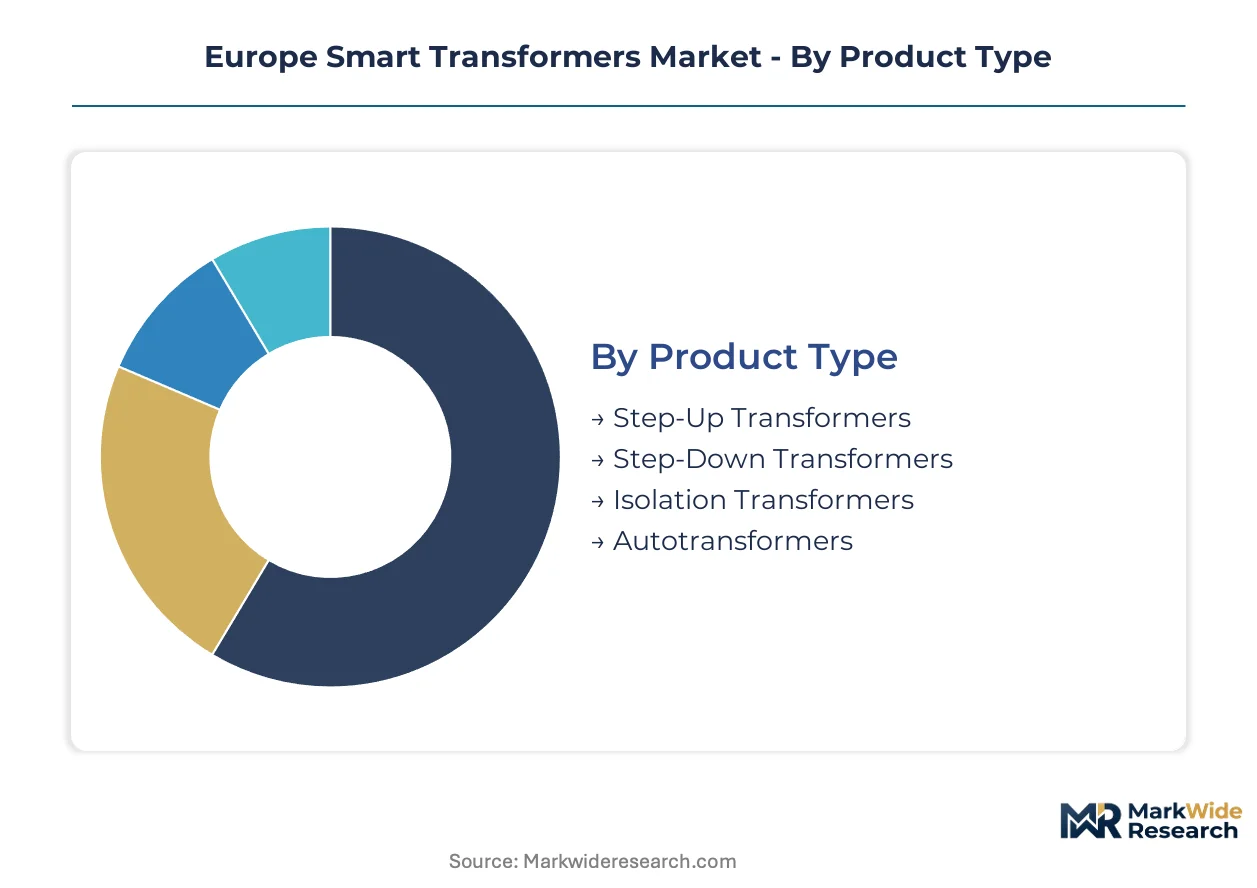
Smart transformer procurement patterns diverge sharply across product architectures and deployment contexts. Segment-level intelligence reveals where technology substitution accelerates versus where legacy specifications dominate purchasing decisions.
Product Type:
Domestic production concentrates on medium-voltage distribution units for German and French utilities, while export demand pulls high-voltage specialty designs toward North Sea offshore clusters.
- Step-Up Transformers:These units elevate voltage from generator terminals to transmission levels, typically 10-30 kV to 110-400 kV. Offshore wind interconnection projects in the Danish and German North Sea corridors drive procurement volume, constrained by 400 kV testing facility bottlenecks across continental Europe.
- Step-Down Transformers:Voltage reduction devices for distribution networks constitute the largest installed base across European utilities. German municipal utilities and French Enedis distribution networks are accelerating replacement of electromagnetic designs with silicon carbide-based solid-state alternatives to meet EU Green Deal efficiency mandates.
- Isolation Transformers:Galvanic separation units protect sensitive downstream equipment in medical and data center applications. Premium pricing reflects copper winding specifications and custom shielding requirements.
- Autotransformers:Single-winding voltage conversion delivers material efficiency for high-power railway electrification and industrial motor drives. Traction power supply modernization in Italy and Spain sustains niche demand.
Step-down transformers command the established base. The steepest expansion runs through step-up units serving offshore wind export cables.
Technology:
Cost tier separation is pronounced: digital control modules occupy mid-range pricing while cloud-connected predictive platforms capture premium service contracts.
- Digital Control:Embedded microprocessor-based voltage regulation enables millisecond response to grid disturbances. German transmission system operators mandate this capability for new substation installations under national grid code revisions.
- IoT Integration:Sensor-equipped assets transmit thermal, load, and insulation condition data to centralized asset management platforms. Nordic utilities in Denmark and Sweden are deploying these most aggressively under outcome-based performance contracts that unbundle hardware from operational guarantees.
- Cloud-based Solutions:Remote diagnostics and predictive maintenance algorithms reduce truck-roll frequency for distributed transformer fleets. Cybersecurity certification under the EU AI Act extends deployment timelines by 8-14 months.
- Automation Systems:Self-healing grid coordination protocols enable decentralized fault isolation without central control center intervention. Polish and Romanian distribution networks lag in deployment due to heterogeneous legacy SCADA infrastructure.
Digital control anchors current procurement volumes. IoT integration is climbing the fastest as utilities restructure asset management economics around availability guarantees.
End User:
Application context determines specification stringency: utility procurement emphasizes grid code compliance while industrial users prioritize power quality metrics.
- Utility Companies:Transmission and distribution operators represent the dominant procurement volume across Europe. German TenneT and French RTE are consolidating supplier bases around manufacturers with integrated testing and firmware certification capabilities.
- Industrial Users:Manufacturing facilities and process plants demand voltage sag ride-through and harmonic mitigation. Automotive electrification investments in Hungary and Czechia are expanding medium-voltage substation requirements.
- Commercial Buildings:High-rise and campus installations prioritize compact footprint and low noise emission. Dry-type resin-cast designs are displacing oil-filled units in urban cores under F-Gas Regulation pressure.
- Renewable Energy Facilities:Solar and wind generators require bidirectional power flow and anti-islanding protection. This segment is gaining share fastest as fossil-linked infrastructure phases out across member states.
Utility companies retain the volume base. Renewable energy facilities are expanding most quickly as generation asset mix shifts.
Installation Type:
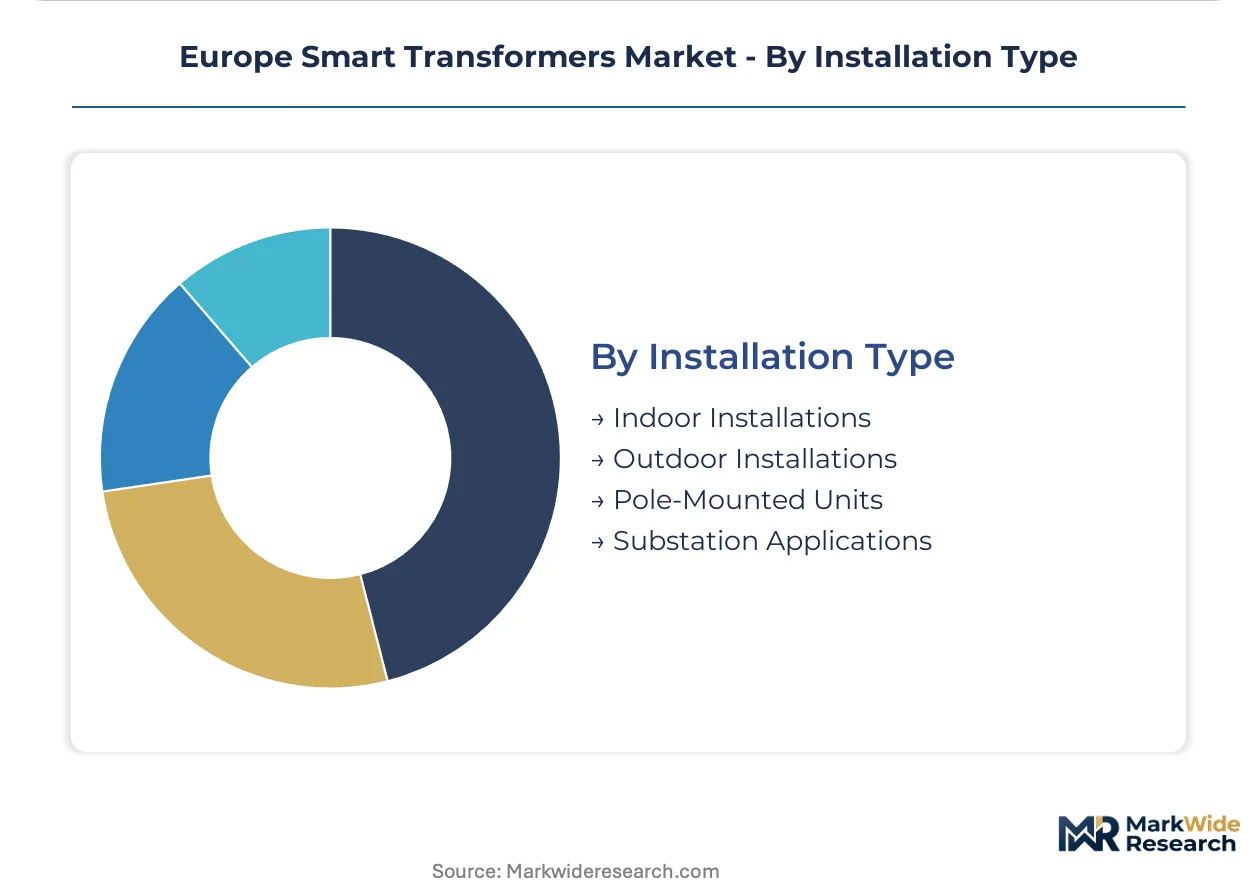
Volume concentrates in outdoor substation applications while margin accrues to specialized pole-mounted and sealed-environment designs.
- Indoor Installations:Climate-controlled environments in data centers and industrial facilities permit compact dry-type designs. Fire safety codes in German commercial construction favor resin-cast insulation over oil-filled alternatives.
- Outdoor Installations:Weather-hardened enclosures dominate utility distribution networks. Salt corrosion specifications tighten for North Sea coastal deployments.
- Pole-Mounted Units:Space-constrained urban and rural distribution rely on compact single-phase designs. Swedish and Finnish utilities favor these for remote line extensions.
- Substation Applications:High-voltage collector and distribution substations integrate multiple transformer bays with switchgear and protection systems. 400 kV class smart transformer validation queues at only six continental European laboratories constrain deployment timelines.
Outdoor installations hold the established footprint. Substation applications are expanding most rapidly as urban network densification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility companies dominate procurement across the region, with German and French transmission operators consolidating supplier bases around manufacturers with integrated testing capabilities. Renewable energy facilities are rotating into the fastest-expanding buyer archetype as fossil-linked infrastructure phases out.
Germany
North Sea offshore wind interconnection projects and urban substation densification drive demand for silicon carbide-based solid-state units. The national grid code revision under the EU Green Deal mandates embedded microprocessor voltage regulation for new installations. Manufacturing concentrates in Bavaria and Baden-Württemberg, where production hubs anchor regional supply chains for distribution network assets.
France
Enedis distribution network modernization and nuclear-to-renewable transition accelerate replacement of electromagnetic transformer designs. CE marking requirements under the EU AI Act extend cybersecurity certification timelines for grid-connected assets. Industrial clusters in Île-de-France and Auvergne-Rhône-Alpes host testing infrastructure for firmware validation and grid code compliance.
United Kingdom
North Sea offshore export cable projects and London network densification create demand for high-voltage specialty designs. The F-Gas Regulation phases down sulfur hexafluoride insulating media, forcing dielectric system reformulation. Manufacturing and testing activity concentrates in the Midlands and Southeast England, serving both domestic utilities and North Sea wind developers.
Italy
Traction power supply modernization and industrial motor drive applications sustain niche demand for autotransformer configurations. ECHA REACH substance restrictions on insulating oils extend supplier qualification timelines for non-EU component sources. Production and engineering capabilities cluster in Lombardy and Emilia-Romagna, supporting railway electrification and manufacturing sector requirements.
Poland
Distribution grid underpenetration relative to Western European benchmarks creates first-mover opportunity for integrated transformer-communication platforms. The CSRD disclosure framework will compel utilities to document embodied carbon in procurement decisions. Warsaw and Silesian industrial corridors are emerging as deployment zones for smart meter and grid automation convergence.
Europe Smart Transformers Market Competitive Landscape
Player mix skews toward diversified electrical equipment conglomerates with integrated manufacturing and firmware certification capabilities. The supplier base concentrates around manufacturers with captive high-voltage testing infrastructure and established relationships with national transmission system operators. Three archetypes dominate: German industrial conglomerates with scale advantages, French energy management specialists with IoT platform integration, and Swiss-Swedish engineering groups with high-voltage digital control expertise. Competitive moves center on strategic partnerships for silicon carbide supply security and geographic expansion into underpenetrated Central European distribution markets.
Among Germany-based industrial groups, Siemens AG anchors the scale-driven tier with deep manufacturing footprints across Bavarian production hubs. Schneider Electric SE occupies the IoT-integrated platform position, exemplifying the energy management specialist archetype through sensor-equipped asset offerings. Hitachi Energy Ltd represents the high-voltage digital control segment, sitting within the engineering group tier focused on substation applications and offshore wind interconnection. These three companies collectively illustrate how regulatory compliance capabilities and testing infrastructure ownership determine competitive positioning in a market where firmware certification timelines stretch 8-14 months.
| Leading Market Players |
|---|
| Hitachi Energy Ltd |
| Siemens AG |
| Eaton Corporation PLC |
| Schneider Electric SE |
| General Electric Company |
| ABB Ltd. |
| SGB-SMIT |
| Westrafo SRL |
| Societa Elettromeccanica Arzignanese SpA |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts with silicon carbide wafer suppliers lock in both supply access and price visibility for European transformer OEMs facing EU Green Deal procurement acceleration. These arrangements tether component costs to indexed rare earth magnet pricing while insulating fabricators from spot market volatility in neodymium and dysprosium processing.
Pricing Analysis
Cost-plus contracts with London Metal Exchange copper indexation dominate procurement between German utilities and Bavarian production hubs. Three-tier pricing structure across premium firmware-certified, standard CE-marked, and economy non-connected tiers separates grid code compliance levels. Price differentiation rests on cybersecurity certification under the EU AI Act and embedded sensor density. Cost compression in the economy tier is intensifying because Polish and Romanian distributors prioritize capital expenditure minimization over predictive maintenance capability. Renewable energy facilities exhibit lowest price sensitivity given outcome-based availability guarantees that unbundle hardware from service contracts.
Supply Chain Analysis
Inventory buffers for silicon carbide power modules extend to 26-32 weeks given yield constraints above 3.3 kV voltage classes. Manufacturing concentrates in Germany, France, and Switzerland for high-voltage digital control systems, while China and Vietnam anchor rare earth magnet processing. Raw material dependencies span copper windings, grain-oriented electrical steel, and biodegradable ester fluids substituting for sulfur hexafluoride under F-Gas Regulation. Single-source vulnerability concentrates in neodymium processing capacity. Distribution runs through utility-direct procurement channels and EPC contractor bundling for offshore wind interconnection projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Smart Transformers Market represents a high-growth disruption as solid-state transformer topology displaces conventional electromagnetic designs under binding EU Green Deal efficiency mandates. This technological inflection compresses replacement cycles and reconfigures supplier qualification around firmware certification capabilities.
For Market Incumbents: Shield market position by deepening captive silicon carbide supply relationships and accelerating high-voltage testing facility expansion in Germany and France. Grid code compliance timelines stretching 8-14 months create defensive moats against emerging entrants lacking regulator relationships. Prioritize backward integration into power electronics assembly to capture margin from solid-state topology adoption. For New Entrants and Emerging Players: Anchor in Polish and Romanian distribution grid underpenetration where smart meter deployment lags Western European benchmarks by 7-10 years. Target integrated transformer-communication platforms that bundle automation systems with hardware sales. Pursue partnership-based entry with national transmission system operators seeking to diversify supplier bases beyond incumbent conglomerates. For Investors and Strategic Acquirers: Firmware-certified mid-cap specialists with embedded IoT platforms and established ECHA REACH compliance represent the most attractive acquisition target archetype. Long-term viability hinges on exposure to offshore wind interconnection growth and CSRD-driven embodied carbon disclosure requirements. Monitor silicon carbide wafer yield improvements as the critical inflection signal for production scale economics in utility-grade installations.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Agreement | Secures semiconductor input for solid-state transformer production at German manufacturing hubs. |
| High-Voltage Testing Facility Expansion | Reduces validation queue bottlenecks for 400 kV class units at continental European laboratories. |
| Firmware Certification Investment | Accelerates grid code compliance timelines under national regulator protocols in Germany and France. |
| Outcome-Based Service Contract | Captures recurring revenue from Nordic utilities unbundling hardware from availability guarantees. |
| Biodegradable Ester Fluid Adoption | Maintains CE marking eligibility under F-Gas Regulation phasedown of fluorinated insulating media. |
Research Methodology
Cross-validation between utility procurement officer interviews and secondary regulatory filings anchors the qualitative findings in documented policy implementation timelines. Primary fieldwork engaged transmission system operators, distribution network planners, EPC contractors for offshore wind projects, and power electronics procurement leads at German and French utilities. Secondary sources span EU Green Deal implementation reports, ECHA REACH substance restriction databases, national grid code revision filings, and CE marking certification records. Bottom-up unit deployment tracking and top-down infrastructure investment flows were triangulated to bound volume estimates.
Sensitivity analysis across silicon carbide yield scenarios and rare earth magnet price volatility bands tests forecast robustness over the projection horizon. The analytical framework models product type, technology tier, end-user segment, and installation context as core dimensions, with regulatory compliance intensity as an industry-specific overlay. CAGRs were derived from compound growth trajectory fitting to utility capital expenditure plans and renewable interconnection project pipelines. Forecast inputs incorporate EU Green Deal binding targets, F-Gas Regulation phase-down schedules, and CSRD disclosure implementation timelines.
Material uncertainties — rare earth export restrictions, silicon carbide wafer yield breakthroughs, and grid code revision delays — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and technology substitution rates that could shift with policy or innovation shocks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Amorphous Core Transformers Market
Transformers
South America Transformer Market
Transformers
Current Transformer Market
Transformers
United States Power Transformer Market
Transformers
Oil Immersed Transformer and Dry Type Transformer Market
Transformers
United States Transformer Market
Transformers
Latin America Transformer Market
Transformers
HVDC Converter Transformers Market
Transformers
China Transformer Market
Transformers
Cast Resin Transformers Market
Transformers
India Power Transformer Market
Transformers
Europe Telecom Transformers Market
Transformers
Neon Transformer Market
Transformers
United States Distribution Transformer Market
Transformers
Traction Transformer Market
Transformers
North America Dry Type Transformer Market