
 Electric Submersible Pump Cable Market | 2026-2036
Electric Submersible Pump Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Submersible Pump Cable Market Analysis
Asset-light leasing models for downhole electrical infrastructure are reshaping competitive dynamics in the ESP cable sector. Prysmian Group leverages integrated compound manufacturing to sustain margin control across high-temperature insulation grades. Schlumberger anchors its position through captive demand from artificial lift service bundling. Nexans competes via specialized EPDM and polypropylene formulations rated for gas-lift corrosive environments.
Electric submersible pump cable consists of multiple conductor assemblies encased in elastomeric or thermoplastic insulation barriers, typically rated for continuous operation at temperatures exceeding 200°C in hydrocarbon-laden wellbores. The product transmits three-phase electrical power from surface variable-speed drives to downhole ESP motors operating at depths beyond 3,000 meters. Flat profile configurations dominate onshore shale applications where narrow wellbore clearances limit round cable deployment. Copper conductor material commands premium positioning due to superior conductivity in extended-reach horizontal wells. Medium voltage power rating segments show fastest expansion as operators push deeper into unconventional reservoirs requiring higher horsepower delivery.
API RP 11S4 sets minimum electrical and mechanical qualification thresholds for ESP cable integrity under simulated downhole pressure cycling. IEC 60502-2 governs extruded insulation thickness and partial discharge limits for medium voltage submersible applications. NHTSA and OSHA surface equipment standards indirectly shape cable armoring specifications through motor control enclosure requirements. Stakeholders must monitor API qualification protocol revisions and IEC harmonization timelines to anticipate insulation material substitution cycles.
Market Dynamics
Horizontal lateral extension beyond 15,000 feet in Permian Basin shale formations is forcing cable manufacturers to engineer conductor geometries that maintain electrical integrity under extreme tensile loading and thermal cycling.
Growth Catalysts
- API RP 11S4 qualification tightening:The American Petroleum Institute's revised downhole electrical integrity protocols are mandating enhanced partial discharge resistance in insulation systems, compelling operators to replace legacy cable inventories.
- Saudi Aramco artificial lift expansion:The national oil company's accelerated deployment of high-horsepower ESP systems in mature carbonate reservoirs is generating concentrated demand for medium-voltage flat-profile cable configurations.
- EPDM compound advancement:Next-generation ethylene propylene diene monomer formulations rated for 232°C continuous operation are unlocking deeper well applications previously restricted by thermal degradation limits.
Market Restraints
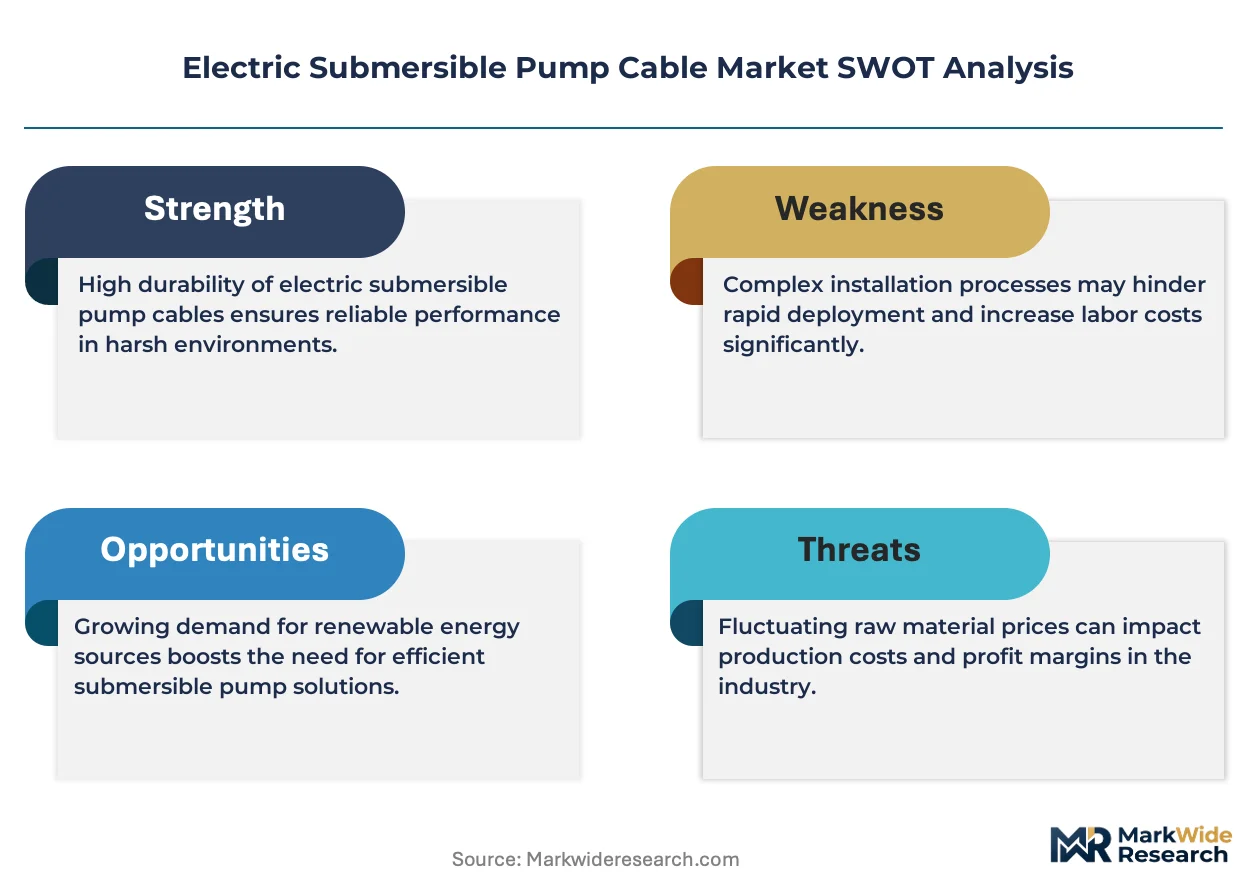
- Copper price volatility:Conductor material constitutes 35-45% of finished cable cost, and London Metal Exchange price swings directly compress manufacturer margins without pass-through mechanisms.
- Specialized compound supply concentration:High-temperature insulation polymer production clusters in Germany and Japan, creating single-source vulnerability for cable fabricators in North America and the Middle East.
- Hydrogen sulfide permeation limits:Sour gas environments above 5,000 ppm H2S accelerate elastomer degradation, restricting cable service life in specific Anadarko Basin and North Sea applications.
Strategic Opportunities
- China unconventional reservoir development:Sinopec and PetroChina are scaling shale ESP deployment in Sichuan Basin formations, creating import substitution potential for qualified international cable suppliers.
- Digital twin integration:Convergence of downhole cable monitoring sensors with surface predictive analytics platforms enables condition-based replacement contracts displacing time-based maintenance schedules.
- US Inflation Reduction Act domestic content:Tax credit incentives for domestically manufactured energy infrastructure components are reshaping sourcing calculus for Permian Basin operators.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise for high-voltage EPDM and polypropylene insulation systems concentrates among retiring specialists at compound manufacturers.
- IEC-API harmonization timeline:Divergent partial discharge testing methodologies between European and American qualification bodies extend product certification cycles by 8-14 months.
- Legacy wellhead compatibility:New flat-profile cable geometries require surface equipment modifications in 40% of installed ESP bases, complicating retrofit economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Submersible Pump Cable Market |
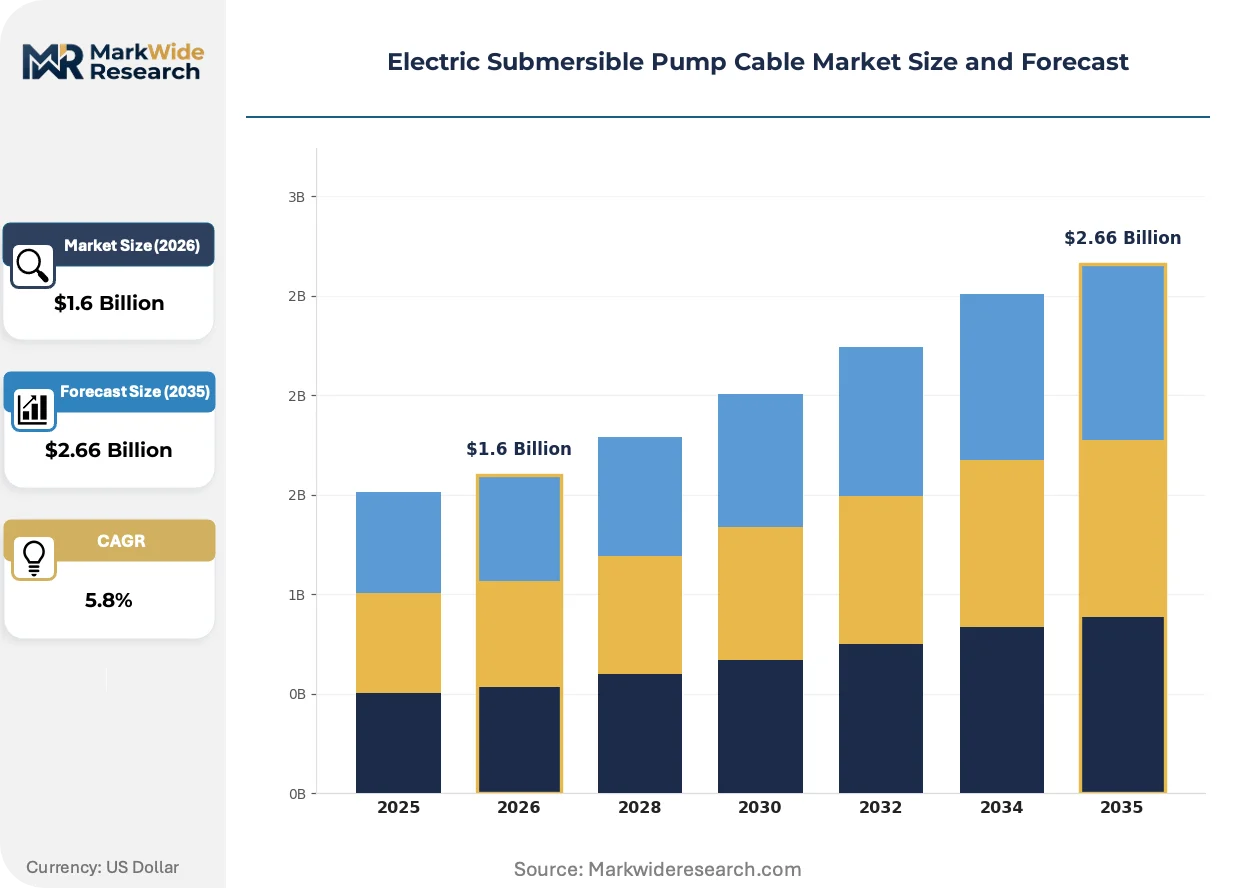
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $2.66 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Core, Multi-Core, Flat, Round Material: Copper, Aluminum, PVC, Rubber Installation Type: Permanent, Temporary, Submerged, Above Ground Power Rating: Low Voltage, Medium Voltage, High Voltage, Ultra High Voltage |
| Companies Covered | Prysmian Group, General Cable, Schlumberger, Southwire Company, Nexans, Marmon Group, Borets, Hitachi Metals, Weatherford International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Submersible Pump Cable Market Emerging Trajectories
Downhole electrical infrastructure is undergoing material science and digital integration transformation. Three developments are compressing traditional equipment lifecycles and rewiring supplier-operator relationships.
Polyimide-based insulation tape systems are virtualizing the thermal protection layer in medium-voltage ESP cables. Permian Basin shale operators are specifying these materials for 250°C rated installations where conventional EPDM compounds fail. This virtualization is compressing the qualification timeline for next-generation cable architectures by enabling rapid thermal modeling validation without extended field trials.
REACH SVHC candidate list expansion is restricting chlorinated flame retardant additives in European-manufactured cable compounds. The European Chemicals Agency's 2024 update triggered reformulation investments at compound suppliers serving North Sea operators. Medium-voltage product lines are responding fastest, with polypropylene-based halogen-free insulation systems displacing legacy PVC-sheathed configurations in EU-sourced inventory.
Lease-versus-own contracting is displacing capital purchase models for downhole electrical systems. Artificial lift service providers are bundling cable replacement into performance-based lift contracts, transferring technical risk from E&P operators to integrated suppliers. This behavior shift concentrates most visibly in US onshore shale plays where operator balance sheet discipline favors operational expenditure structures.
Electric Submersible Pump Cable Market Segmentation
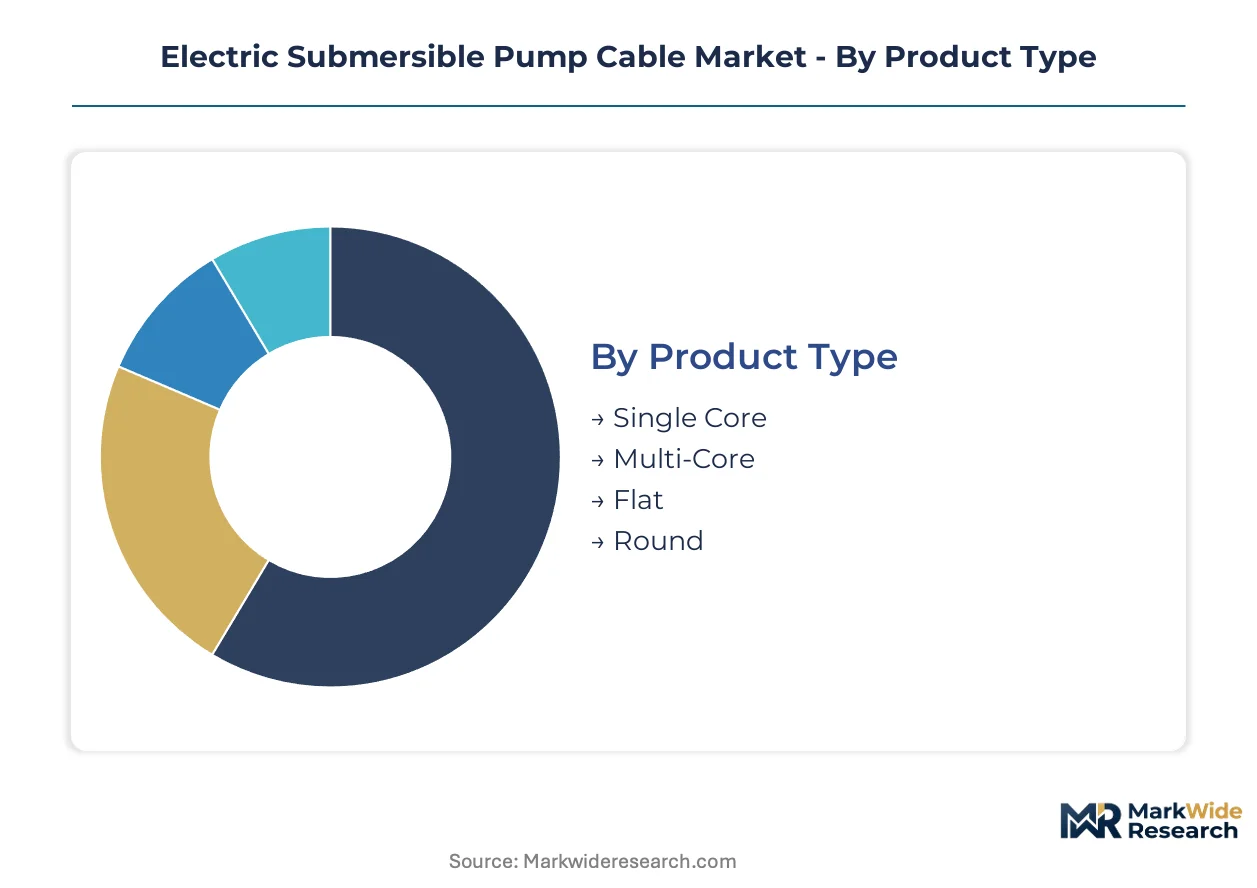
ESP cable segmentation reflects the tension between wellbore geometry constraints and power delivery requirements. Product architecture and material selection directly determine deployment feasibility across conventional and unconventional reservoir profiles.
Product Type:
Mature flat and round configurations dominate established markets while emerging multi-core designs address complex artificial lift architectures.
- Single Core:Simple conductor geometry with individual insulation barriers suits shallow vertical wells with minimal power requirements. Permian Basin operators specify single core for stripper well retrofits where capital efficiency outweighs performance optimization.
- Multi-Core:Integrated three-phase conductor assemblies reduce installation complexity and eliminate field splicing in extended-reach laterals. Saudi Aramco's high-horsepower ESP programs in mature carbonate reservoirs are driving specification shifts toward factory-terminated multi-core bundles.
- Flat:Low-profile cross-section maximizes annular clearance in narrow horizontal wellbores. Shale operators in the Permian and Sichuan Basins specify flat profiles for laterals exceeding 15,000 feet.
- Round:Conventional circular geometry maintains mechanical robustness under tensile loading in deviated well trajectories. Round cables persist in offshore and deepwater applications where crush resistance outweighs clearance constraints.
Flat configurations handle the majority of throughput in unconventional basins; multi-core designs are expanding most quickly in premium artificial lift contracts.
Material:
Cost tier stratification separates premium conductor metals from commodity insulation compounds.
- Copper:Superior electrical conductivity minimizes resistive losses across extended horizontal laterals. US shale producers specify oxygen-free copper for wells exceeding 3,000 meters measured depth despite price volatility exposure.
- Aluminum:Reduced material density lowers deployment weight in deep vertical completions. Chinese national oil companies specify aluminum conductors for cost-sensitive conventional field redevelopment programs.
- PVC:Thermoplastic sheathing provides cost-effective environmental sealing in low-temperature, non-corrosive wellbores. PVC persists in surface cable runs and temporary installations.
- Rubber:EPDM and nitrile formulations deliver hydrocarbon resistance and thermal stability above 200°C. API RP 11S4 qualification protocols are accelerating rubber compound substitution for legacy thermoplastic systems.
Copper maintains the dominant revenue position; rubber insulation compounds are climbing the fastest on specification intensity.
Installation Type:
Application context separates capital-intensive permanent deployments from operational expenditure-driven temporary configurations.
- Permanent:Factory-integrated cable-motor assemblies designed for full well lifecycle operation. Saudi Aramco and ADNOC specify permanent installations in offshore platforms where workover economics prohibit retrieval.
- Temporary:Retrievable cable systems for trial production and exploration appraisal wells. US independents favor temporary installations in Permian infill programs where parent-child well interference demands frequent reconfiguration.
- Submerged:Pressure-rated assemblies for full downhole immersion in wellbore fluids. Submerged ratings are mandatory for all ESP applications below surface packer depths.
- Above Ground:Surface power distribution from variable-speed drives to wellhead penetrations. Above-ground segments face standard industrial cable competition outside API qualification scope.
Permanent installations absorb the bulk of capital allocation; temporary configurations are gaining share fastest through lease-versus-own contracting models.
Power Rating:
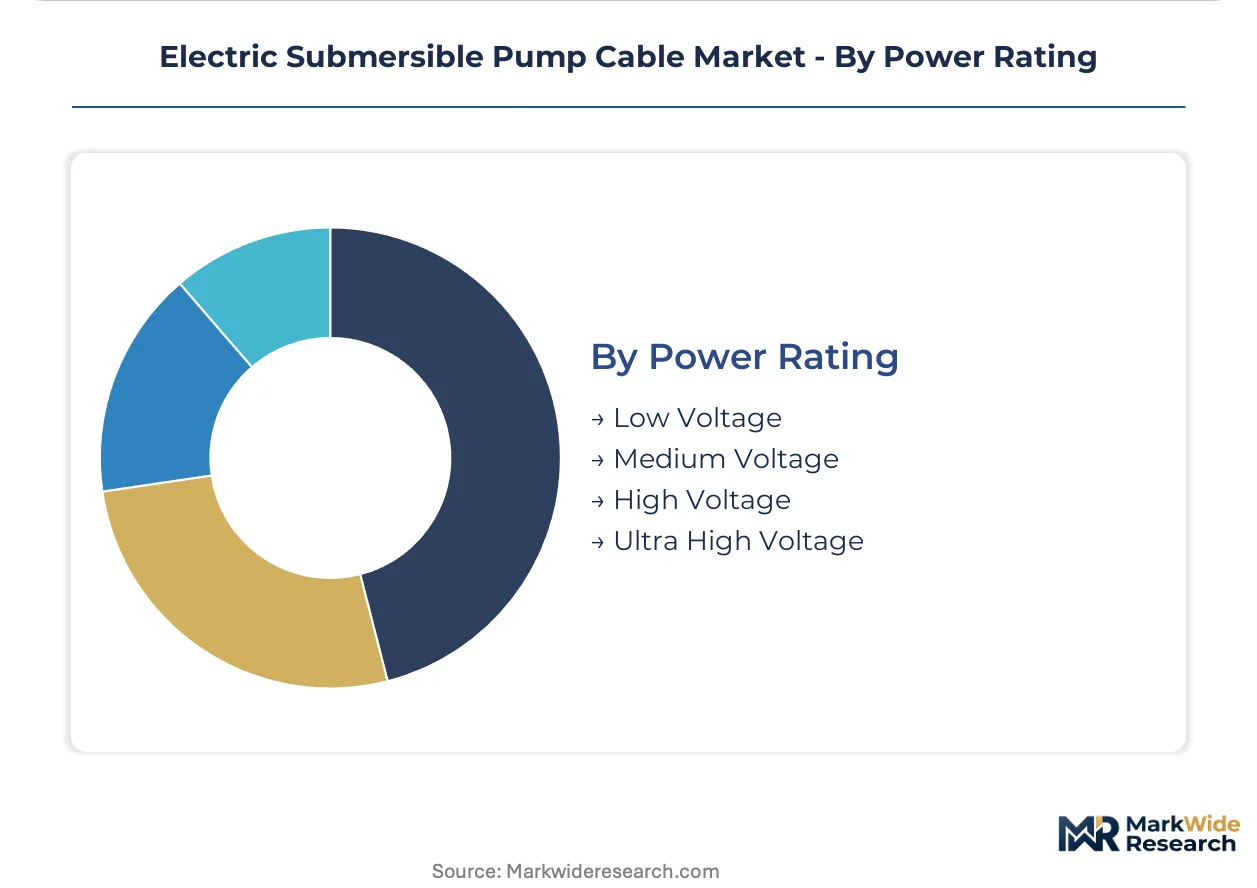
Volume distribution clusters in established voltage tiers while margin expansion concentrates in emerging high-capacity segments.
- Low Voltage:Ratings below 1 kV serve shallow conventional wells with limited horsepower requirements. Low voltage persists in stripper well populations across the US Mid-Continent and mature Middle East fields.
- Medium Voltage:1-5 kV ratings balance power delivery with insulation thickness constraints in horizontal laterals. Sinopec's Sichuan shale programs are specifying medium voltage for 2,500+ meter true vertical depth completions.
- High Voltage:5-10 kV systems enable single-cable power transmission to high-horsepower ESP motors. Schlumberger and Baker Hughes are qualifying high-voltage flat profiles for next-generation 1,500+ horsepower downhole systems.
- Ultra High Voltage:Ratings exceeding 10 kV address ultra-deep reservoirs and extended-reach laterals requiring minimal conductor cross-section. Ultra high voltage remains pre-commercial with IEC partial discharge testing protocols still under harmonization.
Medium voltage carries the dominant installation base; high voltage exhibits the steepest expansion trajectory as operators push deeper into unconventional targets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with US shale operators commanding volume discounts on flat-profile cable bundles, while Saudi Aramco's term contracts for high-horsepower systems sustain premium realizations for European compound manufacturers.
United States
Permian Basin producers are extending horizontal laterals beyond 15,000 feet, forcing cable fabricators to engineer tensile-resistant conductor geometries. OSHA surface equipment standards shape armoring specifications through motor control enclosure mandates. Midland-Odessa cable service yards are expanding inventory positions for multi-core flat configurations.
Saudi Arabia
Saudi Aramco's mature carbonate field redevelopment is generating concentrated demand for medium-voltage permanent installations. The national oil company's artificial lift expansion programs prioritize factory-integrated cable-motor assemblies. Dhahran-based procurement centers are qualifying new EPDM compound formulations for 232°C continuous operation.
China
Sinopec and PetroChina are scaling ESP deployment in Sichuan Basin shale formations, creating import substitution openings for qualified international suppliers. GB standards for extruded insulation thickness diverge from IEC protocols, extending certification timelines. Chengdu manufacturing clusters are developing domestic polypropylene compound capacity.
Germany
High-temperature insulation polymer production concentrates in German chemical corridors, creating single-source vulnerability for North American cable fabricators. REACH SVHC candidate list restrictions are triggering chlorinated flame retardant reformulation investments. Cologne-Ruhr compound specialists are advancing polyimide-based tape systems for 250°C rated installations.
Japan
Specialized EPDM and polypropylene formulation expertise concentrates among retiring polymer chemists at Japanese compound manufacturers. METI industrial standards influence partial discharge testing methodologies that diverge from API protocols. Osaka-Kobe chemical clusters are licensing thermal protection layer virtualization technologies to Permian Basin operators.
Electric Submersible Pump Cable Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in insulation compound and conductor manufacturing. The market exhibits tiered concentration with three to five integrated artificial lift providers controlling premium contract flow, while mid-scale cable fabricators compete on qualification speed and regional logistics. Strategic archetypes separate captive demand aggregators, compound-integrated manufacturers, and pure-play cable specialists. Competitive moves center on lease-versus-own contracting structures and backward integration into high-temperature polymer formulation.
Within the integrated service tier, Schlumberger anchors platform positioning through artificial lift bundling. Prysmian Group exemplifies compound-integrated manufacturing with in-house insulation grade production. Nexans occupies a position among specialized formulation providers rated for gas-lift corrosive environments.
| Leading Market Players |
|---|
| Prysmian Group |
| General Cable |
| Schlumberger |
| Southwire Company |
| Nexans |
| Marmon Group |
| Borets |
| Hitachi Metals |
| Weatherford International |
| Others |
Supply Flow & Price Mechanics
German chemical corridors concentrate high-temperature EPDM and polypropylene compound production, anchoring margin pools with insulation-grade suppliers who command premium positioning over North American cable fabricators facing single-source vulnerability. Copper conductor costs constitute the largest variable in finished cable economics, with London Metal Exchange volatility transmitting directly through to operator procurement budgets without full pass-through mechanisms.
Pricing Analysis
Configured-to-order pricing for API RP 11S4-qualified multi-core flat profiles commands spreads over standard round cable configurations due to factory termination complexity and extended qualification timelines. Three-tier pricing structure across premium, standard, and economy levels separates oxygen-free copper conductor systems from aluminum alternatives and commodity thermoplastic sheathing. Pricing pressure stems from Saudi Aramco term contract consolidation favoring bundled artificial lift procurement over discrete cable purchases. Permian Basin independents exhibit highest price sensitivity through lease-versus-own contracting preferences, while offshore operators in mature carbonate fields show lowest sensitivity due to workover economics prohibiting retrieval.
Supply Chain Analysis
Extended payment terms from artificial lift service providers are reshaping working capital requirements for compound manufacturers who must finance raw material positions ahead of cable fabricator demand. Geographic supply concentration centers on Germany, Japan, and China for specialized insulation polymers, with Chinese domestic polypropylene capacity expanding fastest. Raw material dependencies rest on copper cathode, ethylene propylene diene monomer feedstock, and chlorinated flame retardant precursors facing REACH SVHC restriction. Single-source vulnerability concentrates in German high-temperature tape systems for 250°C rated installations. Distribution runs through integrated service providers bundling cable replacement into performance-based lift contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating with Saudi Aramco and Sinopec procurement centralization, fragmenting the operator base into price-sensitive independents and term-contract national oil companies with divergent sourcing preferences.
For Market Incumbents: Harden compound-integrated manufacturing positions through captive EPDM formulation capacity in Germany and Japan to defend against REACH-driven material substitution cycles. Secure API RP 11S4 qualification speed advantages as IEC harmonization timelines extend competitor certification cycles. Prioritize lease-versus-own contracting infrastructure to capture operational expenditure shifts among Permian Basin shale operators. For New Entrants and Emerging Players: Build out domestic polypropylene compound capacity in Chengdu manufacturing clusters to serve Sinopec and PetroChina import substitution requirements in Sichuan Basin shale programs. Target temporary installation segments among US independents where parent-child well interference demands frequent cable reconfiguration. Lead with digital twin integration capabilities enabling condition-based replacement contracts displacing time-based maintenance schedules. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cable fabricators lacking backward integration into high-temperature polymer formulation. Long-term viability over the next decade hinges on insulation material virtualization technologies and qualification protocol harmonization completion. Watch for IEC-API partial discharge testing methodology convergence as inflection indicator for certification cycle compression and margin normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compound Manufacturing | Prysmian Group's captive EPDM production sustains margin control across 232°C insulation grades. |
| API RP 11S4 Qualification Investment | Enhanced partial discharge resistance mandates are compelling legacy cable inventory replacement cycles. |
| Digital Twin Platform Development | Downhole cable monitoring sensor convergence enables predictive analytics-driven replacement contracting. |
| Domestic Content Positioning | US Inflation Reduction Act tax credits are reshaping Permian Basin operator sourcing calculus. |
| Halogen-Free Formulation Transition | REACH SVHC restrictions are accelerating polypropylene-based insulation displacement of PVC-sheathed configurations. |
Methodological Framework
Operator-level perspectives from artificial lift service directors, ESP procurement managers at national oil companies, compound manufacturing R&D leads, and cable fabricator plant engineers anchored the qualitative base. Primary interview insights combined with secondary validation from API qualification protocol documentation, IEC standard harmonization timelines, ECHA REACH SVHC candidate list updates, and London Metal Exchange copper price series. Bottom-up field deployment estimates and top-down artificial lift capital expenditure triangulation established volume boundaries across the analysis window.
Scenario-bracketing framed conservative and expansion cases without year-specific milestones, modeling product type penetration shifts, power rating tier migration, and installation type preference evolution across the projection horizon. Segmentation dimensions spanned conductor geometry, insulation material grade, deployment permanence, and voltage capacity tier. CAGRs derived from installation base growth rates and replacement cycle compression factors, with horizontal lateral extension beyond 15,000 feet and high-horsepower ESP adoption serving as primary demand elasticity inputs.
Stress conditions across copper price volatility bands, REACH regulatory expansion scenarios, and IEC-API harmonization timeline delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding shale lateral extension rates and mature field artificial lift intensification. Macroeconomic commodity swings, unilateral regulatory acceleration, or breakthrough downhole power transmission technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Marine Switchboard Market
Electrical Power Equipment
Smart Electric Heater Market
Electrical Power Equipment
Global Explosion-Proof Electric Motors and Actuators Market
Electrical Power Equipment
Residential Air Insulated Power Distribution Component Market
Electrical Power Equipment
Gas Water Heater Market
Electrical Power Equipment
Transformer Oil Testers Market
Electrical Power Equipment
ESE Lightning Rod Market
Electrical Power Equipment
AC-DC Controller Market
Electrical Power Equipment
MV Protection Relay Market
Electrical Power Equipment
Battery Charger Market
Electrical Power Equipment
Packaged Substation Market
Electrical Power Equipment
Power Line Filters Market
Electrical Power Equipment
North America Surge Arresters Market
Electrical Power Equipment
Power Line Carrier System Market
Electrical Power Equipment
Taiwan Electric Power Equipment Market
Electrical Power Equipment
Containerized Substation Market