
 Overhead Power Cables Market | 2026-2036
Overhead Power Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Overhead Power Cables Market Outlook
China is reshaping overhead power cable supply dynamics through massive ultra-high voltage corridor builds and domestic conductor capacity expansion. Prysmian Group leverages its European manufacturing footprint and submarine cable expertise to anchor premium conductor segments across Mediterranean utilities. Sumitomo Electric Industries Ltd. competes through advanced aluminum-zirconium alloy technology and dominant positioning in Japan's earthquake-resistant grid infrastructure. Nexans S.A. specializes in fire-resistant and low-sag conductor designs for dense European transmission corridors.
Overhead power cables are stranded conductor assemblies, typically aluminum or copper cores reinforced with steel or composite materials, engineered to transmit electrical energy across aerial suspension systems at specified mechanical loads and thermal ratings. ACSR conductors dominate installed base volumes due to proven cost-efficiency in long-span transmission, while AAAC variants gain share in corrosion-prone coastal corridors where steel core degradation accelerates replacement cycles. High voltage and extra high voltage classifications command concentrated margin pools as utilities prioritize reliability in backbone grid segments over low voltage distribution commodity procurement.
FERC interconnection standards in the United States, EU Green Deal grid modernization mandates under the European Commission, and BIS conductor specifications in India collectively tighten product certification requirements and reshape procurement qualification thresholds. China's GB standards and MIIT energy efficiency directives further compress allowable electrical losses in new conductor installations. Stakeholders must monitor evolving national content rules and carbon border adjustment mechanisms that threaten to fragment supplier eligibility across formerly open procurement markets.
Market Dynamics
Grid modernization mandates and renewable energy integration requirements are compressing conductor replacement cycles while tightening performance specifications across transmission utilities worldwide.
Growth Catalysts
- EU Green Deal grid mandates:Backbone transmission corridors require reconductoring with low-sag designs to accommodate higher renewable penetration across continental interconnectors.
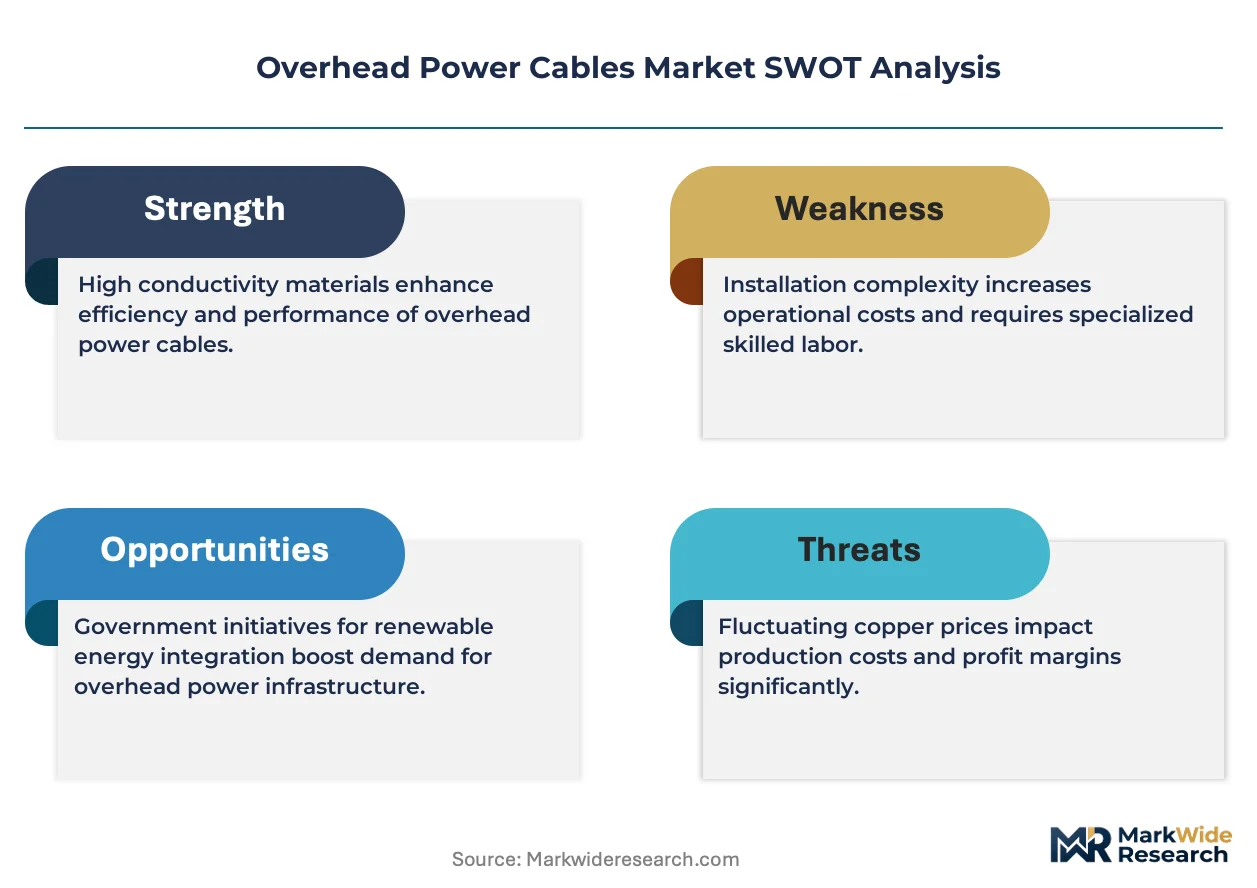
- Aluminum-zirconium alloys:Superior thermal ratings enable utilities to increase line capacity without tower replacement, accelerating adoption in constrained rights-of-way.
- India rural electrification:State distribution companies are procuring AAAC and ACSR conductors at scale to extend 33kV networks into underserved agricultural zones.
Market Restraints
- Aluminum price volatility:LME aluminum fluctuations compress fabrication margins and complicate long-term utility procurement contracting.
- Steel core supply concentration:Galvanized steel wire production clusters in China, creating single-source dependency risks for ACSR manufacturers elsewhere.
- Right-of-way acquisition delays:Environmental permitting timelines for new transmission corridors extend project completion horizons by 3-7 years in most jurisdictions.
Strategic Opportunities
- Brazil Amazon grid extension:Remote hydroelectric integration projects demand specialized corrosion-resistant conductors for humid tropical environments.
- Carbon border adjustment mechanisms:EU CBAM implementation favors low-carbon aluminum smelters, creating first-mover advantage for European conductor producers.
- Drone-assisted line inspection:Predictive maintenance services bundled with conductor supply contracts create recurring revenue streams beyond hardware margins.
Industry Challenges
- High-voltage testing certification:Laboratory capacity constraints delay type-approval for new conductor designs, bottlenecking product launches.
- Composite core integration:Manufacturing scale-up for carbon fiber reinforced conductors requires capital-intensive autoclave investments that strain mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Overhead Power Cables Market |
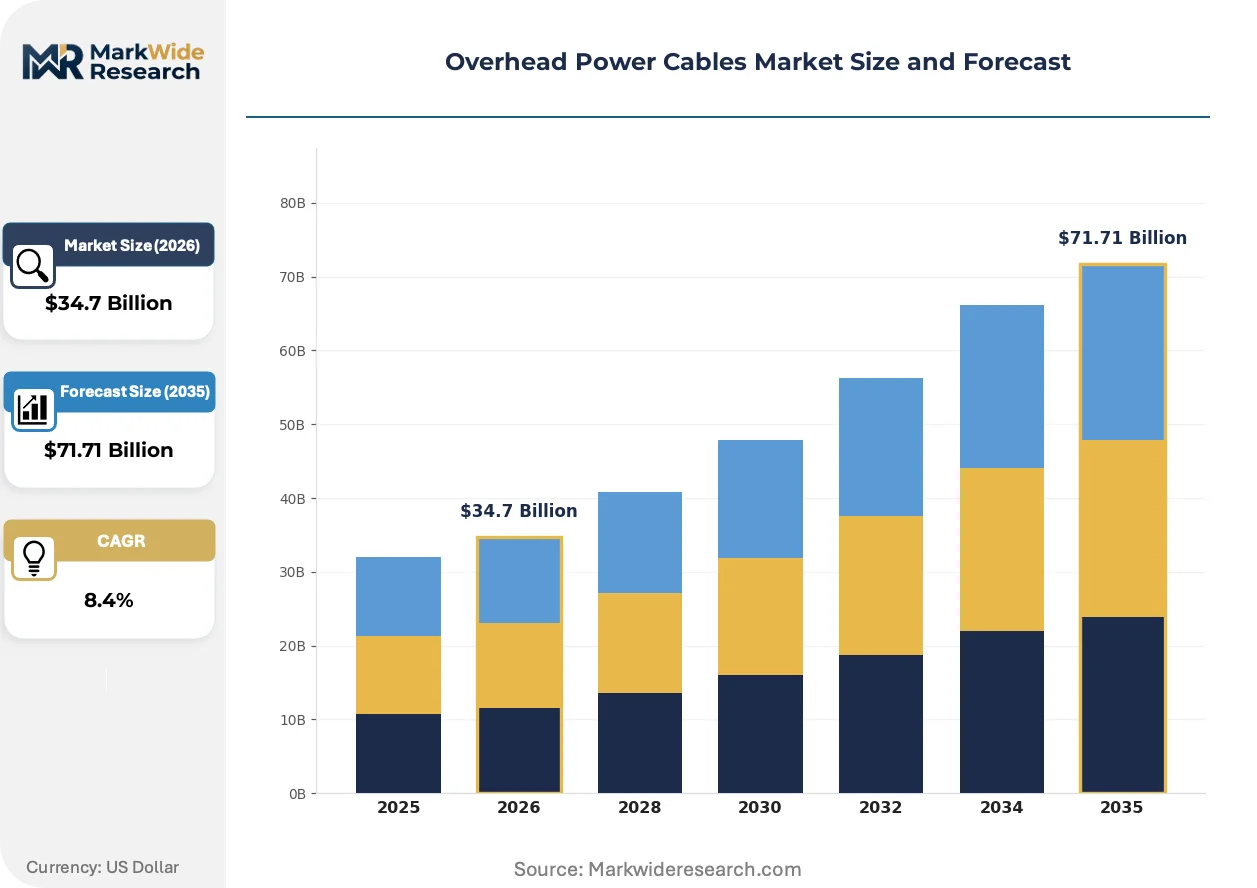
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $71.71 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ACSR, AAAC, AAC, Conductors Material: Aluminum, Copper, Steel, Composite Voltage Level: Low Voltage, Medium Voltage, High Voltage, Extra High Voltage End User: Utilities, Industrial, Commercial, Residential |
| Companies Covered | Sumitomo Electric Industries Ltd., LS Cable & System Ltd., Prysmian Group, General Cable Corporation, NKT A/S, Nexans S.A., Furukawa Electric Co. Ltd., Polycab India Ltd., Southwire Company LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Overhead Power Cables Market Strategic Shifts
Material science advances and digital grid technologies are redefining conductor performance benchmarks while reshaping how utilities evaluate lifecycle costs against upfront procurement expenditure.
High-temperature low-sag (HTLS) conductors incorporating composite cores are migrating from pilot installations to mainstream procurement specifications. European transmission system operators now mandate thermal ratings exceeding 150°C for new cross-border interconnectors. This technology is compressing the total cost of ownership advantage previously held by conventional ACSR designs.
China's MIIT energy efficiency directives and updated GB standards are mandating maximum electrical loss thresholds for new conductor installations. Domestic manufacturers must certify reduced resistivity specifications to qualify for state grid tenders. High-voltage corridor projects in western provinces face procurement disqualification for non-compliant suppliers.
Performance-based contracting is displacing unit-price procurement across Scandinavian utilities. Contractors now guarantee conductor thermal performance over 30-year service lives, with penalties for sag exceedance or corrosion failure. This model concentrates risk with manufacturers while compressing supplier margins in Norway and Sweden.
Overhead Power Cables Market Segmentation
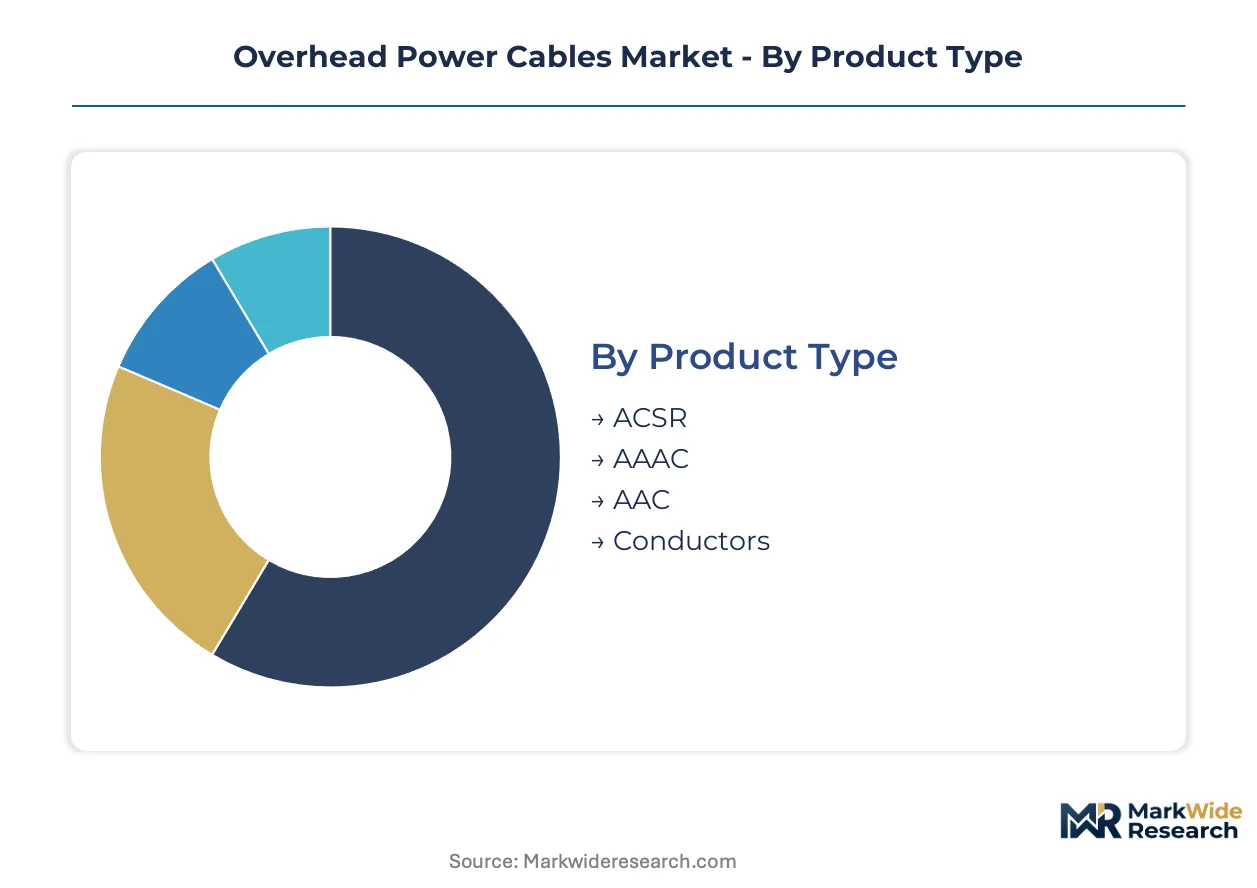
Overhead power cable procurement varies sharply by application environment, material economics, and grid hierarchy tier. Understanding segment boundaries clarifies where manufacturers compete on specification compliance versus commodity scale.
Product Type:
Stranded conductor architectures span from legacy steel-reinforced designs to advanced alloy formulations, each matching distinct mechanical load and corrosion exposure profiles.
- ACSR:Aluminum conductor steel-reinforced construction pairs high conductivity outer strands with galvanized steel core wires for tensile strength. India's state distribution companies procure ACSR at scale for rural 33kV extensions where cost efficiency outweighs weight penalties. Established volume favors ACSR; emerging adoption favors AAAC.
- AAAC:All-aluminum alloy conductors eliminate steel core corrosion risk through homogeneous aluminum-zirconium or aluminum-magnesium-silicon construction. Coastal utilities in Brazil's Amazon corridor specify AAAC for humid tropical environments where galvanized steel degradation accelerates replacement cycles. Aluminum-zirconium variants enable 150°C thermal ratings without tower modifications.
- AAC:All-aluminum conductors serve short-span distribution networks with moderate mechanical loading requirements where steel reinforcement adds unnecessary cost.
- Conductors:Specialty composite-core and high-temperature low-sag designs address constrained rights-of-way requiring capacity upgrades without structural expansion.
Volume concentration tilts toward established ACSR specifications; premium thermal performance drives AAAC expansion in replacement corridors.
Material:
Raw material selection governs conductivity, tensile performance, and lifecycle durability across aerial transmission systems.
- Aluminum:Primary conductor metal offering conductivity-to-weight ratio superiority over copper for long-span applications. LME price volatility complicates long-term procurement contracting for utilities and fabricators alike. Aluminum dominates installed conductor mass globally.
- Copper:Reserved for specialized low-voltage distribution segments and earthing applications where oxidation resistance justifies density penalties.
- Steel:Galvanized wire cores provide tensile reinforcement in ACSR constructions. Production concentration in China creates single-source dependency risks for manufacturers elsewhere.
- Composite:Carbon fiber and glass fiber reinforced polymer cores enable HTLS conductor thermal ratings exceeding conventional designs. Autoclave manufacturing scale-up demands capital-intensive investments that strain mid-tier suppliers.
Aluminum maintains cost-driven dominance; composite cores climb fastest in premium reconductoring specifications.
Voltage Level:
Grid hierarchy tiers separate commodity distribution procurement from reliability-critical backbone transmission investments.
- Low Voltage:Distribution networks below 1kV serving residential and small commercial connections. Procurement emphasizes unit cost minimization over advanced material specifications.
- Medium Voltage:Sub-transmission and primary distribution between 1kV and 69kV. India's rural electrification drives concentrated conductor demand in this tier.
- High Voltage:Backbone transmission corridors from 69kV to 230kV requiring reconductoring with low-sag designs under EU Green Deal mandates. European system operators prioritize reliability certification over commodity pricing.
- Extra High Voltage:Ultra-high voltage corridors exceeding 230kV including China's western province builds and continental interconnectors. MIIT energy efficiency directives mandate maximum loss thresholds for qualification.
High and extra high voltage segments command concentrated margin pools; low voltage procurement remains price-commoditized.
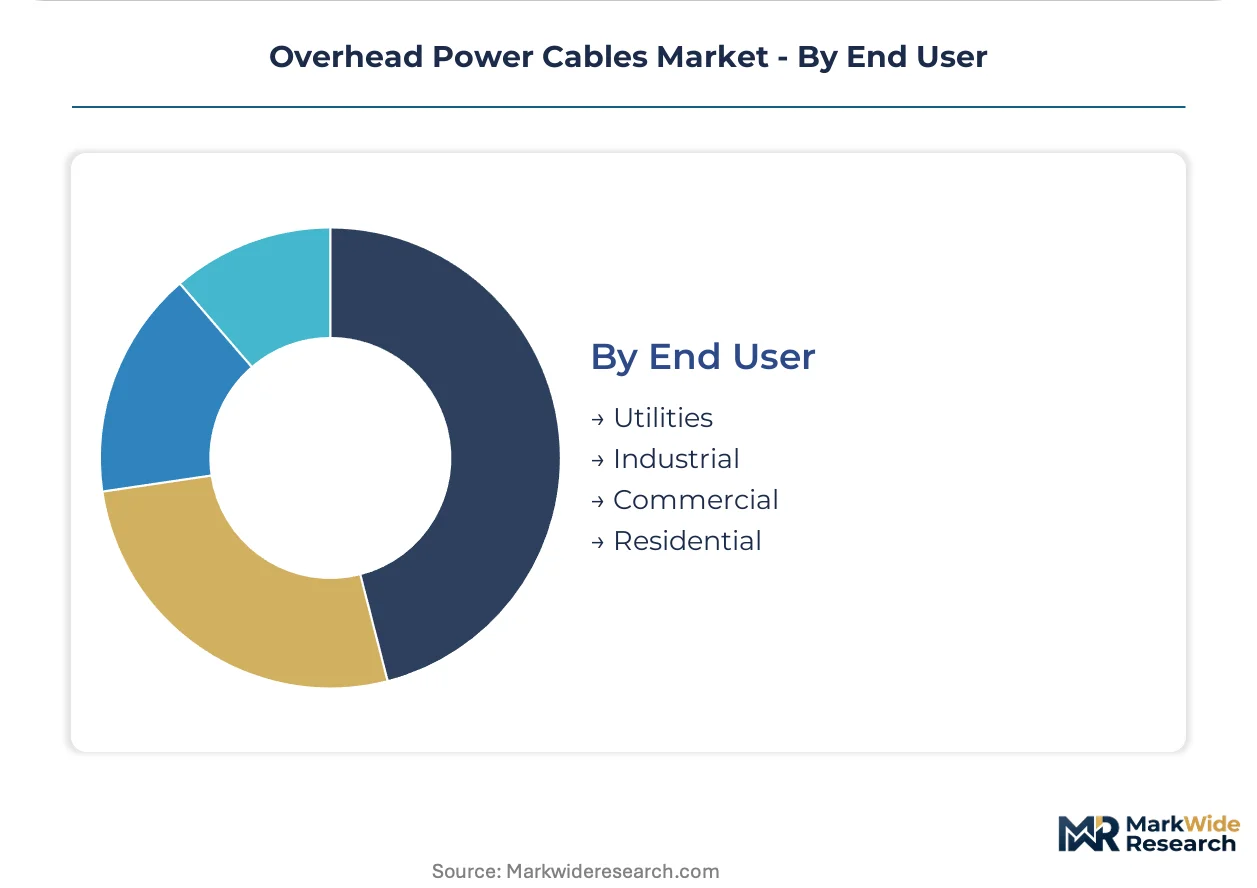
End User:
Customer type shapes specification stringency, contract structure, and lifecycle service expectations.
- Utilities:Transmission and distribution system operators account for dominant procurement volumes. Scandinavian utilities are displacing unit-price contracting with performance-based agreements guaranteeing 30-year thermal ratings.
- Industrial:Mining, petrochemical, and heavy manufacturing facilities requiring dedicated feeder lines with customized corrosion and load specifications.
- Commercial:Data centers, logistics hubs, and commercial developments procuring medium-voltage connections with accelerated installation timelines.
- Residential:Individual property connections and small-scale development projects with standardized low-voltage conductor requirements.
Utility procurement dominates volume scale; industrial specifications drive margin premiums for specialized designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Galvanized steel wire production clusters in China, creating single-source dependency risks for ACSR manufacturers elsewhere. Fabricators in India and Brazil compete through alloy innovation and coastal corrosion specialization. European and North American utilities drive premium reconductoring specifications.
China
Ultra-high voltage corridor builds in western provinces consume massive conductor volumes under MIIT energy efficiency directives. GB standards mandate maximum electrical loss thresholds for state grid tender qualification. Xining and Lanzhou anchor manufacturing clusters where domestic fabricators expand capacity to serve 800kV+ transmission projects.
India
Rural electrification and smart grid investments accelerate AAAC and ACSR procurement cycles across state distribution companies. BIS conductor specifications tighten material purity and sag-tension requirements for 33kV network extensions. Gujarat and Maharashtra host concentrated fabrication capacity serving agricultural zone electrification programs.
United States
FERC interconnection standards drive reconductoring investments across aging transmission infrastructure. Backbone corridor upgrades prioritize reliability certification over commodity pricing in competitive wholesale markets. Texas and California utilities lead procurement for renewable integration across constrained rights-of-way.
Germany
EU Green Deal grid modernization mandates require low-sag conductor designs for cross-border interconnectors. ECHA REACH compliance and carbon border adjustment mechanisms reshape supplier eligibility for state tenders. Industrial clusters in North Rhine-Westphalia fabricate fire-resistant specifications for dense European transmission corridors.
Brazil
Amazon grid extension projects demand specialized corrosion-resistant conductors for humid tropical environments. Remote hydroelectric integration drives AAAC specification for steel-free construction in coastal zones. São Paulo-based fabricators serve southeastern industrial load centers while northern corridors expand into rainforest territories.
Overhead Power Cables Market Competitive Environment
Integrated conglomerates and specialized cable fabricators split the market between scale-driven commodity supply and premium thermal performance segments. The vendor base concentrates around three strategic archetypes: Japanese industrial conglomerates with alloy metallurgy expertise, European specialists in fire-resistant and low-sag designs, and emerging Asian fabricators capturing rural electrification volumes. Competitive moves center on backward integration into aluminum smelting and strategic partnerships for composite core technology licensing.
Among Japanese industrial conglomerates, Sumitomo Electric Industries Ltd. and Furukawa Electric Co. Ltd. exemplify metallurgy-forward positioning through advanced aluminum-zirconium alloy capabilities. European specialists anchor premium segments, with Prysmian Group representing Mediterranean utility focus and Nexans S.A. occupying a position in fire-resistant transmission corridor specifications. Polycab India Ltd. sits within the emerging market fabricator archetype, capturing scale advantages in rural distribution procurement cycles.
| Leading Market Players |
|---|
| Sumitomo Electric Industries Ltd. |
| LS Cable & System Ltd. |
| Prysmian Group |
| General Cable Corporation |
| NKT A/S |
| Nexans S.A. |
| Furukawa Electric Co. Ltd. |
| Polycab India Ltd. |
| Southwire Company LLC |
| Others |
Value Chain & Pricing Dynamics
Xining and Lanzhou anchor manufacturing clusters where domestic fabricators expand capacity to serve 800kV+ transmission projects, compressing pricing power for imported conductors across Asian procurement markets. LME aluminum volatility feeds directly into contract renegotiation cycles, forcing utilities to accept shorter-term pricing structures or absorb margin risk.
Pricing Analysis
MIIT energy efficiency directives dictate the pricing tier structure across Chinese state grid tenders, separating certified low-loss suppliers from commodity fabricators. Three-tier pricing structure across premium HTLS composite-core, standard AAAC alloy, and economy ACSR specifications reflects certification grade and thermal performance. Cost compression in economy ACSR tiers is intensifying because galvanized steel core supply concentrates in Chinese mills. State distribution companies in India exhibit highest price sensitivity; European transmission system operators prioritize reliability certification over unit cost minimization.
Supply Chain Analysis
Primary aluminum smelting concentrates in China, India, and Russia, with secondary fabrication clustering in Gujarat, Maharashtra, and São Paulo. Raw material procurement draws from LME-traded aluminum ingot, galvanized steel wire from Hebei province mills, and carbon fiber composite cores from Japanese and European specialty suppliers. Single-source vulnerability runs through Chinese steel core production for ACSR manufacturers elsewhere. Distribution runs through utility tender processes, EPC contractor specifications, and industrial direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drone-assisted line inspection and predictive maintenance services bundled with conductor supply contracts create recurring revenue streams expanding faster than hardware margins across utility procurement cycles.
For Market Incumbents: Pre-empt composite core technology licensing bottlenecks by securing exclusive partnerships with carbon fiber reinforced polymer suppliers before mid-tier competitors achieve autoclave scale. Backward integration into aluminum-zirconium alloy smelting defends margin position against LME volatility and Chinese domestic capacity expansion. Certification investment in EU CBAM compliance creates procurement eligibility moats as carbon border adjustment mechanisms reshape supplier qualification. For New Entrants and Emerging Players: Brazil's Amazon grid extension corridors offer underpenetrated white-space for corrosion-resistant AAAC specifications where established European and Japanese suppliers maintain limited presence. India's rural electrification programs present volume scale entry points through state distribution company tenders with lower technical qualification thresholds than ultra-high voltage corridors. Target drone-assisted inspection service bundling as differentiated go-to-market angle against commodity hardware competitors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors HTLS composite-core specialists with proven thermal rating certifications and utility performance guarantees over legacy ACSR volume players. Long-term viability hinges on reconductoring cycle duration and renewable integration mandates across European and North American backbone grids. Watch EU CBAM implementation pace as inflection indicator for low-carbon aluminum smelter valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Smelting | Captures margin from LME volatility and secures MIIT-compliant low-loss feedstock for state grid tenders. |
| Composite Core Technology Licensing | Accelerates HTLS manufacturing scale without capital-intensive autoclave investments straining balance sheets. |
| Drone-Assisted Inspection Service Bundling | Creates recurring revenue streams beyond hardware margins across Scandinavian performance-based contracting markets. |
| EU CBAM Compliance Certification | Maintains procurement eligibility as carbon border adjustment mechanisms reshape supplier qualification thresholds. |
| Amazon Corridor Corrosion-Resistant Product Line | Addresses humid tropical degradation risks where steel-free AAAC construction accelerates replacement cycles. |
Study Parameters
The analysis maps ACSR, AAAC, AAC, and HTLS composite-core conductor segments, each validated through utility procurement officers, EPC contractor specification engineers, and aluminum smelter technical directors. Primary interviews with transmission system operators and distribution company planners combined with secondary validation from IEC standards documentation, BIS conductor specifications, MIIT energy efficiency directives, and FERC interconnection filings. Bottom-up volume modeling triangulates against top-down grid investment forecasts across the analysis window.
Assumptions held fixed include regulatory compliance thresholds under EU Green Deal mandates and MIIT loss reduction directives, while aluminum price trajectories and right-of-way permitting timelines were varied across sensitivity scenarios. Segmentation dimensions modeled span product type, material composition, voltage tier, and end-user category. CAGRs derive from utility capital expenditure pipelines and reconductoring cycle compression trends, with renewable integration targets and grid modernization spend as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-owned fabricators or breakthrough composite core cost reductions would shift outcomes beyond modeled ranges. Cross-checking against IEA grid investment benchmarks and national transmission operator disclosed procurement pipelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Europe Gas Insulated Switchgear Market
Electrical Power Equipment
Asia Pacific Gas Insulated Switchgear Market
Electrical Power Equipment
Frameless Brushless DC Motors Market
Electrical Power Equipment
Residential Air Insulated Power Distribution Component Market
Electrical Power Equipment
Switching Residential Voltage Regulator Market
Electrical Power Equipment
North America Air-Insulated Switchgear Market
Electrical Power Equipment
SF6 Gas Circuit Breaker Market
Electrical Power Equipment
Asia-Pacific Air-Insulated Switchgear Market
Electrical Power Equipment
India Instrument Transformer Market
Electrical Power Equipment
Industrial Power Supply Market
Electrical Power Equipment
High Voltage Ionising Air Gun Market
Electrical Power Equipment
Europe Electric Space Heaters Market
Electrical Power Equipment
AC Drives Market
Electrical Power Equipment
Electric Insulator Market
Electrical Power Equipment
Storage Water Heater Market
Electrical Power Equipment
Global Low Voltage Electric Drives Market