
 Global Electric Power Substation Automation Market | 2026-2036
Global Electric Power Substation Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electric Power Substation Automation Market Intelligence
Utility procurement is decoupling from traditional single-vendor frameworks as municipal power departments and independent system operators diversify supplier portfolios. ABB leverages its IEC 61850 protocol leadership to anchor premium automation contracts across European transmission networks. Siemens competes through integrated hardware-software platforms that sustain long-term service revenue streams.
Electric power substation automation encompasses the deployment of intelligent electronic devices, remote terminal units, and communication gateways within high-voltage substations to execute protection, control, monitoring, and data acquisition functions with sub-cycle response times. These systems enable real-time situational awareness for grid operators managing renewable intermittency and bi-directional power flows. Intelligent electronic devices dominate current revenue pools due to their role in merging unit protection and process bus architectures. Supervisory control and data acquisition systems represent the fastest-expanding automation type as utilities prioritize centralized visibility across geographically dispersed assets.
The Federal Energy Regulatory Commission in the United States mandates critical infrastructure protection standards that shape cybersecurity requirements for substation communication networks. China's National Energy Administration enforces GB standards for smart grid equipment interoperability, while India's Central Electricity Authority specifies communication protocol compliance for national grid modernization. Stakeholders must monitor evolving cybersecurity certification regimes and protocol convergence timelines to align product roadmaps with procurement specifications.
Market Dynamics
Transmission operators are accelerating IEC 61850 retrofit programs to replace legacy serial communication with Ethernet-based process bus architectures, forcing incumbent vendors to reengineer hardware platforms and service delivery models around interoperability mandates rather than proprietary lock-in.
Growth Catalysts
- China's National Energy Administration mandates:Grid reliability standards require smart grid equipment interoperability across eastern coastal provinces, compelling state grid corporations to automate substations with IEC 61850-compliant intelligent electronic devices.
- Renewable intermittency management:Bi-directional power flows from distributed solar and wind installations demand sub-cycle protection responses that only modern substation automation architectures can deliver.
- India's western industrial corridors:Central Electricity Authority procurement specifications for national grid modernization are compressing vendor qualification timelines and accelerating deployment of supervisory control and data acquisition systems.
Market Restraints
- Semiconductor supply concentration:Specialized analog chips for protective relaying concentrate fabrication in Taiwan and South Korea, exposing automation vendors to geopolitical disruption and allocation constraints.
- Copper and rare earth input volatility:Intelligent electronic device manufacturing depends on dysprosium and terbium for high-performance magnetics, with prices fluctuating based on Chinese export quota policies.
- Cybersecurity certification friction:The United States Federal Energy Regulatory Commission's critical infrastructure protection standards impose multi-year compliance timelines that delay product launches and inflate engineering overhead.
Strategic Opportunities
- Brazil's transmission expansion:ANEEL's grid modernization programs create procurement windows for IEC 61850-integrated automation suites in the Southeast and Northeast transmission corridors.
- Digital twin convergence:Real-time physics simulation combined with substation automation data streams enables predictive maintenance contracts that extend vendor revenue cycles beyond hardware sales.
- Edge computing distribution:Containerized analytics deployed within substation gateways reduces latency for fault location applications, opening subscription-based software revenue in European transmission networks.
Industry Challenges
- IEC 61850 engineering expertise scarcity:Substation configuration language programming and system integration testing require specialized technicians that utilities and vendors struggle to recruit and retain.
- Legacy protocol migration complexity:Thousands of operational substations run DNP3 and IEC 60870-5-101, forcing phased retrofits that risk service continuity during cutover windows.
- Multi-vendor interoperability testing:Certification gaps between manufacturer implementations of process bus sampling values create integration failures that delay project commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electric Power Substation Automation Market |
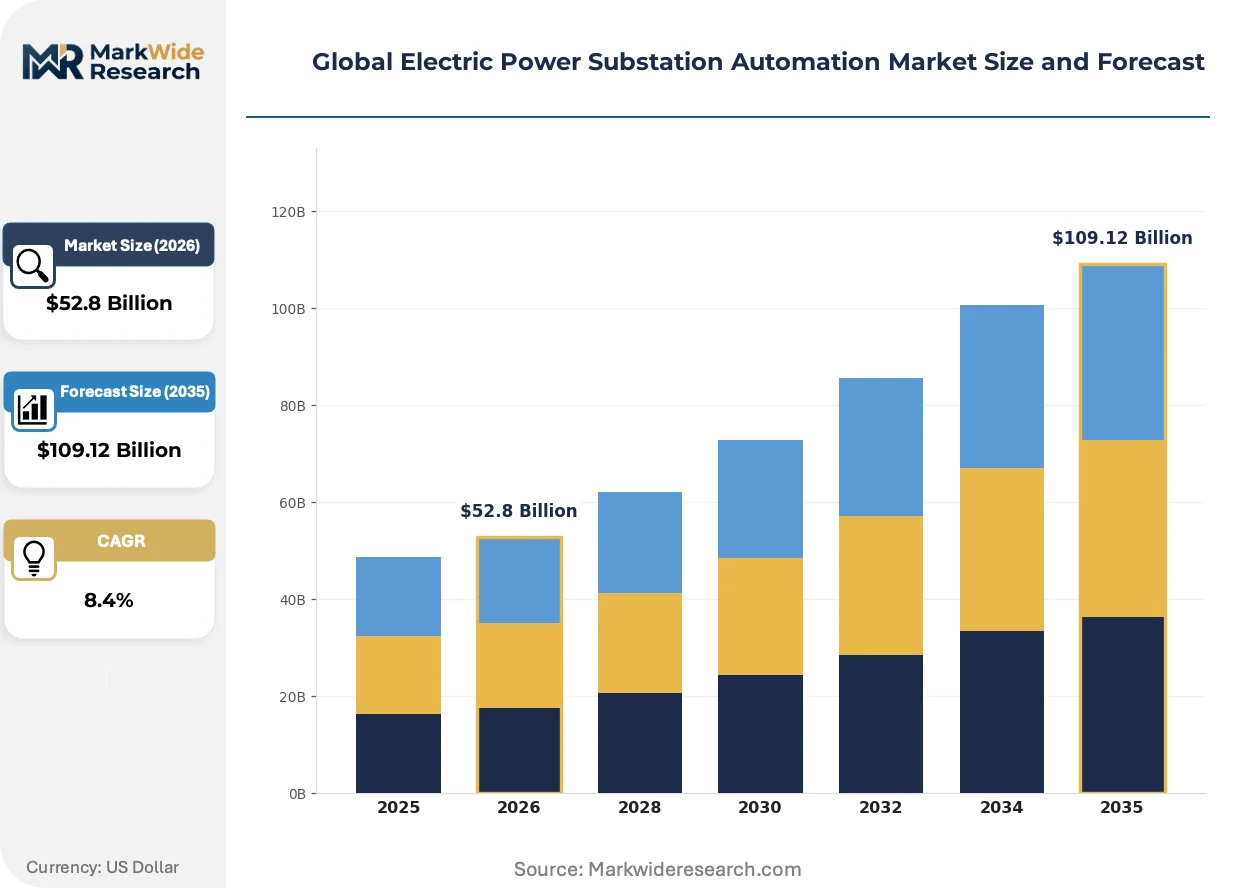
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $109.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Automation Type: Remote Terminal Units, Intelligent Electronic Devices, Supervisory Control & Data Acquisition, Distributed Control Systems Technology: IEC 61850, DNP3, Modbus, Profibus, OPC Application: Grid Management, Load Balancing, Fault Detection, Energy Management Systems End User: Electric Utilities, Transmission Operators, Municipal Power Departments, Independent System Operators |
| Companies Covered | General Electric, Eaton, ABB, Mitsubishi Electric, Schweitzer Engineering Laboratories, Siemens, Hitachi Energy, Ingeteam, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electric Power Substation Automation Market Strategic Shifts & Innovations
Substation automation is converging around software-defined protection and centralized analytics platforms that decouple hardware refresh cycles from functional upgrades, compressing traditional seven-year replacement timelines.
Time-sensitive networking is integrating deterministic Ethernet transport into substation process bus architectures, replacing copper-based hardwired trip circuits with synchronized sampled value streams. European transmission system operators in Germany and France are piloting these architectures for 400kV substation greenfield projects. The technology is integrating protection, measurement, and control functions onto unified computing platforms that reduce panel space and copper consumption by over sixty percent.
The European Union's Cyber Resilience Act imposes mandatory security update obligations and vulnerability disclosure requirements on connected industrial equipment including substation gateways and remote terminal units. Manufacturers must now maintain software support lifecycles exceeding fifteen years for deployed automation systems. European vendors are responding by restructuring engineering organizations around product security incident response teams and automated patch distribution infrastructure.
Utility engineering departments are unbundling hardware procurement from long-term service agreements, compressing vendor selection criteria toward interoperability certification and lifecycle cost transparency. Municipal power departments in Japan and South Korea are leading this transition, favoring multi-vendor panels over single-source automation suites. This pattern is most visible in Tokyo and Seoul metropolitan grid expansions, where independent system operators mandate protocol conformance testing before final acceptance.
Global Electric Power Substation Automation Market Segmentation
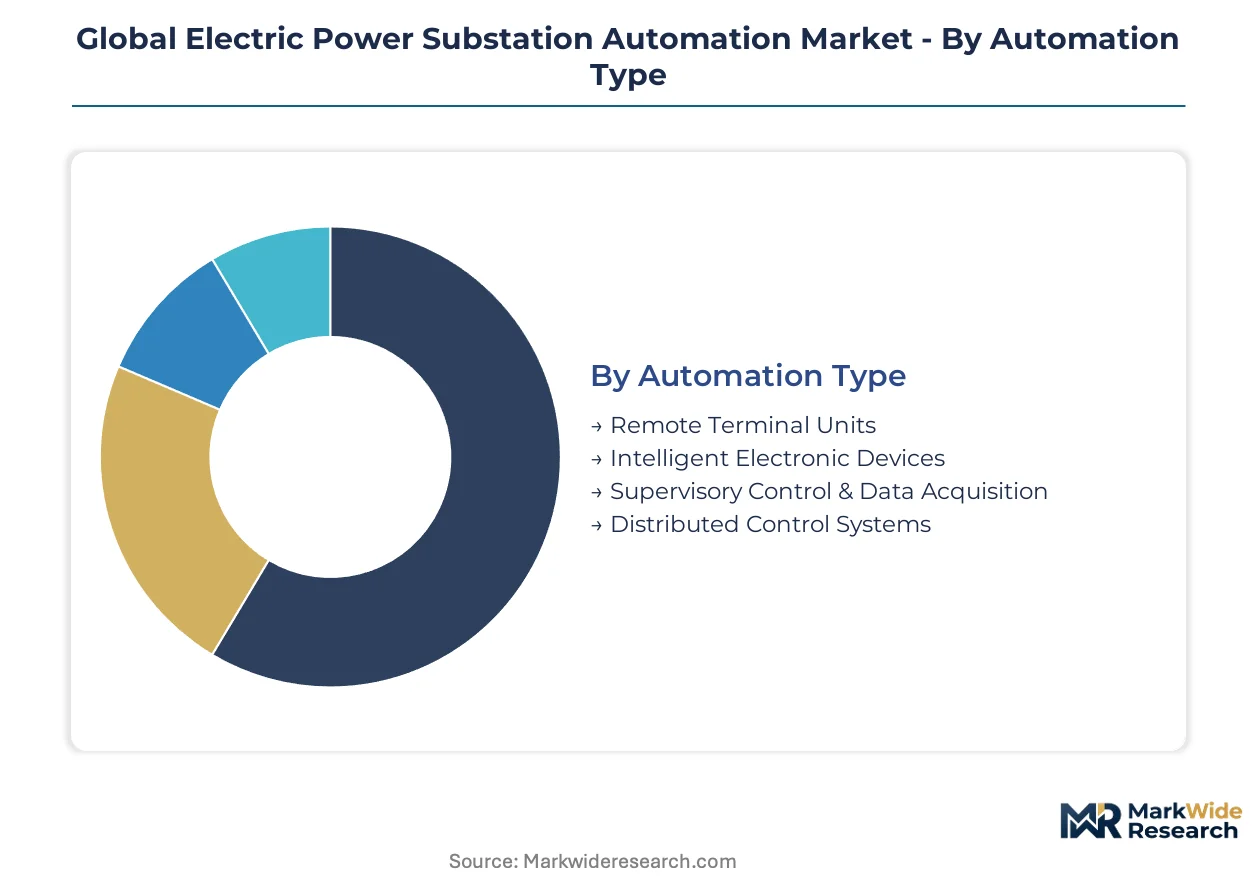
Substation automation procurement varies sharply by technical complexity and integration depth. Capital allocation decisions hinge on whether utilities prioritize hardware refresh cycles, protocol migration timelines, or centralized software platforms.
Automation Type:
Capital intensity peaks with intelligent electronic devices and distributed control systems, where specialized protective relaying and redundant computing architectures drive per-unit costs above simpler telemetry hardware.
- Intelligent Electronic Devices:These units merge protection, measurement, and control functions through embedded multi-core processors executing sub-cycle fault algorithms. Demand concentrates in China's eastern coastal provinces where State Grid Corporation mandates IEC 61850 process bus architectures for new 500kV substations.
- Supervisory Control & Data Acquisition:Centralized visibility platforms aggregate telemetry from geographically dispersed assets through redundant communication hierarchies. India's western industrial corridors are compressing deployment timelines as Central Electricity Authority procurement specifications prioritize SCADA integration for national grid modernization.
- Remote Terminal Units:Ruggedized data concentrators bridge legacy field equipment to modern communication backbones.
- Distributed Control Systems:Redundant controller networks manage complex substation bay interlocking and automated switching sequences.
Intelligent electronic devices absorb the bulk of installed capacity; supervisory control and data acquisition is expanding most quickly.
Technology:
Protocol selection determines interoperability certification costs and long-term vendor lock-in exposure, with utilities weighing migration complexity against functional capabilities.
- IEC 61850:This Ethernet-based standard enables sampled value process buses and substation configuration language engineering, eliminating copper hardwiring. Transmission operators across Germany and France are piloting 400kV greenfield implementations that reduce panel space consumption by over sixty percent.
- DNP3:Serial and TCP/IP variants dominate North American utility telemetry, with Secure Authentication extensions addressing FERC critical infrastructure protection mandates for encrypted command pathways.
- Modbus:Simple register-based protocol persists in retrofit applications where legacy device compatibility outweighs advanced functionality requirements.
- Profibus:Fieldbus architecture sees residual deployment in European industrial substations with process control integration needs.
- OPC:Unified architecture standard facilitates horizontal data exchange between substation gateways and enterprise IT systems.
IEC 61850 commands the steepest expansion trajectory as regulatory mandates displace proprietary protocols; DNP3 retains the largest installed base in legacy infrastructure.
Application:
Functional priorities shift with grid modernization maturity, from basic telemetry visibility toward predictive analytics and autonomous response capabilities.
- Grid Management:Real-time topology processing and state estimation algorithms enable dynamic stability control across interconnected transmission networks. Municipal power departments in Tokyo and Seoul metropolitan areas are unbundling hardware procurement from service agreements to prioritize interoperability-certified grid management platforms.
- Fault Detection:Traveling wave and impedance-based location algorithms reduce outage duration through sub-cycle isolation and automatic restoration sequencing.
- Load Balancing:Automated tap changer and capacitor bank coordination manages voltage profiles amid renewable intermittency.
- Energy Management Systems:Economic dispatch integration optimizes generation scheduling and congestion management across market boundaries.
Grid management absorbs the bulk of installed capacity; fault detection is gaining share fastest as reliability metrics tighten.
End User:
Procurement authority fragmentation creates divergent vendor engagement models, from centralized national tenders to municipal technical specifications.
- Transmission Operators:These entities manage high-voltage backbone infrastructure above 132kV, specifying redundancy requirements and cybersecurity certification regimes. China's National Energy Administration grid reliability mandates are compelling state grid corporations to accelerate automation procurement across provincial transmission networks.
- Electric Utilities:Vertically integrated generation-transmission-distribution entities balance standardization against legacy system preservation.
- Municipal Power Departments:City-owned distributors in Japan and South Korea are mandating multi-vendor panels and protocol conformance testing before final acceptance.
- Independent System Operators:Regional grid coordinators prioritize wide-area situational awareness and market interface standardization.
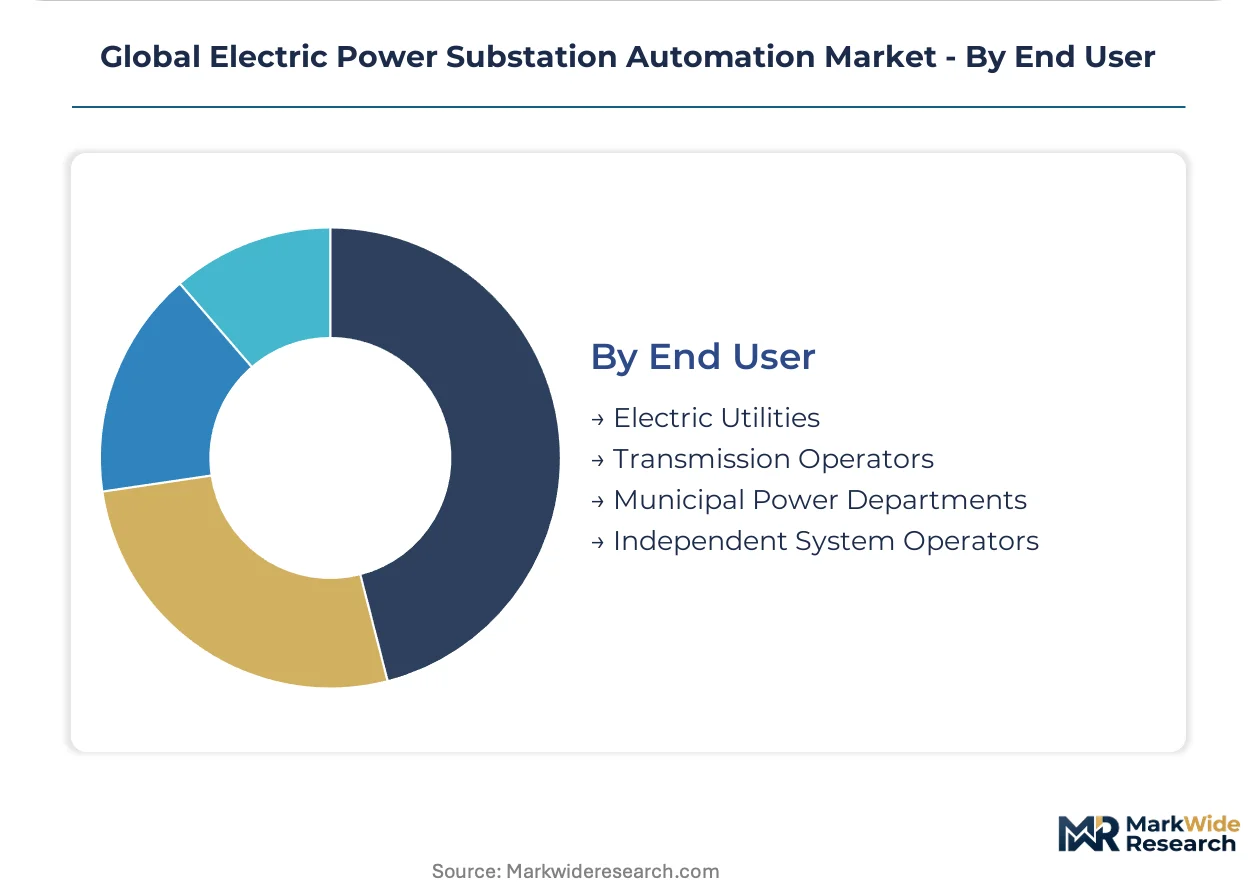
Transmission operators absorb the bulk of installed capacity; municipal power departments are climbing the fastest as decentralization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the dominant share of substation automation procurement, with State Grid Corporation driving IEC 61850-compliant deployments across 500kV transmission infrastructure. India's western industrial corridors and Germany's renewable integration zones concentrate the next tier of demand.
China
State Grid Corporation mandates process bus architectures for new ultra-high-voltage substations across eastern coastal provinces. The National Energy Administration enforces GB standards for smart grid equipment interoperability. Jiangsu and Zhejiang provinces host the densest concentration of 500kV greenfield projects with full Ethernet-based automation.
Germany
Transmission system operators prioritize time-sensitive networking pilots for 400kV substation modernization. The EU Cyber Resilience Act imposes fifteen-year software support obligations on automation vendors. Bavaria and Baden-Württemberg cluster the largest renewable integration zones demanding sub-cycle protection responses.
India
Western industrial corridors in Gujarat and Maharashtra compress vendor qualification timelines for SCADA integration. The Central Electricity Authority specifies communication protocol compliance for national grid modernization. Mumbai and Ahmedabad metropolitan grids accelerate multi-vendor panel deployments.
United States
Independent system operators prioritize wide-area situational awareness across ERCOT and PJM interconnection zones. The Federal Energy Regulatory Commission mandates critical infrastructure protection standards for encrypted command pathways. Texas and Illinois transmission corridors concentrate retrofit demand for DNP3-to-IEC 61850 migration.
Japan
Tokyo Electric Power unbundles hardware procurement from long-term service agreements to prioritize interoperability certification. METI drives standardization for earthquake-resilient substation automation. The Kanto and Kansai metropolitan grids mandate protocol conformance testing before final acceptance.
Global Electric Power Substation Automation Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue edge computing and digital twin adjacencies. The vendor base stratifies across three tiers: integrated hardware-software platforms, protocol-specialist component suppliers, and regional system integrators. Two dominant competitive moves define positioning: vertical integration into semiconductor sourcing for supply security, and strategic partnerships with transmission operators for long-term service contracts.
Among diversified industrial conglomerates, General Electric, Siemens, and Hitachi Energy exemplify the integrated platform archetype. These entities anchor premium-tier positioning through captive protocol expertise and multi-decade utility relationships. ABB and Schneider Electric occupy adjacent positions within the European vendor cluster. Mitsubishi Electric represents the Asia-based integrated alternative. Schweitzer Engineering Laboratories and Ingeteam exemplify the specialist tier focused on protective relaying and regional integration services respectively.
| Leading Market Players |
|---|
| General Electric |
| Eaton |
| ABB |
| Mitsubishi Electric |
| Schweitzer Engineering Laboratories |
| Siemens |
| Hitachi Energy |
| Ingeteam |
| Schneider Electric |
| Others |
Cost & Logistics Intelligence
State grid corporations in China and transmission operators across Germany anchor procurement volume, compressing vendor margins through multi-year framework agreements that bundle hardware, software, and fifteen-year service obligations into single-tender awards.
Pricing Analysis
High-volume transmission tenders sacrifice margin for market share capture, while specialized protective relaying commands premium pricing through IEC 61850 certification scarcity and sub-cycle performance guarantees. Three-tier pricing structure across premium, standard, and economy levels separates fully integrated automation suites from modular component suppliers and regional system integrators. Pricing pressure stems from municipal power departments in Japan and South Korea unbundling hardware from service contracts, forcing vendors to disclose lifecycle costs transparently. Price sensitivity peaks among municipal power departments optimizing capital expenditure; transmission operators tolerate premium pricing for redundancy-certified architectures.
Supply Chain Analysis
Regional distribution centers in Singapore, Rotterdam, and Dubai buffer lead times for European and Asia-Pacific deployment, though specialized analog chips for protective relaying concentrate fabrication in Taiwan and South Korea. Intelligent electronic device manufacturing draws from dysprosium and terbium for high-performance magnetics, with copper busbar and rare earth magnet supply tethered to Chinese export quota volatility. Single-source vulnerability in semiconductor fabrication exposes automation vendors to geopolitical disruption and allocation constraints. Distribution runs through direct vendor-to-utility contracts for large transmission projects, with regional system integrators handling municipal-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as vendors pursue captive semiconductor sourcing to secure specialized analog chip supply against Taiwan and South Korea concentration risks.
For Market Incumbents: Anchor premium positioning through IEC 61850 protocol leadership and multi-decade utility relationships that resist unbundling pressure from municipal power departments. Defend against emerging software-defined protection entrants by restructuring engineering organizations around product security incident response teams mandated by the EU Cyber Resilience Act. Prioritize backward integration into semiconductor sourcing to mitigate Taiwan fabrication concentration. For New Entrants and Emerging Players: Edge computing analytics for fault location applications offers a technology-first wedge into European transmission networks where latency requirements outpace incumbent platform refresh cycles. Target Brazil's ANEEL grid modernization programs in the Southeast and Northeast transmission corridors where vendor qualification timelines remain compressed and incumbent relationships less entrenched. Pursue subscription-based software revenue models that decouple from hardware procurement cycles. For Investors and Strategic Acquirers: The window for entry favors protocol-specialist component suppliers with IEC 61850 engineering expertise scarcity that utilities and vendors struggle to recruit. Long-term viability hinges on fifteen-year software support lifecycle capabilities mandated by European regulation. Watch for FERC critical infrastructure protection standard enforcement intensity as the signal indicating US cybersecurity certification friction relaxation or tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Sourcing | Mitigates Taiwan and South Korea fabrication concentration risks for protective relaying chips. |
| IEC 61850 Process Bus Architecture Deployment | State Grid Corporation mandates this standard for new 500kV substations across eastern coastal provinces. |
| Digital Twin Platform Development | Enables predictive maintenance contracts extending vendor revenue cycles beyond hardware sales. |
| Product Security Incident Response Team Formation | EU Cyber Resilience Act imposes fifteen-year software support obligations on automation vendors. |
| Multi-Vendor Panel Certification Investment | Tokyo and Seoul metropolitan grids mandate protocol conformance testing before final acceptance. |
Research Approach
Regulatory filings from FERC, CEA, and METI, alongside IEC standard documentation and utility procurement databases, formed the secondary backbone for market sizing and protocol adoption tracking. Primary interviews with utility planning officers, substation automation engineering directors, EPC contractors, and grid operators validated deployment timelines and vendor selection criteria. Bottom-up aggregation of project-level procurement data triangulated against top-down macroeconomic indicators refined volume and value estimates across the analysis window.
Historical trendline analysis of automation type penetration rates informed projection modeling, with segmentation across intelligent electronic devices, supervisory control systems, remote terminal units, and distributed control architectures. Technology protocol splits, application functional priorities, and end-user procurement authority fragmentation provided dimensional granularity. CAGRs were derived from fitted growth curves adjusted for regulatory mandate acceleration in China and India, with renewable intermittency management requirements and cybersecurity certification timelines as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption scenarios or abrupt shifts in Chinese rare earth export policy. Outputs reflect documented assumptions regarding IEC 61850 migration velocity and municipal procurement unbundling adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Domestic Hot Water (DHW) Tanks Market
Electrical Power Equipment
Power Strip Market
Electrical Power Equipment
Gas Water Heater Market
Electrical Power Equipment
Composite Line Post Insulators Market
Electrical Power Equipment
Power Line Filters Market
Electrical Power Equipment
HV Bushing Market
Electrical Power Equipment
Electrodialysis System Market
Electrical Power Equipment
Transformer Oil Testers Market
Electrical Power Equipment
Europe Brushless DC Motors Market
Electrical Power Equipment
South America Medium Voltage Switchgear Market
Electrical Power Equipment
Immersion Heater Market
Electrical Power Equipment
Europe Gas Insulated Switchgear Market
Electrical Power Equipment
Gas Insulated Switchgears (GIS) Market
Electrical Power Equipment
Magnetic Ballast Market
Electrical Power Equipment
Protective Relay Market
Electrical Power Equipment
Instant Water Heater Market