
 Frameless Brushless DC Motors Market | 2026-2036
Frameless Brushless DC Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Frameless Brushless DC Motors Market Foresight
REACH is rebalancing the cost-of-entry calculus for frameless brushless DC motor suppliers serving European medical and industrial automation customers. Maxon leverages its Swiss manufacturing base and vertical integration in winding technology to sustain premium positioning across surgical robotics and semiconductor equipment. Kollmorgen anchors North American demand through specialized direct-drive torque motors for defense and aerospace applications. Faulhaber competes in miniature frameless architectures where ironless winding configurations dominate precision instrumentation.
Frameless brushless DC motors are permanent-magnet synchronous machines manufactured without integrated housings or bearings, designed for direct embedding into customer mechanical assemblies with typical continuous torque densities exceeding 5 Nm/kg in compact outer-rotor configurations. These motors eliminate mechanical transmission elements, enabling higher dynamic response and reduced maintenance in precision motion systems. Outer rotor architectures lead in robotics and direct-drive automation where high torque at low speed is paramount, while slotless and ironless variants command premium positioning in medical imaging and optical scanning where cogging-free motion is essential. Sensorless control and field-oriented drive technologies are displacing traditional Hall-based commutation in high-reliability aerospace and surgical tool applications.
The EPA regulates rare earth material sourcing and disposal pathways affecting permanent magnet supply chains, while FDA device clearance requirements shape validation protocols for motor-integrated surgical instruments. ISO 13485 medical device quality management and IEC 60034 rotating machinery standards constrain design freedoms but create compliance barriers that favor established suppliers with dedicated regulatory affairs capabilities. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's embodied carbon tracking requirements will reshape magnet material provenance and motor recycling obligations.
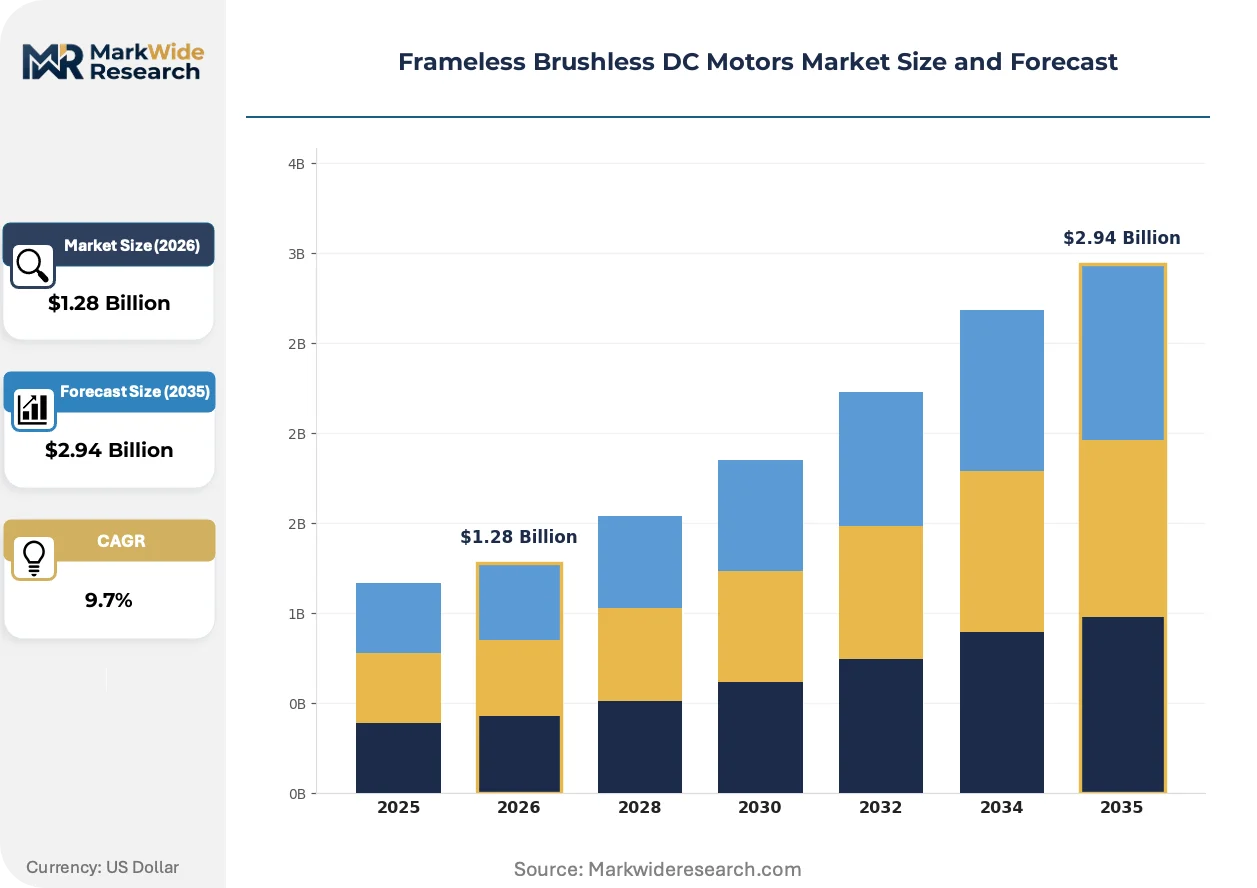
Market Dynamics
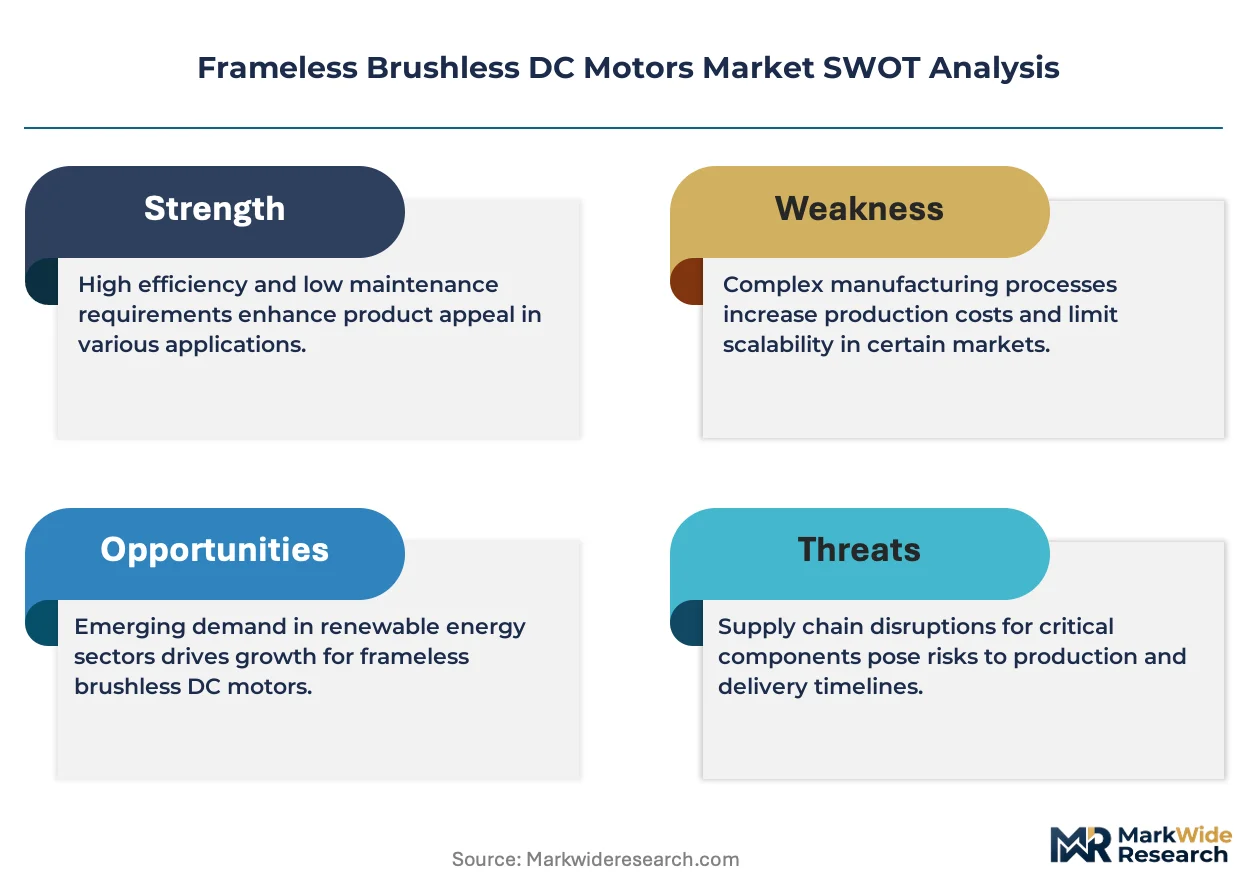
Sensorless field-oriented control architectures are compressing commissioning timelines and eliminating Hall-effect sensor dependencies across aerospace and surgical tool applications, reshaping supplier qualification criteria.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for fluorinated greenhouse gases are accelerating demand for hermetic frameless motor designs in medical imaging equipment requiring compliant encapsulant formulations.
- Collaborative robotics:Joint actuator integration in cobot arms is pulling torque-dense outer-rotor configurations into precision automation clusters around Stuttgart and Munich.
- Ironless winding technology:Slotless architectures with zero cogging torque are penetrating optical scanning and semiconductor wafer handling where nanometer positioning fidelity is non-negotiable.
Market Restraints
- Neodymium price volatility:Dysprosium and terbium supply concentration in Chinese processing facilities exposes permanent magnet cost structures to export quota fluctuations.
- REACH compliance burden:ECHA substance restrictions on winding insulation materials and potting compounds force reformulation cycles that extend product development timelines.
- Direct-drive torque motor substitution:Frameless alternatives face displacement in high-inertia applications where integrated bearing systems reduce mechanical assembly risk.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for advanced manufacturing equipment are attracting motor suppliers to Pune and Bangalore automation corridors.
- Surgical robotics unmet demand:FDA 510(k) pathway experience gaps among Asian suppliers create white space for established European wound-motor specialists.
- AI-driven predictive maintenance convergence:Integration of motor thermal models with edge computing platforms is enabling condition-monitoring service contracts in defense ground systems.
Industry Challenges
- Electromagnetic compatibility certification:IEC 60034-25 testing protocols for variable-speed drive systems impose multi-month validation cycles that strain smaller winding houses.
- ISO 13485 quality management implementation:Medical device traceability requirements demand dedicated regulatory affairs capabilities that fragment engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frameless Brushless DC Motors Market |
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Motor Type: Outer Rotor, Inner Rotor, Slotless, Ironless Application: Robotics, Aerospace Systems, Medical Devices, Industrial Automation, Consumer Electronics End User: Machine Builders, OEMs, Medical Equipment Manufacturers, Automation Integrators Drive Technology: Sensorless Control, Hall Sensor Control, Field-Oriented Control, Direct Torque Control |
| Companies Covered | Maxon, Kollmorgen, Faulhaber, Portescap, Allied Motion, Moog, Nidec, Shinano Kenshi, BEI Kimco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frameless Brushless DC Motors Market Shifts & Advancements
Control electronics miniaturization and magnet material provenance tracking are converging to redefine competitive differentiation in precision motion systems.
Integrated GaN-based inverter modules are automating commutation logic previously handled by external servo drives. Semiconductor equipment OEMs in Taiwan and South Korea are adopting these embedded power stages to reduce cabinet footprint. This integration is automating the traditional separation between motor and drive procurement decisions.
REACH authorization requirements for persistent organic pollutants in insulation systems are forcing winding material transitions. European medical device manufacturers now specify halogen-free encapsulants that withstand autoclave sterilization cycles. Surgical instrument suppliers with established ECHA registration dossiers are capturing preference share from competitors facing substance sunset deadlines.
Modular torque motor kits with standardized mechanical interfaces are displacing fully custom frameless assemblies. German machine tool builders now specify catalog torque ratings with adapted flange geometries rather than clean-sheet motor designs. This specification shift concentrates volume with wound-motor houses maintaining flexible stator lamination tooling.
Frameless Brushless DC Motors Market Segmentation
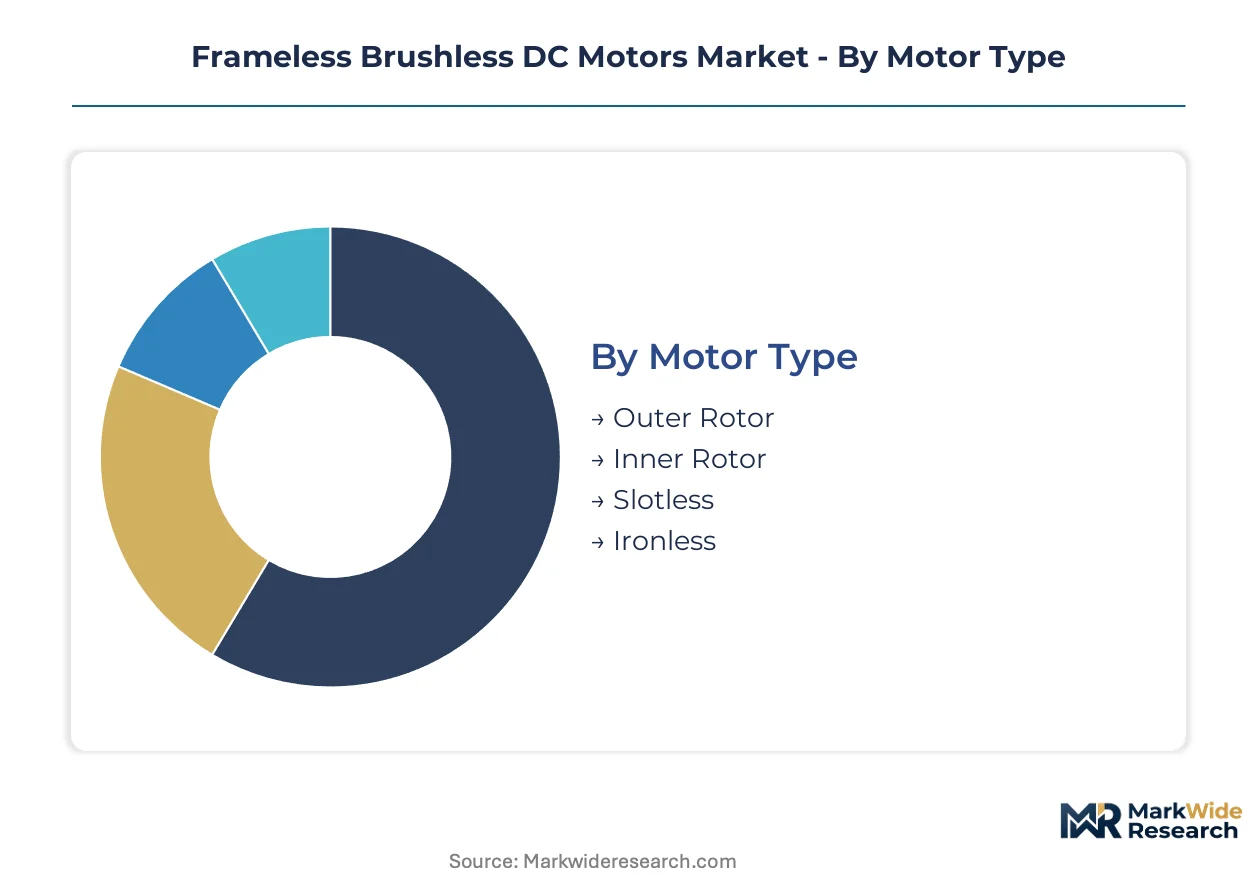
Frameless brushless DC motors fragment across four intersecting dimensions: motor architecture, application intensity, buyer procurement patterns, and control methodology. Each axis reshapes supplier qualification requirements and margin structures differently.
Motor Type:
Architectural choices between rotor placement and magnetic circuit design determine torque density, thermal performance, and cogging characteristics.
- Outer Rotor:High-pole-count configurations with rotor magnets positioned outside the stator winding deliver peak torque density exceeding 5 Nm/kg. Collaborative robot joint actuators in Germany's Stuttgart automation cluster specify these for direct-drive torque output without gear reduction.
- Slotless:Eliminating stator teeth removes cogging torque entirely, enabling nanometer-scale positioning fidelity. Semiconductor wafer handling equipment in Taiwan and South Korea requires these configurations for lithography stage motion.
- Inner Rotor:Traditional concentric geometry with internal rotor mass offers superior acceleration bandwidth for high-speed spindle applications.
- Ironless:Removing stator iron cores minimizes eddy current losses and inductance variation, serving precision optical scanning and medical imaging gantries where electromagnetic interference must be suppressed.
Outer rotor leads on scale; slotless leads on momentum.
Application:
End-use environments impose divergent certification burdens and reliability specifications.
- Robotics:Cobot arm manufacturers in Munich's precision automation corridor demand torque-dense outer-rotor assemblies with ISO 13849 functional safety compliance for human-collaborative operation.
- Medical Devices:FDA 510(k) clearance requirements and ISO 13485 quality management constrain motor-integrated surgical instruments to suppliers with dedicated regulatory affairs capabilities.
- Aerospace Systems:DO-160 environmental qualification and MIL-STD-810 vibration testing extend validation timelines for defense and satellite actuator applications.
- Industrial Automation:Machine tool builders in Germany now specify catalog torque ratings with adapted flange geometries rather than clean-sheet motor designs.
- Consumer Electronics:Price-sensitive volume applications favor ironless architectures from Asian winding houses with flexible lamination tooling.
Industrial automation leads on scale; medical devices lead on momentum.
End User:
Buyer sophistication and procurement integration depth segment the demand base.
- Medical Equipment Manufacturers:These buyers mandate REACH-compliant halogen-free encapsulants and autoclave sterilization resistance, capturing preference share from competitors facing ECHA substance sunset deadlines.
- Automation Integrators:System houses in India's Pune and Bangalore corridors leverage PLI scheme incentives to source modular torque motor kits with standardized mechanical interfaces.
- Machine Builders:German OEMs concentrate procurement around wound-motor specialists maintaining flexible stator lamination tooling for adapted flange geometries.
- OEMs:Original equipment manufacturers with captive drive electronics capabilities favor sensorless control architectures to compress commissioning timelines.
Machine builders lead on scale; medical equipment manufacturers lead on momentum.
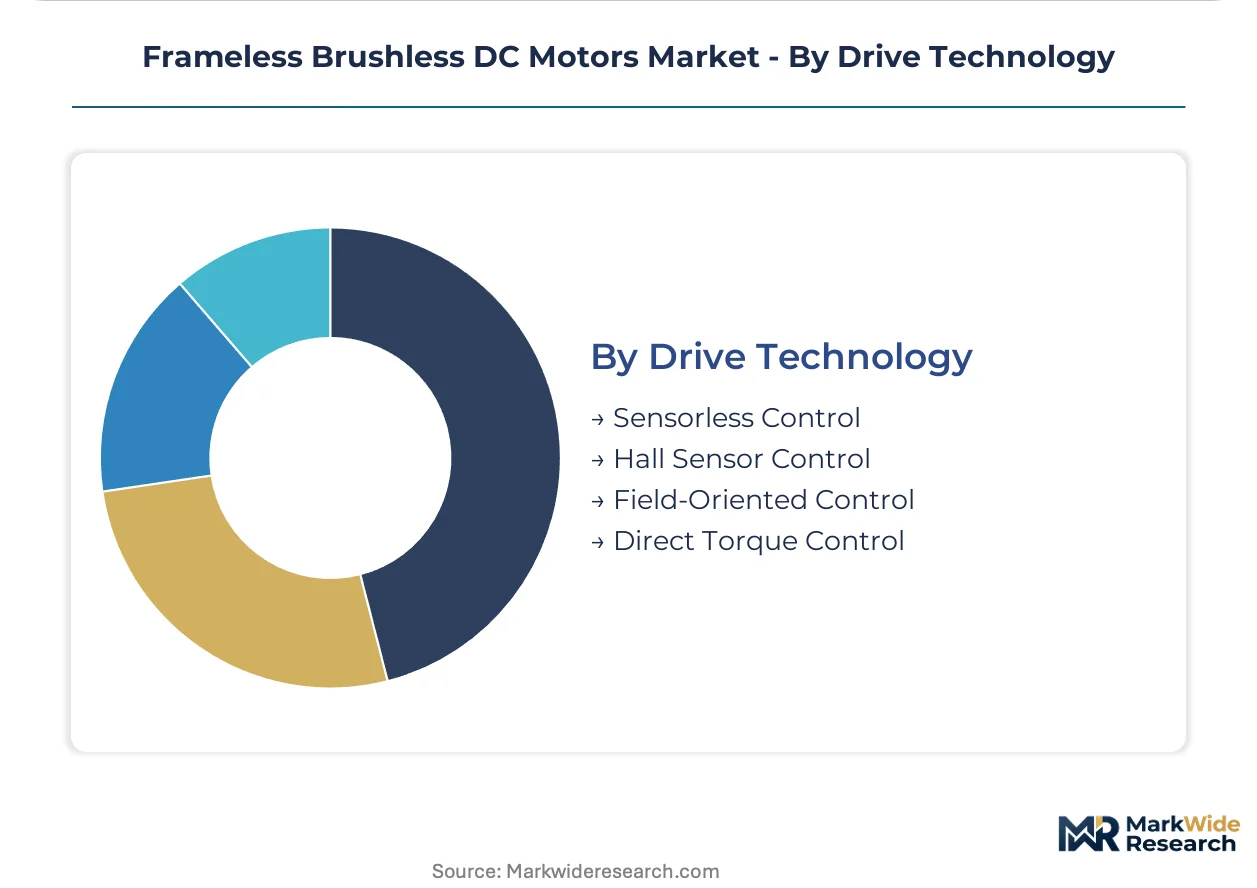
Drive Technology:
Commutation methodology determines sensor dependencies, control bandwidth, and system integration complexity.
- Sensorless Control:Back-EMF estimation algorithms eliminate Hall-effect sensors and their failure modes, penetrating aerospace and surgical tool applications where component count reduction improves mean time between failures.
- Field-Oriented Control:Vector current regulation maximizes torque-per-ampere across speed ranges, displacing traditional trapezoidal commutation in high-performance automation.
- Hall Sensor Control:Discrete position feedback persists in cost-constrained consumer electronics where absolute rotor position at startup remains essential.
- Direct Torque Control:Hysteresis-based torque regulation offers rapid dynamic response for high-inertia loads in defense ground systems.
Field-oriented control leads on scale; sensorless control leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered precision motion systems engineering in the 1970s, establishing the technical foundations for frameless motor architectures now adopted worldwide. Stuttgart and Munich remain the world's densest concentration of collaborative robotics and machine tool integration. The analysis examines five countries where demand concentrates.
Germany
Collaborative robot joint actuators and semiconductor wafer handling equipment drive procurement from Stuttgart and Munich automation clusters. REACH compliance mandates from ECHA restrict winding insulation materials, forcing halogen-free encapsulant transitions. Baden-Württemberg machine builders now specify catalog torque ratings with adapted flange geometries rather than clean-sheet designs.
United States
Defense ground systems and surgical robotics applications anchor demand for sensorless control architectures. FDA 510(k) clearance requirements shape validation protocols for motor-integrated instruments. Boston and Pittsburgh precision automation corridors concentrate procurement among established suppliers with dedicated regulatory affairs capabilities.
China
Dual carbon goals and rare earth processing dominance reshape magnet material provenance tracking for permanent magnet supply chains. MIIT industrial upgrading programs accelerate domestic precision motor manufacturing. Yangtze River Delta electronics OEMs integrate GaN-based inverter modules to reduce cabinet footprint in semiconductor equipment.
Japan
Optical scanning and medical imaging gantries demand ironless winding configurations with zero cogging torque. METI technology roadmaps prioritize high-torque-density motor development for next-generation robotics. Nagoya and Osaka industrial automation clusters specify slotless architectures for nanometer positioning fidelity.
India
Production-linked incentive schemes for advanced manufacturing equipment attract motor suppliers to Pune and Bangalore corridors. BIS standards alignment with IEC 60034 rotating machinery specifications accelerates supplier qualification. Automation integrators leverage modular torque motor kits with standardized mechanical interfaces for cost-sensitive deployments.
Frameless Brushless DC Motors Market Competitive Landscape
The competitive structure tilts toward vertically integrated specialists with captive winding technology and established regulatory dossiers. Premium-tier positioning concentrates among Swiss and German houses with ISO 13485 medical device quality management capabilities. Three archetypes dominate: precision wound-motor specialists, diversified motion control conglomerates, and Asian volume manufacturers with flexible lamination tooling. Strategic moves center on backward integration into magnet material supply chains and ECHA registration dossier accumulation for REACH-compliant encapsulant formulations.
Within the precision wound-motor tier, Maxon and Kollmorgen exemplify divergent geographic anchoring strategies. Maxon leverages its Swiss manufacturing base to sustain premium positioning across surgical robotics and semiconductor equipment applications. Kollmorgen anchors North American demand through specialized direct-drive torque motors for defense and aerospace end uses. Faulhaber occupies a distinct position in miniature frameless architectures where ironless winding configurations dominate precision instrumentation markets.
| Leading Market Players |
|---|
| Maxon |
| Kollmorgen |
| Faulhaber |
| Portescap |
| Allied Motion |
| Moog |
| Nidec |
| Shinano Kenshi |
| BEI Kimco |
| Others |
Supply & Pricing Matrix
Sensorless field-oriented control architectures are compressing commissioning timelines while simultaneously eliminating Hall-effect sensor costs and consolidating procurement decisions around integrated drive-motor systems. This technological shift rewards suppliers with captive inverter production capabilities and punishes pure-play motor houses dependent on external servo drive partnerships.
Pricing Analysis
Bundled motor-drive packages command premium positioning against unbundled component procurement, with pricing stratifying across ISO 13485-certified medical tiers, IEC 60034 industrial grades, and uncertified economy offerings for consumer electronics. Price differentiation hinges on REACH-compliant encapsulant formulations and autoclave sterilization resistance for surgical robotics applications. Cost compression in standard industrial tiers intensifies as Chinese winding houses with flexible lamination tooling enter European machine builder supply chains. Medical equipment manufacturers exhibit lowest price sensitivity due to FDA 510(k) validation lock-in, while consumer electronics OEMs drive aggressive commoditization of ironless architectures.
Supply Chain Analysis
Direct-to-OEM channels handle demand from German machine tool builders and surgical robotics specialists, while distributor networks serve smaller automation integrators in India's Pune corridor. Magnet material provenance draws from Chinese rare earth processing dominance, German precision lamination tooling, and Swiss winding automation equipment. Neodymium-dysprosium-terbium supply concentration in Chinese export quota systems creates single-source vulnerability for permanent magnet cost structures. Distribution runs through specialized motion control distributors in Europe and direct mill relationships for high-volume Asian electronics OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH substance sunset deadlines for persistent organic pollutants in insulation systems compound competitive advantage for suppliers with established ECHA registration dossiers, transforming regulatory compliance into a demand driver for premium-tier positioning.
For Market Incumbents: Acquire ECHA-authorized encapsulant formulation capabilities to defend against Asian suppliers facing substance sunset deadlines. Deepen backward integration into rare earth magnet supply chains to mitigate Chinese export quota volatility. Capture preference share in surgical robotics by accelerating ISO 13485 quality management investments ahead of FDA 510(k) pathway expansion. For New Entrants and Emerging Players: The price-point gap between Swiss-German premium wound-motor specialists and Asian volume manufacturers creates entry space for mid-tier suppliers offering REACH-compliant standard industrial grades. Target India's PLI scheme corridors with modular torque motor kits featuring standardized mechanical interfaces. Penetrate through automation integrators in Pune and Bangalore seeking alternatives to fully custom frameless assemblies. For Investors and Strategic Acquirers: Valuations sit cheapest among European winding houses lacking dedicated regulatory affairs capabilities but possessing flexible stator lamination tooling. Long-term viability centers on suppliers bridging medical device certification requirements with industrial automation scale economics. Monitor ECHA substance authorization timelines as inflection indicators for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnet Supply | Captive rare earth sourcing mitigates Chinese export quota exposure for permanent magnet cost structures. |
| ECHA Registration Dossier Accumulation | REACH-compliant encapsulant formulations capture preference share from competitors facing substance sunset deadlines. |
| ISO 13485 Quality Management Investment | Medical device traceability capabilities unlock FDA 510(k) pathway access for surgical robotics applications. |
| GaN-Based Inverter Module Integration | Embedded power stages reduce cabinet footprint for Taiwan and South Korea semiconductor equipment OEMs. |
| Modular Torque Motor Kit Standardization | Catalog torque ratings with adapted flange geometries displace clean-sheet designs among German machine tool builders. |
Research Methodology
Direct dialogue with motor design engineers, procurement leads at surgical robotics OEMs, regulatory affairs specialists, and automation integrators informed qualitative grounding across the frameless brushless DC motors value chain. Secondary validation drew from ECHA substance restriction databases, FDA 510(k) clearance filings, IEC 60034 rotating machinery standards, and customs trade data for rare earth magnet flows. Bottom-up segment sizing triangulated against top-down macroeconomic indicators for precision automation equipment investment cycles.
Unit shipment and revenue estimates emerged from disaggregated modeling across motor architecture, application intensity, buyer procurement patterns, and control methodology dimensions. The analytical framework incorporated torque density specifications, thermal performance curves, and certification tier penetration rates throughout the projection horizon. CAGRs derived from regression analysis of historical procurement patterns correlated with collaborative robotics deployment trajectories and semiconductor capital expenditure cycles.
The model assumes a particular technology adoption path; alternative pathways for sensorless control architectures displacing Hall-based commutation would alter the outlook for drive electronics integration strategies. Forecasts reflect assumptions regarding REACH enforcement timelines, rare earth supply quota stability, and medical device regulatory harmonization that warrant periodic reassessment. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
North America Protective Relays Market
Electrical Power Equipment
Bucket Water Heater Market
Electrical Power Equipment
Electric Substation Market
Electrical Power Equipment
Smart Electric Heater Market
Electrical Power Equipment
Asia-Pacific Air-Insulated Switchgear Market
Electrical Power Equipment
Domestic Hot Water (DHW) Tanks Market
Electrical Power Equipment
Carbon Brush Market
Electrical Power Equipment
Europe Electric Radiators Market
Electrical Power Equipment
High Voltage Direct Current (HVDC) Cables Market
Electrical Power Equipment
Alternators Market
Electrical Power Equipment
Electric Submersible Pump Cable Market
Electrical Power Equipment
High Voltage Oil Insulated Switchgear Market
Electrical Power Equipment
North America Oil Filled Electric Heaters Market
Electrical Power Equipment
AV Power Conditioners Market
Electrical Power Equipment
Bio-Based Transformer Oil Market
Electrical Power Equipment
HV Bushing Market