
 Domestic Hot Water (DHW) Tanks Market | 2026-2036
Domestic Hot Water (DHW) Tanks Market Size, Share, and Industry Trends Forecast 2026-2036
Domestic Hot Water (DHW) Tanks Market Insights
Wholesale distribution networks for heating equipment is rewriting how manufacturers reach end-users across Europe. A. O. Smith Corporation leverages its captive dealer network to sustain replacement-cycle revenue in North American suburbs. Rheem Manufacturing Company anchors its position through backward integration into heat pump compressor supply. Bosch Thermotechnology competes on system integration, bundling tanks with controls and solar thermal collectors.
Domestic hot water tanks are insulated cylindrical vessels engineered to store and maintain potable water between 49°C and 60°C, utilizing steel or glass-lined carbon steel shells with polyurethane foam insulation and sacrificial anode corrosion protection. These units serve the fundamental purpose of delivering reliable sanitary hot water to residential, commercial, and institutional buildings on demand. Heat pump tanks now lead product type growth as building codes tighten efficiency minimums, while the 81-120 liter capacity band dominates urban apartment retrofits where space constraints limit unit size. Electric tanks retain the largest installed base across European residential buildings, though gas-fired replacements face accelerating displacement where natural gas hookup bans advance.
The US Department of Energy enforces minimum energy factor standards that ratchet upward every six years, forcing manufacturers to redesign insulation packages and burner systems. The EU Ecodesign Directive and F-Gas Regulation together constrain refrigerant choices in heat pump tanks while mandating standby heat loss thresholds below 50 watts. The EPA WaterSense program extends labeling requirements to commercial tank categories, expanding compliance scope beyond residential units. Stakeholders must monitor how refrigerant transition timelines and efficiency tier reclassifications reshape product portfolio economics across manufacturing footprints.
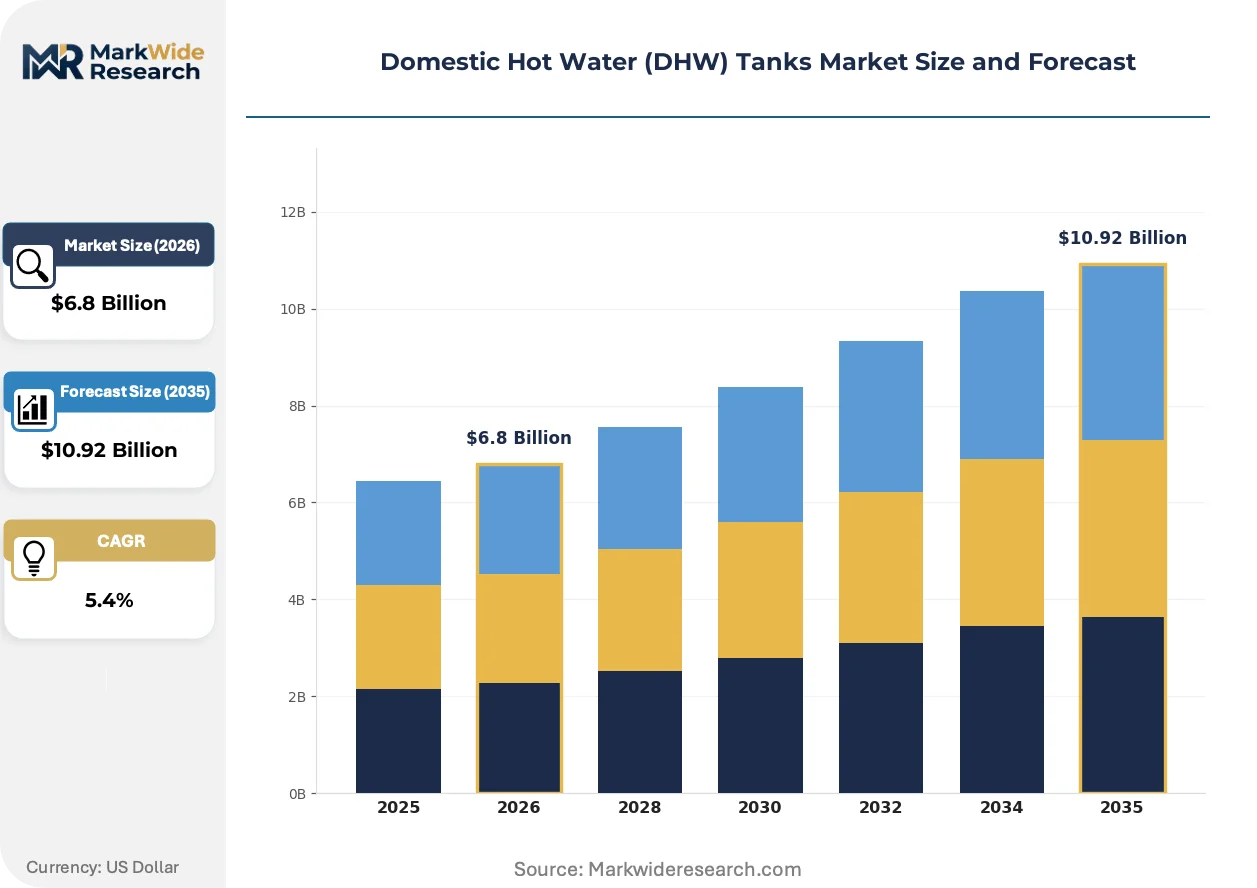
Market Dynamics
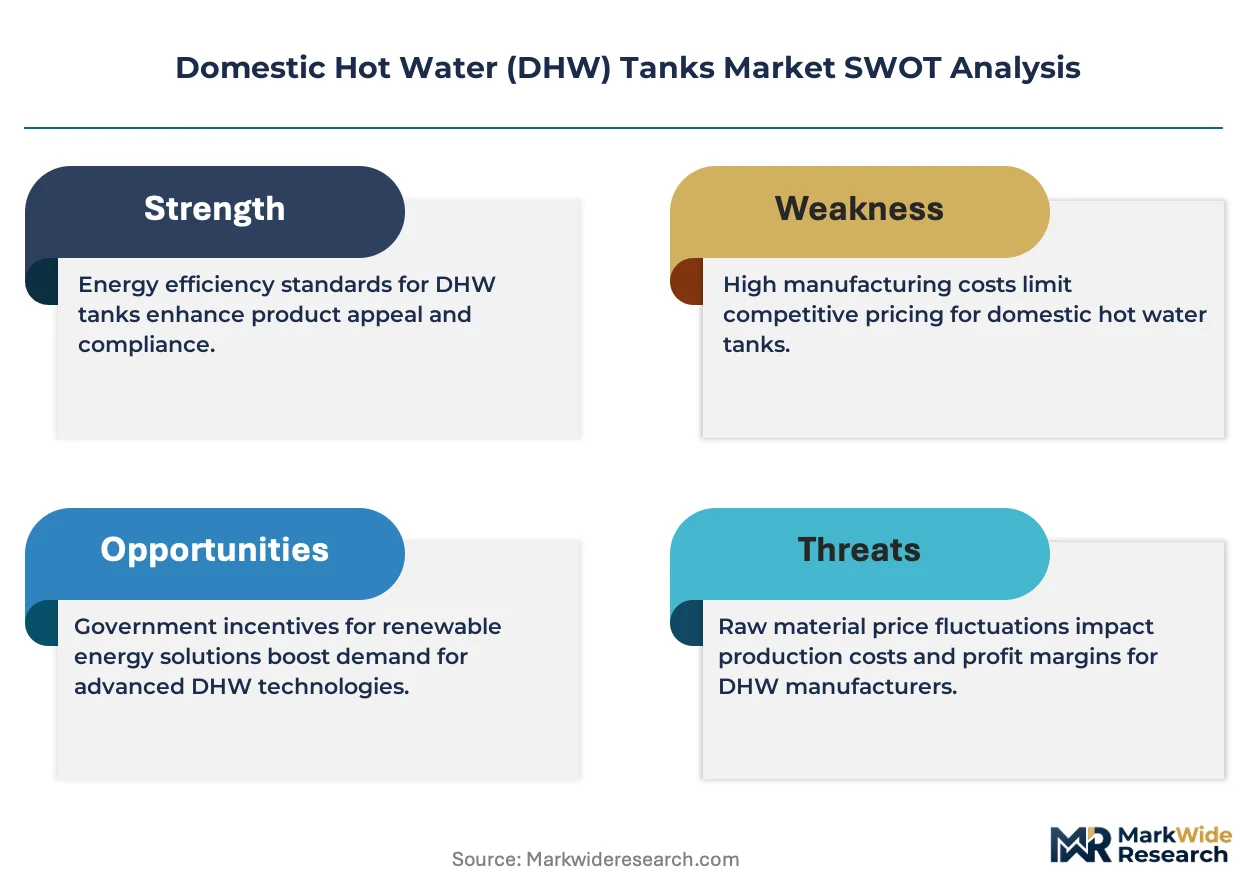
The EU F-Gas Regulation phase-down is compressing refrigerant availability for heat pump tanks, forcing manufacturers to redesign compressor architectures and accelerating the displacement of conventional electric resistance units across European residential retrofits.
Growth Catalysts
- EU Ecodesign Directive standby loss mandates:French and German building codes now require heat pump tanks in new construction, pulling forward replacement demand from gas-fired systems.
- Natural gas hookup bans:Municipal ordinances in California, New York, and the Netherlands block fossil fuel connections in new buildings, redirecting demand toward electric and solar-assisted storage.
- Heat pump compressor efficiency gains:R290 propane refrigerant systems achieve coefficient of performance ratings above 3.0, shrinking operating cost gaps with gas-fired alternatives.
Market Restraints
- Copper and steel input volatility:Tank shell and heat exchanger materials face price swings tied to energy-intensive smelting operations in China and Chile.
- Refrigerant supply concentration:Fluorinated gas production clusters among Chinese chemical conglomerates, exposing European and North American assemblers to export quota risks.
- Installation skill scarcity:Heat pump tank deployment requires refrigeration-certified technicians, creating bottlenecks where vocational training lags regulatory deadlines.
Strategic Opportunities
- Polish and Romanian renovation waves:EU Recovery and Resilience Facility funds flow toward building efficiency upgrades in Eastern European markets with aging Soviet-era heating infrastructure.
- Solar thermal hybrid integration:Vacuum tube collector pairing with stratified storage tanks opens premium positioning in Mediterranean climates with high insolation.
- Direct-to-installer digital platforms:Bypassing traditional wholesale distributors, manufacturers capture margin and capture real-time demand signals from plumbing contractors.
Industry Challenges
- Refrigerant transition engineering timelines:R32 and R290 compatibility testing with existing heat pump architectures compresses product development cycles ahead of F-Gas quota reductions.
- Legacy electrical panel capacity:Residential service upgrades required for heat pump tank installation add soft costs and project abandonment risk in older urban housing stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Domestic Hot Water (DHW) Tanks Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Tanks, Gas-Fired Tanks, Solar Tanks, Indirect Tanks, Heat Pump Tanks Capacity: 50-80 Liters, 81-120 Liters, 121-150 Liters, Above 150 Liters Application: Residential Buildings, Commercial Complexes, Institutional Facilities, Hospitality Establishments Installation Type: Wall-Mounted, Floor-Standing, Outdoor, Integrated |
| Companies Covered | A. O. Smith Corporation, Rheem Manufacturing Company, Bosch Thermotechnology, Ariston Thermo, Bradford White Corporation, Rinnai Corporation, Stiebel Eltron, Viessmann Group, Vaillant Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Domestic Hot Water (DHW) Tanks Market Trends and Innovations
Product architecture is pivoting from standalone vessels toward system-integrated thermal storage, with controls, heat sources, and distribution plumbing converging into pre-engineered packages that slash field installation labor.
Heat pump water heaters with integrated CO2 transcritical cycles are rendering obsolete traditional electric resistance tanks in Nordic commercial applications. Danish and Swedish district heating operators specify these units for decentralized peak shaving. The technology compresses carbon intensity metrics for building portfolio certifications.
The EPA WaterSense labeling extension to commercial tank categories tightens efficiency disclosure requirements. Manufacturers must submit third-party test data for standby loss and recovery rates. Commercial facility managers in California and Texas now specify labeled units to meet corporate sustainability procurement standards.
Buying committees at multi-family housing developers now unbundle equipment specification from installation contracting. Engineering firms retain tank selection authority while mechanical contractors compete purely on labor pricing. This pattern concentrates in German and Austrian social housing tenders where lifecycle cost modeling dominates award criteria.
Domestic Hot Water (DHW) Tanks Market Segmentation
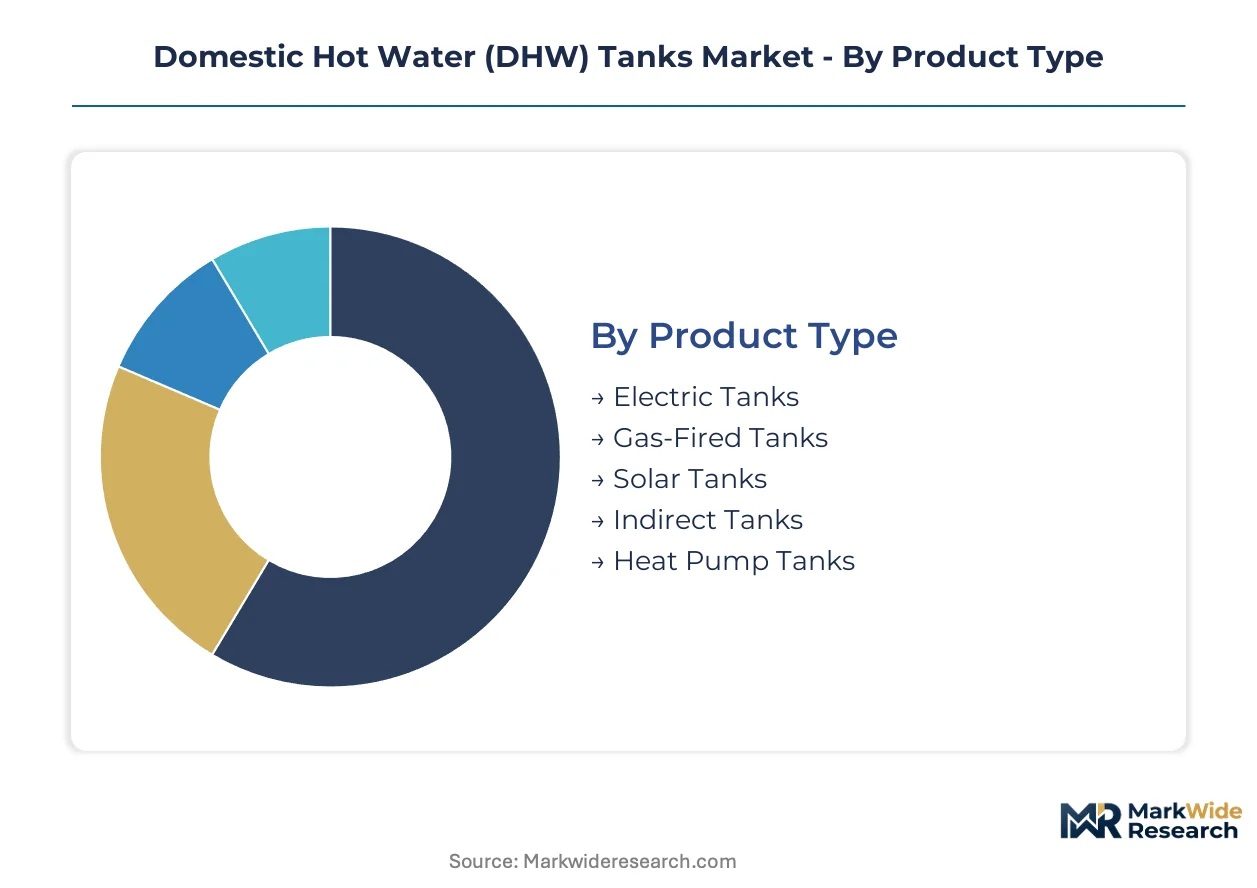
Domestic hot water tank segmentation reveals how efficiency regulations and building stock characteristics reshape procurement patterns across heating equipment categories. Manufacturers must align product portfolios with divergent technical requirements in renovation versus new construction channels.
Product Type:
Mature electric resistance technology dominates installed base volumes while emerging heat pump architectures capture regulatory-driven replacement cycles.
- Electric Tanks:Steel vessels with immersed resistance elements deliver water at 60°C through polyurethane-insulated shells. German apartment buildings retain these units where electrical panel upgrades prove cost-prohibitive for heat pump retrofits.
- Heat Pump Tanks:Refrigerant-cycle systems extract ambient thermal energy to achieve coefficient of performance ratings above 3.0. French new construction mandates under the EU Ecodesign Directive accelerate displacement of gas-fired alternatives in single-family housing.
- Gas-Fired Tanks:Atmospheric and power-vented burners with glass-lined storage remain prevalent in North American suburban housing with existing natural gas infrastructure.
- Solar Tanks:Stratified storage vessels with dual heat exchangers pair with vacuum tube or flat-plate collectors for renewable fraction compliance in Mediterranean markets.
- Indirect Tanks:Stainless steel coils transfer heat from external boilers without direct firing, serving hydronic system integration in Central European multi-family buildings.
Electric tanks handle the majority of throughput; heat pump tanks are expanding most quickly on share.
Capacity:
Cost tier positioning separates commodity replacement volumes from premium system-integrated specifications.
- 81-120 Liters:Compact cylindrical vessels with 50mm polyurethane insulation serve urban apartment retrofits where utility closet dimensions constrain unit selection. French renovation contractors specify this band for studio and one-bedroom replacement cycles.
- Above 150 Liters:Heavy-gauge steel shells with enhanced anode protection support commercial hospitality and institutional applications with simultaneous draw requirements. German hospital engineering departments prioritize this capacity for surgical suite sterilization supply.
- 50-80 Liters:Point-of-use electric units with minimal standby loss serve kitchen and secondary bathroom installations in space-constrained renovations.
- 121-150 Liters:Mid-range vessels bridge residential and light commercial duty cycles, common in Polish multi-family housing upgrades.
The 81-120 liter band anchors replacement revenue; above-150 liter systems command the steepest expansion trajectory in commercial channels.
Application:
Customer type differentiation separates price-sensitive residential procurement from lifecycle-cost-optimized commercial specification.
- Residential Buildings:Single-family and multi-family installations drive volume through replacement cycles triggered by failure or efficiency regulation. Dutch homeowners facing municipal gas hookup bans redirect demand toward electric and heat pump alternatives.
- Hospitality Establishments:Hotels and resorts require redundant capacity with rapid recovery rates to accommodate morning peak demand. California facility managers specify EPA WaterSense-labeled units for corporate sustainability procurement compliance.
- Commercial Complexes:Office buildings and retail centers prioritize compact footprint and minimal maintenance in mechanical room installations.
- Institutional Facilities:Schools and municipal buildings emphasize durability and safety certifications in public tender specifications.
Residential buildings absorb the bulk of unit shipments; hospitality establishments generate the fastest share gains through sustainability-driven procurement.
Installation Type:
Supply concentration in pre-engineered system packages compresses field labor requirements and accelerates deployment timelines.
- Floor-Standing:Conventional vertical vessels with seismic restraints dominate North American basement and utility room installations. Texas mechanical contractors favor this configuration for straightforward replacement logistics.
- Integrated:Factory-assembled packages combining storage, heat pump compressor, and controls reduce commissioning complexity. Swedish district heating operators deploy these units for decentralized peak shaving in building portfolio retrofits.
- Wall-Mounted:Horizontal cylinder configurations maximize floor space in compact European apartments.
- Outdoor:Weatherized enclosures with enhanced insulation serve climates where interior mechanical space is unavailable.
Floor-standing configurations maintain the largest installed base; integrated systems are climbing the fastest on specification frequency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers command pricing power across EU retrofit channels while Chinese fabricators dominate commodity electric tank exports to Southeast Asian construction markets.
United States
Municipal gas hookup bans in California and New York redirect single-family construction toward heat pump tank specifications. The EPA WaterSense labeling program tightens efficiency disclosure requirements for commercial tank categories. Texas mechanical contractors concentrate floor-standing replacement volumes in suburban Dallas-Fort Worth and Houston corridors.
Germany
Residential builders accelerate heat pump tank deployments ahead of EU F-Gas Regulation phase-down deadlines. The EU Ecodesign Directive mandates standby heat loss thresholds below 50 watts across new construction. Bavarian and Baden-Württemberg housing cooperatives specify integrated system packages for multi-family efficiency retrofits.
France
Homeowners in the renovation sector replace aging gas-fired units with electric and solar-assisted storage systems. French building codes now require heat pump tanks in new construction under transposed EU efficiency directives. The Île-de-France region concentrates demand for compact 81-120 liter units in Parisian apartment retrofits.
China
Domestic construction drives volume for electric resistance tanks in multi-family residential towers. The country's national efficiency regulator enforces escalating minimum energy factor standards on manufacturers. Yangtze River Delta fabricators supply heat pump compressor components to European and North American assemblers.
Poland
EU Recovery and Resilience Facility funds flow toward building efficiency upgrades targeting Soviet-era heating infrastructure. National building codes align with EU Ecodesign Directive transposition timelines for standby loss mandates. Warsaw and Krakow municipal housing authorities tender for mid-range 121-150 liter capacity systems.
Domestic Hot Water (DHW) Tanks Market Competitive Landscape
Integrated-system specialists and component-scale fabricators split the market between premium specification channels and price-sensitive replacement volumes. The vendor base concentrates among diversified heating equipment conglomerates with captive distribution networks and regional specialists serving renovation contractors. Three archetypes dominate: full-system integrators bundling tanks with controls and solar thermal collectors; heat pump technology specialists with backward integration into compressor supply; and commodity electric tank producers competing on manufacturing scale. Competitive moves center on M&A activity targeting refrigeration-certified installation service networks and capacity expansion into R290 propane refrigerant production lines.
Among North American heating equipment conglomerates, A. O. Smith Corporation and Rheem Manufacturing Company exemplify the captive-distribution archetype, while Bosch Thermotechnology represents the European system-integration model. These three entities anchor competitive positioning across regulatory-driven replacement cycles in their respective home markets.
| Leading Market Players |
|---|
| A. O. Smith Corporation |
| Rheem Manufacturing Company |
| Bosch Thermotechnology |
| Ariston Thermo |
| Bradford White Corporation |
| Rinnai Corporation |
| Stiebel Eltron |
| Viessmann Group |
| Vaillant Group |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in European heat pump compressor fabrication is tightening supplier pricing power while compressing procurement timelines for tank assemblers. German and French manufacturers now compete for limited R290 propane refrigerant component volumes, forcing premium positioning on configured-to-order system packages.
Pricing Analysis
The customization-premium spread separates standard electric resistance tanks from configured heat pump systems with integrated controls and solar thermal coupling. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under EU Ecodesign Directive standby loss thresholds and brand positioning in renovation versus new construction channels. Pricing pressure stems from copper and steel input volatility tied to energy-intensive smelting operations in China and Chile. Residential replacement contractors in suburban North American markets exhibit highest price sensitivity, while German housing cooperatives prioritize lifecycle cost optimization over first cost.
Supply Chain Analysis
Tariff exposure between Chinese chemical conglomerates and European tank assemblers dominates supply chain risk planning for refrigerant-dependent heat pump architectures. Manufacturing concentrates in China for electric resistance tank shells, Germany for precision heat pump compressor systems, and Poland for mid-range capacity vessels serving Eastern European renovation demand. Raw material dependencies center on copper heat exchangers, polyurethane foam insulation precursors, and glass-lined carbon steel substrates. Single-source vulnerability clusters in fluorinated gas production where export quota risks threaten component availability. Distribution runs through captive dealer networks for replacement-cycle revenue and direct-to-installer digital platforms capturing real-time demand signals from plumbing contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where system integration—bundling storage, controls, and heat sources into pre-engineered packages—rewards ecosystem orchestrators over standalone vessel producers. Interoperability between heat pump compressors and building energy management systems is redefining competitive boundaries.
For Market Incumbents: Build switching-cost moats through captive installation service networks with refrigeration-certified technicians. A. O. Smith Corporation and Rheem Manufacturing Company should deepen backward integration into R290 propane refrigerant production lines ahead of EU F-Gas Regulation quota reductions. Certification investment in EPA WaterSense labeling for commercial tank categories locks in specification authority with California and Texas facility managers facing corporate sustainability procurement mandates. For New Entrants and Emerging Players: Establish a beachhead in Polish and Romanian renovation waves where EU Recovery and Resilience Facility funds flow toward Soviet-era heating infrastructure replacement. The 81-120 liter capacity band in Parisian and Warsaw apartment retrofits offers lowest competitive density against established German and French system integrators. Direct-to-installer digital platforms bypassing traditional wholesale distributors capture margin and real-time demand signals from plumbing contractors. For Investors and Strategic Acquirers: Capital is best deployed toward heat pump technology specialists with upstream control over compressor supply and refrigeration-certified installation networks. Long-term viability over the coming decade hinges on R290 refrigerant compatibility testing capabilities and F-Gas Regulation compliance positioning. The signal to watch is municipal gas hookup ban acceleration in California, New York, and the Netherlands redirecting new construction specification toward electric and solar-assisted storage.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Supply | Rheem Manufacturing Company secures R290 propane refrigerant component availability ahead of EU F-Gas quota reductions. |
| Direct-to-Installer Digital Platform Launch | Manufacturers bypass wholesale distributors to capture margin and real-time demand signals from plumbing contractors. |
| Refrigeration-Certified Technician Network Acquisition | Installation skill scarcity creates bottlenecks where vocational training lags regulatory deadlines for heat pump deployment. |
| Solar Thermal Hybrid System Integration | Vacuum tube collector pairing with stratified storage opens premium positioning in Mediterranean climates with high insolation. |
| EPA WaterSense Commercial Labeling Investment | California and Texas facility managers specify labeled units to meet corporate sustainability procurement standards. |
Research Methodology
A spread of perspectives from product engineering directors at heating equipment manufacturers, procurement leads at multi-family housing developers, refrigeration-certified installation contractors, and regulatory affairs specialists at EU trade associations converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, EU Ecodesign Directive transposition documents, EPA WaterSense program specifications, and customs trade data on copper and steel inputs. Bottom-up unit shipment estimates by product type and capacity tier triangulated against top-down market value reconstruction across the analysis window.
Demand-supply-balance framing anchored the analytical framework, modeling replacement-cycle velocity against new construction penetration rates across residential, hospitality, and institutional application segments. Segmentation dimensions included product architecture, capacity band, installation type, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to efficiency regulation phase-in timelines and natural gas hookup ban adoption patterns. Heat pump coefficient of performance improvement trajectories and refrigerant transition engineering timelines served as industry-specific forecast inputs.
Sensitivities concentrate around EU F-Gas Regulation quota enforcement stringency, copper price volatility from Chilean smelting operations, and municipal gas hookup ban acceleration in North American jurisdictions. Forecasts reflect documented assumptions on replacement-cycle duration and new construction specification rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Electric Vehicle Charging Cables Market
Electrical Power Equipment
Substation Market
Electrical Power Equipment
Residential Air Insulated Power Distribution Component Market
Electrical Power Equipment
US Air Filter Market
Electrical Power Equipment
India Gas Insulated Switchgear Market
Electrical Power Equipment
Latin America Hazardous Location Motor Starters Market
Electrical Power Equipment
North America Gas Insulated Switchgear Market
Electrical Power Equipment
3rd Rail Current Collector Market
Electrical Power Equipment
Busbar Protection Market
Electrical Power Equipment
Alternate Current (AC) Drives Market
Electrical Power Equipment
Instant Water Heater Market
Electrical Power Equipment
Europe Alternating Current (AC) Drive Market
Electrical Power Equipment
Containerized Substation Market
Electrical Power Equipment
Overhead Aluminium Conductors Market
Electrical Power Equipment
Global Surge Arrester Market
Electrical Power Equipment
High Voltage Ionising Air Gun Market