
 Spain Solar Energy Market | 2026-2036
Spain Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Solar Energy Market Outlook
Multi-source EPC contracting is realigning how Spanish solar developers manage construction risk and capital deployment. Iberdrola leverages its integrated utility-developer model to control grid interconnection timelines across Castilla-La Mancha. ACCIONA Energía anchors its competitive position through in-house civil engineering capabilities that reduce reliance on third-party construction consortia. Prodiel specializes in substation and medium-voltage infrastructure, occupying a technical niche that larger IPPs often outsource.
Spain solar energy encompasses photovoltaic and concentrated solar power systems that convert electromagnetic radiation into electrical output through semiconductor junctions or thermal-fluid cycles, typically achieving module efficiencies between twenty-one and twenty-four percent for monocrystalline silicon arrays. These installations serve grid-connected generation, distributed commercial supply, and isolated industrial loads across the Iberian Peninsula's high-insolation zones. Photovoltaic technology dominates capacity additions due to modularity and declining levelized cost structures, while concentrated solar power retains structural relevance in utility-scale configurations that incorporate molten-salt thermal storage for dispatchable evening output. Utility-scale power capacity captures the dominant share of new investment, though commercial end-user segments are expanding faster as behind-the-meter economics improve for Spanish manufacturing and logistics facilities.
Spain's Ministry for Ecological Transition and Demographic Challenge shapes project economics through auction mechanisms and grid-access queue reforms, while CNMC oversight of transmission tariff structures influences locational returns for developers. EU Green Deal alignment and REPowerEU targets reinforce domestic renewable deployment mandates that accelerate permitting timelines for strategic solar zones. Stakeholders must monitor how regional land-use conflicts and agricultural water restrictions reshape site selection criteria in southern provinces.
Market Dynamics
Streamlined grid-access permitting under Spain's national energy transition framework is accelerating utility-scale procurement across Andalusian and Extremaduran solar parks, compressing interconnection timelines and reshaping developer capital deployment cycles.
Growth Catalysts
- REPowerEU Targets:EU Green Deal alignment reinforces domestic renewable deployment mandates that accelerate permitting timelines for strategic solar zones across Castilla-La Mancha.
- High-Irradiance Zones:Concentrated project pipelines in Andalusia and Extremadura exploit superior land availability and solar resource density to drive down levelized cost structures.
- Auction Mechanisms:Spain's Ministry for Ecological Transition and Demographic Challenge shapes project economics through competitive procurement frameworks that de-risk developer returns.
Market Restraints
- Polysilicon Supply Concentration:Upstream crystalline silicon feedstock dependence on Asian refining capacity exposes Spanish EPCs to input cost volatility and logistics bottlenecks.
- Agricultural Water Restrictions:Regional land-use conflicts in southern provinces limit site selection criteria for thermal-solar hybrid configurations requiring cooling water access.
- Grid Interconnection Queues:CNMC oversight of transmission tariff structures creates locational return disparities that strand projects in lower-priority network zones.
Strategic Opportunities
- Behind-the-Meter Commercial:Distributed generation economics are improving for Spanish manufacturing and logistics facilities seeking to isolate from wholesale price volatility.
- Molten-Salt Storage Convergence:Concentrated solar power retains structural relevance in utility-scale configurations incorporating thermal storage for dispatchable evening output.
- Substation Infrastructure Gaps:Technical specialization in medium-voltage infrastructure creates white space for EPCs occupying niches that larger IPPs routinely outsource.
Industry Challenges
- Electrical Grid Integration Complexity:Synchronous inverter deployment and reactive power management require specialized commissioning expertise that outpaces Spanish technical training pipeline output.
- Land-Use Permitting Variability:Municipal zoning inconsistencies across autonomous communities fragment project development timelines and inflate pre-construction carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Solar Energy Market |
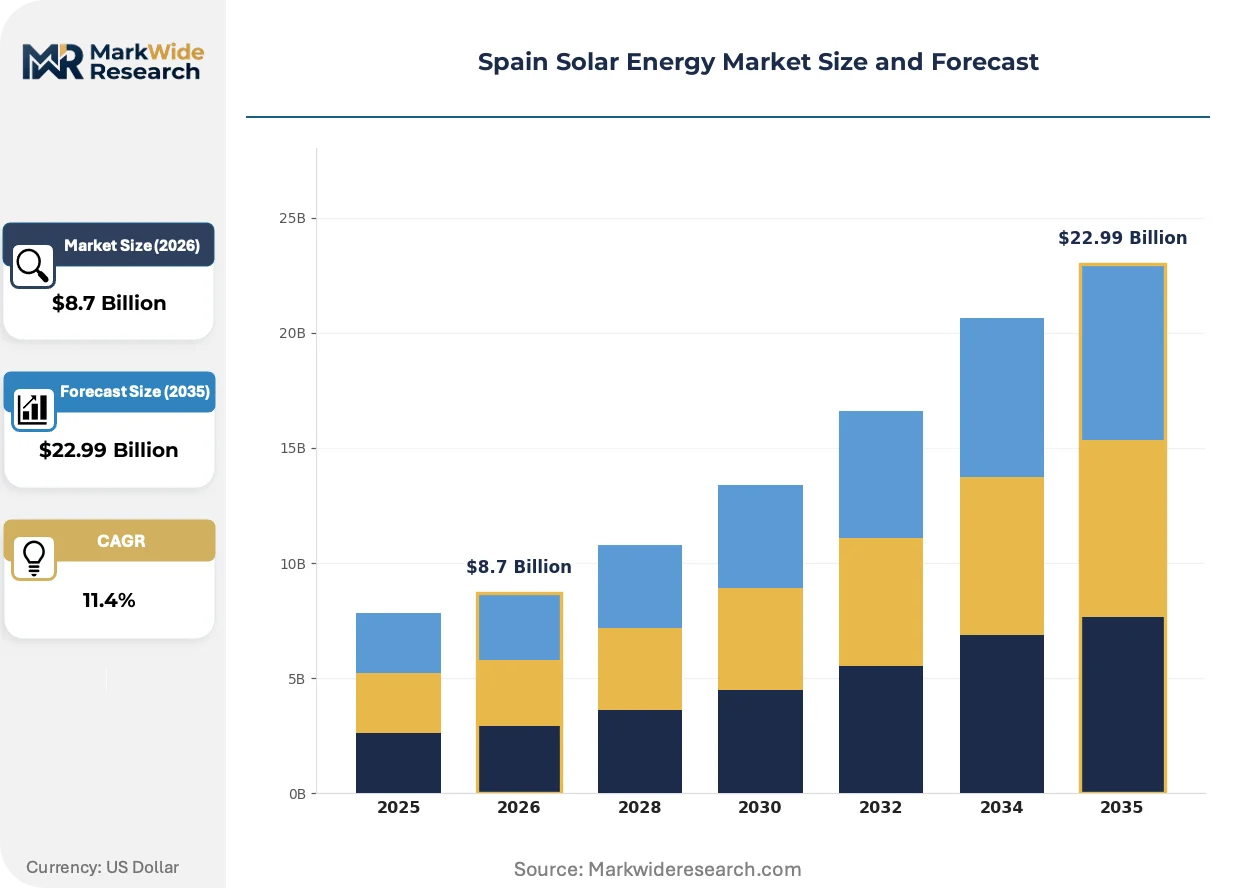
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Photovoltaic, Concentrated Solar Power, Thin-Film, Bifacial End User: Residential, Commercial, Industrial, Utility Installation Type: On-Grid, Off-Grid, Hybrid, Community Power Capacity: Small Scale, Medium Scale, Large Scale, Utility-Scale |
| Companies Covered | Prodiel, Zelestra, Iberdrola, Lightsource BP, Enel Green Power, ACCIONA Energía, Matrix Renewables, SSE Renewables, Avangrid Renewables, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Solar Energy Market Strategic Shifts
Bifacial photovoltaic modules and automated robotic cleaning systems are compressing operational expenditure profiles while Spanish developers pursue hybrid configurations that co-locate solar generation with battery storage or green hydrogen electrolysis.
Monocrystalline PERC and TOPCon cell architectures are electrifying module efficiency benchmarks above twenty-two percent in utility-scale deployments. Spanish IPPs operating in Extremadura and Andalusia are specifying these higher-wattage modules to reduce land intensity per megawatt installed. The technology is electrifying balance-of-system cost structures by cutting racking, cabling, and labor requirements per unit of capacity.
EU Green Deal implementation through delegated acts on renewable energy deployment is tightening sustainability criteria for module supply chains. Spanish project financiers now require carbon footprint documentation and forced-labor-free certifications that filter out lower-tier Asian manufacturers. Domestic developers are responding by diversifying procurement toward European-tier panel suppliers with verifiable ESG credentials.
Power purchase agreement structures are fragmenting as offtake buyers demand shorter tenors and more flexible volume scheduling. Large Spanish industrial consumers in the chemicals and metals sectors are negotiating virtual PPAs that separate physical delivery from financial hedging. This behavioral shift concentrates in Basque Country and Catalonia, where energy-intensive manufacturing clusters possess sufficient credit quality to support bespoke contract engineering.
Spain Solar Energy Market Segmentation
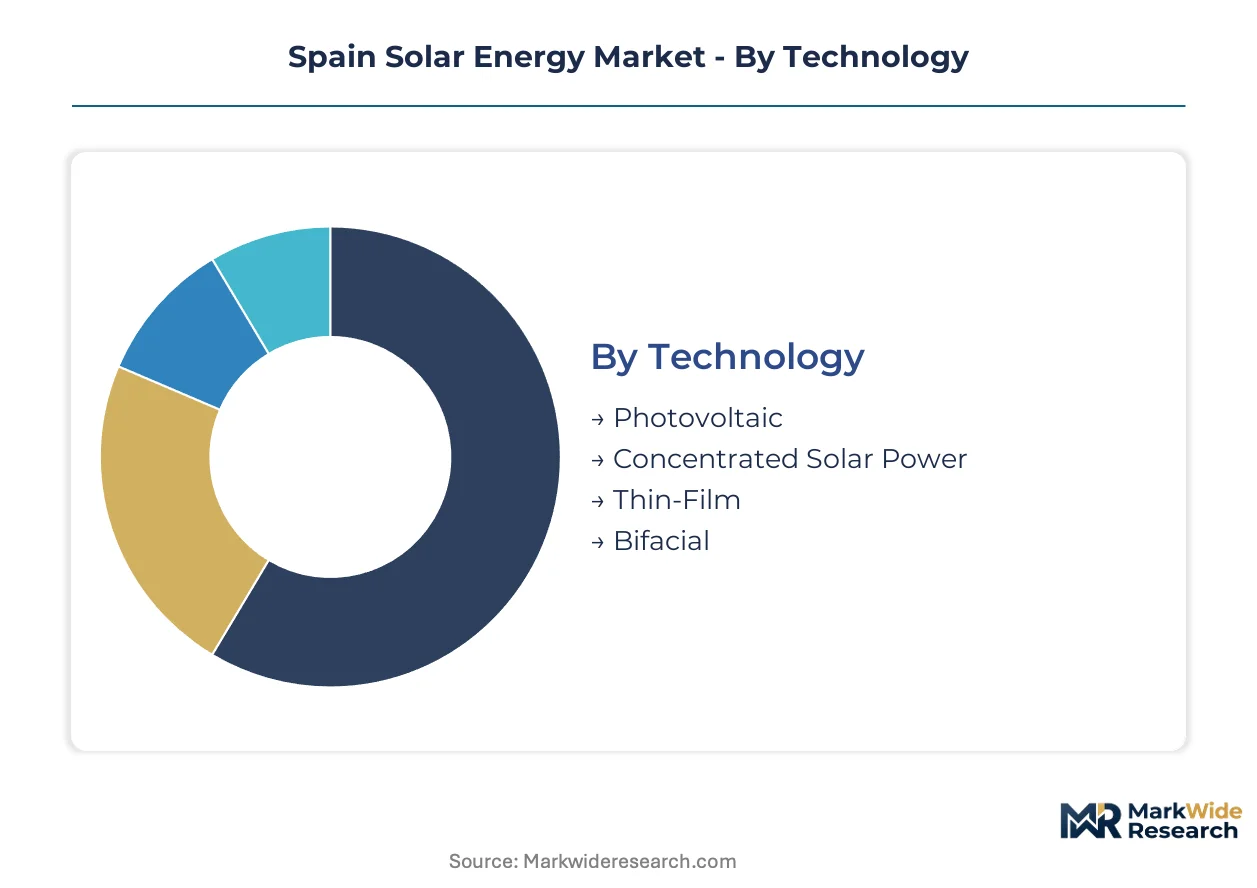
Technology differentiation determines capital efficiency and dispatchability profiles across Spanish solar deployments. Developers align segment selection with grid-access priority zones and offtake contract structures.
Technology:
Upgrade cycles favor higher-efficiency architectures as developers replace aging fixed-tilt installations with advanced module technologies.
- Photovoltaic:Monocrystalline silicon arrays with PERC or TOPCon cell architectures dominate new capacity. Utility-scale procurement in Extremadura specifies modules exceeding twenty-two percent efficiency to compress land intensity per megawatt.
- Concentrated Solar Power:Parabolic trough and solar tower configurations incorporate molten-salt thermal storage for dispatchable evening output. Andalusian developers exploit this segment where grid operators prioritize schedulable renewable capacity.
- Thin-Film:Cadmium telluride and copper indium gallium selenide modules occupy niche applications with high temperature coefficients or flexible mounting requirements.
- Bifacial:Dual-sided energy capture from reflected irradiance improves yield in high-albedo environments like arid southern provinces.
Volume placements concentrate in Photovoltaic; the faster expansion belongs to Bifacial.
End User:
Customer type segmentation reveals divergent procurement patterns between price-takers and price-makers in Spanish electricity markets.
- Utility:Grid-scale developers auction into national procurement frameworks administered by Spain's Ministry for Ecological Transition. These actors control interconnection queue positioning through strategic land banking in Castilla-La Mancha.
- Industrial:Energy-intensive manufacturing clusters in Basque Country and Catalonia negotiate virtual PPAs that isolate operations from wholesale price volatility. Chemicals and metals processors drive behind-the-meter demand.
- Commercial:Logistics facilities and retail distribution centers exploit improving distributed generation economics for rooftop and carport installations.
- Residential:Self-consumption regulations and net metering structures shape deployment in urban peripheries and vacation property markets.
Volume placements concentrate in Utility; Commercial is climbing the fastest.
Installation Type:
Grid-connection status determines regulatory pathway complexity and revenue certainty for Spanish project sponsors.
- On-Grid:Synchronous inverter deployment connects generation to transmission infrastructure under CNMC tariff oversight. This segment captures the dominant share of capital deployment.
- Hybrid:Co-located battery storage or electrolyzer integration addresses grid curtailment risk and captures price arbitrage opportunities in intraday markets.
- Off-Grid:Isolated industrial loads in mining and agricultural processing operate without transmission access.
- Community:Shared ownership structures aggregate residential and small commercial subscribers under collective self-consumption frameworks.
Volume placements concentrate in On-Grid; Hybrid is gaining share fastest.
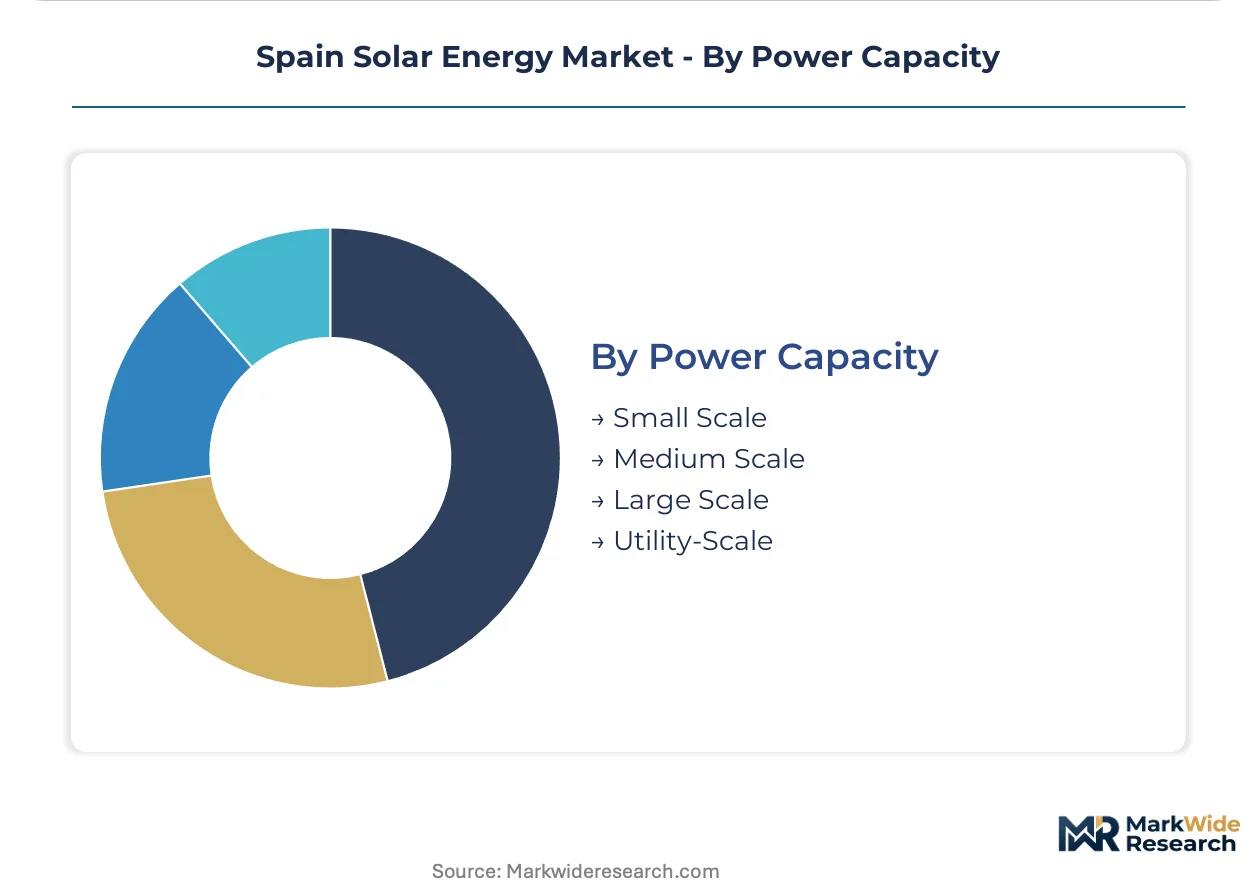
Power Capacity:
Scale tier segmentation maps directly to permitting authority and grid interconnection voltage levels across autonomous communities.
- Utility-Scale:Installations exceeding fifty megawatts connect at high voltage and compete in national auctions. Streamlined permitting under REPowerEU alignment accelerates pipeline development in strategic solar zones.
- Large Scale:Twenty-to-fifty megawatt projects occupy a middle tier with regional permitting and distribution-level interconnection.
- Medium Scale:Five-to-twenty megawatt installations serve commercial offtakers and industrial microgrids.
- Small Scale:Sub-five megawatt systems dominate residential and small commercial rooftop deployment.
Volume placements concentrate in Utility-Scale; Medium Scale shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silica sand deposits in Castile and León anchor module glass supply chains for Spanish photovoltaic manufacturing, while high-purity quartz from Extremadura feeds domestic crucible production for polysilicon refining.
Andalusia
Concentrated solar power developers exploit Guadalquivir Valley irradiance levels exceeding two thousand kilowatt-hours per square meter annually. The Junta de Andalucía administers strategic solar zone designations that compress environmental impact assessment timelines. Seville and Córdoba host engineering consortia specializing in parabolic trough assembly and molten-salt thermal storage integration.
Extremadura
Utility-scale photovoltaic pipelines concentrate on the Llanos de Cáceres and La Serena plain where land prices remain below Castilian averages. Regional government auctions under the Plan de Recuperación allocate grid-access priority points to projects above fifty megawatts. Mérida and Badajoz serve as logistics hubs for module staging and EPC workforce mobilization.
Castilla-La Mancha
Flat topography and minimal agricultural competition enable gigawatt-scale solar park configurations across Toledo and Ciudad Real provinces. The Ministry for Ecological Transition and Demographic Challenge designates this territory as a renewable energy acceleration zone under REPowerEU implementation. Puertollano anchors industrial demand through green hydrogen electrolyzer projects co-located with solar generation.
Catalonia
Behind-the-meter commercial installations accelerate for chemicals and automotive suppliers seeking price stability outside wholesale market volatility. The Catalan Energy Institute streamlines distributed generation permitting for rooftop and carport configurations. Barcelona and Tarragona host corporate PPA negotiation clusters serving energy-intensive manufacturing.
Basque Country
Industrial self-consumption dominates deployment as steel and aluminum processors negotiate virtual power purchase agreements with independent power producers. The Basque Energy Entity coordinates grid interconnection for medium-scale hybrid installations incorporating battery storage. Bilbao and Vitoria-Gasteiz concentrate financial structuring expertise for synthetic renewable energy certificate transactions.
Spain Solar Energy Market Competitive Environment
Global majors compete with regional champions across EPC contracting and grid interconnection control. The vendor structure concentrates around integrated utilities with captive development pipelines, specialized infrastructure contractors, and international IPPs with Spanish auction exposure. Three archetypes dominate: utility-developers controlling land banking and transmission queue positioning, EPC specialists commanding substation and medium-voltage technical niches, and European majors leveraging balance-sheet scale for merchant risk absorption. Competitive dynamics center on strategic land banking in high-irradiance zones and backward integration into grid infrastructure construction.
Within the utility-developer tier, Iberdrola and ACCIONA Energía exemplify integrated models that internalize interconnection risk through in-house civil engineering capabilities. Prodiel occupies a technical specialist position focused on substation and medium-voltage infrastructure that larger IPPs routinely outsource. These three entities anchor the competitive structure while Zelestra and Matrix Renewables represent international developers competing for auction allocation under national procurement frameworks.
| Leading Market Players |
|---|
| Prodiel |
| Zelestra |
| Iberdrola |
| Lightsource BP |
| Enel Green Power |
| ACCIONA Energía |
| Matrix Renewables |
| SSE Renewables |
| Avangrid Renewables |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal sustainability mandates are forcing Spanish project financiers to demand carbon footprint documentation and forced-labor-free certifications that filter procurement toward European-tier panel suppliers, compressing margins for EPCs locked into Asian sourcing contracts and reshaping competitive bidding dynamics across utility-scale auctions.
Pricing Analysis
Warranty and O&M service bundling now separates premium EPC bids from unbundled commodity offerings in Spanish solar tenders. Three-tier pricing structure across premium, standard, and economy levels tracks module efficiency grades and certification tiers, with TOPCon architectures commanding premiums over PERC equivalents. Pricing pressure stems from polysilicon input cost volatility and logistics bottlenecks tied to Asian refining capacity. Utility-scale developers with balance-sheet scale exhibit lowest price sensitivity; distributed commercial installers face acute margin compression.
Supply Chain Analysis
Single-source vulnerability sits with Chinese polysilicon refining capacity that feeds Spanish module assembly through Southeast Asian cell manufacturing hubs. Crystalline silicon wafers and silver metallization pastes draw from concentrated East Asian supply bases. Tariff exposure on Chinese-origin components creates structural risk for EPCs without alternative sourcing frameworks. Distribution runs through Iberian logistics hubs at Valencia and Barcelona with final-mile staging to Andalusian and Extremaduran project sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's solar market is becoming a vertical-integration race where control over substation construction and grid interconnection timelines determines auction success, with players pursuing backward integration into medium-voltage infrastructure to capture margin pools that pure developers forfeit.
For Market Incumbents: Anchor competitive position through captive civil engineering capabilities that compress construction schedules and reduce third-party EPC dependency. ACCIONA Energía's in-house infrastructure model demonstrates how backward integration into substation construction insulates against interconnection queue delays. Prioritize land banking in Castilla-La Mancha acceleration zones where REPowerEU streamlined permitting creates first-mover advantage. Defend against international IPP entrants by controlling transmission tariff structures through strategic grid-access point positioning. For New Entrants and Emerging Players: Capture white space in medium-voltage infrastructure specialization and hybrid storage integration where larger utilities outsource technical execution. The substation EPC niche that Prodiel occupies offers penetrable entry points for technical specialists with electrical commissioning expertise. Target behind-the-meter commercial segments in Catalonia and Basque Country where industrial virtual PPA demand outpaces utility-scale auction competition. Establish go-to-market credibility through EPC partnerships with established grid operators rather than direct auction bidding. For Investors and Strategic Acquirers: Re-rating potential sits with integrated utility-developers given their control of interconnection timelines and land banking pipelines that accelerate project monetization. Long-term viability favors entities with backward integration into grid infrastructure construction and captive development pipelines rather than pure merchant developers. Acquisition target archetype: EPC specialists with medium-voltage substation capabilities and established CNMC relationships. Signal to watch: auction allocation shifts toward hybrid storage-mandated tenders that favor integrated developers with battery supply chain access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substation Infrastructure | Control over CNMC interconnection timelines compresses project development cycles and captures EPC margin pools. |
| Hybrid Storage Co-location | Battery integration addresses grid curtailment risk and captures intraday price arbitrage in Spanish electricity markets. |
| Green Certification Program | EU Green Deal alignment filters procurement toward European-tier suppliers with verifiable ESG credentials. |
| Strategic Land Banking | Priority positioning in Castilla-La Mancha acceleration zones secures streamlined permitting under REPowerEU implementation. |
| Virtual PPA Structuring | Bespoke contract engineering for Basque and Catalan industrial offtakers isolates developers from merchant price exposure. |
Study Parameters
Independent corroboration across EPC contractor interviews, grid operator consultations, and project finance documentation underwrites the qualitative findings. Primary fieldwork engaged utility planning officers at Iberdrola and Enel Green Power, IPP project developers active in Extremadura auctions, substation specialists at Prodiel, and CNMC regulatory affairs leads. Secondary validation drew from Spanish Ministry for Ecological Transition auction records, CNMC transmission tariff filings, EU Green Deal delegated acts on renewable energy deployment, and REPowerEU implementation progress reports. Bottom-up project pipeline aggregation triangulates against top-down market sizing from national capacity addition forecasts.
Comparable-period anchoring to historical auction allocation patterns and installed capacity trends across the analysis window informs the projection framework. Segmentation modeling spans technology architecture, end-user procurement type, installation grid-connection status, and power capacity tier. CAGRs derive from regression analysis of auction pricing trajectories and module cost decline curves. Key forecast inputs include polysilicon spot price volatility assumptions and CNMC queue reform implementation pace.
The model holds under sustained REPowerEU permitting acceleration and stable EU-China trade frameworks; deviation in tariff exposure on Chinese module components or grid interconnection queue backlogs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Asia-Pacific Bifacial Solar Market
Solar Power Systems
Middle-East and Africa Distributed Solar Power Generation Market
Solar Power Systems
Switzerland Solar Energy Market
Solar Power Systems
Denmark Solar Energy Market
Solar Power Systems
Italy Solar Energy Market
Solar Power Systems
South America Rooftop Solar Market
Solar Power Systems
North America Rooftop Solar Market
Solar Power Systems
Solar Shingles Market
Solar Power Systems
Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Photovoltaic Glass Market
Solar Power Systems
Solar Bench Market
Solar Power Systems
Outdoor Solar LED Market
Solar Power Systems
Bifacial Solar Panels Market
Solar Power Systems
Colombia Solar Energy Market
Solar Power Systems
North America Single Axis Solar Tracker Market
Solar Power Systems
GCC Solar Photovoltaic (PV) Market