

AC Residential Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
AC Residential Switchgear Market Insights
Market Context
China is narrowing its cost advantage in AC residential switchgear production as energy transition policies reshape manufacturing economics across Asia. Schneider Electric leverages extensive distribution networks to sustain leadership in European residential electrical infrastructure. Siemens anchors its position through deep R&D investment in digital switchgear platforms for smart home ecosystems. ABB competes aggressively in modular housing segments with compact breaker designs tailored for space-constrained installations.
Technical Definition and Segments
AC residential switchgear encompasses protective and control apparatus—including circuit breakers, fuses, and disconnect switches—engineered for alternating current systems rated typically below 1000 volts, designed to isolate faults and manage electrical distribution within dwelling units. Circuit breakers dominate product type revenue due to mandatory resettable protection requirements in modern building codes, while solid state technology segments gain traction from silent operation and extended cycle life in smart panel applications. Multi-family units represent the fastest-growing application dimension as urban density policies accelerate apartment construction in metropolitan zones, and residential contractors constitute the most concentrated end user channel with direct specification influence over brand selection.
Regulatory Framework
UL 489 and IEC 61439 standards govern breaker performance and assembly verification, compelling manufacturers to maintain dual certification portfolios for transatlantic market access. The EU Green Deal and national electrification mandates in Germany and France tighten efficiency thresholds for residential distribution equipment. Stakeholders must monitor evolving smart grid interoperability requirements as utility-side connectivity becomes a procurement criterion rather than an optional feature.
Market Dynamics
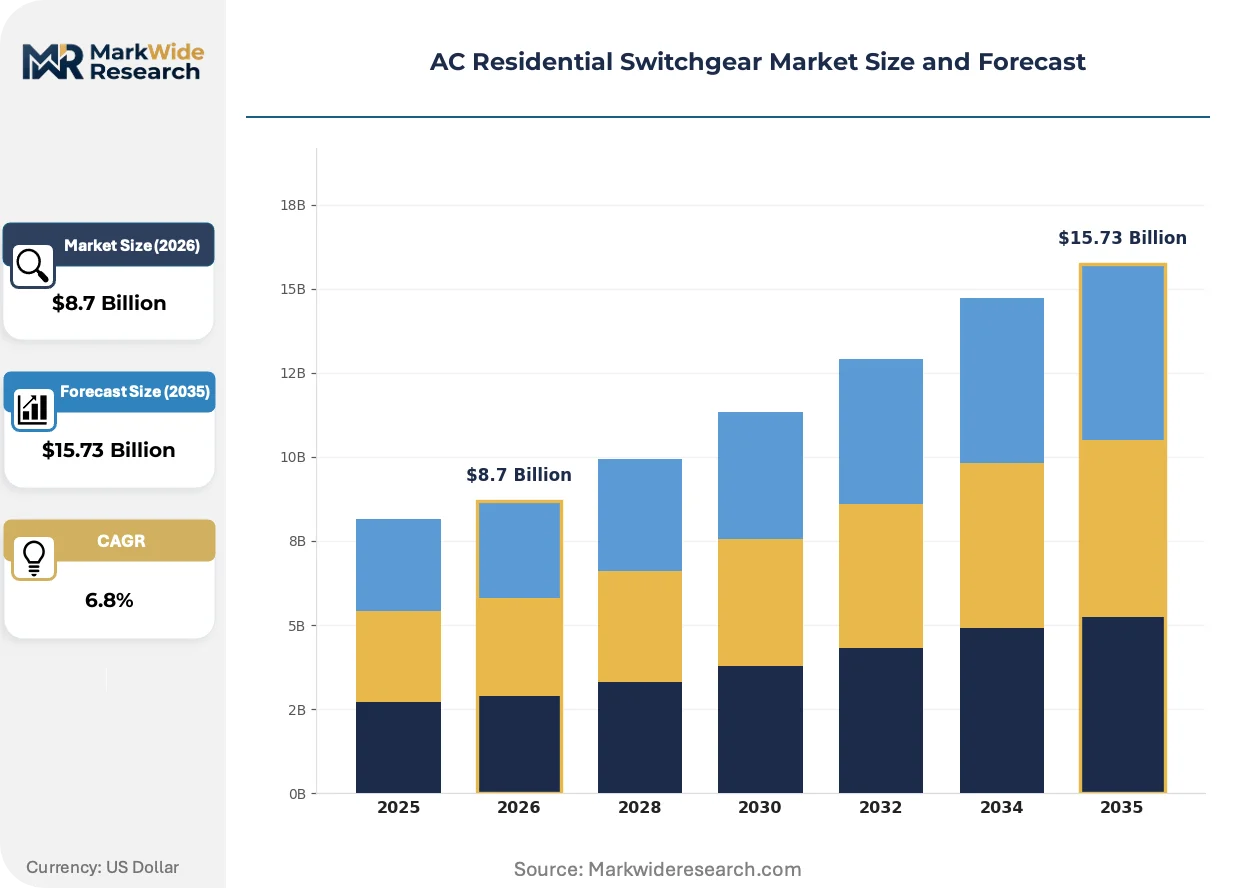
Residential electrification mandates are compressing replacement cycles for legacy fuse-based panels across OECD housing stocks, forcing incumbent manufacturers to reconfigure product portfolios around smart-ready architectures.
Growth Catalysts
- EU Green Deal efficiency mandates:Germany and France now require minimum performance thresholds for residential distribution boards, compelling wholesale panel upgrades in pre-2000 housing stock.
- Smart home integration protocols:Matter and KNX standards are creating specification pull for circuit breakers with embedded metering and remote trip functionality in single-family new construction.
- Urban density policies:Multi-family permitting accelerations in Shanghai, Mumbai, and São Paulo are concentrating demand for compact, stackable switchgear designs.
Market Restraints
- Copper and silver price volatility:Contact and busbar materials account for 35-45% of variable production costs, exposing margins to LME commodity swings.
- Semiconductor supply concentration:Taiwan and South Korea dominate silicon carbide MOSFET supply for solid-state breaker prototypes, creating single-source risk for digital switchgear roadmaps.
- IEC 61439-3 testing backlog:Assembly verification protocols for arc-fault detection devices now extend lead times by 8-14 weeks at notified bodies.
Strategic Opportunities
- Retrofit-ready smart panels:US and German contractors are specifying drop-in monitoring modules that upgrade existing enclosures without full replacement.
- Grid-interactive demand response:FERC Order 2222 compliance is opening utility procurement channels for residential load control switchgear in California, Texas, and New York.
- Prefabricated electrical rooms:Modular construction integrators in Sweden, the Netherlands, and Singapore are sourcing factory-tested switchgear skids for high-rise residential towers.
Industry Challenges
- Arc-fault detection calibration:Nuisance tripping rates in early AFCI generations have eroded contractor confidence, requiring field-level firmware updates and technician retraining.
- Legacy enclosure interoperability:DIN rail dimensional variations across 1970s-1990s European installations complicate smart breaker retrofits without full panel replacement.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AC Residential Switchgear Market Trends and Innovations
Digitalization is collapsing the functional boundary between protective devices and energy management systems, embedding metering, communication, and control into hardware previously valued only for fault interruption.
Solid-state circuit breakers based on silicon carbide power semiconductors are collapsing the mechanical arc-interruption paradigm that has dominated residential protection for a century. High-end smart home integrators in California, Germany, and Australia are specifying these devices for silent operation and 100,000-cycle endurance. The technology is collapsing the traditional separation between switchgear and power electronics, forcing incumbents to acquire semiconductor packaging capabilities or cede premium segments.
REACH substance restrictions on halogenated flame retardants are compelling resin reformulation for breaker housings and busbar supports across European manufacturing. Compounders in Germany and Belgium are qualifying phosphorus-nitrogen intumescent systems to maintain UL 94 V-0 ratings without brominated additives. Asian exporters to the EU are retooling molding lines ahead of 2026 sunset dates, with compliance costs compressing margin structures for standard-grade product families.
Electrical contractor purchasing cooperatives are consolidating specification influence in US and Canadian residential construction, displacing traditional wholesale distributor primacy. These buying groups aggregate multi-state volume to extract price concessions and technical service commitments directly from manufacturers. The shift is most visible in Texas, Florida, and Arizona metro markets where production homebuilders account for 60%+ of single-family completions.
AC Residential Switchgear Market Segmentation
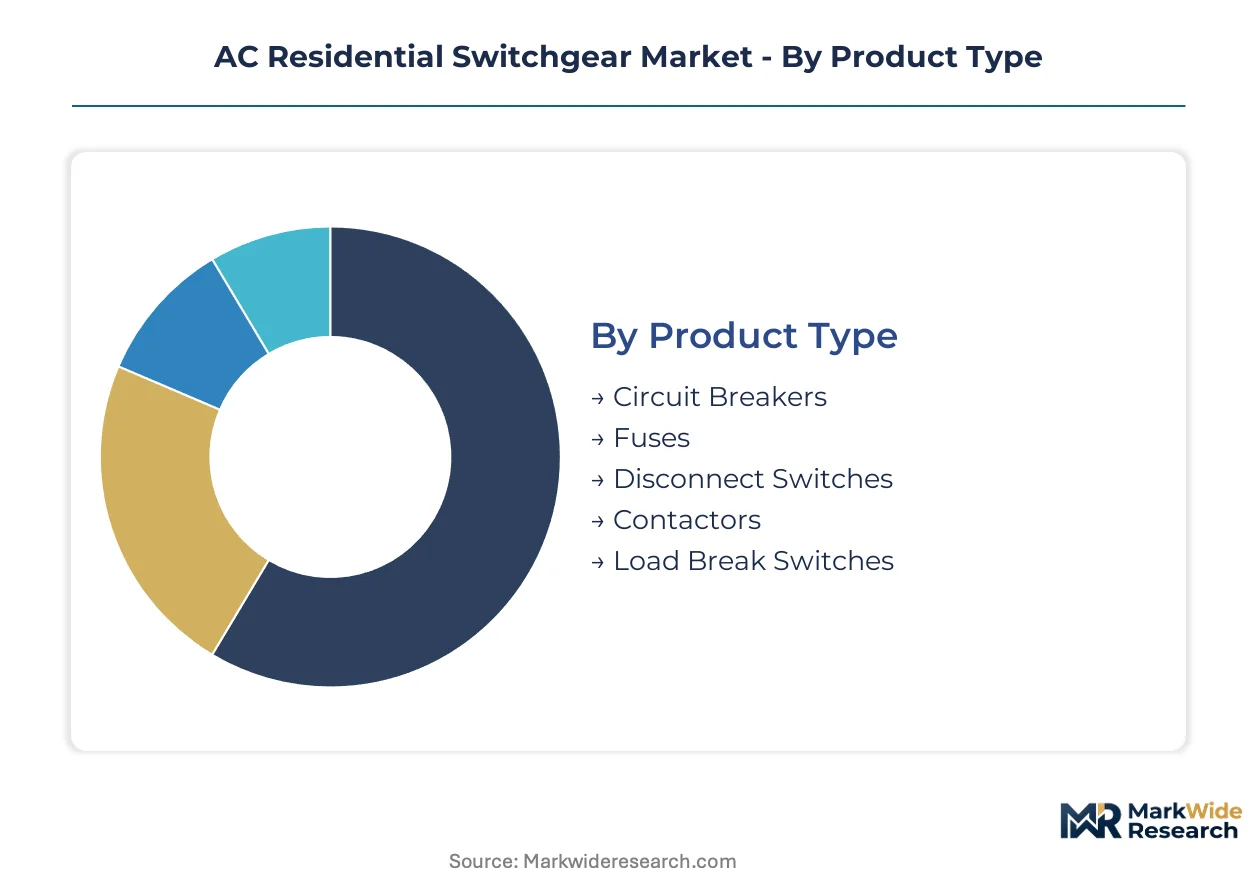
Segmentation in AC residential switchgear reveals divergent replacement rhythms across hardware categories. Cycle times range from decades for passive components to under ten years for digitally integrated breakers, reshaping inventory and service models for channel partners.
Product Type:
Circuit breakers turn over fastest where smart home retrofits accelerate, while fuses linger in legacy installations with minimal upgrade pressure.
- Circuit Breakers:Resettable thermal-magnetic and electronic trip units constitute the functional core of modern residential panels. Demand concentrates in single-family new construction across Texas, Florida, and Arizona where IEC 61439-3 arc-fault compliance is mandatory and contractors specify smart-ready platforms.
- Fuses:One-time protection elements persist in pre-1980s housing stock and accessory structures where code grandfathering applies. Replacement cycles extend 25-40 years, concentrating maintenance demand in rural Germany and northeastern US markets with aging housing inventories.
- Disconnect Switches:Visible-blade isolation devices serve HVAC and solar inverter applications with 15-20 year service intervals.
- Contactors:Electromechanical switching elements manage heavy loads in heat pump and EV charger circuits with moderate replacement frequency.
- Load Break Switches:Manual switching devices for sub-panel isolation carry the longest cycles, typically outlasting enclosure lifespans.
Circuit breakers dominate installed base. Fuses are where expansion concentrates only in emerging market rural electrification.
Technology:
Cost tiers separate mature electromechanical platforms from premium solid-state architectures with semiconductor content driving price multiples.
- Solid State:Silicon carbide MOSFET-based breakers eliminate mechanical arc interruption entirely. California and German smart home integrators specify these for silent operation and 100,000-cycle endurance in high-end residential automation.
- Electromechanical:Conventional magnetic trip mechanisms with bimetallic thermal elements serve volume markets with proven reliability and minimal electronics exposure. Demand concentrates with price-sensitive residential contractors in India and Brazil where total installed cost governs procurement.
- Thermal Magnetic:Combined sensing approaches dominate standard-grade residential breakers with balanced cost-performance positioning.
- Electronic:Microprocessor-based trip units enable precise curve shaping and communication integration for smart panel applications.
- Vacuum:Sealed interrupter technology penetrates higher-current residential sub-feeds and small commercial borderline applications.
Electromechanical platforms anchor volume production. Solid state is climbing the fastest as semiconductor packaging costs decline and smart home specification tightens.
Application:
Urban density policies are compressing development timelines for multi-family vertical construction while single-family permitting faces elongated entitlement processes.
- Multi-Family Units:Apartment and condominium towers require stackable, compact switchgear with centralized metering integration. Shanghai, Mumbai, and São Paulo permitting accelerations are concentrating specification activity for DIN-rail assemblies with 125A main breaker capacity.
- Single-Family Dwellings:Detached homes drive smart panel adoption where homeowners control energy visibility. Demand clusters in US Sun Belt metros and Australian suburban corridors where solar-plus-storage integration requires grid-interactive protection.
- Modular Homes:Factory-built housing demands pre-tested electrical skids with standardized breaker configurations for rapid site installation.
- Accessory Buildings:Garages, workshops, and detached ADUs carry lighter protection requirements with slower upgrade cycles tied to main dwelling renovations.
Single-family dwellings retain the largest installed base. Multi-family units are gaining share fastest as metropolitan zoning reforms accelerate apartment construction.
End User:
Customer type determines specification authority, with contractors wielding direct brand influence while distributors battle purchasing cooperative consolidation.
- Residential Contractors:Licensed electricians and electrical subcontractors specify breaker brands at the point of installation. US purchasing cooperatives in Texas and Florida now aggregate multi-state volume to extract manufacturer concessions, displacing traditional wholesale primacy.
- Electrical Distributors:Counter-based supply houses maintain inventory depth and technical support relationships. German and French distributors face margin compression from direct contractor-manufacturer contracting.
- Homebuilders:Production builders standardize panel specifications across subdivisions with multi-year supply agreements.
- Property Managers:Multi-family operators prioritize lifecycle cost and tenant safety compliance over upfront equipment cost.
Residential contractors control active specification. Electrical distributors are where channel conflict concentrates as purchasing cooperatives restructure procurement hierarchies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American bulk power grid interconnects with Canadian and Mexican systems through 40+ high-voltage tie lines, positioning the United States as the central demand node for residential switchgear upgrades tied to electrification mandates.
United States
Production homebuilders in Texas, Florida, and Arizona drive specification volume for smart-ready panels with AFCI compliance. FERC Order 2222 opens utility procurement channels for grid-interactive residential load control in California, Texas, and New York. Contractor purchasing cooperatives in the Sun Belt now aggregate multi-state volume to extract manufacturer concessions, displacing traditional wholesale distributor primacy in Phoenix, Dallas, and Tampa metro markets.
Germany
The EU Green Deal efficiency mandates compel wholesale panel upgrades in pre-2000 housing stock across Bavaria and North Rhine-Westphalia. ECHA REACH substance restrictions on halogenated flame retardants force resin reformulation for breaker housings ahead of 2026 sunset dates. Electrical distributors in Frankfurt and Munich face margin compression from direct contractor-manufacturer contracting as procurement hierarchies restructure.
China
Urban density policies in Shanghai accelerate apartment construction requiring compact, stackable switchgear with centralized metering integration. MIIT dual carbon goals reshape manufacturing economics and narrow cost advantages in production. Pearl River Delta factories retool molding lines to meet EU REACH compliance for export-bound product families.
India
Rural electrification programs under the CEA expand fuse-based protection in legacy installations across Maharashtra and Gujarat. BIS certification requirements tighten for imported switchgear assemblies. Mumbai and Pune metropolitan permitting accelerations concentrate demand for DIN-rail assemblies with 125A main breaker capacity in high-rise residential towers.
Australia
Solar-plus-storage integration in New South Wales and Victoria requires grid-interactive protection for residential energy systems. State-level building codes tighten arc-fault detection requirements in new construction. Sydney and Melbourne smart home integrators specify solid-state breakers for silent operation in premium residential automation projects.
AC Residential Switchgear Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in a market structure that fragments across electromechanical volume producers and semiconductor-enabled premium entrants. The vendor base clusters around three strategic archetypes: diversified electrical conglomerates with distribution depth, regional specialists with contractor-channel intimacy, and technology insurgents betting on solid-state architectures. Competitive moves concentrate on backward integration into semiconductor packaging and geographic expansion through distributor acquisition.
Within the diversified conglomerate tier, Schneider Electric and Siemens occupy positions as archetypal platform integrators with extensive European distribution networks. ABB anchors the modular housing specialist segment with compact breaker designs. These three exemplify how incumbent scale advantages translate into specification authority across contractor-driven procurement channels.
| Leading Market Players |
|---|
| Schneider Electric |
| Siemens |
| ABB |
| Eaton |
| Legrand |
| Hager Group |
| Hubbell |
| Honeywell |
| Fuji Electric |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Asian molding facilities is compressing margin structures for standard-grade breaker housings and forcing suppliers into volume-discount negotiations with contractor purchasing cooperatives. This utilization dynamic simultaneously erodes pricing power for commodity electromechanical breakers while concentrating premium positioning among semiconductor-enabled solid-state architectures with captive silicon carbide sourcing.
Pricing Analysis
Volume-discount tiering structures dominate procurement between residential contractors and manufacturers, with three-tier pricing separating IEC 61439-3 arc-fault certified smart breakers from standard thermal-magnetic units and economy-grade fuse replacements. Price differentiation hinges on certification grade and after-sales firmware support bundling. Pricing pressure stems from copper and silver commodity volatility on contact materials. Price-sensitive contractors in India and Brazil prioritize total installed cost, while German smart home integrators exhibit minimal sensitivity for silent-operation solid-state specifications.
Supply Chain Analysis
Export-control restrictions on silicon carbide wafer fabrication equipment limit technology transfer to mainland China and constrain supply expansion for solid-state breaker semiconductors. Manufacturing concentrates in Germany, China, and the United States for electromechanical assemblies, with Taiwan and South Korea anchoring silicon carbide MOSFET supply. Raw material dependencies include copper busbar stock, silver contact plating, and phosphorus-nitrogen intumescent resins. Single-source vulnerability permeates semiconductor packaging capabilities. Distribution runs through electrical distributors facing displacement by contractor purchasing cooperatives in Texas and Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state circuit breaker commercialization represents a high-growth disruption as silicon carbide power semiconductors collapse the century-old mechanical arc-interruption paradigm. FERC Order 2222 grid-interactive mandates and EU Green Deal efficiency thresholds accelerate specification pull for digitally integrated protection platforms.
For Market Incumbents: Entrench specification authority through backward integration into silicon carbide semiconductor packaging capabilities or risk ceding premium segments to technology insurgents. Deepen arc-fault detection firmware calibration investments to restore contractor confidence eroded by nuisance tripping incidents. Prioritize certification maintenance for dual UL 489 and IEC 61439 portfolios as assembly verification backlogs extend lead times at notified bodies. For New Entrants and Emerging Players: Pursue retrofit-ready smart panel modules as the most penetrable white-space target, enabling drop-in monitoring upgrades without full enclosure replacement in US and German pre-2000 housing stock. Target multi-family vertical construction in São Paulo and Mumbai where compact DIN-rail assemblies with 125A main breaker capacity face supply constraints. Lead with direct contractor channel engagement bypassing distributor margin extraction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among solid-state breaker manufacturers with embedded metering and remote trip functionality subscriptions. Five-to-ten year viability favors technology insurgents with captive semiconductor packaging capabilities over pure-play electromechanical assemblers exposed to commodity cost compression. Watch silicon carbide MOSFET supply expansion announcements as the critical inflection signal for premium segment penetration timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Packaging Integration | Captive silicon carbide MOSFET supply secures premium solid-state breaker positioning against Taiwan concentration risk. |
| Retrofit-Ready Module Development | Drop-in monitoring compatibility with legacy enclosures captures pre-2000 housing upgrade cycles in Germany and the United States. |
| Dual Certification Portfolio Maintenance | Simultaneous UL 489 and IEC 61439 compliance preserves transatlantic market access amid testing backlog delays. |
| Contractor Cooperative Direct Engagement | Bypassing distributor intermediaries captures margin compression recovery in Texas and Florida production homebuilder markets. |
| Grid-Interactive Load Control Certification | FERC Order 2222 compliance opens utility procurement channels for residential demand response switchgear in California and New York. |
Research Methodology
Initial hypotheses were tested against primary input from residential electrical contractors, electrical distributor procurement managers, smart home integration specialists, and utility demand response program officers, and refined through secondary validation against SEC 10-K filings, IEC standards documentation, FERC order records, and customs trade data. Bottom-up triangulation across product type, technology platform, application segment, and end-user channel dimensions converged with top-down macroeconomic anchoring.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling circuit breaker, fuse, disconnect switch, contactor, and load break switch categories alongside electromechanical, solid-state, thermal magnetic, electronic, and vacuum technology tiers. CAGRs were derived from installation base turnover analysis and replacement cycle compression factors. Forecast inputs incorporated residential electrification mandate timelines and smart home protocol adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by semiconductor packaging specialists or solid-state technology insurgents would shift outcomes. Material shifts in silicon carbide supply expansion, REACH substance restriction enforcement, or contractor cooperative consolidation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.