
 Bio-Based Transformer Oil Market | 2026-2036
Bio-Based Transformer Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based Transformer Oil Market Outlook
Aftermarket fluid testing and reclamation services is rewriting margin capture across the transformer oil value chain. Shell plc leverages its integrated lubricant distribution network to secure utility procurement contracts in mature European markets. Cargill anchors its position through captive supply of high-oleic soybean feedstock for ester production. Nynas AB competes by sustaining refining expertise adapted to bio-hydrocarbon streams.
Bio-based transformer oil comprises triglyceride or synthetic ester formulations with fire points exceeding 300°C and biodegradability rates above 90% in standardized aquatic toxicity tests, serving primarily as dielectric coolant and insulation medium in liquid-filled electrical apparatus. Vegetable oil formulations lead volume shipments due to established supply chains and cost-competitive feedstock access, while synthetic esters command premium positioning in high-voltage transformers where oxidative stability requirements are most stringent. Distribution transformers represent the most penetrated application segment, though renewable generation interconnection is expanding fastest as offshore wind and solar farms specify fire-safe fluids for pad-mounted and underground installations.
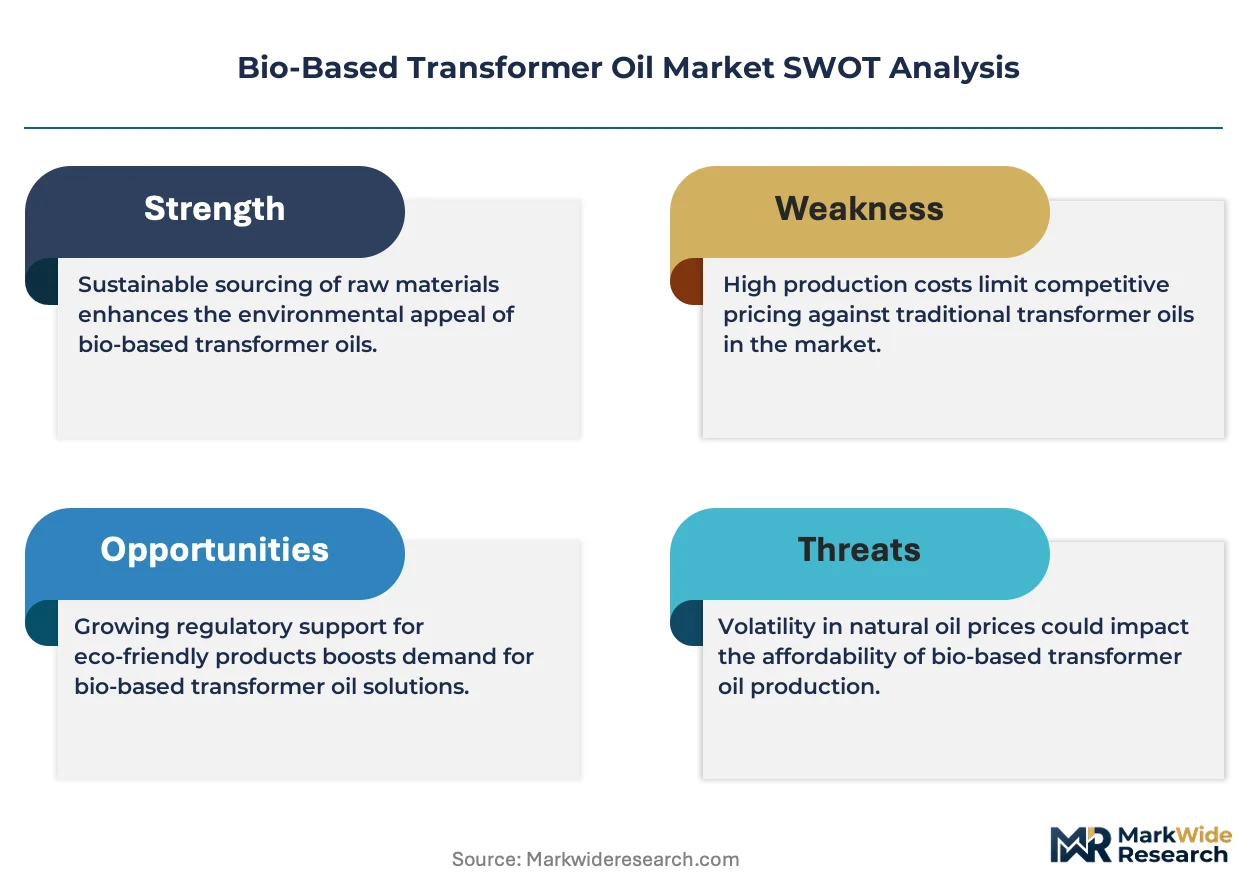
EPA regulations under the Spill Prevention, Control, and Countermeasure program and EU F-Gas Regulation phase-down schedules are accelerating utility migration from mineral oil to biodegradable alternatives, with IEC 61099 and ASTM D6871 certification gates controlling product market access. India's BIS and China's SAMR are developing aligned national standards for ester-based insulating liquids, creating parallel compliance pathways for suppliers. Stakeholders must monitor feedstock price volatility against mineral oil spreads and pre-position for certification harmonization across North American, European, and Asian utility procurement frameworks.
Market Dynamics
Utility procurement mandates under the EU Green Deal and EPA spill-prevention rules are compressing replacement cycles for mineral oil transformers, forcing distributors to reconfigure inventory toward certified ester formulations.
Growth Catalysts
- EU F-Gas Regulation phase-down:Member state utilities face binding reduction targets for fluorinated greenhouse gases, accelerating pad-mounted transformer retrofits with biodegradable dielectric fluids.
- Offshore wind interconnection:Fire-safety specifications for subsea cable terminations and platform substations specify synthetic ester insulation in North Sea development zones.
- High-oleic soybean cultivation:Expanded crop acreage in the US Midwest secures cost-competitive triglyceride feedstock for domestic ester production.
Market Restraints
- Palm oil price volatility:Malaysian and Indonesian export duty fluctuations transmit directly to vegetable-based transformer fluid cost structures.
- Refining capacity concentration:Specialty ester production clusters in northwest Europe create geographic supply vulnerability for Asian utilities.
- Oxidative stability ceiling:Natural ester formulations face performance limits above 275 kV system voltages, restricting penetration in ultra-high-voltage transmission.
Strategic Opportunities
- India rural electrification:The country's national standards body BIS is finalizing ester liquid specifications for distribution transformers serving agricultural load centers.
- Digital transformer monitoring:Integration of dissolved gas analysis sensors with bio-based fluid systems enables predictive maintenance contracts for industrial microgrids.
- Carbon border adjustment:EU CBAM implementation creates preferential positioning for low-emission ester producers against mineral oil imports.
Industry Challenges
- IEC 61099 certification backlog:Testing laboratory capacity constraints extend product qualification timelines for new market entrants.
- Retrofit engineering expertise:Field service technicians require retraining on seal compatibility and thermal management for ester conversions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Based Transformer Oil Market |
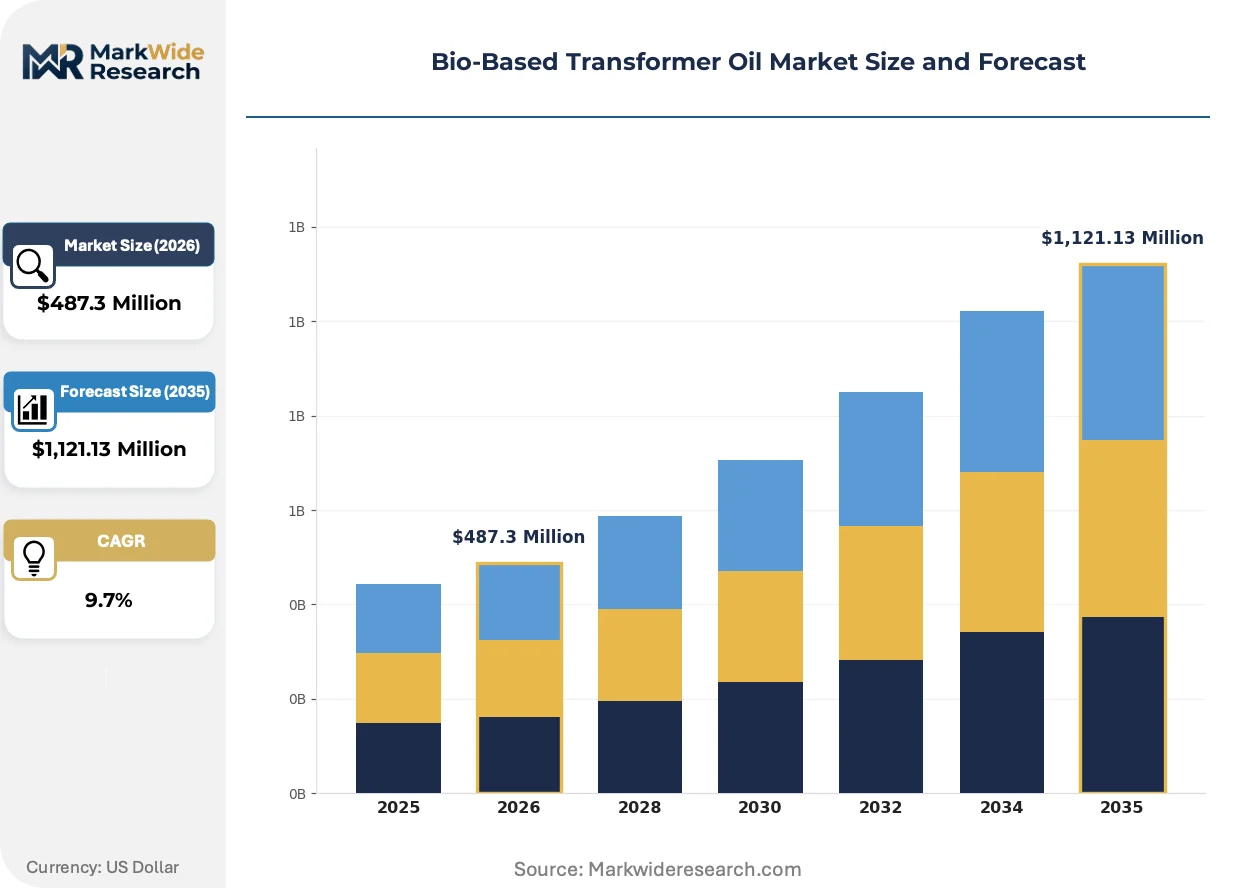
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,121.13 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Oil, Synthetic Esters, Animal Fat, Bio-Oil End User: Utilities, Manufacturing, Renewable Energy, Construction Application: High Voltage Transformers, Distribution Transformers, Industrial Equipment, Renewable Generation Certification: ASTM D6871, IEC 61099, ISO 14001, Others |
| Companies Covered | Shell plc, Cargill, BASF, TotalEnergies, Nynas AB, APAR Industries, Renewable Energy Group, China Petrochemical Corporation, Ergon, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based Transformer Oil Market Strategic Shifts
Formulation chemistry advances and procurement digitization are compressing the traditional mineral-oil-to-ester transition timeline from decades to single-digit years.
Synthetic aromatic ester chemistry is collapsing the historical trade-off between fire safety and oxidative longevity. Offshore wind developers in the North Sea and Taiwan Strait specify these fluids for platform transformers operating in salt-laden, high-humidity environments. The technology is collapsing price premiums that once separated natural and synthetic ester categories.
REACH authorization requirements for medium-chain chlorinated paraffins are forcing reformulation of legacy fire-resistant hydraulic fluids in transformer manufacturing plants. German industrial regulators now classify certain mineral oil alternatives as substances of very high concern. Transformer OEMs in Baden-Württemberg and Bavaria are accelerating supplier audits to exclude restricted chemistries from coating and insulation systems.
Utility purchasing departments now bundle fluid supply with dissolved gas analysis and reclamation services under multi-year performance agreements. Equipment manufacturers in Scandinavia unbundle hardware from fluid provision, creating direct contracting relationships between ester producers and grid operators. This restructuring is most advanced in Denmark and Sweden, where state-owned transmission companies negotiate carbon-intensity clauses into dielectric fluid procurement specifications.
Bio-Based Transformer Oil Market Segmentation
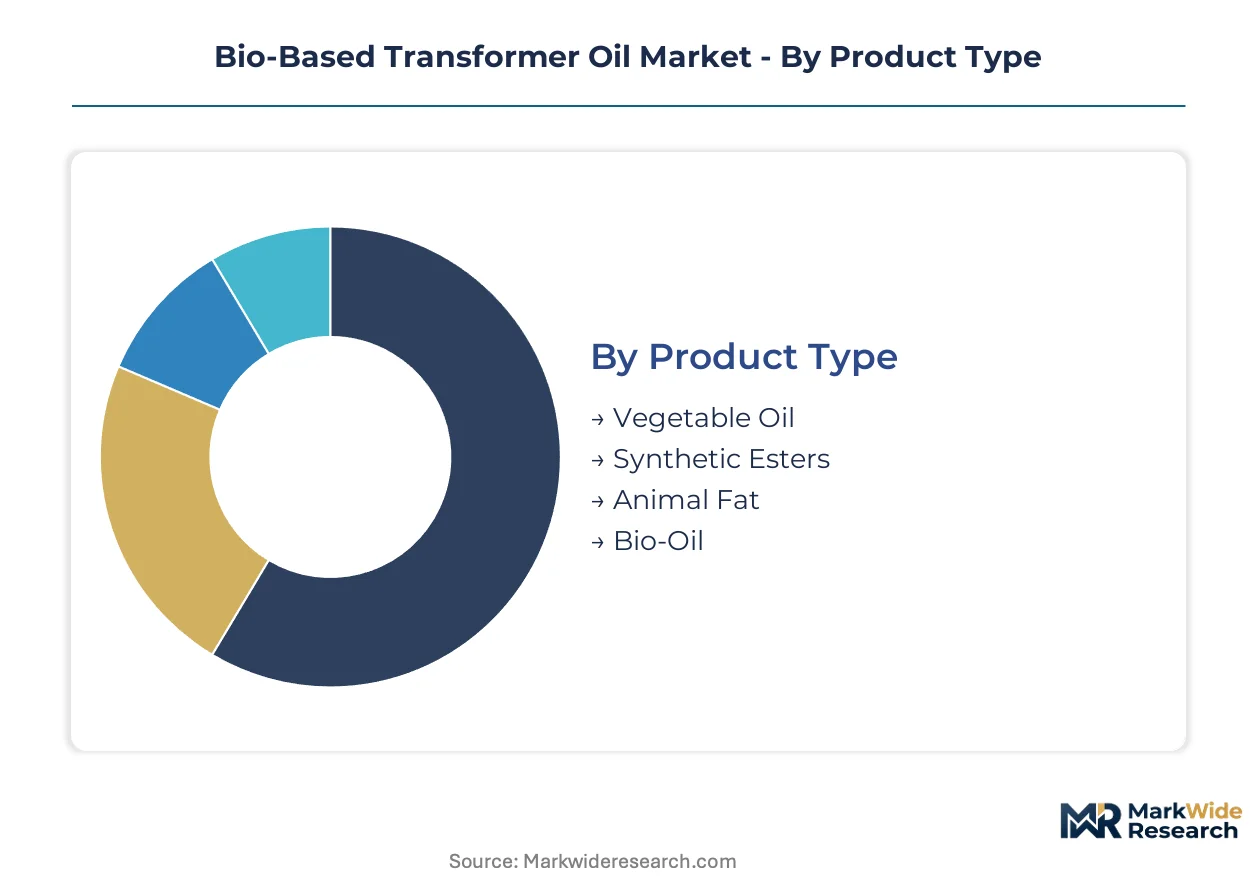
Transformer oil segmentation reveals how formulation chemistry, end-use voltage requirements, and regulatory certification gates partition commercial opportunity. Suppliers must align product portfolios with distinct technical specifications and procurement frameworks governing each segment.
Product Type:
Cost tier stratification separates commodity triglyceride formulations from performance-engineered synthetic esters with divergent feedstock and refining economics.
- Vegetable Oil:Triglyceride formulations derived from high-oleic soybean and rapeseed deliver fire points above 300°C and biodegradability exceeding 90% in OECD 301 testing. Distribution transformer retrofits in Germany and the United States concentrate procurement volume as utilities execute EU Green Deal and EPA SPCC compliance timelines. Feedstock price volatility from Malaysian palm oil duties constrains margin stability for non-captive producers.
- Synthetic Esters:Aromatic and pentaerythritol ester chemistry achieves oxidative stability thresholds required for 275 kV+ transmission infrastructure. Offshore wind interconnection projects in the North Sea specify these fluids for platform substations operating in salt-laden environments. Price premiums over natural esters are compressing as production scale increases.
- Animal Fat:Tallow-based formulations serve niche applications in legacy industrial equipment requiring fire-resistant dielectric fluids with established compatibility profiles.
- Bio-Oil:Pyrolysis-derived hydrocarbons from lignocellulosic biomass remain pre-commercial for transformer applications pending IEC 61099 certification completion.
Vegetable oil commands the established base. The steepest expansion runs through synthetic esters.
End User:
Customer type determines procurement scale, contract duration, and technical service bundling requirements across the value chain.
- Utilities:State-owned and investor-owned grid operators in Denmark and Sweden negotiate multi-year performance agreements bundling fluid supply with dissolved gas analysis and reclamation services. Carbon-intensity clauses now appear in dielectric fluid procurement specifications.
- Renewable Energy:Offshore wind developers and solar farm operators specify fire-safe fluids for pad-mounted and underground installations. Interconnection project timelines drive spot purchasing with accelerated qualification requirements.
- Manufacturing:Industrial microgrids and captive power systems adopt bio-based fluids for fire-safety compliance in densely occupied facilities.
- Construction:Temporary power infrastructure for large-scale projects generates seasonal demand with limited long-term service attachment.
Utilities anchor volume commitments. Renewable energy projects are climbing the fastest.
Application:
Voltage class and installation environment dictate thermal management requirements and fluid specification stringency.
- Distribution Transformers:Pad-mounted and pole-top units below 69 kV represent the most penetrated segment with established retrofit engineering protocols. US Midwest utilities and German municipal operators lead replacement cycle compression.
- High Voltage Transformers:Transmission infrastructure above 230 kV requires synthetic ester formulations with superior oxidative stability. Performance limits above 275 kV restrict natural ester penetration.
- Renewable Generation:Solar inverters and wind turbine step-up transformers specify biodegradable fluids for remote installations with environmental sensitivity.
- Industrial Equipment:Furnace transformers and rectifier units in steel and chemical plants prioritize fire safety over biodegradability in fluid selection.
Distribution transformers hold the installed base. Renewable generation applications are gaining share fastest.
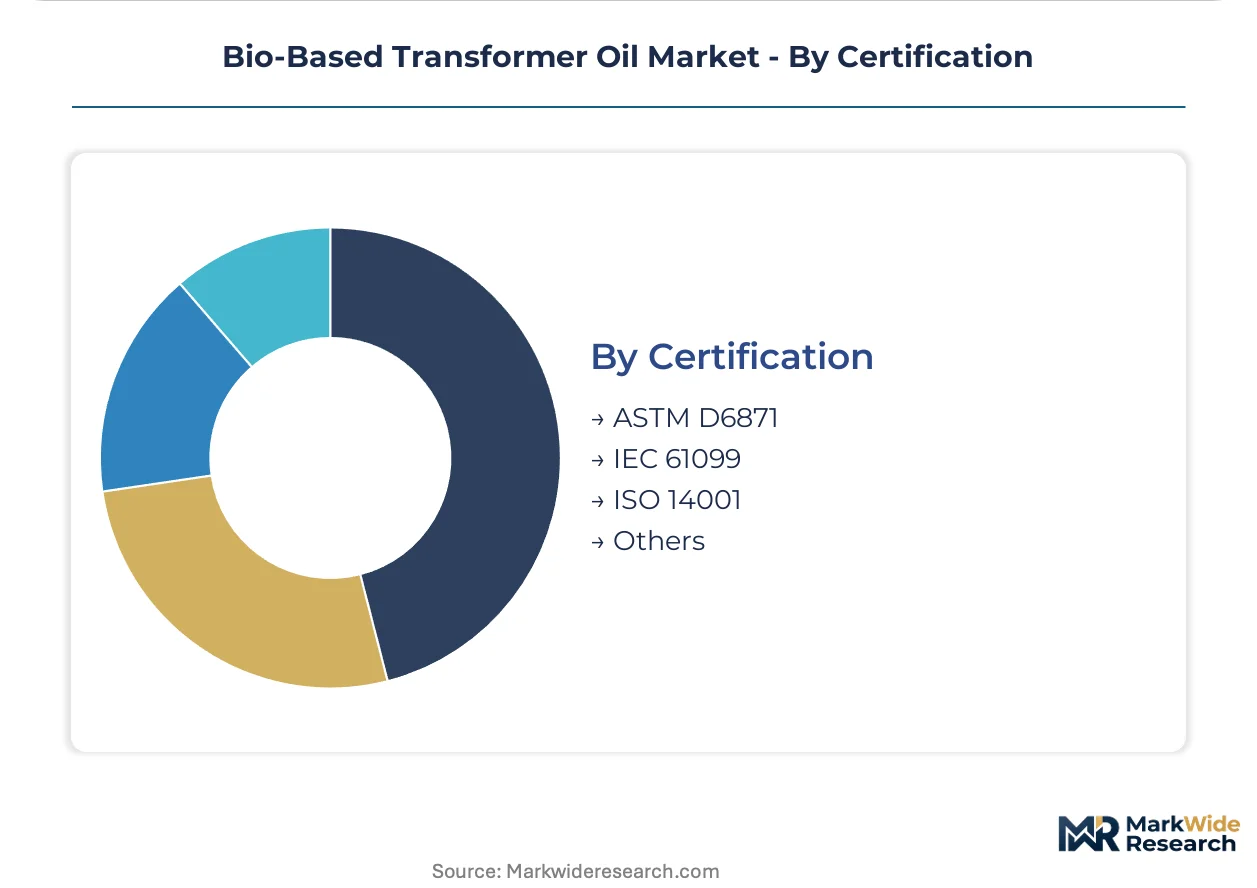
Certification:
Regulatory geography determines which testing protocols gate market access for supplier qualification.
- IEC 61099:The international standard for synthetic ester insulating liquids controls European and Asian utility procurement. Testing laboratory capacity constraints extend qualification timelines for new market entrants.
- ASTM D6871:The US specification for natural ester fluids governs EPA SPCC-compliant installations. BIS in India and SAMR in China are developing aligned national standards creating parallel compliance pathways.
- ISO 14001:Environmental management system certification supports carbon-intensity claims in EU CBAM-exposed supply chains.
- Others:National standards including JIS in Japan and GB in China maintain regional specification variations requiring localized testing investment.
IEC 61099 dominates cross-border trade. ASTM D6871 is expanding most quickly as US utility procurement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States consume bio-based transformer oil through utility-led retrofit programs, while China and India deploy it primarily in new renewable interconnection infrastructure rather than replacement cycles.
United States
Midwest utilities in Illinois and Ohio are executing the most concentrated distribution transformer retrofits. EPA Spill Prevention, Control, and Countermeasure rules mandate secondary containment upgrades that favor biodegradable fluids. Chicago-based procurement consortia aggregate demand from municipal operators seeking ASTM D6871-certified formulations.
Germany
Baden-Württemberg and Bavaria host transformer OEMs accelerating supplier audits for REACH-compliant dielectric fluids. EU Green Deal decarbonization targets compress replacement cycles for mineral-oil-filled units. Industrial regulators in Stuttgart classify certain legacy fire-resistant fluids as substances of very high concern.
China
State Grid Corporation specifies ester-based insulation for offshore wind platforms in the Taiwan Strait development zone. SAMR-aligned national standards for insulating liquids are creating parallel compliance pathways for domestic producers. Yangtze River Delta manufacturing clusters scale synthetic ester output for 275 kV transmission infrastructure.
India
Maharashtra and Gujarat distribution utilities pilot vegetable-oil formulations for agricultural load centers. BIS finalizes ester liquid specifications that will govern rural electrification procurement under national grid expansion programs. Tamil Nadu solar farm developers specify fire-safe fluids for pad-mounted installations.
Sweden
Svenska kraftnät negotiates carbon-intensity clauses into dielectric fluid procurement specifications for transmission infrastructure. State-owned grid operators bundle fluid supply with dissolved gas analysis services under multi-year performance agreements. Scandinavian equipment manufacturers unbundle hardware from fluid provision.
Bio-Based Transformer Oil Market Competitive Environment
Capability concentration sits with specialty ester chemists; scale advantage sits with integrated energy majors with lubricant distribution networks. The market structures around three tiers: global oil majors leveraging existing utility relationships, agribusiness conglomerates with captive feedstock supply, and regional refiners with adapted bio-hydrocarbon expertise. Consolidation pressure runs through backward integration into high-oleic oilseed cultivation and forward integration into fluid testing and reclamation services.
Among integrated energy majors, Shell plc and TotalEnergies occupy positions anchored by lubricant distribution networks securing utility procurement contracts. Cargill exemplifies the agribusiness archetype through upstream control over high-oleic soybean feedstock supply. Nynas AB represents regional refining specialists sustaining adapted expertise for bio-hydrocarbon processing streams.
| Leading Market Players |
|---|
| Shell plc |
| Cargill |
| BASF |
| TotalEnergies |
| Nynas AB |
| APAR Industries |
| Renewable Energy Group |
| China Petrochemical Corporation |
| Ergon, Inc. |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta synthetic ester manufacturing clusters anchor global capacity for high-voltage transformer fluids, translating geographic production concentration into pricing leverage for producers serving IEC 61099-certified procurement channels. This supply hub dynamics compresses margin negotiation space for utilities in import-dependent markets while creating arbitrage opportunities for integrated producers with captive feedstock positions.
Pricing Analysis
Long-term offtake agreements dominate utility-scale procurement in Germany and Scandinavia, bundling fluid supply with dissolved gas analysis and reclamation services under multi-year performance contracts. Price differentiation rests on certification tier—ASTM D6871 versus IEC 61099—and the inclusion of predictive maintenance telemetry. Cost compression in vegetable oil formulations is intensifying because Malaysian palm oil export duties transmit directly to triglyceride feedstock costs. Distribution utilities exhibit highest price sensitivity due to thin O&M budgets, while offshore wind developers accept premiums for synthetic ester fire-safety specifications.
Supply Chain Analysis
High-oleic soybean cultivation in the US Midwest and rapeseed processing in northwest Europe feed triglyceride ester production, while aromatic ester chemistry draws from petrochemical streams adapted to bio-hydrocarbon specifications. Raw material dependencies center on vegetable oil feedstock quality, specialty catalysts for hydrogenation, and IEC-certified additive packages. Single-source vulnerability concentrates in northwest European specialty ester refining capacity, exposing Asian utilities to logistics chokepoints. Distribution runs through integrated energy majors with existing lubricant infrastructure and direct contracting relationships with state-owned grid operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket fluid testing and reclamation services are expanding faster than hardware shipments, converting one-time product sales into recurring revenue streams with superior retention economics. This service-attach layer rewards suppliers who integrate predictive maintenance platforms with certified fluid provision.
For Market Incumbents: Insulate margin positions by securing captive supply agreements for high-oleic soybean acreage in the US Midwest and accelerating IEC 61099 certification investments to extend qualification timelines for challengers. Backward integration into feedstock cultivation defends against palm oil price volatility while channel control through dissolved gas analysis bundling locks in utility procurement relationships. For New Entrants and Emerging Players: Establish a beachhead in India's rural electrification segment where BIS ester specifications are finalizing and incumbent service infrastructure remains underdeveloped. Agricultural load center distribution transformers offer lowest certification barriers and shortest procurement cycles, with field service partnerships providing the fastest go-to-market path against integrated majors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among regional refiners with adapted bio-hydrocarbon expertise and established reclamation service networks. Long-term viability over a multi-year horizon favors acquisition targets combining synthetic ester chemistry capabilities with utility direct-contracting relationships. Watch for IEC 61099 testing laboratory capacity expansion as the inflection signal for accelerated new entrant qualification and price competition intensification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Cultivation | Captive high-oleic soybean supply in Illinois and Ohio insulates margin from Malaysian palm oil duty volatility. |
| Long-term Performance Agreement Expansion | Multi-year fluid-plus-service contracts with Svenska kraftnät convert transactional sales into predictable recurring revenue. |
| Joint Venture with Testing Laboratory | Partnerships with IEC 61099 certification facilities compress qualification timelines for synthetic ester market entry. |
| Geographic Expansion into India | BIS specification alignment creates first-mover positioning in agricultural load center transformer retrofits. |
| Technology Licensing for Digital Monitoring | Dissolved gas analysis sensor integration licenses enable predictive maintenance platform penetration in industrial microgrids. |
Study Parameters
A standing panel of utility procurement officers, transformer OEM technical directors, ester chemistry R&D leads, and field service operations managers provided ongoing calibration across primary interview cycles. Secondary validation drew from EPA SPCC enforcement records, EU ECHA REACH authorization databases, IEC standard revision drafts, and customs trade data for high-oleic oilseed and finished ester fluid movements. Bottom-up utility procurement surveys were triangulated against top-down capacity estimates from northwest European and Yangtze River Delta refining clusters.
Scenario-bracketing around feedstock price volatility bands and regulatory acceleration timelines framed the analytical envelope across the projection horizon. Segmentation dimensions modeled included formulation chemistry tier, voltage class application, end-user procurement scale, and certification geography. CAGRs were derived from utility replacement cycle compression rates and renewable interconnection project pipelines, with synthetic ester oxidative stability thresholds and natural ester biodegradability benchmarks serving as industry-specific forecast anchors.
Stress conditions across Malaysian palm oil export duty fluctuations, IEC 61099 testing laboratory capacity constraints, and EU CBAM carbon border adjustment implementation timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding utility compliance timeline execution and offshore wind development permitting velocity. Cross-checking against State Grid Corporation and Svenska kraftnät procurement disclosure patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Bucket Water Heater Market
Electrical Power Equipment
Global Air Insulated Switchgear Market
Electrical Power Equipment
Magneto Optic Current Transformer Market
Electrical Power Equipment
North America Power Inverter Market
Electrical Power Equipment
Switching Residential Voltage Regulator Market
Electrical Power Equipment
Hollow Core Insulator Market
Electrical Power Equipment
Europe Electric Space Heaters Market
Electrical Power Equipment
Subsea Cables Equipment Market
Electrical Power Equipment
South America Medium Voltage Switchgear Market
Electrical Power Equipment
Power Line Filters Market
Electrical Power Equipment
Global Magnetic Circuit Breaker Market
Electrical Power Equipment
Power Strip Market
Electrical Power Equipment
Packaged Substation Market
Electrical Power Equipment
Electric Radiators Market
Electrical Power Equipment
Electric Insulator Market
Electrical Power Equipment
AC Residential Switchgear Market