
 Global Medium Voltage AC Drives Market | 2026-2036
Global Medium Voltage AC Drives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medium Voltage AC Drives Market Outlook
Integrated drive architecture with embedded transformer and input switchgear is unwinding legacy multi-cabinet configurations across heavy process industries. ABB leverages its installed base in mining hoists and grinding mills to sustain aftermarket service revenues. Siemens competes through digital twin integration and predictive maintenance modules bundled with its medium voltage drive platforms.
Medium voltage AC drives are power conversion systems operating between 2.3 kV and 13.8 kV that regulate motor speed and torque through pulse-width modulation or multilevel inverter topologies, primarily serving energy-intensive industries seeking to cut electricity consumption in centrifugal load applications. Variable frequency drives dominate the type category due to their established cost position and broad compatibility with induction and synchronous motors. Pumping applications anchor the largest share of end-use demand, while offshore installations command premium pricing driven by marine-grade enclosure requirements and redundant cooling systems.
The EPA mandates efficiency thresholds under its motor standards program, while the EU F-Gas Regulation restricts fluorinated greenhouse gases in drive cooling circuits, and China's GB standards enforce harmonic emission limits through SAMR compliance testing. These frameworks push manufacturers toward liquid-cooled designs and wide-bandgap semiconductor transitions. Stakeholders must weigh regional certification divergence against platform standardization economics when allocating R&D budgets.
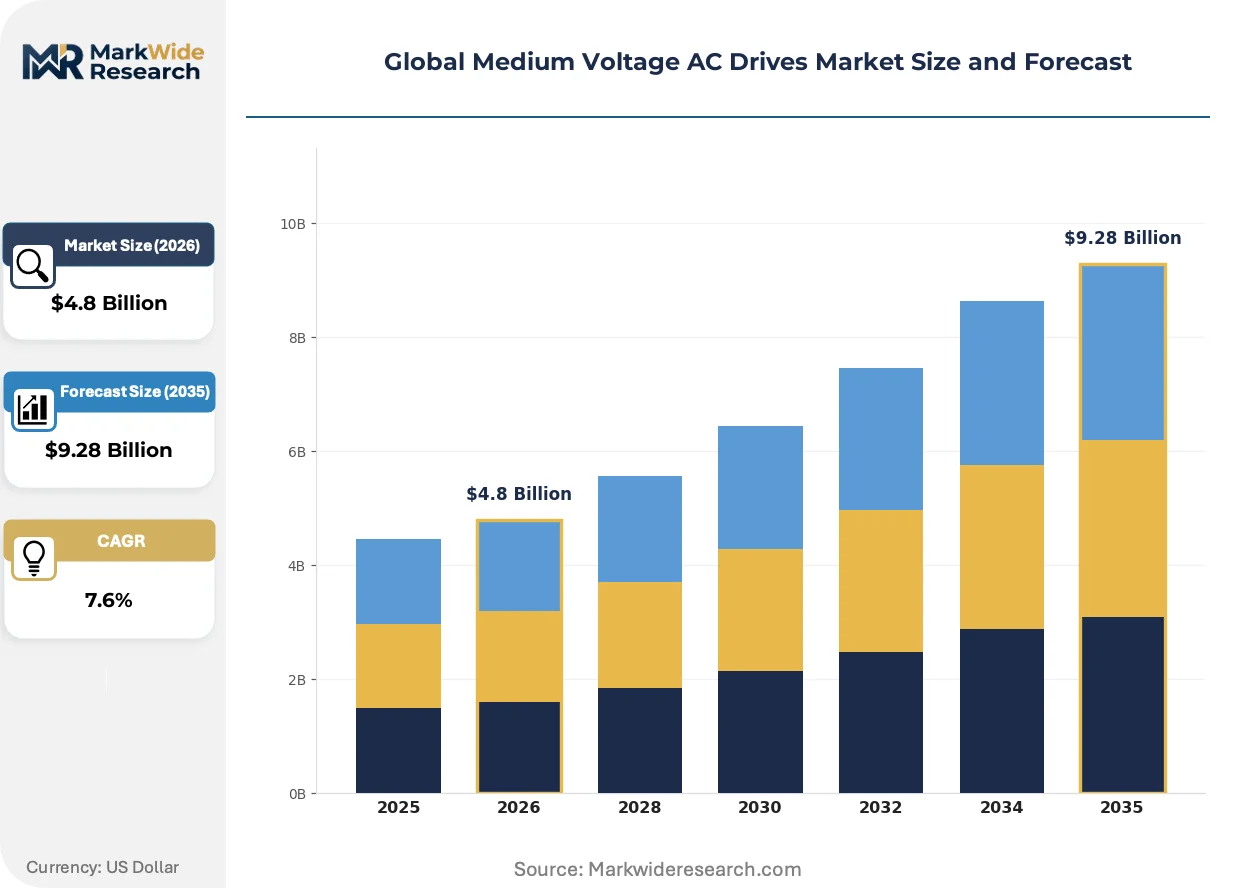
Market Dynamics
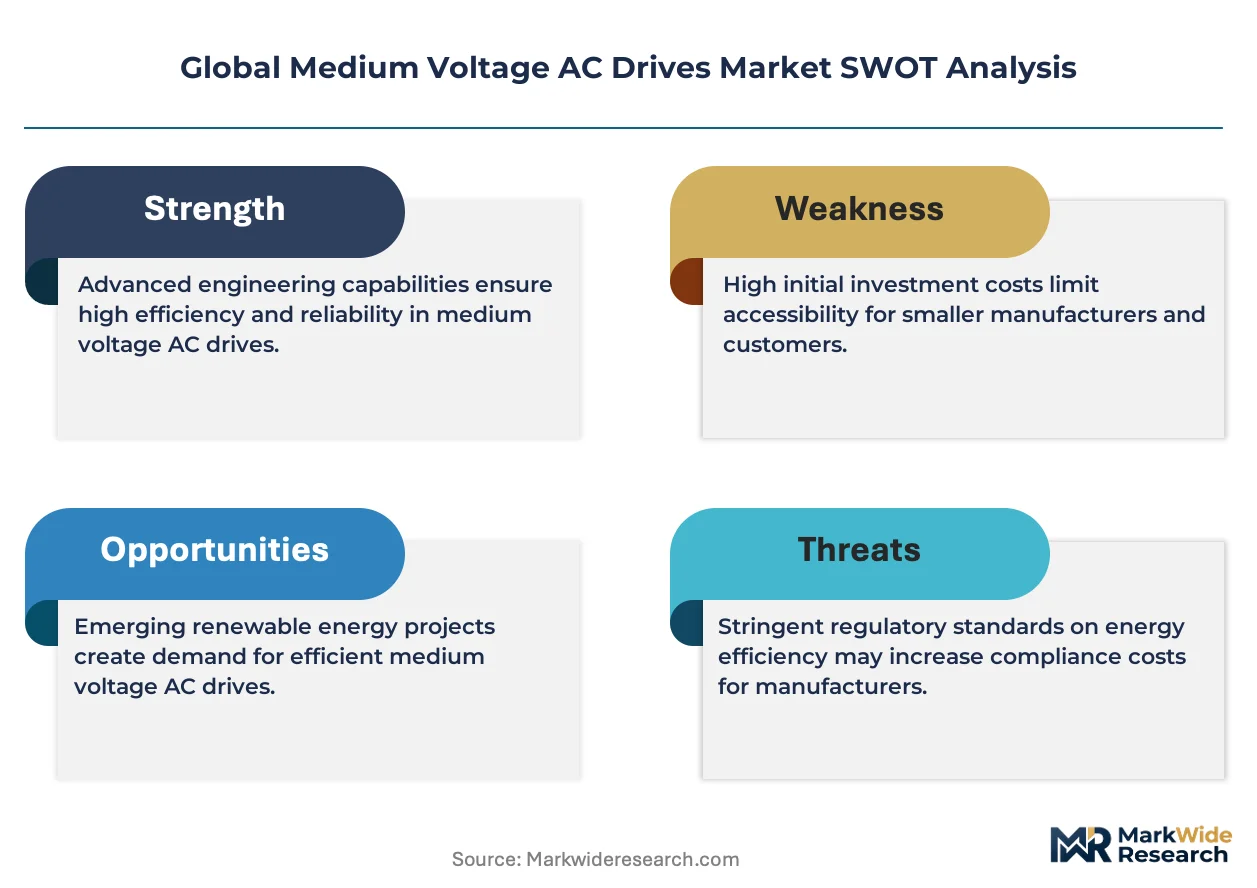
Integrated drive architecture is compressing legacy multi-cabinet configurations across heavy process industries, while the EU F-Gas Regulation and EPA efficiency mandates simultaneously accelerate semiconductor transitions and liquid-cooled design adoption.
Growth Catalysts
- Grid Modernization Mandates:China's state-backed infrastructure investments in petrochemical capacity and power distribution networks require high-reliability variable speed drive infrastructure at scale.
- Upstream Electrification:Oil and gas operators are expanding medium voltage AC drive deployment for electric submersible pump control in offshore and deepwater extraction environments.
- Efficiency Compliance Deadlines:The EPA's motor standards program and the EU F-Gas Regulation tighten minimum performance thresholds, forcing replacement cycles in installed industrial motor bases.
Market Restraints
- Wide-Bandgap Semiconductor Supply Concentration:Silicon carbide and gallium nitride substrate production concentrates in East Asian foundries, creating input cost volatility and allocation risk for drive manufacturers.
- Marine-Grade Enclosure Cost Structure:Offshore installations require redundant cooling systems and corrosion-resistant housing, elevating capital expenditure thresholds versus onshore equivalents.
- Harmonic Emission Compliance Friction:China's GB standards enforced through SAMR compliance testing impose redesign burdens for legacy product lines seeking market access.
Strategic Opportunities
- Digital Twin Convergence:Predictive maintenance modules bundled with medium voltage drive platforms enable aftermarket service revenue streams and remote diagnostics capabilities.
- Retrofit Installation Channel:Mining hoists and grinding mills present white space for integrated drive architecture replacements of aging multi-cabinet systems in established industrial clusters.
- Renewable Integration Applications:Variable frequency drives compatible with synchronous motors capture demand from pumped hydro storage and grid-scale battery coupling projects.
Industry Challenges
- Power Electronics Talent Scarcity:Design and field commissioning of multilevel inverter topologies requires specialized expertise in pulse-width modulation and thermal management engineering.
- Legacy System Integration Complexity:Existing motor control infrastructure in heavy process industries demands customized interface engineering, extending deployment timelines and eroding margin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medium Voltage AC Drives Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Variable Frequency Drives, Soft Starters, Integrated Drives, Multi-Motor Drives End User: Oil & Gas, Water & Wastewater, Mining, Power Generation Installation: Onshore, Offshore, Indoor, Outdoor Application: Pumping, Fan Control, Compressor Control, Conveyor Systems |
| Companies Covered | ABB, Danfoss, Schneider Electric, Siemens, Rockwell Automation, Nidec, Hitachi, TMEIC, WEG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medium Voltage AC Drives Market Strategic Shifts
Power semiconductor evolution and regulatory chemistry restrictions are rewiring medium voltage drive design priorities, while procurement patterns shift toward lifecycle service bundling.
Multilevel inverter topologies using cascaded H-bridge or neutral-point-clamped architectures is miniaturizing drive footprints by consolidating power conversion stages. Mining operators in Australia and Chile are adopting these compact configurations for underground hoist retrofits where space constraints limit cabinet expansion. The structural compression is enabling skid-mounted and containerized drive packages for remote extraction sites previously requiring permanent electrical rooms.
The EU F-Gas Regulation's phasedown of fluorinated greenhouse gases is prohibiting conventional refrigerants in drive cooling circuits. Manufacturers are pivoting toward liquid-cooled designs using water-glycol mixtures or dielectric fluids, particularly for offshore platforms where ambient temperatures stress air-cooled systems. Marine-grade installations in the North Sea and Gulf of Mexico are experiencing accelerated specification changes as 2024-2027 quota reductions tighten supply of legacy cooling compounds.
After-sales service unbundling is fragmenting traditional bundled maintenance contracts. End-users in the petrochemical sector are separating hardware procurement from predictive analytics subscriptions, pressuring OEM margins on initial equipment sales. This decoupling is most pronounced in the United States, where independent service providers certified under IEEE standards are capturing routine maintenance volumes previously captive to manufacturer service networks.
Global Medium Voltage AC Drives Market Segmentation
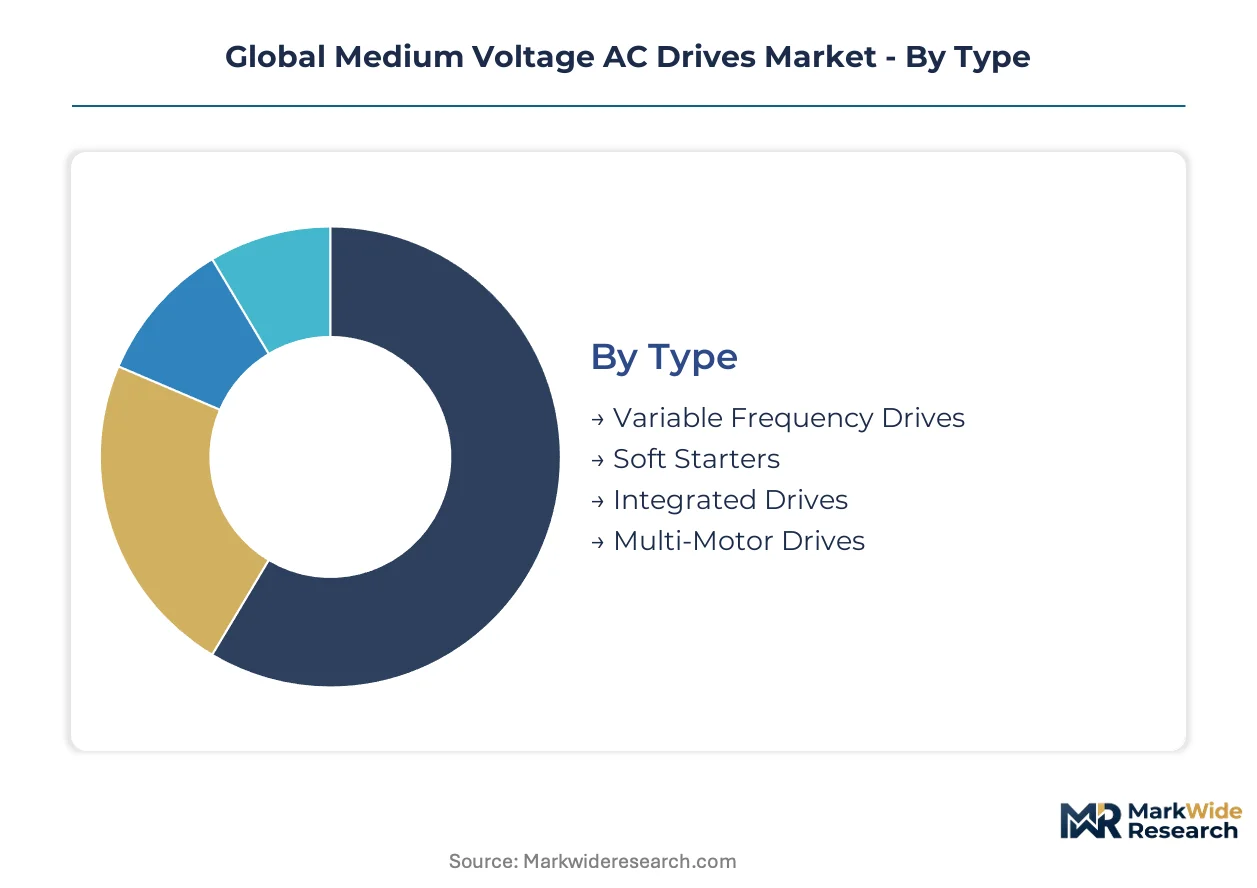
Segmentation reveals how medium voltage AC drive specifications diverge across voltage classes, cooling architectures, and integration levels. Procurement patterns cluster around application intensity and regulatory exposure rather than geography alone.
Type:
Variable frequency drives dominate domestic manufacturing bases in China and Germany, while integrated drive architectures increasingly ship to export markets seeking compact footprints for retrofit installations.
- Variable Frequency Drives:These systems regulate motor speed through pulse-width modulation across 2.3 kV to 13.8 kV ranges, serving induction and synchronous motors with established cost positions. Demand concentrates in Chinese petrochemical complexes and German automotive manufacturing facilities where harmonic compliance under GB standards and CE marking drives specification rigor.
- Integrated Drives:Embedded transformer and input switchgear configurations compress legacy multi-cabinet setups into single-enclosure designs. Export-led demand from Australian mining hoists and Chilean grinding mills accelerates adoption as operators prioritize space-constrained underground and remote site installations.
- Soft Starters:Reduced-voltage starting systems limit inrush current for fixed-speed applications requiring gentle acceleration profiles.
- Multi-Motor Drives:Centralized control architectures coordinate multiple motor loads from single power conversion units, common in conveyor-heavy material handling operations.
Variable frequency drives hold the largest share; momentum sits with integrated drives.
End User:
Cost tier differentiation separates specification-intensive offshore oil and gas from price-sensitive municipal water infrastructure.
- Oil & Gas:Upstream operators deploy medium voltage drives for electric submersible pump control in deepwater extraction environments. Premium pricing prevails in Gulf of Mexico and North Sea platforms where redundant cooling and marine-grade enclosures satisfy EPA offshore emissions protocols and EU F-Gas phasedown requirements.
- Mining:Hoist and grinding mill retrofits drive replacement cycles in established industrial clusters. Australian underground operations and Chilean open-pit copper mines specify compact multilevel inverter topologies where cabinet space constraints limit expansion options.
- Water & Wastewater:Municipal pumping stations prioritize energy recovery and harmonic mitigation over performance extremes.
- Power Generation:Grid-scale battery coupling and pumped hydro storage applications demand synchronous motor compatibility with precise torque control.
Oil and gas commands premium pricing tiers; mining presents the steepest expansion trajectory for integrated architectures.
Installation:
Volume concentration favors onshore indoor configurations, while margin accretion concentrates in offshore marine-grade specifications.
- Offshore:Corrosion-resistant housings and redundant cooling systems elevate capital expenditure thresholds versus onshore equivalents. North Sea platforms and Gulf of Mexico floating production facilities accelerate specification changes as 2024-2027 F-Gas quota reductions eliminate conventional refrigerant options.
- Onshore:Standardized air-cooled and liquid-cooled designs serve petrochemical complexes and manufacturing facilities across China, Germany, and the United States with lower enclosure engineering burdens.
- Indoor:Controlled-environment electrical rooms accommodate legacy multi-cabinet configurations with standard ingress protection ratings.
- Outdoor:Weatherized enclosures with extended temperature ranges serve remote extraction sites and distribution substations lacking permanent infrastructure.
Onshore installations dominate unit volume; offshore specifications capture the highest margin per kilowatt.
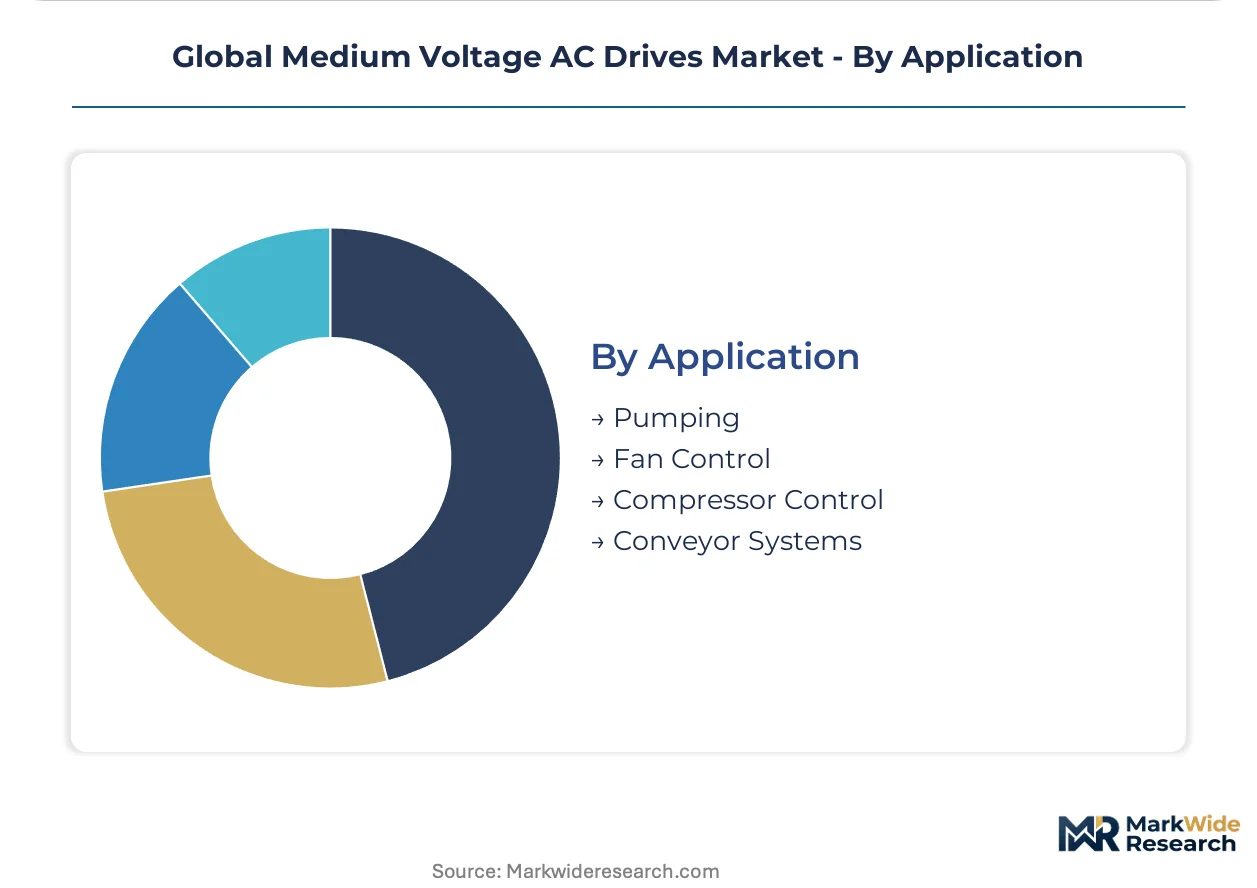
Application:
Customer type stratification separates continuous-process pumping from intermittent conveyor duty cycles.
- Pumping:Centrifugal load regulation in electric submersible pumps and pipeline booster stations constitutes the largest application category. Chinese state-backed grid modernization and petrochemical capacity additions require high-reliability variable speed infrastructure at scale for water injection and hydrocarbon transport.
- Compressor Control:Gas compression and refrigeration cycles demand precise torque management across varying suction pressures. LNG liquefaction facilities in Qatar and Australia specify drives with synchronous motor compatibility for large-frame centrifugal compressors.
- Fan Control:Draft and ventilation systems in power generation and heavy process industries require less dynamic response than pumping or compression.
- Conveyor Systems:Material handling applications in mining and bulk commodity transport prioritize starting torque and overload capacity over speed precision.
Pumping anchors the largest demand share; compressor control is gaining share fastest in LNG infrastructure expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon carbide substrate fabrication concentrates in East Asian foundries, creating input cost volatility for drive manufacturers sourcing power semiconductors. Demand clusters around state-backed grid modernization programs and upstream oilfield electrification projects across five major economies.
China
State Grid Corporation's ultra-high voltage transmission buildout requires variable speed drive infrastructure at petrochemical complexes in Ningbo and Dalian. SAMR enforces GB harmonic emission limits through mandatory compliance testing. Yangtze River Delta manufacturing clusters absorb integrated drive architectures for space-converted textile and chemical plants.
United States
Permian Basin operators deploy electric submersible pump drives for shale extraction electrification. EPA motor standards program mandates efficiency thresholds that accelerate replacement cycles in Gulf Coast refineries. Houston's energy corridor hosts specification engineering for marine-grade offshore installations serving deepwater platforms.
Germany
Ruhr Valley chemical producers retrofit legacy motor bases with liquid-cooled systems under EU F-Gas Regulation phasedown timelines. CE marking requirements and REACH chemical compliance shape procurement specifications. Bavarian automotive manufacturing facilities integrate medium voltage drives into paint shop and stamping line automation.
Australia
Pilbara iron ore operators specify compact multilevel inverter topologies for underground hoist retrofits where electrical room expansion is physically constrained. State-level renewable energy targets drive pumped hydro storage projects requiring synchronous motor compatibility. Perth engineering consultancies coordinate containerized drive packages for remote mine sites.
Brazil
Pre-salt offshore fields in the Santos Basin command premium marine-grade specifications with redundant cooling systems. ANVISA-equivalent industrial safety frameworks govern equipment certification for platform installations. São Paulo state's petrochemical complex in Cubatão sources variable frequency drives for pipeline booster stations.
Global Medium Voltage AC Drives Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the medium voltage AC drives sector. European and Japanese conglomerates anchor premium-tier positions through digital twin integration and predictive maintenance modules. Scale-driven specialists from emerging economies compete on integrated architecture cost compression. Dominant competitive moves include portfolio diversification into lifecycle service bundling and geographic expansion through mining sector retrofit channels.
Within the diversified industrial conglomerate tier, ABB and Siemens exemplify technology-forward positioning through aftermarket service revenue capture in established mining clusters. TMEIC represents Japanese precision engineering specialization in multilevel inverter topologies for heavy process applications. These three anchors illustrate how heritage in adjacent power infrastructure sectors translates into medium voltage drive platform credibility.
| Leading Market Players |
|---|
| ABB |
| Danfoss |
| Schneider Electric |
| Siemens |
| Rockwell Automation |
| Nidec |
| Hitachi |
| TMEIC |
| WEG |
| Others |
Value Chain & Pricing Dynamics
Twenty-six-week lead times for silicon carbide power modules concentrate pricing power among East Asian substrate foundries and force European drive manufacturers to absorb input cost volatility through liquid-cooled design premiums. This inventory compression cascades through marine-grade enclosure specifications where redundant cooling systems and corrosion-resistant housings elevate capital expenditure thresholds versus onshore equivalents.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across marine-grade offshore installations and standard onshore configurations. Three-tier pricing structure across premium, standard, and economy levels separates Gulf of Mexico platforms with redundant cooling from Chinese petrochemical complexes with air-cooled designs from municipal water infrastructure with basic variable frequency drives. Cost compression in the standard tier intensifies because independent service providers certified under IEEE standards fragment aftermarket revenue previously captive to OEM service networks. Municipal water infrastructure operators exhibit the highest price sensitivity due to fixed-rate tariff constraints, while offshore oil and gas operators demonstrate the lowest sensitivity given operational continuity premiums.
Supply Chain Analysis
Strait of Malacca transit underwrites raw material flows for silicon carbide substrates and rare-earth magnetic materials feeding multilevel inverter fabrication. East Asian foundries in Japan and South Korea anchor wide-bandgap semiconductor supply alongside Chinese substrate producers, while German and Swiss component specialists provide precision thermal management subsystems. Single-source vulnerability concentrates in 6-inch silicon carbide wafer production where capacity expansion lags demand growth from electric vehicle and industrial drive applications. Distribution runs through authorized industrial distributors serving petrochemical complexes and direct OEM relationships for offshore platform engineering procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as after-sales service unbundling fragments traditional bundled maintenance contracts and creates niche entry points for specialized predictive analytics providers. End-users in the petrochemical sector separating hardware procurement from software subscriptions fragment incumbent revenue models.
For Market Incumbents: Shield installed base revenue in Australian mining hoists and Chilean grinding mills by embedding predictive maintenance modules with medium voltage drive platforms. Vertical integration into liquid-cooled thermal management subsystems mitigates East Asian semiconductor foundry allocation risk. Capture lifecycle service contracts before independent IEEE-certified providers consolidate routine maintenance volumes.
For New Entrants and Emerging Players: Predictive analytics software layers where ABB and Siemens under-serve mid-tier mining operators present the most penetrable white space. Target Brazilian pre-salt offshore fields in the Santos Basin where ANVISA-equivalent certification requirements slow incumbent response times. Pursue containerized drive package partnerships with Perth engineering consultancies coordinating remote mine site logistics.
For Investors and Strategic Acquirers: Long-term, this sits as a service-arbitrage play because hardware commoditization accelerates while predictive maintenance software retains pricing power. Acquire mid-cap specialists with synchronous motor compatibility expertise for pumped hydro storage applications. Watch F-Gas quota reduction enforcement velocity as the inflection indicator for liquid-cooled design adoption curves.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Semiconductors | Captive silicon carbide supply mitigates East Asian foundry concentration risk for drive manufacturers. |
| Liquid-Cooled Design Platform Launch | EU F-Gas Regulation compliance enables marine-grade offshore specifications in North Sea platforms. |
| Predictive Maintenance Software Unbundling | Independent service providers capture recurring revenue from petrochemical sector procurement shifts. |
| Mining Hoist Retrofit Channel Expansion | Integrated drive architectures replace legacy multi-cabinet systems in Australian underground operations. |
| Synchronous Motor Compatibility Investment | Pumped hydro storage projects in Australia require precise torque control for grid-scale applications. |
Study Parameters
A standing panel of plant engineers at petrochemical complexes, procurement leads at oilfield service companies, aftermarket service heads at drive OEMs, and EPC contractors specializing in offshore platform electrification provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with maintenance directors at mining operations and technical R&D directors at power semiconductor suppliers. Secondary validation drew from SEC 10-K filings of listed industrial conglomerates, customs trade data for medium voltage drive exports, IEEE standards documentation, and SAMR compliance testing records. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Cross-referencing against external benchmarks confirmed output consistency across voltage class, cooling architecture, and integration level segmentations. The analytical framework modeled demand across variable frequency drives, integrated architectures, soft starters, and multi-motor configurations alongside end-use intensity and regulatory exposure dimensions. CAGRs were derived from logistic adoption curves fitted to replacement cycle data and capacity expansion announcements. Forecast inputs included State Grid Corporation transmission buildout schedules, EPA motor standards compliance deadlines, and EU F-Gas phasedown quota trajectories.
Forecasts assume regulatory continuity in EPA motor standards, EU F-Gas Regulation, and China's GB standards enforcement; material policy shifts would require re-modeling adoption curves and replacement timelines. Semiconductor supply concentration, harmonic emission compliance friction, and power electronics talent scarcity constitute specific risk factors that could revise projections. Practitioners should keep alternative scenarios live as wide-bandgap substrate capacity expansion and F-Gas refrigerant quota reductions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Wind Turbine Bolts Market
Power Equipment
Heavy Duty Gas Turbine Market
Power Equipment
Power Plant Lightning Protection Services Market
Power Equipment
Middle East Power Filter Market
Power Equipment
India Power EPC Market
Power Equipment
Saudi Arabia Power EPC Market
Power Equipment
Asia-Pacific Steam Turbine Market
Power Equipment
Advanced Gas Generators Sales Market
Power Equipment
Global Auxiliary Power Unit Market
Power Equipment
Submarine Power Cable Market
Power Equipment
United Kingdom Power EPC Market
Power Equipment
Power Equipment Testing Market
Power Equipment
Power Grid Primary and Secondary Fusion Equipment Market
Power Equipment
Industrial Power Transmission Drive Belts Market
Power Equipment
Global Exhaust Heat Recovery System Market
Power Equipment
Turbomachinery Control Systems, Retrofitting, and Ancillary Services Market