

3rd Rail Current Collector Market Size, Share, and Industry Trends Forecast 2026-2036
3rd Rail Current Collector Market Insights
Specialized carbon-composite manufacturing expertise is redrawing competitive boundaries in the 3rd Rail Current Collector Market. Wabtec Corporation leverages its vertically integrated carbon materials capability to dominate North American transit authority procurement. Schunk Group anchors European supply through its precision sintering operations for high-wear contact shoes. Mersen competes by extending its graphite specialization into lightweight collector assemblies for automated metro systems.
A 3rd rail current collector is an electromechanical device that draws direct current from a conductor rail through sliding or rolling contact, typically employing copper-graphite or carbon composite contact blocks rated for continuous currents exceeding 3,000 amperes at operating voltages up to 1,500 volts DC. Its primary purpose is to deliver reliable traction power to rail vehicles while minimizing arcing, wear, and electromagnetic interference in tunnel and open-track environments. Composite collector product types command widening preference as operators trade stainless steel durability for reduced mass and superior fire performance. Sliding shoe technology occupies the largest installed base across legacy metro networks, though magnetic contact systems represent the fastest-growing category in driverless transit deployments. Application demand concentrates in metro systems, where frequent stop-start cycles and tunnel ventilation constraints amplify collector material selection.
The Federal Railroad Administration enforces contact force and electrical clearance standards that shape collector design for US commuter corridors, while the EU Rail Safety Directive mandates EN 45545 fire-smoke toxicity compliance for all new rolling stock subsystems. China's National Railway Administration applies GB/T rail electrification standards that specify collector dynamic performance under heavy humidity and particulate loading. Stakeholders must weigh material certification timelines against fleet replacement cycles as regulatory divergence between jurisdictions complicates platform standardization strategies.
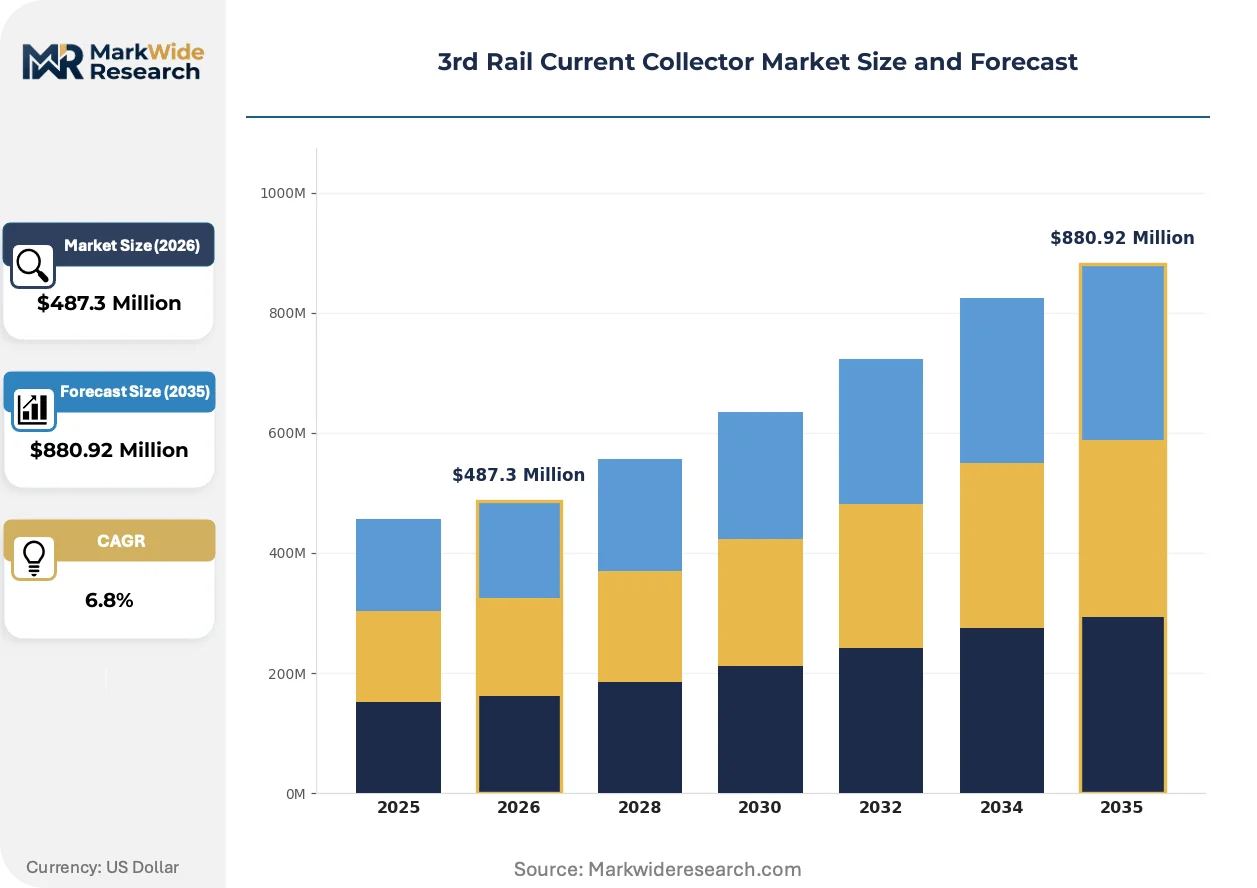
Market Dynamics
Composite contact materials are compressing replacement cycles and rewiring supplier-buyer power dynamics as metro operators prioritize fire-safety certification over raw mechanical durability in procurement specifications.
Growth Catalysts
- EU Rail Safety Directive EN 45545:Mandated fire-smoke toxicity compliance for rolling stock subsystems accelerates composite collector specification in European metro procurement tenders.
- Automated metro deployment:Driverless transit systems in Asian urban corridors demand precision-engineered magnetic contact assemblies with reduced maintenance intervals.
- India's urban rail buildout:Network extensions across Delhi, Mumbai, and Bangalore generate concentrated procurement volume for high-amperage collector systems.
Market Restraints
- Copper-graphite supply concentration:Specialized carbon composite precursor materials concentrate among limited German and Japanese chemical processors, exposing buyers to input volatility.
- Certification timeline friction:Divergent fire-safety testing protocols between EU EN 45545 and China's GB/T standards extend product validation cycles for multinational suppliers.
- Stainless steel substitution threat:Legacy metro operators in cost-constrained markets retain metal shoe specifications despite composite performance advantages.
Strategic Opportunities
- Underpenetrated Southeast Asian corridors:Vietnam and Indonesia's nascent metro programs lack established collector supply relationships, creating first-mover positioning potential.
- Technology convergence:Integration of predictive wear sensors with composite collector assemblies enables condition-based maintenance contracts.
- Regulatory tailwind:India's CEA electrification mandates for urban rail create compliance-driven demand for certified high-current collection systems.
Industry Challenges
- Composite manufacturing skill scarcity:Precision sintering expertise for carbon-ceramic contact shoes concentrates among aging specialist workforces in Germany and Japan.
- Legacy system integration complexity:Retrofitting composite collectors onto 1960s-era metro fleets requires custom mechanical adaptation and electrical clearance revalidation.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3rd Rail Current Collector Market Trends and Innovations
Material science advances and regulatory harmonization pressures are compressing product development timelines while fragmenting procurement authority across engineering, safety, and sustainability functions.
Carbon-ceramic composite formulations is supplanting traditional copper-graphite blends in high-frequency metro applications. European operators adopting EN 45545-certified assemblies reduce collector mass by approximately one-third while extending service intervals. This substitution is compressing the addressable market for conventional metal shoe suppliers and elevating materials science capabilities to primary competitive differentiators.
REACH chemical registration requirements in Europe are forcing reformulation of binder systems used in carbon composite manufacturing. Industrial consequence includes accelerated R&D expenditure for collector producers seeking EU market access. Metro procurement teams in Germany and France now require full material disclosure documentation, shifting supplier evaluation criteria toward chemical compliance depth.
Lifecycle cost contracting is displacing unit-price procurement in mature metro networks. Scandinavian and Dutch transit authorities unbundle collector supply from installation and predictive maintenance services, selecting vendors on total cost of ownership models. This restructuring concentrates contract value with integrated solution providers capable of sensor-enabled remote monitoring.
3rd Rail Current Collector Market Segmentation
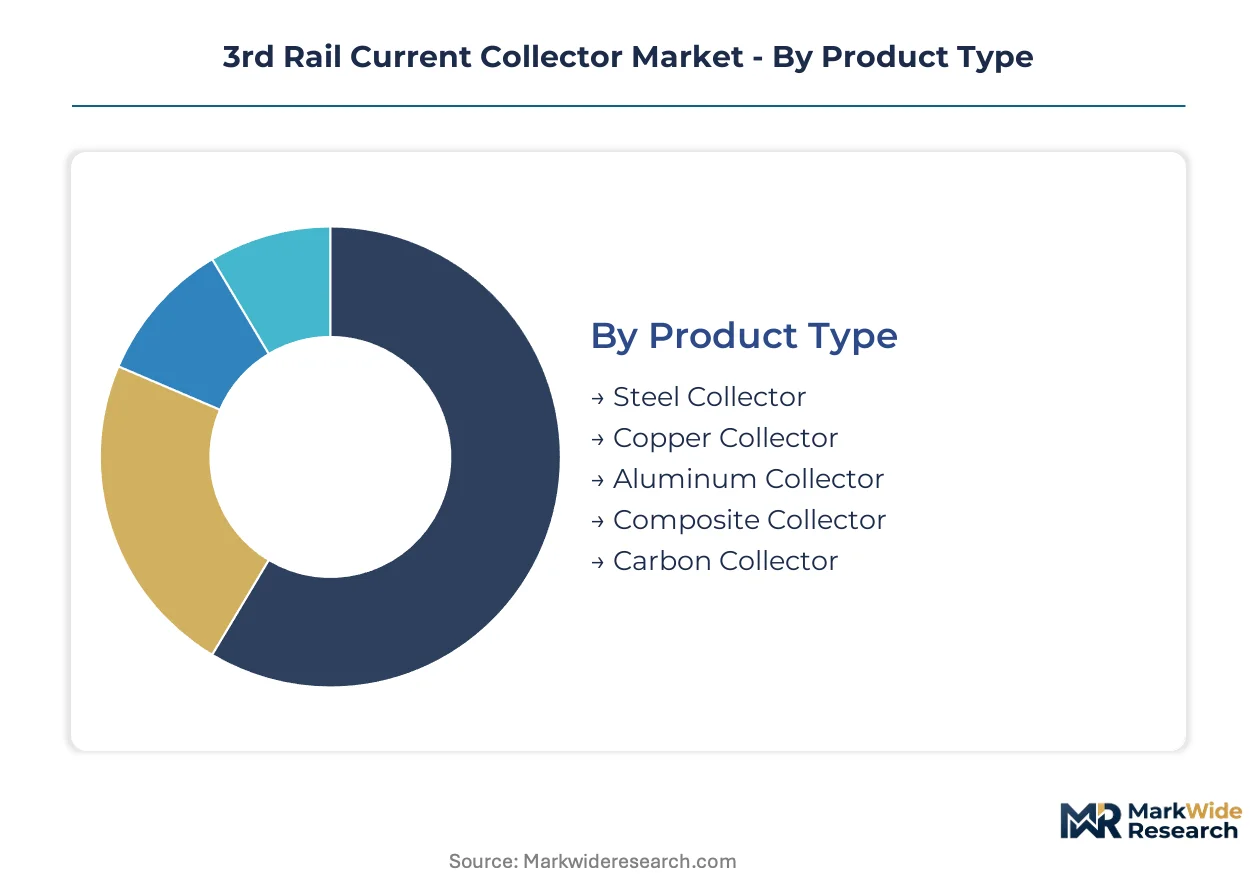
Segmentation in the 3rd Rail Current Collector Market reveals how material selection, contact mechanism design, and deployment environment collectively determine procurement specifications. Operators balance fire-safety certification, electrical load capacity, and lifecycle maintenance costs when specifying collector subsystems for electrified rail networks.
Product Type:
EN 45545 fire-smoke toxicity mandates in Europe and GB/T rail standards in China impose divergent material performance thresholds that reshape competitive positioning across metallic and composite formulations.
- Composite Collector:Carbon-ceramic formulations reduce collector mass by approximately one-third versus metal alternatives while satisfying stringent fire-safety protocols. Demand concentrates in European metro procurement tendering where EN 45545 compliance functions as a gatekeeping specification, though India's urban rail buildout in Delhi, Mumbai, and Bangalore accelerates adoption for tunnel ventilation-constrained environments.
- Steel Collector:Stainless steel contact shoes deliver proven mechanical durability for legacy metro fleets operating high-frequency stop-start cycles. Procurement volume remains concentrated among North American commuter rail corridors where FRA contact force standards prioritize structural reliability over mass reduction, particularly on above-ground track sections with lower fire containment requirements.
- Copper Collector:Copper-graphite blends maintain established installed bases across Asian heavy-rail networks requiring continuous current ratings exceeding 3,000 amperes.
- Aluminum Collector:Lightweight aluminum assemblies serve cost-constrained light rail deployments prioritizing capital expenditure minimization.
- Carbon Collector:Pure carbon contact blocks address specialized high-temperature operating conditions in desert-climate rail corridors.
Established volume favors steel collector specifications; emerging adoption favors composite collector platforms.
Technology:
Contact mechanism selection correlates directly with automation level and maintenance interval requirements across deployment scenarios.
- Sliding Shoe:Fixed-position sliding contact dominates legacy metro infrastructure with proven reliability under 750-1,500V DC electrification. Procurement concentrates in India's network extensions where standardized mechanical interfaces reduce fleet integration complexity, though wear rates under frequent stop-start cycling compress replacement intervals relative to magnetic alternatives.
- Magnetic Contact:Electromagnetically actuated contact assemblies enable precision force modulation for driverless transit systems. Deployment clusters in Asian automated metro corridors where reduced maintenance access intervals demand predictive wear management, with Singapore and Dubai transit authorities specifying magnetic systems for unmanned operations.
- Rotating Brush:Cylindrical brush mechanisms distribute wear across multiple contact surfaces for extended service life.
- Conductive Strip:Flexible conductive strip configurations accommodate track curvature variations in light rail geometries.
- Contact Shoe:Traditional shoe designs persist in freight rail electrification with lower duty cycle requirements.
Sliding shoe technology commands current installed base dominance; magnetic contact systems are gaining share fastest in greenfield automated deployments.
Application:
Operating environment characteristics—tunnel confinement, stop-start frequency, and ventilation constraints—determine collector material and cooling specifications.
- Metros:Underground and elevated urban rail systems impose the most stringent collector performance requirements due to tunnel ventilation limitations and high-frequency traction demands. Network extensions across India's major metropolitan areas generate concentrated procurement volume, with Delhi Metro Rail Corporation and Mumbai Metro specifying composite assemblies for fire-safety compliance.
- Light Rail Transit:Surface-level tram networks with moderate electrical loads and open-air cooling favor cost-optimized aluminum and steel collector configurations.
- Commuter Rail:Suburban corridor operations balance high-amperage collection with extended maintenance intervals.
- High-Speed Rail:Continuous high-speed contact dynamics demand specialized wear-resistant formulations exceeding standard metro specifications.
- Automated People Movers:Closed-loop airport and campus systems prioritize minimal maintenance magnetic contact solutions.
Metro applications anchor procurement volume concentration; automated people movers represent the steepest expansion trajectory among application categories.
End User:
Procurement authority fragmentation across engineering, safety, and sustainability functions reshapes vendor evaluation criteria by organization type.
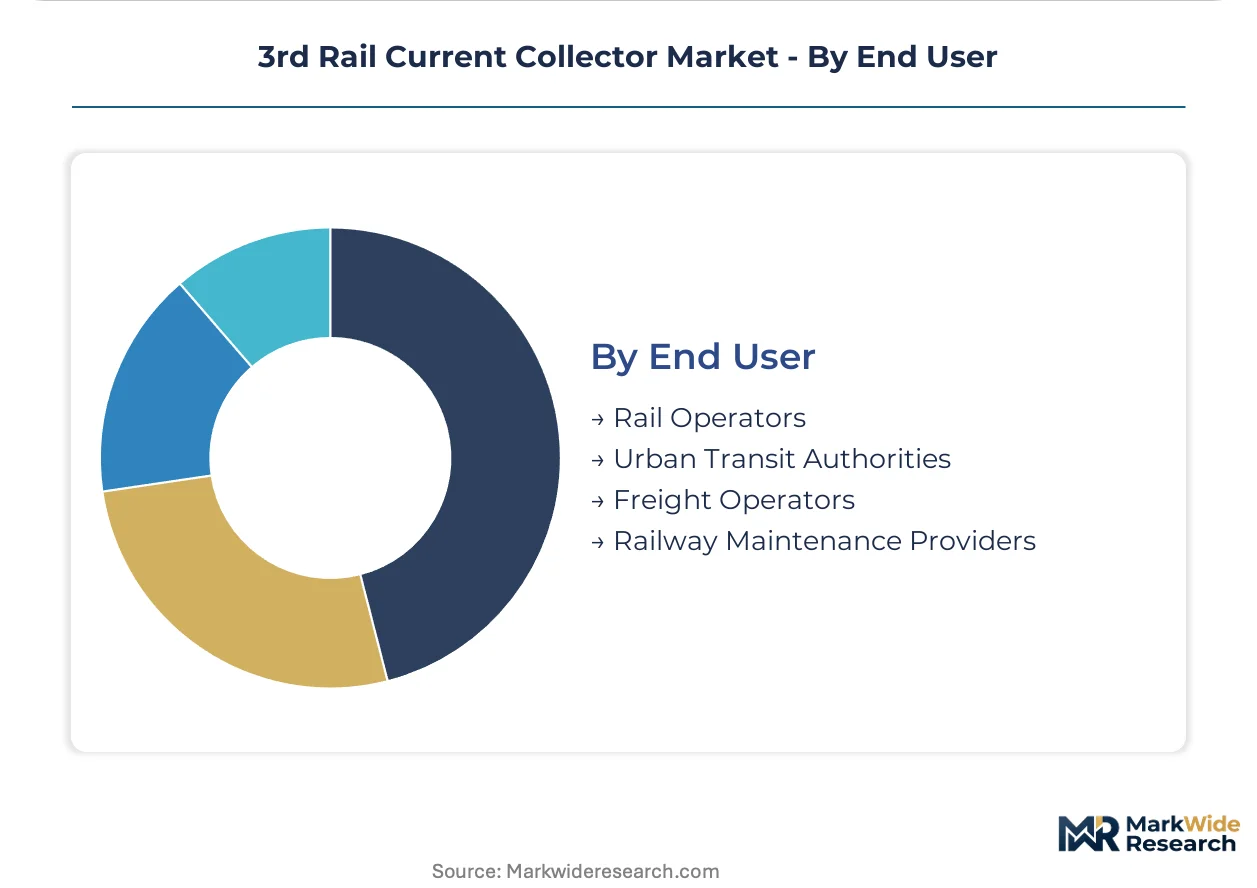
- Urban Transit Authorities:Municipal and regional transit agencies in European and Asian metro corridors unbundle collector supply from lifecycle maintenance services, selecting vendors on total cost of ownership models incorporating sensor-enabled remote monitoring. Scandinavian and Dutch authorities lead this contracting restructuring.
- Rail Operators:National and private rail operating companies prioritize interoperability across mixed-fleet deployments.
- Freight Operators:Cargo-focused electrified rail networks emphasize mechanical durability over fire-safety certification.
- Railway Maintenance Providers:Third-party maintenance contractors influence aftermarket collector replacement specifications.
Urban transit authorities concentrate procurement decision-making authority; railway maintenance providers are gaining specification influence through lifecycle service contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metro operators in India deploy composite collectors at substantially higher rates than their North American counterparts, where stainless steel shoes retain procurement preference for above-ground commuter corridors. This consumption-mix differential reflects divergent regulatory priorities: fire-safety certification dominates European and Asian tendering, while mechanical durability anchors U.S. specifications.
United States
The Federal Railroad Administration enforces contact force and electrical clearance standards that shape collector design for commuter corridors serving New York, Boston, and Chicago. FRA compliance timelines extend product validation cycles for composite material introductions. Procurement concentrates among transit authorities in the Northeast Corridor, where aging infrastructure replacement programs sustain demand for high-durability metal shoe configurations.
Germany
REACH chemical registration requirements force reformulation of binder systems used in carbon composite manufacturing, accelerating R&D expenditure for producers seeking EU market access. EN 45545 fire-smoke toxicity mandates function as gatekeeping specifications in Berlin, Munich, and Hamburg metro tendering. Industrial concentration clusters in Baden-Württemberg, where precision sintering operations supply contact shoe assemblies to European rolling stock manufacturers.
China
The National Railway Administration applies GB/T rail electrification standards specifying collector dynamic performance under heavy humidity and particulate loading conditions prevalent in southern provinces. Network expansion in the Yangtze River Delta and Pearl River Delta generates procurement volume for high-amperage collection systems. Manufacturing gravity centers on state-owned rolling stock producers in Changchun and Qingdao, which integrate collector subsystems into domestic metro fleet builds.
India
The Central Electricity Authority mandates urban rail electrification compliance that creates certification-driven demand for high-current collection systems across Delhi, Mumbai, and Bangalore. Metro network extensions in these corridors generate concentrated procurement volume for composite assemblies addressing tunnel ventilation constraints. Industrial activity clusters around the Delhi-Mumbai Industrial Corridor, where fleet electrification programs accelerate composite collector specification in new tendering.
Japan
METI industrial standards govern carbon composite precursor material specifications, concentrating specialized chemical processing expertise among established suppliers in the Kansai and Chubu regions. Automated metro deployments in Tokyo and Osaka demand precision-engineered magnetic contact assemblies with reduced maintenance intervals. Manufacturing capability concentrates in Nagoya's industrial belt, where materials science specialists serve domestic rail original equipment manufacturers.
3rd Rail Current Collector Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the 3rd Rail Current Collector Market, with vertical integration into carbon materials and precision sintering operations separating the tiers. The upper tier commands premium positioning through captive supply of composite precursors and EN 45545 certification depth. Three archetypes populate the competitive field: diversified industrial conglomerates with rail divisions, specialized carbon-ceramic component manufacturers, and rolling stock integrators with captive collector production. Dominant competitive moves include backward integration into carbon precursor supply and geographic expansion through certification-first entry into India's urban rail buildout.
Among North American industrial conglomerates, Wabtec Corporation exemplifies the integrated leader archetype through its vertically structured materials capabilities. Schunk Group and Mersen occupy specialist tier positions, with the former representing German precision manufacturing heritage and the latter anchoring French graphite specialization. These three names illustrate how competitive positioning correlates with geographic regulatory alignment: Wabtec with FRA standards, Schunk with EN 45545 frameworks, and Mersen with automated metro system requirements.
| Leading Market Players |
|---|
| Wabtec Corporation |
| Schunk Group |
| Mersen |
| Morgan Advanced Materials |
| Siemens Mobility |
| Alstom |
| Stadler Rail |
| Hitachi Rail |
| CAF |
| Others |
Pricing and Supply Chain Analysis
Twenty-four to thirty-six week lead times for EN 45545-certified carbon-ceramic precursor materials concentrate pricing power with German and Japanese chemical processors, compressing margin flexibility for downstream collector assemblers serving European and Indian metro procurement.
Pricing Analysis
Long-term offtake agreements dominate procurement between established metro operators and certified composite suppliers, though spot purchasing persists for legacy stainless steel shoe replacement cycles. Price differentiation rests on EN 45545 certification tier and bundled predictive maintenance sensor integration. Cost compression in standard-grade steel collectors is intensifying because Indian transit authorities are unbundling supply from installation services. Freight operators exhibit highest price sensitivity; automated metro authorities in Singapore and Dubai demonstrate lowest sensitivity due to total cost of ownership contracting.
Supply Chain Analysis
Germany and Japan anchor precision sintering operations for carbon-ceramic contact shoes, while China concentrates copper-graphite blending and aluminum extrusion capacity. Raw material flows draw from petroleum coke feedstock, synthetic graphite powders, and ceramic binder systems. Single-source vulnerability concentrates in specialized carbon precursor supply from Kansai-region chemical processors. Distribution runs through rolling stock original equipment manufacturers who integrate collector subsystems into fleet builds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
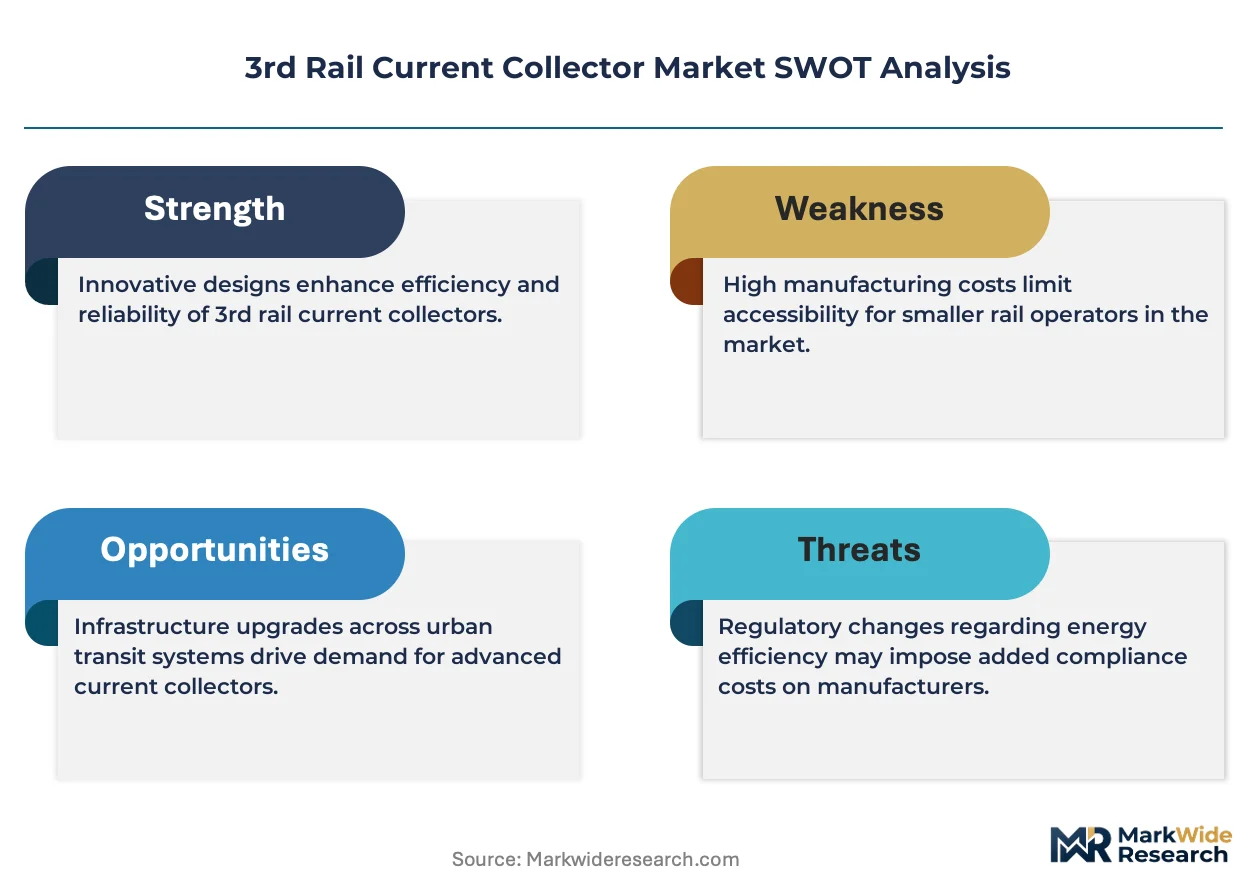
Composite material substitution and regulatory harmonization pressures are disrupting established procurement patterns, with EN 45545 and India's CEA electrification mandates compressing validation timelines for traditional metal shoe suppliers.
For Market Incumbents: Shield market position by deepening backward integration into carbon precursor supply and accelerating EN 45545 certification depth for next-generation formulations. Capacity addition in India's Delhi-Mumbai Industrial Corridor addresses the fastest-growing procurement corridor. Magnetic contact system R&D investment counters emerging automated metro specification shifts. For New Entrants and Emerging Players: Lifecycle service bundling gaps in Southeast Asian metro programs create first-mover positioning potential. Vietnam and Indonesia's nascent electrification corridors lack established collector supply relationships. Target predictive maintenance integration as the primary go-to-market angle for Scandinavian and Dutch transit authority tenders. For Investors and Strategic Acquirers: Long-term, this sits as a materials-science consolidation play because carbon-ceramic formulation expertise concentrates among aging specialist workforces in Germany and Japan. Acquisition targets with captive sintering operations and EN 45545 certification portfolios offer defensive positioning. Monitor India's metro network extension tendering volume as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Precursor Supply | German and Japanese chemical processors control critical feedstock for EN 45545-compliant formulations. |
| EN 45545 Certification Acceleration | European metro tendering treats fire-smoke toxicity compliance as a non-negotiable specification gate. |
| Predictive Maintenance Sensor Integration | Scandinavian and Dutch authorities unbundle supply from sensor-enabled remote monitoring contracts. |
| Magnetic Contact System Development | Singapore and Dubai automated metro deployments specify precision-engineered electromagnetic actuation. |
| India Corridor Manufacturing Footprint | Delhi, Mumbai, and Bangalore network extensions generate concentrated procurement volume for composite assemblies. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and rolling stock procurement databases through structured interviews with metro engineering directors, transit authority procurement managers, carbon materials R&D leads, and aftermarket maintenance contractors. Bottom-up demand modeling triangulates against top-down market sizing across product type, technology, application, and end-user segmentation dimensions.
Segmentation dimensions modeled include contact material formulation, actuation mechanism design, deployment environment characteristics, and procurement authority structure across the analysis window. CAGRs derive from elasticity-adjusted installation base projections and replacement cycle compression factors. Industry-specific forecast inputs incorporate EN 45545 adoption curves and India's CEA electrification compliance timelines.
Forecasts assume regulatory continuity in EU REACH and EN 45545 frameworks, India's CEA mandates, and China's GB/T standards; material policy shifts in fire-safety testing protocols or electrification subsidies would require re-modeling. Recalibration cycles align with material shifts in metro fleet electrification programs and composite material certification adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.