
 South America Gas Insulated Switchgear Market | 2026-2036
South America Gas Insulated Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
South America Gas Insulated Switchgear Market Insights
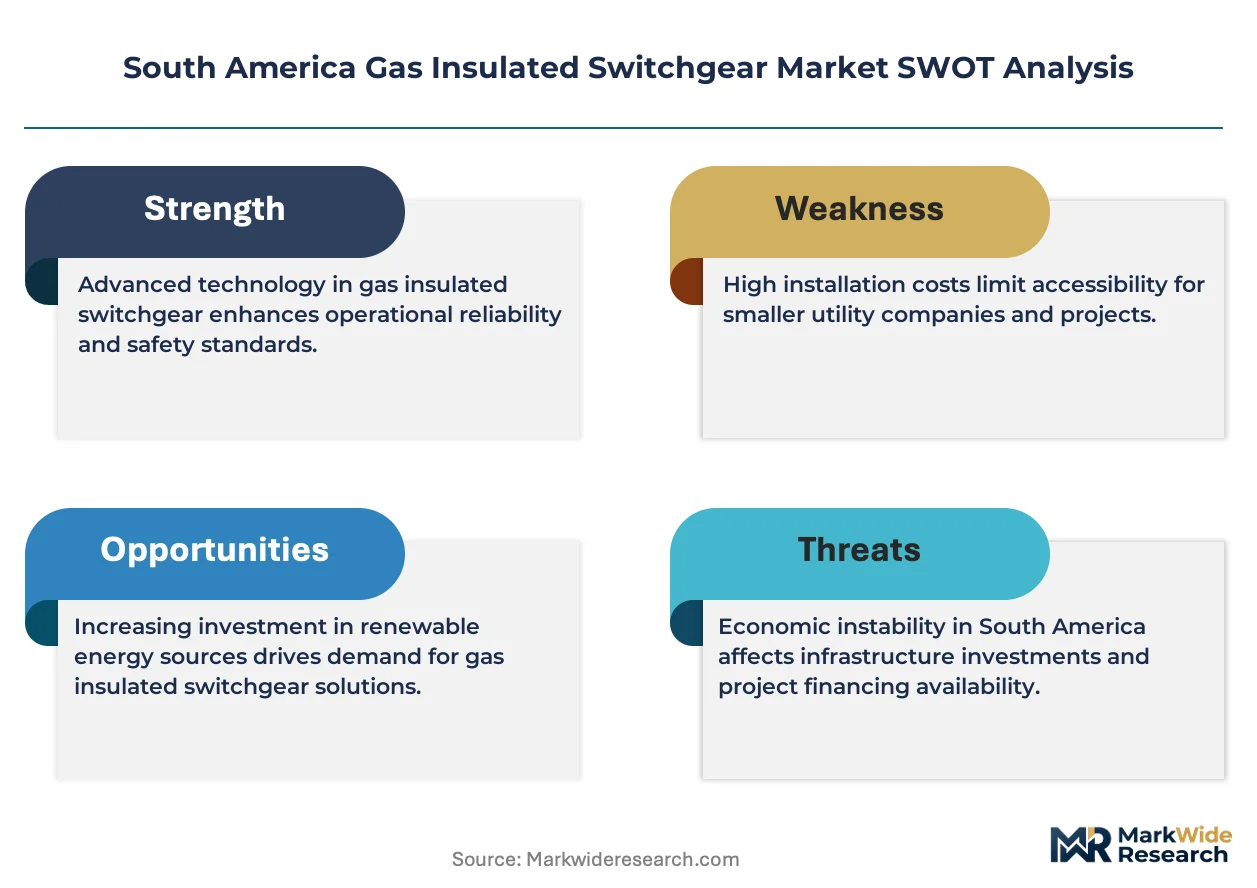
SF6 gas is rebalancing product economics across South America as environmental scrutiny intensifies and alternative insulation technologies mature. Siemens Energy leverages its regional manufacturing footprint to anchor supply security for Brazilian utilities. WEG competes through deep localization in São Paulo state, while ABB differentiates via technology leadership in vacuum-interruption systems for medium-voltage applications.
Gas insulated switchgear encloses electrical conductors and circuit breakers within sealed metal compartments pressurized with sulfur hexafluoride or alternative insulating gas, achieving dielectric strength roughly three times that of air at equivalent pressure; this compact architecture serves critical functions in space-constrained urban substations and high-reliability industrial installations. Medium voltage equipment dominates current procurement volumes across South American utilities, while high voltage installations represent the fastest-expanding category as countries reinforce cross-border transmission links. Renewable end users constitute a concentrated demand pocket, with developers of wind and solar parks specifying containerized GIS solutions to compress project timelines.
Brazil's ANEEL, Argentina's ENRE, and Chile's SEC collectively shape product standards through grid-code enforcement and environmental compliance timelines that manufacturers must satisfy for market access. SF6 phase-down protocols under these national regulators are redirecting procurement specifications toward vacuum and air-insulated alternatives, compressing technology transition windows for incumbent suppliers. Stakeholders must calibrate R&D commitments and local partnership strategies against the pace at which each national regulator tightens environmental performance thresholds.
Market Dynamics
SF6 phase-down mandates from Brazil's ANEEL are compressing technology transition windows across South American utilities, forcing simultaneous grid reliability investments and environmental compliance overhauls. Manufacturers must now dual-track R&D for vacuum-interruption and air-insulated alternatives while maintaining legacy gas-insulated production lines.
Growth Catalysts
- ANEEL grid reliability mandates:Brazil's regulatory authority enforces strict uptime standards that favor GIS compact footprint and sealed-environment durability over air-insulated alternatives in dense urban substations.
- Wind and solar park developers:Renewable energy projects across Argentina's Patagonia and Chile's Atacama specify containerized GIS solutions to accelerate commissioning timelines and reduce land acquisition requirements.
- Cross-border transmission reinforcement:Integration of remote hydroelectric and wind generation into national grids drives high-voltage GIS procurement for interconnectors between Brazil, Argentina, and Uruguay.
Market Restraints
- SF6 gas cost volatility:Sulfur hexafluoride pricing fluctuates with European F-Gas Regulation supply constraints, pressuring total cost of ownership calculations for utilities locked into gas-insulated architectures.
- Import dependency for specialized components:Vacuum interrupters and cast resin insulators concentrate manufacturing in European and East Asian facilities, exposing South American utilities to currency risk and extended lead times.
- Technical limitation in extreme altitude applications:Standard GIS dielectric performance degrades above 3,000 meters elevation, complicating deployment in Bolivia's Altiplano and Chilean Andean mining operations.
Strategic Opportunities
- Colombia's underpenetrated Andean corridor:Bogotá and Medellín utilities lag in GIS adoption relative to São Paulo, creating first-mover advantages for suppliers offering localized service networks.
- Digital twin integration:Convergence of GIS hardware with IoT sensors and predictive analytics platforms enables utilities to unbundle maintenance contracts and monetize operational data.
- Chile SEC carbon-neutral procurement guidelines:The national energy regulator's environmental scoring criteria create preferential purchasing pathways for SF6-free switchgear technologies.
Industry Challenges
- Specialized field technician scarcity:Vacuum interrupter maintenance and gas handling certification programs remain underdeveloped across Brazilian technical institutes, constraining service expansion.
- Legacy air-insulated substation integration:Retrofitting existing 138kV and 230kV open-air facilities with GIS modules requires complex busbar reconfiguration and extended outage windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Gas Insulated Switchgear Market |
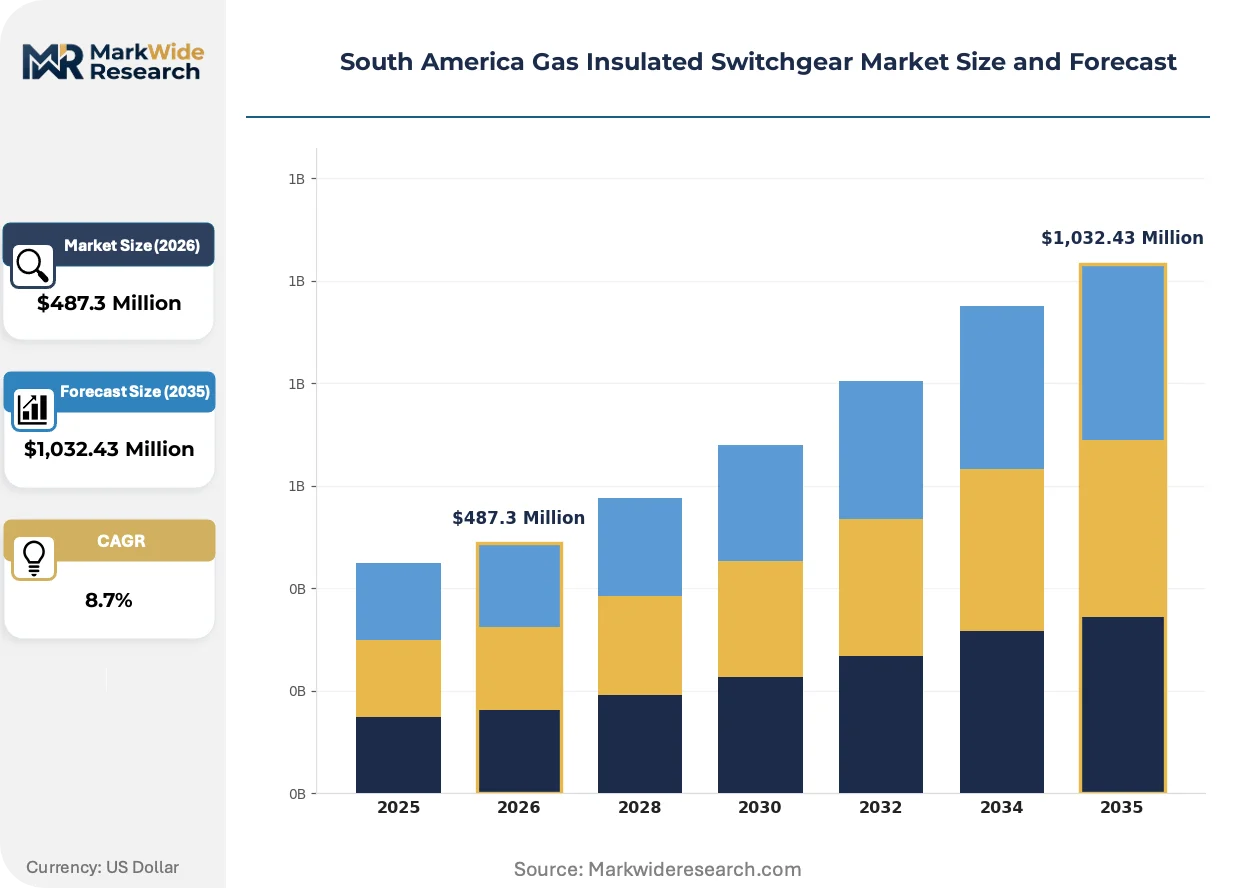
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medium Voltage, High Voltage, Super Voltage, Ultra High Voltage End User: Power Utilities, Industrial, Commercial, Renewable Installation Type: Indoor, Outdoor, Hybrid, Containerized Technology: SF6, Vacuum, Air Insulated, Others |
| Companies Covered | Eaton Corporation, General Electric Company, Siemens AG, Schneider Electric SE, Hitachi Energy Ltd, ABB, Siemens Energy, WEG, EFACEC, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Gas Insulated Switchgear Market Trends and Innovations
Alternative insulation technologies are maturing faster than regulatory deadlines, compressing the window for incumbent suppliers to recoup SF6-dependent R&D investments. The competitive frontier now centers on who can deliver certified vacuum-interruption systems at gas-insulated price parity.
Dry air insulation technology is expanding into medium-voltage distribution applications previously dominated by SF6-filled switchgear. Brazilian utilities in São Paulo state pilot 36kV air-insulated ring main units for urban underground networks. This technology is expanding into secondary substation designs, enabling utilities to defer gas handling infrastructure and simplify environmental compliance reporting.
Brazil's ANEEL Resolution 1,000 establishes mandatory SF6 leak monitoring and reporting thresholds for transmission assets above 230kV. Utilities must deploy infrared detection systems and maintain decade-long equipment registries. High-voltage GIS procurement specifications now prioritize sealed-for-life designs with welded tank construction over gasket-dependent architectures common in legacy installations.
Renewable developers now specify engineering-procurement-construction contracts with embedded GIS commissioning deadlines rather than equipment-only purchases. This bundling compresses supplier involvement from component delivery through energization, favoring manufacturers with regional installation partnerships. Argentina's wind sector exhibits this pattern most visibly, with developers in Buenos Aires province demanding 90-day energization guarantees.
South America Gas Insulated Switchgear Market Segmentation
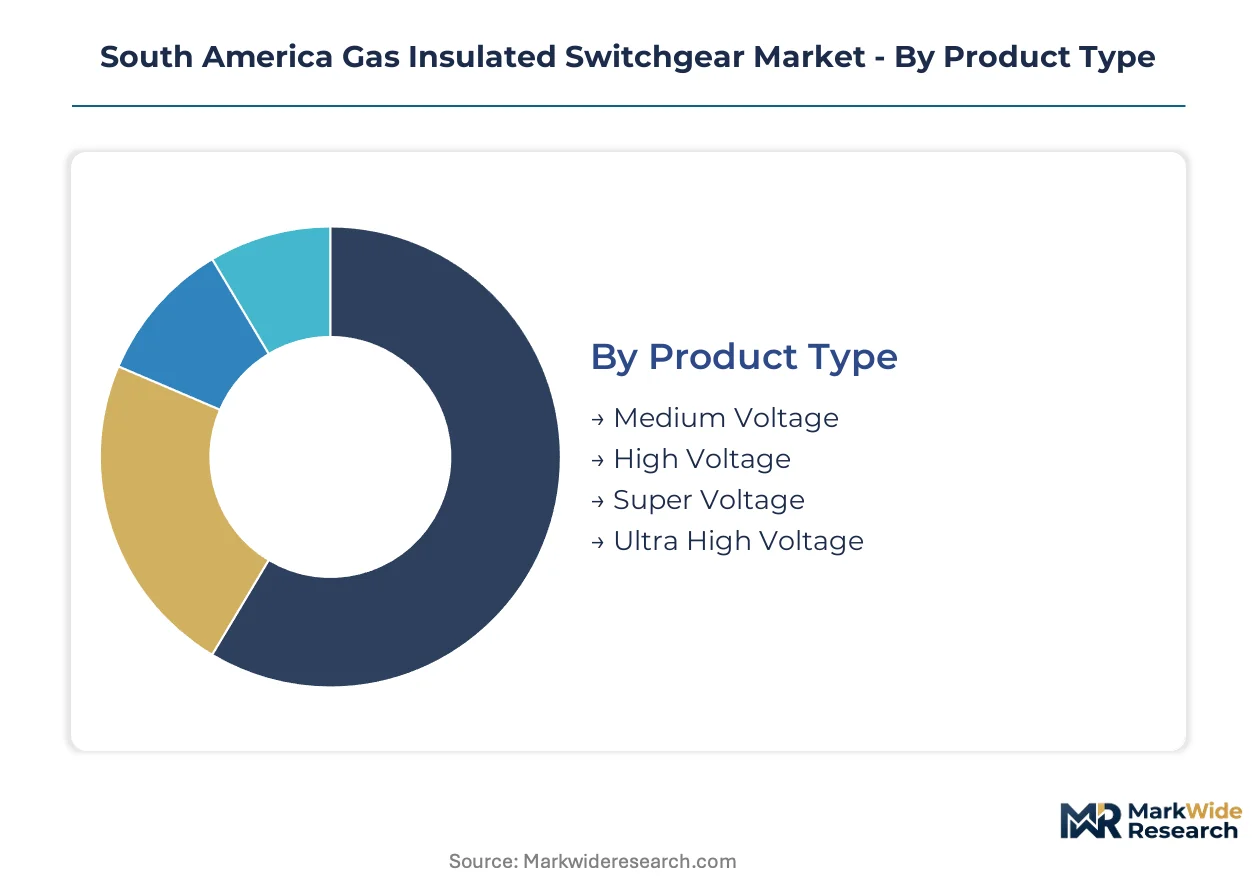
Segmentation reveals how capital allocation and regulatory pressure reshape procurement patterns across South American utilities. Voltage tier and insulation technology now determine supplier positioning more than geographic footprint alone.
Product Type:
Capital intensity escalates exponentially with voltage rating, compressing supplier margins at the highest tiers while medium voltage sustains volume-driven profitability.
- Medium Voltage:Equipment rated 1kV to 52kV dominates current procurement volumes across Brazilian distribution utilities. São Paulo's metropolitan network operators specify compact 36kV GIS modules for underground substations where land scarcity commands premium solutions.
- High Voltage:Installations spanning 72.5kV to 245kV anchor cross-border transmission reinforcement between Brazil, Argentina, and Uruguay. ANEEL reliability mandates accelerate replacement of aging air-insulated substations in Minas Gerais state's industrial corridor.
- Super Voltage:300kV to 550kV systems concentrate in hydroelectric integration projects.
- Ultra High Voltage:Above 550kV installations remain nascent, limited to conceptual interconnector studies.
Most installed capacity flows through Medium Voltage. Expansion is steepest in High Voltage.
End User:
Customer type dictates service intensity, with renewable developers demanding bundled EPC contracts while utilities retain component-only purchasing.
- Power Utilities:State-owned transmission operators in Brazil and Argentina drive scheduled replacement programs. Grid reliability penalties under ANEEL Resolution 1,000 force accelerated modernization of 138kV and 230kV assets.
- Renewable:Wind developers in Argentina's Patagonia and solar park operators in Chile's Atacama specify containerized GIS to compress commissioning timelines. Buenos Aires province developers now demand 90-day energization guarantees embedded in procurement contracts.
- Industrial:Mining and petrochemical facilities in southeastern Brazil prioritize sealed-environment durability.
- Commercial:Data center and hospital applications in São Paulo city favor compact indoor installations.
Power Utilities command the largest installed base. Renewable applications are climbing the fastest.
Installation Type:
Physical configuration determines logistics complexity, with containerized solutions commanding freight premiums that renewable developers willingly absorb.
- Indoor:Sealed metal-enclosed designs suit space-constrained urban substations in São Paulo and Bogotá. Underground network access requirements favor compact footprints that minimize excavation costs.
- Containerized:Factory-integrated modules enable rapid deployment for renewable projects with fixed commissioning deadlines. Argentine wind sector procurement now embeds GIS energization guarantees within EPC contracts rather than equipment-only purchases.
- Outdoor:Conventional open-air arrangements persist in legacy substations.
- Hybrid:Mixed configurations address retrofit scenarios requiring phased migration.
Indoor installations dominate urban utility procurement. Containerized formats are expanding most quickly.
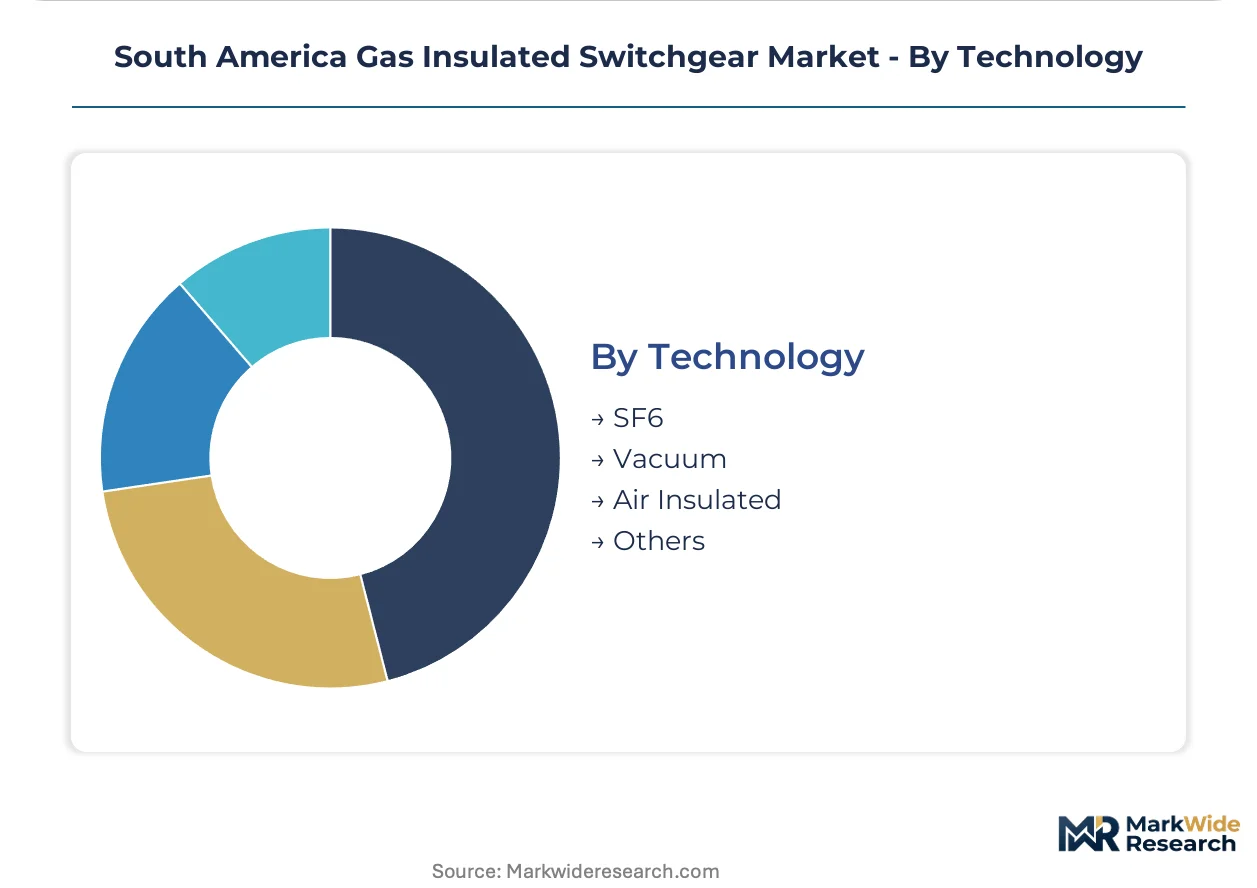
Technology:
Insulation medium now functions as a regulatory compliance variable, with environmental scoring criteria redirecting procurement specifications faster than pure economics would predict.
- SF6:Sulfur hexafluoride retains dielectric performance advantages but faces accelerating phase-down under Brazil's ANEEL mandates. European F-Gas Regulation supply constraints inject price volatility that utilities factor into total cost of ownership calculations.
- Vacuum:Interruption technology matures for medium-voltage applications, with Brazilian utilities piloting 36kV designs. Siemens Energy and ABB compete on certified vacuum systems that achieve gas-insulated price parity.
- Air Insulated:Dry air technology expands into secondary substation designs, enabling simplified environmental compliance reporting for São Paulo state utilities.
- Others:Fluoronitrile and fluoroketone blends remain developmental for high-voltage tiers.
SF6 retains the largest installed base. Vacuum technology is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The southeastern industrial corridor spanning São Paulo and Minas Gerais states anchors South American GIS demand. Brazil's regulatory mandates and transmission expansion programs concentrate procurement volumes. Cross-border interconnectors and renewable integration projects distribute activity across Argentina, Chile, Colombia, and Uruguay.
Brazil
ANEEL's grid reliability mandates and SF6 phase-down protocols drive replacement of aging 138kV and 230kV substations. Resolution 1,000 establishes mandatory leak monitoring thresholds for transmission assets above 230kV. São Paulo metropolitan operators specify compact 36kV modules for underground networks where land scarcity commands premium solutions.
Argentina
Wind developers in Buenos Aires province and Patagonia specify containerized GIS with 90-day energization guarantees embedded in EPC contracts. ENRE grid-code enforcement shapes product standards for market access. Cross-border transmission reinforcement with Brazil and Uruguay concentrates high-voltage procurement in the northeastern industrial belt.
Chile
Solar park operators in the Atacama Desert prioritize rapid-deployment containerized solutions to compress commissioning timelines. SEC carbon-neutral procurement guidelines create preferential purchasing pathways for SF6-free technologies. Mining operations in the Andean highlands face technical constraints as standard GIS dielectric performance degrades above 3,000 meters elevation.
Colombia
Bogotá and Medellín utilities lag São Paulo in GIS adoption, creating first-mover advantages for suppliers with localized service networks. The country's national energy regulator enforces environmental compliance timelines that redirect procurement specifications. Andean corridor industrial clusters generate concentrated demand for medium-voltage urban substation upgrades.
Uruguay
Integration of remote wind generation into the national grid drives high-voltage GIS procurement for Brazil-Uruguay interconnectors. The state-owned transmission operator manages scheduled replacement programs for cross-border assets. Montevideo's metropolitan network operators evaluate compact indoor installations for space-constrained urban substations.
South America Gas Insulated Switchgear Market Competitive Landscape
Global majors compete with regional champions across technology licensing and manufacturing localization. The supplier base concentrates around three tiers: integrated electrical conglomerates with full voltage-range portfolios, regional manufacturers with deep in-country fabrication, and specialized component suppliers. Dominant competitive moves include backward integration into vacuum interrupter production and strategic partnerships for containerized system integration.
Within the integrated conglomerate tier, Siemens AG and ABB exemplify technology leadership archetypes, while WEG represents the regional champion model with São Paulo-state manufacturing depth. Eaton Corporation and Schneider Electric SE occupy positions bridging global scale with localized service networks. These five anchors demonstrate how competitive positioning stratifies across technology certification, manufacturing proximity, and aftermarket service density rather than price alone.
| Leading Market Players |
|---|
| Eaton Corporation |
| General Electric Company |
| Siemens AG |
| Schneider Electric SE |
| Hitachi Energy Ltd |
| ABB |
| Siemens Energy |
| WEG |
| EFACEC |
| Others |
Pricing and Supply Chain Analysis
ANEEL's SF6 phase-down mandates gate qualified supply and premium-tier pricing access for Brazilian utilities, compressing the window for manufacturers to certify vacuum-interruption alternatives while maintaining legacy gas-insulated production economics. Buyers seeking ANEEL-compliant equipment face constrained vendor pools and extended lead times that translate into pricing power for certified suppliers.
Pricing Analysis
Input-cost pass-through from European F-Gas Regulation supply constraints intensifies pricing pressure on SF6-dependent equipment tiers, forcing utilities to recalculate total cost of ownership across gas-insulated versus vacuum-interruption architectures. Three-tier pricing structure across premium, standard, and economy levels separates sealed-for-life welded-tank designs from gasket-dependent legacy systems and basic air-insulated alternatives. Cost compression in medium-voltage segments runs through accelerated localization by WEG and Siemens Energy. Renewable developers in Argentina's wind sector exhibit lowest price sensitivity due to embedded EPC contracting with 90-day energization guarantees.
Supply Chain Analysis
Reverse-logistics flows for vacuum interrupter refurbishment and SF6 gas recovery create aftermarket revenue streams that anchor service-network economics for incumbent suppliers. Manufacturing concentrates in Brazil, Germany, and Switzerland for core GIS assemblies, while vacuum interrupters and cast resin insulators source from specialized facilities in Japan and Italy. Raw material dependencies span sulfur hexafluoride gas, epoxy resin systems, and copper conductor stock. Single-source vulnerability concentrates in European vacuum interrupter supply. Distribution runs through utility procurement departments, EPC contractors, and direct manufacturer relationships for large transmission projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America Gas Insulated Switchgear Market functions as a stable compounder, with ANEEL regulatory mandates and renewable integration programs delivering predictable procurement volumes across the analysis window.
For Market Incumbents: Deepen backward integration into vacuum interrupter production to reduce dependency on Japanese and Italian component suppliers. Expand certified service technician programs across São Paulo and Minas Gerais states to capture maintenance contract economics from ANEEL Resolution 1,000 leak monitoring requirements. Address emerging threat from SF6-free technology migration by accelerating price-parity positioning for vacuum-interruption systems. For New Entrants and Emerging Players: Begin with Colombia's underpenetrated Andean corridor, where Bogotá and Medellín utilities lag São Paulo in GIS adoption and localized service networks remain sparse. Target containerized GIS formats for Chilean solar park developers seeking rapid-deployment solutions under SEC carbon-neutral procurement guidelines. Pursue engineering-procurement-construction partnerships with Argentine wind developers as the primary go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among regional manufacturers with São Paulo-state fabrication depth and incomplete vacuum-interruption certification portfolios. Long-term viability hinges on technology transition completion across the projection horizon. Target acquisition archetype: mid-cap Brazilian manufacturers with established utility relationships and underinvested R&D pipelines. Monitor ANEEL enforcement intensity on SF6 leak thresholds as the critical inflection signal for technology substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum Interrupter Backward Integration | Captive supply of critical components reduces currency exposure and lead time risk for Brazilian utilities. |
| Containerized GIS Platform Standardization | Factory-integrated modules compress commissioning timelines for Patagonia wind developers under fixed deadlines. |
| SF6-Free Technology Certification | ANEEL environmental scoring criteria redirect procurement specifications toward compliant suppliers. |
| Andean Service Network Expansion | First-mover positioning in Bogotá and Medellín captures utility modernization programs. |
| Digital Twin Integration Partnership | Predictive analytics platforms enable utilities to monetize operational data from GIS assets. |
Research Methodology
Coverage spans South America with primary inputs from each major national market, combining structured interviews with utility planning officers, EPC contractors, renewable project developers, and aftermarket service heads with secondary validation. Primary fieldwork engaged transmission asset managers at Brazil's state-owned operators, procurement leads at Argentine wind developers, and grid operators at Chile's SEC-regulated utilities. Secondary sources include ANEEL regulatory filings, ENRE grid-code documentation, SEC procurement guidelines, customs and trade data for GIS component imports, and utility capital expenditure disclosures. Bottom-up equipment procurement tracking triangulates against top-down transmission investment forecasts.
Rate-of-change decomposition separates volume growth from price-mix effects across voltage tier, insulation technology, installation type, and end-user segment throughout the forecast period. Segmentation dimensions modeled include product type, end user, installation configuration, and technology platform, with regional regulatory cluster as an additional cross-cutting variable. CAGRs derive from utility capital expenditure pipelines, renewable project development databases, and ANEEL-mandated replacement schedules for aging 138kV and 230kV assets. Industry-specific inputs incorporate SF6 gas price volatility indices and vacuum interrupter supply lead time trends.
Several conditions sit outside the modeled scope, including abrupt currency devaluations in Argentina, political discontinuities affecting cross-border transmission agreements, and technological breakthroughs in solid-state switchgear that could displace vacuum-interruption architectures. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and renewable project completion rates. Practitioners should monitor ANEEL Resolution 1,000 enforcement intensity, European F-Gas Regulation supply restrictions, and Chilean mining sector altitude-deployment technical resolutions for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
AV Power Conditioners Market
Electrical Power Equipment
High Voltage Ionising Air Gun Market
Electrical Power Equipment
Middle East and Africa Hazardous Location Motor Starters Market
Electrical Power Equipment
Magnetic Ballast Market
Electrical Power Equipment
Electric Submersible Pump Cable Market
Electrical Power Equipment
Utility Equipment Market
Electrical Power Equipment
Composite Insulators Market
Electrical Power Equipment
Europe Brushless DC Motors Market
Electrical Power Equipment
GCC Induction Motor Market
Electrical Power Equipment
Electric Substation Market
Electrical Power Equipment
Switching Residential Voltage Regulator Market
Electrical Power Equipment
Carbon Brush Market
Electrical Power Equipment
Alternators Market
Electrical Power Equipment
Global Magnetic Circuit Breaker Market
Electrical Power Equipment
Europe Alternating Current (AC) Drive Market
Electrical Power Equipment
Electric Insulator Market