
 Power Over Ethernet Lighting Market | 2026-2036
Power Over Ethernet Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Power Over Ethernet Lighting Market Outlook
Market Context
Modular fixture-and-control bundling is broadening buyer choice in PoE lighting procurement. Signify Holding leverages its luminaire portfolio to anchor integrated system offerings across commercial verticals. Cisco Systems competes through networking infrastructure that extends PoE power distribution into lighting endpoints. Wipro Lighting specializes in project-specific configurations for office and retail deployments in Asia-Pacific markets.
Technical Definition and Segments
Power over Ethernet lighting delivers both electrical power and data connectivity to luminaires through standard Ethernet cabling, typically operating at 55-100 watts per port under IEEE 802.3bt to support LED arrays, sensors, and control modules in a single infrastructure layer. LED product types dominate value capture due to efficiency mandates and declining semiconductor costs, while smart controls represent the fastest-expanding margin pool as building operators prioritize programmable automation. Commercial installation channels sustain premium pricing compared to residential segments, with warehouses and schools under end-user classification showing concentrated retrofit activity.
Regulatory Frame and Outlook
The IEEE 802.3 standards body governs power delivery specifications, while the EU Ecodesign Directive and U.S. Department of Energy efficiency rules shape product compliance thresholds across major markets. China's GB standards and MIIT technology roadmaps further condition market access for imported PoE lighting components. Stakeholders must monitor evolving power-over-cable limits and regional building electrification codes to align R&D roadmaps with enforceable deployment requirements.
Market Dynamics
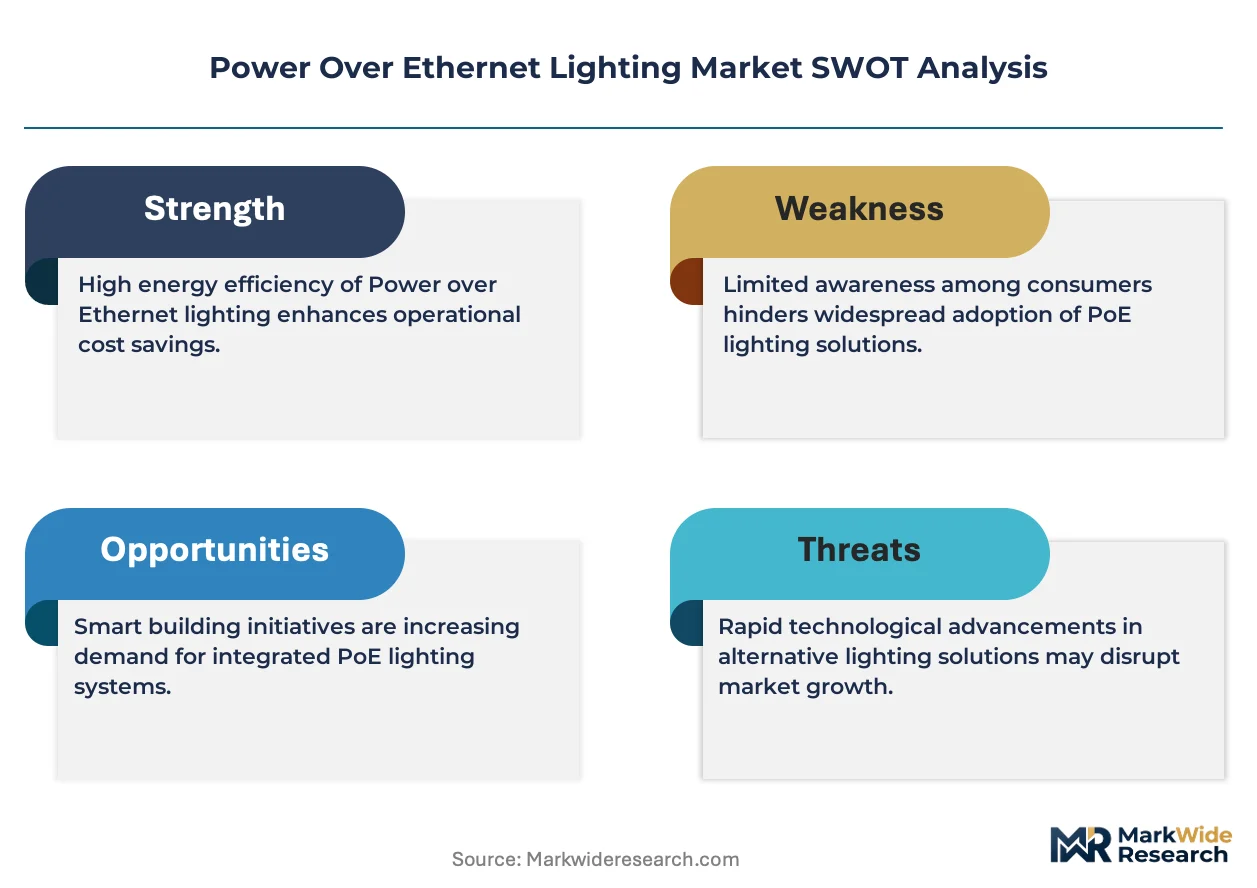
The transition from proprietary lighting control protocols to open IP-based architectures is compressing vendor lock-in and forcing incumbent fixture manufacturers to cede margin to networking specialists who now own the power distribution layer.
Growth Catalysts
- Building electrification mandates:The EU Ecodesign Directive's 2023 tightening of standby power limits for lighting systems is accelerating LED-to-PoE retrofits in German and French commercial real estate portfolios.
- Sensor fusion architectures:Occupancy detection, air quality monitoring, and daylight harvesting through unified PoE endpoints is displacing siloed building management systems in US Class A office towers.
- Installation labor arbitrage:Reduction of separate electrical and data contractor mobilizations is cutting project timelines by 30-40% in Singapore and Dubai smart building developments.
Market Restraints
- Copper cable cost volatility:Fluctuations in Cat6A and Cat8 copper pricing are compressing gross margins for system integrators bidding fixed-price commercial contracts.
- Power budget physics:IEEE 802.3bt's 90-watt ceiling constrains high-lumen output fixtures in atrium and industrial high-bay applications, forcing hybrid AC-PoE designs.
- Qualified installer scarcity:Shortage of BICSI-certified technicians capable of certifying PoE power delivery is extending commissioning timelines in secondary US metropolitan markets.
Strategic Opportunities
- Healthcare vertical penetration:Patient room circadian lighting programs at Kaiser Permanente and NHS trusts are creating specification pull for tunable-white PoE systems with clinical-grade uptime requirements.
- DC microgrid convergence:Integration of PoE lighting with 380V DC building distribution eliminates AC-DC conversion losses, attracting hyperscale data center operators in Northern Virginia and Frankfurt.
- Indoor positioning services:Visible light communication (VLC) overlays on PoE luminaires are enabling sub-meter asset tracking, opening recurring SaaS revenue streams from warehouse operators.
Industry Challenges
- Legacy DALI integration complexity:Bridging existing DALI-2 controlled fixtures into PoE-managed zones requires protocol gateway hardware that adds cost and failure points.
- Cybersecurity certification lag:UL 2900 and IEC 62443 compliance timelines for networked lighting controls are extending product launch cycles by 8-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Over Ethernet Lighting Market |
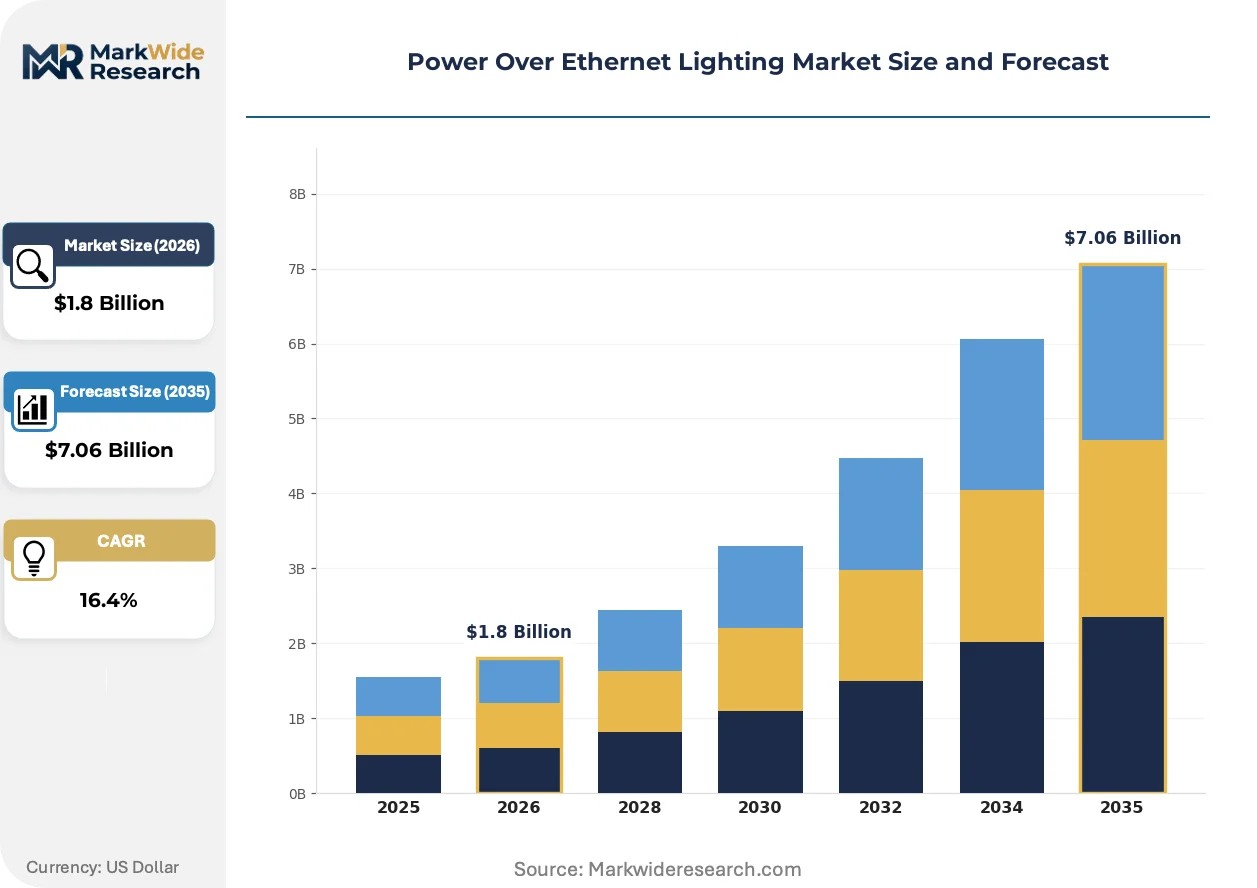
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Smart Controls, Fixtures, Sensors Installation: Commercial, Industrial, Residential, Outdoor End User: Offices, Retail Spaces, Warehouses, Schools Connectivity: Wired, Wireless, Hybrid, Others |
| Companies Covered | Igor, Innovative Lighting, Signify Holding, Molex, H.E. Williams, Hubbell, NuLEDs, Wipro Lighting, Cisco Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Over Ethernet Lighting Market Strategic Shifts
Standardization of power delivery specifications is eroding proprietary control ecosystems while opening the fixture layer to commodity competition. Vendors now compete on software-defined lighting experiences rather than hardware differentiation alone.
PoE++ switch hardware is modularizing around disaggregated power supply units and fanless designs. Colocation facilities and edge data centers are adopting these configurations for hot-aisle containment zones. This architecture is modularizing procurement patterns, allowing facility managers to scale power budgets incrementally rather than overprovisioning upfront.
The EU's F-Gas Regulation is accelerating phase-out of fluorescent lamp ballasts containing sulfur hexafluoride, creating regulatory pull for all-LED PoE retrofits in institutional buildings. Member state transposition variations are fragmenting compliance timelines, with Germany's Bundesimmissionsschutzverordnung enforcing stricter disposal requirements than southern European counterparts. Healthcare and education verticals face the steepest retrofit obligations under national building renovation roadmaps.
Facility managers are consolidating vendor relationships through master service agreements that bundle lighting-as-a-service with HVAC and access control. This purchasing consolidation is compressing the specifier channel, with MEP engineers losing influence to procurement departments armed with total-cost-of-ownership models. The shift is most pronounced in US commercial office portfolios managed by Blackstone and Brookfield, where standardization across multi-building footprints overrides project-specific customization.
Power Over Ethernet Lighting Market Segmentation
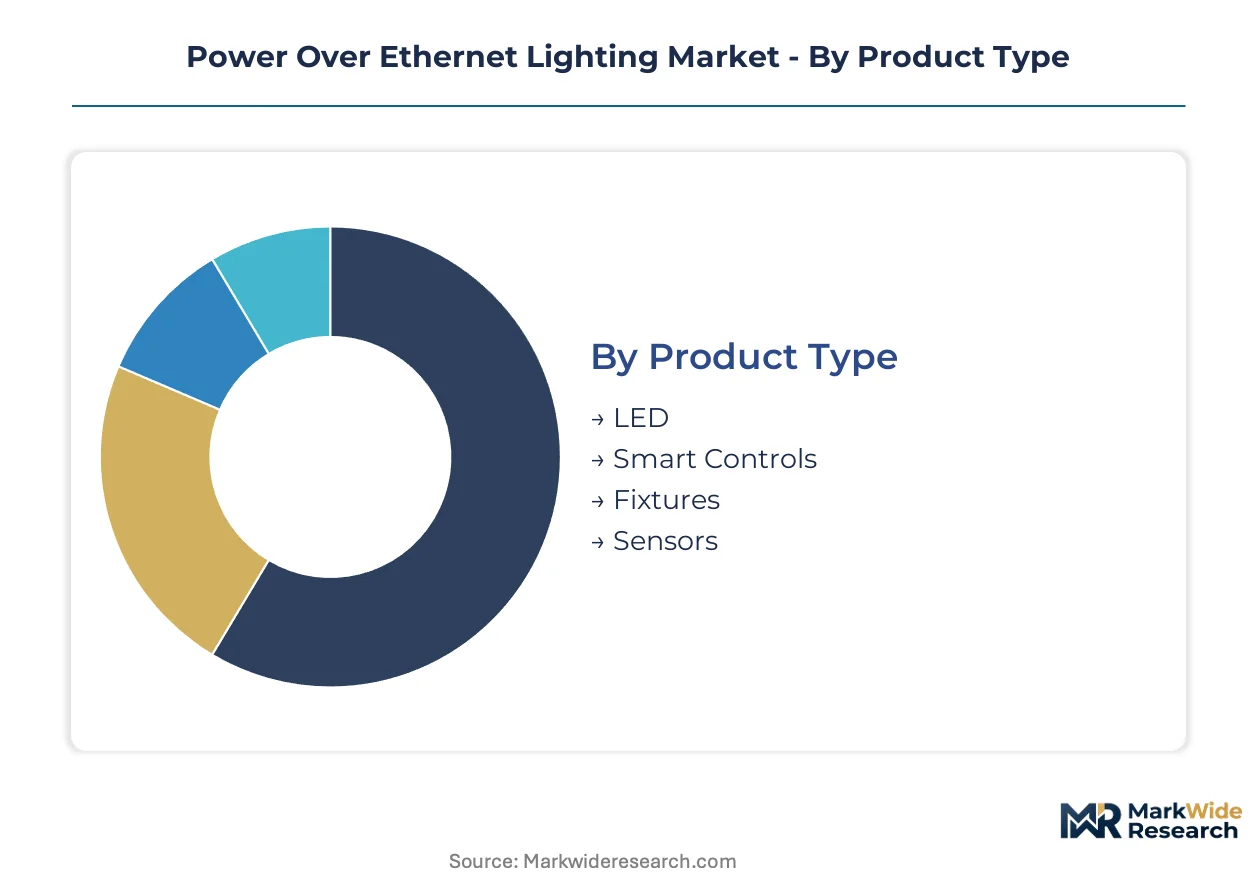
PoE lighting procurement decisions cascade through multiple technical and commercial dimensions. Product specifications determine power budget allocation. Installation context governs labor economics and code compliance. End-use requirements shape uptime expectations and integration complexity.
Product Type:
LED luminaires dominate volume shipments while smart controls command premium pricing expansion.
- LED:Solid-state arrays operating at 90W IEEE 802.3bt ceilings deliver lumen packages sufficient for open-plan offices. Demand concentrates in US commercial retrofits where DOE efficiency rules accelerate fluorescent displacement.
- Smart Controls:Programmable dimming, circadian scheduling, and daylight harvesting algorithms execute at the network edge. German and French building operators specify these for Ecodesign Directive compliance and granular energy accountability.
- Fixtures:Modular housings accommodating PoE driver modules and sensor mounts.
- Sensors:Occupancy detection and environmental monitoring endpoints.
Today's leader: LED. Tomorrow's challenger: Smart Controls.
Installation:
Channel economics separate specification-heavy commercial deployments from price-sensitive residential adoption.
- Commercial:Class A office towers and corporate campuses in Singapore and Dubai deploy integrated PoE for 30-40% installation timeline compression. MEP engineers specify integrated power-data infrastructure to reduce contractor mobilization.
- Industrial:High-bay warehousing and manufacturing facilities face IEEE 802.3bt power ceiling constraints, forcing hybrid AC-PoE architectures for lumen-intensive applications.
- Residential:Single-family and multifamily deployments remain limited by electrician preference for conventional line-voltage wiring.
- Outdoor:Street furniture and campus pathway lighting requiring IP-rated enclosures and extended temperature operating ranges.
Commercial installations anchor current revenue. Industrial retrofits are climbing fastest as warehouse automation demands unified infrastructure.
End User:
Workplace modernization budgets outpace institutional capital cycles, concentrating near-term deployment.
- Offices:Blackstone and Brookfield portfolio standardization drives master service agreements bundling lighting-as-a-service with HVAC. US Class A towers prioritize sensor fusion for hot-desking optimization.
- Retail Spaces:Merchandising teams demand tunable-white systems for product color rendering consistency.
- Warehouses:Indoor positioning services via visible light communication overlays attract operators seeking sub-meter asset tracking accuracy.
- Schools:EU F-Gas Regulation fluorescent phase-out obligations accelerate institutional retrofits, with German Bundesimmissionsschutzverordnung enforcing stricter disposal timelines than southern European counterparts.
Offices command specification authority today. Warehouses are gaining share fastest through automation-linked infrastructure investment.
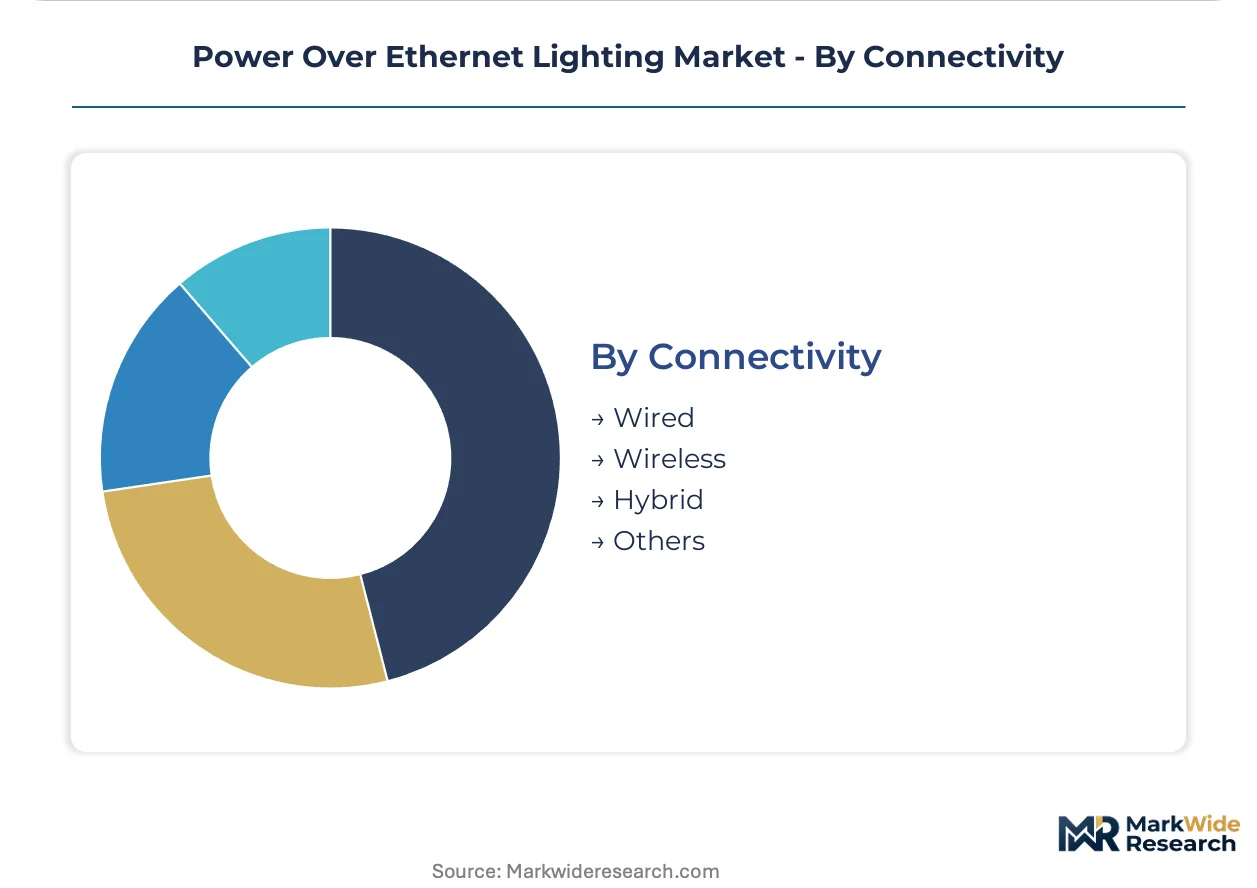
Connectivity:
Physical layer choices trade installation flexibility against cybersecurity surface area and power delivery certainty.
- Wired:Cat6A and Cat8 copper infrastructure delivers guaranteed 90W power budgets with deterministic latency for real-time control loops. BICSI-certified technician scarcity extends commissioning timelines in secondary US metropolitan markets.
- Wireless:Zigbee and Bluetooth mesh overlays reduce cabling requirements but introduce battery maintenance or local power injection complexity.
- Hybrid:Segmented architectures combining wired power backbone with wireless sensor extensions.
- Others:Proprietary RF and powerline communication variants in legacy retrofit scenarios.
Wired architectures defend mission-critical deployments. Hybrid configurations are expanding most quickly as facility managers balance reliability against incremental installation cost.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PoE lighting commercialization traces its roots to early Ethernet standardization efforts in the United States during the late 1990s, with IEEE 802.3af establishing baseline power delivery that later expanded through 802.3at and 802.3bt revisions. Deployment patterns now concentrate in markets with aggressive building electrification mandates and mature smart building ecosystems.
United States
Class A office towers in Manhattan and Chicago drive specification volume as Blackstone and Brookfield standardize master service agreements across portfolios. The Department of Energy enforces efficiency rules that accelerate fluorescent displacement in commercial retrofits. Northern Virginia's hyperscale data center corridor experiments with DC microgrid convergence for 380V distribution.
Germany
The Bundesimmissionsschutzverordnung enforces stricter fluorescent disposal timelines than EU baseline requirements, forcing institutional retrofits in healthcare and education verticals. The Ecodesign Directive's standby power limits tighten compliance thresholds for lighting systems. Frankfurt's financial district clusters demand tunable-white systems for circadian programming in premium workspaces.
China
MIIT technology roadmaps condition market access for imported PoE components while GB standards govern domestic product certification. Yangtze River Delta manufacturing clusters produce LED driver modules at scale for regional system integrators. Shanghai's Pudong district hosts pilot deployments integrating PoE lighting with municipal smart city infrastructure.
Singapore
Building and Construction Authority codes incentivize integrated power-data infrastructure in new commercial developments. The city-state's smart nation initiative funds sensor fusion architectures in government-owned properties. Marina Bay and Jurong Lake District projects demonstrate 30-40% installation timeline compression through unified contractor mobilization.
United Arab Emirates
Dubai's green building regulations mandate energy management systems in commercial developments above specified floor areas. TAQA and other state-linked developers specify PoE for portfolio-wide standardization in hospitality and mixed-use assets. Dubai Design District and Expo City clusters serve as demonstration sites for indoor positioning services via visible light communication overlays.
Power Over Ethernet Lighting Market Competitive Environment
Premium-margin players sit above commodity-margin players across software-defined control capabilities and certified integration services. The vendor base stratifies between networking infrastructure specialists who own power distribution layers and luminaire manufacturers adapting to open IP architectures. Three archetypes dominate: integrated system bundlers, networking-centric power distributors, and regional project configurators. Competitive moves concentrate on strategic partnerships bridging fixture and network domains, plus geographic expansion through local certification acquisition.
Within the integrated system tier, Signify Holding and Cisco Systems exemplify divergent approaches to market positioning. Signify leverages luminaire portfolio breadth to anchor bundled offerings across commercial verticals. Cisco competes through networking infrastructure that extends PoE power distribution into lighting endpoints. Wipro Lighting occupies a position among Asia-Pacific project configurators specializing in office and retail deployment specifications. These three represent how vendor archetypes map to distinct margin pools and customer relationship models.
| Leading Market Players |
|---|
| Igor |
| Innovative Lighting |
| Signify Holding |
| Molex |
| H.E. Williams |
| Hubbell |
| NuLEDs |
| Wipro Lighting |
| Cisco Systems |
| Others |
Value Chain & Pricing Dynamics
Commercial real estate portfolio managers at Blackstone and Brookfield anchor pricing power through master service agreements that bundle lighting-as-a-service with HVAC and access control, compressing project-specific customization premiums into standardized recurring contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling. Premium tiers carry UL 2900 and IEC 62443 cybersecurity compliance plus clinical-grade uptime guarantees for healthcare deployments. Cost compression in standard tiers intensifies because copper cable volatility forces system integrators to absorb margin risk on fixed-price commercial contracts. Residential electricians show highest price sensitivity, while data center operators in Northern Virginia demonstrate lowest sensitivity due to DC microgrid convergence savings.
Supply Chain Analysis
Cat6A and Cat8 copper cable supply rests on Chinese smelters, South Korean wire manufacturers, and German specialty cable producers for high-frequency data transmission. LED driver module production draws from Yangtze River Delta foundries and Taiwanese semiconductor packaging houses. Single-source vulnerability concentrates in IEEE 802.3bt-compliant power sourcing equipment where Cisco Systems and Huawei dominate switch silicon. Distribution runs through BICSI-certified system integrators for commercial commissioning, with direct OEM relationships serving hyperscale data center operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as building operators shift demand toward clinical-grade uptime specifications and cybersecurity-certified controls that command durable margin premiums.
For Market Incumbents: To counter networking specialists ceding margin from fixture manufacturers, Signify Holding and Hubbell should deepen captive supply of PoE driver modules through backward integration into LED semiconductor packaging. Prioritize UL 2900 certification investment to extend product launch cycles into defensible premium tiers. For New Entrants and Emerging Players: Sensor fusion software for occupancy detection and air quality monitoring offers the most penetrable wedge into US Class A office towers where MEP engineers seek unified building management alternatives. Target warehouse automation verticals in Dubai and Singapore through indoor positioning service overlays that generate recurring SaaS revenue. For Investors and Strategic Acquirers: Networking infrastructure specialists are the most active acquirer in this space, with Cisco Systems and Huawei seeking fixture-layer capabilities to complete vertical integration. Over a five-to-ten-year window, acquisition targets center on Asia-Pacific project configurators with BICSI-certified installation networks. Watch IEEE 802.3bt power ceiling revision timelines as the critical inflection signal for hybrid AC-PoE architecture obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | UL 2900 and IEC 62443 compliance opens healthcare specification channels at Kaiser Permanente and NHS trusts. |
| Backward Integration into Driver Modules | Yangtze River Delta LED semiconductor packaging captive supply insulates margin from copper cable volatility. |
| Sensor Fusion Platform Launch | Unified occupancy and air quality endpoints displace siloed building management systems in Singapore government properties. |
| DC Microgrid Partnership | 380V distribution convergence with Northern Virginia hyperscale operators eliminates AC-DC conversion losses. |
| Indoor Positioning Service Rollout | Visible light communication overlays enable sub-meter asset tracking SaaS revenue from Dubai warehouse operators. |
Study Parameters
Coverage spans the United States, Germany, China, Singapore, and the United Arab Emirates, with primary inputs from each combining interviews with MEP engineers, BICSI-certified system integrators, commercial real estate portfolio managers, and LED driver module procurement leads. Secondary validation draws from IEEE 802.3 standards documentation, EU Ecodesign Directive regulatory filings, MIIT technology roadmaps, and SEC 10-K disclosures from networking infrastructure specialists. Bottom-up shipment data from fixture manufacturers triangulates against top-down building electrification mandate spending models.
Granularity-level framing models product type at the SKU level for LED luminaires and smart controls, installation channel at the project-bid level for commercial versus industrial segments, and end-user vertical at the specification-authority level for offices versus warehouses. CAGR derivation across the analysis window applies logistic adoption curves for IEEE 802.3bt transition timing and regulatory compliance deadline clustering. Industry-specific inputs include copper cable futures pricing volatility indices and BICSI technician certification pipeline data.
The model holds under stable IEEE 802.3 standards evolution and continued Ecodesign Directive enforcement; deviation in F-Gas Regulation transposition timelines or IEEE power ceiling revisions would shift retrofit acceleration curves. Forecasts reflect documented assumptions about building electrification mandate continuity and cybersecurity certification timeline normalization. A small set of named triggers warrants ongoing watch: IEEE 802.3bt successor standard development, EU F-Gas Regulation member state enforcement variance, and BICSI certification program expansion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Latin America Hazardous Location Motor Starters Market
Electrical Power Equipment
AV Power Conditioners Market
Electrical Power Equipment
Train Contactor Market
Electrical Power Equipment
High Voltage Oil Insulated Switchgear Market
Electrical Power Equipment
GCC Induction Motor Market
Electrical Power Equipment
ESE Lightning Rod Market
Electrical Power Equipment
Solar Combiner Boxes Market
Electrical Power Equipment
Gas Water Heater Market
Electrical Power Equipment
Domestic Hot Water (DHW) Tanks Market
Electrical Power Equipment
High Voltage Direct Current (HVDC) Cables Market
Electrical Power Equipment
Low Voltage Protection Control Market
Electrical Power Equipment
Fault Circuit Indicator Market
Electrical Power Equipment
India Gas Insulated Switchgear Market
Electrical Power Equipment
Global Electric Power Substation Automation Market
Electrical Power Equipment
Frameless Brushless DC Motors Market
Electrical Power Equipment
Electric Insulator Market