
 High Voltage Ionising Air Gun Market | 2026-2036
High Voltage Ionising Air Gun Market Size, Share, and Industry Trends Forecast 2026-2036
High Voltage Ionising Air Gun Market Insights
REACH compliance is repositioning material selection for ionizing air gun housings and emitter assemblies across European supply chains. Simco-Ion leverages its corona discharge patent portfolio to anchor premium positioning in semiconductor cleanroom deployments. EXAIR Corporation sustains North American channel control through integrated compressed-air system bundling. Meech International specializes in textile anti-static applications, occupying a defensible niche against generalized competitors.
A high voltage ionising air gun generates balanced ion streams through corona discharge or needle ionizer architectures, typically operating at 5-7 kV emitter potentials to neutralize electrostatic charges on sensitive surfaces. The device combines compressed air delivery with real-time ion polarity switching, protecting semiconductor wafers and electronic assemblies from electrostatic discharge damage during handling. Handheld configurations dominate current manufacturing plant installations due to operator flexibility, while multi-nozzle systems capture expanding margin pools in automated electronics assembly lines where throughput scaling drives equipment replacement cycles. Corona discharge technology leads in unit economics for standard cleanroom protocols, though plasma-based systems are gaining traction in next-generation nanofabrication facilities requiring sub-micron particle control.
EPA industrial effluent guidelines shape emitter material specifications in US manufacturing plants, while REACH restricts certain plating chemistries used in European needle ionizer production. China's GB standards for electrostatic protection in electronics manufacturing mandate ionizer deployment in Class 1000 and cleaner environments, directly conditioning procurement volumes. Stakeholders must weigh regional certification divergence against platform standardization strategies as cleanroom classifications tighten and cross-border equipment qualification costs escalate.
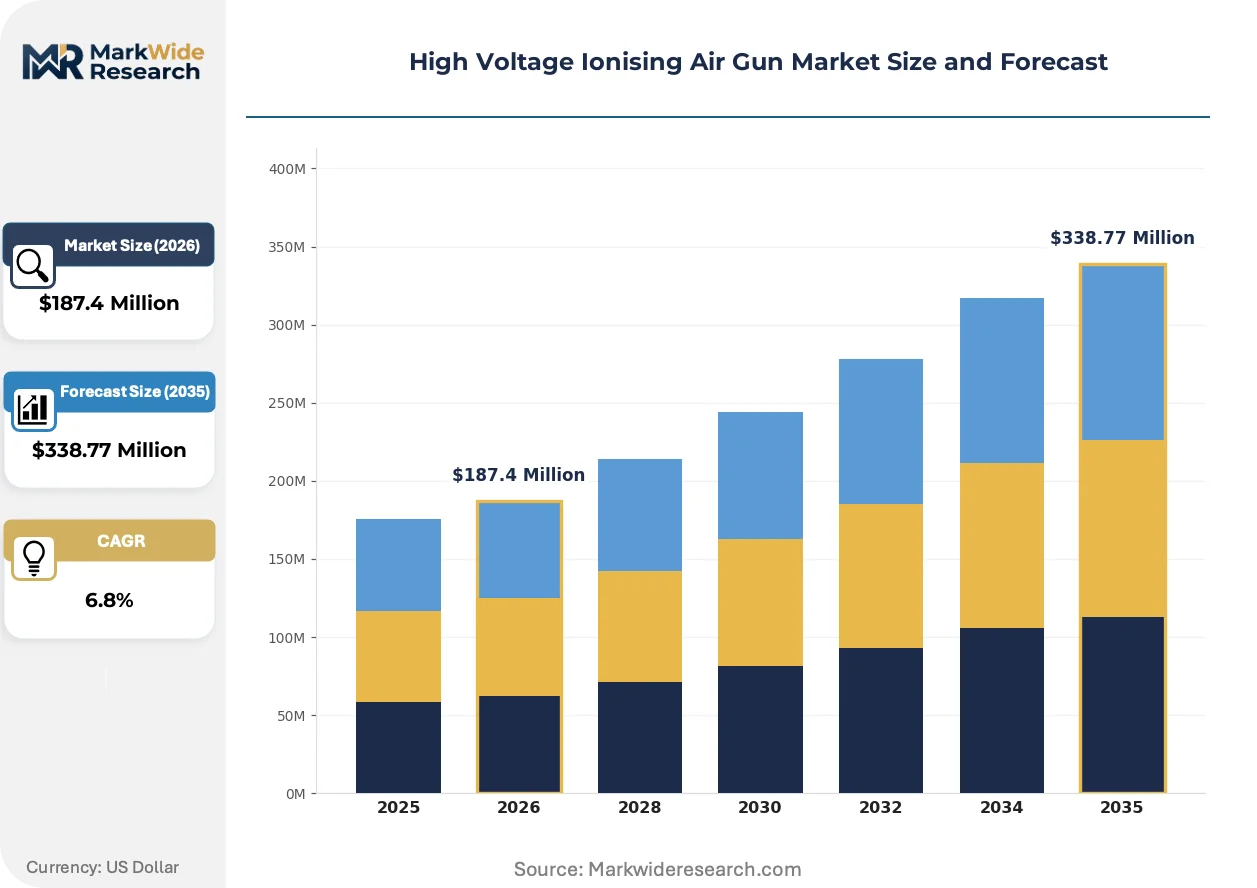
Market Dynamics
Sub-7nm semiconductor fabrication is compressing ionization equipment replacement cycles as fabs in Taiwan and South Korea chase yield targets that now exceed ISO Class 3 particle thresholds.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon-based cooling in cleanroom infrastructure redirects capital toward electrostatic discharge control systems, expanding procurement pools for ionizing equipment.
- China GB standards:Mandated ionizer deployment in Class 1000 and cleaner electronics manufacturing environments directly conditions equipment procurement volumes across East Asian supply chains.
- Plasma-based architectures:Next-generation nanofabrication facilities requiring sub-micron particle control are accelerating adoption of advanced ionization technologies beyond traditional corona discharge systems.
Market Restraints
- High-purity tungsten supply:Needle ionizer emitter tips depend on concentrated rare metal sourcing, exposing manufacturers to input cost volatility and geopolitical supply disruption.
- REACH plating restrictions:European chemical regulations limit certain surface treatment chemistries used in emitter assembly production, constraining local manufacturing flexibility.
- Pulsed DC technology:Lower-cost static control alternatives threaten to substitute premium high-voltage ionizing systems in mid-tier electronics assembly applications.
Strategic Opportunities
- India electronics manufacturing:The country's PLI scheme for semiconductor and component production creates underpenetrated demand for cleanroom ionization infrastructure as fabs establish greenfield operations.
- Multi-nozzle automation:Convergence of compressed-air systems with machine vision-guided placement robots opens white space in high-throughput electronics assembly lines.
- EPA effluent alignment:US industrial discharge guidelines favoring reduced chemical processing create regulatory tailwinds for dry ionization methods over wet cleaning alternatives.
Industry Challenges
- Ion balance calibration expertise:Shortage of technicians capable of maintaining ±5V offset tolerances in high-precision semiconductor environments extends equipment commissioning timelines.
- Cross-border qualification costs:Divergent certification requirements between EPA, REACH, and GB standards force manufacturers to maintain multiple product variants, fragmenting R&D resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Voltage Ionising Air Gun Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop, Handheld, Foot Pedal Operated, Multi-Nozzle, Lightweight Technology: Corona Discharge, Needle Ionizer, Bar Ionizer, Plasma, Electrostatic Application: Semiconductor, Electronics Assembly, Printing, Plastic Molding, Textile Processing End User: Manufacturing Plants, Cleanrooms, Quality Control Labs, Research Institutions |
| Companies Covered | Simco-Ion, EXAIR Corporation, Meech International, HAUG, Eltex, Keyence, Panasonic, SMC, Fraser Anti-Static Techniques, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Voltage Ionising Air Gun Market Trends and Innovations
Real-time polarity switching and compressed-air integration are redefining performance benchmarks, while regulatory chemistry restrictions and automation roadmaps reshape competitive priorities across equipment tiers.
Plasma-based ionization is overtaking corona discharge in next-generation nanofabrication facilities. These systems generate balanced ion streams without particulate emitter degradation. Leading memory and logic chip manufacturers in Taiwan and South Korea are adopting plasma architectures for sub-5nm production nodes. The technology is overtaking legacy needle ionizers in premium cleanroom segments by eliminating emitter tip replacement cycles and enabling continuous operation at ISO Class 2-equivalent environments.
REACH restrictions on hexavalent chromium and cadmium plating chemistries are forcing European manufacturers to reformulate emitter surface treatments. The regulation compresses acceptable material portfolios for needle ionizer production. Semiconductor equipment suppliers serving EU fabs are accelerating qualification of alternative coating processes to maintain supply continuity.
Equipment-as-a-service models are displacing capital purchase structures in mid-tier electronics assembly. Contract manufacturers in Vietnam and Mexico now favor operational expenditure arrangements bundling hardware, calibration, and consumables. This shift concentrates vendor selection power with regional system integrators rather than end-user engineering teams.
High Voltage Ionising Air Gun Market Segmentation
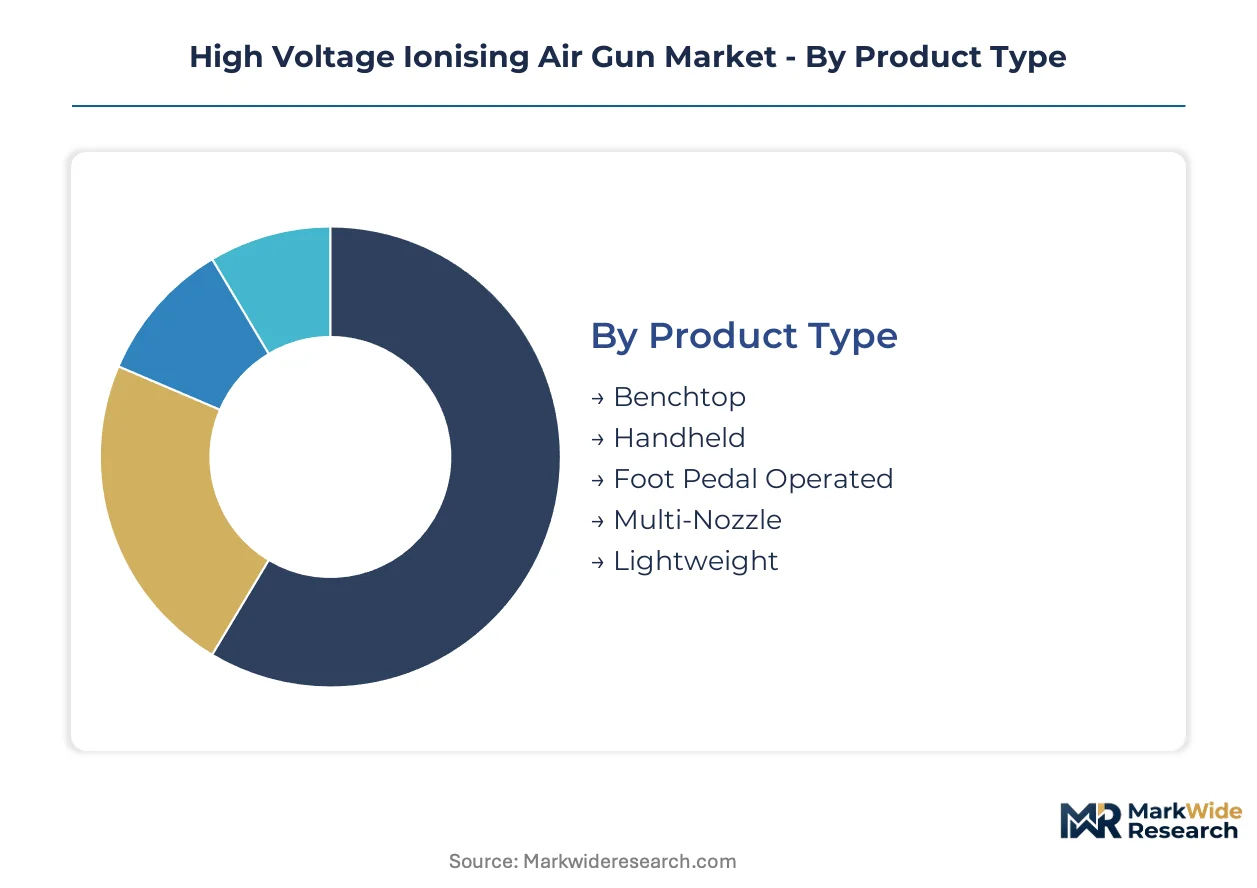
Equipment replacement cycles in semiconductor fabs and electronics assembly plants create distinct performance tiers across ionizing air gun configurations. Procurement decisions hinge on cleanroom classification requirements, automation integration depth, and operator mobility needs.
Product Type:
Upgrade timelines diverge sharply between manual operator tools and fixed automation arrays, with compressed-air integration requirements driving replacement decisions.
- Benchtop:Stationary units with integrated work surfaces serve quality control labs and small-batch electronics assembly. Taiwan and South Korea semiconductor fabs favor these for probe station applications where localized ionization protects wafer handling tools without cleanroom infrastructure modification.
- Handheld:Pistol-grip configurations with flexible air hoses dominate current manufacturing plant floors due to operator adaptability across mixed product lines. These units face compressed replacement cycles in Vietnam and Mexico contract manufacturing as GB standards tighten electrostatic protection mandates.
- Foot Pedal Operated:Hands-free activation suits precision assembly tasks requiring both hands for component placement.
- Multi-Nozzle:Fixed arrays with synchronized polarity switching capture expanding procurement pools in automated surface mount technology lines.
- Lightweight:Reduced-mass designs address operator fatigue in high-repetition textile and plastics processing environments.
Volume placements concentrate in Handheld configurations; the faster expansion belongs to Multi-Nozzle systems.
Technology:
Cost tier separation between mature corona systems and emerging plasma architectures is widening as sub-7nm fabrication requirements escalate.
- Corona Discharge:Needle-to-ground electrode arrays operating at 5-7 kV dominate unit economics for standard cleanroom protocols. South Korean memory manufacturers maintain substantial installed bases despite emitter tip degradation requiring quarterly replacement in high-duty cycles.
- Plasma:Radio-frequency excited ion generation eliminates particulate emitter degradation and enables continuous ISO Class 2-equivalent operation. Taiwan foundries at sub-5nm nodes are accelerating procurement as yield targets compress tolerance for contamination events.
- Needle Ionizer:Tungsten-tipped precision emitters serve mid-tier electronics assembly with balanced cost-performance positioning.
- Bar Ionizer:Linear emitter arrays integrate into conveyor systems for plastics extrusion and printing applications.
- Electrostatic:Capacitive coupling methods serve niche applications requiring minimal air turbulence.
Cost concentration remains with Corona Discharge; the steepest expansion trajectory belongs to Plasma systems.
Application:
Application-specific ionization requirements create margin differentiation between precision semiconductor handling and commodity manufacturing processes.
- Semiconductor:Wafer handling, photomask protection, and lithography tool maintenance demand ±5V ion balance precision. Taiwan and South Korea fabs account for dominant procurement volumes as sub-7nm production ramps drive equipment refresh cycles.
- Electronics Assembly:Surface mount technology lines and final inspection stations require rapid static neutralization without residue deposition. Vietnam and Mexico contract manufacturers are expanding multi-nozzle deployments under PLI-equivalent incentive structures.
- Printing:Sheet-fed and web offset presses use ionization to prevent ink misting and register drift.
- Plastic Molding:Injection and blow molding operations deploy bar ionizers to eliminate part ejection defects.
- Textile Processing:Fiber opening and winding operations rely on lightweight handheld units for operator mobility.
Procurement volume centers on Semiconductor applications; Electronics Assembly is climbing the fastest.
End User:
End-user facility classification determines certification requirements and service contract structures across the installed base.
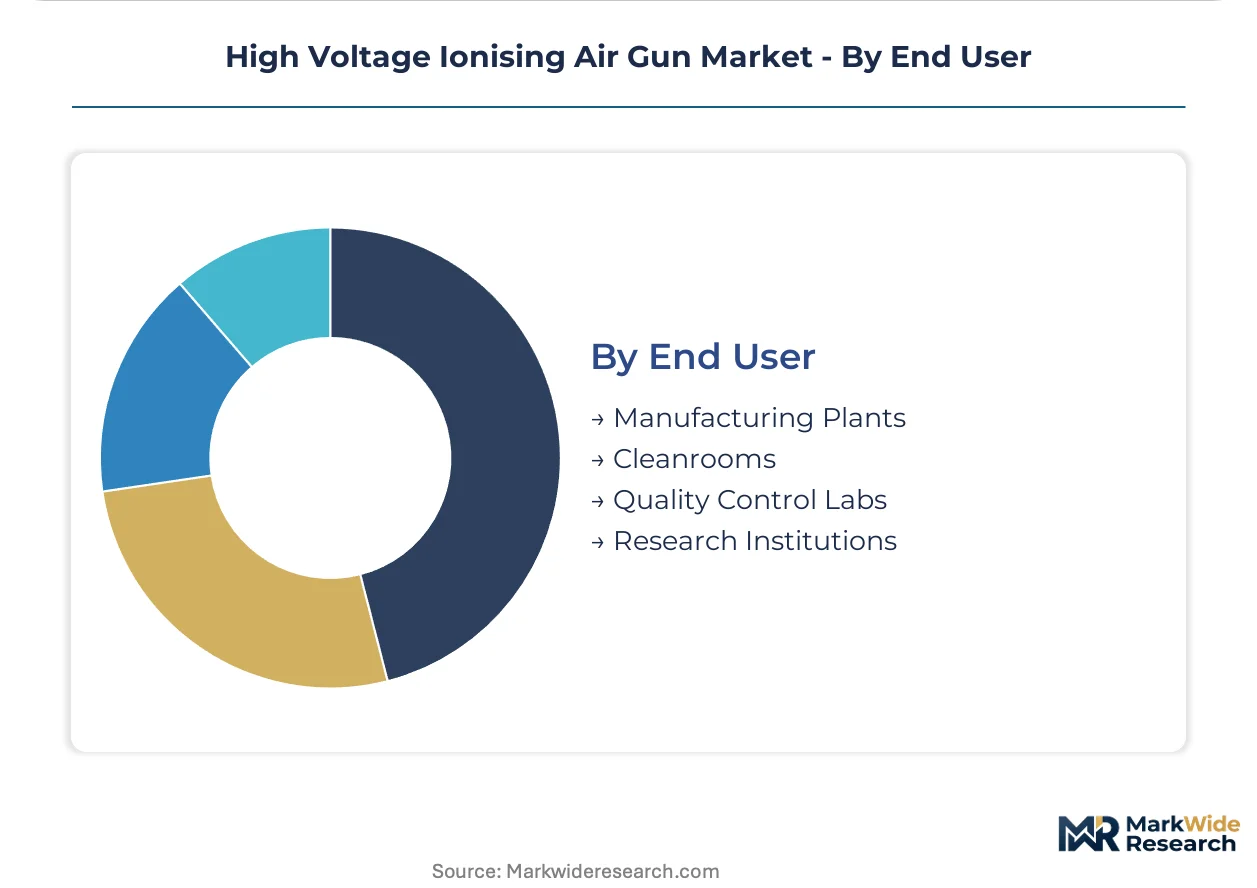
- Manufacturing Plants:General electronics and component production facilities represent the broadest addressable base. China's GB standards mandate ionizer deployment in Class 1000 and cleaner zones, directly conditioning procurement volumes across East Asian supply chains.
- Cleanrooms:ISO Class 3 and stricter environments command premium equipment specifications with continuous monitoring capabilities. Taiwan and South Korea semiconductor fabs drive replacement cycles as particle thresholds tighten.
- Quality Control Labs:Benchtop-focused procurement with emphasis on calibration traceability and audit documentation.
- Research Institutions:Specialized configurations for materials science and nanofabrication pilot lines.
Equipment placements concentrate in Manufacturing Plants; Cleanrooms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's Hsinchu Science Park anchors semiconductor ionization demand as sub-7nm fabs compress equipment replacement cycles. South Korea's Yongin cluster and China's Yangtze River Delta electronics corridors concentrate procurement volumes under tightening GB standards.
Taiwan
TSMC and UMC fabs in Hsinchu and Tainan drive ionizer procurement for sub-5nm wafer handling. The National Development Council's semiconductor advancement programs subsidize cleanroom infrastructure upgrades. Kaohsiung's emerging advanced packaging cluster is expanding ionization deployments for 3DIC production lines.
South Korea
Samsung and SK Hynix memory fabs in Yongin and Icheon mandate ISO Class 2-equivalent ionization for yield protection. METI-aligned industrial standards enforce electrostatic discharge protocols in electronics manufacturing. Busan's materials science research complex is piloting plasma-based systems for next-generation lithography tool maintenance.
China
GB standards mandate ionizer deployment in Class 1000 and cleaner electronics environments across Shenzhen and Suzhou manufacturing corridors. MIIT's industrial upgrading directives prioritize domestic electrostatic control equipment procurement. Chengdu's semiconductor fabrication zone is expanding ionization infrastructure under western development incentive structures.
United States
Intel and GlobalFoundries fabs in Arizona and New York drive cleanroom ionization demand for advanced logic production. EPA industrial effluent guidelines shape emitter material specifications in domestic manufacturing plants. Austin's emerging semiconductor cluster is attracting ionization equipment suppliers for greenfield fab construction.
Germany
Infineon and Bosch semiconductor operations in Dresden and Reutlingen anchor European ionization demand for automotive chip production. REACH restrictions on hexavalent chromium plating chemistries force emitter surface treatment reformulation. Bavaria's precision manufacturing corridor is qualifying alternative coating processes for needle ionizer supply continuity.
High Voltage Ionising Air Gun Market Competitive Landscape
East Asian producers anchor the technology-intensive tier; European specialists hold regulatory-compliant positioning in REACH jurisdictions. The market structures around three strategic archetypes: patent-anchored cleanroom equipment suppliers, compressed-air system integrators, and textile-focused niche specialists. Capacity expansion in Taiwan and South Korea dominates competitive moves, while strategic partnerships between ionizer manufacturers and semiconductor equipment distributors reshape channel access.
Within the cleanroom equipment tier, Simco-Ion and Keyence exemplify technology-anchored positioning through corona discharge patent portfolios. Panasonic occupies a position bridging industrial automation and precision electronics manufacturing. Among European specialists, HAUG and Eltex represent REACH-compliant fabrication capabilities serving regulated industrial environments.
| Leading Market Players |
|---|
| Simco-Ion |
| EXAIR Corporation |
| Meech International |
| HAUG |
| Eltex |
| Keyence |
| Panasonic |
| SMC |
| Fraser Anti-Static Techniques |
| Others |
Pricing and Supply Chain Analysis
The EU F-Gas Regulation's phasedown of hydrofluorocarbon-based cooling systems gates qualified supply for cleanroom-grade ionizing air guns, restricting premium-tier pricing access to manufacturers with REACH-compliant emitter surface treatments and certified compressed-air integration capabilities.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent procurement from scheduled replacement cycles, with Taiwan semiconductor fabs paying premiums for sub-30-day delivery of plasma-based systems while spot inventory of corona discharge units trades at discounts in Vietnam contract manufacturing. Three-tier pricing structure across premium, standard, and economy levels aligns with ISO Class certification tiers, where plasma architectures command top positioning and handheld needle ionizers face cost compression from pulsed DC alternatives. Contract manufacturers in Mexico exhibit highest price sensitivity due to PLI-equivalent incentive structures favoring operational expenditure models.
Supply Chain Analysis
China's GB standards and India's PLI scheme are reshaping sourcing patterns, compelling manufacturers to establish localized assembly for Class 1000 and cleaner environment certifications. High-purity tungsten for emitter tips concentrates in Chinese and Russian supply channels, while compressed-air system components anchor in German and Japanese industrial clusters. Single-source vulnerability in rare metal feedstock exposes producers to geopolitical disruption. Distribution runs through semiconductor equipment distributors and regional system integrators serving fab construction projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase as plasma-based ionization displaces corona discharge architectures in sub-5nm semiconductor fabrication.
For Market Incumbents: To counter plasma system commoditization from emerging Korean and Chinese suppliers, Simco-Ion and Keyence should deepen patent enforcement in corona discharge portfolios while accelerating backward integration into tungsten emitter tip supply. Capacity addition in Taiwan's Hsinchu corridor preserves proximity to TSMC and UMC procurement centers. For New Entrants and Emerging Players: Launch via equipment-as-a-service distribution models targeting Vietnam and Mexico contract manufacturers seeking operational expenditure structures. India's PLI-driven semiconductor greenfield expansions represent the most penetrable geography, with white space in multi-nozzle automation arrays for surface mount technology lines and textile anti-static applications underserved by generalized competitors. For Investors and Strategic Acquirers: Taiwan foundries' accelerated plasma procurement for sub-5nm nodes is the leading indicator that premium cleanroom ionization will sustain technology-intensive margins over the mid-term horizon. Acquisition targets should profile REACH-compliant European specialists with alternative coating process qualifications, monitoring EPA industrial effluent guideline revisions as inflection signals for US manufacturing demand.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Technology Licensing | Taiwan foundries license sub-micron particle control systems from Korean memory manufacturers. |
| Backward Integration into Tungsten Supply | Emitter tip sourcing control reduces exposure to Chinese and Russian rare metal volatility. |
| REACH-Compliant Coating Qualification | European fabs require alternative surface treatments as hexavalent chromium plating faces restriction. |
| Multi-Nozzle Automation Partnership | Machine vision integrators bundle ionization arrays for high-throughput electronics assembly lines. |
| Equipment-as-a-Service Launch | Vietnam contract manufacturers shift capital expenditure to operational models bundling calibration. |
Research Methodology
Multi-period observation of fab equipment procurement cycles, cleanroom classification upgrades, and ion balance calibration service contracts anchored the trend analysis, supplemented by interviews with cleanroom engineering directors, semiconductor equipment procurement managers, ionization system calibration technicians, and compressed-air system integrators. Secondary validation drew from EPA industrial effluent guidelines, ECHA REACH restriction updates, Chinese GB standard revisions, SEC filings of semiconductor capital equipment suppliers, and customs data for high-purity tungsten trade flows. Bottom-up equipment unit tracking across Taiwan, South Korea, and China manufacturing corridors triangulated against top-down fab capital expenditure disclosures.
Input-output matrices modeled corona discharge and plasma system deployment across product type, technology architecture, application severity, and end-user facility classification segments. CAGRs derived from equipment replacement cycle compression rates in sub-7nm fabrication and automation penetration curves in electronics assembly. Forecast inputs included Taiwan foundry yield target trajectories, F-Gas Regulation capital redirection timelines, and India PLI scheme fab construction schedules.
Geopolitical supply disruption in rare metal sourcing, divergence between EPA, REACH, and GB certification requirements, and pulsed DC substitution rates in mid-tier electronics assembly are the dominant revision risks that could alter trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Transformer Oil Testers Market
Electrical Power Equipment
Busbar Protection Market
Electrical Power Equipment
High Voltage Oil Insulated Switchgear Market
Electrical Power Equipment
Hollow Core Insulator Market
Electrical Power Equipment
North America Power Inverter Market
Electrical Power Equipment
Gas Insulated Switchgears (GIS) Market
Electrical Power Equipment
Magnetic Ballast Market
Electrical Power Equipment
Portable Space Heater Market
Electrical Power Equipment
Power Strip Market
Electrical Power Equipment
Nuclear Cables Sales Market
Electrical Power Equipment
Protective Relay Market
Electrical Power Equipment
Global Duct Heaters Market
Electrical Power Equipment
Middle East and Africa High Voltage Switchgear Market
Electrical Power Equipment
Substation Testing Equipment Market
Electrical Power Equipment
High Voltage Direct Current (HVDC) Cables Market
Electrical Power Equipment
North America Oil Filled Electric Heaters Market