
 Renewable Energy Transformer Market | 2026-2036
Renewable Energy Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Renewable Energy Transformer Market Insights
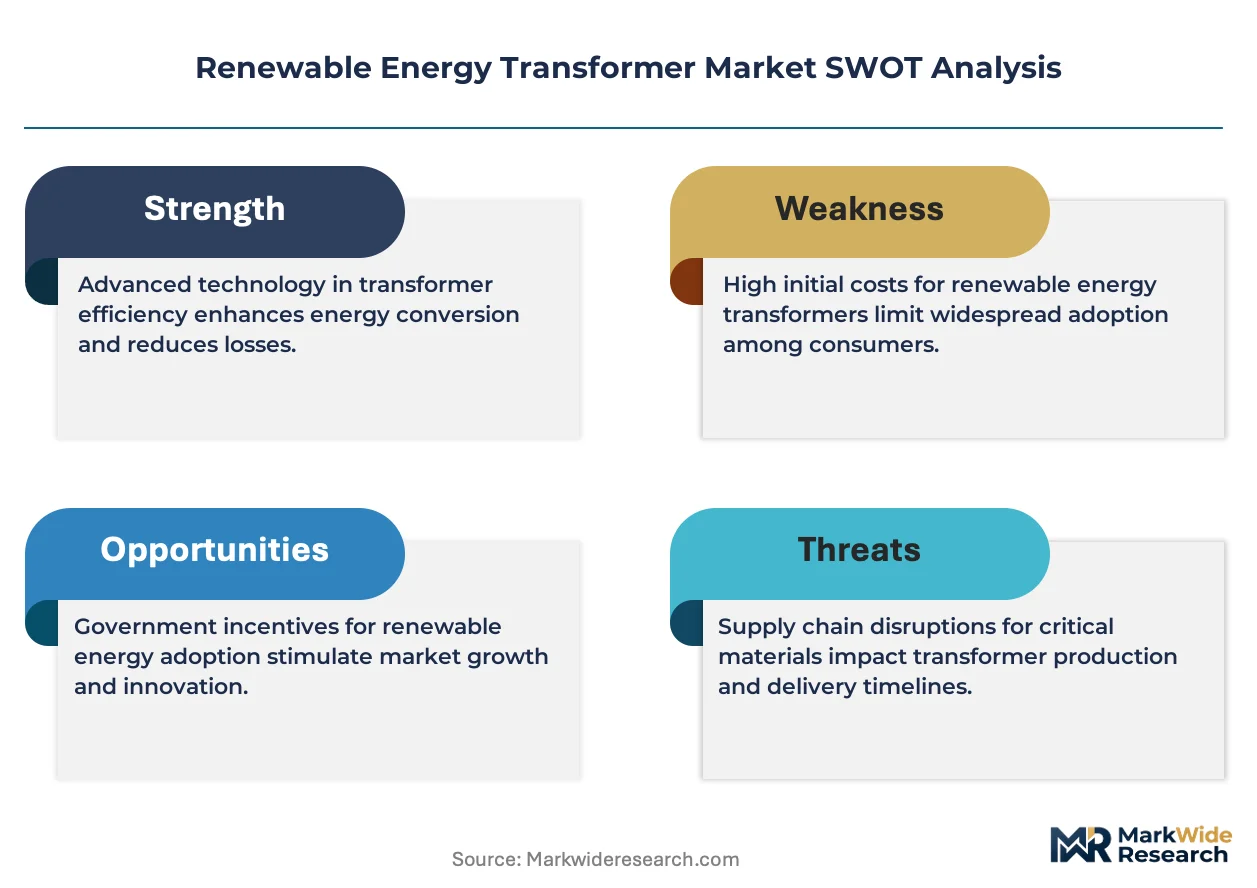
The EU Green Deal is rebalancing the cost-of-entry calculus for transformer manufacturers serving European renewable projects. Siemens Energy leverages its vertical integration into power electronics to sustain margin capture across offshore wind collector platforms. Hitachi Energy anchors its position through R&D intensity in eco-efficient switchgear alternatives to SF6 insulation. GE Vernova competes by dominating the North American utility-scale solar step-up segment with modular transformer designs.
Renewable energy transformers are electromagnetic devices engineered to transfer electrical power between circuits through magnetic induction, typically operating at voltage classes from 34.5 kV to 765 kV with liquid-immersed or dry-type insulation systems designed for variable renewable output profiles. Their primary purpose is to step up generator-level voltage for efficient long-distance transmission from wind and solar farms to grid interconnection points. Step-up transformers lead installed capacity across utility-scale solar and onshore wind projects where generator voltages must escalate to transmission levels. Smart transformers represent the fastest-expanding technology segment as grid operators demand real-time load balancing and predictive maintenance capabilities for distributed renewable assets. Oil-immersed designs still occupy the largest margin pool in offshore applications due to superior thermal performance in subsea and coastal environments.
The EPA enforces efficiency standards under its transformer loss regulations while the EU F-Gas Regulation mandates phased reduction of sulfur hexafluoride used in switchgear integrated with transformer substations. China's MEE enforces GB standards on no-load and load losses for grid-connected equipment, shaping procurement criteria for domestic wind and solar developers. Stakeholders must monitor how evolving grid codes across multiple jurisdictions redefine transformer efficiency tiers and insulation material specifications before committing to platform designs.
Market Dynamics
The EU F-Gas Regulation and parallel EPA efficiency mandates are forcing transformer manufacturers to abandon sulfur hexafluoride insulation and redesign thermal management systems for offshore wind collector platforms. This regulatory compression is accelerating R&D spend on eco-efficient switchgear alternatives while raising the technical barrier to entry for new suppliers.
Growth Catalysts
- Offshore wind deployment:North Sea lease rounds in Germany, Denmark, and the Netherlands are requiring high-voltage DC collection systems that demand specialized step-up transformers rated for subsea environments.
- EU Green Deal grid codes:Efficiency tier upgrades under the EU Green Deal are mandating lower no-load and load losses for interconnection assets, compelling asset owners to replace aging transformer fleets.
- Interconnection expansion:China's State Grid and Southern Power Grid are adding ultra-high-voltage transmission corridors to absorb utility-scale solar from western provinces, creating pull-through demand for 765 kV class transformers.
Market Restraints
- Grain-oriented electrical steel concentration:Supply of high-permeability core steel concentrates among Japanese and South Korean mills, exposing transformer manufacturers to price volatility and allocation risk during demand surges.
- Copper winding cost exposure:Copper constitutes 25-30% of transformer material cost, and London Metal Exchange price swings directly compress OEM margins on fixed-price utility contracts.
- Solid-state transformer substitution:Silicon carbide power electronics are emerging as direct substitutes for conventional step-up transformers in distributed solar applications below 10 MVA.
Strategic Opportunities
- India renewable integration:India's Central Electricity Authority mandates 500 GW non-fossil capacity by 2030, creating demand for 765 kV and 400 kV transformers to connect Rajasthan solar parks and Gujarat wind zones to the national grid.
- Digital twin convergence:Integration of transformer monitoring sensors with cloud-based predictive analytics platforms enables asset owners to shift from time-based to condition-based maintenance, opening recurring revenue streams for OEMs.
- SF6-free switchgear tailwind:The EU F-Gas Regulation's phase-down schedule creates first-mover advantage for manufacturers with validated dry-air or vacuum insulation designs for 145 kV and above.
Industry Challenges
- High-voltage testing capacity scarcity:Few laboratories worldwide can perform impulse and partial discharge testing on 765 kV transformers, creating bottlenecks for new product qualification and extending time-to-revenue.
- Legacy asset interoperability:Smart transformers with IEC 61850 communication protocols must interface with decades-old substation automation systems lacking digital interfaces, requiring costly protocol gateways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renewable Energy Transformer Market |
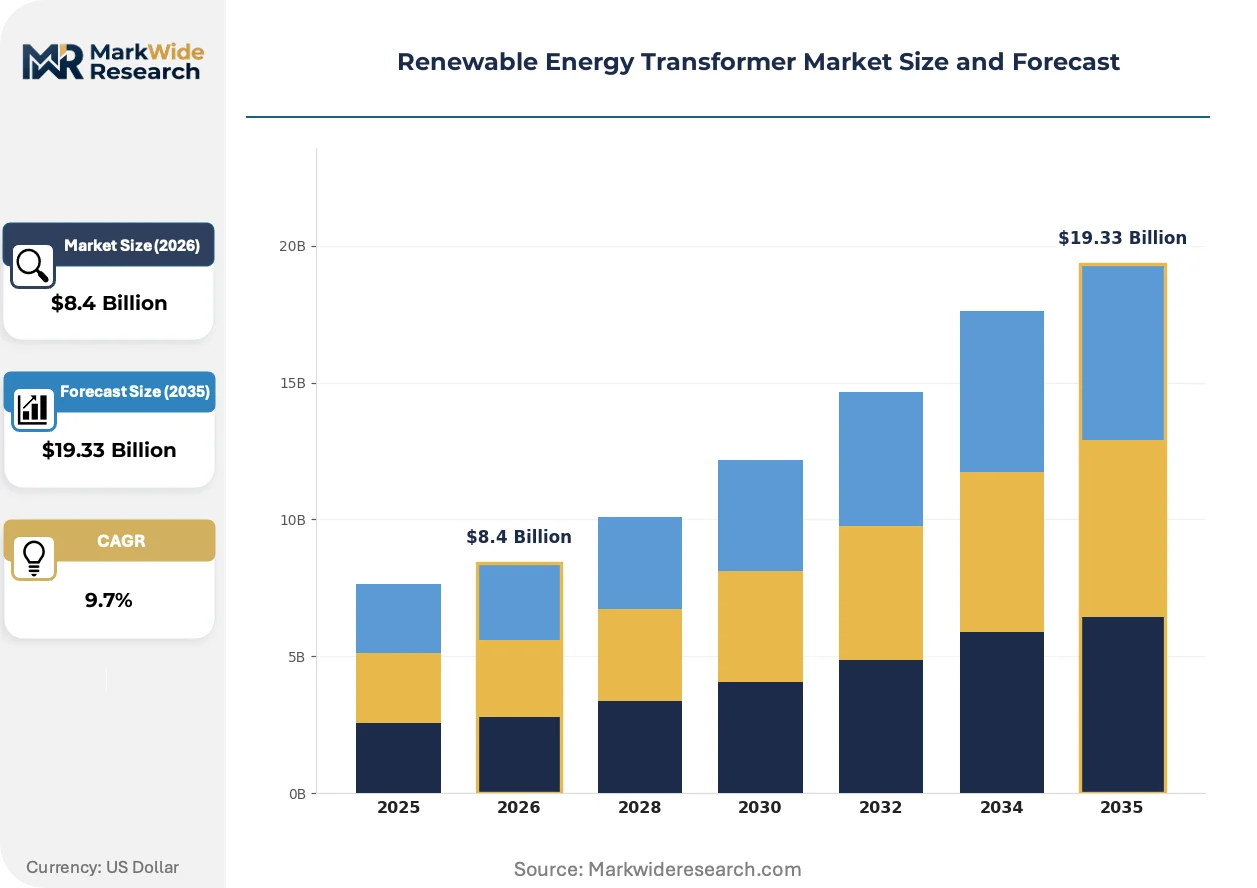
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Step-up Transformers, Step-down Transformers, Isolated Transformers, Autotransformers Technology: Conventional Transformers, Smart Transformers, Power Electronic Transformers, Oil-immersed Transformers End User: Power Generation, Utilities, Industrial, Commercial Installation: Onshore, Offshore, Indoor, Outdoor |
| Companies Covered | Siemens Energy, Hitachi Energy, GE Vernova, Mitsubishi Electric, Eaton, Hyosung Heavy Industries, HD Hyundai Electric, Hammond Power Solutions, MGM Transformer Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renewable Energy Transformer Market Trends and Innovations
Transformer technology is bifurcating between massive, liquid-immersed units for offshore wind collector platforms and intelligent, digitally enabled designs for distributed solar and storage integration. This divergence is reshaping R&D allocation and manufacturing footprints across the supplier base.
Natural ester insulating fluids are integrating into offshore transformer designs as direct replacements for mineral oil. Siemens Energy and Hitachi Energy have qualified synthetic and natural ester formulations for 66 kV and 132 kV collector platforms. The technology is integrating fire-safety and biodegradability credentials that satisfy insurer requirements for unmanned offshore substations while maintaining thermal performance in North Sea ambient conditions.
The EPA's transformer loss regulations and the EU F-Gas Regulation are tightening in parallel, creating a dual-compliance burden for manufacturers serving both markets. The EPA mandates maximum no-load and load losses by kVA rating under 10 CFR 431. The EU F-Gas Regulation mandates 80% SF6 phase-down by 2030 and bans the gas in new switchgear from 2032. Offshore wind projects in German and Danish waters are most affected, with developers now specifying SF6-free GIS integrated with transformer substations.
Utility procurement departments are consolidating transformer purchasing through framework agreements with integrated OEM-service providers. European TSOs including TenneT and 50Hertz are moving from transactional spot purchasing to 10-year service-inclusive contracts covering installation, monitoring, and end-of-life replacement. This shift concentrates volume with vertically integrated suppliers capable of delivering lifecycle solutions across German and Dutch offshore zones.
Renewable Energy Transformer Market Segmentation
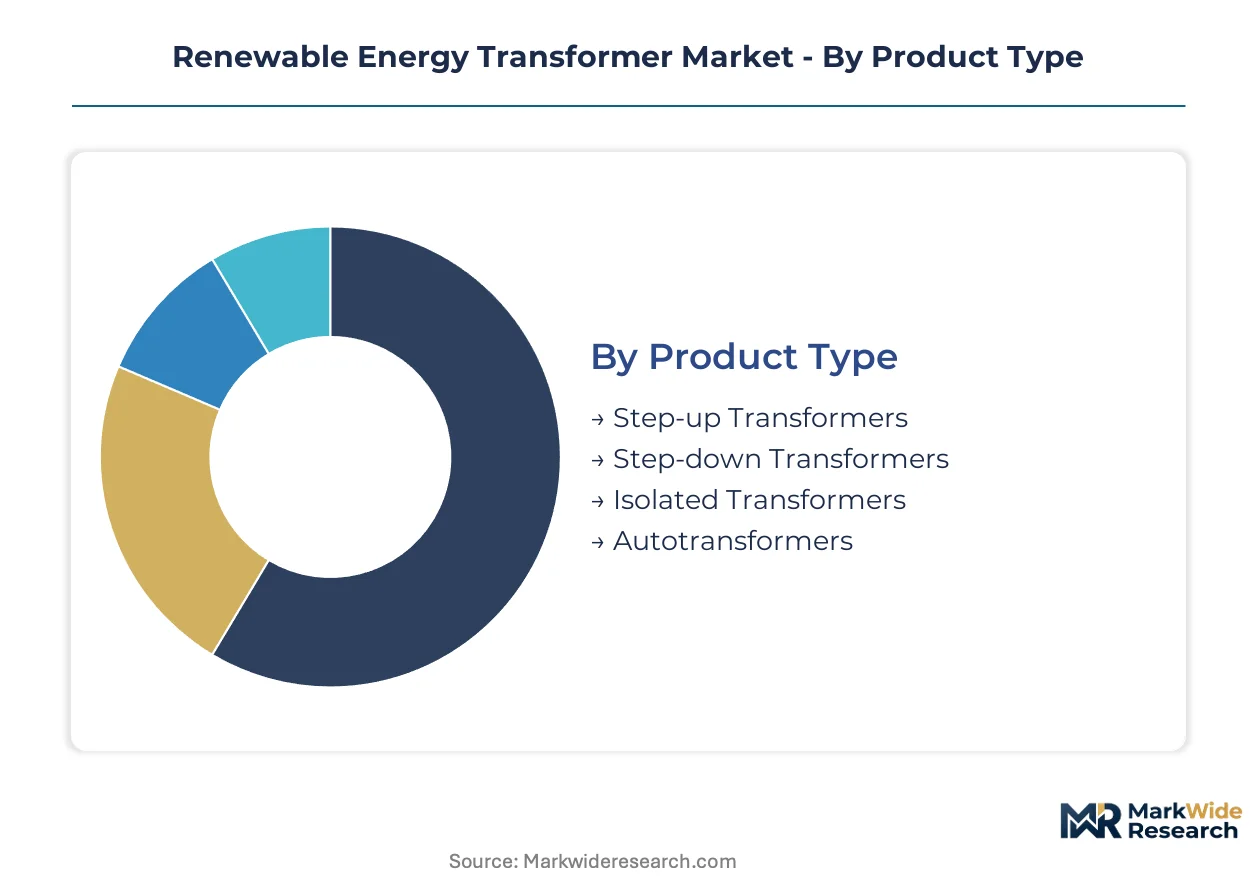
Transformer specification tiers align with voltage class, thermal management requirements, and grid integration complexity across renewable asset classes. Segmentation reveals how offshore wind, utility-scale solar, and distributed generation each impose distinct technical demands on electromagnetic design and insulation systems.
Product Type:
Voltage transformation directionality defines core electromagnetic architecture and winding configurations for renewable interconnection.
- Step-up Transformers:These units escalate generator-level voltage from 34.5 kV to transmission tiers between 138 kV and 765 kV. Offshore wind farms in the North Sea and utility-scale solar parks in China's western provinces drive procurement of liquid-immersed designs rated for high-voltage DC collection.
- Step-down Transformers:Distribution substations employ these to reduce transmission voltage to medium-voltage levels for local grid injection. Industrial microgrids with captive renewable generation in Germany specify compact step-down units for direct facility integration.
- Isolated Transformers:Galvanic separation protects sensitive power electronics from grid transients. Solar inverter manufacturers in the United States integrate these into string inverter architectures for commercial rooftop systems.
- Autotransformers:Single-winding designs reduce material intensity for voltage ratios below 3:1. Transmission operators in India deploy these for voltage matching within ultra-high-voltage corridors connecting Rajasthan solar zones.
Mature deployment sits with step-up configurations. Newer deployment is concentrated in autotransformer variants for inter-regional voltage matching.
Technology:
Control intelligence and thermal management chemistry differentiate cost tiers and operational capability across renewable applications.
- Conventional Transformers:Established electromagnetic designs with passive cooling and electromechanical protection. These dominate existing fleet replacement cycles in the United States where EPA efficiency mandates drive upgrades of aging mineral-oil units.
- Smart Transformers:Integrated sensors and IEC 61850 communication enable real-time load balancing and predictive maintenance. Grid operators in Germany and Denmark specify these for offshore collector platforms requiring remote monitoring of unmanned substations.
- Power Electronic Transformers:Silicon carbide-based solid-state designs eliminate magnetic cores for applications below 10 MVA. Distributed solar and storage hybrids in California pilot these for DC-coupled architectures with bidirectional power flow.
- Oil-immersed Transformers:Mineral oil or natural ester fluid provides superior thermal conductivity for high-power density. Subsea installations in the North Sea mandate these for 66 kV and 132 kV collector systems exposed to saline ambient conditions.
Volume concentration favors conventional designs. Steepest expansion trajectory belongs to smart transformer platforms with embedded digital monitoring.
End User:
Asset ownership structure determines procurement scale, service contract duration, and technical specification authority.
- Power Generation:Wind and solar developers specify transformers during project origination. Independent power producers in India negotiate 10-year service-inclusive contracts covering installation through end-of-life replacement.
- Utilities:Transmission system operators standardize designs across renewable interconnection portfolios. TenneT and 50Hertz in Germany consolidate purchasing through framework agreements with integrated OEM-service providers.
- Industrial:Captive renewable installations supply manufacturing facilities with direct power purchase agreements. Chemical and data center operators in the Netherlands specify on-site step-up units for corporate renewable energy targets.
- Commercial:Distributed solar hosts procure compact dry-type units for rooftop and carport installations. Property developers in the United States select modular designs permitting phased capacity expansion.
Procurement scale peaks with utility transmission operators. Fastest-growing demand originates from industrial captive generation seeking price hedging through direct renewable supply.
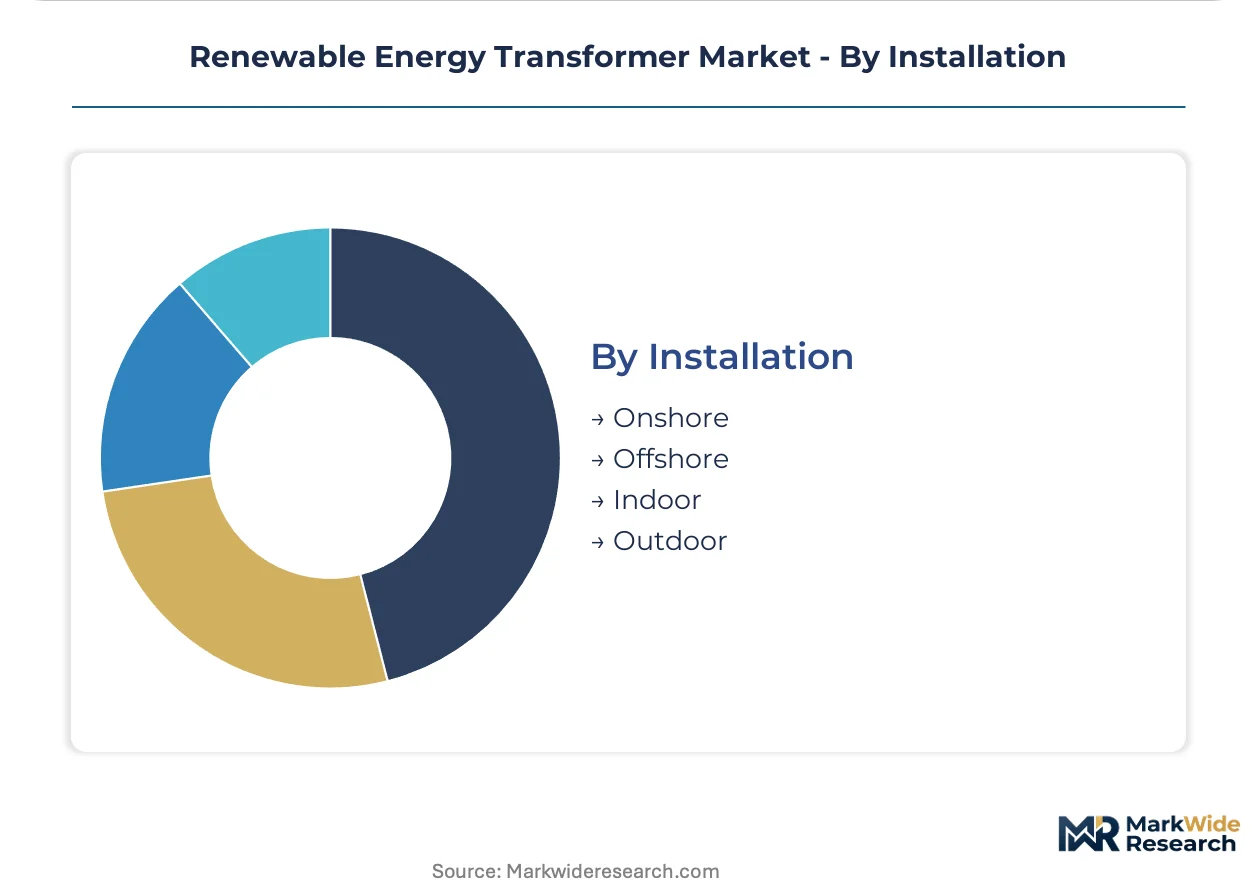
Installation:
Environmental exposure and accessibility constraints dictate enclosure ratings, cooling architecture, and maintenance protocol design.
- Onshore:Ground-mounted installations at wind farms and solar parks permit standard weatherproofing. China's State Grid deploys these across ultra-high-voltage transmission corridors absorbing utility-scale solar from western provinces.
- Offshore:Subsea and platform-mounted units require marine-grade sealing and corrosion protection. German and Danish North Sea lease rounds specify SF6-free switchgear integrated with transformer substations for unmanned collector platforms.
- Indoor:Controlled environments in urban substations permit reduced enclosure ratings. Fire-safety codes in commercial buildings in Japan mandate dry-type or natural ester designs for basement transformer rooms.
- Outdoor:Pole-mounted and pad-mounted units serve rural distribution networks. Utility-scale solar developers in the United States favor these for rapid deployment without permanent building infrastructure.
Standard deployment concentrates in outdoor onshore configurations. Technical complexity and margin premium cluster in offshore platform installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for renewable energy manufacturing in China, India, and Germany concentrate transformer demand. Tax incentives in these zones attract OEMs to co-locate with wind turbine and solar panel producers. Grid interconnection mandates in each zone accelerate procurement of high-voltage step-up units.
China
State Grid Corporation builds ultra-high-voltage corridors from western solar provinces to coastal load centers. MEE enforces GB standards on transformer losses for all grid-connected equipment. The Yangtze River Delta hosts manufacturing clusters where domestic OEMs supply 765 kV class units for inter-regional transmission.
Germany
North Sea offshore lease rounds require SF6-free switchgear integrated with collector platform transformers. EU F-Gas Regulation mandates 80% phase-down of sulfur hexafluoride by 2030. TenneT and 50Hertz in Hamburg and Berlin consolidate procurement through decade-long service-inclusive framework agreements.
United States
Utility-scale solar deployment in Texas and California drives demand for modular step-up transformers. EPA enforces efficiency standards under 10 CFR 431 for no-load and load losses. The Southwest Power Pool and CAISO interconnection queues concentrate procurement authority with independent power producers.
India
Central Electricity Authority targets 500 GW non-fossil capacity by 2030, requiring 765 kV and 400 kV transformers. CEA technical standards govern insulation coordination and short-circuit withstand for renewable interconnection. Rajasthan solar parks and Gujarat wind zones anchor demand in western states.
Denmark
Energy Island projects in the North Sea mandate high-voltage DC collection systems with subsea-rated transformers. National grid codes align with EU Green Deal efficiency tiers for interconnection assets. Copenhagen and Esbjerg harbor zones concentrate offshore substation fabrication and marine logistics.
Renewable Energy Transformer Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across voltage classes and application segments. Market structure tilts toward consolidation at the high-voltage offshore tier while fragmenting across dry-type and distribution-class units. Three archetypes dominate: vertically integrated energy majors with power electronics capabilities, regional electrical equipment specialists with transformer-only portfolios, and industrial conglomerates with broad infrastructure exposure. Competitive moves center on backward integration into core steel and copper supply, plus long-term service contract capture.
Among the integrated energy majors, Siemens Energy, Hitachi Energy, and GE Vernova occupy positions defined by geographic footprint and technology breadth. Siemens Energy exemplifies the vertically integrated archetype with captive power electronics manufacturing. Hitachi Energy represents R&D-intensive specialization in eco-efficient switchgear alternatives. GE Vernova anchors the North American utility-scale solar segment with modular platform designs. These three entities structure competitive dynamics through framework agreements, lifecycle service bundling, and offshore project consortium participation.
| Leading Market Players |
|---|
| Siemens Energy |
| Hitachi Energy |
| GE Vernova |
| Mitsubishi Electric |
| Eaton |
| Hyosung Heavy Industries |
| HD Hyundai Electric |
| Hammond Power Solutions |
| MGM Transformer Company |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed producers in China's State Grid supply chain anchor pricing discipline through captive allocation of grain-oriented electrical steel, while private-equity-rolled-up specialists in North America compete on service bundling rather than unit economics. This ownership bifurcation concentrates upstream pricing power with East Asian mills while fragmenting downstream negotiation leverage among project developers.
Pricing Analysis
Lead-time-driven pricing creates 15-20% premiums for transformers deliverable under 12 months versus standard 18-month cycles, reflecting high-voltage testing capacity scarcity at 765 kV qualification laboratories. Project-based contract structures dominate, with price differentiation resting on IEC 61850 smart monitoring integration and natural ester fluid certification tiers. Cost compression in standard step-up units is intensifying because Chinese OEMs are absorbing copper volatility through state-backed raw material reserves. Independent power producers in India exhibit highest price sensitivity due to tariff-competitive auction structures, while German offshore wind consortia prioritize SF6-free switchgear compliance over unit cost.
Supply Chain Analysis
Direct-to-utility framework agreements handle hyperscale demand from TenneT and 50Hertz, bypassing distributor markups for offshore collector platform procurement. Geographic supply concentration centers on Japan and South Korea for grain-oriented electrical steel, China for copper winding production, and Germany for 765 kV insulation system assembly. Raw material dependencies rest on high-permeability core steel, LME-grade copper, and natural ester insulating fluids derived from soybean and rapeseed feedstocks. Single-source vulnerability in 765 kV impulse testing laboratories creates qualification bottlenecks extending time-to-revenue for new product introductions. Distribution runs through integrated OEM-service providers capturing lifecycle value across installation, monitoring, and end-of-life replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-voltage testing capacity scarcity at 765 kV qualification laboratories props pricing premiums for certified suppliers, creating a supply-constrained market structure favoring incumbents with captive laboratory access or decade-long framework agreements.
For Market Incumbents: Anticipate silicon carbide power electronics substitution below 10 MVA by accelerating solid-state transformer R&D partnerships with California distributed solar developers. Defensive consolidation through backward integration into grain-oriented electrical steel supply from Japanese and South Korean mills secures core material allocation during demand surges. Prioritize SF6-free switchgear certification investment to capture EU F-Gas Regulation compliance premiums in German and Danish North Sea lease rounds. For New Entrants and Emerging Players: The price-point gap between premium smart transformers with IEC 61850 integration and economy conventional units creates white-space opportunity for mid-tier digital retrofit solutions. Target India's 500 GW renewable integration mandate through 765 kV and 400 kV transformer supply to Rajasthan solar parks, where CEA technical standards favor new entrants with rapid qualification timelines. Pursue joint venture structures with established EPC contractors to bypass framework agreement barriers at European TSOs. For Investors and Strategic Acquirers: First-mover SF6-free switchgear validation at 145 kV and above is the leading indicator that eco-efficient insulation technology will consolidate market share ahead of the 2032 EU ban deadline. Long-term viability over the next decade rests on service contract recurring revenue streams rather than equipment margins alone. Acquisition target archetypes include regional specialists with captive high-voltage testing relationships or natural ester fluid formulation IP. Monitor German offshore lease round award announcements as inflection signals for platform transformer demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| SF6-Free Switchgear Certification | EU F-Gas Regulation compliance secures first-mover advantage in German offshore wind procurement. |
| Natural Ester Fluid Qualification | Synthetic and natural ester formulations satisfy insurer requirements for unmanned North Sea platforms. |
| Digital Twin Platform Integration | Cloud-based predictive analytics enable OEMs to capture condition-based maintenance recurring revenue. |
| Backward Integration into Core Steel | Captive supply from Japanese and South Korean mills hedges price volatility and allocation risk. |
| 765 kV Testing Capacity Expansion | Laboratory scarcity creates bottlenecks; qualification access accelerates time-to-revenue for ultra-high-voltage units. |
Research Methodology
Multi-period observation of transformer loss regulations, offshore wind lease awards, and ultra-high-voltage corridor commissioning anchored the trend analysis, supplemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Primary fieldwork combined with secondary validation from EIA data, IEA reports, FERC filings, and project development databases. Bottom-up unit economics triangulated against top-down transmission investment forecasts to reconcile segment-level demand with macro infrastructure deployment.
Segment-weighting across voltage class, installation environment, and end-user ownership structure informed the analytical framework over the projection horizon. Modeled dimensions included step-up versus step-down transformation directionality, onshore versus offshore platform mounting, and utility versus independent power producer procurement authority. CAGRs derived from infrastructure investment trajectories and regulatory compliance timelines. Forecast inputs incorporated GB standards enforcement by China's MEE and EPA efficiency mandates under 10 CFR 431.
Inputs from FERC interconnection queues, EU Green Deal grid code amendments, and CEA technical standards were available through the study window; gaps in real-time commodity pricing for grain-oriented electrical steel introduce uncertainty bands around margin projections. Forecasts reflect assumptions on copper price stability and laboratory qualification capacity expansion. Periodic stress-testing of base assumptions against regulatory acceleration or supply chain disruption scenarios is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Distribution Transformer Market
Transformers
Green Power Transformers Market
Transformers
Traction Transformer Market
Transformers
Saudi Arabia Transformer Market
Transformers
Global Transformer Market
Transformers
Transformer Steel Market
Transformers
Industrial Control Transformers Market
Transformers
Rail Traction Transformers Market
Transformers
United States Large Power Transformer Market
Transformers
Green Transformer Market
Transformers
Transformer Bobbin Market
Transformers
India Power Transformer Market
Transformers
Asia-Pacific Power Transformer (Below 100 MVA) Market
Transformers
Europe Transformer Market
Transformers
US Oil Filled Distribution Transformer Market
Transformers
Oil Immersed Transformer and Dry Type Transformer Market