
 Mexico Renewable Energy Market | 2026-2036
Mexico Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Renewable Energy Market Outlook
Market Context with Strategic Players
Mexican solar and wind project pipelines is broadening as independent power producers and state-linked entities race to capture resource-rich zones. Enel Green Power leverages its operational scale across multiple states to sustain development velocity in utility-scale solar parks. Iberdrola SA anchors its position through long-term power purchase agreements with industrial offtakers in Monterrey and Guadalajara. Siemens Gamesa Renewable Energy SA competes aggressively in the wind turbine supply segment, controlling nacelle and blade logistics for projects across the Isthmus of Tehuantepec.
Technical Definition and Structural Segments
Mexico renewable energy encompasses electricity generation from solar photovoltaic arrays, onshore wind turbines, biomass combustion systems, and small-to-large hydroelectric facilities, typically operating at voltage levels from low-tension residential connections to high-voltage transmission interties at 400 kV. These technologies displace fossil fuel baseload, reduce grid carbon intensity, and supply power to residential, commercial, industrial, and utility-scale buyers under regulated and deregulated frameworks. Solar photovoltaic dominates capacity additions due to plunging module costs and high irradiance in northern Mexico, while wind concentrates in Oaxaca and Tamaulipas where corridor geography sustains capacity factors above thirty-five percent. Utility-scale application captures the deepest margin pools through economies in land acquisition and grid interconnection, though commercial and industrial behind-the-meter installations accelerate fastest as corporations pursue renewable power purchase agreements.
Regulatory Framework and Forward Outlook
CRE, the national energy regulator, oversees power market rules and interconnection permits, while SEMARNAT evaluates environmental impact statements for renewable projects exceeding fifty megawatts. Mexico's Energy Transition Law and associated clean energy certificates create compliance obligations that shape offtaker procurement strategies and project finance structures. SENER's long-term planning documents signal transmission expansion priorities that will determine which resource zones achieve grid access. Stakeholders must monitor permit approval timelines and certificate market liquidity as decisive variables for capital allocation.
Market Dynamics
Utility-scale procurement mandates from Mexico's Federal Electricity Commission (CFE) and accelerating corporate power purchase agreements are compressing project development timelines and reshaping capital allocation across the northern solar belt and Isthmus wind corridors.
Growth Catalysts
- Clean Energy Certificates (CELs):Mexico's Energy Transition Law obligates load-serving entities to acquire CELs, creating guaranteed offtake demand that de-risks project finance for developers in Sonora and Baja California.
- Industrial load growth:Nearshoring manufacturing expansion across Nuevo León and Querétaro is driving direct renewable procurement from automotive and electronics assemblers seeking price stability.
- High irradiance resource concentration:Solar parks in the Sonoran Desert achieve capacity factors exceeding twenty-eight percent, lowering levelized cost thresholds against combined-cycle gas generation.
Market Restraints
- Transmission congestion:SENER's grid expansion lags behind generation additions in Oaxaca's Isthmus region, forcing curtailment on wind farms awaiting 400 kV intertie completion.
- Policy uncertainty:Constitutional reforms favoring state-owned generation have chilled private equity flows into merchant renewable projects since 2021.
- Equipment import dependency:Photovoltaic module supply concentrates on Southeast Asian and Chinese manufacturers, exposing developers to tariff volatility and shipping bottlenecks at Lázaro Cárdenas.
Strategic Opportunities
- Behind-the-meter commercial solar:Unpenetrated mid-size manufacturing facilities in Guanajuato and Jalisco represent distributed generation growth vectors bypassing transmission queue delays.
- Green hydrogen pilot zones:SENER's proposed regulatory framework for electrolytic hydrogen production in Baja California Sur could anchor offtake for stranded renewable capacity.
- Agrivoltaic convergence:Dual-use solar installations over irrigated agriculture in Sinaloa offer land efficiency gains as water-intensive crop zones face electricity cost pressures.
Industry Challenges
- Permitting timeline compression:SEMARNAT environmental impact reviews for projects exceeding fifty megawatts now average fourteen months, delaying financial close and construction mobilization.
- Grid code compliance costs:New CRE interconnection standards requiring fault ride-through and reactive power capabilities impose retrofits on operational wind farms in Tamaulipas.
- Specialized technician scarcity:High-voltage substation commissioning and inverter maintenance skills concentrate in Mexico City and Monterrey, forcing project developers to import crews to remote sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Renewable Energy Market |
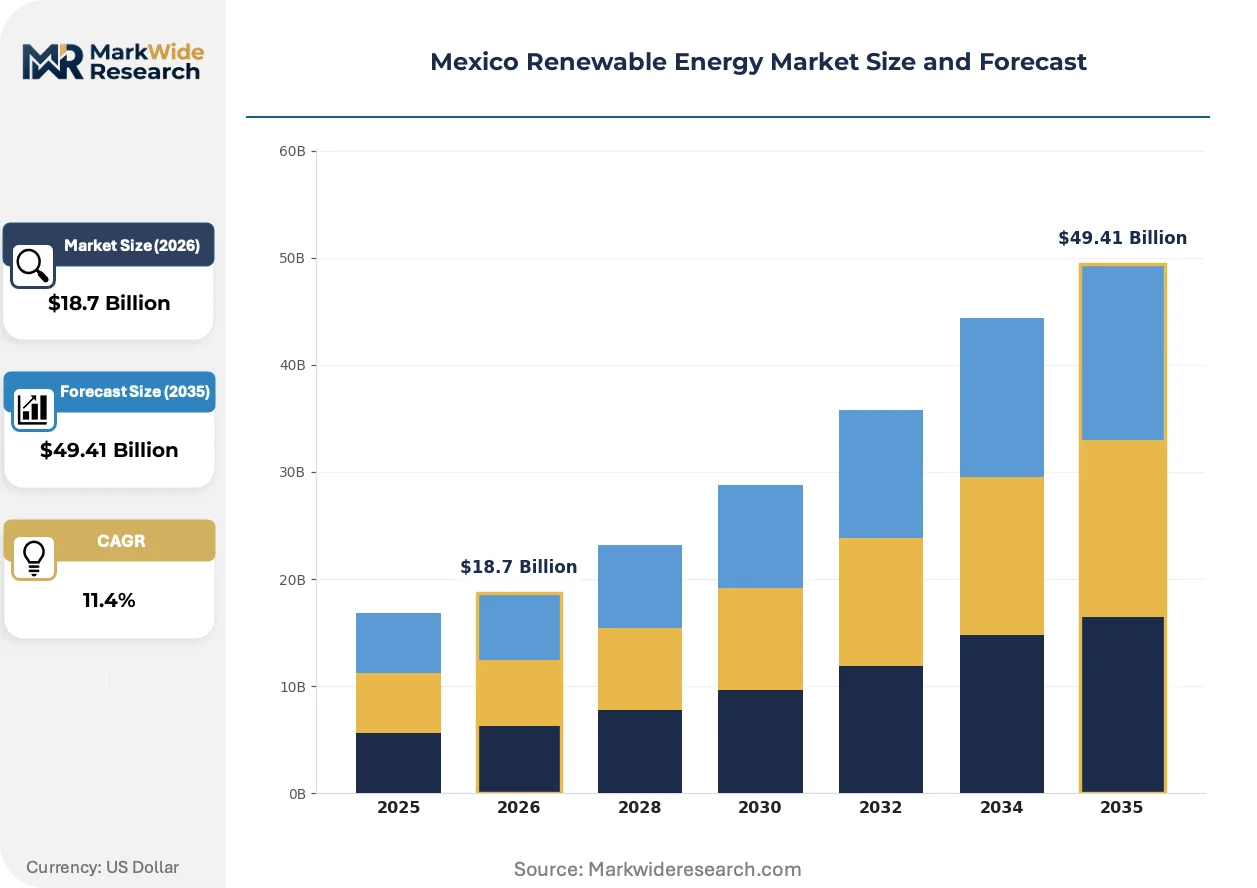
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Solar, Wind, Biomass, Hydro Application: Residential, Commercial, Industrial, Utility-scale Technology: Photovoltaic, Concentrated Solar Power, Wind Turbines, Bioenergy End User: Households, Corporations, Government, Utilities |
| Companies Covered | Enel Green Power, Cox Energy, Comisión Federal de Electricidad (CFE), Siemens Gamesa Renewable Energy SA, Canadian Solar Inc., Iberdrola SA, Sunstone Power, Vestas Wind Systems A/S, Acciona Energía, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Renewable Energy Market Strategic Shifts
Bifacial photovoltaic modules and advanced power electronics are compressing balance-of-system costs while policy instruments and procurement models fragment across federal and state jurisdictions.
Bifacial solar modules capturing reflected irradiance from albedo surfaces are rewriting project economics in Chihuahua's high-desert terrain. Industrial offtakers in Ciudad Juárez manufacturing parks are specifying bifacial arrays in tender documents to maximize generation density on constrained land parcels. This technology is rewriting competitive positioning between thin-film and crystalline silicon suppliers as performance guarantees tighten.
CRE's 2023 grid code reforms mandate synthetic inertia and voltage regulation capabilities for all new renewable interconnections above ten megawatts. Battery energy storage system developers are capturing incremental revenue streams from ancillary service contracts as CFE procures grid stability reserves. Wind-solar hybrid projects in the Isthmus of Tehuantepec are most affected, with developers resizing inverter loading ratios to comply.
Corporate buyers are bypassing traditional utility intermediaries to execute direct bilateral contracts with renewable generators. Food and beverage processors in Jalisco and automotive suppliers in Aguascalientes are aggregating demand through energy service companies that structure twenty-year fixed-price agreements. This pattern is most visible in central Mexico where CFE's regulated tariffs exceed merchant market clearing prices by fifteen to twenty percent.
Mexico Renewable Energy Market Segmentation
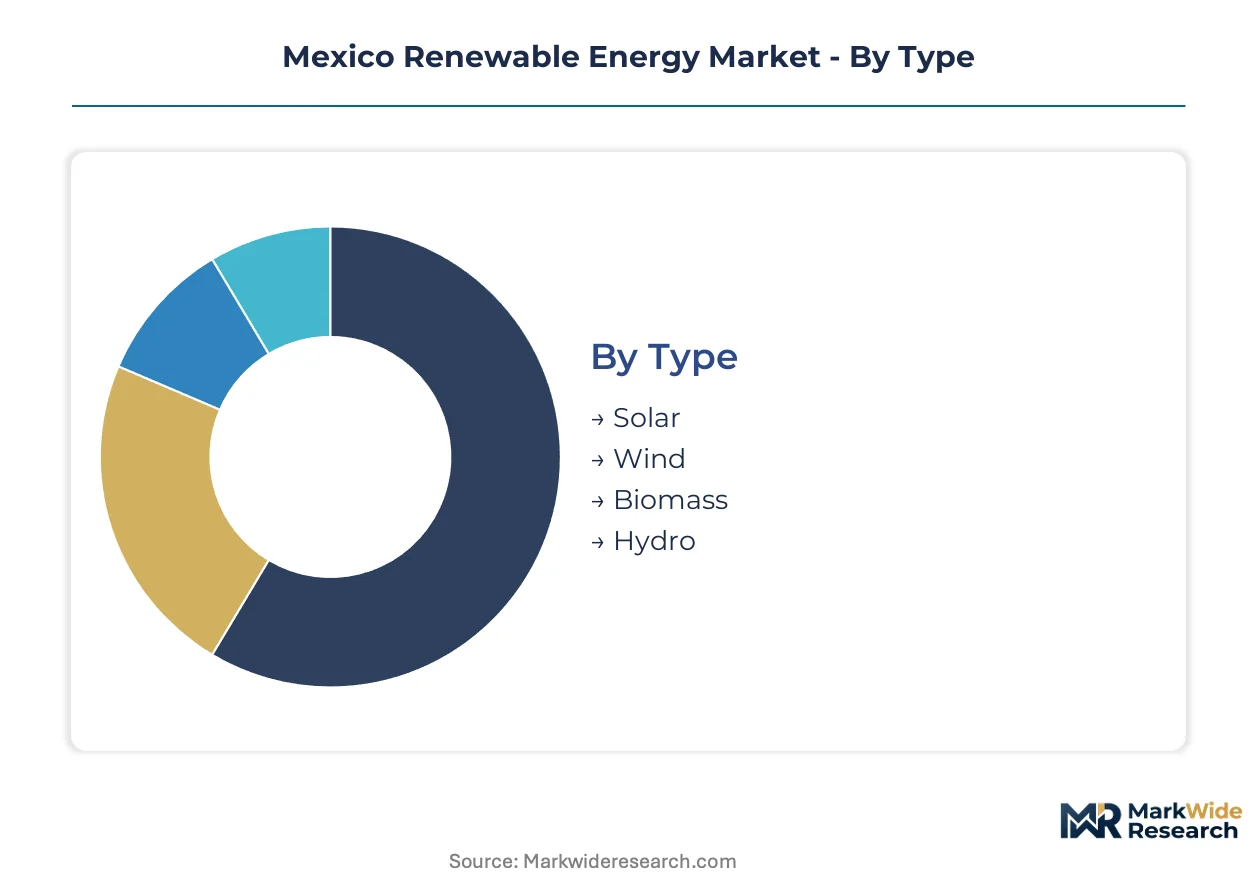
Technology choice and application scale determine capital intensity, permitting pathways, and offtake contract structures across Mexico's renewable buildout. Segment-level positioning dictates which developers capture CFE procurement mandates versus corporate PPA flows.
Type:
Technology selection maps directly to resource geography and grid access economics in Mexico's renewable deployment.
- Solar:Photovoltaic arrays dominate capacity additions, exploiting irradiance levels exceeding 2,200 kWh/m² annually across Sonora and Baja California. Northern manufacturing clusters in Ciudad Juárez and Tijuana anchor demand for clean power offtake.
- Wind:Onshore turbines concentrate in Oaxaca's Isthmus of Tehuantepec and Tamaulipas coastal corridors where capacity factors surpass thirty-five percent. Transmission congestion here forces developers to size projects against existing 230 kV and 400 kV intertie capacity.
- Biomass:Agricultural residue combustion and biogas capture serve sugar mills in Veracruz and livestock operations in Jalisco, supplying captive industrial heat and limited grid injection.
- Hydro:Small run-of-river facilities in Chiapas and large reservoir plants in Guerrero provide firm capacity, though environmental review timelines for new large-scale projects now exceed four years.
Solar leads on scale; wind leads on momentum.
Application:
Project scale determines regulatory jurisdiction, financing structure, and offtake risk profile across Mexico's power market.
- Residential:Distributed solar installations under 10 kW connect via net metering schemes regulated by CRE, concentrated in middle-income suburbs of Mexico City and Monterrey where electricity tariffs exceed fifteen pesos per kWh.
- Commercial:Mid-size rooftop and carport solar serves retail chains and office complexes in Guadalajara and Querétaro, typically financed through leasing structures that transfer tax benefits to offtakers.
- Industrial:Behind-the-meter systems for automotive assemblers and electronics manufacturers in Nuevo León bypass CFE's regulated tariff, capturing price stability through twenty-year self-supply contracts.
- Utility-scale:Projects exceeding 50 MW interconnect at high voltage and compete for CFE long-term auctions or merchant spot market exposure, requiring land assemblies of 500+ hectares in northern desert zones.
Utility-scale commands capital deployment; industrial applications are expanding most quickly.
Technology:
Equipment specification shapes balance-of-system costs and grid compliance obligations under evolving CRE standards.
- Photovoltaic:Crystalline silicon modules, increasingly bifacial designs, capture albedo gains in Chihuahua's high-desert terrain. Inverter loading ratios now sized to accommodate new synthetic inertia mandates.
- Concentrated Solar Power:Parabolic trough and tower systems with molten salt storage provide dispatchable renewable capacity, though only one operational plant exists in Sonora given higher capital intensity versus PV.
- Wind Turbines:Siemens Gamesa and Vestas supply nacelles rated 3-5 MW for Isthmus projects, with hub heights climbing to 120 meters to capture stronger wind shear layers.
- Bioenergy:Anaerobic digesters and combustion boilers convert agricultural waste to electricity, concentrated in states with established sugar and livestock processing infrastructure.
Photovoltaic leads on scale; wind turbines lead on momentum.
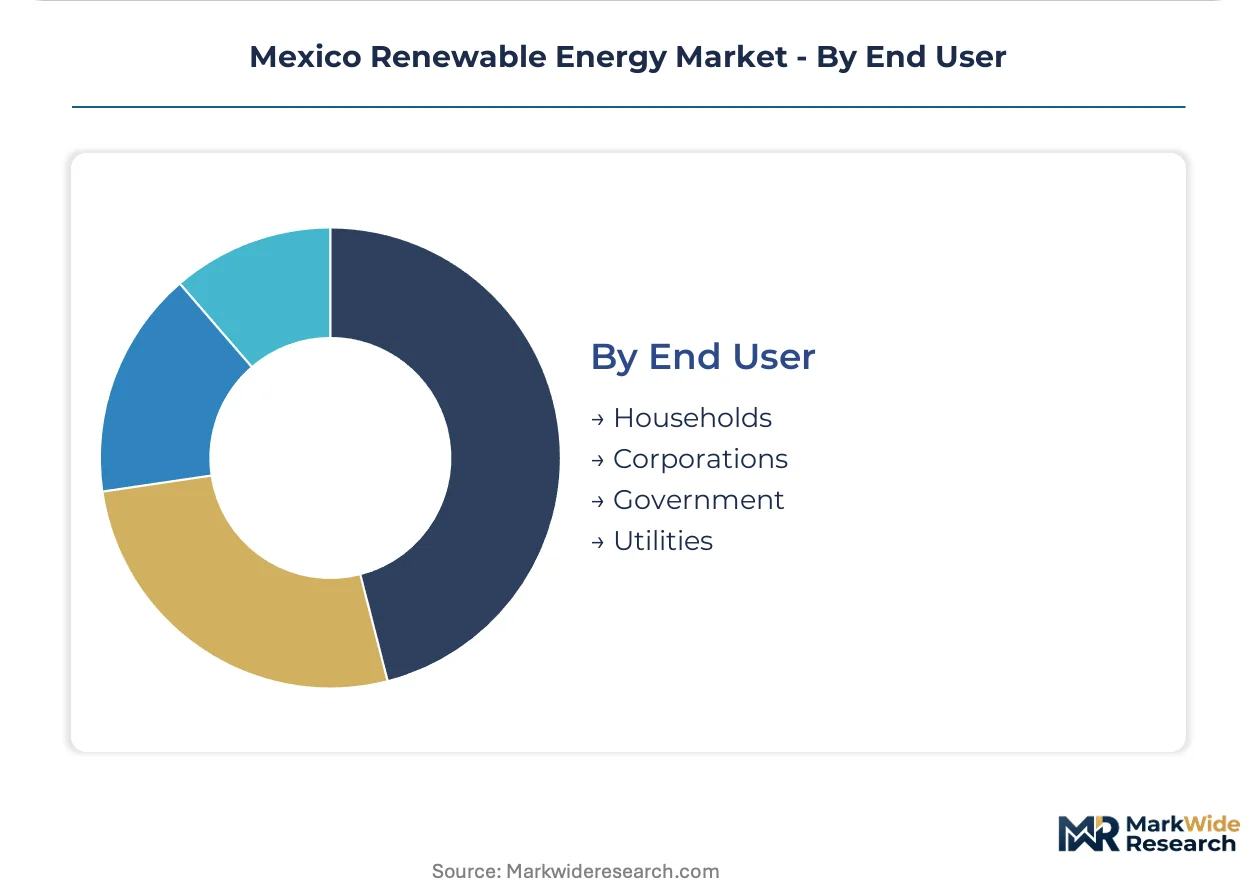
End User:
Customer category determines contract tenor, credit risk weighting, and regulatory compliance exposure for project developers.
- Households:Individual consumers participate through net metering and community solar programs, with aggregate demand constrained by CFE's interconnection queue capacity in urban distribution zones.
- Corporations:Multinational manufacturers and data center operators execute direct bilateral PPAs, driving procurement in Baja California and Querétaro to meet Scope 2 emissions targets.
- Government:Federal and state entities procure renewable capacity through CFE-administered auctions, with SENER setting clean energy certificate obligations that shape tender design.
- Utilities:CFE and private load-serving entities acquire renewable assets to meet Energy Transition Law mandates, though constitutional reforms since 2021 have shifted procurement toward state-controlled generation.
Corporations lead on scale; utilities lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Renewable project development migrates toward states offering streamlined permitting and grid access, creating regulatory arbitrage between northern resource zones and congested southern corridors. Developers prioritize sub-regions where SENER transmission expansion timelines align with project completion schedules.
Nuevo León
Automotive and electronics manufacturing clusters in Monterrey and Apodaca drive corporate PPA demand as assemblers seek price stability. The state's industrial development authority coordinates land assembly for utility-scale solar parks. CFE's 400 kV intertie expansion through García substation enables merchant capacity additions serving the Monterrey metro load center.
Sonora
Solar irradiance exceeding 2,200 kWh/m² annually attracts concentrated photovoltaic deployment across the Sonoran Desert. SEMARNAT environmental reviews for projects above 50 MW average fourteen months, compressing development timelines against certificate compliance deadlines. Puerto Peñasco hosts the nation's sole operational concentrated solar power tower with molten salt storage.
Oaxaca
The Isthmus of Tehuantepec wind corridor sustains capacity factors above 35 percent across coastal ridges. Transmission congestion forces developers to size projects against existing 230 kV intertie capacity pending SENER grid expansion. Juchitán and La Venta anchor turbine supply logistics for Siemens Gamesa and Vestas nacelle installations.
Baja California
Cross-border electricity trade opportunities and isolated grid configuration attract behind-the-meter solar for maquiladora operations in Tijuana and Mexicali. CRE net metering schemes enable commercial rooftop deployment without CFE interconnection queue delays. SENER's proposed green hydrogen regulatory framework targets stranded renewable capacity in Baja California Sur.
Jalisco
Food and beverage processors in Guadalajara execute direct bilateral contracts bypassing CFE regulated tariffs. Commercial solar leasing structures transfer tax benefits to retail chain offtakers across the metropolitan zone. Tlajomulco and El Salto industrial parks concentrate distributed generation installations financed through energy service companies.
Mexico Renewable Energy Market Competitive Environment
Italian and Spanish utilities anchor one tier through operational scale across multiple states; Danish and German turbine specialists hold equipment supply positions in wind corridors. The market structures around three archetypes: state-linked generation entities with auction access, independent power producers with corporate PPA relationships, and equipment suppliers controlling nacelle and module logistics. Consolidation pressures concentrate in utility-scale development rights, while technology licensing agreements reshape competitive positioning between crystalline silicon and thin-film module suppliers.
Within the independent power producer tier, Enel Green Power and Iberdrola SA exemplify developers leveraging multi-state operational footprints to sustain development velocity. Siemens Gamesa Renewable Energy SA anchors wind turbine supply positioning across the Isthmus of Tehuantepec corridor.
| Leading Market Players |
|---|
| Enel Green Power |
| Cox Energy |
| Comisión Federal de Electricidad (CFE) |
| Siemens Gamesa Renewable Energy SA |
| Canadian Solar Inc. |
| Iberdrola SA |
| Sunstone Power |
| Vestas Wind Systems A/S |
| Acciona Energía |
| Others |
Value Chain & Pricing Dynamics
CRE's clean energy certificate mandates gate qualified supply access and premium-tier pricing for developers serving CFE and corporate offtakers. Certificate compliance deadlines compress development timelines, forcing buyers to absorb higher execution premiums for shovel-ready projects with secured interconnection permits.
Pricing Analysis
Direct-to-OEM offtake discounts dominate large-scale renewable procurement, with automotive assemblers in Nuevo León extracting fifteen-to-twenty percent tariff savings against CFE regulated rates. Price differentiation rests on interconnection queue position and environmental permit status, with SEMARNAT-approved projects commanding development premiums. Cost compression in utility-scale solar intensifies as Chinese module oversupply flows through Lázaro Cárdenas. Industrial buyers show lowest price sensitivity, absorbing green premiums to secure Scope 2 compliance; residential net-metering participants face highest sensitivity to upfront capital requirements.
Supply Chain Analysis
Regional distribution centers at Guadalajara and Monterrey anchor hub-and-spoke turbine component logistics for wind corridors in Oaxaca and Tamaulipas. Module supply concentrates in China, Vietnam, and Thailand, with inverter electronics sourced from Germany and Taiwan. Raw material dependencies span polysilicon, rare-earth magnets, and high-grade steel. Tariff exposure on Southeast Asian solar components threatens developer margins. Distribution runs through specialized EPC contractors with CRE certification for high-voltage substation commissioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Mexico's renewable sector hinges on bifacial module cost-down curves and corporate PPA premium capture. Developers securing early-mover positions in transmission-constrained zones extract scarcity rents as grid expansion lags.
For Market Incumbents: Anticipate constitutional reform impacts on auction access by diversifying toward bilateral corporate contracts with nearshoring manufacturers. Consolidate land positions in Sonora and Baja California before SEMARNAT review timelines extend further. Vertical integration into battery storage engineering addresses CRE's synthetic inertia mandates and captures ancillary service revenue streams. For New Entrants and Emerging Players: Launch via energy service company partnerships targeting mid-size commercial rooftops in Guanajuato and Jalisco, bypassing utility-scale interconnection queues. Behind-the-meter solar for food processors represents the most penetrable white-space segment. White-label financing structures transfer tax equity benefits to offtakers while preserving developer cash flows. For Investors and Strategic Acquirers: Roll-up economics work for distributed generation platforms because CRE's net metering caps create fragmented local markets with operational synergies. Five-to-ten year viability favors developers with contracted PPA backlogs exceeding development pipeline costs. Monitor SENER transmission expansion announcements as the inflection signal for stranded capacity repricing in Oaxaca.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement | Corporate offtakers in Nuevo León bypass CFE tariffs through direct bilateral contracts. |
| Capacity Buildout | Utility-scale solar parks in Sonora exploit irradiance levels exceeding 2,200 kWh/m² annually. |
| Vertical Integration into Storage | Battery developers capture CRE ancillary service contracts for grid stability reserves. |
| Green Certification Program | Clean energy certificate compliance de-risks project finance for private developers. |
| Technology Licensing | Bifacial module suppliers rewrite competitive positioning through performance guarantees in Chihuahua. |
Study Parameters
Bottom-up offtake modeling reconciled against top-down generation capacity tracking forms the analytical core of this study. Primary interviews with IPP project developers, CFE planning officers, EPC contractors, and corporate energy procurement leads inform demand assumptions. Secondary validation draws from SENER planning documents, CRE interconnection databases, SEMARNAT environmental filings, and IEA renewable outlooks. Triangulation between stakeholder-grounded capacity forecasts and equipment import data ensures consistency across the analysis window.
Historical trendline analysis of capacity additions and certificate market liquidity establishes baseline growth parameters. Segmentation dimensions span technology type, application scale, end-user category, and regional grid configuration. CAGRs derive from fitted growth curves applied to announced project pipelines, adjusted for permitting timeline risks and transmission expansion schedules. Forecast inputs incorporate module cost trajectories and corporate PPA execution rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under constitutional reform implementation and trade policy shifts. Outputs reflect documented assumptions regarding SENER transmission timelines and SEMARNAT review durations. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Saudi Arabia Renewable Energy Market
Renewable Energy
Renewable Energy Consulting Service Market
Renewable Energy
Solar Drying System Market
Renewable Energy
France Renewable Energy Market
Renewable Energy
Renewable Energy Consulting Market
Renewable Energy
Wave Energy Converter Market
Renewable Energy
South Asia Renewable Energy Market
Renewable Energy
North America Ocean Power Market
Renewable Energy
Wind Turbine Crane Market
Renewable Energy
Tidal Energy Generation Systems Market
Renewable Energy
Kazakhstan Renewable Energy Market
Renewable Energy
North Europe Renewable Energy Market
Renewable Energy
Ocean Energy Market
Renewable Energy
North America Renewable Energy Market
Renewable Energy
Indonesia Renewable Energy CAPEX Market
Renewable Energy
PV Water Heater Market