
 Power Line Carrier System Market | 2026-2036
Power Line Carrier System Market Size, Share, and Industry Trends Forecast 2026-2036
Power Line Carrier System Market Analytics
Modular hardware-software bundling is hardening as the dominant procurement pattern for utility buyers. Siemens leverages its embedded software stack to anchor long-term service contracts. ABB competes through integrated substation automation platforms that extend PLC functionality into broader grid orchestration.
A power line carrier system transmits data signals over existing electrical power lines, typically operating in frequency bands between 3 kHz and 500 kHz to avoid interference with standard 50/60 Hz power transmission. The technology enables bidirectional communication for load management and network monitoring without requiring dedicated communication infrastructure. Signal modulation technologies dominate current installations due to proven reliability in noisy electrical environments, while demand response applications are expanding fastest as grid operators seek real-time consumption flexibility. Utilities represent the deepest margin pool given their multi-decade asset replacement cycles and preference for certified, interoperable systems.
FERC Order 2222 in the US and the EU Green Deal's grid digitalization targets are reshaping compliance requirements for bidirectional communication infrastructure. China's GB standards for power line communication, administered by SAMR, mandate electromagnetic compatibility testing that filters out non-compliant equipment suppliers. Grid operators must monitor evolving cybersecurity frameworks from IEC and national regulators, as data encryption capabilities transition from optional features to baseline procurement requirements.
Market Dynamics
China's dual carbon goals from MEE are compressing grid efficiency mandates across utility procurement cycles, forcing distribution automation upgrades that embed power line carrier hardware into multi-decade asset replacement programs.
Growth Catalysts
- Smart Metering Mandates:Utility-scale smart metering programs in China, India, and Germany are creating sustained demand for bidirectional communication infrastructure that operates over existing power lines.
- FERC Order 2222:This US regulation mandates bidirectional communication capabilities for distributed energy resource aggregation, directly expanding addressable market for PLC-enabled grid orchestration systems.
- Signal Modulation Reliability:Proven performance in noisy electrical environments makes narrowband PLC the default choice for load management applications across residential and industrial substations.
Market Restraints
- Copper Price Volatility:Input costs for power line coupling equipment fluctuate with commodity markets, squeezing hardware margins for system integrators.
- Frequency Bandwidth Limitations:Operation between 3 kHz and 500 kHz constrains data throughput for high-resolution grid monitoring applications.
- Cellular Substitution Threat:NB-IoT and LoRaWAN networks are capturing last-mile communication contracts where dedicated infrastructure economics prove favorable.
Strategic Opportunities
- Rural Electrification in India:Underpenetrated distribution networks offer white space for PLC deployment where fiber backhaul remains economically unviable.
- Cybersecurity Certification Tailwinds:IEC frameworks transitioning encryption from optional to baseline requirements create upgrade cycles for installed base systems.
- Edge-AI Convergence:Integration of embedded analytics with PLC endpoints enables real-time fault detection without centralized cloud dependency.
Industry Challenges
- EMC Testing Bottlenecks:China's GB standards administered by SAMR impose lengthy electromagnetic compatibility certification timelines that delay product launches.
- Legacy System Integration:Utilities operating decades-old SCADA architectures face complex retrofit requirements for PLC overlay deployment.
- Specialized Firmware Talent:Shortage of engineers proficient in real-time embedded systems for noisy channel communication limits vendor scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Line Carrier System Market |
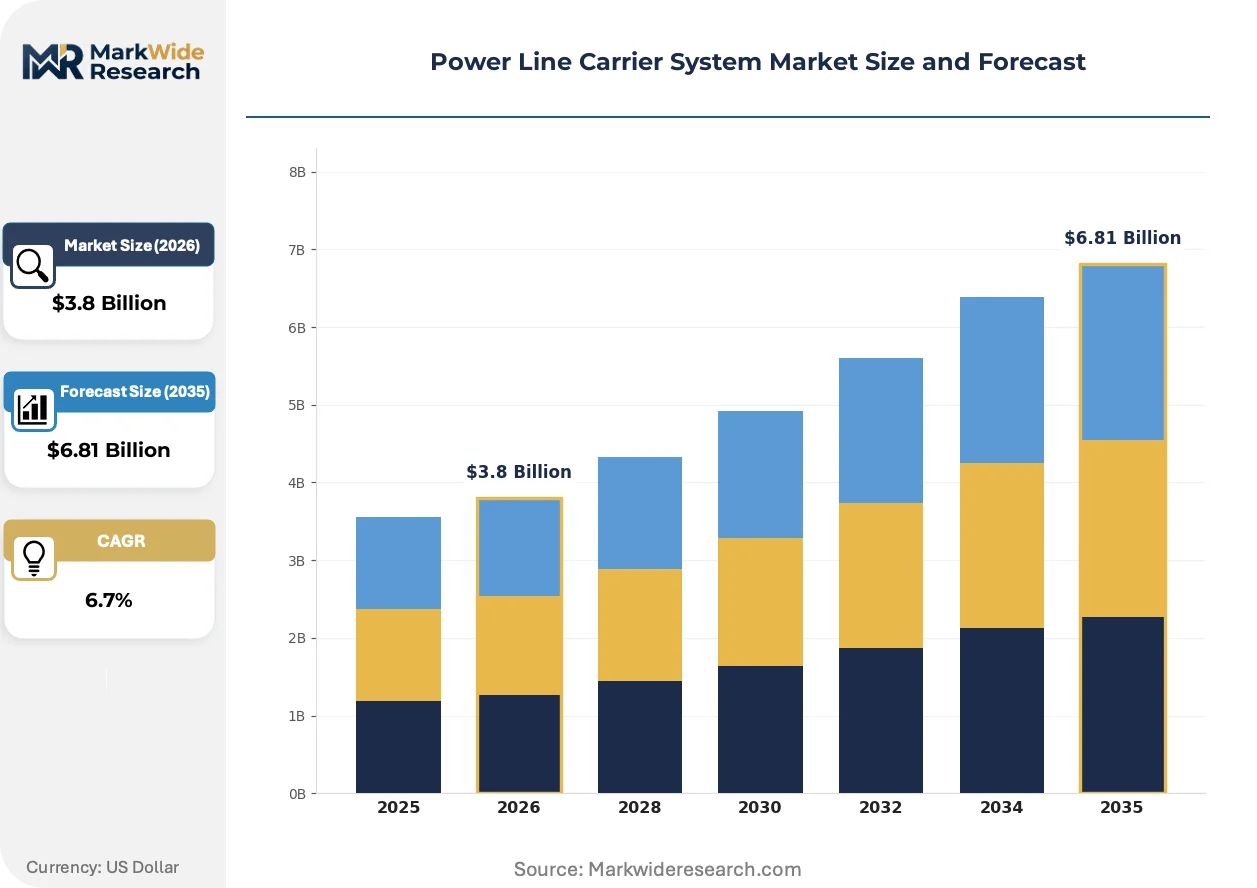
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Signal Modulation, Data Encryption, Load Management, Network Monitoring Application: Smart Metering, Remote Monitoring, Demand Response, Distribution Automation End User: Utilities, Industrial Plants, Commercial Facilities, Residential Users Installation: On-grid, Off-grid, Underground, Overhead |
| Companies Covered | Siemens, ABB, Schneider Electric, General Electric, NETGEAR, AMETEK, Hitachi Energy, TP-Link Technologies, Landis+Gyr, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Line Carrier System Market Evolving Landscape
Modular hardware-software bundling is hardening as the dominant procurement pattern, with vendors anchoring long-term service contracts through embedded software stacks rather than discrete equipment sales.
Broadband power line communication is unifying medium-voltage grid monitoring with last-mile consumer access in single infrastructure deployments. European utilities in Germany and Austria are piloting these converged architectures for rural distribution networks. This unification is compressing total cost of ownership calculations against fiber alternatives.
The EU Green Deal's grid digitalization targets are mandating real-time consumption visibility as a condition of network access tariffs. Industrial loads above 250 kW must install sub-15-minute interval metering with bidirectional communication capability. German grid operators are responding with PLC-centric retrofit programs to avoid fiber trenching costs.
Utility procurement committees are consolidating vendor relationships around certified interoperability rather than lowest-bid hardware. Siemens and ABB are capturing multi-year framework agreements that bundle equipment, software licensing, and predictive maintenance. This consolidation is most visible in China's State Grid tender processes where technical qualification gates now exceed price weighting.
Power Line Carrier System Market Segmentation
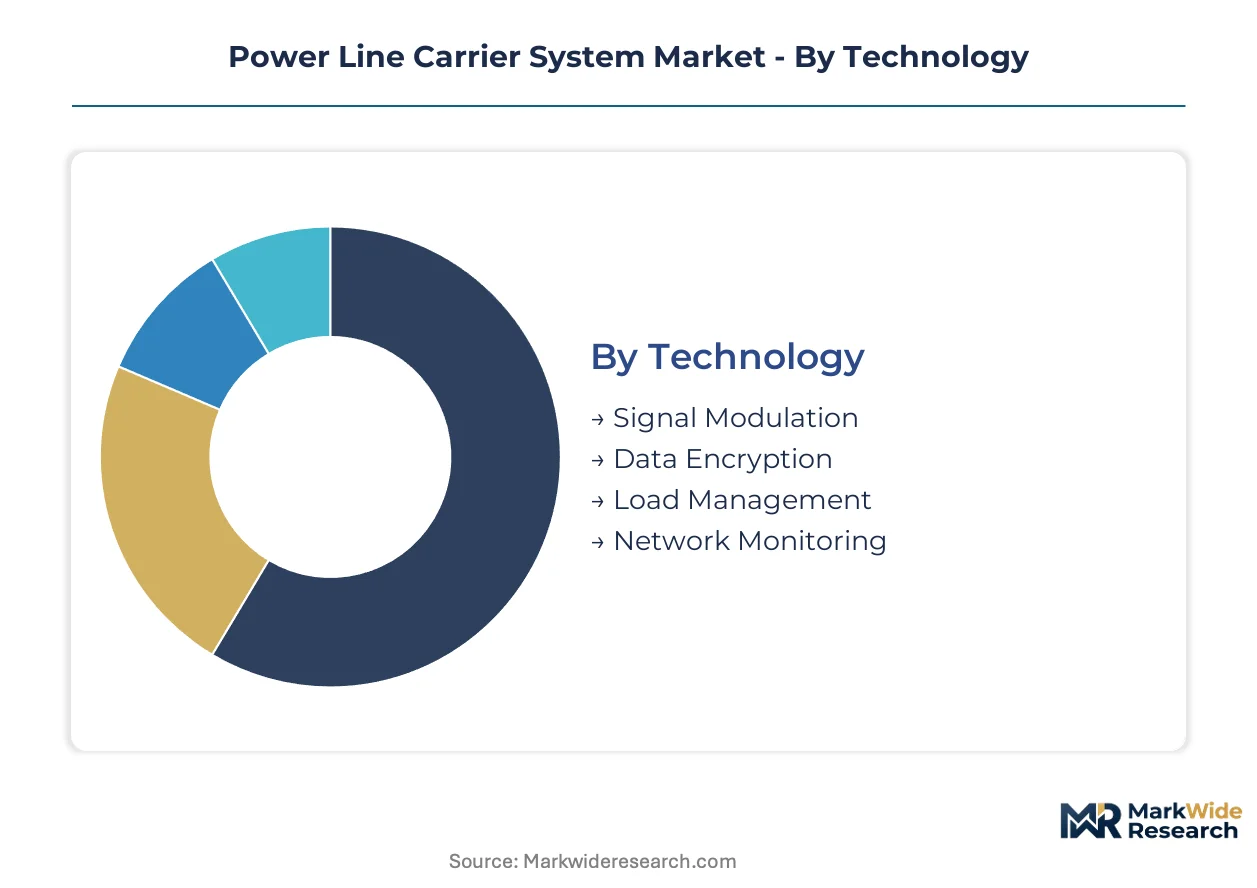
Power line carrier system procurement varies sharply across deployment contexts. Utility buyers prioritize certified interoperability for multi-decade asset cycles, while industrial and commercial adopters weigh installation flexibility against throughput requirements. Understanding these segment-specific decision drivers exposes where margin pools concentrate.
Technology:
Certification complexity and electromagnetic compatibility testing requirements dominate technology selection for grid-scale buyers.
- Signal Modulation:Narrowband modulation schemes between 3 kHz and 500 kHz avoid interference with standard power transmission frequencies. Chinese State Grid tenders specify these schemes for distribution automation, with SAMR-administered GB standards filtering non-compliant suppliers from procurement shortlists.
- Data Encryption:Hardware-level encryption capabilities are transitioning from optional features to baseline requirements under IEC cybersecurity frameworks. German utilities facing EU Green Deal mandates now specify encrypted PLC endpoints for industrial loads above 250 kW.
- Load Management:Bidirectional communication enables real-time consumption flexibility for demand response programs.
- Network Monitoring:Embedded analytics at PLC endpoints support fault detection without centralized cloud dependency.
Signal modulation leads on scale; data encryption leads on momentum.
Application:
Regulatory mandates reshape application prioritization across geographies.
- Smart Metering:Utility-scale deployment programs in China, India, and Germany create sustained infrastructure demand. FERC Order 2222 in the US mandates bidirectional capabilities for distributed energy resource aggregation, expanding addressable market for PLC-enabled systems.
- Distribution Automation:China's MEE dual carbon goals compress grid efficiency mandates, forcing automation upgrades that embed PLC hardware into asset replacement cycles. State Grid procurement processes now weight technical qualification above price.
- Remote Monitoring:Real-time visibility requirements spread across medium-voltage and last-mile networks.
- Demand Response:Consumption flexibility applications expand fastest as operators seek load balancing tools.
Smart metering dominates installed base; distribution automation climbs fastest.
End User:
Asset replacement cycles and procurement sophistication diverge sharply across user categories.
- Utilities:Multi-decade infrastructure horizons and preference for certified, interoperable systems create the deepest margin pool. Framework agreements bundle equipment, software licensing, and predictive maintenance across 5-10 year contracts.
- Industrial Plants:Sub-15-minute interval metering mandates under EU network access tariffs drive retrofit demand. German industrial operators favor PLC solutions to avoid fiber trenching costs.
- Commercial Facilities:Mid-scale loads seek cost-effective communication without dedicated infrastructure investment.
- Residential Users:Smart home integration and time-of-use pricing participation create emerging demand pockets.
Utilities anchor revenue concentration; industrial plants show steepest expansion trajectory.
Installation:
Physical deployment constraints determine total cost of ownership calculations.
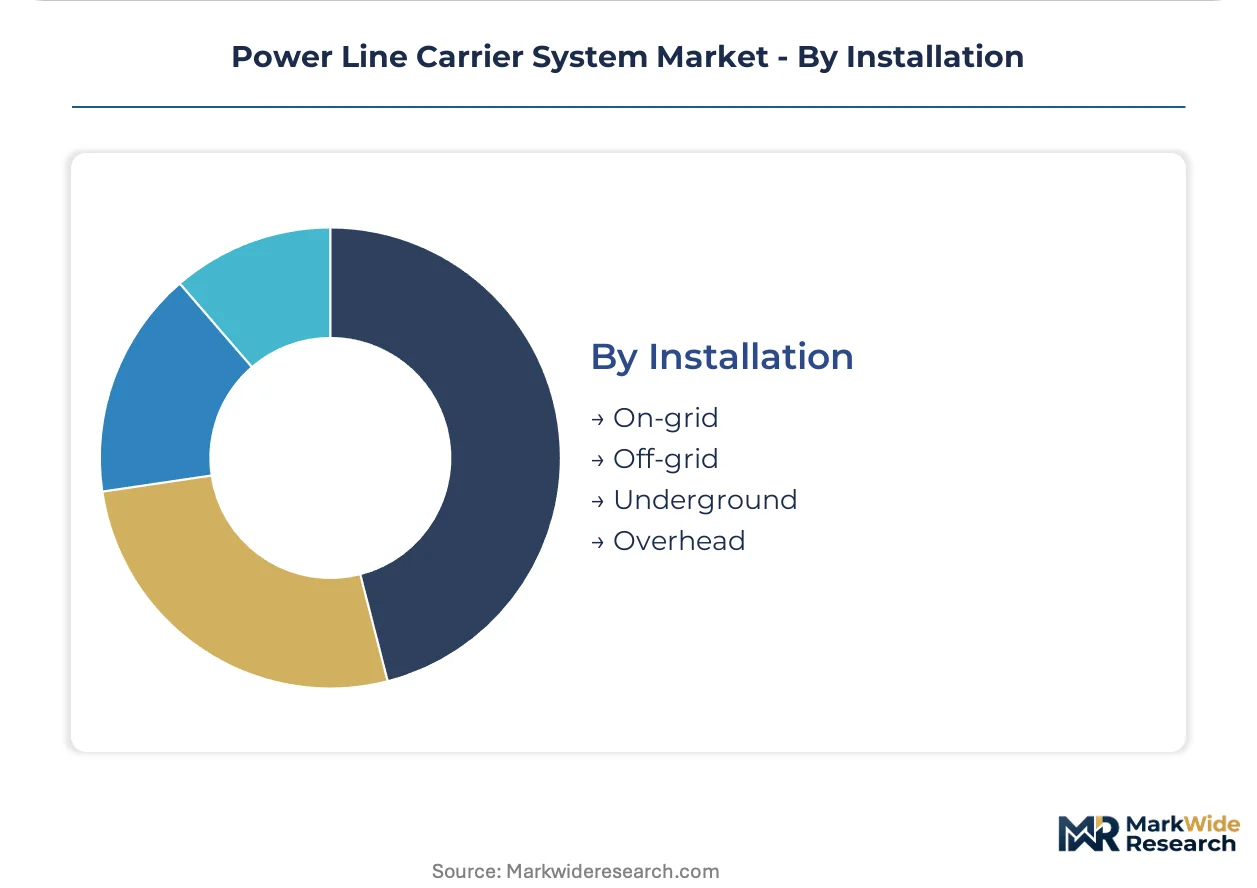
- On-grid:Existing power line infrastructure eliminates dedicated communication cable requirements. European utilities in Germany and Austria pilot converged architectures unifying medium-voltage monitoring with consumer access.
- Underground:Trenching cost avoidance favors PLC in dense urban environments where fiber deployment faces right-of-way barriers.
- Overhead:Rural distribution networks with existing pole infrastructure suit rapid PLC overlay deployment.
- Off-grid:Microgrid and remote electrification applications emerge in underpenetrated networks.
On-grid installations dominate deployment volume; underground configurations gain share fastest in urban retrofit markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power line carrier technology achieved commercial scale in Germany during the 1990s through early smart metering pilots, establishing narrowband PLC as the foundational architecture for utility-scale bidirectional communication over existing electrical infrastructure.
China
State Grid Corporation operates the world's largest smart metering deployment, with over 500 million PLC-enabled endpoints installed across provincial grids. SAMR-administered GB standards mandate electromagnetic compatibility testing that filters non-compliant equipment from procurement shortlists. Jiangsu and Zhejiang provinces lead distribution automation upgrades, embedding carrier hardware into multi-decade asset replacement cycles under MEE dual carbon mandates.
Germany
EU Green Deal grid digitalization targets compress network access tariff compliance timelines, requiring industrial loads above 250 kW to install sub-15-minute interval metering with bidirectional capability. Federal Network Agency regulations favor PLC retrofit programs to avoid fiber trenching costs in dense urban environments. Bavaria and North Rhine-Westphalia utilities pilot converged architectures unifying medium-voltage monitoring with consumer access.
United States
FERC Order 2222 mandates bidirectional communication capabilities for distributed energy resource aggregation, expanding addressable market for PLC-enabled grid orchestration systems. State-level renewable portfolio standards in California and Texas accelerate demand response program deployment. PJM Interconnection territory shows concentrated utility procurement activity for load flexibility infrastructure.
India
Rural electrification programs under the Ministry of Power create white space for PLC deployment where fiber backhaul remains economically unviable across underpenetrated distribution networks. CEA technical standards specify communication protocols for smart grid pilots in Maharashtra and Gujarat. Bangalore and Hyderabad industrial clusters drive commercial facility adoption for cost-effective energy management without dedicated infrastructure investment.
Japan
METI strategic energy plan targets 100% smart meter penetration by 2024, with Tokyo Electric Power and Kansai Electric deploying narrowband PLC for residential load management. Post-Fukushima grid resilience investments prioritize fault detection capabilities at distribution endpoints. Osaka and Nagoya manufacturing corridors represent concentrated industrial demand for real-time consumption visibility.
Power Line Carrier System Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification complexity and service contract duration, with utility procurement committees consolidating vendor relationships around certified interoperability rather than lowest-bid hardware. The vendor base stratifies into three archetypes: integrated industrial conglomerates bundling equipment with embedded software stacks, specialized communication technology firms competing on protocol flexibility, and regional system integrators capturing retrofit installation contracts. Dominant competitive moves include framework agreement anchoring through predictive maintenance bundling and geographic expansion via local certification partnerships.
Within the integrated conglomerate tier, Siemens and ABB exemplify archetype positioning through multi-year utility framework agreements that extend beyond discrete equipment sales. Schneider Electric occupies a position representing the protocol-specialist vector, while NETGEAR and TP-Link Technologies sit within the consumer-access equipment segment where installation flexibility competes against throughput requirements. These named entities anchor industry-level commentary on procurement pattern evolution without implying specific strategic actions or market share positions.
| Leading Market Players |
|---|
| Siemens |
| ABB |
| Schneider Electric |
| General Electric |
| NETGEAR |
| AMETEK |
| Hitachi Energy |
| TP-Link Technologies |
| Landis+Gyr |
| Others |
Value Network & Pricing Analysis
Captive in-house production of signal modulation chipsets anchors supply positioning for integrated vendors while licensing arrangements dominate specialized communication technology firms, concentrating pricing power with conglomerates that bundle embedded software stacks into multi-year service contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Siemens and ABB's framework-agreement bundles from Schneider Electric's protocol-flexible offerings and regional integrators' retrofit installation contracts. Price differentiation hinges on IEC cybersecurity certification tier and predictive maintenance bundling depth. Cost compression in economy-tier hardware is intensifying because copper price volatility squeezes coupling equipment margins. Industrial plants above 250 kW show least price sensitivity due to EU Green Deal compliance mandates, while commercial facilities exhibit highest sensitivity to upfront capital outlay.
Supply Chain Analysis
Freight cost escalation from Asia-Pacific manufacturing hubs to European utility deployment sites compresses margin structures for non-integrated vendors. Component assembly concentrates in China, Germany, and Japan, drawing from silicon wafer foundries in Taiwan and South Korea. Raw material dependencies span copper for coupling equipment, semiconductor substrates for modulation chipsets, and rare earth elements for electromagnetic shielding. Single-source vulnerability in narrowband PLC chipset supply creates bottleneck risk. Distribution runs through certified system integrators with SAMR-administered GB standards compliance credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory tailwinds into sustained demand visibility, with FERC Order 2222 mandating bidirectional communication infrastructure expansion across US grid territories.
For Market Incumbents: To counter NB-IoT and LoRaWAN substitution threats in last-mile contracts, Siemens and ABB should deepen predictive maintenance bundling to extend framework agreement lock-in, while accelerating edge-AI firmware development to differentiate against cellular competitors. Certification investment in China's SAMR-administered GB standards remains essential for State Grid tender participation. For New Entrants and Emerging Players: The premium-economy tier gap in India's rural electrification programs offers white-space entry where fiber backhaul economics fail. Target Maharashtra and Gujarat distribution networks under CEA technical standards with modular hardware-software bundles priced below integrated conglomerate frameworks. Partner with local system integrators possessing existing SAMR or BIS certification pathways to bypass lengthy electromagnetic compatibility testing timelines. For Investors and Strategic Acquirers: Roll-up economics work for regional system integrators with captive certification credentials because utility procurement committees are consolidating vendor relationships around certified interoperability rather than lowest-bid hardware. Long-term viability extends through the grid digitalization investment cycle. Acquisition targets should demonstrate embedded software stack development capability and existing framework agreements with State Grid or Bundesnetzagentur-registered operators. Watch for IEC cybersecurity framework transitions from optional to mandatory encryption as inflection signal for installed base upgrade demand.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | IEC framework transitions create upgrade cycles for encryption-capable PLC endpoints. |
| Edge-AI Firmware Development | Embedded analytics integration enables real-time fault detection without cloud dependency. |
| Rural Electrification Partnership | India's Ministry of Power programs offer white space where fiber economics fail. |
| Framework Agreement Anchoring | Multi-year utility contracts bundle equipment, software licensing, and predictive maintenance. |
| Local Certification Partnership | SAMR-administered GB standards and BIS compliance accelerate product launch timelines. |
Research Methodology
Bottom-up utility procurement modeling reconciled against top-down semiconductor shipment tracking forms the analytical core of this study. Primary interviews with utility planning officers, grid automation procurement leads, substation integration engineers, and carrier system firmware developers combined with secondary validation from FERC filings, EIA grid infrastructure databases, IEC standards documentation, and State Grid tender announcements. Triangulation across these sources ensures segmentation integrity.
Historical trendline analysis of narrowband PLC deployment velocity informed projection framework construction across technology, application, end user, and installation dimensions. CAGRs derive from regression-adjusted growth rates applied to utility-scale smart metering program commitments and distribution automation upgrade cycles. Forecast inputs incorporate MEE dual carbon mandate compliance timelines and EU Green Deal network access tariff implementation schedules.
Caveats apply where copper commodity price volatility, cellular substitution acceleration, or cybersecurity framework timeline shifts could materially shift the outlook. Forecasts reflect assumptions regarding regulatory mandate adherence and infrastructure investment continuity. A model refresh is warranted upon material change in SAMR certification processing timelines or FERC Order 2222 implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
US Electric Towers and Poles Market
Electrical Power Equipment
Packaged Substation Market
Electrical Power Equipment
Industrial Power Supply Market
Electrical Power Equipment
Copper Ground Rod Market
Electrical Power Equipment
HV Bushing Market
Electrical Power Equipment
High Voltage Direct Current (HVDC) Capacitor Market
Electrical Power Equipment
North America Power Inverter Market
Electrical Power Equipment
Substation Testing Equipment Market
Electrical Power Equipment
Electric Vehicle Charging Cables Market
Electrical Power Equipment
Magnetic Optical Current Transformer Market
Electrical Power Equipment
Utility Equipment Market
Electrical Power Equipment
Load Bank Market
Electrical Power Equipment
High Voltage Direct Current (HVDC) Cables Market
Electrical Power Equipment
Low Voltage Protection Control Market
Electrical Power Equipment
AC Drives Market
Electrical Power Equipment
Middle East and Africa High Voltage Switchgear Market