
 South America Medium Voltage Switchgear Market | 2026-2036
South America Medium Voltage Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
South America Medium Voltage Switchgear Market Insights
Industrial buyers are reorganizing procurement priorities around arc-flash safety and remote monitoring capabilities, pulling investment away from traditional utility-centric specifications. ABB Ltd leverages its regional manufacturing footprint to sustain competitive lead times across Brazilian utility tenders. Schneider Electric anchors its position through localized assembly of gas-insulated switchgear for mining and petrochemical clients. Siemens AG differentiates with integrated digital twin offerings that span protection relay and switchgear portfolios.
South America medium voltage switchgear encompasses electrical apparatus rated between 1 kV and 52 kV, designed to control, protect, and isolate power circuits through vacuum, SF6, or air-insulated interruption mediums. These systems serve critical functions in distribution networks, industrial facilities, and infrastructure projects where fault current interruption and operational continuity determine system reliability. Circuit breakers command the largest product share due to mandatory protection requirements across utility and heavy industrial installations, while disconnectors gain traction in renewable interconnection projects requiring visible isolation points. Compact and modular installation types are expanding fastest as urban substations face space constraints and accelerated deployment timelines in Chilean and Peruvian mining corridors.
ANEEL in Brazil, Argentina's ENRE, and Colombia's CREG enforce technical standards governing short-circuit withstand, seismic qualification, and environmental compliance for medium voltage equipment procurement. These frameworks effectively mandate IEC-certified designs and localized testing protocols, creating compliance barriers for non-established suppliers. Stakeholders must monitor evolving carbon border adjustments and SF6 phase-down commitments that will reshape insulation technology selection and supplier qualification criteria across Andean and Mercosur jurisdictions.
Market Dynamics
ANEEL's loss-reduction mandates are compressing utility procurement cycles across Brazil, forcing simultaneous grid modernization and supplier qualification acceleration that reshapes competitive positioning for established equipment vendors.
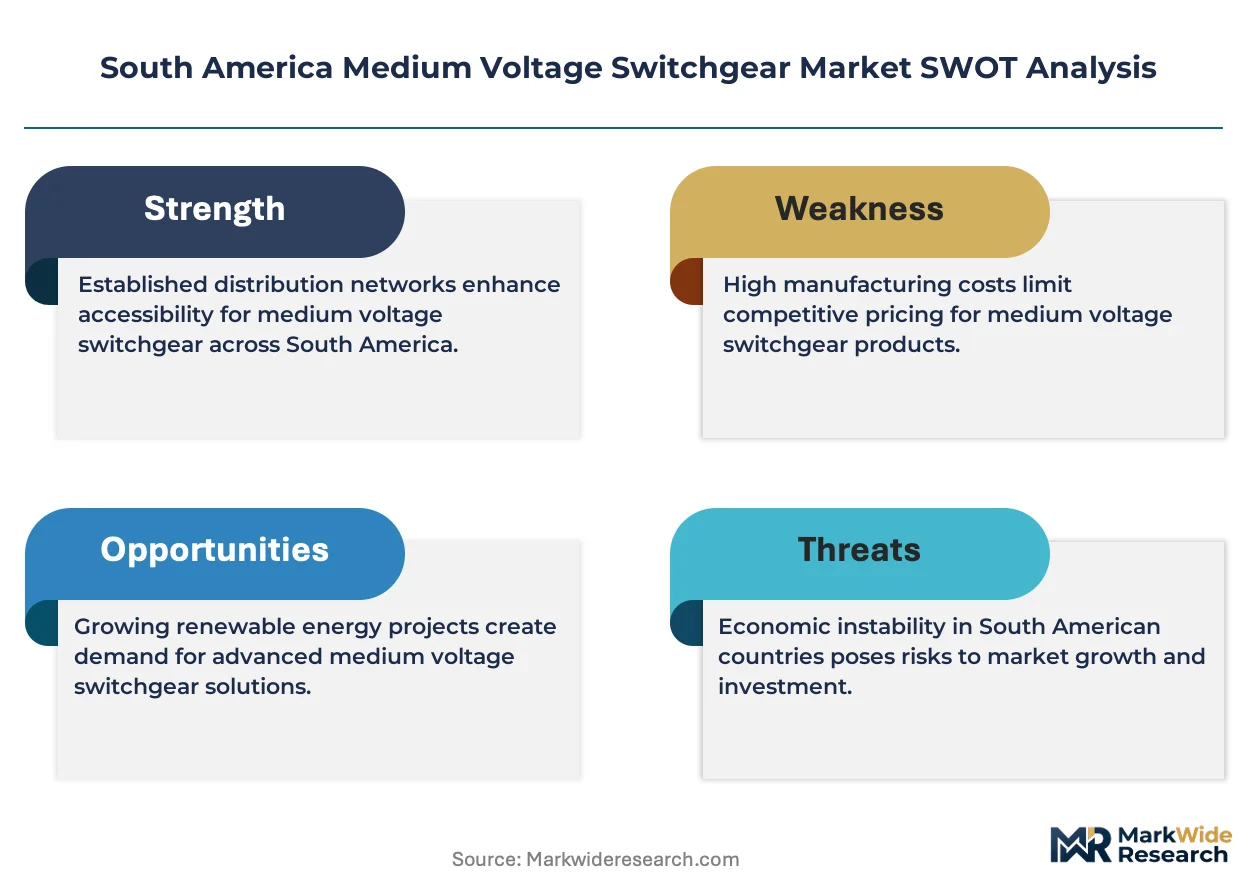
Growth Catalysts
- ANEEL Regulatory Mandates:Brazil's national electric energy agency enforces mandatory loss-reduction targets that accelerate substation replacement schedules and expand tender volumes for gas-insulated and vacuum interrupter technologies.
- Mining Corridor Electrification:Chilean and Peruvian copper and lithium extraction operations require compact modular switchgear for remote site power distribution, creating sustained demand for seismic-qualified equipment.
- SF6 Phase-Down Commitments:Environmental compliance frameworks across Mercosur and Andean jurisdictions are pulling investment toward vacuum interruption and dry-air insulation alternatives.
Market Restraints
- Copper and Steel Input Volatility:Raw material price swings for conductive and structural components compress OEM margins and complicate long-term tender pricing for Brazilian and Argentine utilities.
- Localized Testing Protocol Barriers:ANEEL, ENRE, and CREG certification requirements create compliance friction for non-regional suppliers lacking accredited in-country testing facilities.
- Extended Asset Lifecycles:Existing air-insulated switchgear installations operate 30-40 years, slowing replacement velocity despite reliability pressures.
Strategic Opportunities
- Colombian Renewable Interconnection:Wind and solar project pipelines in La Guajira and Antioquia require visible isolation disconnectors and specialized protection coordination.
- Digital Twin Integration:Convergence of protection relay intelligence with switchgear asset management creates service-contract expansion potential for predictive maintenance offerings.
- Data Center Load Concentration:São Paulo and Campinas hyperscale facility construction demands premium arc-flash-rated equipment with remote monitoring capabilities.
Industry Challenges
- Specialized Field Technician Scarcity:Vacuum interrupter maintenance and gas-insulated system commissioning require certified personnel that utilities and EPCs struggle to recruit across the region.
- Legacy Protection Coordination Complexity:New intelligent electronic device integration with electromechanical relay infrastructures creates commissioning delays and fault-clearance verification bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Medium Voltage Switchgear Market |
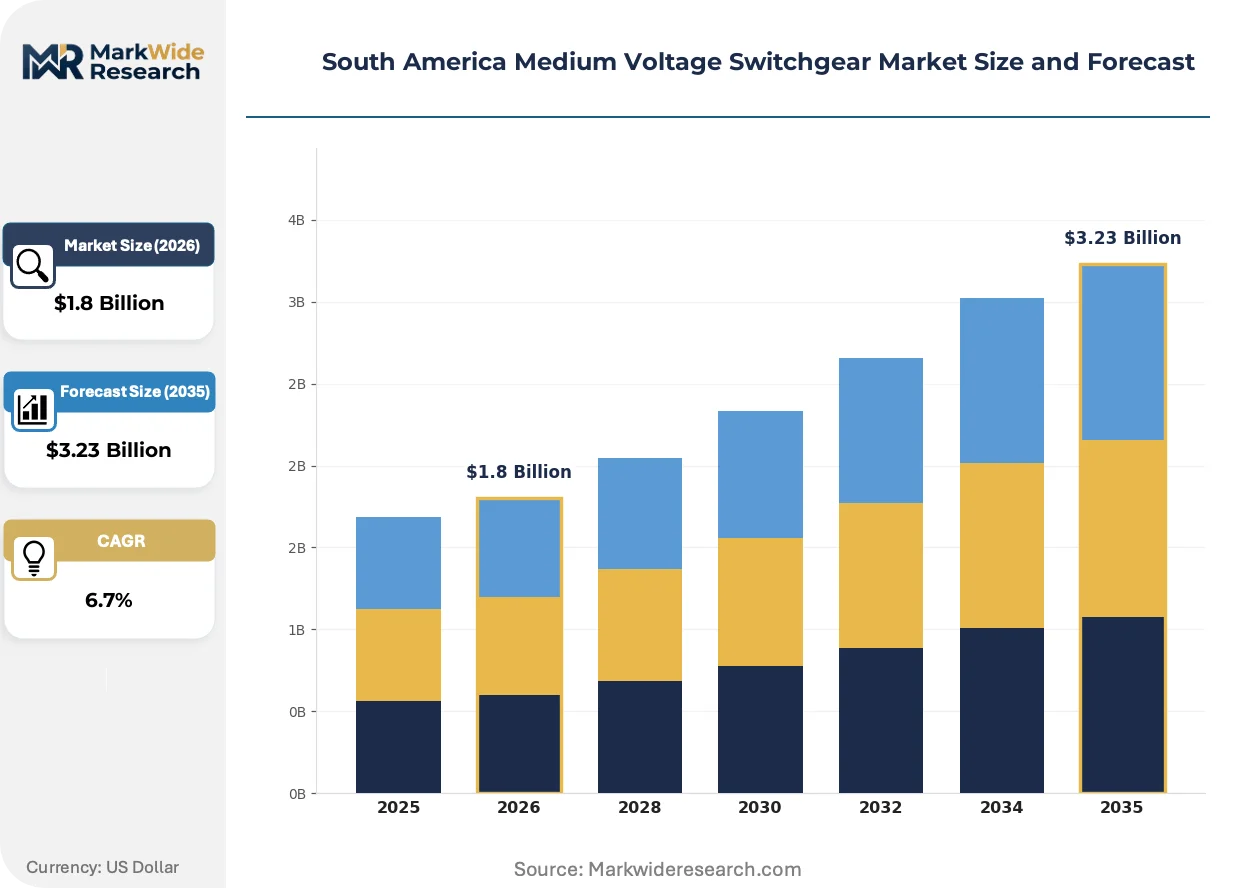
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switchgear, Circuit Breakers, Disconnectors, Load Break Switches End User: Utilities, Industrial, Commercial, Residential Installation Type: Indoor, Outdoor, Compact, Modular Deployment Model: New Installation, Retrofit, Replacement, Maintenance |
| Companies Covered | ABB Ltd, Schneider Electric, Siemens AG, Eaton Corporation, Mitsubishi Electric Corporation, GE Vernova, Hitachi Energy Ltd, Toshiba Energy Systems and Solutions Corporation, HD Hyundai Electric, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Medium Voltage Switchgear Market Trends and Innovations
Technology trajectories across South American medium voltage infrastructure are compressing traditional equipment categories while regulatory and procurement models force faster supplier adaptation cycles.
Vacuum interrupter technology is decomposing the historical dominance of SF6-insulated circuit breakers in utility distribution applications. Mining operators in Chile and Peru specify vacuum solutions for remote site reliability, while Brazilian utilities accelerate vacuum adoption to preempt carbon-border compliance costs. The technology shift compresses maintenance intervals and eliminates gas-handling infrastructure.
Brazil's ANEEL, Argentina's ENRE, and Colombia's CREG are tightening seismic qualification and environmental compliance standards for medium voltage equipment procurement. These frameworks mandate IEC-certified designs with localized testing protocols. Heavy industrial buyers in petrochemical and steel sectors face compressed supplier qualification timelines as certification requirements expand.
Industrial energy managers are unbundling switchgear procurement from traditional EPC lump-sum contracts. Mining and data center operators now specify equipment directly, forcing distributors to add application engineering and commissioning support. This pattern concentrates in Brazil's Southeast industrial corridor where manufacturing clusters and hyperscale facilities operate parallel procurement functions.
South America Medium Voltage Switchgear Market Segmentation
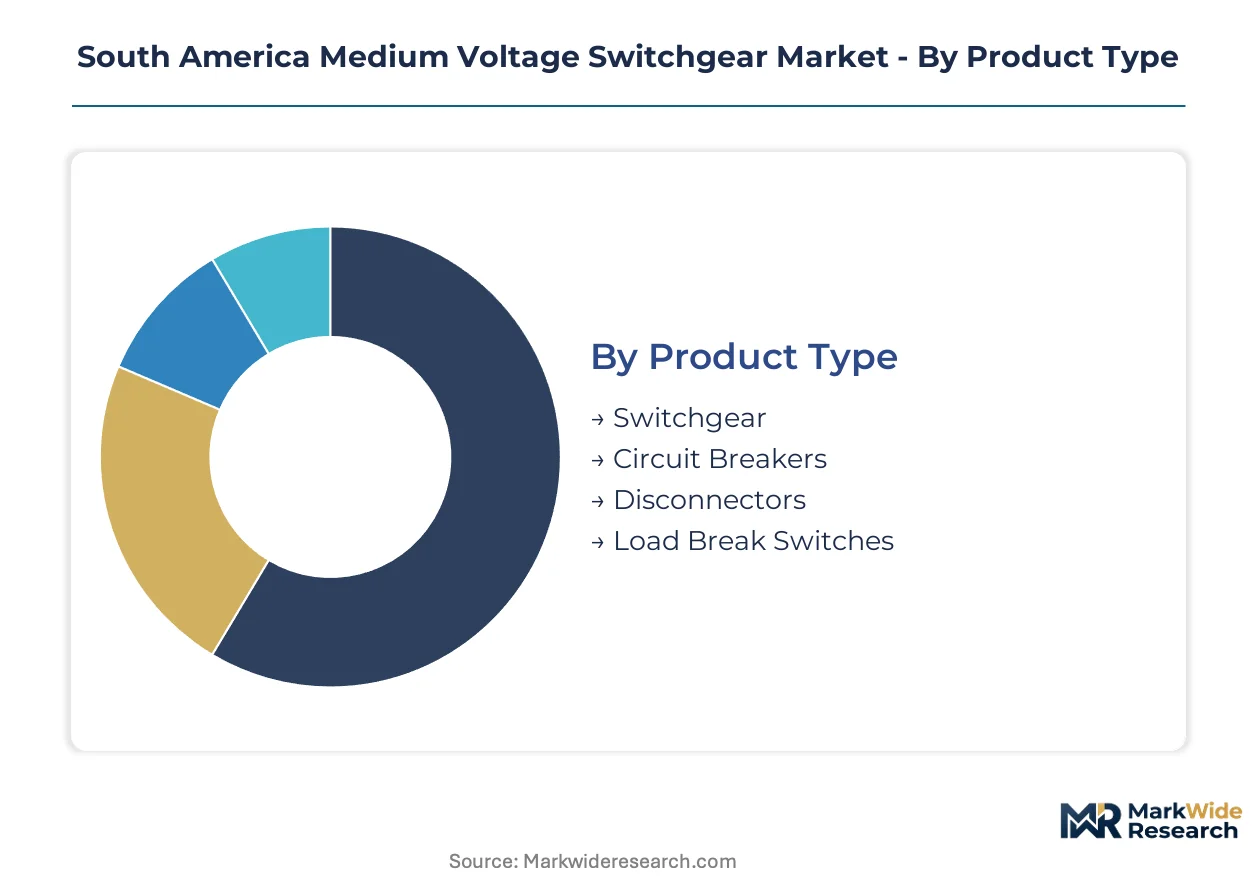
Medium voltage switchgear procurement across South America fragments across four structural dimensions. Each dimension carries distinct regulatory, technical, and commercial imperatives that reshape supplier positioning.
Product Type:
Domestic demand concentrates in utility-specified equipment, while mining and petrochemical exports from Chile and Peru pull specialized interruption technologies.
- Switchgear:Integrated assemblies combining interruption, protection, and metering functions within metal-enclosed housings. Brazilian utilities in the Southeast industrial corridor specify these for substation consolidation projects driven by ANEEL loss-reduction mandates.
- Circuit Breakers:Vacuum and SF6 interruption mechanisms rated for fault current clearing up to 40 kA. Mining operators across Chilean copper belts and Peruvian lithium corridors demand seismic-qualified vacuum variants for remote site reliability.
- Disconnectors:Visible isolation points for maintenance safety and renewable interconnection compliance.
- Load Break Switches:Cost-optimized switching for distribution feeder sectionalization in Argentine and Colombian rural networks.
Circuit breakers command the established base. The steepest expansion runs through disconnectors.
End User:
Customer type determines specification stringency, with industrial buyers unbundling procurement from traditional EPC contracts.
- Utilities:Grid operators across Brazil, Argentina, and Colombia procuring under ANEEL, ENRE, and CREG mandates. These buyers enforce IEC-certified designs with localized testing protocols, creating qualification barriers for non-regional suppliers.
- Industrial:Mining, petrochemical, steel, and data center operators specifying equipment directly. São Paulo and Campinas hyperscale facilities demand arc-flash-rated equipment with remote monitoring capabilities.
- Commercial:Shopping centers, hospitals, and office complexes requiring compact indoor installations.
- Residential:Distribution utilities serving urban densification projects with standardized pad-mounted equipment.
Utilities anchor volume procurement. Industrial buyers are expanding fastest.
Installation Type:
Space constraints and deployment velocity reshape physical configuration preferences across Andean and Mercosur jurisdictions.
- Indoor:Metal-clad and metal-enclosed assemblies for controlled-environment substations. Brazilian urban utilities favor these for theft prevention and environmental protection in dense Southeast corridors.
- Outdoor:Weather-resistant housings for transmission substations and rural distribution points.
- Compact:Reduced-footprint designs for urban land-scarce environments. Chilean and Peruvian mining operators specify these for remote site mobilization where construction windows are compressed.
- Modular:Factory-assembled, transportable substations enabling rapid deployment. Data center construction timelines in Brazil's industrial Southeast drive specification of these plug-and-play configurations.
Outdoor installations retain the largest installed base. Compact configurations are climbing the fastest.
Deployment Model:
Asset lifecycle stage determines supplier engagement model and service contract potential.
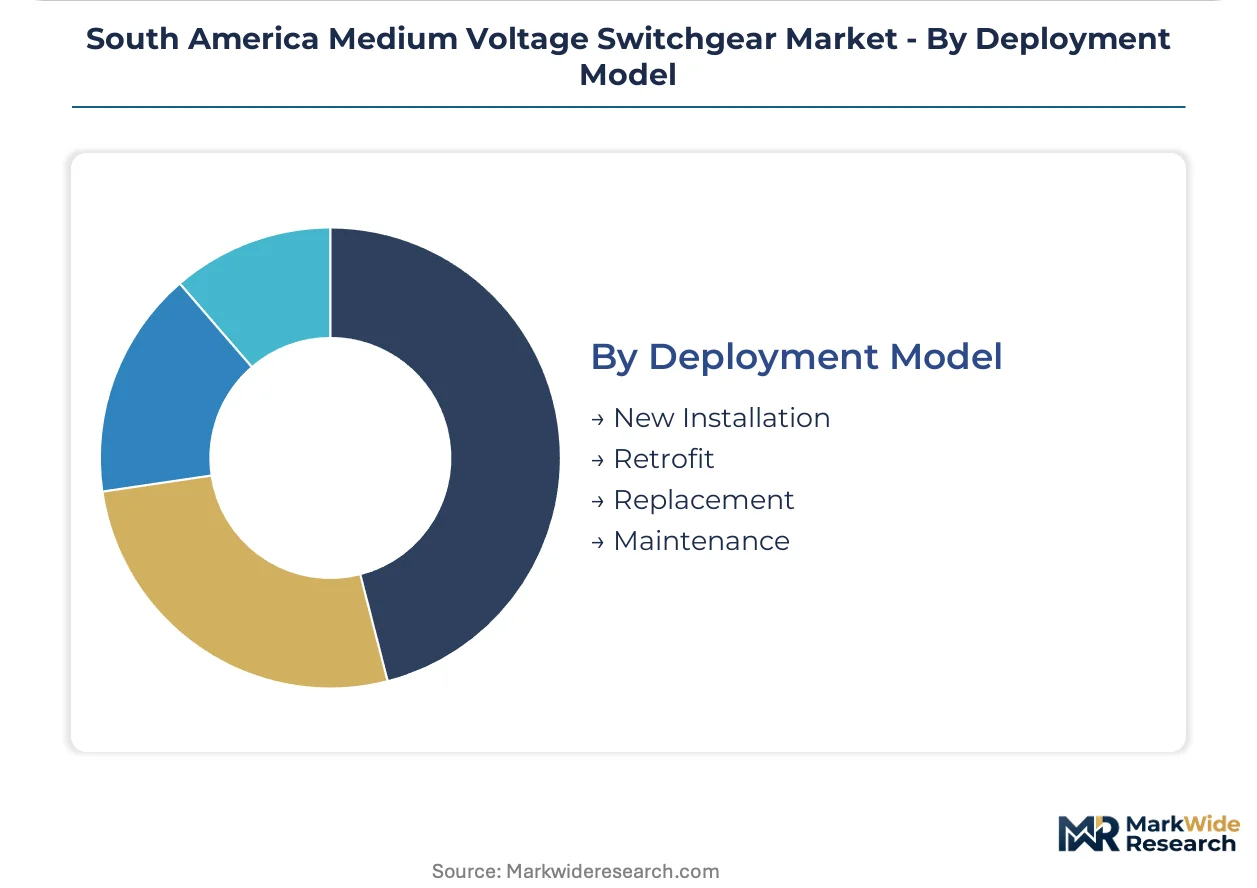
- New Installation:Greenfield substations and industrial facility construction. Colombian wind and solar pipelines in La Guajira and Antioquia require visible isolation disconnectors and specialized protection coordination.
- Retrofit:Intelligent electronic device integration with legacy electromechanical relay infrastructures. Brazilian utilities face commissioning delays and fault-clearance verification bottlenecks in these projects.
- Replacement:End-of-life air-insulated switchgear substitution. ANEEL mandates compress procurement cycles despite 30-40 year asset lifecycles slowing replacement velocity.
- Maintenance:Vacuum interrupter servicing and gas-insulated system commissioning. Specialized field technician scarcity constrains service capacity across the region.
Replacement work commands the established base. Retrofit activity is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chilean mining operators export specialized seismic-qualified switchgear configurations to Peruvian lithium corridors, establishing a cross-Andes equipment trade flow that shapes procurement patterns across the Southern Cone.
Brazil
ANEEL's loss-reduction mandates compress utility procurement cycles across the Southeast industrial corridor. São Paulo and Campinas hyperscale data centers demand arc-flash-rated equipment with remote monitoring capabilities. Manufacturing clusters in Minas Gerais and Rio de Janeiro drive substation consolidation projects.
Chile
Copper and lithium extraction operations in the Atacama and Antofagasta regions require compact modular switchgear for remote site power distribution. The country's national mining regulator enforces seismic qualification standards for electrical infrastructure. Santiago-based engineering firms coordinate procurement for northern mining corridors.
Argentina
ENRE technical standards govern medium voltage equipment procurement for Buenos Aires metropolitan utilities. Vaca Muerta shale development in Neuquén Province pulls specialized gas-insulated configurations for oilfield electrification. Mendoza and Córdoba industrial zones face compressed supplier qualification timelines.
Colombia
Wind and solar project pipelines in La Guajira and Antioquia require visible isolation disconnectors for renewable interconnection compliance. CREG certification frameworks mandate localized testing protocols for imported equipment. Bogotá-based utilities coordinate grid modernization across the Andean highlands.
Peru
Lithium extraction operations in the Puno region and copper mining in Arequipa drive demand for seismic-qualified vacuum interrupter technologies. The country's national energy regulator enforces IEC-certified design standards for medium voltage infrastructure. Lima-based EPCs manage procurement for remote Andean mining sites.
South America Medium Voltage Switchgear Market Competitive Landscape
Player mix skews toward integrated electrical equipment conglomerates with regional manufacturing footprints. Market structure concentrates around three to four dominant suppliers capable of meeting ANEEL, ENRE, and CREG certification requirements simultaneously. Two strategic archetypes define competitive positioning: vertically integrated multinationals with captive component production and regional assembly specialists leveraging licensed technology partnerships. Dominant competitive moves include capacity expansion in Brazilian industrial corridors and strategic partnerships with mining EPCs for remote site commissioning support.
Within the integrated multinational tier, ABB Ltd, Schneider Electric, and Siemens AG exemplify the certification-heavy positioning required for South American utility tenders. ABB Ltd occupies a position anchored in regional manufacturing presence. Schneider Electric represents the localized assembly archetype for industrial applications. Siemens AG sits within the digital integration specialist category. These three companies collectively illustrate how competitive positioning in this market depends on simultaneous compliance with multiple national regulatory frameworks rather than scale or pricing alone.
| Leading Market Players |
|---|
| ABB Ltd |
| Schneider Electric |
| Siemens AG |
| Eaton Corporation |
| Mitsubishi Electric Corporation |
| GE Vernova |
| Hitachi Energy Ltd |
| Toshiba Energy Systems and Solutions Corporation |
| HD Hyundai Electric |
| Others |
Pricing and Supply Chain Analysis
Vacuum interrupter substitution for SF6-insulated equipment is redrawing procurement economics across Brazilian and Chilean utility tenders, compressing technology premiums while shifting supplier qualification costs toward certification-heavy jurisdictions. This material transition simultaneously elevates pricing power for IEC-certified regional assemblers and erodes margins for gas-handling dependent incumbents facing carbon-border compliance headwinds.
Pricing Analysis
SF6-to-vacuum technology-generation pricing gaps stratify procurement tiers across South American utilities, with legacy gas-insulated configurations commanding residual premiums in remote mining corridors where handling infrastructure is already sunk. Price differentiation rests on ANEEL certification grade and seismic qualification tier, with Brazilian industrial buyers showing lowest sensitivity due to arc-flash safety mandates while Argentine rural utilities face acute cost compression. Pricing pressure stems from copper and steel input volatility that complicates long-term tender anchoring.
Supply Chain Analysis
Strategic stockpile preferences dominate raw material procurement for conductive and structural components, with Brazilian OEMs maintaining elevated copper inventories to hedge exchange-rate-driven cost swings. Manufacturing concentration centers on Brazil, Argentina, and Chile, with vacuum interrupter cores and gas-insulation systems drawing from East Asian and European component sources. Single-source vulnerability runs through specialized seismic testing accreditation, while distribution feeds through authorized distributor networks with application engineering bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANEEL's accelerating loss-reduction mandates constitute a regulatory inflection compressing replacement cycles and forcing simultaneous grid modernization across Brazil's Southeast industrial corridor. This creates a high-growth disruption window where technology transition and procurement unbundling reshape competitive access.
For Market Incumbents: Shield installed base relationships through captive certification investment in ANEEL-accredited Brazilian testing facilities, countering emerging Asian suppliers with accelerated localized assembly capacity. Vacuum interrupter backward integration represents the priority defensive lever against margin compression from component import exposure.
For New Entrants and Emerging Players: Predictive maintenance service-layer gaps in remote Chilean and Peruvian mining corridors expose incumbent under-investment in field technician deployment. Target Colombian renewable interconnection projects in La Guajira for visible isolation disconnector specialization, entering through EPC partnership rather than direct utility qualification.
For Investors and Strategic Acquirers: The market sits at a technology-substitution phase that favors vertically integrated specialists with captive IEC certification and regional assembly footprints. Acquisition targets should demonstrate simultaneous ANEEL, ENRE, and CREG qualification with vacuum interrupter sourcing relationships. The signal to watch is SF6 phase-down commitment acceleration across Mercosur jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| ANEEL Certification Investment | Accredited Brazilian testing facilities unlock utility tender participation against non-regional competitors. |
| Vacuum Interrupter Backward Integration | In-house core production hedges import cost volatility and accelerates lead time compression. |
| Mining EPC Partnership | Remote site commissioning support captures Chilean and Peruvian copper-lithium corridor specification. |
| Digital Twin Service Contract | Predictive maintenance bundling extends revenue per unit beyond equipment sale across utility accounts. |
| Colombian Renewable Interconnection Specialization | Visible isolation disconnector focus targets La Guajira wind and Antioquia solar pipeline growth. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, EPC procurement leads, mining maintenance directors, and switchgear OEM technical sales heads; and secondary validation through ANEEL regulatory filings, CREG certification databases, customs import records for electrical equipment, and IEC standard revision documentation. Bottom-up equipment shipment tracking triangulated against top-down utility capital expenditure disclosures.
Across the projection horizon, the analytical framework modeled volume and value outputs across product type, end user category, installation configuration, and deployment model dimensions. CAGRs derived from segment-level growth rate reconciliation with macro grid investment forecasts, incorporating ANEEL loss-reduction target compliance timelines and mining corridor electrification project pipelines as industry-specific inputs.
Underlying assumptions cover regulatory enforcement continuity, raw material price band stability, and certification protocol harmonization, with deviation risk concentrated in carbon-border adjustment implementation timing and seismic standard tightening velocity. Revision becomes warranted when SF6 phase-down commitment schedules accelerate beyond modeled baselines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Busbar Protection Market
Electrical Power Equipment
Power Strip Market
Electrical Power Equipment
Alternator Regulator Market
Electrical Power Equipment
Gas Insulated Switchgears (GIS) Market
Electrical Power Equipment
High Voltage Direct Current (HVDC) Cables Market
Electrical Power Equipment
Asia-Pacific Air-Insulated Switchgear Market
Electrical Power Equipment
Latin America Hazardous Location Motor Starters Market
Electrical Power Equipment
Hollow Core Insulator Market
Electrical Power Equipment
Gas Water Heater Market
Electrical Power Equipment
Fault Circuit Indicator Market
Electrical Power Equipment
Composite Line Post Insulators Market
Electrical Power Equipment
US Air Filter Market
Electrical Power Equipment
Train Contactor Market
Electrical Power Equipment
Protective Relay Market
Electrical Power Equipment
GCC Induction Motor Market
Electrical Power Equipment
Immersion Heater Market