
 Global Low Voltage Electric Drives Market | 2026-2036
Global Low Voltage Electric Drives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Low Voltage Electric Drives Market Foresight
The industrial distributor channel is reconfiguring around digital specification tools and localized technical support. ABB Limited leverages its direct service network to anchor premium retrofit contracts across European process industries. Siemens AG competes through integrated automation platforms that bundle drives with control hardware and edge analytics. Danfoss A/S specializes in HVAC-optimized drive portfolios, sustaining margin pools in building automation where energy codes tighten fastest.
Low voltage electric drives are power electronic devices that convert fixed-frequency AC input to variable-frequency output, typically operating below 690 volts, to enable precise motor speed and torque control in industrial machinery. They incorporate insulated-gate bipolar transistor switching, EMC filtering, and regenerative braking circuits to meet IEC 61800 efficiency classes. AC drives dominate installed base volumes across pump control and conveyor systems applications where variable-speed operation yields the steepest energy savings. Servo drives command premium positioning in textile machinery and precision motion axes where dynamic response and encoder feedback resolution determine system performance. Pulse width modulation technology leads unit shipments while direct torque control gains share in high-inertia material handling where torque accuracy at low speeds reduces mechanical wear.
The US Department of Energy enforces minimum efficiency standards through NHTSA-aligned industrial equipment rules while the EU F-Gas Regulation and Ecodesign Directive jointly pressure motor-drive system replacements. China's MIIT implements GB 18613 efficiency tiers that restrict sales of IE2-equivalent drive-motor combinations below specified power thresholds. Stakeholders must monitor divergence between regional efficiency test methods and certificate reciprocity agreements that fragment product platform strategies.
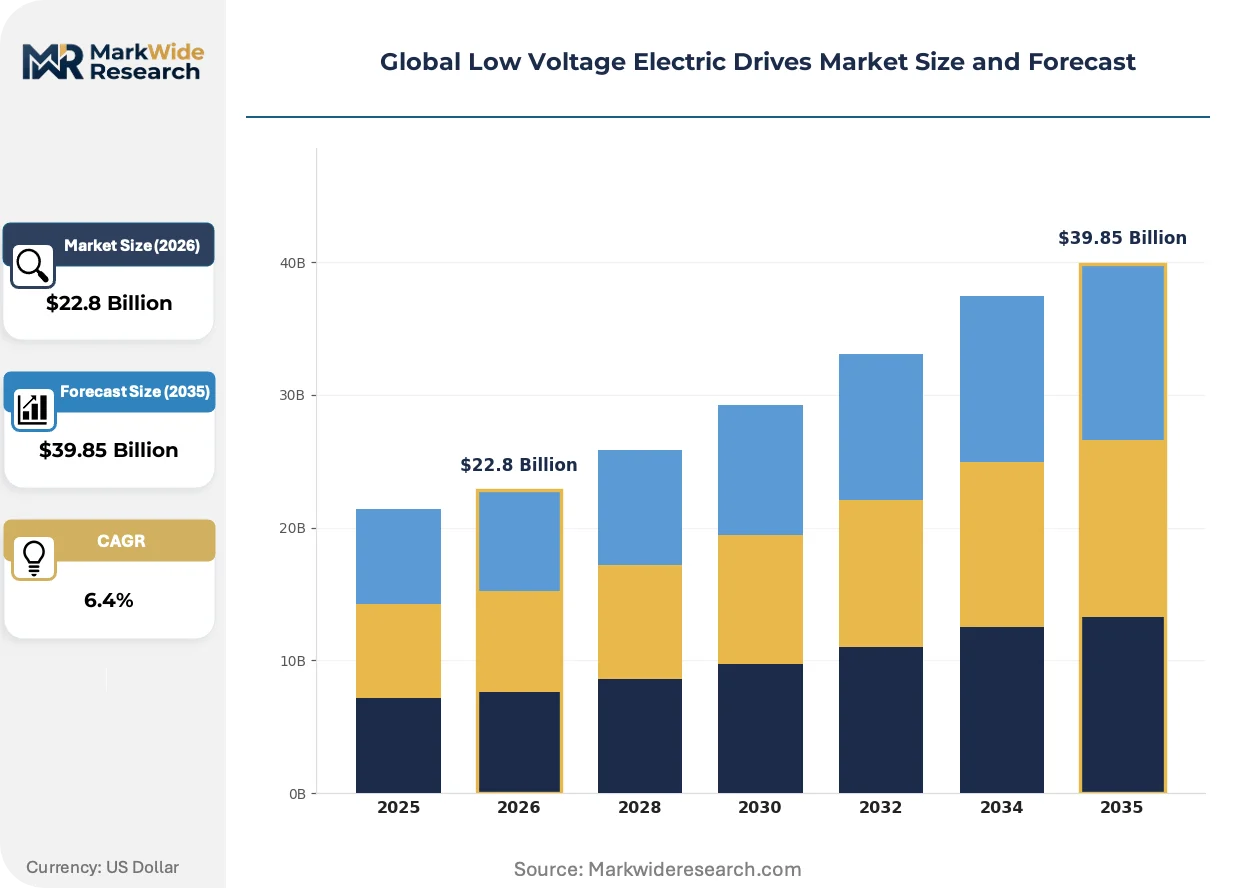
Market Dynamics
IE4 and IE5 efficiency mandates from the EU Ecodesign Directive are forcing industrial operators to scrap legacy motor-drive combinations ahead of scheduled replacement cycles, compressing demand timelines and reshaping procurement patterns across process industries.
Growth Catalysts
- EU Ecodesign Directive:Mandatory IE4/IE5 efficiency tiers accelerate retrofit demand in German and Italian process manufacturing, compelling operators to replace drive-motor systems that fail new minimum performance standards.
- Water treatment infrastructure:Municipal and industrial water facilities deploy variable-frequency drives for pump optimization, cutting energy consumption in aeration and filtration processes where motors run continuously.
- China MIIT GB 18613 standards:Efficiency tier restrictions below specified power thresholds block sales of IE2-equivalent combinations, redirecting procurement toward premium drive platforms in domestic manufacturing.
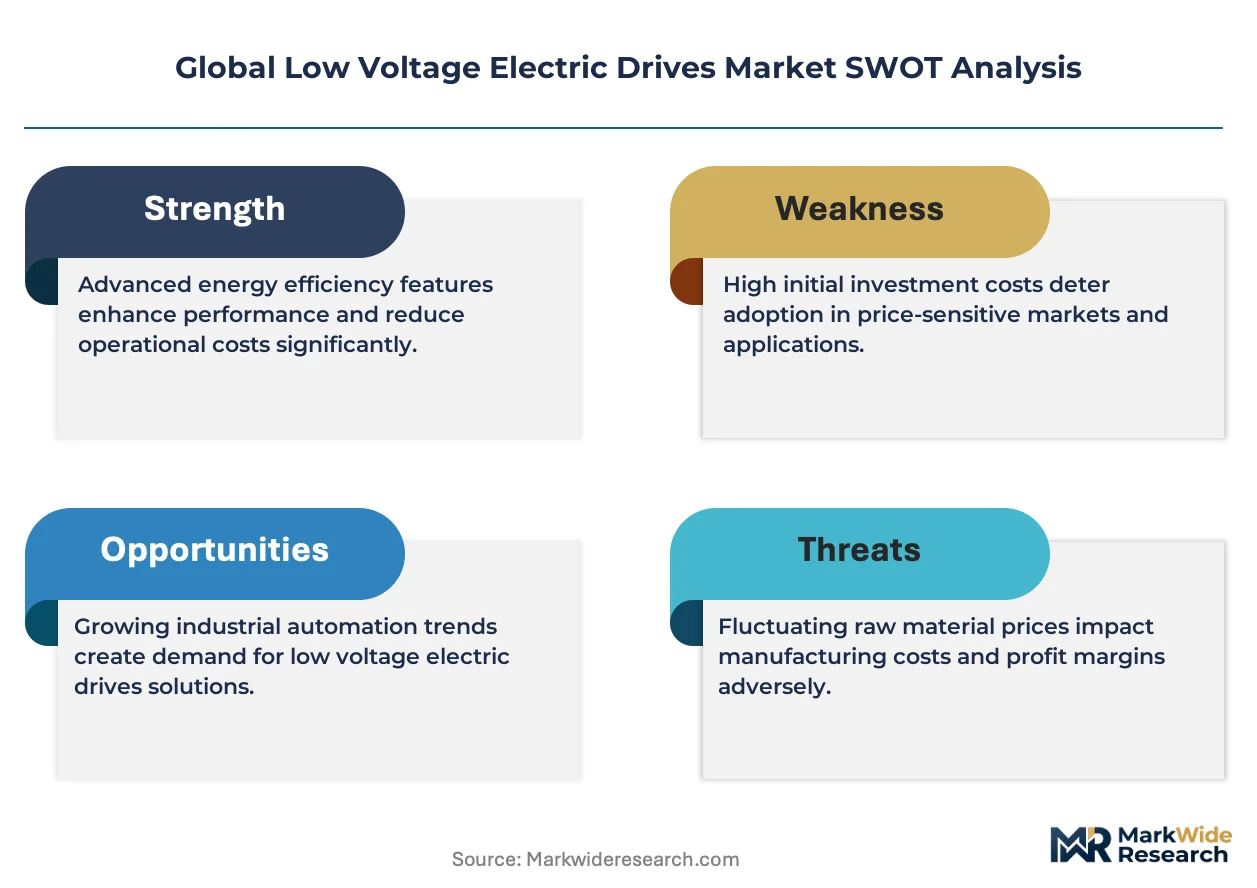
Market Restraints
- IGBT and silicon carbide supply concentration:Power semiconductor fabrication concentrates in Taiwan and South Korea, exposing drive manufacturers to foundry allocation volatility and extended lead times.
- Copper and rare earth magnet costs:Permanent magnet motors paired with advanced drives face input price swings from Chinese export quota policies on neodymium and dysprosium.
- Certificate reciprocity fragmentation:Divergent efficiency test methods between IEC, NEMA, and GB standards force redundant certification cycles that delay product launches in multi-regional portfolios.
Strategic Opportunities
- India industrial corridor expansion:PLI scheme incentives for manufacturing automation create first-mover positioning for drive suppliers in Gujarat and Tamil Nadu automotive component clusters.
- Edge analytics convergence:Integration of drive-mounted vibration sensors with predictive maintenance platforms opens recurring software revenue streams in pulp and paper applications.
- HVAC energy code tightening:Building automation retrofits in California and New York mandate variable-speed fan and pump control, expanding addressable market for compact drive form factors.
Industry Challenges
- Power electronics engineering scarcity:Shortage of specialists in electromagnetic compatibility design and thermal management slows R&D cycles and extends time-to-certification for new drive platforms.
- Legacy system integration complexity:Retrofit projects in established process plants require protocol bridging between modern fieldbus architectures and decades-old DCS installations, inflating commissioning costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Low Voltage Electric Drives Market |
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $39.85 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Drives, DC Drives, Servo Drives, Vector Drives Technology: Pulse Width Modulation, Direct Torque Control, Sensorless Control, Field Oriented Control Application: Pump Control, Conveyor Systems, HVAC Systems, Textile Machinery End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | Rockwell Automation, Emerson Electric, ABB Limited, General Electric, Mitsubishi Electric, Siemens AG, Danfoss A/S, Yaskawa Electric, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Low Voltage Electric Drives Market Shifts & Advancements
Digital twin architectures are virtualizing drive commissioning and performance optimization, collapsing traditional physical prototyping cycles while enabling remote diagnostics that reshape service delivery economics.
Digital twin software for low voltage drives is virtualizing motor-load matching and harmonic analysis before physical installation. Mining and metals operators in Western Australia deploy these tools to pre-validate high-inertia material handling configurations. The technology is virtualizing field service requirements, compressing commissioning timelines and shifting technical support toward remote analytics centers.
The EU F-Gas Regulation now restricts fluorinated greenhouse gases in cooling systems, indirectly pressuring drive-integrated thermal management designs. Industrial refrigeration OEMs must redesign heat dissipation architectures to comply with phasedown schedules. German and French cold chain operators accelerate procurement of drives with liquid-cooled or natural convection alternatives to avoid refrigerant-dependent cooling circuits.
Specification authority is migrating from maintenance departments to centralized engineering procurement functions with enterprise sustainability mandates. Large manufacturing conglomerates in the United States now bundle drive purchases under capital efficiency programs with carbon accounting requirements. This concentration of buying power favors suppliers offering lifecycle energy data and verified efficiency certificates over distributors competing on availability alone.
Global Low Voltage Electric Drives Market Segmentation
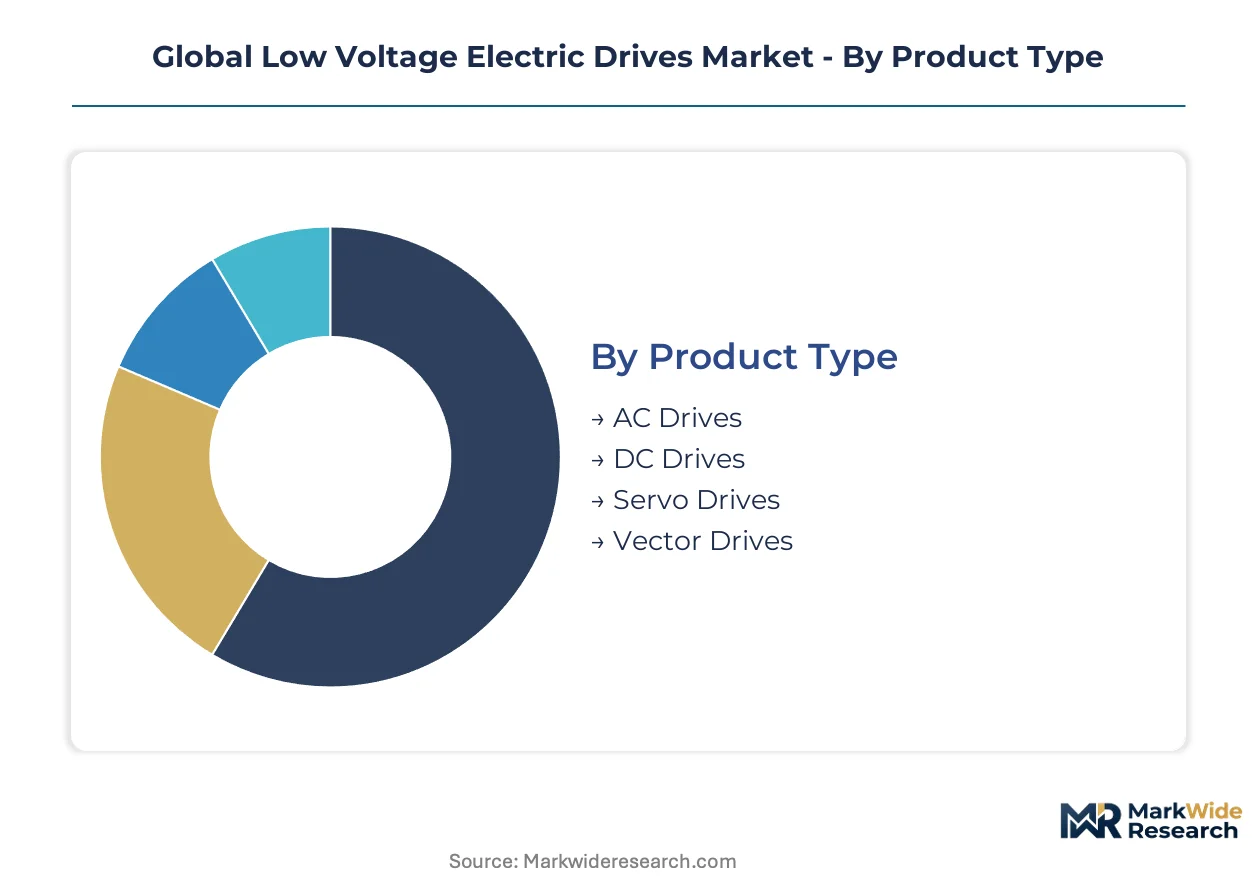
Segmentation in low voltage electric drives reveals divergent procurement rhythms across industrial verticals. OEMs refresh drive platforms on 5-7 year product cycles while aftermarket replacements compress to 2-3 year intervals based on failure modes and efficiency mandate deadlines.
Product Type:
AC drives turn over fastest in pump and fan retrofits where efficiency payback justifies accelerated replacement, while servo drives persist longest in precision manufacturing cells where integration complexity extends service life.
- AC Drives:These units dominate pump control and conveyor installations through insulated-gate bipolar transistor switching architectures. Municipal water treatment facilities in Germany and China specify these drives for continuous-duty aeration pumps where variable-frequency operation yields energy recovery. IEC 61800 efficiency classes and EU Ecodesign Directive mandates are compressing replacement timelines across European process industries.
- Servo Drives:High-dynamic-response systems with encoder feedback resolution determine performance in textile machinery and precision motion axes. Machine tool builders in Japan and automotive component manufacturers in Germany anchor demand for these premium-positioned units where positioning accuracy reduces mechanical wear.
- DC Drives:Legacy infrastructure in metals processing and crane applications sustains residual demand despite technology displacement.
- Vector Drives:General-purpose industrial machinery in emerging manufacturing clusters absorbs volume for mid-tier torque control applications.
AC drives anchor the volume base while servo drives gain share at the steepest rate.
Technology:
Cost tiers separate mature pulse width modulation platforms from premium direct torque control implementations where torque accuracy commands price premiums.
- Pulse Width Modulation:The dominant switching methodology across installed base volumes uses carrier-frequency modulation to synthesize variable-frequency output. Standard industrial pumps and conveyors in the United States and China deploy these cost-optimized platforms where harmonic performance requirements remain moderate.
- Direct Torque Control:High-inertia material handling in mining operations across Western Australia and steel mills in India leverages this technology for torque accuracy at low speeds. The elimination of encoder dependencies in certain configurations reduces commissioning complexity while maintaining dynamic response.
- Sensorless Control:HVAC retrofits in commercial buildings favor these reduced-wiring architectures for fan and pump duty.
- Field Oriented Control:Precision servo applications in robotics and semiconductor manufacturing equipment require this high-performance vector control methodology.
Pulse width modulation commands the installed base while direct torque control climbs the fastest among new specifications.
Application:
Volume concentration varies sharply by end-use energy intensity and regulatory exposure, with water infrastructure and building automation showing divergent procurement authority structures.
- Pump Control:Continuous-duty municipal water and wastewater operations represent the largest addressable application segment. Variable-frequency drives in aeration and filtration processes across treatment facilities in the United States, Germany, and China cut energy consumption where motors run 24-hour cycles. EU Ecodesign Directive efficiency tiers and China MIIT GB 18613 standards redirect procurement toward premium platforms.
- HVAC Systems:Building automation retrofits in California and New York energy code jurisdictions mandate variable-speed fan and pump control. Commercial real estate operators bundle drive purchases under sustainability-linked financing where verified efficiency certificates determine supplier selection.
- Conveyor Systems:Logistics and distribution centers absorb standard AC drive volumes for material handling automation.
- Textile Machinery:Precision winding and weaving operations in India and Vietnam sustain servo drive demand for tension control.
Pump control anchors the volume base while HVAC systems expand most quickly under building energy code tightening.
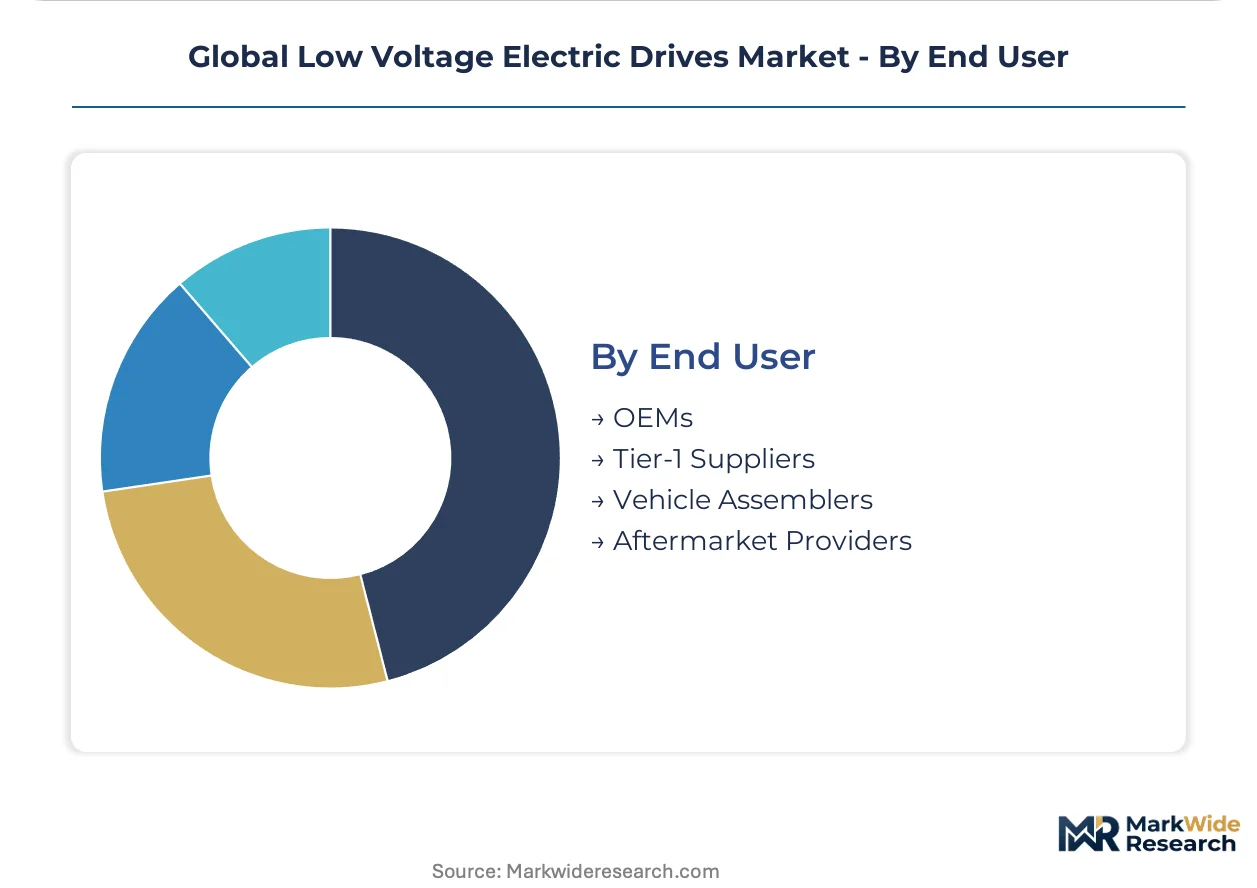
End User:
Customer type determines specification authority concentration, with centralized engineering procurement functions displacing decentralized maintenance purchasing in large manufacturing conglomerates.
- OEMs:Original equipment manufacturers in industrial machinery and automation systems integrate drives at the design stage. German and Japanese machine builders specify drive-motor combinations during R&D cycles, locking in component relationships across 10-15 year product lifecycles. Lifecycle energy data and verified efficiency certificates increasingly determine supplier selection over unit cost alone.
- Aftermarket Providers:Service organizations and independent distributors capture replacement demand from legacy system failures and efficiency mandate accelerations. The EU Ecodesign Directive IE4/IE5 deadlines compress demand timelines as operators scrap non-compliant drive-motor combinations ahead of scheduled replacement cycles.
- Tier-1 Suppliers:Automotive component manufacturers in Gujarat and Tamil Nadu industrial corridors absorb drives for production line automation under India PLI scheme incentives.
- Vehicle Assemblers:Final assembly plant automation sustains demand for coordinated multi-axis drive systems in paint and body shops.
OEMs anchor the volume base while aftermarket providers gain share at the steepest rate under regulatory-driven replacement acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Energy efficiency mandates and industrial automation incentives are reshaping procurement patterns across major manufacturing economies. National regulators enforce divergent efficiency tiers that fragment product strategies while concentrated industrial clusters absorb premium drive platforms.
Germany
Process manufacturing and automotive component production anchor demand for IE4/IE5-compliant drive systems. The EU Ecodesign Directive accelerates replacement cycles in chemical and food processing plants. The Ruhr industrial corridor and Bavarian manufacturing zones concentrate retrofit activity where operators scrap legacy motor-drive combinations ahead of compliance deadlines.
China
Water treatment infrastructure expansion and domestic manufacturing automation sustain volume procurement of variable-frequency drives. MIIT's GB 18613 efficiency tier restrictions block sales of IE2-equivalent combinations below specified power thresholds. The Yangtze River Delta and Pearl River Delta industrial clusters redirect procurement toward premium drive platforms under dual carbon policy enforcement.
United States
Municipal water facilities and building automation retrofits drive specification of pump-optimized and HVAC-focused drive portfolios. The Department of Energy enforces minimum efficiency standards through NHTSA-aligned industrial equipment rules. California and New York energy code jurisdictions mandate variable-speed fan and pump control in commercial real estate sustainability-linked financing programs.
India
Automotive component manufacturing and textile machinery sustain demand for servo and AC drive platforms. PLI scheme incentives for manufacturing automation create procurement concentration in Gujarat and Tamil Nadu industrial corridors. The Delhi-Mumbai Industrial Corridor absorbs coordinated multi-axis drive systems for production line automation under scheme eligibility requirements.
Japan
Precision machinery and semiconductor manufacturing equipment sustain premium positioning for high-dynamic-response servo drives. METI efficiency standards and JIS certification requirements shape product platform development. The Chubu region around Nagoya and the Kansai manufacturing belt concentrate machine tool builder demand where positioning accuracy reduces mechanical wear.
Global Low Voltage Electric Drives Market Competitive Landscape
On the supply side, the industry is consolidating around integrated automation platforms and specialized vertical portfolios. A tiered structure separates full-range electrical conglomerates from focused drive specialists and regional component fabricators. Strategic archetypes include bundled automation providers, HVAC-optimized portfolio specialists, and precision motion control developers. Competitive moves concentrate on geographic expansion through localized technical support networks and portfolio diversification into edge analytics and predictive maintenance software.
Within the bundled automation tier, ABB Limited and Siemens AG exemplify integrated platform strategies that combine drives with control hardware and digital services. Danfoss A/S occupies a specialist position in building automation applications where energy code tightening sustains margin pools. Among precision motion developers, Yaskawa Electric and Mitsubishi Electric represent Japanese-origin archetypes emphasizing encoder feedback resolution and dynamic response in textile and machine tool applications. Rockwell Automation anchors North American process industry positioning through direct service network density.
| Leading Market Players |
|---|
| Rockwell Automation |
| Emerson Electric |
| ABB Limited |
| General Electric |
| Mitsubishi Electric |
| Siemens AG |
| Danfoss A/S |
| Yaskawa Electric |
| Schneider Electric |
| Others |
Supply & Pricing Matrix
Taiwanese foundry capacity dynamics in Hsinchu and Tainan Science Parks directly determine pricing power for insulated-gate bipolar transistor and silicon carbide modules that anchor drive manufacturing economics. The concentration of power semiconductor fabrication in these hubs creates allocation volatility that propagates through tiered supplier contracts into end-equipment margins.
Pricing Analysis
Certification level creates the primary spread between IE4-compliant and IE5-premium drive platforms, with EU Ecodesign Directive enforcement widening the gap. Pricing stratifies across premium, standard, and economy tiers based on efficiency class and integrated thermal management architecture. Cost compression in the standard tier is intensifying because Chinese domestic manufacturers are scaling GB 18613-compliant production. OEM procurement teams show the least price sensitivity due to lifecycle energy accounting mandates, while independent aftermarket distributors face the highest margin pressure.
Supply Chain Analysis
TSMC and Samsung Foundry hold dominant capacity for IGBT and silicon carbide wafer production that feeds drive power module assembly. Manufacturing concentrates in Taiwan, South Korea, and Germany for precision control electronics. The chain draws from copper winding wire, rare earth permanent magnets, and EMC filtering components. Single-source vulnerability in Taiwanese foundry allocation poses the dominant structural risk. Distribution runs through industrial distributor networks with localized technical support requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global Low Voltage Electric Drives Market expansion sits in early-cycle acceleration as IE4/IE5 efficiency mandates force premature replacement of installed base systems ahead of scheduled end-of-life. Regulatory deadlines across the EU, China, and select US jurisdictions compress demand timelines and expand addressable retrofit volume.
For Market Incumbents: Entrench service network density in German process corridors and Chinese Yangtze River Delta clusters where retrofit timelines are most compressed. Prioritize backward integration into power module supply through captive sourcing agreements with Taiwanese foundries to offset allocation volatility. Defend against emerging Chinese domestic manufacturers by accelerating IEC 61800-9 efficiency certification cycles that newcomers cannot match. For New Entrants and Emerging Players: Build out HVAC-optimized drive portfolios targeting California and New York building automation retrofits where energy code tightening outpaces incumbent response capacity. The most penetrable white space sits in compact form-factor pump drives for Indian municipal water treatment under PLI scheme automation incentives. Lead with edge analytics bundling that established players have not yet productized for mid-market commercial real estate operators. For Investors and Strategic Acquirers: Long-term, this sits as an efficiency-regulation compounding play because mandatory replacement cycles recur on tightening intervals with each efficiency tier revision. Acquisition targets should emphasize drive-integrated predictive maintenance software developers and regional service networks with dense technician footprints in mandated retrofit corridors. Watch for MIIT announcements on GB 18613 tier advancement as the signal for next replacement wave timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Semiconductors | Captive IGBT sourcing from Taiwanese foundries insulates margin against allocation volatility. |
| Edge Analytics Platform Integration | Drive-mounted vibration sensors with predictive maintenance software open recurring revenue in pulp and paper. |
| HVAC-Optimized Portfolio Expansion | Compact form factors for California and New York energy code retrofits capture building automation growth. |
| Regional Service Network Density Buildout | Localized technical support in Gujarat and Tamil Nadu clusters secures India PLI scheme positioning. |
| IE5 Efficiency Certification Acceleration | Early IEC 61800-9 compliance creates differentiation against Chinese domestic manufacturers. |
Research Methodology
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews across these stakeholder roles with secondary validation from customs trade data, SEC filings of listed drive manufacturers, IEC certification databases, and EU Ecodesign Directive implementation reports. Bottom-up unit demand modeling triangulated against top-down manufacturing value chain estimates.
Scenario-bracketing framed the analytical approach across the projection horizon, with efficiency mandate acceleration and foundry capacity constraints as primary uncertainty bands. Segmentation dimensions modeled include product type, technology architecture, application vertical, end-user category, and regional regulatory cluster. CAGRs derived from installed base turnover analysis and replacement cycle compression under mandate deadlines. Industry-specific inputs incorporated MIIT GB 18613 enforcement timelines and EU F-Gas Regulation thermal management redesign requirements.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic manufacturers or foundry allocation disruptions would shift outcomes. Quarterly review of IEC certification pipeline data, foundry utilization disclosures, and regulatory deadline announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Taiwan Electric Power Equipment Market
Electrical Power Equipment
Power Strip Market
Electrical Power Equipment
Offshore Cables Market
Electrical Power Equipment
Load Bank Market
Electrical Power Equipment
Power Line Filters Market
Electrical Power Equipment
Global Explosion-Proof Electric Motors and Actuators Market
Electrical Power Equipment
Fuse Link Market
Electrical Power Equipment
Global Electrical SCADA Market
Electrical Power Equipment
ESE Lightning Rod Market
Electrical Power Equipment
Europe Electric Radiators Market
Electrical Power Equipment
Alternating Current (AC) Electric Drives Market
Electrical Power Equipment
Europe Gas Insulated Switchgear Market
Electrical Power Equipment
Instrument Transformers Market
Electrical Power Equipment
Global Surge Arrester Market
Electrical Power Equipment
Europe Alternating Current (AC) Drive Market
Electrical Power Equipment
Utility Poles Market