
 France Power EPC Market | 2026-2036
France Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
France Power EPC Market Foresight
Utility-scale solar deployment is decoupling from traditional baseload contracting models as grid operators prioritize intermittency management. EDF Renewables leverages its reactor maintenance heritage to anchor nuclear EPC restart programs across Flamanville and Penly sites. ENGIE Solutions competes aggressively in district heating-linked cogeneration, while VINCI Energies controls the high-voltage interconnection segment through its Omexom subsidiary.
France Power EPC encompasses the integrated engineering, procurement, and construction of electricity generation facilities, requiring compliance with RCC-M nuclear pressure equipment codes and IEC 61400 wind turbine standards for grid connection certification. Turnkey contracts now dominate offshore wind given the complexity of foundation installation and array cable logistics in the Channel and Atlantic lease zones. Solar EPC under 100 MW capacity sustains margin pools for independent operators, whereas nuclear projects above 1000 MW concentrate engineering resources among a closed consortium of qualified suppliers.
ANSM oversees nuclear safety compliance for pressure equipment manufacturing, while the French Energy Regulatory Commission shapes grid access tariffs that determine project finance viability for independent developers. The EU Green Deal's REPowerEU acceleration targets and France's national low-carbon strategy are tightening domestic content requirements for renewable EPC contractors. Stakeholders must monitor the convergence of nuclear restart timelines with offshore wind auction schedules, as engineering labor scarcity between these programs will dictate contractor availability and pricing dynamics.
Market Dynamics
France's power EPC sector faces acute engineering labor scarcity as EDF's nuclear restart timeline converges with RTE's grid modernization and offshore wind auction schedules, forcing contractors to bid against each other for finite welding, civil works, and high-voltage expertise.
Growth Catalysts
- EU Green Deal acceleration:REPowerEU targets tighten domestic content requirements, mandating French-sourced steel and cabling for renewable EPC contractors bidding on state-backed projects.
- Grand Est offshore wind clustering:Lease zone overlaps with nuclear refurbishment sites create shared logistics infrastructure, reducing mobilization costs for foundation and inter-array cable installation.
- RCC-M code harmonization:Streamlined pressure equipment certification paths for nuclear-qualified suppliers lower barriers to entry for civil nuclear EPC work at Flamanville and Penly.
Market Restraints
- Specialized welding consumables:Inconel and stainless steel electrode supply concentrates among German and Japanese producers, exposing EPC margins to nickel price volatility and maritime freight premiums.
- Foundation installation bottleneck:Heavy-lift vessel availability for monopile and jacket installations in the Channel lease zones rests with a North Sea-based fleet of under ten operators.
- ANSM inspection backlogs:Extended lead times for nuclear pressure equipment manufacturing audits delay reactor component handover, compressing EPC schedule float.
Strategic Opportunities
- Hauts-de-France hydrogen integration:Electrolyzer-linked solar and offshore wind EPC bundles attract offtake from Dunkirk industrial cluster decarbonization mandates.
- District heating cogeneration:Urban heating network retrofits in Lyon and Paris create bundled thermal-electric EPC contracts with 20-year heat purchase agreements.
- High-voltage digital substations:RTE's smart grid rollout demands integrated protection and control systems, opening margins for EPC firms with IEC 61850 commissioning expertise.
Industry Challenges
- Pressure vessel welder certification:ANSM-qualified welding procedure specifications require 18-month apprenticeship cycles, outstripping training pipeline output for nuclear restart demand.
- Array cable burial depth variance:Atlantic lease zone seabed geology demands project-specific ploughing and jetting specifications, fragmenting installation equipment deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Power EPC Market |
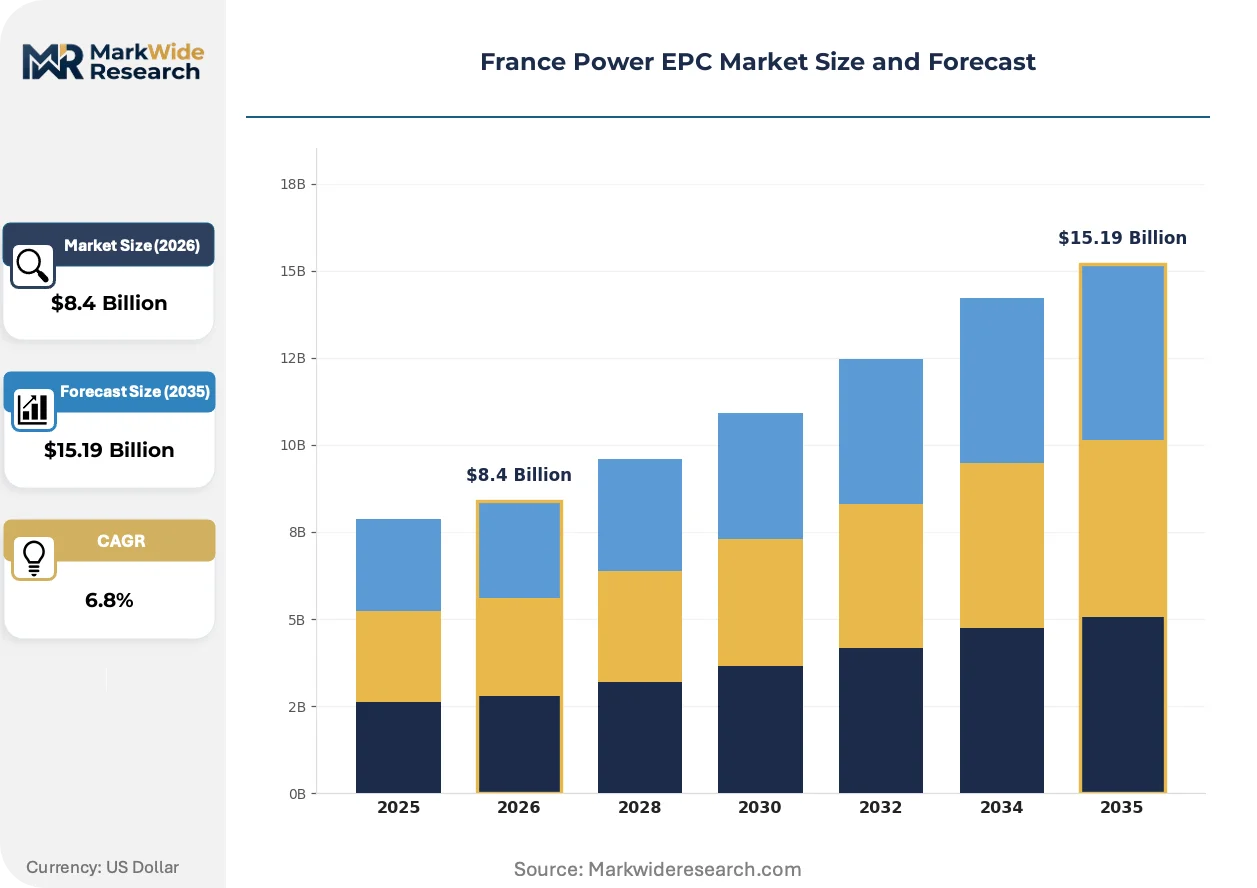
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Thermal, Hydro, Solar, Wind, Nuclear Contract Type: Engineering, Procurement, Construction, Design & Build, Turnkey Power Capacity: Below 100 MW, 100–500 MW, 501–1000 MW, Above 1000 MW Client Type: Utility Companies, Independent Operators, Transmission Firms, Local Distributors |
| Companies Covered | ENGIE Solutions, EDF Renewables, TotalEnergies Renewables France, Eiffage Énergie Systèmes, Bouygues Energies & Services, VINCI Energies, Schneider Electric, Vestas Wind Systems, Siemens Gamesa Renewable Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Power EPC Market Shifts & Advancements
Digital engineering platforms and modular construction methods are compressing EPC delivery timelines while RTE's grid access tariff reforms reshape project finance structures for independent developers.
Floating offshore wind foundation technology is expanding into the Mediterranean and Atlantic deep-water lease zones beyond fixed-bottom depth limits. EDF Renewables and independent developers are piloting semi-submersible platforms at three pre-commercial sites off Brittany. This technology is expanding into supply chains previously dedicated to oil and gas subsea fabrication, repurposing Saint-Nazaire and Marseille yard capacity.
France's Multiannual Energy Programme (PPE) revision tightens renewable capacity auction timelines and nuclear fleet availability requirements. Industrial consequence includes compressed EPC tendering windows and parallel-track permitting for co-located generation assets. Grid-scale battery storage EPC contracts face the strictest delivery penalties under this framework, with RTE imposing non-availability charges on delayed commissioning.
Turnkey contracting models now dominate offshore wind procurement, displacing multi-contract structures that separated foundation, turbine, and interconnection packages. Developers in the Channel lease zones favor single-point liability for foundation scour protection and array cable burial scope. This concentration is most visible in Normandy and Brittany, where marine warranty surveyor coordination costs previously fragmented project budgets.
France Power EPC Market Segmentation
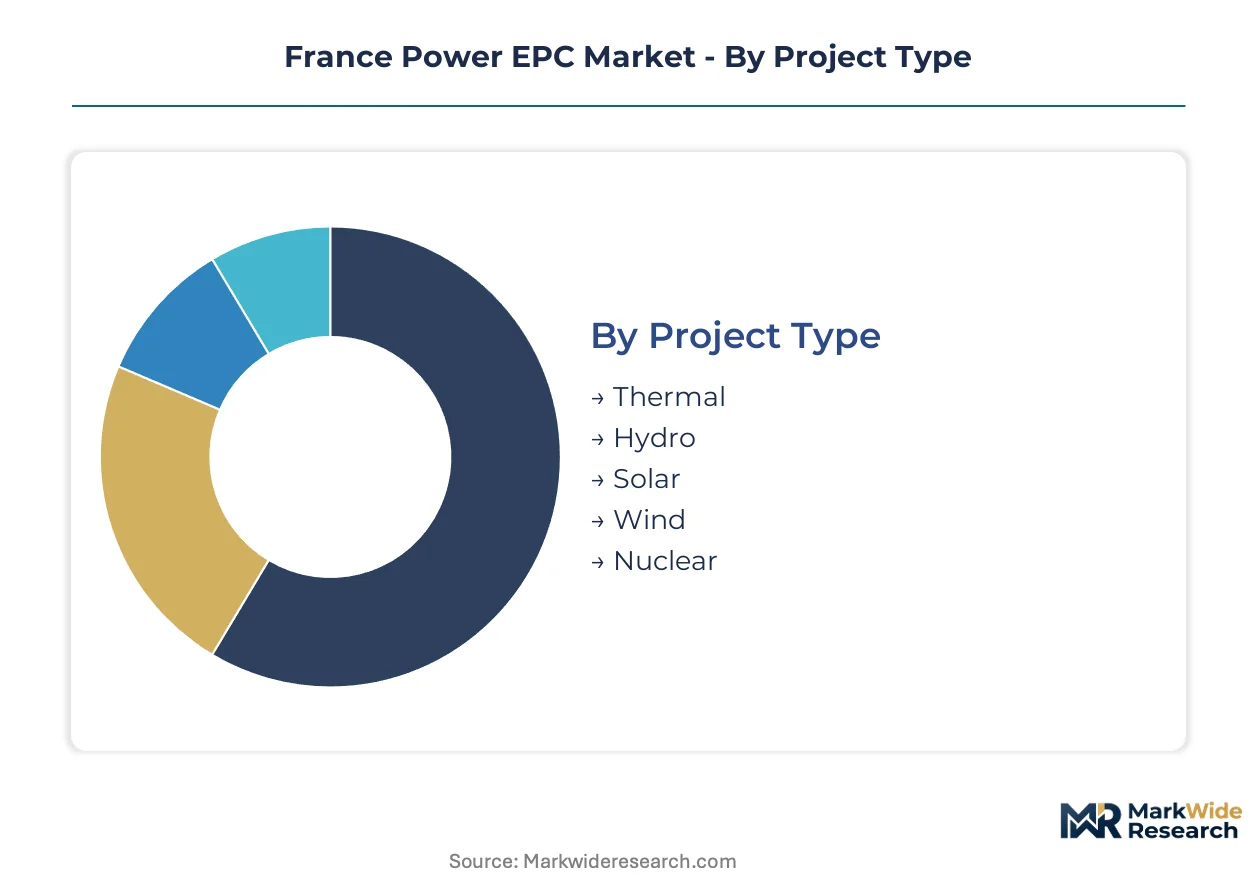
Segmentation in the France Power EPC market reveals how contractor capabilities, regulatory requirements, and financing structures align with distinct project archetypes. Each dimension shapes procurement strategies, risk allocation, and the competitive field for engineering resources.
Project Type:
Technology specifications dictate engineering codes, supply chain configurations, and the qualified contractor pool available for execution.
- Thermal:Combined-cycle gas turbine and biomass installations require compliance with EU Industrial Emissions Directive thresholds. Demand concentrates in Hauts-de-France for district heating integration, where Dunkirk industrial cluster decarbonization mandates sustain cogeneration project pipelines.
- Hydro:Run-of-river and pumped-storage retrofits demand civil works expertise for dam safety upgrades under France's water police authority oversight. Alpine and Pyrenean refurbishment clusters in Auvergne-Rhône-Alpes and Occitanie attract specialized tunnelling contractors.
- Solar:Utility-scale photovoltaic arrays dominate Grand Est deployment schedules.
- Wind:Fixed-bottom offshore foundations in Channel lease zones require marine warranty coordination.
- Nuclear:RCC-M pressure equipment certification limits qualified EPC participation to pre-approved supplier consortia.
Nuclear leads on scale through EDF's restart program; offshore wind leads on momentum through RTE's grid access tariff reforms.
Contract Type:
Risk transfer mechanisms determine margin structures, bonding requirements, and the scope of contractor liability for schedule and performance guarantees.
- Engineering:Front-end design services cover feasibility studies, basic engineering packages, and permitting support for complex offshore wind and nuclear projects. Grand Est developers commission these separately when foundation geology or grid connection uncertainty requires phased commitment.
- Procurement:Long-lead equipment sourcing concentrates on wind turbine generators, nuclear steam supply system components, and high-voltage transformers. ANSM oversight of pressure equipment manufacturing audits extends procurement cycles for nuclear-qualified suppliers.
- Construction:Civil works and electromechanical installation contracts sustain regional contractor networks in Normandy and Brittany.
- Design & Build:Single-point responsibility for solar and onshore wind projects under 100 MW attracts independent developers seeking compressed tendering timelines.
- Turnkey:Full EPC wrap contracts now dominate offshore wind procurement in Channel lease zones, consolidating foundation, turbine, and interconnection scope under unified liability.
Turnkey contracts are gaining share fastest in offshore wind; Engineering services retain the broadest addressable base across all project scales.
Power Capacity:
Project scale thresholds separate competitive dynamics, with distinct contractor tiers, financing structures, and regulatory pathways governing each bracket.
- Below 100 MW:Distributed solar and onshore wind projects sustain independent EPC operators with standardized module and turbine supply chains. Solar EPC in this bracket maintains margin pools for regional contractors serving local distributor offtake agreements.
- 100–500 MW:Utility-scale solar and onshore wind clusters attract national contractors with grid connection expertise. Grand Est and Nouvelle-Aquitaine host the densest development pipelines in this range, driven by CRE auction schedules.
- 501–1000 MW:Large offshore wind arrays and combined-cycle thermal plants demand consortia with marine installation or heavy industrial credentials. Foundation installation bottlenecks concentrate risk in this bracket.
- Above 1000 MW:Nuclear new-build and restart programs, plus the largest offshore wind zones, concentrate engineering resources among closed supplier groups. EDF's Flamanville and Penly timelines dominate contractor availability.
Above 1000 MW projects command the deepest engineering resources; Below 100 MW projects are expanding most quickly through standardized procurement.
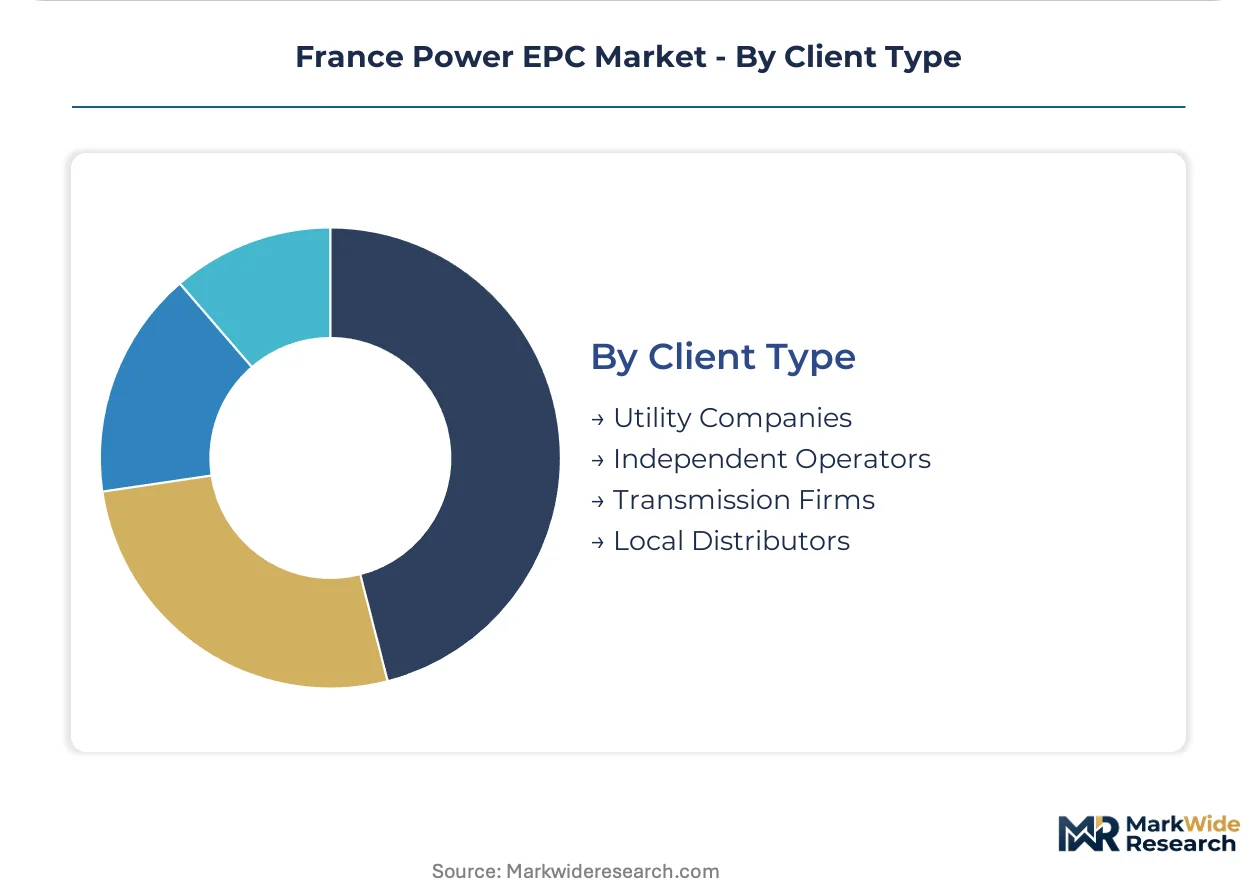
Client Type:
Counterparty credit quality and offtake structure determine project finance viability, tariff negotiations, and EPC payment terms.
- Utility Companies:EDF and ENGIE anchor nuclear restart and large-scale renewable programs with balance-sheet financing. Their procurement leverage extracts performance guarantees and extended defect liability periods from EPC contractors.
- Independent Operators:Project finance-dependent developers rely on CRE tariff awards and power purchase agreements to secure construction debt. Grid access queue position under RTE's connection procedures determines project sequencing.
- Transmission Firms:RTE's grid modernization and interconnection investments create high-voltage substation and submarine cable EPC demand.
- Local Distributors:Enedis-linked distribution network upgrades and urban heating retrofits sustain mid-scale thermal and solar EPC contracts.
Utility companies lead on scale through EDF's nuclear commitment; Independent operators are climbing the fastest as CRE auctions expand renewable capacity allocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping contractor deployment across French sub-regions, as divergent grid access tariffs and local content requirements under the Multiannual Energy Programme create cost-of-compliance gaps that favor Hauts-de-France and Grand Est clusters over saturated Île-de-France infrastructure zones.
Hauts-de-France
Dunkirk industrial cluster decarbonization mandates and electrolyzer-linked offshore wind bundles concentrate EPC demand in this northern corridor. The French Energy Regulatory Commission's tariff reforms for grid connection prioritize this zone's 1 GW offshore wind lease areas. Contractors face compressed mobilization timelines as nuclear refurbishment at Gravelines overlaps with marine foundation installation schedules.
Grand Est
Utility-scale solar deployment and shared logistics infrastructure for nuclear pressure equipment manufacturing define this eastern region's contractor market. ANSM oversight of RCC-M code compliance for Flamanville restart components extends manufacturing audit cycles at supplier yards near Metz and Nancy. Regional welding apprenticeship programs struggle to match EDF's accelerated nuclear component delivery timelines.
Normandy
Channel lease zone offshore wind arrays and turnkey contracting consolidation attract marine installation specialists to Caen and Le Havre port clusters. The EU Green Deal's REPowerEU domestic content requirements mandate French-sourced steel for foundation fabrication at local yards. Heavy-lift vessel bottlenecks for monopile installation fragment contractor deployment schedules across overlapping auction rounds.
Brittany
Floating offshore wind pre-commercial sites and semi-submersible platform fabrication repurposing Saint-Nazaire oil-and-gas yard capacity reshape this western region's EPC specialization. RTE's smart grid rollout demands IEC 61850 commissioning expertise for digital substation integration at Rennes and Brest interconnection points. Marine warranty surveyor coordination costs previously fragmented project budgets now consolidate under single-point liability contracts.
Auvergne-Rhône-Alpes
Alpine pumped-storage retrofits and run-of-river dam safety upgrades sustain specialized civil works demand for tunnelling contractors. France's water police authority oversight of dam refurbishment extends permitting timelines for EDF's hydro fleet modernization. Lyon district heating network retrofits create bundled thermal-electric EPC contracts with 20-year heat purchase agreements anchoring contractor revenue visibility.
France Power EPC Market Competitive Landscape
Consortium formation for nuclear-qualified supplier pools dominates the current landscape as EDF's restart timeline compresses available engineering resources. The market structures around three tiers: integrated energy groups with balance-sheet financing leverage, specialized high-voltage and marine installation contractors, and regional independents serving distributed solar under 100 MW. Strategic archetypes include reactor heritage anchors leveraging RCC-M certification advantages, grid interconnection specialists controlling RTE substation procurement, and marine EPC bundlers consolidating foundation-to-turbine scope. Competitive moves concentrate on turnkey contract capture for offshore wind and backward integration into pressure equipment manufacturing.
Within the integrated energy tier, EDF Renewables exemplifies the reactor maintenance heritage archetype, while ENGIE Solutions occupies the district heating-cogeneration specialization vector. VINCI Energies anchors the high-voltage interconnection segment through its Omexom subsidiary, representing the grid infrastructure control position that shapes contractor availability across overlapping nuclear and renewable timelines.
| Leading Market Players |
|---|
| ENGIE Solutions |
| EDF Renewables |
| TotalEnergies Renewables France |
| Eiffage Énergie Systèmes |
| Bouygues Energies & Services |
| VINCI Energies |
| Schneider Electric |
| Vestas Wind Systems |
| Siemens Gamesa Renewable Energy |
| Others |
Supply & Pricing Matrix
EDF's accelerated nuclear restart procurement schedules compress tendering windows and force contractors to absorb upfront mobilization costs without guaranteed follow-on volume. This buyer-driven urgency concentrates pricing power among ANSM-qualified welding specialists and heavy-lift vessel operators, squeezing margins for mid-tier EPC firms competing on standardized solar and onshore wind packages.
Pricing Analysis
Direct-to-utility contracting dominates large-scale nuclear and offshore wind procurement, eliminating distributor markups but demanding performance bonds and extended defect liability. Three-tier pricing structure across RCC-M certified, grid-qualified, and standard commercial tiers reflects divergent compliance burdens. Cost compression in the standard commercial tier intensifies because module and turbine supply chains face global oversupply. Independent developers under 100 MW capacity exhibit highest price sensitivity, while EDF's balance-sheet financing tolerates premium pricing for schedule certainty.
Supply Chain Analysis
Refurbishment flows for nuclear pressure equipment and repurposed oil-and-gas yard capacity for floating foundation fabrication create secondary supply channels that moderate primary manufacturing bottlenecks. Germany, Japan, and South Korea anchor specialized welding consumables and high-voltage transformer production. Inconel electrode and array cable supplies draw from concentrated metallurgical and subsea manufacturing bases. Single-source vulnerability in heavy-lift vessel availability for Channel zone monopile installation exposes EPC schedules to North Sea fleet allocation decisions. Distribution runs through RTE-mandated grid connection queues that sequence project commissioning and equipment delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France Power EPC market functions as a stable compounder anchored by decarbonization mandates that outlast electoral cycles and commodity price swings. Nuclear restart timelines and offshore wind auction schedules create predictable demand visibility across the projection horizon.
For Market Incumbents: Deepen RCC-M certification advantages by acquiring distressed pressure equipment manufacturing capacity in Grand Est supplier yards. Engineering labor scarcity between nuclear and offshore wind programs threatens contractor availability, making captive welding apprenticeship pipelines essential for schedule compliance. Control high-voltage interconnection procurement through IEC 61850 commissioning expertise to lock in RTE smart grid rollout participation.
For New Entrants and Emerging Players: Marine warranty surveyor networks offer underexploited entry points into Channel lease zone turnkey contracting, where single-point liability consolidation fragments incumbent coordination advantages. District heating-linked cogeneration in Lyon and Paris presents the most penetrable segment for thermal-electric bundled contracts. Pursue electrolyzer EPC partnerships with Hauts-de-France industrial offtakers to anchor revenue visibility before competing for utility-scale renewable auctions.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized high-voltage and civil nuclear contractors possessing ANSM audit relationships and qualified welding procedure specifications. Long-term viability hinges on exposure to France's Multiannual Energy Programme capacity targets rather than merchant power price exposure. Monitor ANSM inspection backlog clearance rates as the inflection indicator for nuclear component delivery acceleration and contractor margin recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| RCC-M Certification Investment | ANSM-qualified pressure equipment manufacturing unlocks EDF nuclear restart procurement participation. |
| Heavy-Lift Vessel Chartering | North Sea fleet allocation agreements secure Channel lease zone foundation installation schedule certainty. |
| IEC 61850 Commissioning Capability | RTE smart grid substation integration demands create defendable positioning in high-voltage EPC. |
| Welding Apprenticeship Pipeline | ANSM 18-month certification cycles outstrip labor supply, making captive training a structural advantage. |
| Floating Foundation Fabrication | Saint-Nazaire and Marseille yard repurposing captures pre-commercial Atlantic and Mediterranean site development. |
Research Methodology
Bottom-up project pipeline modeling reconciled against top-down EPC contractor capacity tracking forms the analytical core of this study. Primary interviews with utility planning officers, IPP project developers, EPC procurement managers, and grid interconnection specialists combined with secondary validation from CRE auction databases, RTE transmission investment disclosures, and ANSM manufacturing audit records. Supply-side triangulation against EDF capital expenditure schedules and offshore wind lease zone development timelines verified demand projections.
Historical trendline analysis of nuclear refurbishment cycles and renewable auction award patterns informed the projection framework across the analysis window. Segmentation modeling incorporated project type, contract structure, power capacity tier, and regional grid access tariff differentials. CAGRs derived from installed capacity buildout trajectories and unit cost normalization curves, with labor scarcity premiums and domestic content requirement compliance costs as industry-specific forecast inputs.
Revisions become necessary when ANSM inspection throughput accelerates, RTE grid connection queue reforms alter project sequencing, or EU domestic content mandates expand beyond current steel and cabling specifications. Forecasts reflect documented assumptions about EDF reactor availability targets and CRE auction volume allocations. Practitioners should monitor heavy-lift vessel charter rate movements and nickel price volatility for early signals of EPC margin compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Wind Turbine Components Market
Power Equipment
Clean Steam Separator Market
Power Equipment
Turbine Governor Market
Power Equipment
Egypt Power EPC Market
Power Equipment
US Power EPC Market
Power Equipment
Wind Tunnel Fans Market
Power Equipment
United States Power Rental Market
Power Equipment
Chad Power EPC Market
Power Equipment
Qatar Power EPC Market
Power Equipment
SCR Power Controller Market
Power Equipment
Power Cables Market
Power Equipment
Australia Power EPC Market
Power Equipment
Global Power Rental Systems Market
Power Equipment
Heavy Duty Gas Turbine Market
Power Equipment
Natural Gas Turbine Market
Power Equipment
Asia-Pacific Steam Turbine Market