
 Battery Charger Market | 2026-2036
Battery Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Charger Market Intelligence
Capital-intensity divergence between automated SMT lines and manual assembly operations is bifurcating competitive tiers in battery charger manufacturing. Exide Technologies leverages its captive lead-acid cell production to anchor integrated charger-pack offerings for industrial motive power. CTEK Sweden AB specializes in precision charging algorithms for cold-climate automotive aftermarket channels. EnerSys dominates motive-power charger segments through direct fleet-service contracts and on-site maintenance infrastructure.
A battery charger is an electrical device that converts AC mains or DC input into regulated DC output at specified voltage and current profiles to replenish electrochemical storage cells, with core parameters including conversion efficiency, ripple current, and thermal management thresholds. Wall chargers and USB chargers occupy mature, high-volume consumer tiers where margin pools have compressed to single-digit percentages. Fast charging and ultra-fast charging technologies are capturing disproportionate value in electric vehicle applications, where power-density requirements exceed 350 kW and thermal runaway protection becomes a critical design constraint.
The US Department of Energy and EPA enforce efficiency standards under ENERGY STAR and EPCA frameworks, while the EU Green Deal and CE marking directives mandate ecodesign compliance for standby power and electromagnetic compatibility. China's GB standards and MIIT circular economy regulations impose domestic content requirements and recyclability quotas on charger imports. Stakeholders must monitor divergence between regional efficiency test protocols and emerging interoperability standards for high-power charging connectors.
Market Dynamics
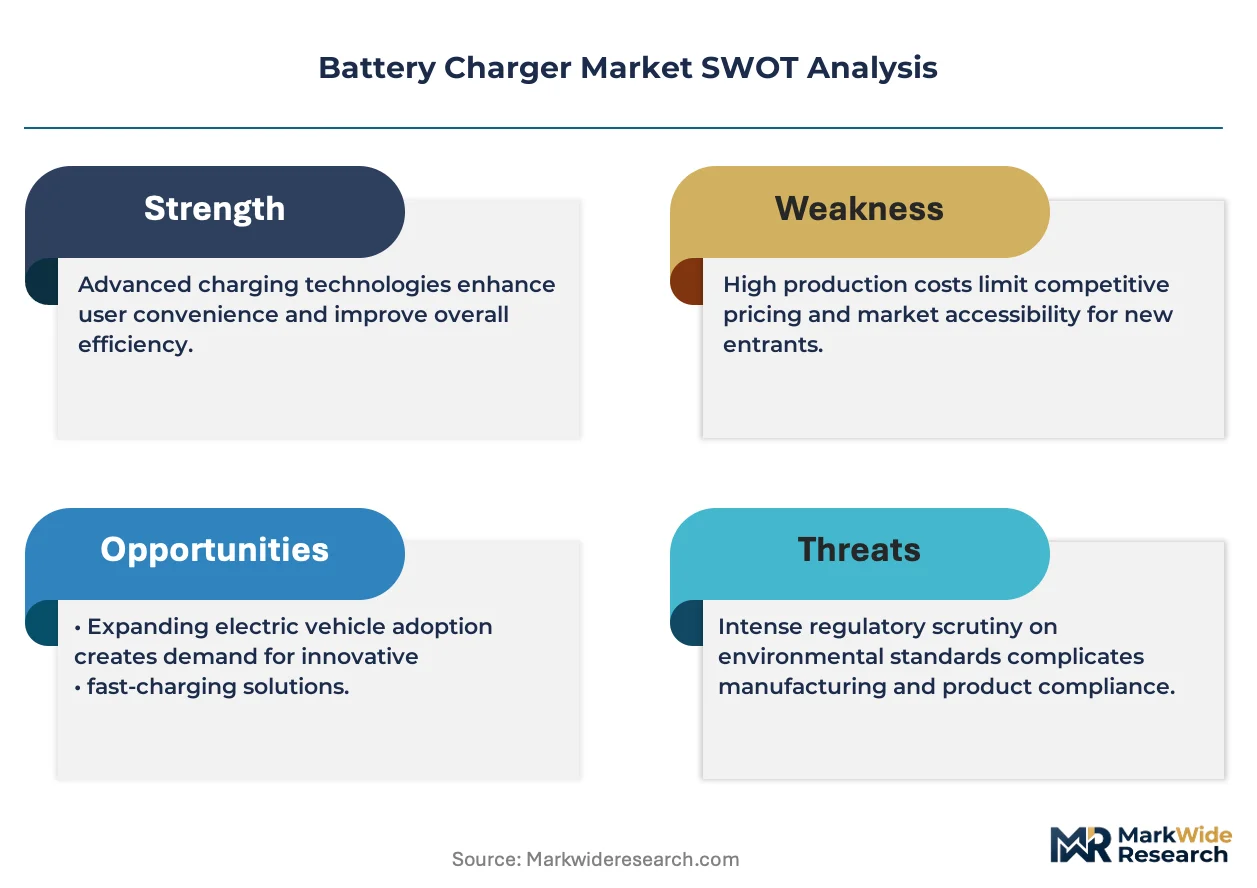
The battery charger market is undergoing a fundamental restructuring as power-density requirements for electric vehicle infrastructure collide with tightening energy-efficiency mandates under the EU F-Gas Regulation and US ENERGY STAR frameworks.
Growth Catalysts
- EU Green Deal decarbonization mandates:The European Commission's ecodesign directives are compelling fleet operators to replace legacy charging assets with high-efficiency systems, creating replacement demand across Germany, France, and the Netherlands.
- Silicon carbide (SiC) power semiconductors:Wide-bandgap devices are enabling charger designs above 350 kW with reduced thermal losses, unlocking ultra-fast charging deployment at highway corridor locations.
- China's dual carbon goals:MIIT circular economy regulations are accelerating domestic manufacturing of charger components, concentrating supply chain investment in Shenzhen and Suzhou industrial clusters.
Market Restraints
- Copper and rare earth price volatility:Input cost swings for magnetics and power conductors are compressing margins in high-volume consumer charger tiers where pricing power remains limited.
- Concentrated semiconductor supply:Dependence on Taiwanese and South Korean foundries for high-voltage power devices creates vulnerability to geopolitical disruption and allocation constraints.
- Lithium-ion thermal runaway physics:Fundamental electrochemical limitations on charge acceptance rates cap the practical benefit of power levels beyond 500 kW for current cell chemistries.
Strategic Opportunities
- V2G bidirectional charging infrastructure:Grid-interactive charger hardware is converging with energy management software to capture value from ancillary services markets in California and Germany.
- India's PLI scheme for electronics:Production-linked incentives are attracting contract manufacturers to establish charger assembly operations serving domestic electric two-wheeler and three-wheeler demand.
- Wireless inductive charging:Automated charging pads for autonomous logistics vehicles and robotic fleets are opening premium application segments beyond plug-in architectures.
Industry Challenges
- Power electronics engineering talent scarcity:Shortage of designers proficient in magnetics optimization and thermal simulation is extending product development cycles for high-frequency charger architectures.
- Multi-protocol certification complexity:Simultaneous compliance with CCS, CHAdeMO, and GB/T connector standards is fragmenting testing budgets and delaying regional market entry timelines.
- Legacy fleet integration friction:Retrofitting existing motive-power battery rooms with smart charging systems requires customized electrical infrastructure upgrades that strain installer capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Charger Market |
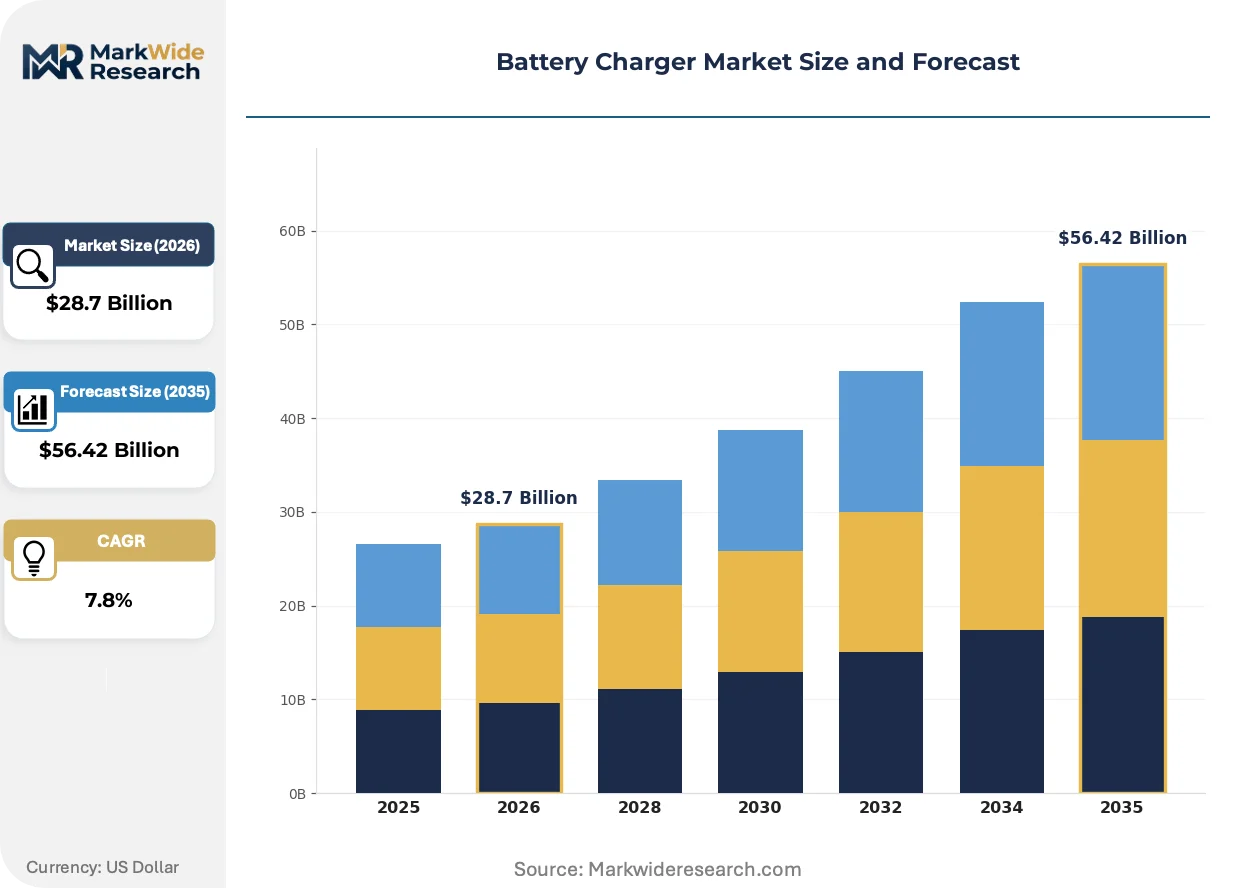
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $56.42 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Chargers, Solar Chargers, Wireless Chargers, USB Chargers Technology: Fast Charging, Smart Charging, Inductive Charging, Ultra-Fast Charging Use Case: Consumer Electronics, Electric Vehicles, Industrial Devices, Medical Equipment End User: Households, Commercial Establishments, Automotive, OEMs |
| Companies Covered | Exide Technologies, Energizer Holdings Inc., Schumacher Electric Corporation, Panasonic Corporation of North America, Spectrum Brands Inc., FRIWO AG, Saft S.A., CTEK Sweden AB, EnerSys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Charger Market Strategic Shifts & Innovations
Gallium nitride and silicon carbide devices are fundamentally altering power conversion economics, while regulatory pressure on standby power and interoperability standards is reshaping product development priorities across all voltage classes.
Silicon carbide MOSFETs are supplanting silicon IGBTs in the primary switching stages of chargers rated above 22 kW. Tier 1 automotive suppliers and charging network operators in Germany and China are adopting SiC-based designs for new installations, compressing the total cost of ownership differential against silicon solutions and enabling higher switching frequencies that reduce magnetics volume and cooling system mass.
The EU F-Gas Regulation's phasedown of fluorinated greenhouse gases is forcing refrigerant transitions in liquid-cooled charger thermal management systems. Equipment manufacturers are redesigning heat exchanger architectures to accommodate CO2 and hydrocarbon alternatives, with the highest power-density segments above 150 kW experiencing the most acute engineering pressure and qualification timeline extensions.
Fleet operators are consolidating charger procurement through long-term service agreements that unbundle hardware capital expenditure from maintenance and energy management functions. This model is displacing spot purchases of standalone equipment in the North American commercial vehicle segment, with logistics companies in California and Texas leading the shift toward performance-guaranteed charging infrastructure contracts.
Battery Charger Market Segmentation
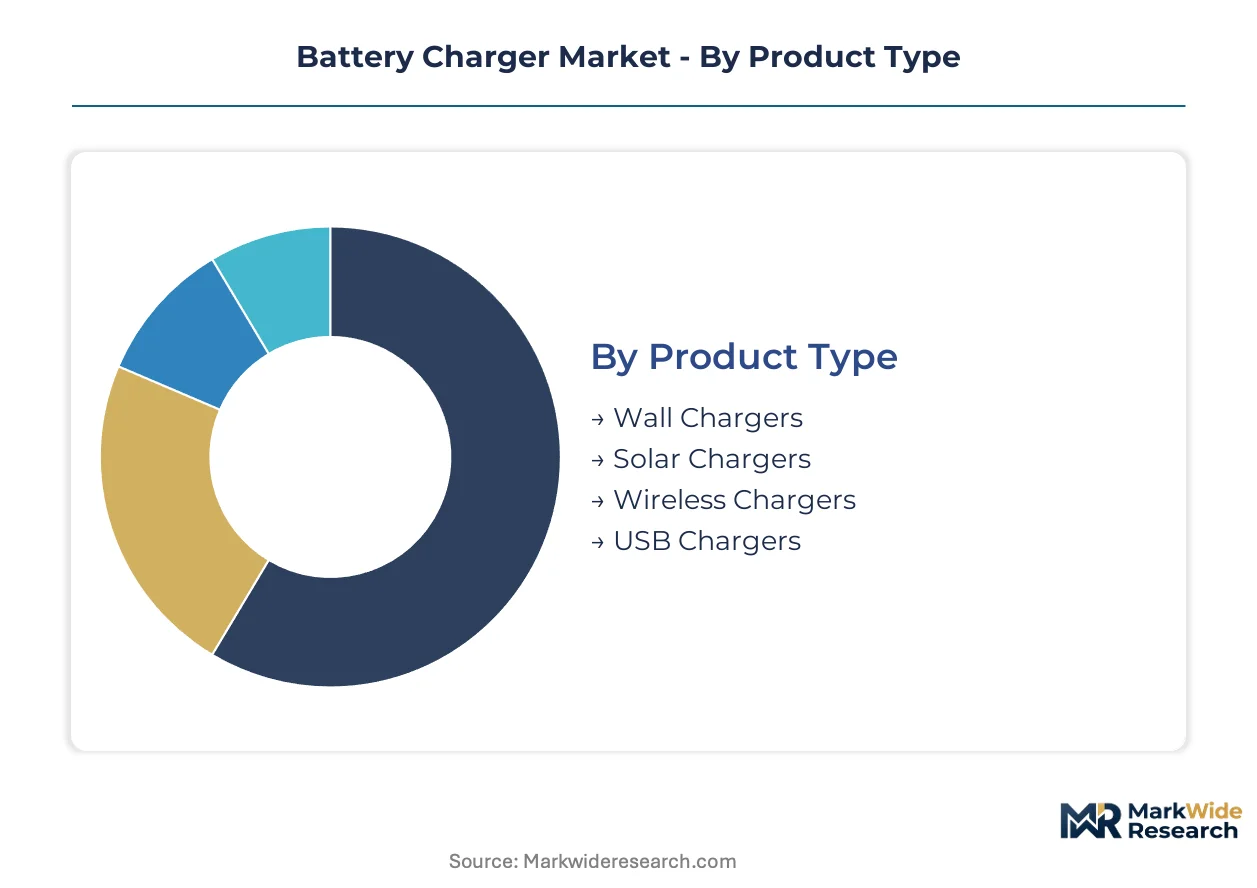
Charger architectures diverge sharply across power classes and thermal envelopes. Product managers must match cooling infrastructure, semiconductor topology, and connector protocols to specific voltage-current profiles demanded by target applications.
Product Type:
Wall chargers and USB chargers face acute substitution pressure from integrated power delivery in laptops and vehicle cabins, while wireless formats erode plug-in dominance in premium consumer tiers.
- Wall Chargers:Rectifier circuits with fixed voltage outputs dominate residential and light commercial installations. Demand concentrates in India and Southeast Asia where electric two-wheeler penetration drives 220V household infrastructure upgrades.
- USB Chargers:Power Delivery 3.1 and Qualcomm Quick Charge protocols now standard in 65W+ laptop adapters. Smartphone OEM bundling practices in China and South Korea are compressing aftermarket pricing power for third-party suppliers.
- Solar Chargers:MPPT-enabled portable units serve off-grid construction and expedition markets. German and Australian camping equipment distributors anchor procurement volumes.
- Wireless Chargers:Qi2 magnetic alignment specification is displacing first-generation inductive pads in automotive center consoles. BMW and Mercedes-Benz factory installations in Germany drive specification upgrades.
Wall chargers anchor the volume base while wireless chargers gain share at the steepest rate.
Technology:
Cost tiers separate legacy silicon architectures from wide-bandgap designs, with thermal management expense creating a 3-5x hardware cost spread between entry-level and ultra-fast systems.
- Fast Charging:22-150 kW DC systems with forced-air cooling dominate highway corridor installations. China's State Grid and Tesla Supercharger networks in the United States concentrate procurement for 120-150 kW mid-speed assets.
- Ultra-Fast Charging:350+ kW liquid-cooled cable assemblies with SiC power stages enable sub-20-minute passenger vehicle replenishment. Germany's Autobahn service areas and California's I-5 corridor host the densest deployment clusters.
- Smart Charging:Embedded metering and OCPP 2.0.1 communication enable demand-response participation. Dutch and Danish fleet operators mandate bidirectional capability in new procurement specifications.
- Inductive Charging:Resonant magnetic coupling systems eliminate connector wear in automated logistics environments. Volvo and Renault pilot programs at Swedish and French manufacturing plants validate 300mm air-gap tolerances.
Fast charging commands the largest installed base while ultra-fast charging climbs the fastest as highway infrastructure scales.
Use Case:
Application-specific duty cycles and safety certifications fragment engineering requirements, with medical and industrial segments demanding isolation transformers and leakage current controls absent from consumer tiers.
- Electric Vehicles:Onboard chargers rated 6.6-22 kW AC plus offboard DC infrastructure constitute the highest absolute power demand. Battery electric bus depots in Shenzhen and Santiago, Chile drive 450 kW depot charger procurement.
- Consumer Electronics:GaN-based compact adapters below 100 grams now standard for laptop and tablet replenishment. Apple's supply chain concentration in Dongguan and Foxconn's Vietnam expansion reshape manufacturing geography.
- Industrial Devices:Opportunity charging systems for forklift fleets operate across 24-80V lead-acid and lithium-ion chemistries. German logistics hubs and Amazon fulfillment centers in Poland specify multi-chemistry compatibility.
- Medical Equipment:IEC 60601-1 compliant isolation and defibrillation-proof construction mandatory for patient-contact devices. Siemens Healthineers and Philips production facilities in Germany and the Netherlands anchor demand.
Consumer electronics sustains shipment volume leadership while electric vehicle applications expand most quickly.
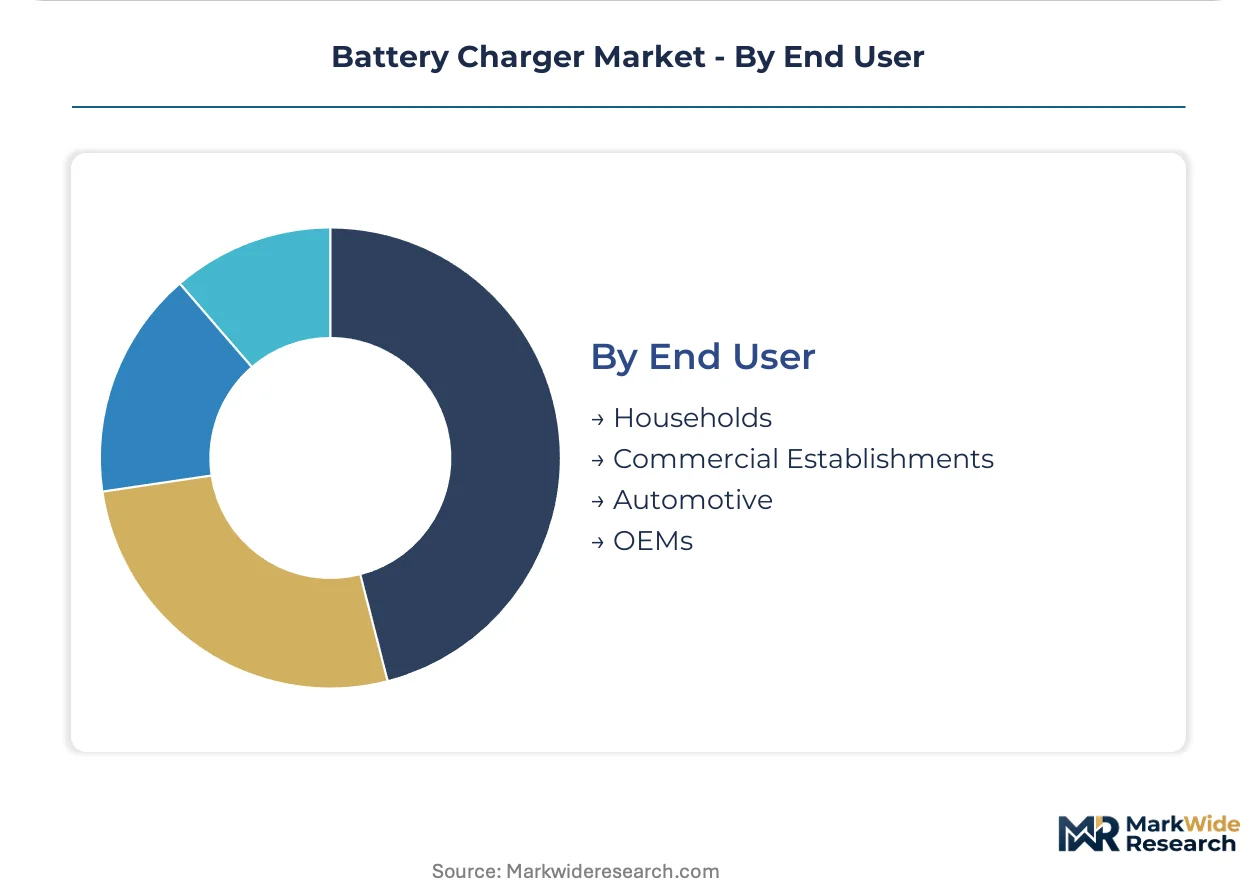
End User:
Customer type determines procurement modality, with households purchasing through retail channels and automotive OEMs negotiating multi-year supply agreements with qualification timelines exceeding 18 months.
- Automotive:Tier 1 suppliers integrate onboard chargers with battery management systems for platform-sharing programs. Volkswagen Group's MEB and Hyundai's E-GMP architectures in Germany and South Korea standardize 11 kW AC and 800V DC capability.
- OEMs:Original equipment manufacturers specify custom form factors and communication protocols for embedded power supplies. Dell and HP procurement teams in Texas and Taiwan negotiate GaN adapter volumes with 3-year price-down trajectories.
- Households:Replacement purchases of smartphone and laptop adapters dominate unit economics. Indian e-commerce platforms and Mexican retail chains drive price-sensitive procurement patterns.
- Commercial Establishments:Workplace and hospitality installations prioritize networked management and utilization analytics. WeWork and Marriott property portfolios in the United States and United Kingdom specify cloud-connected charger assets.
Households anchor unit shipment volumes while automotive OEMs capture value concentration through system integration contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys ultra-fast highway corridor chargers for premium passenger vehicles while China scales depot infrastructure for electric bus fleets, illustrating how geography shapes divergent infrastructure priorities. The United States concentrates investment in workplace and retail installations, whereas India prioritizes affordable two-wheeler charging. Japan maintains precision charging for industrial automation, with each market responding to distinct mobility patterns and regulatory frameworks.
United States
Workplace and retail charging installations dominate procurement as logistics operators electrify last-mile delivery vans. The EPA's ENERGY STAR efficiency standards filter into fleet procurement specifications. California's I-5 corridor hosts dense clusters of 350 kW liquid-cooled highway chargers serving long-haul electric trucking pilots.
Germany
Autobahn service areas drive ultra-fast charging deployment for premium electric passenger vehicles with 800V architectures. The EU F-Gas Regulation forces refrigerant transitions in liquid-cooled thermal management systems. Bavaria's industrial corridor concentrates SiC power semiconductor qualification facilities for next-generation charger designs.
China
Battery electric bus depots in Shenzhen and Beijing anchor 450 kW depot charger procurement volumes. MIIT circular economy regulations impose domestic content requirements on imported charger components. Suzhou and Shenzhen industrial clusters concentrate magnetics and power conductor manufacturing for regional supply chains.
India
Electric two-wheeler and three-wheeler charging infrastructure scales through household 220V upgrades and commercial battery swapping. The PLI scheme for electronics attracts contract manufacturers to establish assembly operations serving domestic demand. Maharashtra and Gujarat host emerging charger component fabrication clusters for regional distribution.
Japan
Precision charging systems serve automated manufacturing and robotic logistics fleets with stringent duty cycle requirements. METI efficiency standards shape standby power specifications for industrial charger categories. The Chubu region around Nagoya concentrates power electronics engineering talent for high-frequency architectures.
Battery Charger Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with captive cell production and direct fleet-service contracts distinguishing the upper stratum from component-assemblers. The middle tier fragments across regional contract manufacturers and technology licensors. Two strategic archetypes dominate: vertically integrated energy storage conglomerates with in-house charger production, and precision electronics specialists focused on algorithm-controlled charging protocols. Competitive moves concentrate on strategic partnerships for semiconductor supply security and geographic expansion into emerging EV markets.
Among Sweden-based specialists, CTEK Sweden AB exemplifies the precision-algorithm archetype for cold-climate automotive applications. EnerSys and Exide Technologies occupy positions within the integrated-leader tier, leveraging captive battery production and direct fleet-service infrastructure to anchor motive-power segments. These three companies represent distinct competitive vectors: Nordic precision engineering, North American industrial service integration, and legacy lead-acid vertical control.
| Leading Market Players |
|---|
| Exide Technologies |
| Energizer Holdings Inc. |
| Schumacher Electric Corporation |
| Panasonic Corporation of North America |
| Spectrum Brands Inc. |
| FRIWO AG |
| Saft S.A. |
| CTEK Sweden AB |
| EnerSys |
| Others |
Cost & Logistics Intelligence
Capacity utilization at Shenzhen and Suzhou power electronics clusters shapes both supply concentration and price floors for high-frequency charger architectures. Taiwan foundry allocation constraints for SiC MOSFETs transmit directly into tiered hardware pricing, with 350 kW liquid-cooled systems commanding substantial premiums over forced-air alternatives.
Pricing Analysis
After-sales service contracts and energy management subscriptions now drive lifetime value in commercial vehicle charging infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates SiC-based ultra-fast systems from silicon IGBT mid-speed assets and entry-level wall chargers. Cost compression in consumer USB tiers is intensifying because smartphone OEM bundling practices in China and South Korea eliminate aftermarket pricing power. Fleet operators show least price sensitivity due to total cost of ownership calculations, while Indian household purchasers of two-wheeler chargers exhibit acute cost consciousness.
Supply Chain Analysis
Port congestion on the Shanghai-Rotterdam trade lane elevates inbound logistics costs for European charger assembly operations sourcing magnetics from East Asia. Manufacturing concentrates in China, Taiwan, and Germany for power semiconductors, magnetics, and precision assembly respectively. Copper windings, rare earth magnets, and high-voltage capacitors constitute critical input dependencies. Single-source vulnerability around Taiwanese foundry capacity for 650V+ SiC devices represents the dominant structural risk. Distribution runs through direct fleet-service agreements for commercial segments and retail electronics channels for consumer tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as electric vehicle fleet electrification creates specialized demand for depot charging, highway corridor infrastructure, and workplace installations simultaneously. V2G bidirectional capability and thermal management differentiation open distinct competitive niches.
For Market Incumbents: Compound defensive positioning through captive semiconductor supply agreements and OCPP 2.0.1 certification depth. Secure allocation commitments with Taiwanese foundries before capacity constraints tighten further. Deepen backward integration into magnetics production to offset copper price volatility exposure.
For New Entrants and Emerging Players: Fleet energy management software gaps where incumbents under-serve create immediate white-space opportunity. Target India's electric two-wheeler charging infrastructure through PLI scheme-aligned assembly partnerships. Pursue wireless inductive charging for automated logistics as the most penetrable premium segment with limited incumbent lock-in.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-algorithm specialists with SiC design capabilities over legacy silicon assemblers. Five-to-ten year viability hinges on wide-bandgap semiconductor engineering talent retention. Monitor German Autobahn and California I-5 corridor deployment velocity as inflection indicator for ultra-fast charging hardware demand.
| Strategic Initiative | Industry Significance |
|---|---|
| SiC Power Semiconductor Supply Agreement | Taiwan foundry allocation secures production capacity for 350 kW charger architectures ahead of competitors. |
| OCPP 2.0.1 Certification Investment | Grid-interoperability compliance unlocks Dutch and Danish fleet procurement specifications for bidirectional systems. |
| Backward Integration into Magnetics | In-house ferrite core production insulates margin structure from copper and rare earth price volatility. |
| Liquid-Cooled Thermal Platform Development | CO2 refrigerant transition under EU F-Gas Regulation creates qualification barrier for non-compliant competitors. |
| India PLI Scheme Manufacturing Entry | Domestic assembly operations capture electric two-wheeler and three-wheeler demand with tariff-advantaged positioning. |
Research Approach
A standing panel of fleet operations directors, power electronics procurement managers, thermal systems engineers, and EV infrastructure planners provided ongoing calibration across the study period. Primary interviews combined with secondary validation from MIIT circular economy filings, EPA ENERGY STAR certification databases, EU F-Gas Regulation implementation reports, and customs trade data for power semiconductor imports. Bottom-up shipment modeling and top-down infrastructure investment triangulation anchored volume estimates.
Consistency checks against external benchmarks validated projections across the analysis window. Segmentation dimensions included power class tier, cooling architecture type, connector protocol standard, end-use application, and regional regulatory cluster. CAGRs derived from installed base growth rates and replacement cycle analysis. Key inputs encompassed SiC device adoption curves, fleet electrification timelines, and efficiency mandate compliance deadlines.
Underlying assumptions cover stable Taiwan foundry capacity allocation, continued EU F-Gas refrigerant phasedown adherence, and copper price band containment, with deviation risk concentrated in geopolitical semiconductor supply disruption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Bio-Based Transformer Oil Market
Electrical Power Equipment
Electric Submersible Pump Cable Market
Electrical Power Equipment
Train Contactor Market
Electrical Power Equipment
Storage Water Heater Market
Electrical Power Equipment
Alternating Current (AC) Electric Drives Market
Electrical Power Equipment
Solar Combiner Boxes Market
Electrical Power Equipment
Alternator Regulator Market
Electrical Power Equipment
North America Power Inverter Market
Electrical Power Equipment
United States Electric Space Heaters Market
Electrical Power Equipment
Gas Water Heater Market
Electrical Power Equipment
India Instrument Transformer Market
Electrical Power Equipment
North America Surge Arresters Market
Electrical Power Equipment
Gas Circuit Breaker Market
Electrical Power Equipment
Europe Alternating Current (AC) Drive Market
Electrical Power Equipment
Electrical Steel for Electric Vehicle Market
Electrical Power Equipment
Electric Radiators Market