
 Instant Grocery Market | 2026-2036
Instant Grocery Market Size, Share, and Industry Trends Forecast 2026-2036
Instant Grocery Market Intelligence
Subscription-based membership tiers is broadening what instant grocery platforms monetize beyond transactional delivery fees. Amazon leverages its Prime ecosystem to bundle grocery delivery with media and retail services. Instacart sustains retailer partnerships that embed its fulfillment layer inside neighborhood supermarkets. Walmart anchors its advantage through in-house production of store-brand perishables and same-day logistics from existing supercenter footprints.
Instant grocery denotes the procurement of food and household consumables through digital platforms promising fulfillment windows under sixty minutes, typically enabled by algorithmic inventory placement in micro-fulfillment centers or dark stores. The category spans perishable produce, ambient packaged goods, chilled beverages, and ready-to-eat snacks, with cold-chain integrity maintained through refrigerated totes and temperature-zoned vehicle compartments. Express delivery models command disproportionate consumer mindshare in dense metropolitan zones, while scheduled delivery and curbside pickup retain stronger traction among suburban households optimizing basket size against delivery cost. Corporate client segments within the customer type dimension generate higher average order values but require dedicated B2B invoicing and bulk handling protocols that individual consumer channels rarely support.
USDA food safety guidelines, FDA labeling requirements, and state-level cottage food laws govern product handling, traceability, and last-mile sanitation standards across the American instant grocery landscape. The EU Green Deal packaging directives and national plastic reduction mandates in France and Germany are forcing platform operators to redesign single-use thermal bags and disposable cooler inserts. Stakeholders must monitor whether municipal zoning boards accelerate or restrict dark-store proliferation in residential districts, as this regulatory variable directly constrains network density and delivery speed promises.
Market Dynamics
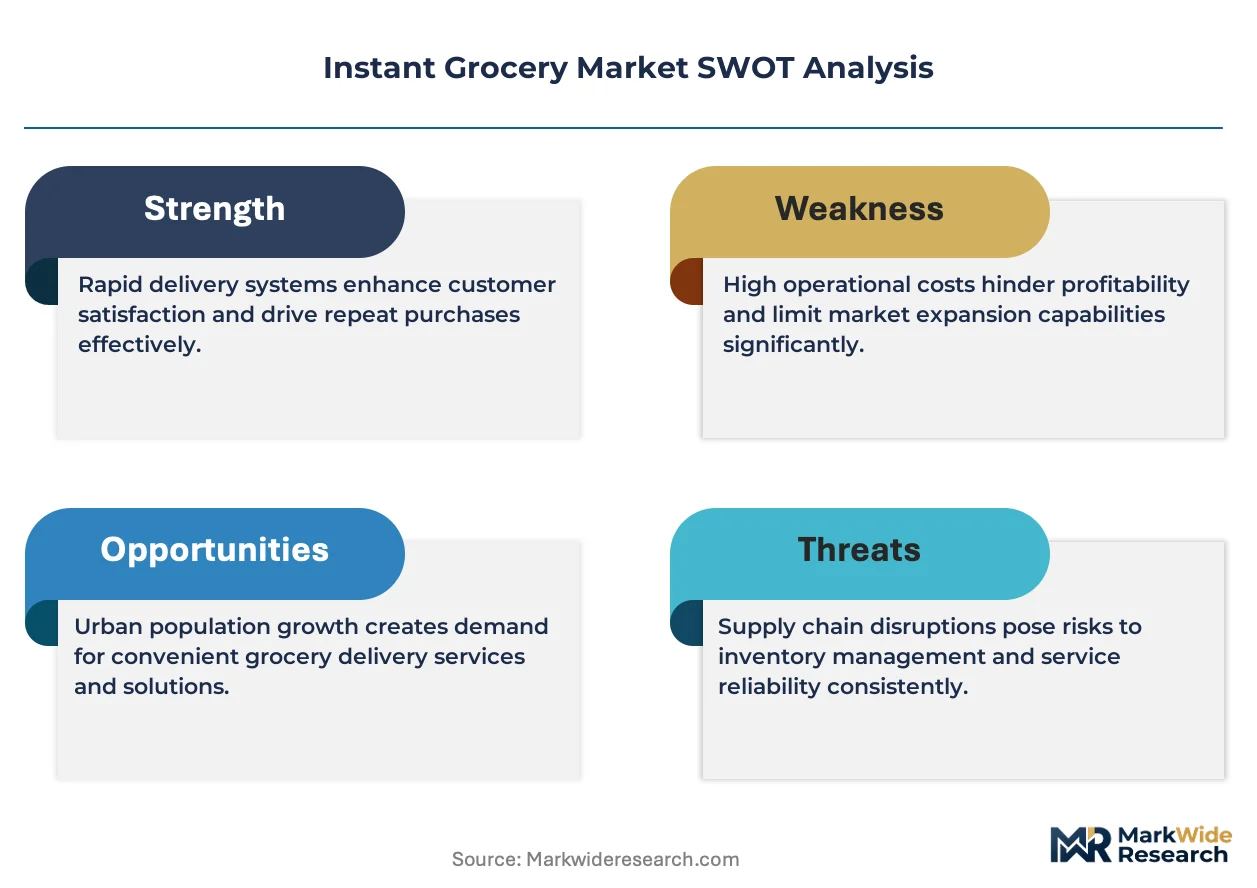
Dark-store proliferation is compressing fulfillment radii across metropolitan cores, forcing platforms to secure micro-fulfillment real estate ahead of zoning restrictions while refrigerated last-mile fleets multiply operating leverage.
Growth Catalysts
- EU Green Deal packaging mandates:France and Germany's single-use plastic reduction deadlines are accelerating investment in reusable thermal packaging systems and reverse logistics infrastructure for grocery delivery.
- Urban household density:Apartment concentration in Mumbai, São Paulo, and Jakarta creates natural delivery-radius economics that suburban sprawl cannot replicate.
- Automated picking systems:Robotic fulfillment in temperature-zoned dark stores is reducing per-order labor minutes and expanding SKU density per square meter.
Market Restraints
- Refrigerated fleet depreciation:Cold-chain vehicle capital intensity and compressor maintenance cycles strain unit economics in markets below 500 orders per dark store daily.
- Perishable shrinkage rates:Temperature excursions during handoffs and failed delivery attempts destroy margin on produce categories with sub-72-hour shelf life.
- Municipal zoning friction:Residential district ordinances in Amsterdam, Berlin, and Barcelona restrict dark-store licensing and cap network density.
Strategic Opportunities
- B2B catering corridors:Corporate kitchen replenishment and restaurant back-of-house supply in London and New York generate basket values 3-4x consumer averages with predictable scheduling.
- Scheduled subscription windows:Off-peak delivery slotting for suburban households reduces fleet idle time and improves route density economics.
- FSSAI traceability mandates:India's food safety digitization requirements create competitive moats for platforms with integrated batch-tracking and recall capabilities.
Industry Challenges
- Cold-chain technician scarcity:Refrigeration system maintenance and HACCP protocol enforcement require specialized labor pools that logistics networks struggle to scale.
- Legacy POS integration:Supermarket partners operate fragmented inventory systems that delay real-time stock synchronization and generate substitution errors.
- Multi-temperature tote standardization:Absence of interoperable container specifications across platforms drives redundant capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instant Grocery Market |
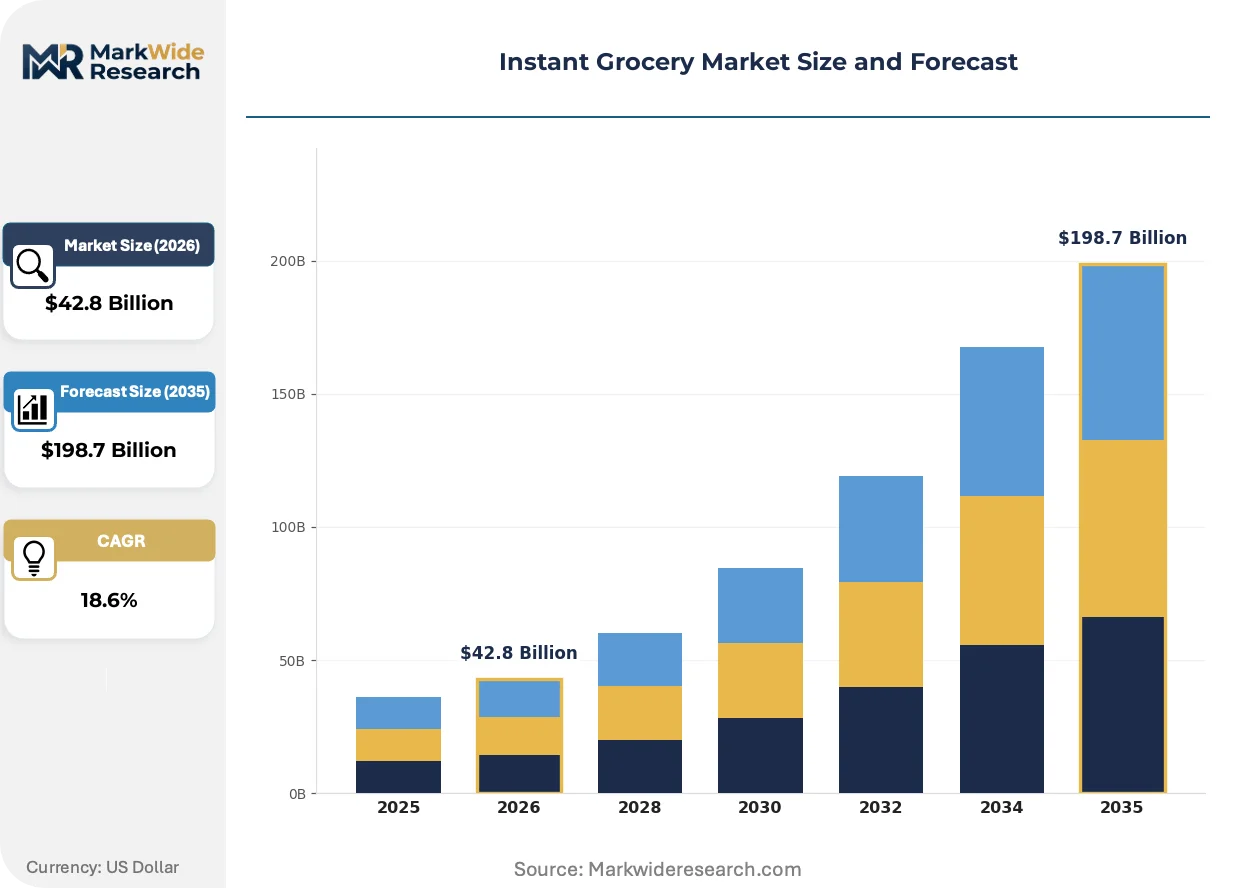
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $198.7 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Perishable, Non-Perishable, Beverages, Snacks End User: Households, Offices, Restaurants, Students Delivery Model: Express Delivery, Scheduled Delivery, Curbside Pickup, Store Pickup Customer Type: Individual Consumers, Corporate Clients, Retailers, B2B Partners |
| Companies Covered | Walmart, Amazon, Instacart, DoorDash, Gopuff, Swiggy, Getir, Uber Technologies, Delivery Hero, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instant Grocery Market Strategic Shifts & Innovations
Algorithmic demand forecasting is reshaping inventory positioning, with predictive models now dictating which SKUs populate each micro-fulfillment node before consumer orders arrive.
Computer vision-enabled automated picking is absorbing labor variability in chilled and frozen zones. Large-format grocery platforms in South Korea and the United Kingdom deploy robotic arms for ambient and produce selection, reducing picker travel time by half. The technology is absorbing tasks previously requiring human judgment on produce quality, compressing training overhead and shift-scheduling complexity.
FDA's Food Traceability Final Rule imposes granular lot-record requirements for high-risk produce categories. Compliance investments are diverting platform engineering resources toward serialization infrastructure and supplier onboarding protocols. Leafy greens and fresh-cut fruit suppliers face the steepest documentation burdens, with some California growers exiting direct-to-platform channels.
Households are consolidating weekly purchasing into fewer, larger baskets while retaining expectation of sub-60-minute availability for emergency replenishment. This bifurcation is splitting platform architecture between scheduled hub-and-spoke models and express dark-store networks. The tension is most visible in Australian and Canadian suburbs, where consumers maintain membership across both model types.
Instant Grocery Market Segmentation
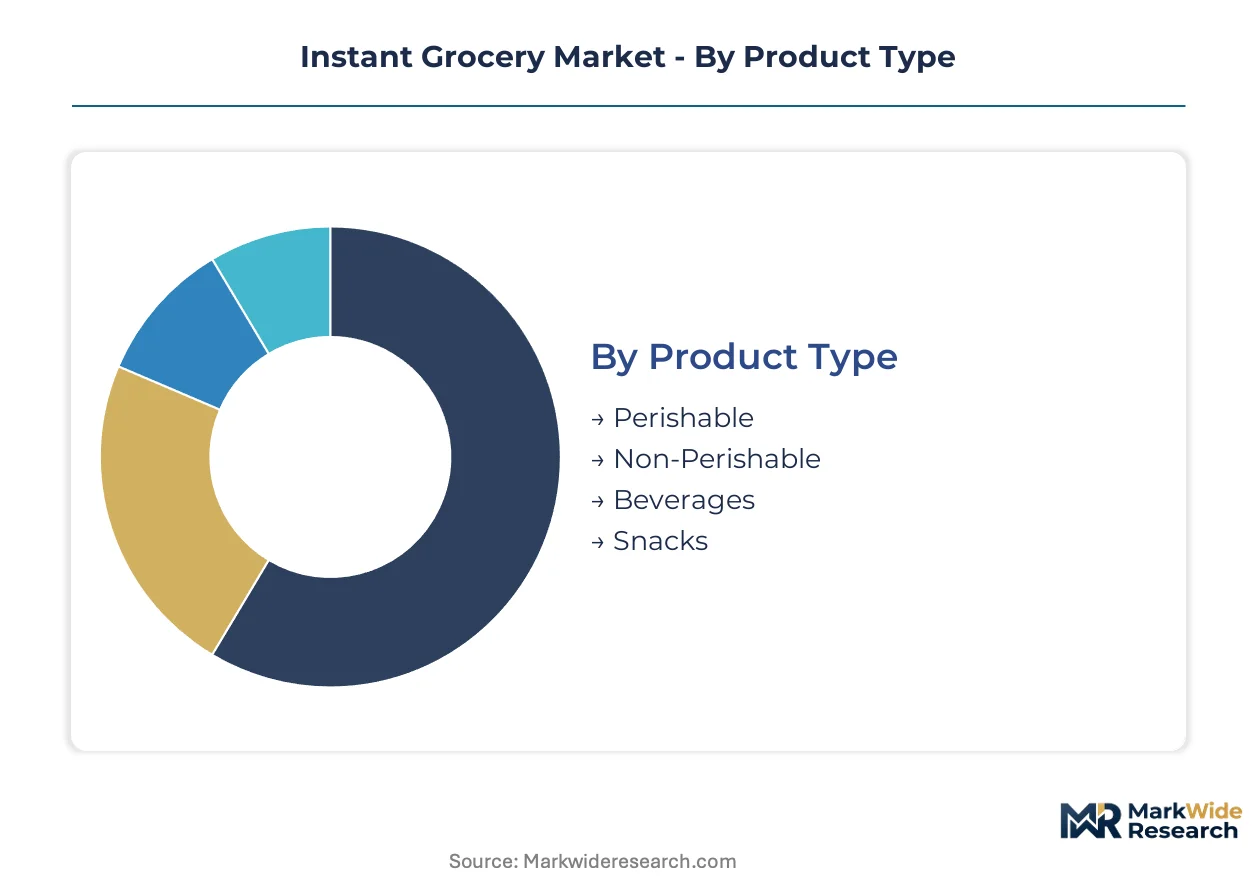
Instant grocery platforms segment demand across temperature sensitivity, fulfillment velocity, and procurement scale. Each dimension shapes inventory positioning, fleet configuration, and margin structure differently. Platforms optimize network density by matching segment characteristics to dark-store placement and cold-chain capacity.
Product Type:
Perishables anchor standalone dark-store networks requiring full cold-chain infrastructure, while ambient categories embed into existing retail fulfillment systems with lower capital barriers.
- Perishable:Temperature-controlled storage between 0-4°C preserves leafy greens, dairy, and fresh proteins. Mumbai and Jakarta households generate concentrated demand for sub-30-minute produce delivery where apartment density supports route economics.
- Non-Perishable:Ambient packaged goods tolerate warehouse conditions without refrigeration, allowing co-location with general e-commerce inventory. Shelf-stable staples absorb substitution pressure when fresh SKUs stock out.
- Beverages:Chilled and ambient drink categories span high-velocity replenishment cycles. Bulk water and multi-pack soft drinks drive basket expansion in suburban scheduled delivery corridors.
- Snacks:Ready-to-eat packaged foods carry lower handling complexity and higher impulse purchase frequency. Convenience positioning captures incremental demand between meal planning occasions.
Volume placements concentrate in Perishable; the faster expansion belongs to Beverages.
End User:
Cost tier differentiation separates high-frequency residential demand from institutional procurement requiring invoicing infrastructure and bulk handling protocols.
- Households:Individual residential buyers dominate order frequency with smaller basket sizes. Urban apartment clusters in São Paulo and London generate the densest delivery-radius economics for express fulfillment.
- Offices:Corporate pantry replenishment and meeting catering generate predictable mid-day demand spikes. B2B account management and consolidated billing systems add operational overhead.
- Restaurants:Back-of-house supply for independent kitchens requires pre-dawn delivery windows and case-quantities incompatible with consumer-facing apps. Specialized B2B platforms capture this segment through dedicated sales teams.
- Students:Campus-adjacent demand clusters around semester calendars with high price sensitivity and preference for snack-heavy, meal-kit alternatives.
Households absorb the greatest volume share; Restaurants are climbing the fastest as platforms build dedicated B2B fulfillment lanes.
Delivery Model:
Application context determines whether speed or cost optimization governs platform architecture, with express models demanding dedicated dark-store density.
- Express Delivery:Sub-60-minute fulfillment promises require micro-fulfillment centers positioned within 3-kilometer radii of demand clusters. Cold-chain fleet utilization depends on order density exceeding 400 daily per node.
- Scheduled Delivery:Hub-and-spoke logistics with next-day or two-day windows aggregate orders for route density optimization. Suburban households in Australian and Canadian markets favor this model for weekly stock-up purchasing.
- Curbside Pickup:Customer vehicle collection at designated points eliminates last-mile labor cost. Supercenter operators leverage existing parking infrastructure without dedicated delivery fleet investment.
- Store Pickup:In-aisle picking from retail inventory exposes platforms to real-time stock-out risk and substitution complexity. Legacy POS integration delays synchronize poorly with consumer-facing availability displays.
Express Delivery commands the densest infrastructure deployment; Scheduled Delivery is gaining share fastest in suburban expansion zones.
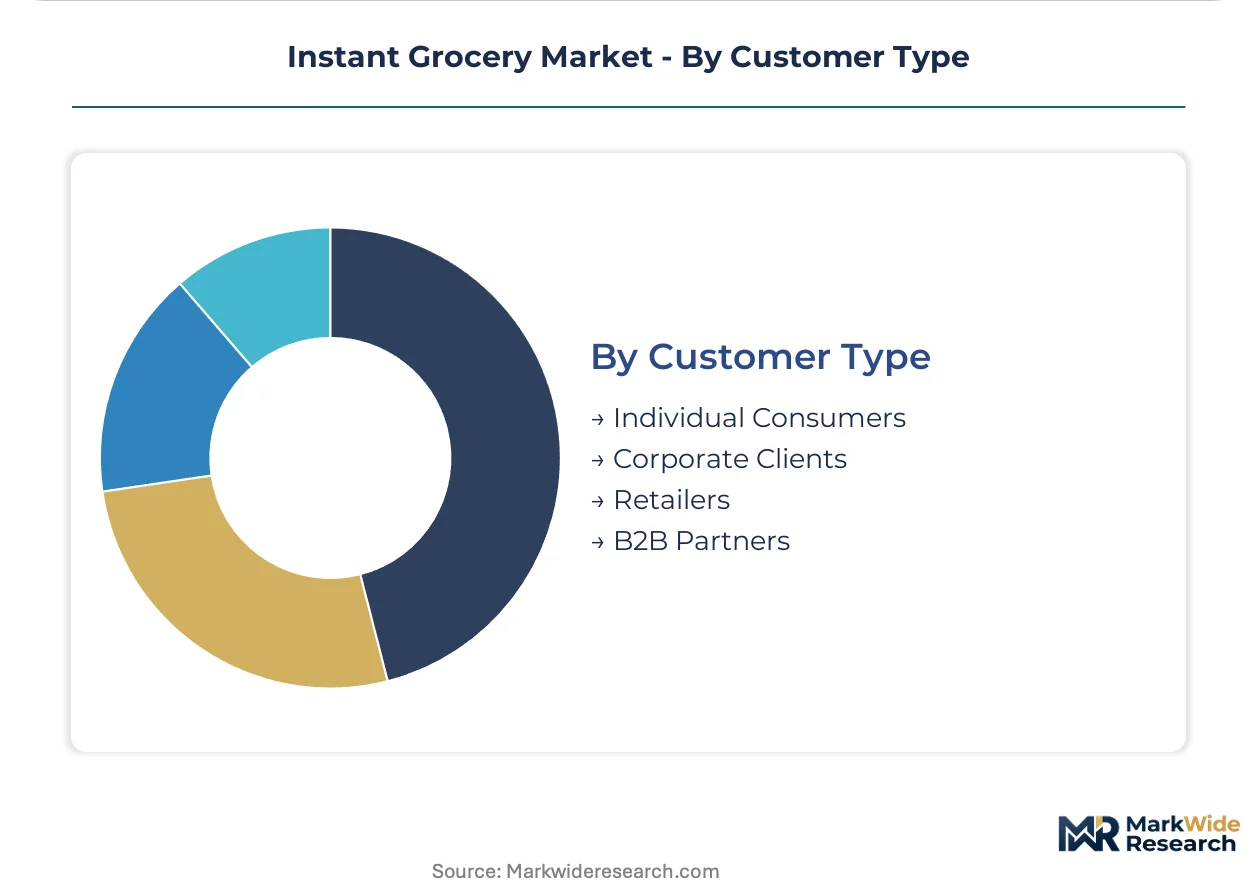
Customer Type:
Margin structure varies sharply between transactional consumer relationships and contracted corporate accounts with negotiated pricing and service-level agreements.
- Individual Consumers:Single-household buyers generate the highest per-order marketing acquisition cost and lowest lifetime value predictability. Subscription membership models attempt to lock in recurring demand and improve retention economics.
- Corporate Clients:Enterprise accounts with centralized procurement generate average order values 3-4x consumer levels. Dedicated account management and customized invoicing workflows require platform investment in B2B sales infrastructure.
- Retailers:Supermarket partners embed third-party fulfillment layers inside existing store networks. Inventory synchronization challenges and margin-sharing negotiations constrain platform profitability.
- B2B Partners:Restaurant suppliers, hotel chains, and institutional foodservice operators demand pre-dawn delivery windows and case-lot quantities. Temperature compliance documentation and HACCP protocol adherence raise operational barriers.
Individual Consumers absorb the greatest transaction volume; B2B Partners follow the steepest expansion trajectory as platforms diversify beyond saturated residential markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform operators concentrate fulfillment infrastructure where urban density justifies cold-chain capital deployment, while consumption spreads across suburban corridors where scheduled delivery models dominate. This geographic split shapes regulatory compliance requirements and network economics differently across markets.
United States
Supercenter operators leverage existing refrigerated footprints to anchor same-day grocery fulfillment in metropolitan corridors. FDA's Food Traceability Final Rule imposes granular lot-record requirements on high-risk produce categories, diverting platform engineering resources toward serialization infrastructure. Dark-store proliferation concentrates in Atlanta, Phoenix, and Dallas-Fort Worth, where municipal zoning boards currently permit micro-fulfillment centers in light industrial districts.
India
Apartment concentration in Mumbai and Bangalore generates natural delivery-radius economics for sub-30-minute produce promises. FSSAI traceability mandates create competitive moats for platforms with integrated batch-tracking capabilities, raising operational barriers for new entrants. Quick-commerce operators cluster in Delhi-NCR and Hyderabad, where campus-adjacent demand and corporate kitchen replenishment drive predictable mid-day order spikes.
United Kingdom
London's dense household clusters sustain express dark-store networks with sub-60-minute fulfillment windows across chilled and ambient categories. EU Green Deal packaging directives and national plastic reduction mandates force platform operators to redesign single-use thermal bags and disposable cooler inserts. Automated picking systems deploy in Birmingham and Manchester fulfillment nodes, reducing per-order labor minutes in temperature-zoned environments.
Germany
Scheduled delivery models gain traction in suburban zones where consumers optimize basket size against delivery cost through weekly stock-up purchasing. ECHA and national packaging regulators enforce strict single-use plastic reduction deadlines, accelerating investment in reusable thermal packaging systems and reverse logistics infrastructure. Berlin and Hamburg face municipal zoning friction that restricts dark-store licensing and caps network density in residential districts.
South Korea
Computer vision-enabled automated picking absorbs labor variability in Seoul's chilled and frozen fulfillment zones, with robotic arms reducing picker travel time by half. METI-aligned efficiency standards and national carbon reduction targets pressure fleet operators toward electric refrigerated vehicles. Large-format grocery platforms deploy temperature-zoned automation in Busan and Daegu, compressing training overhead and shift-scheduling complexity.
Instant Grocery Market Key Industry Players
Top-tier vendors anchor the integrated retail ecosystem tier, while specialized quick-commerce operators and delivery aggregators occupy distinct competitive strata. The market structure stratifies across three archetypes: vertically integrated retailers with captive fulfillment infrastructure, third-party logistics platforms embedding fulfillment layers inside partner store networks, and pure-play rapid delivery specialists operating dedicated dark-store grids. Consolidation pressure manifests through retailer-platform partnerships and technology licensing arrangements, with geographic expansion and portfolio diversification serving as dominant competitive vectors.
Within the integrated retail tier, Walmart and Amazon exemplify divergent approaches to grocery fulfillment scale. Walmart anchors advantage through in-house production of store-brand perishables and same-day logistics from existing supercenter footprints. Amazon leverages its Prime ecosystem to bundle grocery delivery with media and retail services, creating cross-category retention lock-in. Among third-party logistics specialists, Instacart occupies a position representing retailer partnership models that embed fulfillment infrastructure inside neighborhood supermarkets.
| Leading Market Players |
|---|
| Walmart |
| Amazon |
| Instacart |
| DoorDash |
| Gopuff |
| Swiggy |
| Getir |
| Uber Technologies |
| Delivery Hero |
| Others |
Cost & Logistics Intelligence
Automated picking systems in temperature-zoned dark stores are compressing per-order labor minutes while expanding SKU density per square meter, simultaneously lowering fulfillment cost floors and concentrating supply leverage among platforms with capital to deploy robotics at scale. This technology shift tightens margin structures for manual-picking competitors and rewards operators with refrigerated fleet density in Mumbai, London, and Seoul.
Pricing Analysis
Margin tightening in express delivery tiers reflects refrigerated fleet depreciation cycles and perishable shrinkage rates that destroy margin on sub-72-hour shelf-life categories. Three-tier pricing structure across premium, standard, and economy levels segments urban apartment households from suburban stock-up buyers and corporate kitchen accounts. Cost-down pressure on suburban scheduled delivery accelerates because route density economics fail below 400 orders per dark store daily. Corporate clients exhibit lowest price sensitivity due to consolidated procurement and service-level agreements, while student segments on campus-adjacent clusters drive highest price elasticity.
Supply Chain Analysis
Regional distribution centers in the United States, India, and the United Kingdom anchor hub-and-spoke patterns for scheduled delivery corridors, while micro-fulfillment nodes within 3-kilometer radii feed express networks. Cold-chain infrastructure draws from compressor manufacturing in China, refrigerated vehicle assembly in Germany, and thermal packaging production in South Korea. Single-source vulnerability concentrates in municipal zoning approvals that cap dark-store licensing in Amsterdam, Berlin, and Barcelona. Distribution runs through temperature-zoned last-mile fleets to residential apartment clusters and corporate B2B corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold-chain technician scarcity props pricing for platforms with certified maintenance capabilities, constraining supply expansion faster than demand growth across metropolitan fulfillment networks.
For Market Incumbents: Hedge against municipal zoning friction by securing light industrial real estate in Atlanta, Phoenix, and Dallas-Fort Worth ahead of residential district ordinance tightening. Deepen backward integration into reusable thermal packaging systems to offset EU Green Deal compliance costs and build reverse logistics moats against aggregator competitors. For New Entrants and Emerging Players: Quick-service restaurant back-of-house supply in London and New York offers the most penetrable white-space, generating basket values 3-4x consumer averages with predictable pre-dawn scheduling. Campus-adjacent demand clusters in Delhi-NCR and Hyderabad present secondary entry points through snack-heavy, meal-kit alternatives with lower cold-chain capital requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in retailer-platform technology licensing arrangements and geographic portfolio roll-ups. Platforms with integrated FSSAI batch-tracking capabilities in India and FDA serialization infrastructure in the United States represent prime acquisition archetypes. Watch dark-store order density thresholds crossing 500 daily per node as the inflection signal for unit economic sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Dark-Store Network Expansion | Micro-fulfillment positioning within 3-kilometer radii in Mumbai and Jakarta compresses delivery windows below 30 minutes. |
| Reusable Thermal Packaging Transition | Reverse logistics infrastructure investment responds to France and Germany single-use plastic reduction mandates under EU Green Deal. |
| Automated Picking System Deployment | Robotic fulfillment in Seoul and Birmingham temperature-zoned nodes halves picker travel time in chilled categories. |
| B2B Fulfillment Lane Development | Corporate kitchen replenishment in London and New York generates predictable mid-day demand spikes with 3-4x consumer basket values. |
| FSSAI Traceability Integration | Batch-tracking capabilities create competitive moats in India as food safety digitization raises operational barriers for new entrants. |
Research Approach
Multi-period observation of dark-store order density, refrigerated fleet utilization rates, and perishable shrinkage patterns anchored the trend analysis, supplemented by interviews with fulfillment operations directors, cold-chain logistics managers, municipal zoning officers, supermarket category buyers, and B2B account executives at corporate catering platforms. Secondary validation drew from FDA Food Traceability Final Rule documentation, FSSAI digitization mandates, EU Green Deal packaging directives, customs records for refrigerated vehicle imports, and SEC filings of listed grocery retailers. Bottom-up unit economic modeling triangulated against top-down market sizing across temperature sensitivity, fulfillment velocity, and procurement scale dimensions.
Segment-weighting approaches applied differential growth assumptions to express delivery versus scheduled delivery models, with cold-chain capacity constraints and municipal zoning friction calibrated as binding variables across the projection horizon. Product type segmentation modeled perishables, non-perishables, beverages, and snacks separately, while end-user dimensions captured household, office, restaurant, and student demand patterns. CAGRs derived from logistic diffusion curves applied to urban household density projections and refrigerated fleet deployment timelines, with algorithmic demand forecasting adoption and automated picking system penetration serving as technology acceleration inputs.
Several conditions sit outside the modeled scope, including abrupt municipal zoning reversals, cold-chain equipment tariff escalations, and pandemic-scale demand shocks. Forecasts reflect documented assumptions around dark-store licensing continuity and technician labor pool expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
GCC Online Grocery Market
Food Service
United Kingdom Cafes & Bars Market
Food Service
Indonesia Foodservice Market
Food Service
US Healthcare/Hospital Food Services Market
Food Service
Bottled Water Cooler Market
Food Service
North America Cafes & Bars Market
Food Service
Undercounter Ice Makers Market
Food Service
Food & Beverage in Asia Market
Food Service
Food Service Gloves Market
Food Service
South Korea Foodservice Market
Food Service
Food Trays Market
Food Service
Food Service Pasta Market
Food Service
Smart Food Logistics Market
Food Service
Restaurant Griddle Market
Food Service
Personal Chef Services Market
Food Service
Global Online Food Ordering Market