
 US Frozen Bakery Market | 2026-2036
US Frozen Bakery Market Size, Share, and Industry Trends Forecast 2026-2036
US Frozen Bakery Market Analysis
The gap between premium artisan frozen bakery and commodity private-label lines is recalibrating category investment across the US. Rich Products Corporation leverages its foodservice channel control to sustain premium positioning in par-baked and fully finished formats. General Mills, Inc. anchors retail freezer space through scale advantages in frozen dough and biscuit portfolios. Bimbo Bakeries USA, Inc. differentiates via vertical integration into flour sourcing and regional plant networks that reduce landed costs for national accounts.
US frozen bakery comprises wheat-based and specialty-grain doughs, batters, and finished goods preserved at sub-zero temperatures to extend shelf life and enable bake-off or thaw-serve preparation; standard storage maintains minus eighteen degrees Celsius to inhibit starch retrogradation and microbial activity, with par-baked formats requiring finish ovens at one hundred ninety to two hundred four degrees Celsius for crust development. Frozen breads occupy the largest volume position within product type segmentation, though frozen pastries capture disproportionate margin pools due to ingredient complexity and lower private-label penetration. Food retailers represent the fastest-growing end user channel as grocers expand in-store bakery alternatives and frozen-to-oven merchandising.
The FDA governs ingredient declarations, allergen labeling, and nutritional content standards for frozen bakery distributed across state lines, while the USDA oversees egg and dairy component safety through its FSIS arm, creating dual compliance obligations for manufacturers using composite formulations. State-level cottage food laws and commercial kitchen regulations in California, Texas, and New York add further permitting layers for emerging brands entering direct distribution. Stakeholders must monitor evolving sodium and added-sugar reduction mandates from federal health agencies that will reshape reformulation roadmaps and clean-label investment priorities.
Market Dynamics
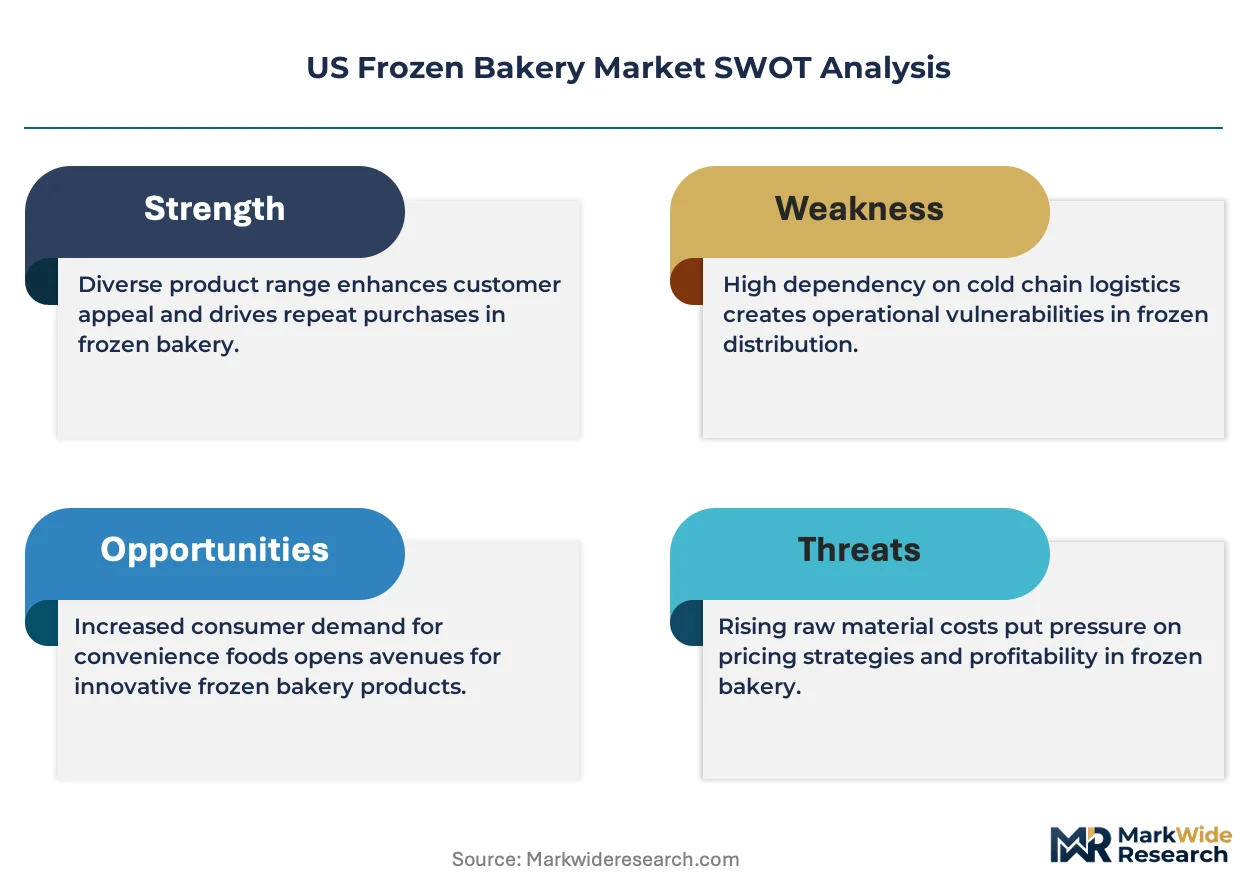
Frozen bakery manufacturers face intensifying pressure from the FDA's updated Nutrition Facts labeling requirements for prepared foods, which are forcing rapid reformulation of sodium and added-sugar content across par-baked and fully finished product lines.
Growth Catalysts
- Quick-service restaurant density:The Southeast's concentration of QSR chains generates sustained demand for frozen bread and pastry inputs that support high-throughput bake-off operations.
- FSIS oversight harmonization:USDA coordination of egg and dairy component safety streamlines multi-state distribution for composite frozen bakery formulations.
- Flash-freezing technology:Advanced cryogenic systems preserve starch structure in specialty-grain doughs, extending viable shelf life without quality degradation.
Market Restraints
- Wheat price volatility:Input cost swings in commodity grains compress margins for mid-tier frozen dough producers lacking long-term supply contracts.
- California cottage food law complexity:State-level commercial kitchen permitting creates friction for emerging brands attempting direct distribution in high-population markets.
- Fresh bakery substitution:In-store bakery alternatives at major grocers capture at-home consumption occasions with perceived freshness advantages.
Strategic Opportunities
- Texas distribution hub expansion:Regional plant networks in the South Central corridor reduce landed costs for national foodservice accounts.
- Frozen-to-oven merchandising:Retail grocers are creating dedicated freezer sections that blur the line between frozen and fresh bakery perception.
- Clean-label ingredient convergence:Combination of enzyme technology and natural preservation methods enables shorter ingredient declarations without compromising shelf stability.
Industry Challenges
- Refrigerated logistics talent scarcity:Qualified cold-chain operators and maintenance technicians remain difficult to recruit in secondary distribution markets.
- Dual compliance timelines:Simultaneous FDA and FSIS certification requirements delay new product launches by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Frozen Bakery Market |
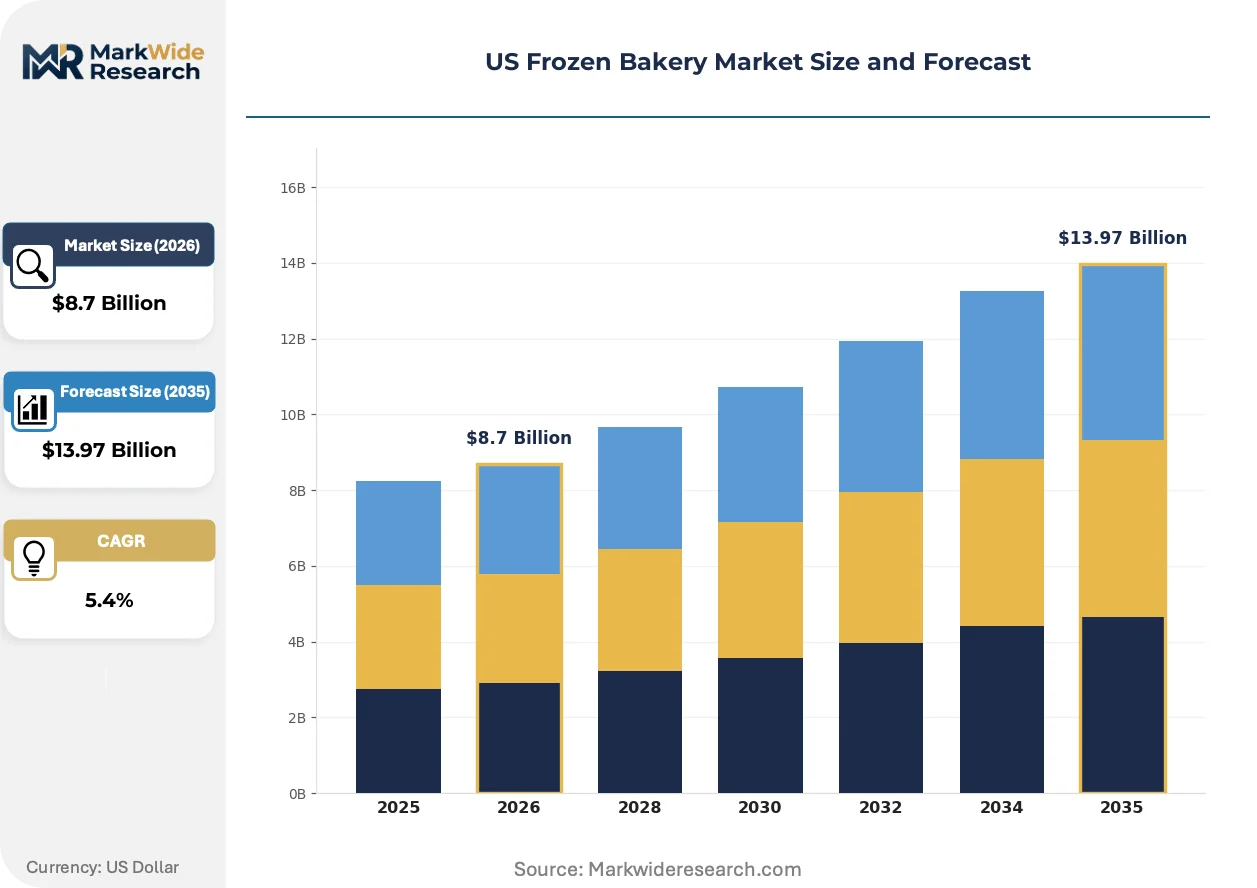
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Breads, Frozen Pastries, Frozen Cakes, Frozen Cookies End User: Restaurants, Cafes, Catering Services, Food Retailers Distribution Channel: Direct Sales, Retail Stores, Online Channels, Wholesale Form: Whole, Slices, Portions, Bites |
| Companies Covered | General Mills, Inc., Rich Products Corporation, Bimbo Bakeries USA, Inc., New York Bakery Co., Otis Spunkmeyer, Inc., Conagra Brands, Inc., Schwan's Company, Bridgford Foods Corp, Flowers Foods, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Frozen Bakery Market Emerging Trajectories
Automation and reformulation science are compressing production cycles while clean-label demands rewrite ingredient sourcing priorities across the frozen bakery value chain.
Advanced enzyme systems are consolidating quality control in frozen dough production. Large-scale manufacturers deploy these biological catalysts to inhibit starch retrogradation and extend freeze-thaw tolerance. Food retailers adopting par-baked formats for in-store bake-off programs benefit from reduced waste and consistent crust development.
The FDA's added-sugar disclosure mandate is forcing ingredient list transparency. Manufacturers must now account for sugars introduced through fruit fillings, glazes, and fermented bases in total nutritional calculations. Frozen pastry segments with complex composite formulations face the steepest reformulation roadmaps to maintain retail placement.
Home baking resurgence is reshaping channel economics. Consumers seeking convenience without sacrificing participation are driving demand for frozen doughs that require minimal finishing skill. This behavioral pivot is most pronounced in suburban Southeast markets where quick-service restaurant exposure has normalized bake-off preparation expectations.
US Frozen Bakery Market Segmentation
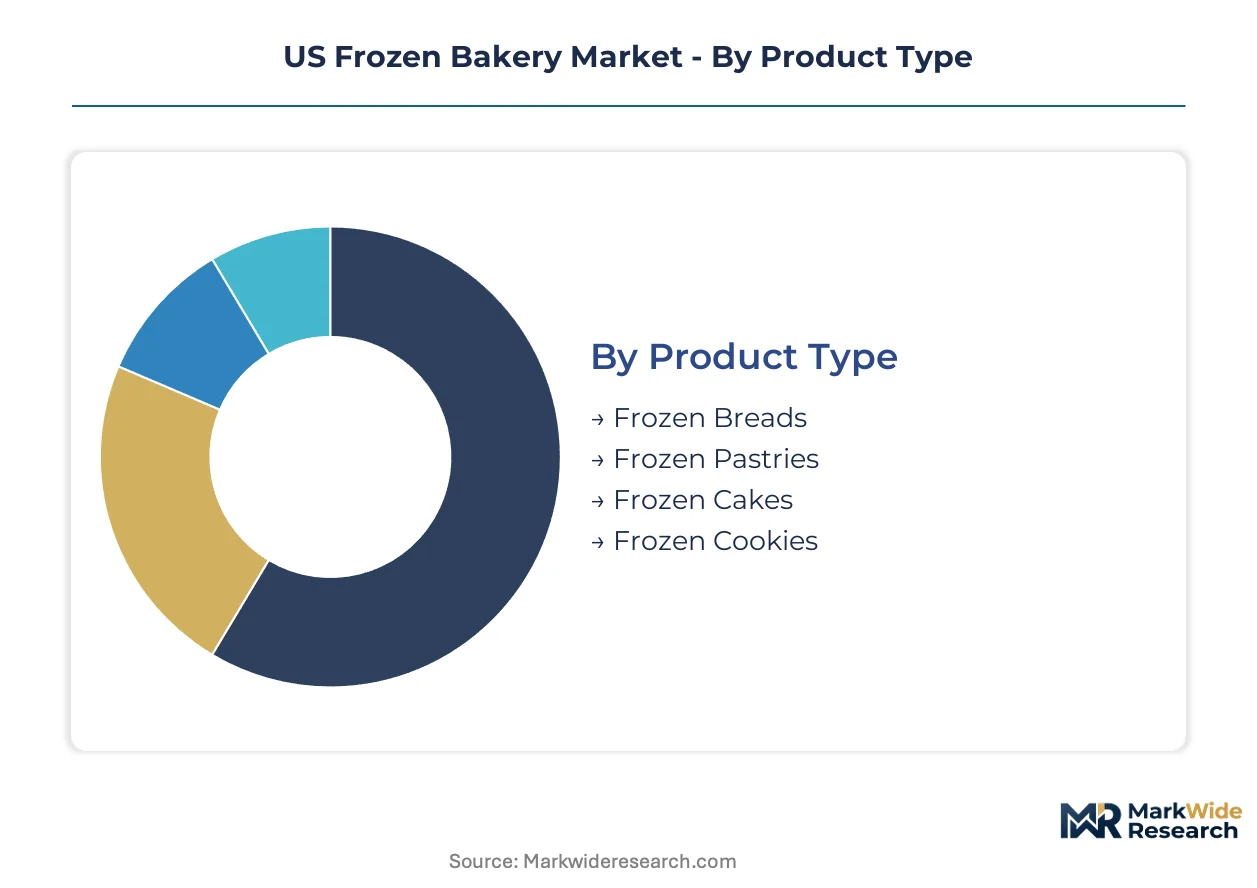
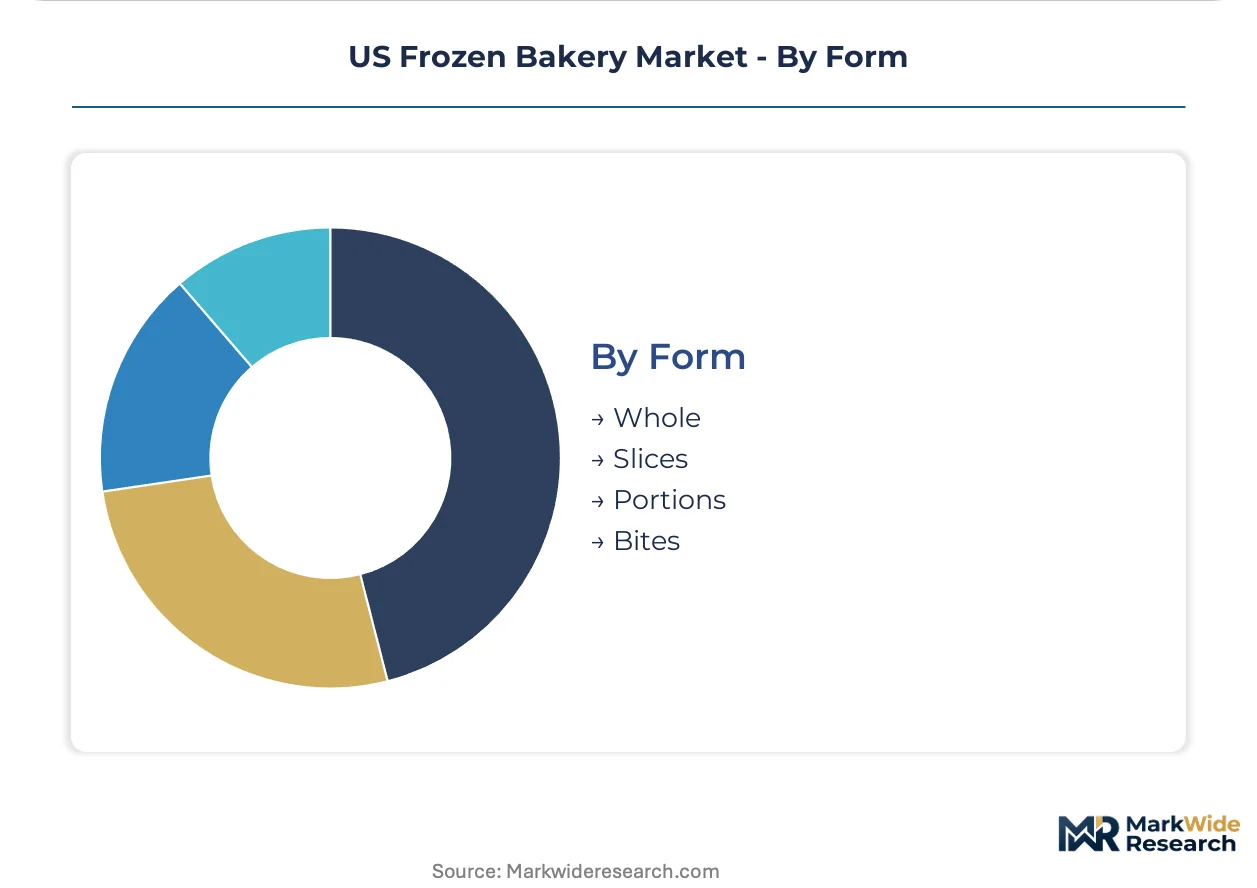
Frozen bakery segmentation reveals how preparation format, buyer scale, and channel economics split manufacturing priorities. Distinct technical requirements for par-baked versus fully finished formats create divergent investment patterns across product categories.
Product Type:
Buyers differentiate by operational complexity and margin structure rather than ingredient cost alone.
- Frozen Breads:Yeast-leavened doughs frozen at proofed or par-baked stages, requiring finish ovens for crust development. Demand concentrates in quick-service restaurant chains across the Southeast, where high-throughput bake-off operations prioritize consistent crumb structure and extended holding tolerance.
- Frozen Pastries:Laminated and chemically leavened products with higher ingredient complexity and lower private-label penetration. Cafes and upscale food retailers in suburban Texas and Florida markets drive expansion, drawn by premium positioning and thaw-serve convenience without skilled labor.
- Frozen Cakes:Fully finished or layer components requiring controlled thaw cycles for frosting integrity. Catering services in metropolitan New York and Los Angeles represent concentrated demand for event-scale portioning.
- Frozen Cookies:Portioned dough or pre-baked formats targeting home baking participation. Food retailers expanding frozen-to-oven merchandising capture at-home consumption occasions with minimal preparation skill.
Volume sits with frozen breads; growth tilts toward frozen pastries.
End User:
Scale of operation and labor availability determine format preferences across buyer categories.
- Restaurants:Full-service and casual dining operations using par-baked breads and portion-controlled pastries to reduce kitchen labor. Chains with centralized procurement in the South Central corridor leverage regional distribution infrastructure for landed cost advantages.
- Cafes:Coffee-forward concepts prioritizing thaw-serve pastries and minimal equipment footprints. Urban clusters in California and Washington State show highest adoption of fully finished formats requiring zero on-site baking.
- Catering Services:Event and institutional foodservice requiring bulk formats with extended holding stability. Demand clusters around metropolitan Atlanta and Dallas-Fort Worth for regional celebration and corporate markets.
- Food Retailers:Grocers expanding in-store bakery alternatives through frozen-to-oven programs. Suburban Southeast markets demonstrate steepest channel expansion as bake-off preparation norms spread from QSR exposure.
Restaurants hold volume concentration; food retailers are climbing the fastest.
Distribution Channel:
Cold-chain reliability and order frequency separate channel economics for manufacturers.
- Direct Sales:Manufacturer-to-account relationships for national foodservice chains with dedicated freezer capacity. Large operators negotiate formula exclusivity and custom portioning in exchange for volume commitments.
- Retail Stores:Branded and private-label placement in supermarket freezer cases. Shelf-space competition intensifies as grocers consolidate bakery alternatives into dedicated frozen sections.
- Online Channels:Direct-to-consumer and specialty food platforms shipping insulated packaging. Emerging brands navigate FDA interstate commerce requirements while building subscription repeat purchase.
- Wholesale:Broadline distributors serving independent restaurants and regional chains. Temperature-controlled consolidation points in Chicago and Philadelphia handle multi-temperature loads for mixed frozen bakery and protein orders.
Wholesale dominates current throughput; online channels show steepest expansion trajectory.
Form:
Portion control and waste reduction drive specification differences across buyer types.
- Whole:Unsliced loaves and complete cakes for foodservice finishing and presentation control. Catering and restaurant accounts in Texas and Florida prefer whole formats for on-site customization.
- Slices:Pre-portioned bread and cake components reducing service labor. Cafes and grab-and-go retail concepts in California metropolitan areas standardize on slice formats for speed of service.
- Portions:Individually wrapped pastries and dessert components for single-serve merchandising. Food retailers expanding convenience-oriented freezer sections prioritize portion formats for household consumption.
- Bites:Miniature formats for sampling, catering platters, and premium snacking. Emerging demand from corporate catering and specialty retail channels seeking differentiation through presentation variety.
Whole formats retain foodservice dominance; portions gain share fastest in retail channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Atlanta anchors frozen bakery throughput through its dense quick-service restaurant corridor and cold-chain distribution infrastructure serving the broader Southeast.
Southeast
Florida and Georgia concentrate frozen bread demand through quick-service restaurant chains requiring high-volume bake-off operations. FDA nutrition labeling requirements reshape formulation priorities for manufacturers supplying this corridor. The Interstate 75 distribution spine connects Atlanta freezer capacity to Tampa and Orlando foodservice markets.
South Central
Texas generates frozen pastry expansion through suburban cafe density and thaw-serve convenience demand. State-level commercial kitchen regulations create permitting friction for emerging brands entering direct distribution. Dallas-Fort Worth hosts regional plant networks that reduce landed costs for national foodservice accounts.
West Coast
California metropolitan clusters drive fully finished frozen bakery formats requiring zero on-site baking capability. Cottage food law complexity adds regulatory layers for emerging brands attempting direct distribution in Los Angeles and San Francisco markets. The Central Valley agricultural corridor supplies specialty grain inputs for clean-label product lines.
Northeast
New York metropolitan catering services concentrate demand for frozen cake formats with event-scale portioning requirements. State commercial kitchen permitting requirements exceed federal baselines for interstate distribution compliance. Newark and Philadelphia cold-chain consolidation points handle mixed frozen bakery loads for independent restaurant accounts.
Midwest
Chicago wholesale distribution serves independent restaurants and regional chains across the Great Lakes corridor. Temperature-controlled logistics talent scarcity complicates cold-chain maintenance in secondary distribution markets. Michigan and Ohio manufacturing bases supply par-baked formats to food retailers expanding frozen-to-oven merchandising.
US Frozen Bakery Market Vendor Landscape
Premium-margin players sit above commodity-margin players across ingredient complexity and channel control dimensions. The vendor base clusters around three strategic archetypes: diversified food conglomerates with retail freezer dominance, specialized frozen bakery operators with foodservice channel control, and regional bakers leveraging vertical integration into flour sourcing. Consolidation pressures intensify through M&A activity targeting regional distribution networks, while capacity expansion concentrates in South Central corridor states with favorable logistics economics.
Within the diversified conglomerate tier, General Mills, Inc. and Conagra Brands, Inc. occupy positions shaped by scale advantages in frozen dough and biscuit portfolios. Rich Products Corporation exemplifies the specialized operator archetype through its foodservice channel focus. Among regional bakers with captive supply integration, Bimbo Bakeries USA, Inc. represents backward integration strategies into flour sourcing and plant network optimization.
| Leading Market Players |
|---|
| General Mills, Inc. |
| Rich Products Corporation |
| Bimbo Bakeries USA, Inc. |
| New York Bakery Co. |
| Otis Spunkmeyer, Inc. |
| Conagra Brands, Inc. |
| Schwan's Company |
| Bridgford Foods Corp |
| Flowers Foods, Inc. |
| Others |
Supply Flow & Price Mechanics
Chicago wheat futures volatility cascades through frozen bakery supply chains into three distinct pricing tiers anchored by ingredient grade, throughput guarantees, and cold-chain service levels. Buyers with national volume commitments command contract-based pricing that insulates against spot-market swings, while independent foodservice operators absorb commodity-driven margin compression without hedging instruments.
Pricing Analysis
Throughput-based bake-off yield anchors value-based pricing for par-baked formats, with quick-service restaurant chains paying premiums for guaranteed crust development consistency and extended holding tolerance. Price differentiation separates certified clean-label tiers from standard formulations, with enzyme-stabilized specialty-grain doughs commanding fifteen to twenty percent spreads over commodity wheat bases. Pricing pressure stems from private-label expansion at major grocers, compressing branded margin pools in frozen bread categories. Food retailers show highest price sensitivity due to shelf-space negotiation leverage, while catering services with event-scale portioning requirements exhibit lowest sensitivity given labor substitution value.
Supply Chain Analysis
FSIS certification for egg and dairy components gates supplier qualification, filtering upstream raw material sources to USDA-inspected facilities with documented HACCP protocols. Supply concentrates in domestic grain belts and regional dairy corridors, with specialty-grain inputs drawing from Central Valley agricultural networks. Wheat flour, butter solids, and cryogenic freezing equipment anchor component dependencies, with tariff exposure on imported enzyme systems creating single-source vulnerability for clean-label formulations. Distribution runs through temperature-controlled consolidation points in Chicago and Philadelphia, where multi-temperature logistics operators handle mixed frozen bakery and protein loads for broadline foodservice delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US frozen bakery sector sits in a technology-transition phase where advanced enzyme systems displace chemical preservatives, rewriting formulation roadmaps and clean-label certification requirements across manufacturing tiers.
For Market Incumbents: Extend flash-freezing technology deployment to capture specialty-grain shelf-life extension premiums before patent cliffs erode competitive moats. Consolidate regional plant networks in the South Central corridor to defend landed cost position against Bimbo Bakeries USA's flour-sourcing integration. Channel control through exclusive quick-service restaurant partnerships remains the priority lever against retail private-label displacement.
For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting suburban Southeast households with bake-off preparation familiarity from quick-service restaurant exposure. White-space concentrates in frozen pastry segments where lower private-label penetration and ingredient complexity sustain margin pools. Texas cottage food law navigation expertise provides go-to-market angle for emerging brands seeking food retailer placement without national distribution infrastructure.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale manufacturers with captive regional distribution networks and FSIS-certified dairy component handling in Georgia or Florida. Long-term viability hinges on clean-label reformulation capability and frozen-to-oven retail channel positioning. Watch FDA sodium reduction mandate timelines as inflection indicator for accelerated consolidation among legacy formulation-dependent operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzyme Technology Licensing | Advanced biological catalysts enable shorter ingredient declarations without compromising starch retrogradation resistance. |
| South Central Plant Network Expansion | Regional manufacturing footprint reduces landed costs for national foodservice accounts competing with vertically integrated rivals. |
| Frozen-to-Oven Retail Partnership | Dedicated freezer section placement blurs freshness perception and captures at-home consumption occasions from in-store bakery alternatives. |
| Clean-Label Certification Investment | FDA added-sugar disclosure compliance creates qualification barrier protecting premium positioning against commodity private-label encroachment. |
| Flash-Freezing Capacity Buildout | Cryogenic systems preserve specialty-grain dough structure, extending viable shelf life for distribution to secondary markets. |
Methodological Framework
USDA crop reports, FDA food additive petitions, and American Bakers Association technical bulletins formed the secondary backbone for input cost and regulatory trajectory assessment. Primary interviews with frozen bakery plant managers, quick-service restaurant procurement directors, food retailer category buyers, and cold-chain logistics operators combined with customs records and SEC 10-K filings to validate volume assumptions. Bottom-up production capacity tallies and top-down consumption estimates underwent triangulation across the analysis window.
Bottom-up modeling segmented volume by product type, preparation format, and end-user channel, while top-down approaches validated aggregate demand against quick-service restaurant chain expansion data and grocery freezer case footage trends. CAGRs derived from regression analysis against wheat price indices, labor cost inflation, and channel shift parameters. Enzyme technology adoption curves and FDA reformulation timelines served as industry-specific forecast inputs throughout the projection horizon.
Wheat futures volatility, FDA sodium mandate acceleration, and flash-freezing equipment lead times are the dominant revision risks warranting model sensitivity testing. Forecasts reflect assumptions about quick-service restaurant density maintenance and retail frozen-to-oven program expansion. A model refresh is warranted upon material change in clean-label certification adoption rates or FSIS dairy component inspection protocol adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Low Fat Baked Goods Market
Bakery Products
Waffle Market
Bakery Products
Low Fat Muffin Market
Bakery Products
Bake Stable Pastry Fillings Market
Bakery Products
GCC Frozen Bakery Products Market
Bakery Products
Toasted Flour Market
Bakery Products
South America Ice Cream Market
Bakery Products
Ready-To-Finish Bakery Products Market
Bakery Products
Organic Frozen Bakery Market
Bakery Products
Gulf Cooperation Council Frozen Bakery Products Market
Bakery Products
Par-Baked Bread Market
Bakery Products
Pizza Crust Market
Bakery Products
GCC Bakery Products Market
Bakery Products
Fondant Market
Bakery Products
Qatar Bakery Product Market
Bakery Products
North America Gluten Free Bakery Mixes Market