
 US Healthcare/Hospital Food Services Market | 2026-2036
US Healthcare/Hospital Food Services Market Size, Share, and Industry Trends Forecast 2026-2036
US Healthcare/Hospital Food Services Market Analytics
The USDA BioPreferred Program and hospital sustainability purchasing mandates are shifting procurement priorities toward cleaner ingredient sourcing and reduced packaging waste. Morrison Healthcare leverages its specialized clinical nutrition infrastructure to anchor large health system accounts across the South. Sodexo competes through technology-integrated patient dining platforms that sustain operational efficiency in multi-site deployments. Compass Group PLC differentiates via its global supply chain controls, which extend cost advantages to its US healthcare division.
Healthcare and hospital food services encompass the planning, preparation, delivery, and nutritional management of meals within acute and post-acute care settings, typically operating under Hazard Analysis Critical Control Point protocols with temperature control specifications of 41°F or below for cold items and 135°F or above for hot service. These operations serve therapeutic, regulatory compliance, and patient experience functions while supporting clinical outcomes through dietitian-directed meal modifications. Inpatient service types dominate contract value due to their integration with clinical care teams and three-meal operational intensity, while nutrition counseling represents the fastest-expanding segment as hospitals seek reimbursable preventive care extensions under value-based arrangements. Off-site delivery modes and vended solutions are gaining structural importance in outpatient and dialysis center environments where capital-intensive kitchen investments prove impractical.
FDA food safety regulations, CMS Conditions of Participation for hospital licensure, and Joint Commission accreditation standards collectively shape operational requirements, supplier qualifications, and audit frequencies across the sector. State health departments add layer-specific inspection protocols that vary in enforcement intensity, creating compliance complexity for multi-state operators. Stakeholders must monitor evolving Medicare Advantage supplemental benefit expansions that could reclassify medically tailored meals as covered services, fundamentally altering reimbursement dynamics and vendor selection criteria.
Market Dynamics
CMS reimbursement rules tying hospital payments to patient satisfaction scores and clinical nutrition outcomes are restructuring procurement priorities, forcing acute care facilities to prioritize vendor capabilities in dietetic expertise and meal customization over pure cost minimization.
Growth Catalysts
- IRAs Hospital Price Transparency Mandate:CMS Conditions of Participation now require documented nutrition care plans, expanding contract scope for food service providers with clinical staffing capabilities.
- Medically Tailored Meal Pilots:Medicare Advantage supplemental benefit expansions in California and Massachusetts are testing reimbursement for condition-specific meal delivery, creating new revenue streams.
- Health System Consolidation:Southeast and Texas markets are seeing multi-hospital contract rollouts that favor vendors with regional kitchen infrastructure and centralized dietitian oversight.
Market Restraints
- Protein and Produce Input Volatility:USDA commodity price swings for poultry and fresh vegetables compress margin predictability for fixed-price contract operators.
- Multi-State Compliance Friction:State health department inspection protocols vary in enforcement intensity across Texas, Florida, and Georgia, creating audit complexity for regional vendors.
- Retail Meal Substitution:Third-party delivery platforms and grocery prepared foods present lower-cost alternatives for hospital staff and visitor dining, eroding captive market capture.
Strategic Opportunities
- Outpatient Dialysis Centers:Off-site meal delivery to renal care facilities represents underpenetrated demand where capital-intensive kitchen investments are impractical for operators.
- USDA BioPreferred Procurement Mandates:Federal purchasing preferences for biobased products create positioning advantages for vendors with certified sustainable packaging and cleaning supply chains.
- AI-Enabled Diet Optimization:Convergence of electronic health record data with predictive nutrition algorithms enables personalized meal planning at population scale.
Industry Challenges
- Registered Dietitian Talent Scarcity:Clinical nutrition staffing shortages delay menu development and patient counseling capacity, constraining service expansion timelines.
- HACCP-Certified Kitchen Retrofit Costs:Temperature control infrastructure and allergen segregation systems require substantial capital outlays for facilities upgrading to acute care standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Healthcare/Hospital Food Services Market |
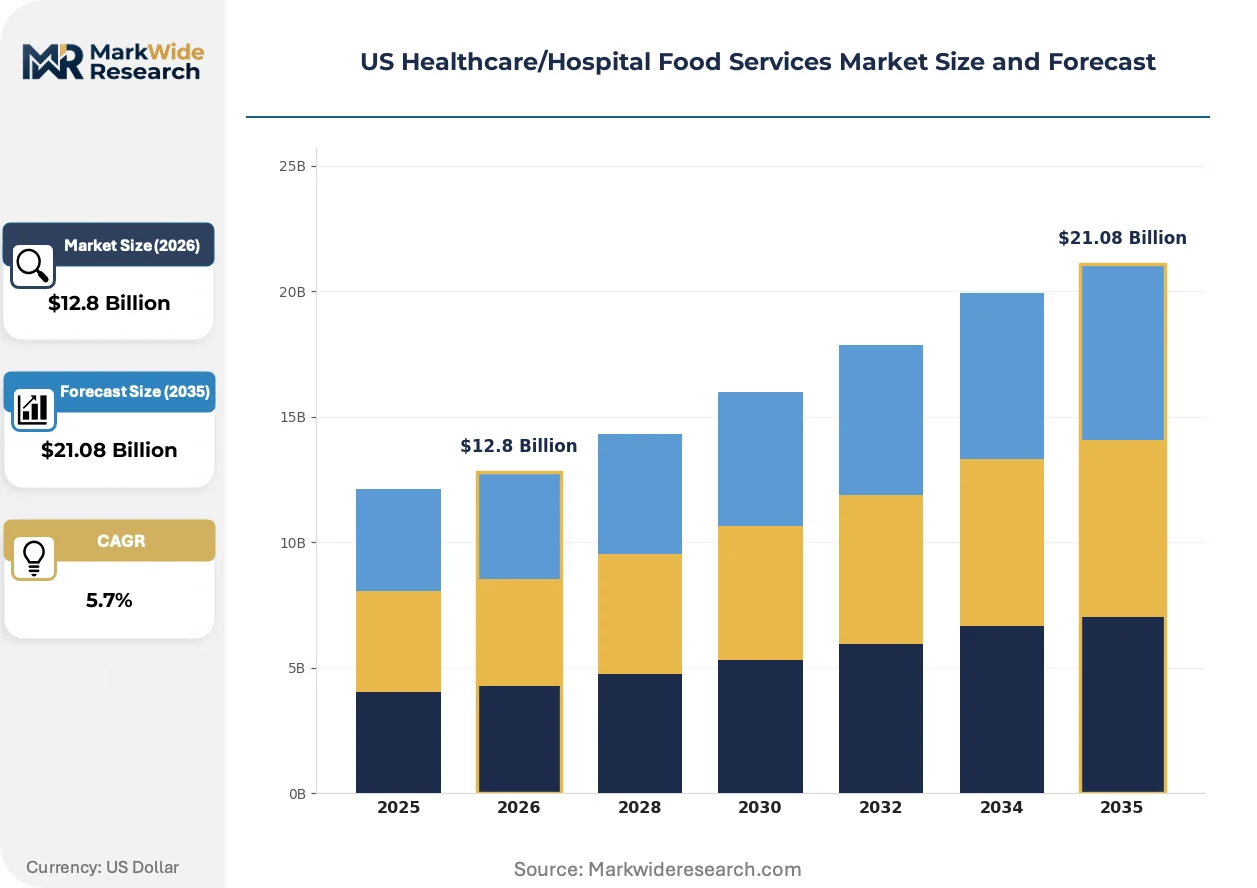
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inpatient, Outpatient, Catering, Nutrition Counseling Delivery Mode: On-site, Off-site, Meal Delivery, Vended Solutions End User: Hospitals, Clinics, Long-term Care Facilities, Dialysis Centers Product Type: Meals, Snacks, Beverages, Supplements |
| Companies Covered | Elior Group, Healthcare Services Group, Compass Group PLC, Morrison Healthcare, Performance Food Group, Sodexo, ISS World, Metz Culinary Management, Aramark, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Healthcare/Hospital Food Services Market Evolving Landscape
Technology deployment in patient dining is accelerating operational efficiency while regulatory pressure on nutrition documentation intensifies compliance requirements across US hospital systems.
Automated meal ordering platforms with bedside tablet interfaces are reducing dietary error rates and labor costs. Acute care hospitals in the Southeast are adopting these systems fastest, driven by nurse staffing constraints. The technology is integrating clinical diet orders directly with kitchen production systems, compressing meal delivery windows and reducing therapeutic diet misalignment.
FDA Food Code updates and Joint Commission accreditation standards are tightening temperature control documentation requirements for prepared food holding. Hospital operators must now maintain continuous digital logs for cold items at 41°F or below and hot service at 135°F or above. Post-acute and skilled nursing facilities face the steepest compliance investment curves as they retrofit aging kitchen infrastructure.
Health system procurement departments are consolidating vendor relationships and demanding outcome metrics linking meal satisfaction to HCAHPS scores. Large integrated delivery networks in Texas and Florida are replacing fragmented local contracts with regional agreements that include dietitian staffing guarantees and patient experience benchmarking. This concentration is most visible in metropolitan hospital clusters where three-meal operational intensity justifies dedicated clinical nutrition personnel.
US Healthcare/Hospital Food Services Market Segmentation
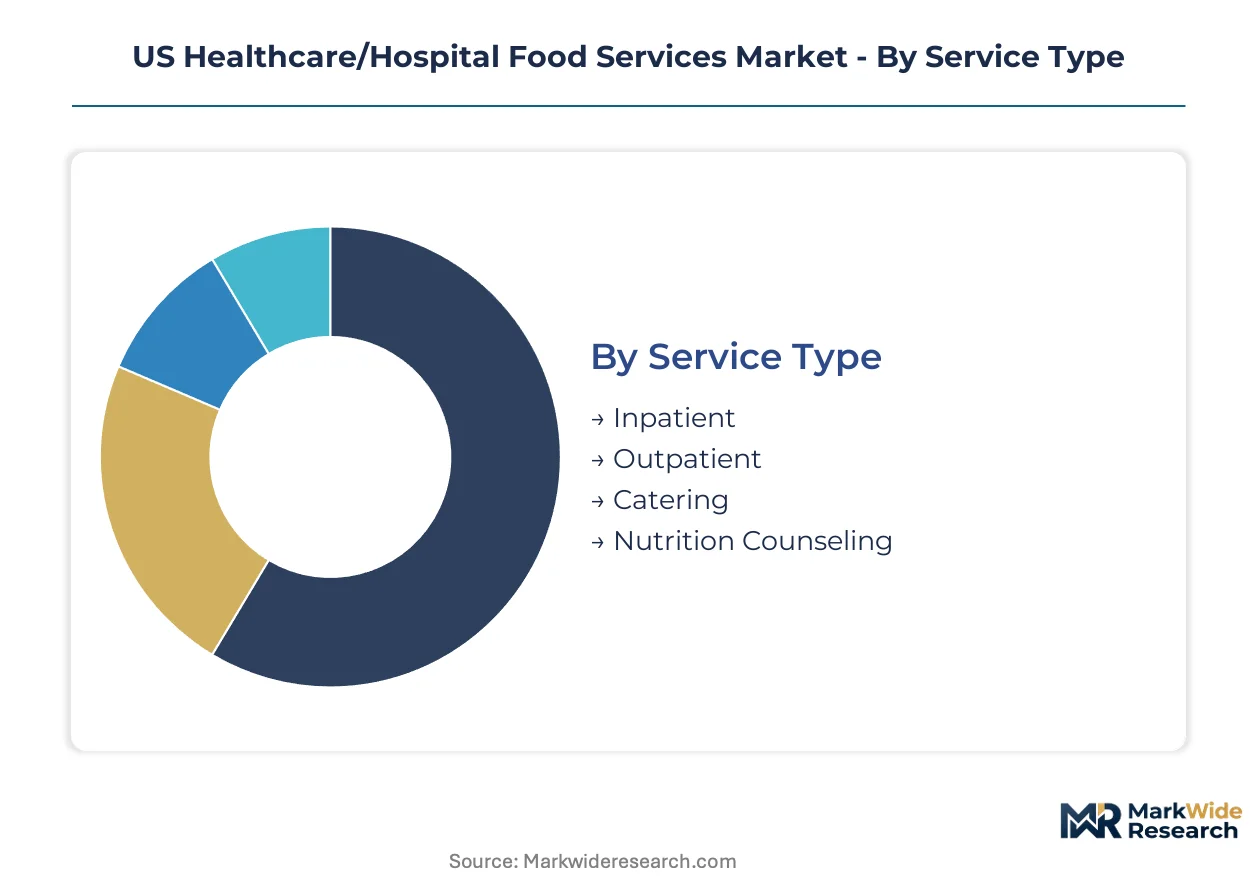
Hospital food service procurement varies sharply by care setting intensity and reimbursement structure. Each segmentation axis reveals distinct operational requirements, capital deployment patterns, and vendor capability thresholds that shape contract economics.
Service Type:
Contract scope and margin structure diverge based on clinical integration depth and meal frequency demands.
- Inpatient:Three-meal daily operations with therapeutic diet modifications require HACCP-certified kitchen infrastructure and embedded registered dietitian staffing. Demand concentrates in acute care hospitals across Texas and Florida health systems, where CMS Conditions of Participation mandate documented nutrition care plans and tie reimbursement to patient satisfaction metrics.
- Nutrition Counseling:Reimbursable preventive care extensions under value-based arrangements drive expansion. Medicare Advantage supplemental benefit pilots in California and Massachusetts are testing condition-specific counseling coverage, creating new revenue streams for vendors with clinical credentialing capabilities.
- Outpatient:Limited meal service tied to same-day procedures and infusion centers, typically operating at lower per-patient contract value with reduced dietetic oversight requirements.
- Catering:Staff and visitor dining with retail substitution pressure from third-party delivery platforms compressing captive market capture rates.
Volume sits with Inpatient; growth tilts toward Nutrition Counseling.
Delivery Mode:
Capital intensity and regulatory exposure separate models requiring kitchen ownership from asset-light alternatives.
- On-site:Full kitchen operations with temperature control infrastructure maintaining 41°F or below for cold items and 135°F or above for hot service. Southeast hospital construction booms favor vendors with regional kitchen footprints and centralized oversight capabilities.
- Off-site:Central commissary production with transport logistics serving multiple facilities. Health system consolidation in Texas metropolitan clusters drives demand for this model, reducing per-site capital requirements while maintaining Joint Commission compliance.
- Meal Delivery:Direct-to-patient distribution for home-bound and post-acute populations, expanding most quickly where medically tailored meal pilots test reimbursement viability.
- Vended Solutions:Refrigerated retail formats with limited fresh preparation, common in outpatient and administrative settings where meal volume cannot justify full kitchen staffing.
Capital deployment favors On-site for anchor facilities; Off-site gains share in consolidated networks.
End User:
Regulatory complexity and reimbursement sophistication determine vendor qualification barriers.
- Hospitals:Acute care facilities with Joint Commission accreditation requirements and FDA Food Code compliance obligations. CMS reimbursement rules tie payments to HCAHPS scores, forcing procurement prioritization of dietetic expertise over pure cost minimization.
- Long-term Care Facilities:Post-acute and skilled nursing settings facing steepest compliance investment curves as they retrofit aging kitchen infrastructure to meet temperature control documentation standards.
- Clinics:Ambulatory settings with limited meal service scope, typically contracting for staff dining or vended solutions rather than patient therapeutic feeding.
- Dialysis Centers:Renal care facilities where capital-intensive kitchen investments prove impractical, creating structural demand for off-site delivery and medically tailored meal programs.
Contract value concentrates in Hospitals; penetration rates climb fastest in Dialysis Centers.
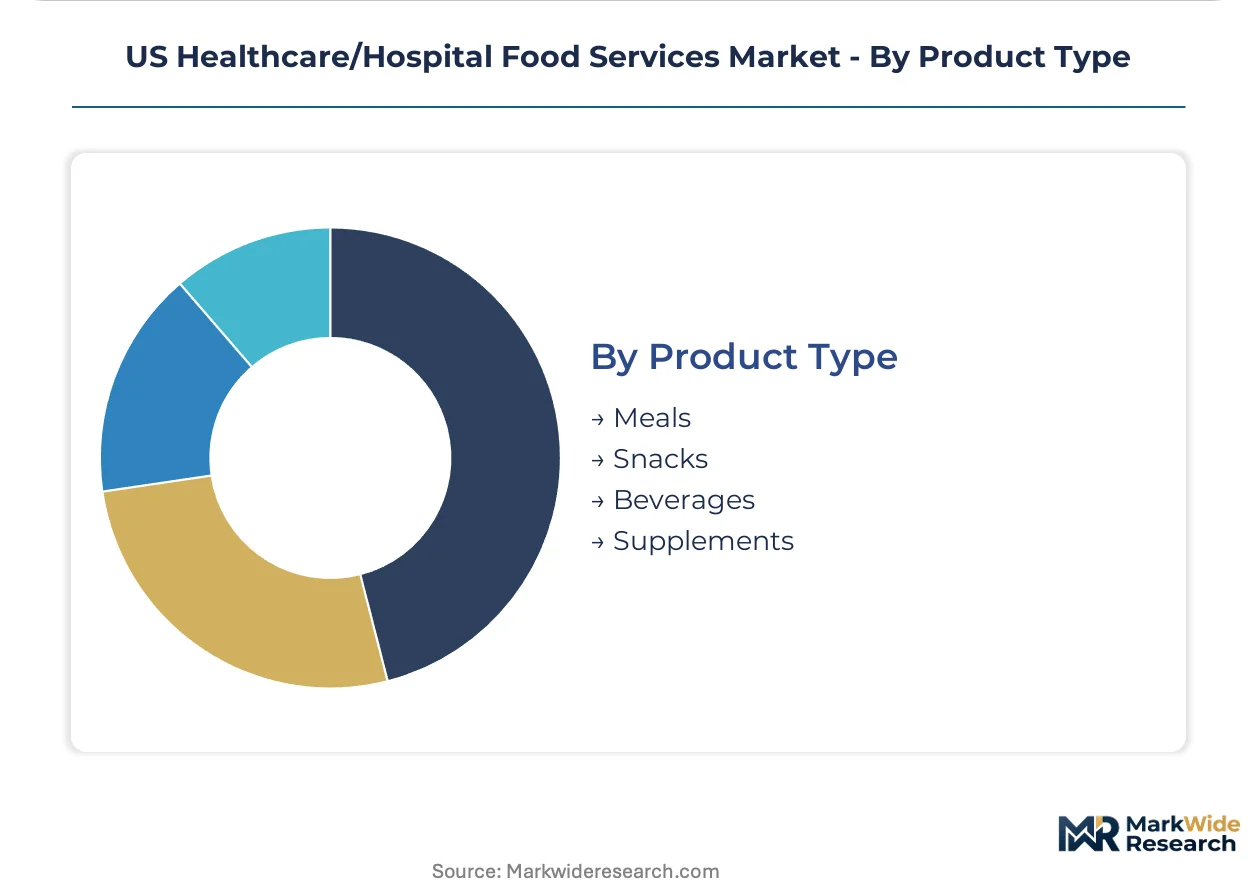
Product Type:
Clinical utility and margin structure vary across therapeutic versus convenience offerings.
- Meals:Therapeutic and regular diet options with dietitian-directed modifications for diabetes, renal, cardiac, and dysphagia protocols. USDA BioPreferred procurement mandates are shifting sourcing priorities toward certified sustainable packaging and cleaner ingredient supply chains.
- Supplements:Oral nutrition support products with clinical evidence requirements for reimbursement eligibility, gaining traction in malnutrition screening protocols tied to value-based care metrics.
- Snacks:Between-meal offerings with limited therapeutic positioning, common in visitor retail and staff dining environments.
- Beverages:Hydration protocols and therapeutic formulations with texture modifications for swallowing disorders, subject to same temperature control requirements as solid food items.
Procurement spend centers on Meals; Supplements demonstrate the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital food service consumption concentrates in states with expanding health system infrastructure, while production capacity clusters around regional commissary networks serving consolidated delivery networks.
Texas
Metropolitan hospital construction in Houston and Dallas-Fort Worth drives contract demand for vendors with centralized kitchen infrastructure. CMS Conditions of Participation enforcement by the Texas Department of State Health Services mandates documented nutrition care plans for acute care licensure. Health system consolidation across the Texas Medical Center and North Texas corridor favors regional food service agreements with embedded dietitian staffing.
Florida
Retirement migration and senior care facility expansion create sustained post-acute meal service demand. The Florida Agency for Health Care Administration inspects skilled nursing kitchen operations under state-specific protocols that exceed federal baselines. Southeast Florida hospital clusters from Miami to West Palm Beach are replacing fragmented local contracts with integrated procurement frameworks.
California
Medicare Advantage supplemental benefit pilots for medically tailored meals test reimbursement models in Los Angeles and San Francisco Bay Area markets. FDA Food Code compliance requirements intersect with state-level organic procurement preferences under California's sustainable purchasing mandates. Northern California health systems are deploying AI-enabled diet optimization platforms linked to electronic health record systems.
Georgia
Atlanta metropolitan hospital expansion and rural critical access facility networks generate bifurcated demand for on-site and off-site delivery models. The Georgia Department of Public Health enforces HACCP certification requirements with variable inspection frequency across urban and rural jurisdictions. Augusta and Savannah health systems are consolidating vendor relationships to capture scale economies in protein and produce procurement.
North Carolina
Research Triangle hospital construction and Duke-UNC health system rivalry intensify competitive bidding for food service contracts with patient experience benchmarking clauses. The North Carolina Department of Health and Human Services coordinates with Joint Commission accreditation surveys for multi-site operators. Charlotte and Raleigh-Durham metropolitan clusters favor vendors with USDA BioPreferred certified supply chains for sustainable packaging compliance.
US Healthcare/Hospital Food Services Market Competitive Landscape
The competitive structure tilts toward diversified food service conglomerates with healthcare-specialized divisions. Tier-one operators leverage multi-site contract consolidation and clinical nutrition staffing guarantees to anchor large health system accounts. Three archetypes dominate: integrated facilities management firms with healthcare verticals, pure-play hospital food service specialists, and broadline food distributors extending into prepared meal service. M&A activity targets regional specialists with established dietitian networks, while technology partnerships accelerate automated ordering platform deployment.
Among diversified service conglomerates, Compass Group PLC, Sodexo, and Aramark occupy positions defined by global supply chain scale and healthcare-specific operational expertise. Compass Group exemplifies the procurement-advantaged archetype through centralized sourcing infrastructure. Sodexo represents technology-forward positioning with patient dining platform integration. Aramark anchors the facilities-integrated model where food service bundles with environmental and clinical support services. Morrison Healthcare and Healthcare Services Group sit within the healthcare-specialist tier, competing through clinical nutrition depth rather than cross-sector diversification. Elior Group and Metz Culinary Management occupy mid-scale positions emphasizing regional kitchen density over national footprint.
| Leading Market Players |
|---|
| Elior Group |
| Healthcare Services Group |
| Compass Group PLC |
| Morrison Healthcare |
| Performance Food Group |
| Sodexo |
| ISS World |
| Metz Culinary Management |
| Aramark |
| Others |
Value Network & Pricing Analysis
Poultry and produce commodity costs cascade through contract tiers, with USDA price volatility compressing margins for fixed-price operators serving Texas and Florida health systems while value-based arrangements with embedded dietitian staffing command premium positioning.
Pricing Analysis
Patient satisfaction outcomes anchor contract valuation, with HCAHPS-linked reimbursement tiers separating vendors with clinical nutrition depth from cost-minimization competitors. Price differentiation rests on Joint Commission accreditation status and registered dietitian staffing ratios. Pricing pressure stems from Medicare Advantage supplemental benefit pilots testing medically tailored meal coverage. Large integrated delivery networks in the Southeast exhibit lowest price sensitivity; rural critical access facilities face acute cost compression.
Supply Chain Analysis
Food waste recovery and sustainable packaging return flows are gaining structural importance under USDA BioPreferred procurement mandates. Protein sourcing concentrates in US poultry processing regions and Midwest grain belts; produce supply draws from California's Central Valley and Florida's winter vegetable operations. Supply chain risk centers on climate-driven commodity price volatility. Distribution runs through regional commissary networks serving consolidated health system clusters.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Health system consolidation across Texas and Florida is forcing subscale regional vendors toward acquisition or exit as multi-hospital contracts demand centralized kitchen infrastructure.
For Market Incumbents: Anchor market position through registered dietitian staffing guarantees and AI-enabled meal ordering platform deployment. Defend against technology-forward competitors by embedding clinical nutrition teams within hospital care coordination workflows. Pursue backward integration into USDA BioPreferred certified packaging supply chains to meet federal purchasing mandates. For New Entrants and Emerging Players: Telehealth-integrated nutrition counseling offers the lowest barrier entry path, targeting Medicare Advantage plans testing condition-specific meal benefit coverage. Dialysis center off-site delivery represents the most penetrable segment where capital-intensive kitchen investments deter established operators. Lead with renal diet specialization and transport logistics expertise. For Investors and Strategic Acquirers: CMS Conditions of Participation enforcement tightening is the leading indicator that clinical nutrition staffing capabilities will separate viable targets from commodity food service operators. Position acquisitions for value-based care expansion over a multi-year horizon. Target regional specialists with established dietitian networks in Southeast and Texas markets. Monitor Medicare Advantage medically tailored meal pilot expansion rates as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Registered Dietitian Staffing Guarantees | CMS Conditions of Participation enforcement makes clinical nutrition staffing mandatory for acute care licensure. |
| AI-Enabled Meal Ordering Platform | FDA Food Code temperature documentation requirements drive adoption of automated compliance logging systems. |
| USDA BioPreferred Certification | Federal purchasing preferences create positioning advantages in health system procurement consolidation. |
| Regional Commissary Network Expansion | Texas and Florida health system consolidation favors vendors with centralized kitchen infrastructure. |
| Medically Tailored Meal Program Development | Medicare Advantage supplemental benefit pilots in California and Massachusetts test reimbursement viability. |
Research Methodology
Independent corroboration across hospital food service directors, GPO contracts managers, and registered dietitian leads underwrites the qualitative findings. Primary fieldwork encompassed supply chain directors at diversified service conglomerates, procurement officers at Texas Medical Center facilities, and sustainability leads implementing USDA BioPreferred mandates. Secondary validation drew from CMS Conditions of Participation filings, FDA Food Code enforcement records, and hospital construction permit databases. Bottom-up contract value estimates triangulated against top-down health system expenditure disclosures.
Comparable historical periods anchored the projection framework across the modeling period. Segmentation dimensions encompassed service type intensity, delivery mode capital requirements, end-user regulatory complexity, and product clinical utility. CAGRs derived from trend extrapolation of health system consolidation rates, Medicare Advantage enrollment shifts, and construction pipeline activity. Forecast inputs incorporated registered dietitian labor market tightness and protein commodity price volatility indices.
The model holds under sustained health system consolidation and CMS reimbursement rule stability; deviation in Medicare Advantage benefit classification or federal procurement mandate enforcement would shift contract value distribution. Forecasts reflect assumptions regarding technology adoption curves and regulatory inspection intensity. Practitioners should monitor Medicare Advantage medically tailored meal pilot expansion and USDA commodity price reports for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Germany Foodservice Market
Food Service
West Africa Food Services Market
Food Service
Tabletop Pizza Oven Market
Food Service
Portable Buffet and Drop-In Ranges Market
Food Service
Russia Foodservice Market
Food Service
Malaysia Food Service Market
Food Service
Quick-Service Restaurants Market
Food Service
Steam Stew Pot Market
Food Service
North America Food Service Disposable Market
Food Service
Restaurant Glassware Market
Food Service
Cambodia Foodservice Market
Food Service
Contract Blending Services Market
Food Service
South Korea Foodservice Market
Food Service
Thailand Food Service Market
Food Service
GCC Biodegradable Food Service Disposables Market
Food Service
Global Dark Store Market