
 Global Online Food Ordering Market | 2026-2036
Global Online Food Ordering Market Size, Share, and Industry Trends Forecast 2026-2036
Global Online Food Ordering Market Foresight
Subscription bundling of meals with grocery and convenience items is consolidating buyer choice around super-app ecosystems. DoorDash leverages its logistics infrastructure to anchor restaurant delivery alongside retail verticals. Uber Eats competes through membership programs that sustain cross-category purchasing frequency. Meituan dominates the Chinese market with hyperlocal services that extend into pharmacy and fresh produce delivery.
Online food ordering encompasses digital platforms that match consumers with foodservice providers through algorithmic routing, real-time inventory APIs, and GPS-tracked last-mile fulfillment. These systems operate on commission-based revenue models that extract value per transaction while optimizing driver dispatch through machine learning. Platform-based services and aggregator models currently occupy the largest revenue pools, though delivery-only kitchens are capturing margin expansion as fixed-cost restaurant operations face rent inflation. Mobile apps lead order channels by transaction volume, while voice ordering and chatbot interfaces represent emerging interfaces for repeat-purchase scenarios.
The EU Digital Services Act and GDPR impose transparency obligations on algorithmic recommendation systems and consumer data handling across European operations. The FDA's Food Code provisions and state-level cottage food laws in the US shape hygiene standards for cloud kitchen entrants and home-based food sellers. Stakeholders must monitor how platform liability frameworks evolve as regulators distinguish between marketplace intermediaries and vertically integrated delivery operators.
Market Dynamics
Platform commission compression and algorithmic labor classification disputes are restructuring unit economics across delivery ecosystems, forcing operators to rebalance driver costs against merchant retention incentives.
Growth Catalysts
- EU Digital Services Act transparency mandates:Algorithmic disclosure requirements for recommendation engines are reducing information asymmetry between restaurants and platforms, enabling data-driven contract negotiations.
- India's tier-two urban penetration:Deepening delivery network coverage in secondary cities is unlocking latent demand from time-constrained working households previously underserved by organized foodservice.
- Cloud kitchen infrastructure:Modular production facilities with shared logistics backends are lowering capital barriers for restaurant entrepreneurs entering delivery-native formats.
Market Restraints
- Fuel price volatility:Driver compensation models tied to per-mile reimbursements expose platforms to diesel and gasoline cost swings that compress already thin contribution margins.
- GDPR data localization:Cross-border transfer restrictions on consumer ordering histories complicate centralized demand forecasting and personalization engine training for EU operations.
- Prepared meal kit substitution:Direct-to-consumer subscription services with pre-portioned ingredients are capturing occasion-based demand from convenience-oriented households.
Strategic Opportunities
- Brazil's underpenetrated northeast corridor:São Paulo-saturated operators face whitespace in Salvador and Recife where smartphone penetration now supports app-based ordering infrastructure.
- Voice-to-order convergence:Smart speaker integration with restaurant POS systems is creating hands-free reordering pathways for habitual purchase scenarios.
- India PLI scheme extension:Potential inclusion of cold-chain logistics equipment under production-linked incentives would reduce refrigerated vehicle acquisition costs for fleet operators.
Industry Challenges
- Algorithmic wage dispute litigation:Courts in California, the United Kingdom, and the Netherlands are delivering conflicting rulings on driver employment status, creating jurisdictional compliance fragmentation.
- Cloud kitchen fire code compliance:Municipal zoning boards in dense urban districts are retroactively applying commercial kitchen ventilation standards to delivery-only facilities, triggering costly retrofit cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Online Food Ordering Market |
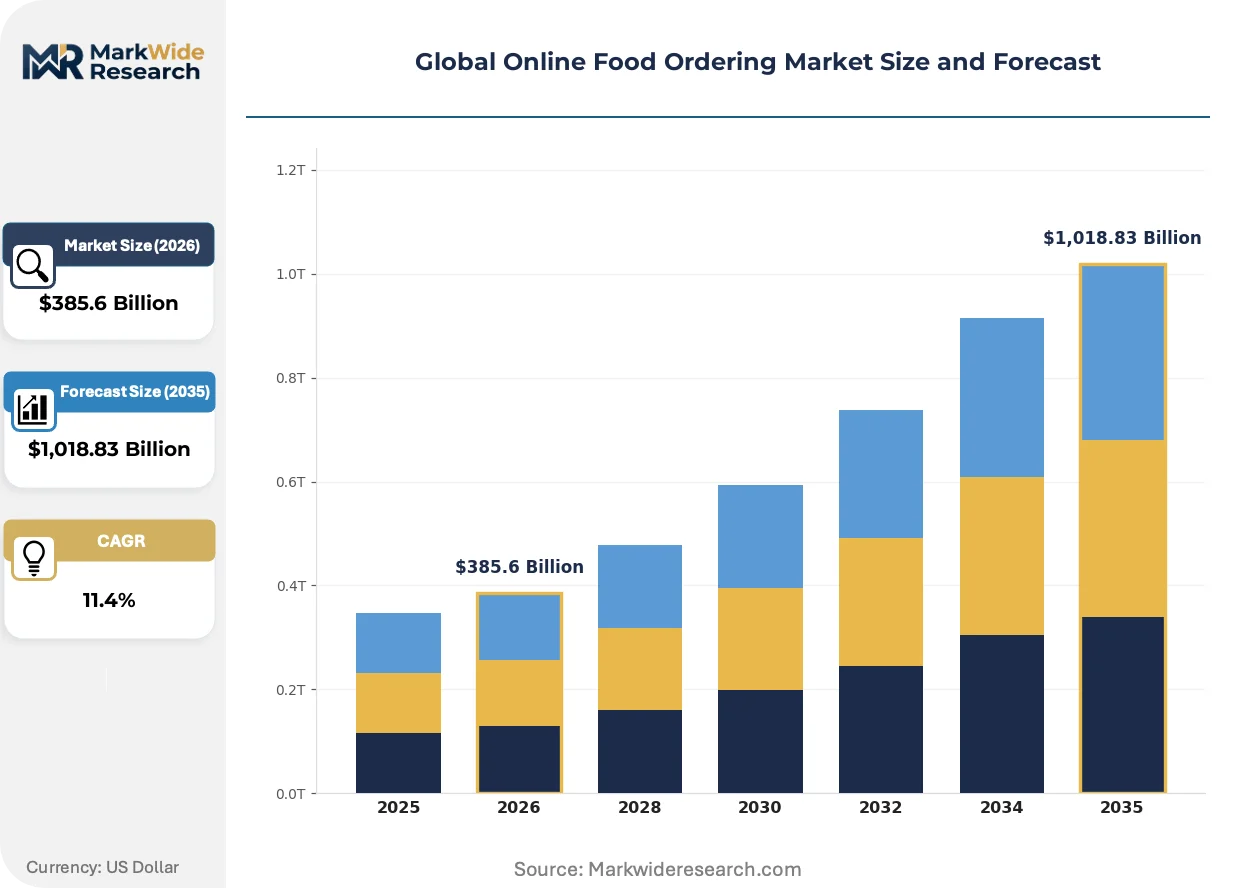
| Market Size in 2026 | $385.6 Billion |
| Market Size in 2035 | $1,018.83 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Platform-Based, Aggregator Model, Delivery-Only Kitchens, Subscription Services, Hyperlocal Delivery Customer Type: Individual Consumers, Corporate Clients, Meal Subscription Users, Event Catering Clients, Group Ordering Customers Order Channel: Mobile App, Website, Third-Party Marketplace, Voice Ordering, Social Media Integration, Chatbots Food Category: Fast Food, Gourmet Cuisine, Healthy Meals, Ethnic Dishes, Desserts, Beverages |
| Companies Covered | DoorDash, Uber Eats, Delivery Hero, Just Eat Takeaway, Grubhub, Deliveroo, Meituan, Ele.me, Zomato, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Online Food Ordering Market Shifts & Advancements
Operational automation and predictive logistics are compressing delivery windows while regulatory scrutiny of platform labor models intensifies across multiple jurisdictions.
Dark store micro-fulfillment networks are expanding into prepared food categories previously reserved for restaurant kitchens. Grocery retailers in South Korea and Mexico are retrofitting automated picking infrastructure to handle hot-meal assembly alongside ambient inventory. This convergence is expanding into 15-minute delivery promises for fresh-cooked items, collapsing the historical separation between restaurant and retail supply chains.
The EU AI Act risk classification framework is imposing documentation burdens on algorithmic dispatch systems that optimize driver routes. Platforms operating across Germany, France, and Italy must now maintain audit trails for machine learning models affecting worker earnings. High-risk system designations are prompting engineering teams to build explainability layers that slow iteration cycles but reduce litigation exposure.
Corporate procurement departments are consolidating meal allowances into platform-agnostic subscription credits. Employees at technology and financial services firms in Singapore and the United Arab Emirates now receive monthly dining budgets redeemable across multiple aggregator apps rather than single-platform corporate accounts. This purchasing flexibility is fragmenting enterprise contract values while raising switching frequency among individual users.
Global Online Food Ordering Market Segmentation
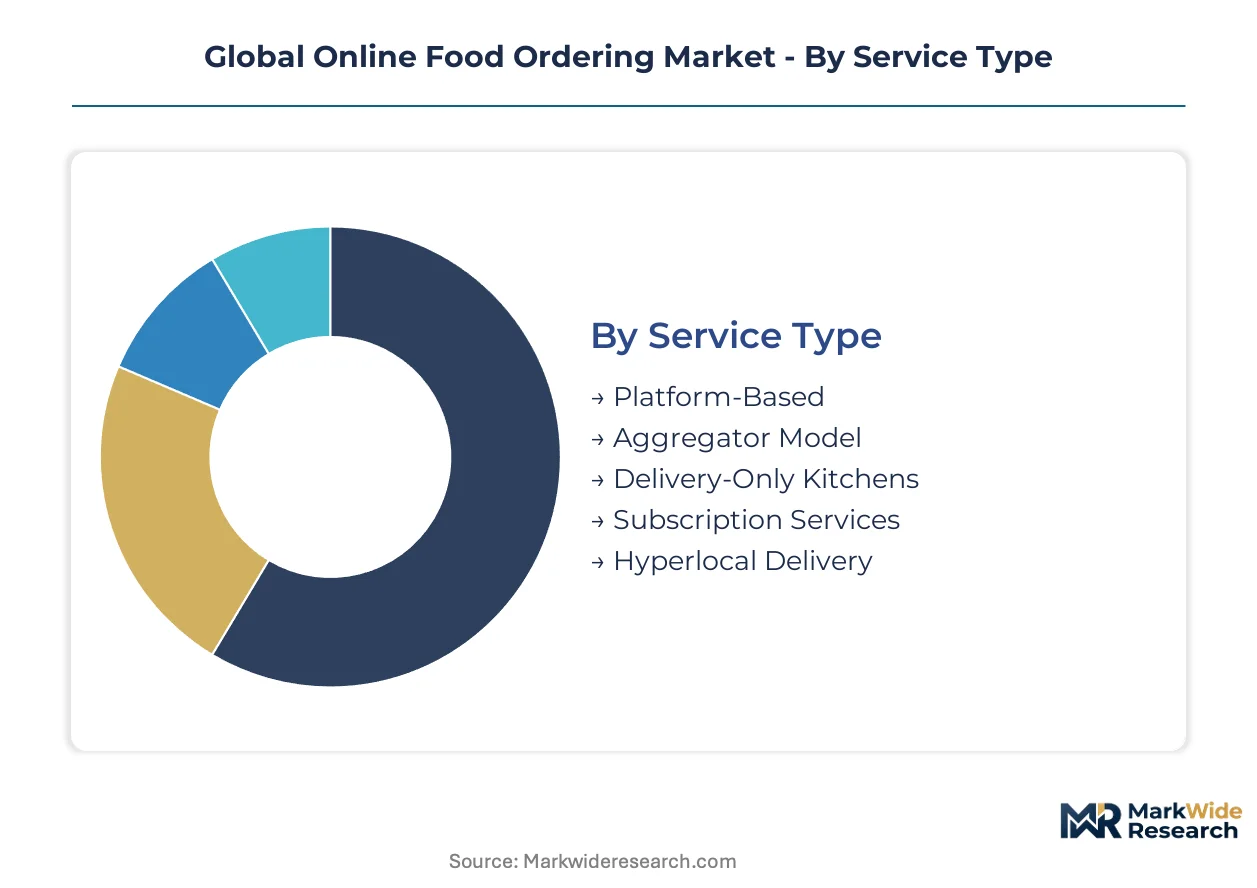
Online food ordering segments fragment across service models, customer archetypes, and interface technologies that each demand distinct logistics configurations and commission structures. Understanding these divisions reveals where platform investments concentrate and which revenue pools resist commoditization.
Service Type:
Capital intensity and asset ownership separate winners from margin-squeezed operators in this dimension.
- Platform-Based:Asset-light marketplace models match consumers with existing restaurants through algorithmic routing, capturing value via per-transaction commissions without kitchen capital exposure. Demand concentrates in dense urban corridors across India, Brazil, and Mexico where restaurant supply outstrips organized delivery infrastructure.
- Aggregator Model:Multi-restaurant interfaces consolidate menu discovery and payment processing while outsourcing fulfillment to contracted fleets, optimizing for order frequency through subscription lock-in. Corporate procurement departments in Singapore and the United Arab Emirates now mandate aggregator-agnostic credits, fragmenting enterprise contract concentration.
- Delivery-Only Kitchens:Modular production facilities eliminate front-of-house costs, enabling cuisine specialization at lower rent per square foot.
- Subscription Services:Recurring revenue models stabilize demand forecasting for operators willing to trade margin for predictability.
- Hyperlocal Delivery:Sub-15-minute promises require inventory positioning within 2 kilometers of demand clusters, constraining menu breadth.
Volume sits with Aggregator Model operators; growth tilts toward Delivery-Only Kitchens as rent inflation erodes full-service restaurant economics.
Customer Type:
Purchase frequency and average order value diverge sharply across these cohorts, forcing distinct retention economics.
- Individual Consumers:Occasion-driven ordering with high price sensitivity and platform-switching propensity, sustained through gamified loyalty programs and personalized push notifications. Time-constrained working households in India's tier-two cities now drive the steepest expansion trajectory as delivery networks deepen penetration.
- Corporate Clients:Consolidated meal allowances with negotiated platform contracts and centralized billing, prioritizing receipt integration and dietary compliance over unit price.
- Meal Subscription Users:Pre-committed weekly orders with predictable prep windows, enabling kitchen capacity optimization.
- Event Catering Clients:Large-batch, scheduled-delivery requirements with quality assurance protocols distinct from individual order fulfillment.
- Group Ordering Customers:Split-payment functionality and coordination tools that reduce friction for office lunch and social occasion aggregation.
Revenue concentrates with Individual Consumers; margin expansion favors Corporate Clients as procurement centralization accelerates.
Order Channel:
Interface choice reflects customer lifecycle stage and technological accessibility constraints.
- Mobile App:Dominant transaction volume channel with biometric payment integration and GPS-enabled real-time tracking, requiring continuous UX investment to reduce cart abandonment. South Korean and Mexican grocery retailers now retrofit app infrastructure for hot-meal assembly alongside ambient inventory.
- Website:Higher average order values from desktop users planning meals in advance, declining share as mobile penetration deepens.
- Third-Party Marketplace:Discovery-driven traffic from super-app ecosystems that bundle food with grocery and convenience purchasing.
- Voice Ordering:Hands-free reordering pathways for habitual purchase scenarios, dependent on smart speaker household penetration.
- Social Media Integration:Impulse conversion from influencer content and native checkout without platform switching.
- Chatbots:Text-based interaction for customer service resolution and order modification, reducing human agent costs.
Transaction volume flows through Mobile App; Voice Ordering gains share fastest among repeat-purchase customer segments.
Food Category:
Preparation complexity and perishability dictate logistics requirements and platform commission tolerance.
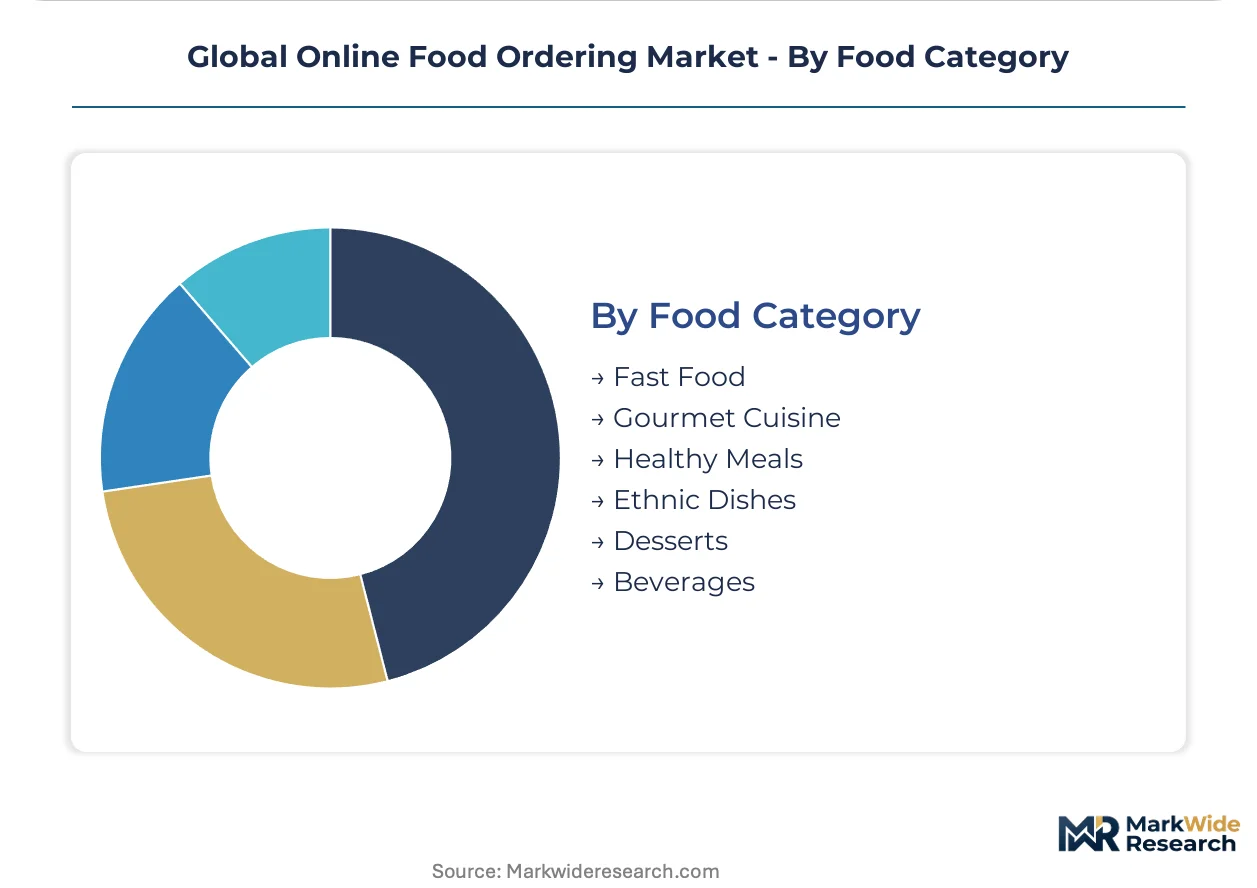
- Fast Food:Standardized production with extended hold times, enabling batched dispatch and driver multi-apping without quality degradation. Cloud kitchen operators in Brazil's northeast corridor target this category for entry given lower culinary skill barriers.
- Gourmet Cuisine:Temperature-sensitive plating requirements and higher customer expectations for packaging integrity, justifying premium delivery fees.
- Healthy Meals:Ingredient transparency demands and dietary restriction accommodations that increase order customization complexity.
- Ethnic Dishes:Niche cuisine availability that drives platform differentiation in culturally diverse metropolitan areas.
- Desserts:Time-critical fulfillment windows and specialized packaging for temperature and structural integrity.
- Beverages:Spill-risk logistics and ice-preservation requirements that constrain delivery radius.
Order frequency peaks with Fast Food; margin expansion clusters around Gourmet Cuisine as willingness-to-pay differentiates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Bangalore and Shenzhen have concentrated cloud kitchen infrastructure investment, drawing logistics operators seeking tax-advantaged production capacity near dense urban demand clusters.
United States
Corporate meal program adoption and subscription bundling sustain order volume concentration in metropolitan corridors. The FDA's Food Code provisions shape hygiene compliance standards for cloud kitchen entrants expanding delivery-native formats. Los Angeles and New York City anchor dark store micro-fulfillment networks that collapse retail-restaurant supply chain separation.
China
Hyperlocal service integration and 15-minute delivery promises drive platform ecosystem consolidation around super-app architectures. SAMR oversight of algorithmic pricing and the MIIT's data governance frameworks constrain centralized demand forecasting operations. The Yangtze River Delta manufacturing belt supplies automated picking infrastructure retrofitting grocery retailers for hot-meal assembly.
India
Tier-two city penetration and time-constrained working household demand unlock latent growth in secondary urban markets. The FSSAI's food safety licensing requirements and potential PLI scheme extension for cold-chain logistics equipment reduce refrigerated fleet acquisition costs. Bangalore's special economic zone concentration attracts cloud kitchen operators seeking tax-advantaged production capacity near IT corridor demand.
Germany
Algorithmic transparency mandates and corporate procurement centralization reshape platform-restaurant contract negotiations. The EU AI Act risk classification framework and GDPR data localization requirements impose documentation burdens on dispatch optimization systems. Berlin's dense urban zoning boards apply retroactive commercial kitchen ventilation standards to delivery-only facilities, triggering costly compliance retrofits.
Brazil
Smartphone penetration thresholds now support app-based ordering infrastructure in previously underserved northeastern metros. ANVISA's food safety protocols govern cloud kitchen entry standards for delivery-native restaurant entrepreneurs. Salvador and Recife represent whitespace expansion targets as São Paulo-saturated operators seek growth beyond saturated southeastern corridors.
Global Online Food Ordering Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure that tilts toward consolidation at the top and fragmentation among regional challengers. Asset-light marketplace operators extract per-transaction commissions without kitchen capital exposure, while vertically integrated delivery operators absorb fleet and real estate costs for margin control. Three archetypes dominate: logistics-anchored super-apps bundling cross-category services, cuisine-specialized cloud kitchen operators, and aggregator platforms optimizing for order frequency through subscription lock-in. Competitive moves concentrate on geographic whitespace expansion and regulatory compliance architecture that anticipates algorithmic labor classification disputes.
Among North American logistics-anchored platforms, DoorDash and Uber Eats exemplify the super-app archetype extending delivery infrastructure across retail verticals beyond restaurant meals. Delivery Hero occupies a position representing European-aggregator consolidation, spanning multiple continental markets through portfolio diversification. Meituan anchors the hyperlocal integration archetype in China, where pharmacy and fresh produce delivery converge with food ordering within unified platform ecosystems. These three entities represent distinct strategic responses to commission compression and driver cost inflation pressures reshaping unit economics globally.
| Leading Market Players |
|---|
| DoorDash |
| Uber Eats |
| Delivery Hero |
| Just Eat Takeaway |
| Grubhub |
| Deliveroo |
| Meituan |
| Ele.me |
| Zomato |
| Others |
Supply & Pricing Matrix
Driver fleet concentration in India's tier-two urban corridors amplifies labor-cost differentials between metropolitan and secondary city operations, widening the spread between premium hyperlocal delivery pricing and economy-tier aggregator commissions. Platform operators absorb these workforce disparities through dynamic zone-based pricing that shifts cost burdens across customer segments.
Pricing Analysis
Lead-time compression commands premium pricing tiers, with sub-15-minute delivery promises sustaining 20-40 percent fee markups over standard 30-45 minute windows. The dominant structure stratifies across premium, standard, and economy tiers differentiated by delivery velocity, order bundling flexibility, and subscription membership status. Pricing pressure stems from fuel reimbursement volatility tied to diesel cost swings, compressing contribution margins in per-mile driver compensation models. Individual consumers exhibit highest price sensitivity, while corporate procurement departments prioritize billing integration and dietary compliance over unit economics.
Supply Chain Analysis
Dual-sourcing mandates from enterprise clients require platform operators to qualify multiple cloud kitchen networks and logistics fleets within each service zone, preventing single-supplier dependency. Supply concentration centers on China for automated picking infrastructure, India for cold-chain vehicle assembly under PLI incentives, and South Korea for dark store micro-fulfillment retrofitting. Critical inputs span refrigerated fleet assets, algorithmic dispatch software licenses, and last-mile thermal packaging. Tariff exposure on Chinese automation equipment presents structural vulnerability. Distribution runs through hub-and-spoke logistics networks anchored in special economic zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over cloud kitchen real estate and captive driver fleets determines margin capture. Players are pursuing backward integration into production capacity to escape commission compression.
For Market Incumbents: Hedge against algorithmic labor reclassification risks by diversifying workforce models across employed, contracted, and third-party logistics layers. Consolidate cloud kitchen positions in Bangalore and Shenzhen special economic zones to lock in tax-advantaged production capacity. Reinforce subscription lock-in through cross-category bundling that raises switching costs for habitual users.
For New Entrants and Emerging Players: Enter via Brazil's northeastern corridor where Salvador and Recife present whitespace below São Paulo saturation thresholds. Target tier-two Indian cities with localized cuisine specialization that incumbent aggregators underserve. Deploy voice-to-order integration as a go-to-market wedge to capture habitual reordering occasions before smart speaker penetration matures.
For Investors and Strategic Acquirers: Re-rating potential sits with cuisine-specialized cloud kitchen operators given regulatory tailwinds for delivery-native formats and rent inflation eroding full-service restaurant economics. Long-term viability favors assets with modular production facilities and multi-zone logistics qualifications. Watch EU AI Act enforcement intensity as the inflection signal for compliance cost escalation that favors scaled platforms over fragmented challengers.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Kitchen Network Expansion | Modular facilities in Bangalore SEZs reduce front-of-house costs while capturing IT corridor demand density. |
| Voice-to-Order Platform Integration | Smart speaker POS connectivity creates hands-free pathways for habitual purchase scenarios. |
| Cold-Chain Fleet Acquisition | PLI scheme eligibility for refrigerated vehicles lowers capital barriers for tier-two network penetration. |
| Algorithmic Explainability Investment | EU AI Act documentation requirements favor engineered audit trails that reduce litigation exposure. |
| Aggregator-Agnostic Corporate Credits | Platform-agnostic subscription budgets fragment enterprise concentration while raising user switching frequency. |
Research Methodology
Multi-period observation of commission rate trajectories, driver supply elasticity, and cloud kitchen capacity utilization anchored the trend analysis, supplemented by interviews with platform operations executives, restaurant franchise development leads, logistics fleet managers, and corporate procurement officers. Secondary validation drew from FSSAI licensing databases, EU Digital Services Act implementation guidance, SEC filings of listed aggregator platforms, and customs records for cold-chain equipment imports. Bottom-up restaurant supply counts and top-down consumer expenditure estimates were triangulated against transaction volume disclosures.
Segment-weighting across service type, customer archetype, order channel, and food category dimensions informed the analytical framework across the projection horizon. CAGRs were derived from logistic diffusion curves fitted to smartphone penetration thresholds and delivery network coverage expansion. Modeled inputs incorporated fuel price volatility scenarios, algorithmic wage dispute litigation outcomes, and cloud kitchen fire code compliance cost cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden regulatory reclassification of driver employment status or abrupt cold-chain equipment tariff adjustments. Deviation in EU AI Act enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Saudi Arabia Full- Service Restaurants Market
Food Service
Commercial Grills Market
Food Service
US Food Service Market
Food Service
Qatar Food Service Market
Food Service
Smart Food Logistics Market
Food Service
Street Vendors Market
Food Service
Meal Voucher Market
Food Service
Mexico Foodservice Market
Food Service
Cambodia Foodservice Market
Food Service
Fast Food Market
Food Service
China Online Food Delivery Market
Food Service
North America Online Grocery Delivery Market
Food Service
Europe Out of Home (OOH) Delivery Market
Food Service
GCC Online Grocery Market
Food Service
Clear Ice Maker Market
Food Service
Middle East Smokeless Indoor Grills Market