
 United Kingdom Cafes & Bars Market | 2026-2036
United Kingdom Cafes & Bars Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Cafes & Bars Market Insights
Modular beverage-and-food bundling is realigning how UK consumers construct their cafe visits, shifting from single-item purchases toward customizable meal deals and subscription formats. Costa Coffee leverages its drive-through network to anchor suburban convenience patterns. JD Wetherspoon plc competes on price-fixed meal bundles across its pub estate. Pret A Manger specializes in grab-and-go bundled breakfast combinations that dominate commuter rail hubs.
United Kingdom cafes and bars comprise licensed and unlicensed hospitality venues serving prepared beverages and light food for on-premise or immediate consumption, operating under strict food safety management systems with documented hazard analysis critical control points protocols. The primary commercial purpose centers on delivering repeatable, location-bound refreshment experiences with high visit frequency and short transaction cycles. Coffee Shops lead service type revenue generation through morning peak traffic and all-day workspace demand. Fast Casual captures the fastest-growing position as hybrid formats merge counter-service speed with elevated ingredient provenance. Millennials represent the core customer type, concentrating spending in digitally native brands with app-based loyalty mechanics.
The Food Standards Agency enforces allergen disclosure and hygiene rating schemes that directly shape menu architecture and kitchen operational design across UK hospitality premises. Environmental Health Officers at local authority level conduct unannounced inspections that determine consumer-facing scores, creating market access barriers for operators unable to maintain consistent compliance standards. Local alcohol licensing boards under the Licensing Act 2003 control trading hours and premises permissions, constraining expansion velocity in saturated high streets. Stakeholders must monitor evolving extended producer responsibility packaging regulations and anticipate how deposit return scheme implementation will alter supply chain cost structures for beverage-led operators.
Market Dynamics
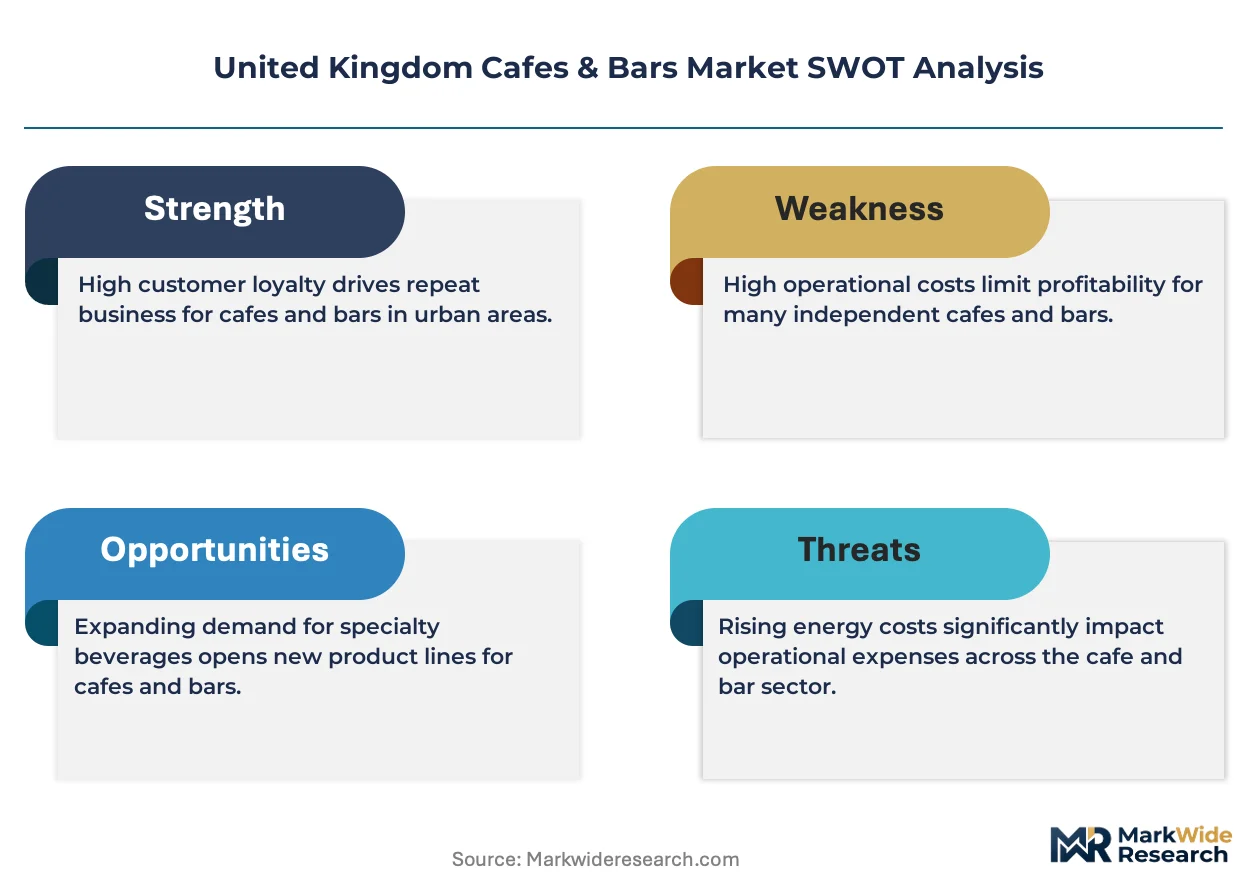
The Food Standards Agency's allergen disclosure mandates and extended producer responsibility packaging regulations are compressing operational margins while forcing capital redeployment toward compliance infrastructure across UK hospitality premises.
Growth Catalysts
- Remote work normalization:Urban professionals now treat cafes as secondary offices, extending dwell times and driving all-day beverage consumption patterns across Greater London and Manchester city centers.
- The UK Soft Drinks Industry Levy:This sugar tax framework is accelerating reformulation investment, opening premium positioning for reduced-sugar specialty beverages that command higher per-unit margins.
- Drive-through format expansion:Suburban convenience demand is pulling infrastructure investment away from traditional high-street footprints toward roadside accessibility models.
Market Restraints
- Arabica coffee price volatility:Input cost instability from Brazilian and Colombian harvest cycles squeezes gross margins for espresso-dependent operators unable to pass through increases.
- Local authority licensing concentration:saturated high streets in Westminster, Camden, and Manchester face moratorium pressures from Licensing Act 2003 boards, constraining greenfield site approvals.
- Energy cost pass-through limitations:Commercial electricity tariffs for refrigeration and HVAC systems outpace menu pricing elasticity, compressing net operating income.
Strategic Opportunities
- Deposit Return Scheme implementation:The anticipated 2025 rollout creates first-mover advantage for operators designing reverse-logistics partnerships with packaging suppliers.
- Subscription loyalty mechanics:App-based prepaid beverage clubs are capturing commuter rail hub traffic that previously flowed through transactional grab-and-go purchases.
- Fast Casual format convergence:Hybrid counter-service models merging coffee specialization with elevated food provenance represent underpenetrated white space in secondary UK cities.
Industry Challenges
- Environmental Health Officer rating volatility:Unannounced inspection schedules and subjective scoring criteria create compliance uncertainty that disrupts marketing investments tied to hygiene score displays.
- Barista skill scarcity:Specialized espresso preparation expertise concentrates in Greater London, limiting service consistency for regional expansion chains.
- Legacy POS integration friction:Kitchen display system upgrades required for real-time allergen tracking conflict with installed payment terminal infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Cafes & Bars Market |
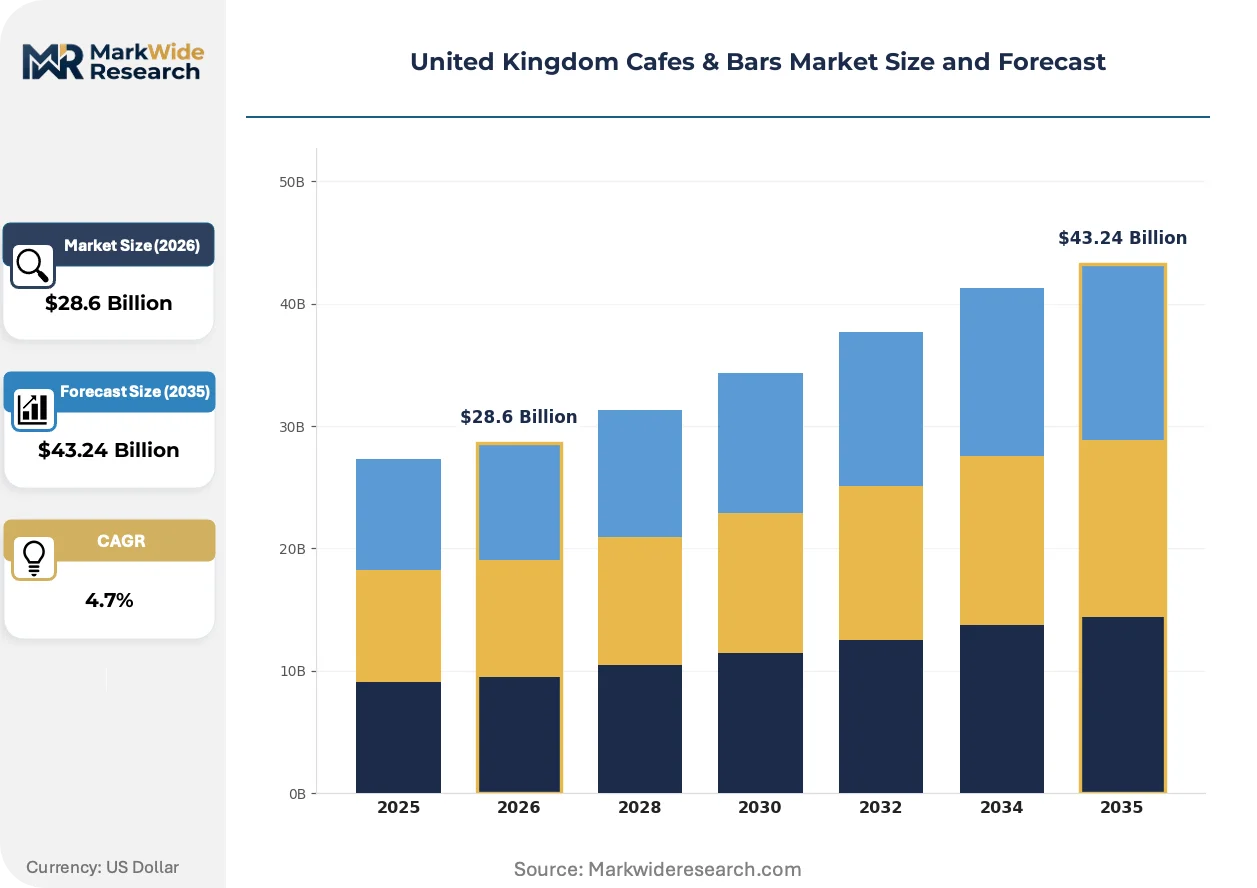
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Coffee Shops, Wine Bars, Cocktail Lounges, Fast Casual Customer Type: Millennials, Families, Professionals, Students Product Offerings: Non-Alcoholic Beverages, Craft Beers, Artisan Breads, Light Snacks Ambiance: Casual Dining, Cozy Atmosphere, Outdoor Seating, Live Music |
| Companies Covered | Costa Coffee, Stonegate Group, JD Wetherspoon plc, Caffè Nero Group Ltd, Starbucks Corporation, Pret A Manger, Greggs, Loungers, Coffee#1, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Cafes & Bars Market Trends and Innovations
Digital ordering infrastructure and regulatory compliance automation are converging to reshape how UK cafes manage throughput, labor deployment, and customer data capture simultaneously.
Mobile order-ahead platforms is unifying payment, loyalty accrual, and production queue management into single-interface workflows. Commuter-dense operators in London's financial district are adopting these systems fastest. This convergence is compressing transaction times while shifting labor allocation from cashier functions toward beverage preparation.
The Food Standards Agency's Natasha's Law mandates full ingredient labeling for pre-packed for direct sale foods. This regulation forces kitchen reconfiguration toward centralized prep facilities with compliant labeling infrastructure. Grab-and-go specialists operating rail hub locations face the steepest compliance capex requirements.
Workspace-as-amenity consumption is displacing pure refreshment purchasing across urban cafe formats. Freelancers and remote employees now select venues based on power outlet density, WiFi reliability, and seating ergonomics rather than beverage quality alone. This behavioral shift concentrates in Manchester's Northern Quarter and Bristol's Harbourside clusters.
United Kingdom Cafes & Bars Market Segmentation
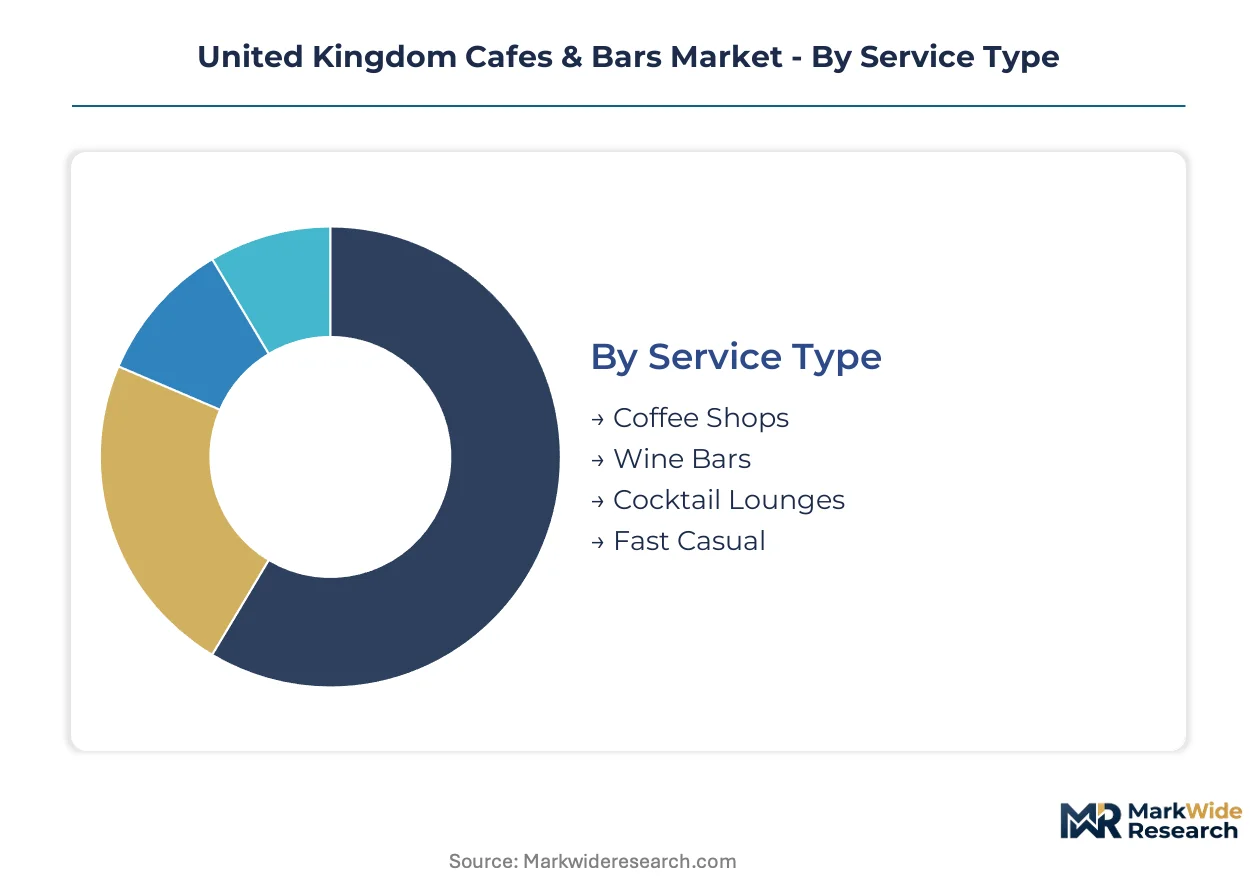
United Kingdom cafes and bars operate across distinct service formats, customer demographics, and experiential positioning that determine capital deployment patterns and margin structures. Each segment carries unique regulatory burdens, from alcohol licensing to food safety protocols, that reshape competitive dynamics across urban and suburban locations.
Service Type:
Supply concentration in Greater London and Manchester favors formats with scalable operational models and repeatable site economics.
- Coffee Shops:Espresso-based beverage preparation dominates morning peak traffic with standardized equipment configurations enabling rapid unit expansion. Demand concentrates in commuter rail corridors and financial districts where workspace-as-amenity positioning extends dwell times. The Food Standards Agency's allergen disclosure mandates force kitchen reconfiguration toward centralized prep facilities with compliant labeling infrastructure.
- Fast Casual:Hybrid counter-service models merge coffee specialization with elevated food provenance, capturing suburban convenience demand through drive-through expansion. Greater London's specialty coffee corridor anchors initial penetration, with secondary UK cities representing underpenetrated white space for format replication.
- Wine Bars:Evening-focused licensed premises operating under Local Authority licensing board constraints with concentrated trading hour permissions. Westminster and Camden saturation creates moratorium pressures that constrain greenfield approvals.
- Cocktail Lounges:Premium spirits-led formats requiring specialized bartender expertise and extended alcohol licensing compliance. Manchester's Northern Quarter cluster demonstrates concentration of skilled labor pools.
Coffee Shops absorb the bulk of installed capacity; Fast Casual is expanding most quickly.
Customer Type:
Cost tier differentiation separates high-frequency commuter segments from occasion-driven family and student spending patterns.
- Millennials:Digital-native consumers concentrating spending in app-based loyalty mechanics with subscription prepaid beverage clubs. Remote work normalization treats cafes as secondary offices, driving all-day consumption across urban centers.
- Professionals:Time-constrained commuters prioritizing grab-and-go speed at rail hubs with premium positioning tolerance for quality consistency. Pret A Manger dominates this segment through bundled breakfast combinations.
- Families:Occasion-driven weekend traffic seeking child-friendly amenities and extended dwell permissions. Suburban drive-through formats capture this demand through accessible parking infrastructure.
- Students:Price-sensitive volume seekers with high WiFi reliability requirements and extended seating occupation. University town operators face compressed per-visit yields offset by frequency advantages.
Millennials absorb the bulk of installed capacity; Professionals are expanding most quickly.
Product Offerings:
Application-specific procurement patterns separate beverage-led operators from food-forward formats with diverging supply chain configurations.
- Non-Alcoholic Beverages:Sugar tax reformulation investment accelerates premium positioning for reduced-sugar specialty lines. The UK Soft Drinks Industry Levy forces capital redeployment toward compliant recipe development.
- Craft Beers:Local brewing partnerships and rotating tap configurations require flexible supplier relationships and extended producer responsibility packaging compliance. Deposit Return Scheme implementation demands reverse-logistics infrastructure investment.
- Artisan Breads:Centralized bakery supply or in-house production decisions determine kitchen footprint requirements and labor skill concentration. Natasha's Law mandates full ingredient labeling for pre-packed direct sale configurations.
- Light Snacks:Grab-and-go refrigeration-dependent categories with shortest shelf-life constraints and highest allergen disclosure burden. Rail hub operators face steepest compliance capex requirements.
Non-Alcoholic Beverages absorb the bulk of installed capacity; Craft Beers are expanding most quickly.
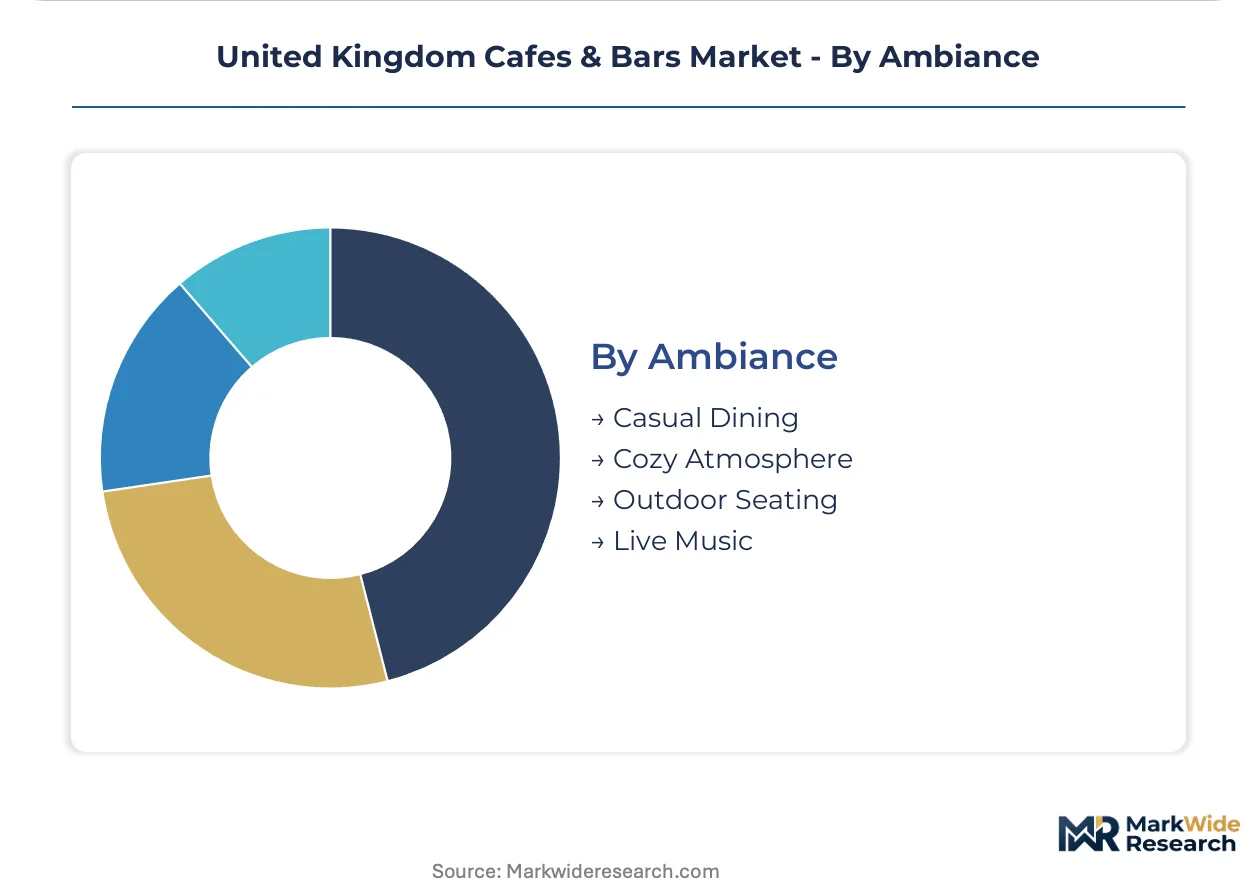
Ambiance:
Geographic clustering in dense urban cores favors experiential differentiation over pure refreshment purchasing.
- Casual Dining:Flexible seating configurations accommodating both rapid turnover and extended occupation patterns. Manchester city centers demonstrate highest concentration of hybrid workspace-cafe formats.
- Cozy Atmosphere:Intimate seating density with acoustic management requirements and lighting design capital intensity. Bristol's Harbourside cluster shows demand concentration for experiential positioning.
- Outdoor Seating:Seasonal revenue volatility with pavement licensing permissions controlled by Local Authority environmental health departments. Westminster terrace configurations face strict public highway constraints.
- Live Music:Entertainment licensing叠加 requirements with noise abatement compliance and performer liability considerations. Camden's established music venue ecosystem concentrates skilled operator expertise.
Casual Dining absorbs the bulk of installed capacity; Cozy Atmosphere is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise Zone tax reliefs and reduced business rates in designated areas concentrate new venue development across England's core urban corridors. Local authority licensing boards under the Licensing Act 2003 shape expansion velocity through trading hour permissions and premises approvals.
London and Southeast England
Remote work normalization drives all-day consumption across the City of London and Canary Wharf financial districts. Westminster and Camden licensing boards impose moratorium pressures on saturated high streets, constraining greenfield approvals. Greater London's specialty coffee corridor anchors premium positioning for espresso-dependent formats.
Midlands
Drive-through format expansion captures suburban convenience demand across Birmingham and Coventry commuter belts. The Food Standards Agency's allergen disclosure mandates force kitchen reconfiguration toward centralized prep facilities. Manchester's Northern Quarter cluster demonstrates concentration of hybrid workspace-cafe formats.
North England
Secondary city white space in Leeds and Liverpool attracts fast casual format replication from Greater London operators. Local Environmental Health Officers conduct unannounced inspections determining consumer-facing hygiene scores. Manchester city centers absorb the bulk of regional workspace-as-amenity demand.
Scotland
Scottish licensing boards under the Licensing (Scotland) Act 2005 control alcohol trading permissions with stricter hour constraints than England. Edinburgh's festival economy creates seasonal demand volatility for cocktail lounge formats. Glasgow's Finnieston district shows emerging specialty coffee corridor development.
Wales
Cardiff Bay regeneration zones offer reduced business rates attracting family-oriented casual dining formats. Welsh local authorities enforce Food Standards Agency hygiene rating schemes with documented hazard analysis protocols. Swansea's Maritime Quarter demonstrates concentration of outdoor seating-dependent seasonal operators.
United Kingdom Cafes & Bars Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base spans multinational coffee chains with drive-through networks, pub estate operators with price-fixed meal bundles, and grab-and-go specialists dominating commuter rail hubs. Three archetypes dominate: scale-driven format replicators, convenience-anchored suburban operators, and workspace-as-amenity urban specialists. Competitive moves concentrate on subscription loyalty mechanics and fast casual format convergence.
Among UK-based operators, Costa Coffee, JD Wetherspoon plc, and Pret A Manger exemplify distinct strategic archetypes. Costa Coffee occupies a position as a scale-driven format replicator with extensive drive-through infrastructure. JD Wetherspoon plc represents the pub estate operator archetype competing on bundled meal economics. Pret A Manger sits within the grab-and-go specialist tier with concentrated commuter rail hub presence. These three anchors demonstrate how geographic clustering and format specialization create defensible market positions under Food Standards Agency regulatory frameworks.
| Leading Market Players |
|---|
| Costa Coffee |
| Stonegate Group |
| JD Wetherspoon plc |
| Caffè Nero Group Ltd |
| Starbucks Corporation |
| Pret A Manger |
| Greggs |
| Loungers |
| Coffee#1 |
| Others |
Pricing and Supply Chain Analysis
Premium-mid-economy pricing differentiation across UK cafes and bars manifests in divergent supply chain configurations, with specialty coffee operators drawing from direct-trade Brazilian and Colombian estates while commodity-tier chains rely on centralized roasting contracts with volume-driven intermediaries. This bifurcation intensifies as arabica price volatility squeezes middle-tier operators unable to secure long-term offtake agreements or absorb spot market fluctuations.
Pricing Analysis
Short lead-time premiums dominate pricing architecture, with grab-and-go rail hub operators commanding per-unit tolerance for immediate availability while suburban drive-through formats discount for predictable batch production. Three-tier pricing structure across premium, standard, and economy levels separates single-origin specialty lines from blended house roasts and private-label retail offerings. Cost compression in the economy tier is intensifying because energy tariffs for refrigeration outpace menu elasticity. Students exhibit highest price sensitivity, while professionals demonstrate lowest sensitivity for quality consistency at commuter nodes.
Supply Chain Analysis
Direct-to-roaster channels handle hyperscale demand from Costa Coffee and Starbucks Corporation, while specialty operators source through importer-curated auction lots. Raw material dependencies center on Brazilian arabica, Colombian washed varieties, and Vietnamese robusta for blend components. Single-source vulnerability concentrates in Colombian harvest cycles, where climate disruption propagates price shocks through London futures markets. Distribution runs through regional distribution centers serving multi-site operators, with independent cafes relying on wholesale intermediaries for smaller lot access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital ordering infrastructure is displacing legacy POS systems across UK hospitality premises, with mobile order-ahead platforms now capturing commuter rail traffic that previously flowed through transactional counter service. This technology transition rewards operators who unify payment, loyalty, and production queue management into single-interface workflows.
For Market Incumbents: Deepen backward integration into roasting infrastructure to defend margin position against arabica price volatility, while consolidating drive-through real estate in suburban commuter belts ahead of licensing moratorium expansion. The Food Standards Agency's extended producer responsibility mandates threaten capital efficiency for operators without reverse-logistics partnerships. Scale-driven format replicators should prioritize certification investment in allergen-tracking kitchen display systems.
For New Entrants and Emerging Players: Capture white space in secondary UK cities where fast casual format convergence remains underpenetrated, specifically Leeds and Liverpool outside Manchester's established cluster. Subscription loyalty mechanics offer the most penetrable go-to-market angle, with app-based prepaid beverage clubs capturing commuter rail hub traffic from transactional incumbents. Target hybrid workspace-cafe positioning in Bristol's Harbourside and emerging Glasgow Finnieston corridors.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform roll-ups of regional specialty chains with compliant labeling infrastructure already deployed. Long-term viability across the analysis window favors operators with demonstrated Environmental Health Officer rating consistency and scalable drive-through unit economics. The signal to watch is deposit return scheme implementation timing, which will alter supply chain cost structures and reward first-mover reverse-logistics design.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Loyalty Platform Launch | Captures commuter rail traffic from transactional grab-and-go competitors through app-based prepaid mechanics. |
| Drive-Through Format Expansion | Redirects infrastructure investment from saturated Westminster and Camden high streets toward suburban accessibility. |
| Centralized Prep Facility Investment | Enables Natasha's Law compliance for grab-and-go operators facing steepest rail hub labeling capex requirements. |
| Reverse-Logistics Partnership Formation | Positions beverage-led operators for deposit return scheme implementation through packaging supplier collaboration. |
| Fast Casual Format Convergence | Merges coffee specialization with elevated food provenance in underpenetrated secondary UK city markets. |
Research Methodology
Document review covered Food Standards Agency enforcement data, local authority licensing board decisions under the Licensing Act 2003, and trade customs records for coffee bean imports, complemented by interviews with operations directors at multi-site hospitality groups, procurement leads at roasting facilities, Environmental Health Officers, and commercial property agents specializing in high-street and roadside retail. Secondary validation drew from UK Hospitality industry association filings, British Coffee Association consumption surveys, and local authority business rate datasets. Bottom-up unit economics modeling and top-down sector aggregation were triangulated against regional demand indicators.
Historical consumption patterns were cross-referenced against panel input from venue operators to establish baseline assumptions, with segmentation modeling across service type, customer demographic, product category, and experiential positioning dimensions. CAGRs were derived through trend extrapolation adjusted for regulatory phase-in schedules and infrastructure deployment timelines. Forecast inputs incorporated remote work normalization trajectories, sugar tax reformulation investment cycles, and drive-through permission velocity by local authority.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to arabica commodity price cycles, licensing board moratorium extensions, and energy tariff pass-through limitations. Forecasts reflect documented assumptions regarding regulatory implementation timing and consumer behavioral persistence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
North America Food Platform-To-Consumer Delivery Market
Food Service
Charbroiler Market
Food Service
Air Fryer Meal Kits Market
Food Service
Turkey Food Service Market
Food Service
Online Grocery Market
Food Service
Snack Subscription Box Service Market
Food Service
Nigeria Food Service Market
Food Service
Germany Foodservice Market
Food Service
United States Food Truck Market
Food Service
Meal Voucher Market
Food Service
Commercial Pizza Oven Market
Food Service
Indonesia Foodservice Market
Food Service
Commercial Deep Fryer Parts and Accessories Market
Food Service
Personal Chef Services Market
Food Service
United States Quick Service Restaurants Market
Food Service
Europe Airline Catering Services Market