
 North America Cafes & Bars Market | 2026-2036
North America Cafes & Bars Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cafes & Bars Market Insights
Specialty beverage licensing is rewriting margin economics across the sector. Starbucks Corporation leverages its roasting infrastructure to control bean-to-cup quality at scale. Dutch Bros Inc. anchors its growth in drive-through velocity and Gen Z brand affinity. Inspire Brands Inc. competes through multi-format portfolio diversification spanning bars and quick-service cafes.
Cafes and bars constitute commercial foodservice establishments where beverage preparation combines with social consumption environments, typically operating with espresso extraction pressures of 9 bars, controlled fermentation for alcohol service, and temperature-calibrated storage systems to preserve product integrity. Full-service cafes and specialty coffee shops capture premium margin pools through experiential differentiation and origin-specific sourcing narratives. Fast casual formats and wine bars extend reach into convenience-oriented and evening-occasion segments respectively.
FDA food code enforcement and state alcohol beverage control boards shape operational standards across the United States, while Health Canada and provincial liquor authorities govern Canadian market access. OSHA workplace safety mandates and municipal health inspections further constrain site-level compliance costs. Stakeholders must monitor evolving cannabis-infused beverage regulations and zero-proof alcohol taxation frameworks as these categories redefine competitive boundaries.
Market Dynamics
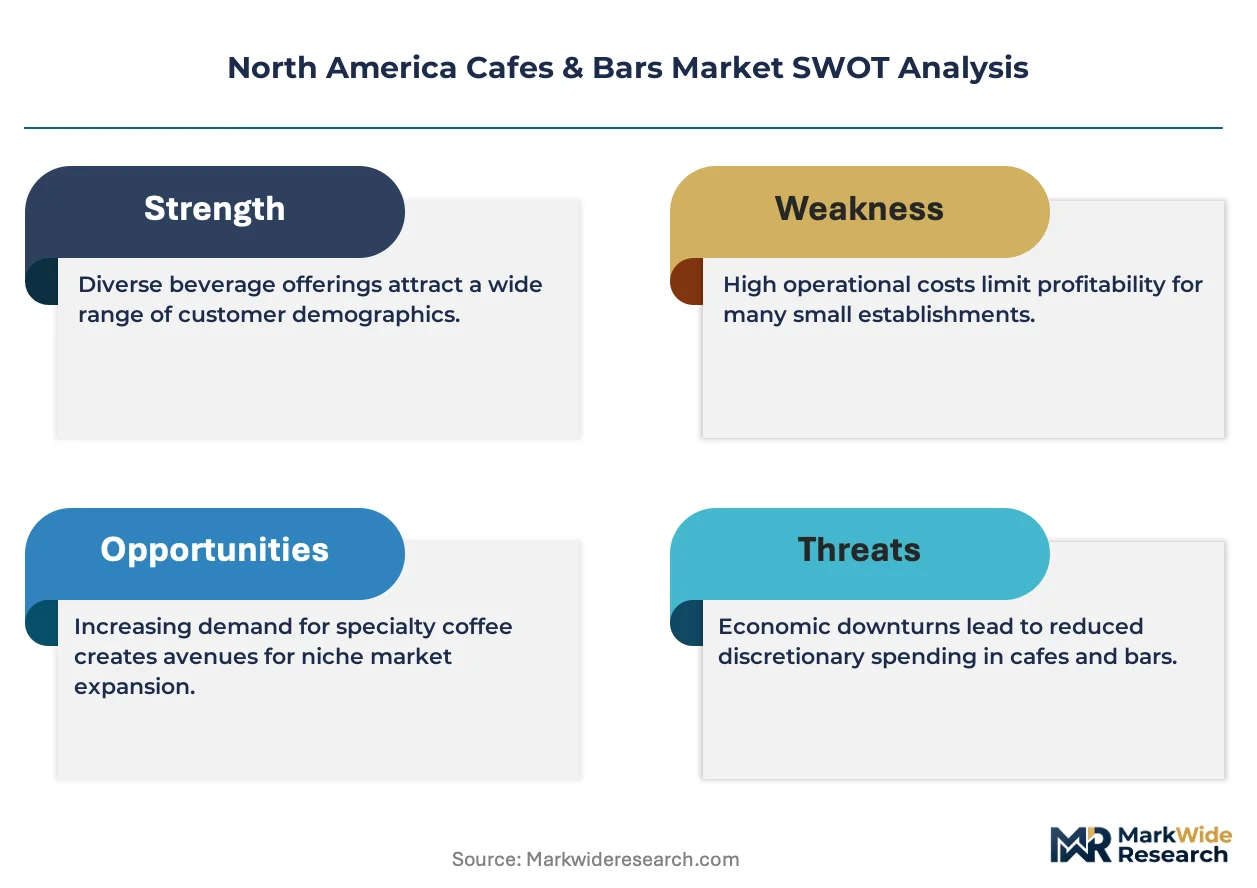
Specialty beverage licensing is compressing margin structures across the North American market, forcing operators to recalibrate revenue models around experiential differentiation and controlled-substance compliance.
Growth Catalysts
- Zero-Proof Taxation Frameworks:Canadian provincial liquor authorities and select US states are creating favorable excise categories for non-alcoholic spirits, opening incremental revenue pools for hybrid cafe-bar concepts.
- Gen Z Drive-Through Velocity:Younger cohorts prioritize convenience and brand affinity over traditional sit-down formats, pulling capital toward high-throughput formats with limited footprints.
- OSHA Workplace Safety Modernization:Updated mandates around repetitive-motion injury prevention are accelerating automation investment in espresso preparation and back-of-house operations.
Market Restraints
- Arabica Price Volatility:Climate-driven supply shocks in Colombia and Brazil are compressing gross margins for operators without forward-contracting capabilities or captive roasting infrastructure.
- State Alcohol Licensing Fragmentation:The patchwork of municipal and state-level beverage control boards creates compliance friction that advantages multi-unit chains with dedicated legal resources over independent operators.
- Cannabis-Infused Regulatory Uncertainty:Divergent federal and state positions on THC beverage service create liability exposure that freezes capital deployment in high-potential markets like California and Colorado.
Strategic Opportunities
- Mexico Market Underpenetration:Northern Mexican urban corridors adjacent to US border populations represent white space for American format replication, particularly in Monterrey and Tijuana metro areas.
- Morning-to-Night Format Convergence:Coffee-to-cocktail transitions within single locations capture occasion-stacking economics that pure-play competitors cannot replicate.
- Health Canada CBD Beverage Pathway:Anticipated regulatory clarity on cannabidiol-infused drinks positions Canadian operators for first-mover advantage before US federal alignment.
Industry Challenges
- Barista Skill Compression:Automated extraction systems are degrading the craft-knowledge pipeline, creating talent scarcity for premium positioning that still requires manual technique demonstration.
- Multi-Jurisdiction Compliance Burden:Operators expanding across state or provincial lines face divergent food code interpretations, alcohol service training mandates, and municipal health inspection cadences that strain centralized management bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cafes & Bars Market |
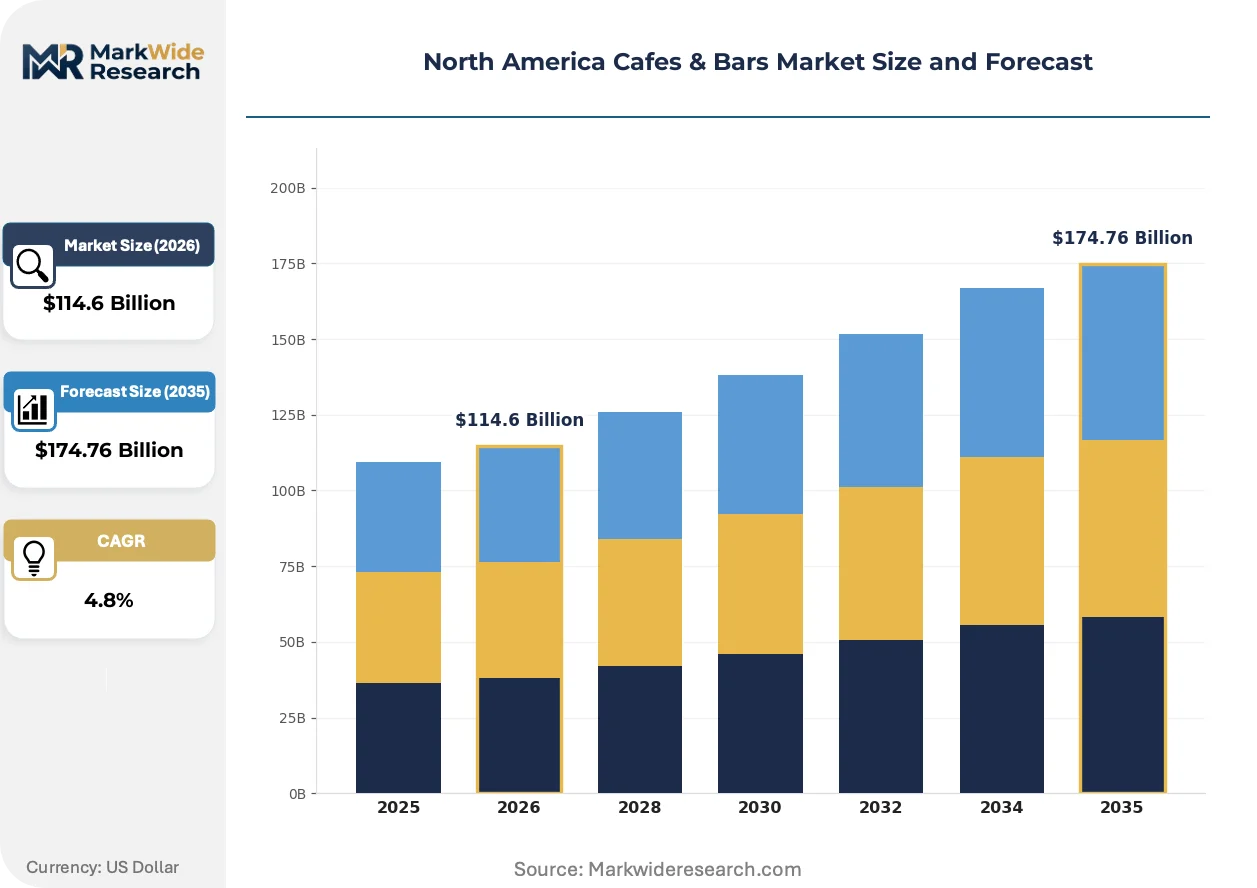
| Market Size in 2026 | $114.6 Billion |
| Market Size in 2035 | $174.76 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service Cafes, Fast Casual, Specialty Coffee Shops, Wine Bars Customer Type: Students, Young Professionals, Families, Tourists Product Offerings: Coffee, Cocktails, Light Snacks, Desserts Atmosphere: Casual, Upscale, Cozy, Trendy |
| Companies Covered | Starbucks Corporation, Dutch Bros Inc., Inspire Brands Inc., Restaurant Brands International Inc., McDonald's Corporation, International Dairy Queen Inc., Smoothie King Franchises Inc., Focus Brands LLC, Jab Holding Company SÀRL, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cafes & Bars Market Trends and Innovations
Automation and regulatory recalibration are actively restructuring competitive advantage in beverage service, separating capital-efficient operators from legacy format incumbents.
Precision batch-brew systems with integrated IoT monitoring are rendering obsolete manual pour-over stations in high-volume specialty environments. Mid-market chains with 50-plus locations are adopting these platforms fastest, compressing labor cost structures while maintaining quality consistency claims that previously required certified barista labor.
FDA Food Code enforcement intensification around temperature-controlled storage documentation is forcing system-wide capital redeployment. Operators now face elevated inspection failure risk without automated logging infrastructure, with California and New York health departments deploying digital audit trails that penalize paper-based compliance programs.
Subscription-based beverage consumption is displacing transactional loyalty programs across urban professional segments. Young professionals in Toronto, Austin, and Seattle are prioritizing fixed-monthly access models over per-drink purchasing, compelling operators to restructure pricing architecture around predictable recurring revenue rather than visit-frequency optimization.
North America Cafes & Bars Market Segmentation
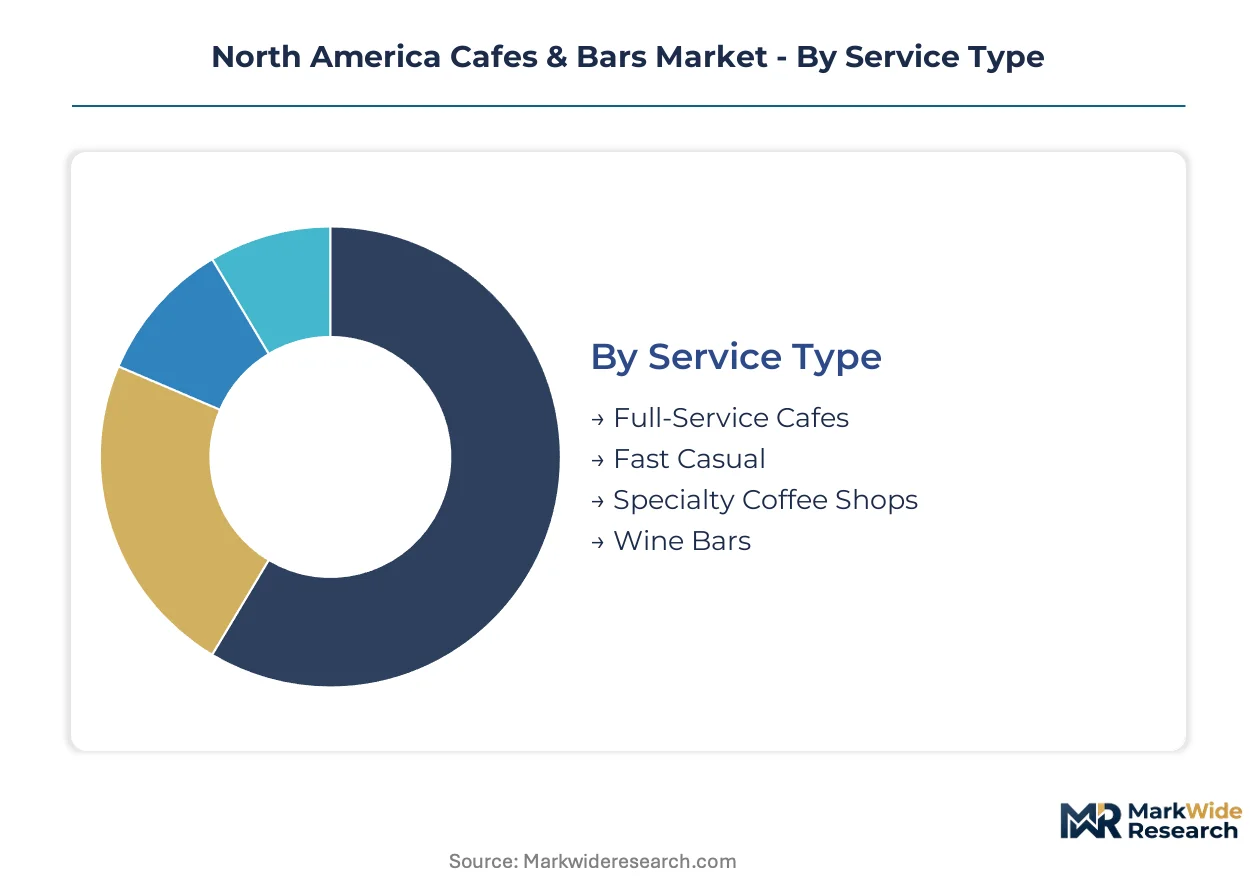
Segmentation in the North American cafes and bars market reveals how service intensity, customer lifecycle value, and occasion-stacking economics determine capital allocation across formats. Operators must align infrastructure investments—espresso equipment specifications, alcohol licensing tiers, and seating configurations—with the specific demands of each segment cluster.
Service Type:
After-sales service intensity varies dramatically across formats, with full-service cafes requiring ongoing equipment maintenance contracts and fast-casual concepts demanding minimal post-installation support.
- Full-Service Cafes:These establishments combine table service with comprehensive beverage programs and kitchen operations. Demand concentrates in California's urban corridors and New York City's neighborhood clusters, where young professionals seek extended dwell-time experiences that justify premium pricing.
- Fast Casual:Counter-service formats with limited menus and accelerated throughput dominate suburban expansion strategies. Gen Z consumers in Austin and Toronto metro areas drive format adoption through convenience prioritization over experiential depth.
- Specialty Coffee Shops:Origin-focused roasting and manual brewing techniques define this segment. Equipment maintenance contracts and barista training programs create elevated service intensity relative to volume.
- Wine Bars:Evening-occasion concepts with curated by-the-glass programs and small-plate pairing menus. Temperature-controlled storage systems and sommelier staffing requirements differentiate operational models.
Full-Service Cafes hold the largest share; momentum sits with Fast Casual.
Customer Type:
Cost tier stratification across customer segments determines pricing architecture and loyalty program design, with young professionals commanding the highest per-visit spend and subscription conversion rates.
- Young Professionals:Urban-dwelling cohorts aged 25-35 prioritize premium experiences and brand affinity over price sensitivity. Subscription-based consumption models in Seattle and Toronto capture predictable recurring revenue from this segment.
- Students:Price-conscious demographics with high visit frequency but compressed per-transaction values. WiFi infrastructure and extended hours drive location selection more than beverage quality differentiation.
- Families:Weekend and holiday-occasion visitors seeking accommodating environments with varied menu options. Highchair availability and noise tolerance shape format suitability.
- Tourists:Transient demand concentrated in destination cities including New York, Los Angeles, and Vancouver. Seasonal volatility requires flexible staffing models and inventory management.
Young Professionals generate the highest margin contribution; Students represent the steepest expansion trajectory for value-format operators.
Product Offerings:
Volume concentration patterns reveal how morning coffee rituals anchor daily traffic while evening alcohol service captures occasion-stacking economics unavailable to single-category competitors.
- Coffee:Espresso-based beverages and specialty batch brews constitute the core morning-daypart revenue driver. Arabica price volatility in Colombian and Brazilian supply regions compresses margins for operators without forward-contracting capabilities.
- Cocktails:Spirit-forward and zero-proof formulations extend revenue into evening occasions. Canadian provincial liquor authorities and select US states are creating favorable excise categories for non-alcoholic alternatives.
- Light Snacks:Prepared food items with limited kitchen infrastructure requirements. FDA Food Code temperature documentation mandates elevate compliance costs for operators without automated logging systems.
- Desserts:Pastry and confection offerings with extended shelf-life considerations. Display case refrigeration and portion-control standardization determine waste rates.
Coffee commands the dominant revenue share; Cocktails deliver the fastest margin expansion for hybrid concepts.
Atmosphere:
Margin stratification across atmospheric positioning separates capital-efficient casual formats from upscale concepts requiring intensive design investment and specialized staffing.
- Casual:Functional environments prioritizing accessibility and turnover over aesthetic differentiation. Strip-mall and transit-adjacent locations maximize convenience-driven demand capture.
- Upscale:Design-forward interiors with premium materials and controlled acoustics. Manhattan and San Francisco operators recover elevated rent burdens through extended dwell-time and elevated check averages.
- Cozy:Intimate scale with residential design cues and soft lighting configurations. Neighborhood anchoring in residential districts of Chicago and Montreal builds repeat-visit loyalty.
- Trendy:Instagram-optimized aesthetics with rotating visual installations and limited-edition collaborations. Social media amplification reduces customer acquisition costs for emerging concepts in Miami and Los Angeles.
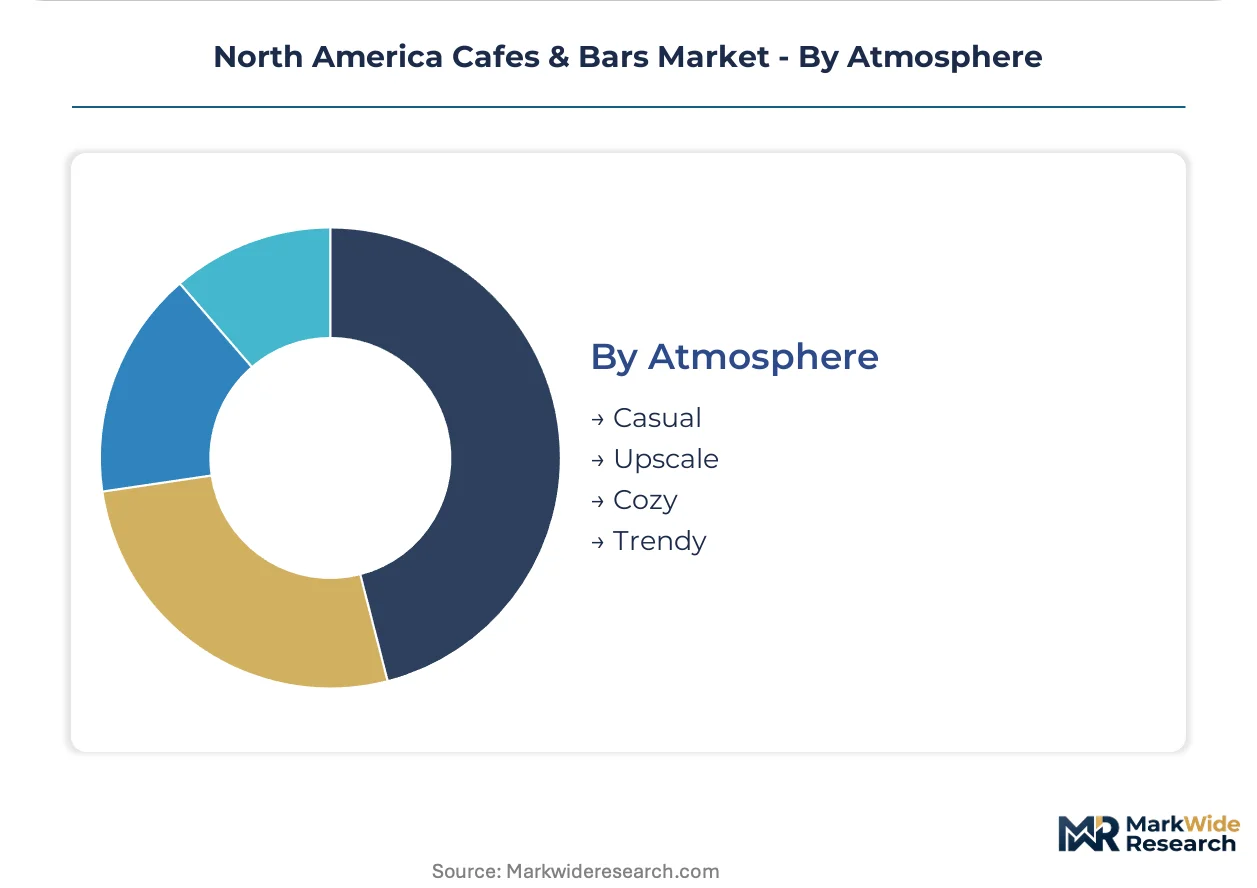
Casual formats hold the largest location count; Trendy concepts are gaining share fastest among venture-backed expansion strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in three distinct national markets where regulatory divergence and urban density patterns create differentiated expansion economics for beverage-service operators.
United States
Young professionals in Seattle and Austin drive subscription-model adoption for specialty coffee formats. FDA food code enforcement around temperature-controlled storage documentation elevates compliance costs for multi-unit operators. California's urban corridors anchor premium-format development, with Los Angeles and San Francisco operators recovering elevated rent through extended dwell-time pricing.
Canada
Toronto's young professional cohort exhibits the highest subscription conversion rates among North American metros. Health Canada and provincial liquor authorities govern market access with divergent excise frameworks for zero-proof alternatives. Vancouver operators face compressed margins from Arabica price volatility despite strong origin-focused positioning in the Pacific Northwest cluster.
Mexico
Monterrey and Tijuana metro areas adjacent to US border populations represent underpenetrated white space for American format replication. Municipal health inspection cadences and state-level business licensing create compliance friction that advantages chains with dedicated legal infrastructure. Mexico City anchors domestic demand concentration, though capital deployment remains constrained by informal competitor density in peripheral districts.
North America Cafes & Bars Market Competitive Landscape
Vertically integrated roasting specialists and drive-through velocity operators split the market between premium-experience and convenience-optimized formats. The vendor base stratifies across three archetypes: captive-supply chains with in-house bean sourcing, franchised high-throughput concepts, and multi-format portfolio conglomerates. Dominant competitive moves include portfolio diversification into hybrid coffee-to-cocktail formats and automation investment to compress labor cost structures.
Within the captive-supply tier, Starbucks Corporation exemplifies vertical integration into roasting infrastructure that insulates margin from commodity volatility. Dutch Bros Inc. occupies a position within the velocity-focused archetype, with drive-through formats capturing Gen Z brand affinity. Inspire Brands Inc. anchors the multi-format conglomerate segment, spanning bars and quick-service cafes through portfolio diversification.
| Leading Market Players |
|---|
| Starbucks Corporation |
| Dutch Bros Inc. |
| Inspire Brands Inc. |
| Restaurant Brands International Inc. |
| McDonald's Corporation |
| International Dairy Queen Inc. |
| Smoothie King Franchises Inc. |
| Focus Brands LLC |
| Jab Holding Company SÀRL |
| Others |
Pricing and Supply Chain Analysis
Colombian and Brazilian arabica concentration anchors cost structures for North American operators, with forward-contracting capabilities determining which chains capture margin versus surrendering it to commodity volatility. Captive roasting infrastructure insulates Starbucks Corporation from spot-market pressure that compresses independent cafe margins.
Pricing Analysis
FDA Food Code enforcement dictates the pricing tier structure across full-service, fast-casual, and specialty formats. Three-tier pricing structure across premium, standard, and economy levels separates origin-specific single-origin offerings from blended house roasts and commodity-grade alternatives. Cost compression in the standard tier is intensifying because climate-driven supply shocks in key growing regions elevate input costs without corresponding price elasticity. Students exhibit the highest price sensitivity, while young professionals in Seattle and Toronto demonstrate willingness to absorb subscription premiums for experiential differentiation.
Supply Chain Analysis
Contract manufacturing concentration for espresso equipment rests with Italian and Swiss original equipment manufacturers, while green bean sourcing draws from Colombia, Brazil, and Vietnam. Roasting infrastructure dependencies center on Probat and Loring systems for precision thermal control. Single-source vulnerability in Brazilian arabica supplies creates exposure to frost and drought cycles that ripple through futures markets. Distribution runs through regional cold-storage hubs before final-mile delivery to operator locations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Zero-proof taxation frameworks and automation investment are restructuring competitive advantage in beverage service, separating capital-efficient operators from legacy format incumbents.
For Market Incumbents: Entrench position through backward integration into roasting infrastructure and automated extraction systems that compress labor cost structures. Gen Z drive-through velocity threatens sit-down format incumbents who fail to reconfigure for high-throughput convenience. Certification investment in FDA-compliant temperature logging systems protects against inspection failure risk in California and New York enforcement corridors. For New Entrants and Emerging Players: Build out presence in Monterrey and Tijuana metro areas where American format replication remains underpenetrated. Morning-to-night format convergence captures occasion-stacking economics unavailable to pure-play coffee or alcohol competitors. Direct-to-consumer subscription models in Toronto and Austin offer the most penetrable entry vector for recurring revenue capture. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated roasting specialists with captive supply chains and drive-through velocity operators exhibiting Gen Z brand affinity. The five-to-ten-year viability window favors concepts with automation-enabled labor compression and hybrid licensing flexibility. Watch Health Canada CBD beverage pathway clarity as the signal for first-mover positioning before US federal alignment.| Strategic Initiative | Industry Significance |
|---|---|
| Roasting Infrastructure Investment | Captive bean sourcing insulates margin from Colombian and Brazilian spot volatility. |
| Drive-Through Format Expansion | High-throughput footprints capture Gen Z convenience preference in Austin and Toronto suburbs. |
| Hybrid Licensing Acquisition | Coffee-to-cocktail transitions capture evening occasion revenue unavailable to single-category competitors. |
| Automation Platform Deployment | IoT-integrated batch-brew systems compress labor costs while maintaining quality consistency claims. |
| Subscription Model Restructuring | Fixed-monthly access programs displace transactional loyalty in Seattle and Toronto professional segments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA enforcement records, state alcohol beverage control board filings, and Health Canada regulatory updates. Primary interviews incorporated cafe operators, espresso equipment procurement managers, green bean sourcing directors, and municipal health inspection officers. Secondary validation drew from OSHA workplace safety mandates, provincial liquor authority excise frameworks, and SEC filings from publicly traded chains. Bottom-up location counts and top-down category spending estimates were triangulated to anchor volume and value outputs.
Forecast inputs span service type segmentation across full-service, fast-casual, specialty coffee, and wine bar formats, with customer type stratification by age cohort and occasion behavior. Product offering splits between coffee, cocktails, light snacks, and desserts were modeled alongside atmosphere positioning from casual to upscale. CAGRs were derived from historical growth trajectory analysis adjusted for regulatory inflection points and automation adoption curves. Arabica futures volatility and zero-proof taxation framework expansion served as industry-specific sensitivity inputs across the projection horizon.
Practitioners should monitor FDA Food Code enforcement intensity, Health Canada CBD beverage pathway developments, and OSHA automation mandate timing for early signals of forecast revision. Quarterly review of inspection failure rates by state, subscription conversion metrics in Toronto and Seattle, and drive-through throughput benchmarks is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Food Trucks Market
Food Service
Asia-Pacific Online Grocery Delivery Market
Food Service
Bar Refrigeration Market
Food Service
Food & Beverage in Asia Market
Food Service
Europe Smokeless Indoor Grills Market
Food Service
Restaurant Glassware Market
Food Service
Self-Heating Hot Pot Market
Food Service
India Foodservice Market
Food Service
Air Fryer Market
Food Service
Supermarkets Market
Food Service
Bottled Water Cooler Market
Food Service
Food Truck Services Market
Food Service
Malaysia Food Service Market
Food Service
Netherlands Food Service Market
Food Service
Meal Voucher Market
Food Service
Egypt Food Service Market