
 Retail Cooler Market | 2026-2036
Retail Cooler Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Cooler Market Intelligence
The ENERGY STAR certification is bifurcating the competitive landscape, creating a divide between premium high-efficiency models and standard units. Carrier Commercial Refrigeration leverages its service network to support large supermarket chains with complex system needs. True Manufacturing specializes in durable glass door merchandisers for convenience stores and restaurants. Danfoss Group supplies advanced compressors and electronic controls to a wide base of equipment manufacturers.
Retail coolers are self-contained or remote commercial refrigeration units designed for the display and preservation of perishable goods in a retail environment. These systems operate on a vapor-compression cycle, using refrigerants to maintain specific internal temperatures, often between 0°C and 5°C for chilled products. Glass door merchandisers command a significant share due to their importance in driving impulse purchases in convenience stores. Supermarkets favor larger, often remote-condensing chest and multi-deck units for bulk storage and display efficiency.
Regulations from the US EPA and the EU's F-Gas Regulation are accelerating the phase-out of high-GWP hydrofluorocarbon (HFC) refrigerants. These rules, alongside China's MEE dual carbon goals, mandate the adoption of natural refrigerants like CO2 and propane in new equipment. Equipment manufacturers must now balance performance and upfront cost against the total cost of ownership and regulatory compliance for their retail clients.
Market Dynamics
The transition to natural refrigerants, driven by global regulations like the EU F-Gas Regulation, is the central force reshaping the retail cooler market. This shift impacts equipment design, service requirements, and the competitive cost structure for all participants.
Growth Catalysts
- Retail Modernization:The expansion of organized retail, particularly convenience store and supermarket formats in India, necessitates investment in new, reliable commercial refrigeration to reduce food spoilage.
- Regulatory Mandates:The EU F-Gas Regulation and parallel rules from the US EPA create a replacement cycle by phasing out high-GWP HFC refrigerants, compelling retailers to purchase compliant equipment.
- Energy Efficiency Standards:Government-backed certifications like ENERGY STAR encourage the adoption of coolers with advanced components, such as variable-speed compressors, to lower operational electricity costs.
Market Restraints
- Higher Upfront Costs:Systems using natural refrigerants like CO2 often carry a higher initial purchase price compared to traditional HFC units, slowing adoption among cost-sensitive independent retailers.
- Component Supply Concentration:The market depends on a limited number of specialized manufacturers for critical components like high-pressure CO2 compressors, creating potential supply chain vulnerabilities.
- Flammability and Pressure Risks:The use of propane (R290) introduces flammability concerns, while CO2 (R744) systems operate at much higher pressures, requiring stricter safety protocols and installation expertise.
Strategic Opportunities
- Service and Retrofitting:A growing installed base of natural refrigerant systems creates opportunities for specialized maintenance, service, and retrofitting contracts for existing HFC-based store layouts.
- Smart Cooler Integration:Incorporating IoT sensors and connectivity into coolers enables remote monitoring and predictive maintenance services, creating new recurring revenue streams for manufacturers.
- Emerging Market Penetration:Modernization of the cold chain in Southeast Asian and Latin American countries presents significant white-space opportunities for suppliers of compact, energy-efficient display coolers.
Industry Challenges
- Technician Skill Gap:A shortage of service technicians trained to safely handle and maintain high-pressure CO2 and flammable propane refrigeration systems constrains post-sale support and installation capacity.
- Compliance Complexity:Navigating the patchwork of local, national, and regional regulations, including differing refrigerant phase-down schedules and safety codes, complicates product design and market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Cooler Market |
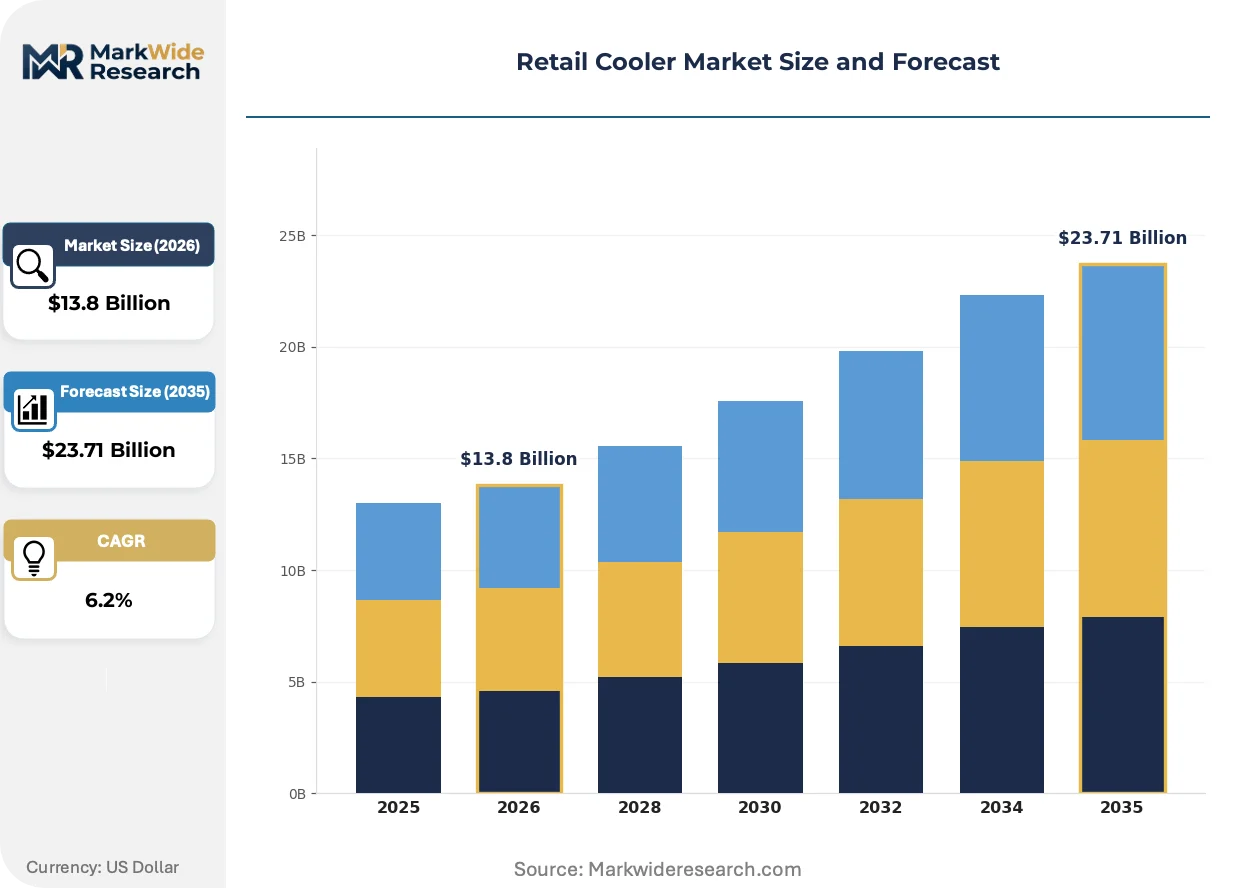
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $23.71 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Door, Chest, Undercounter, Merchandiser Application: Convenience Stores, Supermarkets, Restaurants, Cafés Energy Efficiency: High-Efficiency, Standard, Eco-Friendly, Energy Star Temperature Range: Chilled, Frozen, Ambient, Dual Zone |
| Companies Covered | AHT Cooling Systems GmbH, Daikin Industries, Carrier Commercial Refrigeration, True Manufacturing, Danfoss Group, Hussmann Corporation, Arneg, Dashang, Dover Food Retail, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Cooler Market Strategic Shifts & Innovations
A convergence of sustainability mandates and digitalization is defining the next generation of retail coolers. This forces a re-evaluation of equipment beyond simple cooling to include energy performance, data generation, and lifecycle environmental impact as core value propositions.
Advanced electronic controls paired with variable-speed compressors enable precise temperature management and significant energy savings. Large retail chains are leading the adoption of this technology in new store builds and remodels. The proliferation of these features, often linked to ENERGY STAR ratings, is bifurcating the competitive landscape between premium, high-efficiency systems and basic, standard-cost units.
Global regulations, including the EU F-Gas Regulation and the US EPA’s AIM Act, establish firm timelines for phasing down hydrofluorocarbons (HFCs). This legislative pressure compels equipment manufacturers to transition product portfolios toward natural refrigerants like CO2 and propane. The commercial refrigeration segment for new supermarket systems is most directly impacted, facing significant R&D and retooling demands.
Retailer purchasing criteria are evolving from upfront capital cost to a more sophisticated evaluation of total cost of ownership (TCO). This shift de-emphasizes initial price in favor of long-term operating expenses like energy consumption, maintenance, and compliance risk. The trend is most visible among large supermarket operators in Europe and North America managing extensive refrigeration infrastructure.
Retail Cooler Market Segmentation
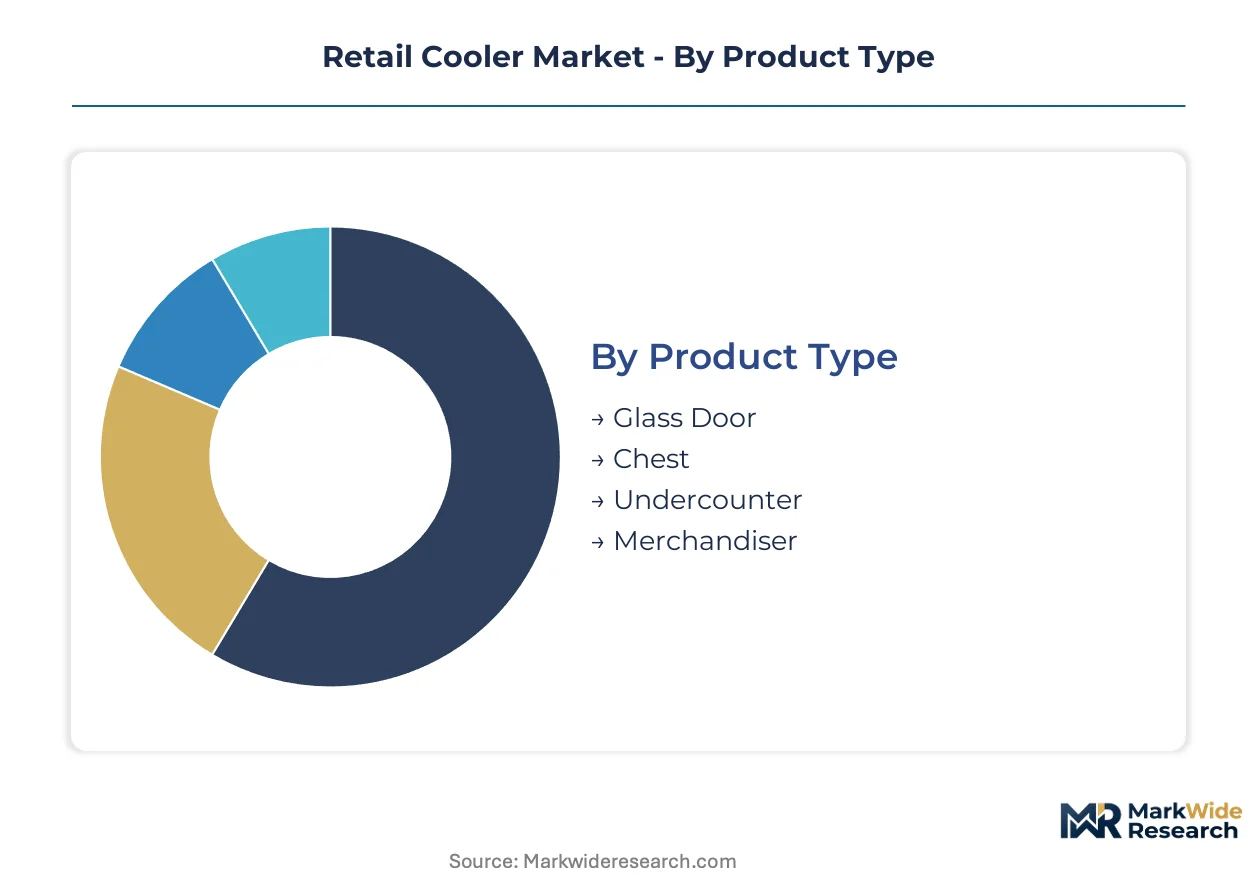
The retail cooler market categorizes product offerings and applications to reflect diverse commercial needs. Understanding these distinctions helps manufacturers align product development with specific retailer demands. Segmentation highlights where innovation is most impactful for operational efficiency and sales performance across the value chain.
Product Type:
Product type segmentation reflects varying preferences and regulatory landscapes across different global retail environments.
- Glass Door:These self-contained units feature transparent fronts, primarily for product visibility and impulse sales. Demand concentrates in convenience stores across India, driven by the need for attractive display and rapid stock rotation.
- Merchandiser:Designed for high-volume product display, these units optimize shelf space and customer access in larger formats. Supermarkets in Europe are increasingly adopting advanced merchandisers to comply with F-Gas regulations, requiring natural refrigerants.
- Chest:These coolers offer bulk storage and often serve as secondary display units for frozen goods.
- Undercounter:Compact refrigeration solutions fit beneath countertops, common in cafes and smaller food service establishments.
Glass Door units command the established base. The steepest expansion runs through Merchandiser units.
Application:
Application segments reveal how different retail environments prioritize capital expenditure and operational costs for refrigeration.
- Convenience Stores:These outlets require compact, energy-efficient units emphasizing product visibility and ease of access. Investment in new units is high in Southeast Asian markets, where rapid urbanization drives new store openings.
- Supermarkets:Large-format stores demand extensive, often remote-condensing refrigeration systems for bulk storage and diverse product displays. European supermarket chains are investing in CO2-based systems to meet stringent F-Gas compliance deadlines.
- Restaurants:Commercial kitchens use coolers for ingredient storage, prioritizing reliability and specific temperature zones.
- Cafés:Smaller refrigeration units are essential for beverages, dairy, and prepared food items in these service-oriented establishments.
Retailers in Convenience Stores drive volume. Strategic investment in Supermarkets shapes long-term market direction.
Energy Efficiency:
Energy efficiency segments highlight varying adoption rates for advanced refrigeration technologies within the market.
- High-Efficiency:These units integrate advanced components like variable-speed compressors and improved insulation to minimize power consumption. Adoption is particularly strong among large supermarket chains in North America, seeking reduced operating expenses.
- Energy Star:This certification denotes products meeting strict energy performance criteria set by the US EPA. Retailers in the United States prioritize ENERGY STAR-rated models to qualify for incentives and demonstrate environmental commitment.
- Standard:Basic refrigeration units offer functional cooling without specific advanced energy-saving features.
- Eco-Friendly:These coolers often incorporate natural refrigerants and sustainable materials, appealing to environmentally conscious businesses.
The installed base largely comprises Standard units. Demand for High-Efficiency models is expanding rapidly.
Temperature Range:
Temperature range segmentation influences product preservation capabilities and associated operational complexity for retailers.
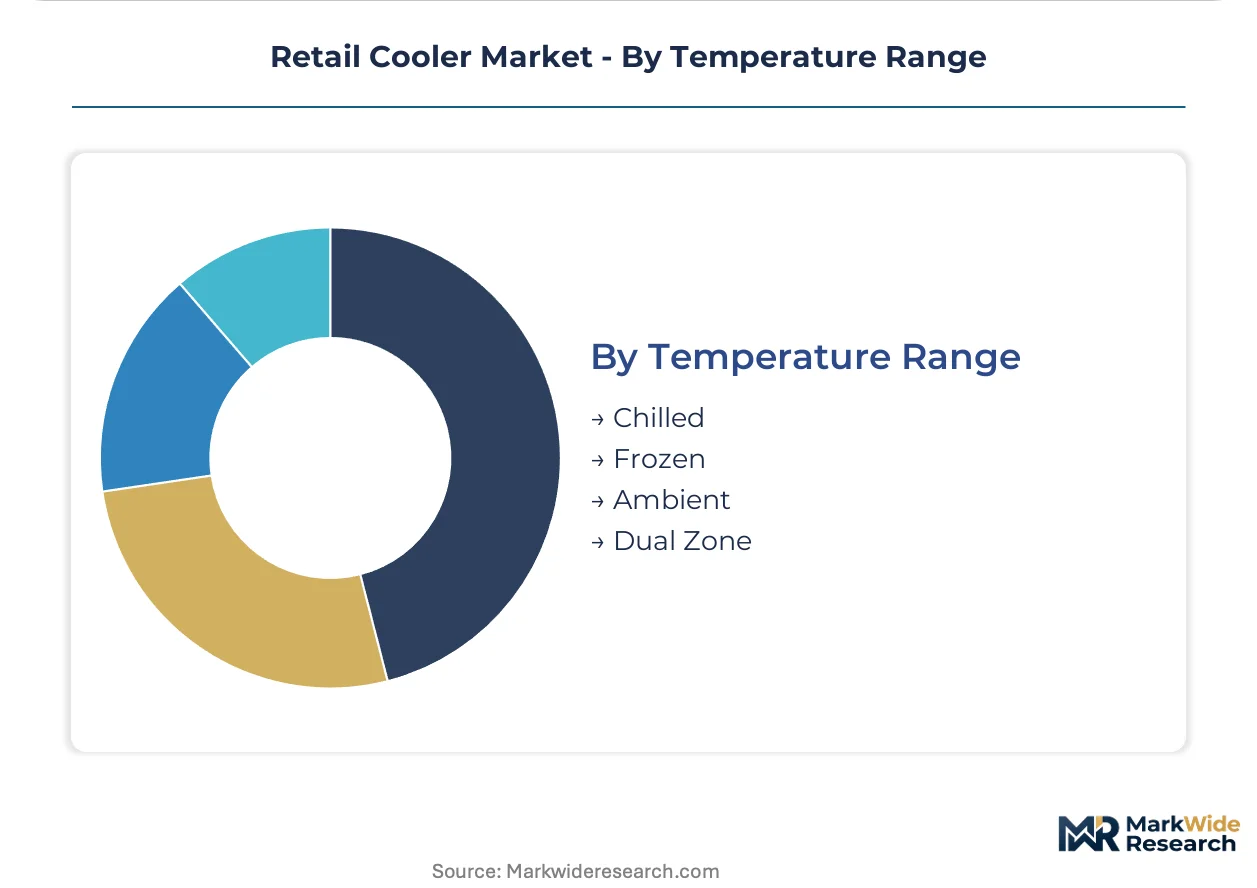
- Chilled:These coolers maintain temperatures typically between 0°C and 5°C, essential for fresh produce, dairy, and beverages. Convenience stores in Europe rely on chilled units for daily stock rotation and impulse purchases.
- Frozen:Units designed for sub-zero temperatures preserve frozen foods, ice cream, and specialty items over extended periods. Supermarkets globally utilize frozen units for their extensive range of long-shelf-life products.
- Ambient:While not strictly cooling, these units often integrate into display systems for non-refrigerated goods.
- Dual Zone:These versatile coolers offer separate compartments with distinct temperature settings, optimizing space for diverse product needs.
The majority of retail cooler deployments fall under Chilled applications. Dual Zone units offer increasing operational flexibility for diverse product lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global regulatory frameworks are significantly influencing retail cooler adoption, particularly the shift to natural refrigerants. Government-backed certifications and energy efficiency standards also shape regional market dynamics. These policies accelerate equipment replacement cycles across diverse retail environments.
United States
The US market sees strong demand for high-efficiency models, driven by large supermarket chains seeking reduced operating expenses. The US EPA's AIM Act is compelling retailers to phase out high-GWP HFC refrigerants. California, a leader in environmental regulations, often pioneers the adoption of eco-friendly refrigeration technologies.
Germany
German supermarkets are actively investing in CO2-based systems to meet stringent environmental targets and reduce energy consumption. The EU F-Gas Regulation establishes firm timelines for phasing down HFCs, impacting equipment design and procurement. Bavaria, with its strong industrial base, hosts significant research and development for advanced refrigeration technologies.
India
India's retail modernization, particularly the expansion of convenience store and supermarket formats, necessitates investment in new commercial refrigeration. The BIS standards for commercial refrigeration guide product development and market entry. Delhi-NCR, a major urban agglomeration, experiences rapid expansion of organized retail chains, driving cooler demand.
China
China's expanding cold chain infrastructure and ambitious MEE dual carbon goals are accelerating the adoption of energy-efficient and natural refrigerant-based coolers. The government's push for sustainable development impacts equipment manufacturing and retail purchasing decisions. The Yangtze River Delta region is a key hub for refrigeration equipment manufacturing and retail sector growth.
Brazil
Brazilian urbanization and the growth of convenience stores and supermarkets drive demand for compact, energy-efficient display coolers. INMETRO energy efficiency labels influence consumer and retailer choices for refrigeration equipment. São Paulo, as a major economic center, is a significant market for retail investment and cold chain development.
Retail Cooler Market Key Industry Players
Listed leaders compete with private specialists across technology innovation and geographic reach. The market shows a tiered structure, with a few large integrated manufacturers alongside numerous regional and niche players. Strategic archetypes include global refrigeration system providers and specialized component suppliers. Companies are making competitive moves through R&D investment in natural refrigerants and expanding service networks.
Among specialized manufacturers, Carrier Commercial Refrigeration and True Manufacturing exemplify distinct market approaches. Carrier Commercial Refrigeration, a global entity, represents providers leveraging extensive service networks for large supermarket clients. True Manufacturing, known for its durable glass door merchandisers, anchors the segment catering to convenience stores and and restaurants. Danfoss Group, a component supplier, sits within the advanced controls and compressor segment, supporting a wide base of equipment manufacturers.
| Leading Market Players |
|---|
| AHT Cooling Systems GmbH |
| Daikin Industries |
| Carrier Commercial Refrigeration |
| True Manufacturing |
| Danfoss Group |
| Hussmann Corporation |
| Arneg |
| Dashang |
| Dover Food Retail |
| Others |
Cost & Logistics Intelligence
Manufacturing scale economies for refrigeration components dictate supply concentration, particularly for high-pressure CO2 compressors, influencing overall system pricing. This concentration establishes price floors for advanced units while driving cost competition in standard segments.
Pricing Analysis
ENERGY STAR certification creates the primary spread in retail cooler pricing, segmenting the market between premium high-efficiency models and basic standard units. The dominant pricing structure is transactional per-unit, with brand premium and after-sales service capabilities driving differentiation. Pricing pressure stems from the higher upfront costs of natural refrigerant systems, especially for cost-sensitive independent retailers. Large supermarket chains, prioritizing total cost of ownership, exhibit lower price sensitivity.
Supply Chain Analysis
China anchors global manufacturing for many standard refrigeration components, while Germany leads in advanced CO2 compressor development. The market draws from a limited number of specialized manufacturers for critical high-pressure CO2 components. Single-source vulnerability for these specialized parts represents a significant supply chain risk. Distribution runs through a mix of direct sales to large supermarket chains and specialized equipment distributors serving smaller retail formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The retail cooler market presents a fragmentation opportunity, driven by diverse regulatory landscapes and retailer-specific needs for energy efficiency. This creates specialized niches for focused technology providers and service organizations.
For Market Incumbents: Compound investment in natural refrigerant R&D, particularly for CO2 and propane systems, to mitigate regulatory phase-out risks for HFCs. Expand specialized technician training programs through existing service networks to address the growing skill gap. Leverage ENERGY STAR certification to reinforce premium positioning against basic unit commoditization. Strategic acquisitions of smart cooler technology providers can enhance product portfolios and recurring revenue streams.
For New Entrants and Emerging Players: Specialized maintenance and retrofitting for natural refrigerant systems represent a significant service-layer gap where incumbents under-serve. Target emerging markets like Southeast Asia with compact, energy-efficient display coolers tailored for rapid urbanization. A focused go-to-market angle on IoT-enabled predictive maintenance services can differentiate offerings. Penetrate independent retailers by offering lower total cost of ownership through advanced energy-saving features.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized component manufacturers and smart cooler integration firms poised for growth. The long-term viability of the retail cooler market is anchored by global regulatory mandates and ongoing retail modernization. Acquire companies with robust intellectual property in CO2 compressor technology or advanced electronic controls. The signal to watch is the accelerated adoption rate of natural refrigerant systems in major supermarket chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in CO2 Refrigeration R&D | Accelerates compliance with EU F-Gas Regulation and US EPA AIM Act. |
| Expand Technician Training Programs | Addresses the critical skill gap for safe handling of natural refrigerants. |
| Integrate IoT for Remote Monitoring | Creates new recurring revenue streams from predictive maintenance services. |
| Target Southeast Asian Retailers | Captures white-space opportunities in rapidly modernizing convenience store formats. |
| Acquire Advanced Compressor Manufacturer | Secures critical component supply and enhances product performance differentiation. |
Research Approach
A standing panel of refrigeration engineers, retail operations managers, and regulatory compliance officers provided ongoing calibration for market trends and validation of primary insights. This study integrated findings from interviews with equipment procurement specialists and industry experts, cross-referenced with secondary data. Secondary sources included US EPA reports, EU F-Gas Regulation documents, BIS standards, and company annual reports. Bottom-up and top-down triangulation ensured data accuracy.
Consistency checks against external benchmarks validated the quantitative market outputs across the modeling period. The analytical framework segmented the market by product type, application, energy efficiency, temperature range, and refrigerant type. Compound annual growth rates were derived from historical data, projected regulatory timelines, and anticipated retail expansion plans. Key forecast inputs included HFC phase-down schedules and energy price trends.
Underlying assumptions cover stable regulatory enforcement and consistent retail investment, with deviation risk concentrated in component supply chain disruptions. Economic downturns or slower-than-expected technology adoption could alter market trajectories. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Commercial Refrigerated Display Cabinet Market
Food Service Equipment
Low-Sugar Rice Cooker Market
Food Service Equipment
Global Commercial Dishwashers Market
Food Service Equipment
Europe Walk-In Refrigerators and Freezers Market
Food Service Equipment
Commercial Convection Ovens Market
Food Service Equipment
Commercial Hot Dog Cooker Market
Food Service Equipment
Digital Menu Boards Market
Food Service Equipment
Food Trays and Bowls Market
Food Service Equipment
Combi Cooler Market
Food Service Equipment
US and Canada Hot Food Vending Machine Market
Food Service Equipment
Prepared Food Equipment Market
Food Service Equipment
Commercial Ventless Cooking Equipment Market
Food Service Equipment
Food Display Counter Market
Food Service Equipment
Rapid Cook-High Speed Ovens Market
Food Service Equipment
Commercial Slush Machine Market
Food Service Equipment
Commercial Foodservice Equipment Market