
 Instant Cooking Food Market | 2026-2036
Instant Cooking Food Market Size, Share, and Industry Trends Forecast 2026-2036
Instant Cooking Food Market Insights
Food technologist talent pools in emerging markets is rotating toward formulation science and shelf-life engineering, tightening supply chains for brands dependent on rapid product iteration. Nestlé S.A. leverages its captive R&D infrastructure across multiple continents to sustain recipe localization at scale. Nissin Foods Holdings Co., Ltd. anchors premium positioning through proprietary noodle texture technologies. Ajinomoto Co., Inc. competes on umami science integration and regional taste adaptation.
Instant cooking food comprises thermally processed, dehydrated, or retort-stabilized meal components requiring minimal preparation time, typically reconstituted with hot water or brief microwave exposure to achieve food-safe internal temperatures. The category serves industrial cafeterias, military provisioning, and residential consumers seeking caloric intake with sub-five-minute preparation cycles. Ready-to-Eat Meals command margin concentration due to protein inclusion and complex formulation barriers. Instant Noodles dominate volume throughput in price-sensitive corridors. Online Retail reshapes distribution economics by collapsing traditional wholesale layers and enabling direct-to-pantry subscription models.
FDA standards govern acidified and low-acid canned formulations in the United States, while EFSA and national EU regulators enforce additive thresholds and labeling protocols across European trade zones. China's SAMR implements GB standards for microbiological limits and packaging migration testing that directly determine factory certification and market access eligibility. Stakeholders must monitor regulatory divergence between preservative permissibility regimes and emerging clean-label compliance thresholds as formulation strategies pivot.
Market Dynamics
Urban workforce compression and China's SAMR packaging migration testing standards are restructuring formulation priorities and factory certification requirements across Asia-Pacific manufacturing networks.
Growth Catalysts
- Retort pouch technology:Shelf-stable protein meals now achieve 18-month stability without refrigeration, opening military and disaster relief procurement channels previously closed to ambient formats.
- Indonesia's BPOM fast-track registration:Streamlined halal certification pathways for pre-packaged meals accelerate product launches for Southeast Asia's Muslim-majority consumer base.
- Freeze-dried ingredient supply:Yunnan and Sichuan province clusters now supply dehydrated vegetables at scale, reducing input lead times for noodle seasoning sachet manufacturers.
Market Restraints
- Palm oil price volatility:Fried noodle production costs fluctuate with Malaysian and Indonesian crude palm oil futures, compressing margins in economy-tier segments.
- Monosodium glutamate supply concentration:Thai and Japanese fermentation facilities control 70% of global umami additive output, creating single-source vulnerability for flavor house procurement.
- GB 4806.7 compliance barriers:China's SAMR plastic migration limits force reformulation of legacy polypropylene cup structures, requiring capital retooling for export-oriented factories.
Strategic Opportunities
- Vietnam's emerging middle-class:Ho Chi Minh City and Hanoi convenience store penetration remains below Thai levels, creating whitespace for premium cup noodle distribution.
- High-pressure processing convergence:Cold pasteurization technology now integrates with retort lines, enabling clean-label positioning without sacrificing ambient shelf stability.
- India's FSSAI nutrient fortification mandates:Government school feeding programs create institutional demand for iron-fortified instant meal formats.
Industry Challenges
- Shelf-life engineering talent scarcity:Food science programs in Bangladesh and Philippines produce insufficient water activity modeling specialists for regional R&D expansion.
- Halal certification timeline compression:MUI Indonesia's audit backlogs extend product launch windows by 4-6 months for multinational brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instant Cooking Food Market |
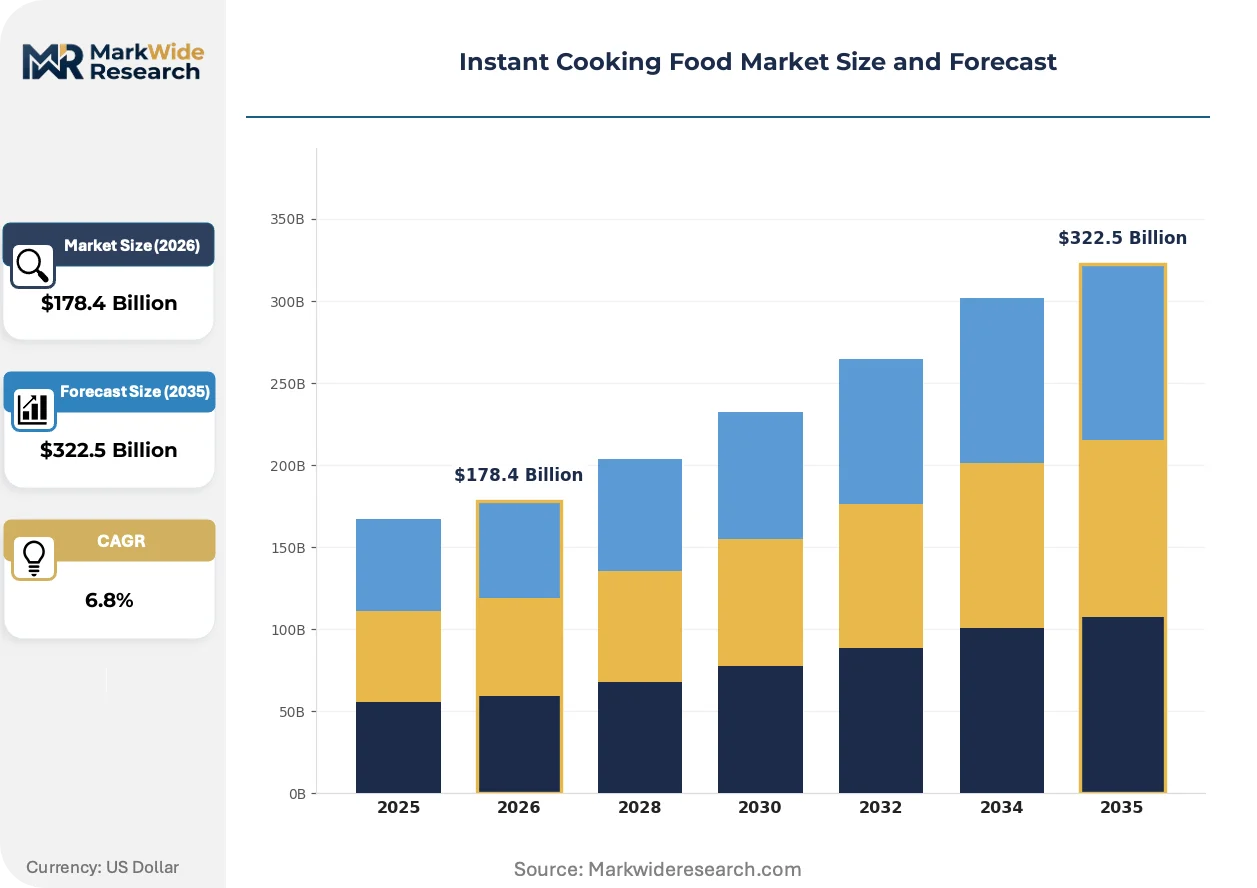
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $322.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Noodles, Ready-to-Eat Meals, Soup Mixes, Instant Rice Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Food Service Customer Type: Millennials, Families, Students, Professionals Packaging Type: Flexible Pouches, Cans, Tetra Packs, Microwaveable Containers |
| Companies Covered | Nestlé S.A., Nissin Foods Holdings Co., Ltd., Unilever PLC, The Kraft Heinz Company, Conagra Brands, Inc., General Mills, Inc., Ajinomoto Co., Inc., McCain Foods Limited, PT Indofood CBP Sukses Makmur Tbk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instant Cooking Food Market Trends and Innovations
Processing technology and regulatory disclosure requirements are fragmenting product positioning strategies while direct-to-pantry subscription channels rewrite last-mile economics for ambient meal formats.
High-moisture extrusion technology is bifurcating plant-based protein texturization capabilities. Food service operators in Singapore and South Korea now specify pea-protein chunks that replicate chicken mouthfeel in cup noodle applications. This capability split separates premium-positioned manufacturers with in-house extrusion lines from commodity assemblers dependent on outsourced textured vegetable protein.
China's SAMR GB 28050 nutrition labeling revisions now mandate front-of-pack disclosure for sodium and sugar content. Reformulation teams must reduce salt loads in seasoning oil packets while maintaining regional taste profiles. Instant noodle manufacturers serving the Yangtze River Delta are accelerating yeast extract and hydrolyzed soy protein adoption to compensate for sodium reduction.
Direct-to-pantry subscription models now capture 15% of premium instant meal volume in Tokyo and Seoul metropolitan areas. Convenience store chains are responding with refrigerated locker networks that blur the channel boundary between retail and home delivery. This behavioral shift concentrates most visibly among single-person households aged 25-34 seeking variety rotation without pantry stockpiling.
Instant Cooking Food Market Segmentation
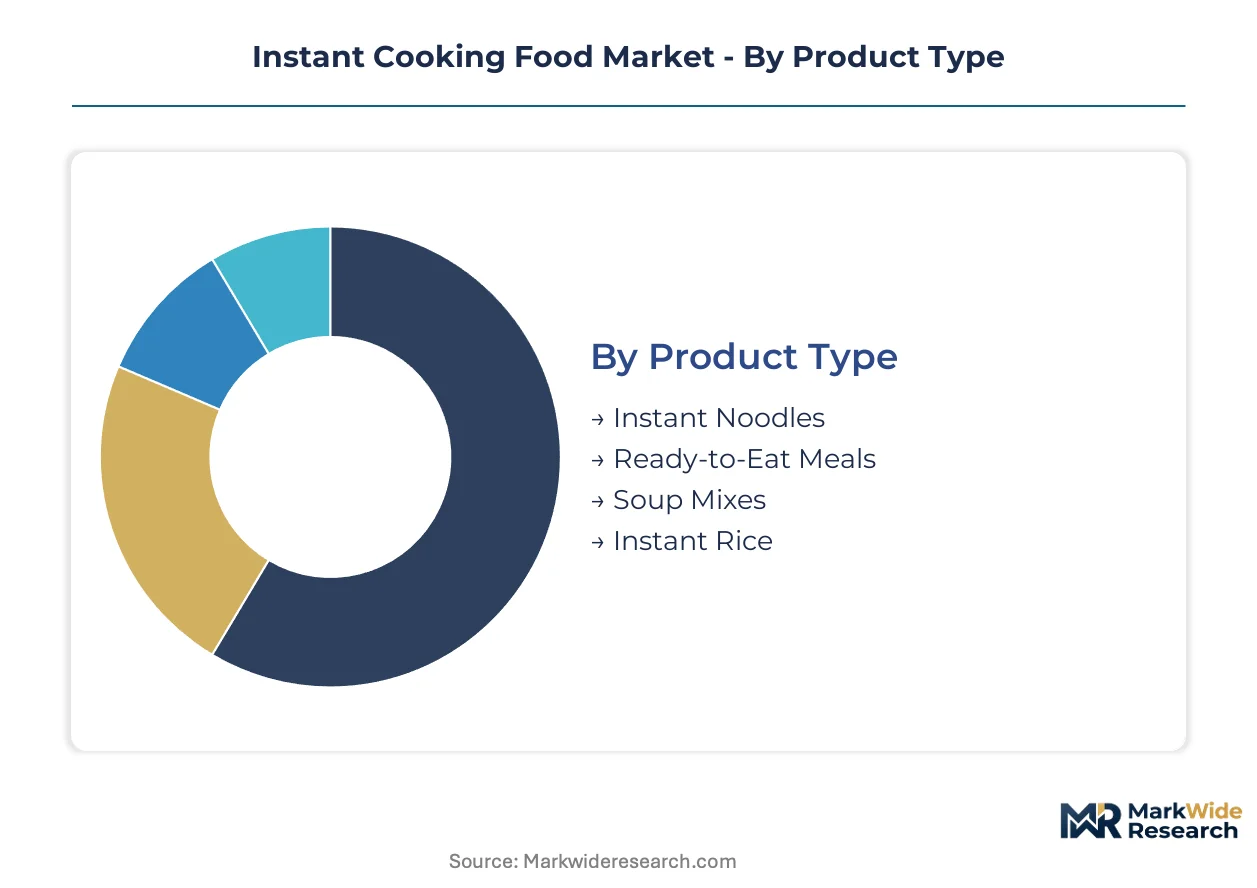
Segmentation in instant cooking food separates margin capture from volume throughput. Protein complexity and packaging technology determine profitability, while channel access dictates geographic penetration speed.
Product Type:
Margin pools concentrate where formulation barriers and thermal processing requirements intersect.
- Instant Noodles:Wheat-flour-based strands, either fried or air-dried, constitute the volume foundation across price-sensitive Asian corridors. Manufacturing concentrates in Indonesian and Vietnamese factory clusters serving Southeast Asian distribution networks, with palm oil input costs driving margin volatility in economy tiers.
- Ready-to-Eat Meals:Retort-stabilized or high-pressure processed protein-vegetable combinations command premium positioning through shelf-stable meat inclusion and complex hydration protocols. Demand clusters in Japanese and South Korean metropolitan convenience channels where single-person households prioritize protein density over preparation speed.
- Soup Mixes:Dehydrated vegetable and broth concentrates reconstituted with hot water serve institutional cafeteria procurement and residential pantry stocking in temperate climates.
- Instant Rice:Pre-cooked, dehydrated grain formats target military provisioning and disaster relief inventory requirements where cooking fuel scarcity eliminates conventional preparation.
The dominant share belongs to Instant Noodles, while Ready-to-Eat Meals is closing the gap fastest.
Distribution Channel:
Channel selection determines working capital intensity and price transparency exposure for manufacturers.
- Supermarkets:Traditional brick-and-mortar retail with dedicated ambient aisle space and promotional slotting fees structures volume access for established brands. Shelf placement negotiations in Chinese hypermarket chains consume 12-18 month lead times for new entrants seeking national distribution.
- Online Retail:Direct-to-pantry subscription models and marketplace platforms collapse wholesale layers, enabling flavor variety rotation without retail intermediary markups. Tokyo and Seoul metropolitan penetration now captures 15% of premium instant meal volume through refrigerated locker networks.
- Convenience Stores:24-hour urban retail with limited SKU count prioritizes cup noodle and microwaveable container formats for immediate consumption.
- Food Service:Industrial cafeteria, university dining, and quick-service restaurant procurement channels specify bulk dehydrated ingredients and retort pouch components.
Supermarkets retain the largest transaction volume, though Online Retail is expanding most quickly in premium segments.
Customer Type:
Demographic targeting shapes seasoning intensity, portion sizing, and packaging portability requirements.
- Millennials:Urban consumers aged 25-40 prioritize flavor novelty, clean-label positioning, and subscription-based variety rotation over pantry stockpiling. South Korean and Taiwanese manufacturers target this cohort with limited-edition collaborations and Instagram-optimized packaging aesthetics.
- Families:Multi-person households seek bulk formats, value-tier pricing, and child-appropriate sodium levels for shared meal occasions.
- Students:Price-sensitive, dormitory-constrained demand centers on cup noodle convenience and electric kettle preparation compatibility.
- Professionals:Time-compressed urban workforce segments prioritize sub-three-minute preparation cycles and desk-consumption portability.
Millennials command the highest per-capita spending, while Professionals show the steepest expansion trajectory in premium ready-to-eat formats.
Packaging Type:
Material selection governs shelf-life extension, microwave compatibility, and regulatory migration compliance costs.
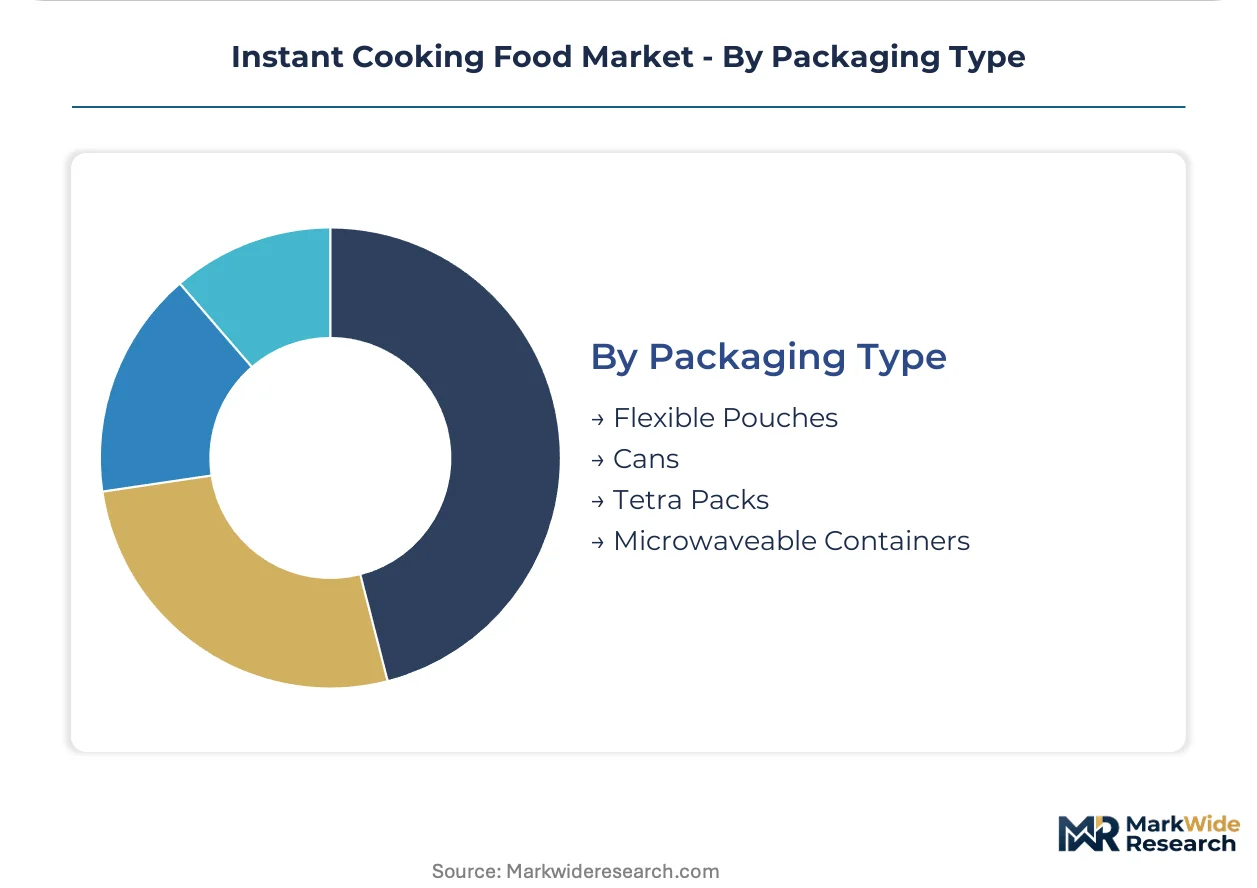
- Flexible Pouches:Multi-layer polymer laminates with oxygen barrier properties enable retort processing and lightweight logistics for soup mixes and dehydrated components. China's SAMR GB 4806.7 migration limits force reformulation of legacy adhesive structures, requiring capital retooling for export-oriented factories.
- Cans:Tinplate or aluminum containers with double-seamed closures provide indefinite shelf stability for ready-to-eat meals targeting military and emergency relief procurement.
- Tetra Packs:Aseptic carton systems with aluminum foil barriers serve liquid soup and broth concentrates in European and Japanese retail channels.
- Microwaveable Containers:Polypropylene or crystallized PET structures with vented lids enable direct heating without dish transfer, dominating Japanese convenience store and South Korean office pantry channels.
Flexible Pouches hold the installed production base advantage, though Microwaveable Containers are gaining share fastest in urban Asian markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR anchors regulatory gravity through GB standards for microbiological limits and packaging migration testing that determine factory certification across Asia-Pacific manufacturing networks. Urban workforce compression in metropolitan centers accelerates adoption of sub-five-minute preparation formats. Distribution clusters concentrate in Yangtze River Delta manufacturing hubs and Southeast Asian export corridors.
China
Working professionals in Shanghai and Beijing drive premium ready-to-eat meal adoption as schedules compress below thirty-minute dinner preparation windows. SAMR's GB 4806.7 plastic migration limits force reformulation of legacy polypropylene cup structures, requiring capital retooling for export-oriented factories in Guangdong province. Yangtze River Delta manufacturers accelerate yeast extract adoption to compensate for sodium reduction mandates under GB 28050 nutrition labeling revisions.
Japan
Single-person households aged 25-34 in Tokyo and Osaka metropolitan areas prioritize protein density and desk-consumption portability over speed alone. METI standards govern additive thresholds and front-of-pack disclosure requirements that shape seasoning oil packet reformulation. Kanto region convenience store chains deploy refrigerated locker networks capturing 15% of premium instant meal volume through direct-to-pantry subscription models.
Indonesia
Muslim-majority consumer bases in Jakarta and Surabaya accelerate demand for halal-certified pre-packaged meals across economy and premium tiers. BPOM fast-track registration streamlines certification pathways, though MUI audit backlogs extend product launch windows by 4-6 months for multinational brands. Java island manufacturing clusters dominate fried noodle production despite palm oil price volatility compressing margins in economy segments.
South Korea
Millennial consumers in Seoul Capital Area prioritize flavor novelty and Instagram-optimized packaging aesthetics over pantry stockpiling behaviors. MFDS enforces additive thresholds and labeling protocols that determine import eligibility for foreign manufacturers. Busan-Ulsan industrial corridors supply high-moisture extrusion capabilities for pea-protein chunks replicating chicken mouthfeel in cup noodle applications.
Vietnam
Emerging middle-class households in Ho Chi Minh City and Hanoi create whitespace for premium cup noodle distribution as convenience store penetration remains below Thai levels. National food safety authority implements microbiological limits and packaging material rules that reshape formulation requirements for domestic and export-oriented producers. Northern manufacturing zones around Hanoi attract seasoning sachet assembly operations sourcing dehydrated vegetables from Yunnan and Sichuan province clusters.
Instant Cooking Food Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational conglomerates leveraging captive R&D infrastructure to sustain recipe localization at scale while regional specialists anchor premium positioning through proprietary texture technologies. The market structure fragments across three strategic archetypes: global FMCG conglomerates with cross-continental formulation capabilities, Asia-Pacific noodle specialists with in-house extrusion lines, and diversified food science companies competing on umami integration and taste adaptation. Dominant competitive moves include backward integration into dehydrated ingredient supply and technology licensing agreements for retort pouch shelf-life extension.
Within the conglomerate tier, Nestlé S.A. and Unilever PLC occupy positions exemplifying global scale advantages in cross-border recipe adaptation and regulatory navigation. Among Asia-Pacific specialists, Nissin Foods Holdings Co., Ltd. represents the proprietary technology archetype, while Ajinomoto Co., Inc. anchors the food science integration segment. These three companies illustrate how geographic origin and corporate structure correlate with competitive positioning: Swiss and British-Dutch entities leverage diversified portfolios, Japanese specialists concentrate texture and umami capabilities, and each sits within distinct strategic tiers without overlapping core competencies.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Nissin Foods Holdings Co., Ltd. |
| Unilever PLC |
| The Kraft Heinz Company |
| Conagra Brands, Inc. |
| General Mills, Inc. |
| Ajinomoto Co., Inc. |
| McCain Foods Limited |
| PT Indofood CBP Sukses Makmur Tbk |
| Others |
Pricing and Supply Chain Analysis
China's SAMR GB 4806.7 plastic migration limits gate both factory certification eligibility and price differentiation across cup noodle and retort pouch tiers, forcing export-oriented manufacturers to absorb capital retooling costs while premium-positioned competitors pass compliance investments through to shelf price.
Pricing Analysis
Long-term offtake contracts dominate dehydrated vegetable procurement from Yunnan and Sichuan clusters, insulating large manufacturers from spot market volatility in palm oil and monosodium glutamate inputs. Three-tier pricing structure across premium, standard, and economy levels separates retort-stabilized protein meals from fried noodle formats and basic dehydrated soups. Cost compression in economy-tier fried noodle segments is intensifying because Malaysian and Indonesian crude palm oil futures swing unpredictably. Students and dormitory-constrained consumers show highest price sensitivity, while single-person households in Tokyo and Seoul metropolitan areas accept premium positioning for protein density and subscription variety rotation.
Supply Chain Analysis
Inventory lead times for seasoning sachet assembly have compressed as Yunnan and Sichuan province clusters scale dehydrated vegetable output, though monosodium glutamate supply remains concentrated in Thai and Japanese fermentation facilities. Manufacturing draws from Indonesian and Vietnamese factory clusters for wheat-flour noodle production, with northern Vietnam zones attracting seasoning assembly operations. Single-source vulnerability in umami additive procurement creates structural risk for flavor house procurement strategies. Distribution runs through Yangtze River Delta manufacturing hubs and Southeast Asian export corridors, with online retail channels collapsing traditional wholesale layers in Tokyo and Seoul.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with regulatory divergence between preservative permissibility regimes and clean-label compliance thresholds, as millennial demand for Instagram-optimized aesthetics and sodium-reduced formulations splits legacy mass-market positioning.
For Market Incumbents: Shield premium positioning by accelerating backward integration into high-moisture extrusion capabilities for pea-protein texturization, countering the threat of commodity assemblers dependent on outsourced textured vegetable protein. Secure halal certification pre-positioning before MUI Indonesia audit backlogs extend further, locking in fast-track BPOM registration pathways for Muslim-majority Southeast Asian markets.
For New Entrants and Emerging Players: Indonesia's BPOM fast-track registration opens whitespace for halal-certified pre-packaged meals targeting Jakarta and Surabaya's Muslim-majority consumer bases. Vietnam's emerging middle-class in Ho Chi Minh City and Hanoi presents underpenetrated convenience store distribution channels below Thai saturation levels. Launch through direct-to-pantry subscription models with refrigerated locker network partnerships, bypassing 12-18 month Chinese hypermarket shelf placement negotiations.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across retort pouch and high-pressure processing line installations as clean-label positioning requires equipment upgrades. Acquisition targets should center on regional specialists with in-house extrusion capabilities and proprietary umami science integration, rather than commodity assemblers. Watch for yeast extract and hydrolyzed soy protein adoption rates as the inflection indicator for sodium-reduction formulation viability under China's GB 28050 labeling revisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dehydrated Ingredient Supply | Yunnan and Sichuan province clusters reduce input lead times for seasoning sachet manufacturers. |
| High-Pressure Processing Line Installation | Cold pasteurization enables clean-label positioning without sacrificing ambient shelf stability. |
| Halal Certification Pre-Positioning | MUI Indonesia audit backlogs extend launch windows by 4-6 months for unprepared multinational brands. |
| Direct-to-Pantry Subscription Launch | Refrigerated locker networks in Tokyo and Seoul capture 15% of premium instant meal volume. |
| Yeast Extract Formulation Adoption | Hydrolyzed soy protein compensates for sodium reduction under China's GB 28050 labeling mandates. |
Research Methodology
Initial hypotheses were tested against primary input from food technologists, R&D directors at instant noodle manufacturers, halal certification auditors, and convenience store category buyers and refined through secondary validation against SAMR GB standards filings, BPOM registration databases, customs trade records, and retail audit data from Nielsen and Circana. Bottom-up volume modeling across manufacturing clusters triangulated with top-down expenditure analysis from institutional cafeteria procurement and military provisioning contracts.
Variance decomposition across product type, distribution channel, packaging technology, and regional regulatory framework segments structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectory blending. Forecast inputs incorporated palm oil futures volatility patterns and MUI Indonesia certification timeline compression effects.
The analysis sits within stated boundaries; outcomes outside sustained urban workforce compression or regulatory divergence on preservative permissibility would require recalibration. Forecasts reflect documented assumptions regarding halal certification pathway efficiency and freeze-dried ingredient supply scaling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Egg Powder Market
Processed Foods
United States Egg Powder Market
Processed Foods
Sugar-Free Ice Cream Market
Processed Foods
Processed Vegetable Market
Processed Foods
United States Ice Cream Market
Processed Foods
United States Fresh Noodles Market
Processed Foods
Pates Market
Processed Foods
Low Moisture Food Market
Processed Foods
India Ready to Mix Food Market
Processed Foods
Fat Free Soup Market
Processed Foods
United States Food Spread Market
Processed Foods
Global Pasta Market
Processed Foods
Processed Eucheuma Seaweed Market
Processed Foods
Potato Soup Market
Processed Foods
Low Fat Vegetable Soups Market
Processed Foods
South America Processed Meat Market