
 South Korea Foodservice Market | 2026-2036
South Korea Foodservice Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Foodservice Market Analytics
MFDS front-of-package sodium reduction guidelines is broadening reformulation priorities across national chains. CJ Foodville Corporation leverages centralized kitchen infrastructure to sustain menu standardization at scale. SPC Group anchors bakery-cafe dominance through Paris Baguette's retail density. Kyochon Food&Beverage Co. Ltd differentiates via proprietary double-frying technology in the chicken category.
South Korea foodservice denotes commercial preparation and sale of meals and beverages through organized eating establishments, encompassing full-service restaurants with table management systems, quick-service outlets operating standardized production lines, and catering operations serving institutional volumes. The sector functions as a critical consumption channel linking agricultural supply chains to urban populations. Quick Service captures the largest transaction volume through speed-optimized formats, while Delivery segments register the fastest structural expansion driven by platform integration. Full Service retains premium margin pools in business-district locations where Professionals represent the highest per-check customer type.
MFDS enforces Hazard Analysis Critical Control Point standards across central kitchens, compelling capital investment in temperature monitoring and traceability systems. KFDA-aligned local ordinances in Seoul and Busan mandate food waste reduction targets that reshape procurement specifications. Stakeholders must monitor platform commission structures and labor regulation shifts as these variables determine unit economics across Delivery and Quick Service formats.
Market Dynamics
Platform-mediated delivery integration is restructuring South Korea foodservice economics, compressing order-to-delivery cycles while elevating commission burdens that reshape unit profitability across quick-service and full-service formats.
Growth Catalysts
- Single-person household proliferation:Demographic compression toward one- and two-person residences in Seoul and Busan corridors drives demand for portion-optimized, speed-oriented meal solutions across convenience-store foodservice and compact quick-service footprints.
- MFDS nutrition labeling mandates:Front-of-package sodium and calorie disclosure requirements accelerate reformulation investment, creating product differentiation vectors for chains that achieve compliance ahead of enforcement windows.
- Cloud kitchen infrastructure:Centralized production facilities without dine-in capacity enable rapid market entry with reduced real estate exposure, particularly in dense metropolitan submarkets where rental costs constrain traditional expansion.
Market Restraints
- Agricultural input cost volatility:Domestic vegetable and protein price swings, amplified by climate-driven supply interruptions and import dependency for beef and wheat, compress margin predictability across menu cycles.
- Platform commission concentration:Two dominant delivery aggregators extract 10-15% of order value plus marketing fees, creating structural margin pressure that independent operators cannot negotiate away.
- Labor supply tightening:MFDS-mandated Hazard Analysis Critical Control Point certification requirements for kitchen staff reduce eligible labor pools, particularly in provincial markets where training infrastructure is sparse.
Strategic Opportunities
- Untapped secondary cities:Daegu, Daejeon, and Gwangju metropolitan zones exhibit foodservice penetration gaps relative to income levels, offering first-mover positioning for format-adapted entrants.
- Waste reduction incentives:Seoul and Busan municipal ordinances aligned with KFDA food waste targets create procurement specification shifts favoring suppliers with verified circular-economy credentials.
- AI-driven demand forecasting:Convergence of point-of-sale data streams with weather and event calendars enables dynamic inventory positioning, reducing spoilage rates in high-SKU bakery-cafe operations.
Industry Challenges
- HACCP compliance timeline compression:MFDS enforcement windows for central kitchen certification require simultaneous capital deployment across temperature monitoring, traceability software, and staff retraining.
- Legacy POS-platform integration:Established chains operating on-premise server-based order management face friction connecting to delivery aggregator APIs, delaying real-time inventory synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Foodservice Market |
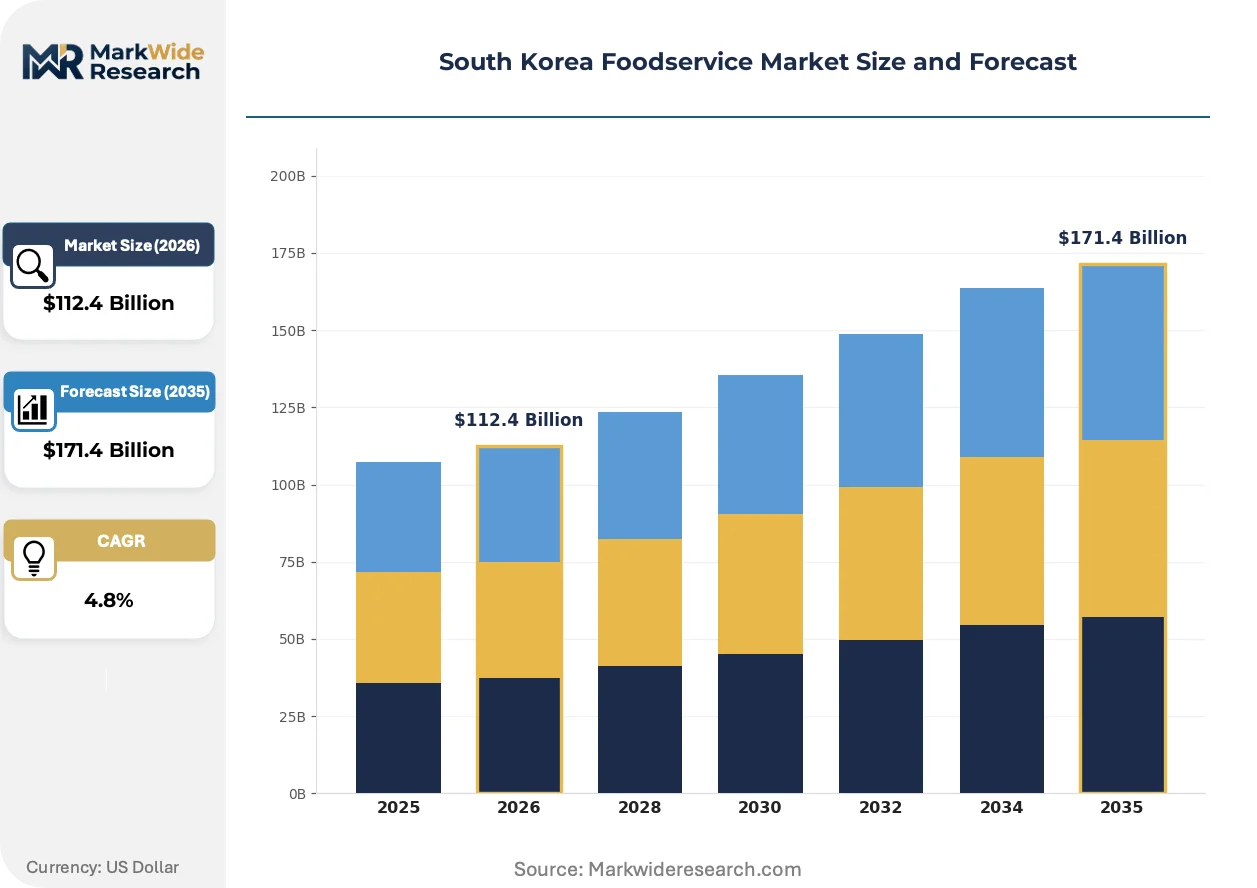
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $171.4 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Quick Service, Catering, Full Service, Delivery Customer Type: Families, Students, Tourists, Professionals Cuisine Type: Korean, Chinese, Japanese, Western Distribution Channel: Online, Offline, Mobile Apps, Third-Party Platforms |
| Companies Covered | SPC Group, Isac Co Ltd, CJ Foodville Corporation, McDonald's Corporation, Mom's Touch & Co, Genesis Co. Ltd, Shinsegae Food Co Ltd, Starbucks Corporation, Kyochon Food&Beverage Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Foodservice Market Evolving Landscape
Operational digitization is penetrating South Korea foodservice at uneven rates, with front-of-house automation advancing faster than back-of-house intelligence, creating capability gaps that differentiate early adopters from laggards.
Robotic food preparation systems are expanding into quick-service frying and assembly stations. Chains operating high-volume chicken and burger formats deploy automated oil filtration and patty grilling to reduce labor dependency during peak hours. This technology is compressing throughput variance between staffed and understaffed shifts, stabilizing service-time consistency.
MFDS sodium reduction guidelines are tightening across processed and prepared food categories. National chains must reformulate core menu items to meet phased targets, redirecting R&D resources toward flavor-masking technologies and alternative seasoning systems. The bakery-cafe segment faces particular pressure given bread and pastry base sodium levels.
Subscription-based meal plans are displacing transactional ordering in urban professional segments. Office workers in Seoul's Gangnam and Yeouido districts pre-commit to weekly lunch deliveries, shifting volume predictability benefits to operators while reducing per-order platform fees. This model concentrates most rapidly among health-positioned concepts with rotating seasonal menus.
South Korea Foodservice Market Segmentation
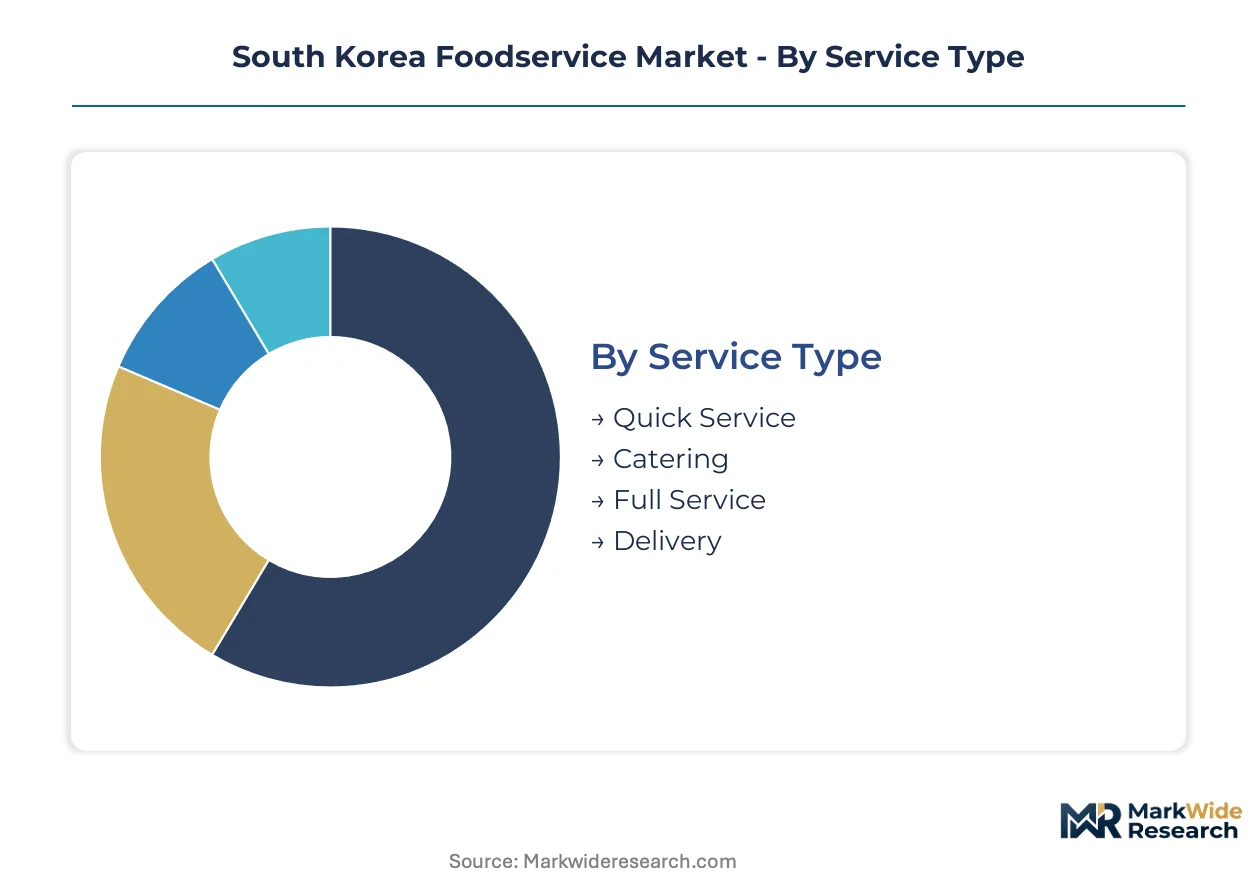
Service format distinctions in South Korea foodservice determine capital intensity, labor models, and regulatory exposure. Customer composition and cuisine positioning further stratify margin structures across Seoul's metropolitan corridor and Busan's coastal cluster.
Service Type:
Speed-optimized production systems and table-management infrastructure separate formats by operational velocity and real estate requirements.
- Quick Service:Standardized assembly lines with speed-optimized production protocols dominate transaction volume. Demand concentrates in Seoul's dense residential submarkets where single-person households seek portion-controlled, rapid-turnover meal solutions.
- Full Service:Table-management systems with staffed floor operations command premium check averages in business-district locations. MFDS HACCP compliance requirements elevate capital barriers for central kitchen investments.
- Catering:Institutional-volume production serving corporate and event segments with batch-cooking infrastructure.
- Delivery:Platform-dependent fulfillment without dine-in capacity is expanding most quickly through cloud kitchen proliferation in high-rent metropolitan zones.
Mature deployment sits with Quick Service. Newer deployment is concentrated in Delivery.
Customer Type:
Spending patterns and occasion frequency vary sharply across demographic cohorts, reshaping menu engineering and location strategy.
- Professionals:Office workers in Gangnam and Yeouido districts drive weekday lunch volume with elevated per-check spending. Subscription meal plans are displacing transactional ordering among this cohort.
- Families:Multi-generational dining occasions concentrate in full-service formats during weekends and holidays.
- Students:Price-sensitive demand clusters near university districts in Seoul, Daejeon, and Gwangju with high frequency, low-margin transaction profiles.
- Tourists:Seasonal inbound volume concentrates in Myeongdong and Hongdae corridors, favoring Korean cuisine positioning with multilingual service capability.
Revenue concentration aligns with Professionals. Volume expansion is fastest among Students.
Cuisine Type:
Flavor-profile positioning determines supply chain sourcing zones and MFDS sodium-reduction compliance intensity.
- Korean:Fermentation-based preparation methods with high sodium content face acute reformulation pressure under MFDS front-of-package guidelines. Demand remains anchored in domestic consumption and tourist orientation.
- Western:Burger and pizza formats deploy automated grilling and frying systems to reduce labor dependency during peak hours. Expansion concentrates in young professional segments seeking international variety.
- Chinese:Wok-based cooking infrastructure with specialized ventilation requirements elevates real estate fit-out costs.
- Japanese:Raw-fish handling protocols impose stringent MFDS temperature monitoring and traceability investments.
Market depth is greatest in Korean. Format innovation is advancing fastest in Western.
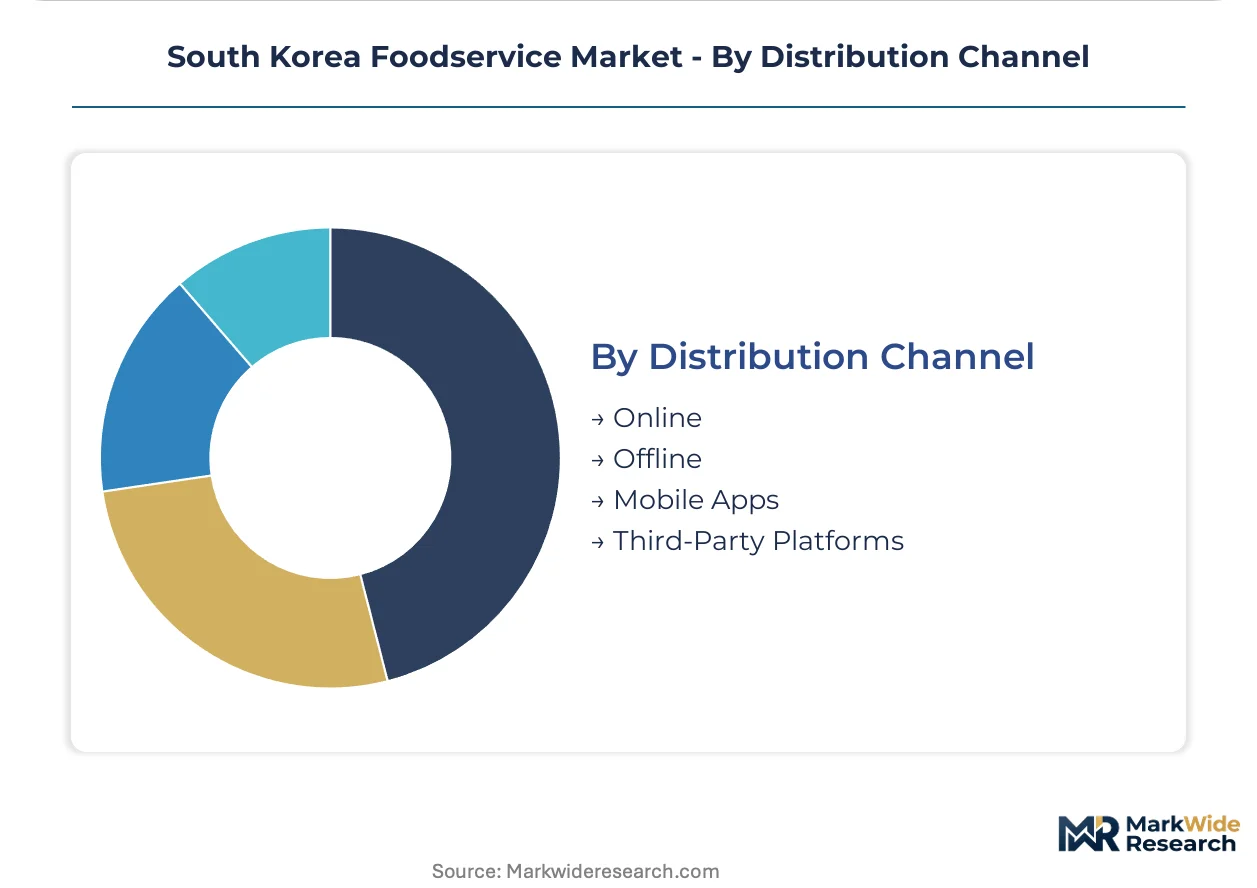
Distribution Channel:
Order origination point determines platform commission exposure and customer data ownership.
- Third-Party Platforms:Aggregator-mediated fulfillment extracts 10-15% of order value plus marketing fees, compressing unit economics for independent operators who lack negotiating leverage.
- Mobile Apps:Direct-to-consumer ordering infrastructure enables subscription model deployment and reduced per-transaction platform costs.
- Online:Web-based ordering through proprietary sites retains margin but requires marketing investment to drive traffic.
- Offline:Walk-in and telephone orders preserve full margin capture but lack demand forecasting data streams.
Volume leadership rests with Third-Party Platforms. Margin protection is shifting toward Mobile Apps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul Capital Area dominates South Korea foodservice activity, concentrating transaction volume and platform innovation density within the metropolitan corridor connecting Gangnam, Yeouido, and Hongdae districts.
Seoul Capital Area
Single-person households in Gangnam and Yeouido drive weekday lunch subscription volumes. MFDS front-of-package sodium labeling mandates accelerate reformulation timelines for chains headquartered here. Cloud kitchen clusters in Mapo and Seongdong submarkets enable rapid delivery-only expansion with reduced real estate exposure.
Busan-Ulsan
Coastal tourism and port-worker demand sustain full-service Korean cuisine operations. KFDA-aligned municipal ordinances mandate food waste reduction targets that reshape procurement specifications. Haeundae and Seomyeon corridors concentrate premium-positioned concepts serving business travelers and domestic tourists.
Daegu-Gyeongbuk
University district density in Daegu creates price-sensitive, high-frequency transaction profiles among student populations. MFDS HACCP certification requirements reduce eligible kitchen staff pools in this secondary market. Kyungpook National University corridor anchors quick-service clustering with compact footprints.
Daejeon-Sejong
Government worker concentrations in Sejong City generate predictable weekday demand for portion-controlled meal solutions. Central kitchen infrastructure investments serve both administrative and research institute populations. Daejeon Express Bus Terminal submarket functions as a logistics hub for provincial supply distribution.
Gwangju-Honam
Untapped foodservice penetration relative to income levels creates first-mover positioning opportunities for format-adapted entrants. Agricultural input cost volatility affects local vegetable supply chains more acutely than metropolitan markets. Dong-gu commercial district exhibits emerging quick-service density alongside traditional market infrastructure.
South Korea Foodservice Market Competitive Landscape
Premium-margin players sit above commodity-margin players across central kitchen infrastructure and platform integration depth. National chains with proprietary production networks capture efficiency advantages that independent operators cannot replicate. Three archetypes dominate: conglomerate-affiliated foodservice divisions, delivery-native cloud kitchen operators, and international format licensees. Consolidation pressure intensifies through M&A activity targeting regional chains and strategic partnerships between aggregators and kitchen infrastructure providers.
Within the conglomerate-affiliated tier, SPC Group and CJ Foodville Corporation exemplify scale-driven central kitchen standardization. Kyochon Food&Beverage Co. Ltd occupies a specialist position in protein-focused quick-service formats. These three entities anchor distinct competitive vectors—bakery-cafe retail density, multi-brand portfolio diversification, and proprietary cooking technology—without overlapping strategic positioning.
| Leading Market Players |
|---|
| SPC Group |
| Isac Co Ltd |
| CJ Foodville Corporation |
| McDonald's Corporation |
| Mom's Touch & Co |
| Genesis Co. Ltd |
| Shinsegae Food Co Ltd |
| Starbucks Corporation |
| Kyochon Food&Beverage Co. Ltd |
| Others |
Value Network & Pricing Analysis
Certification-tier divergence between MFDS HACCP-compliant chains and uncertified independents manifests in both procurement premiums and supply chain access. Premium-positioned operators command ingredient cost advantages through direct agricultural contracts, while commodity-tier players absorb volatility through spot-market vegetable and protein sourcing.
Pricing Analysis
Throughput-based value anchoring dominates quick-service economics, with chains pricing against meal-per-hour productivity rather than ingredient cost-plus models. Three-tier pricing structure across premium, standard, and economy levels separates full-service Gangnam concepts from suburban quick-service and convenience-store tiers. Cost compression in the independent tier is intensifying because platform commission stacking erodes already-thin margins. Students near university districts exhibit highest price sensitivity, while Seoul professionals in subscription meal plans show lowest elasticity.
Supply Chain Analysis
Domestic-content requirements under KFDA-aligned municipal ordinances are reshaping procurement specifications toward verified local suppliers. Agricultural inputs draw from domestic vegetable corridors and imported beef and wheat streams. Temperature-controlled logistics infrastructure and traceability software investments dominate capital allocation. Single-source vulnerability concentrates in cloud kitchen protein supply contracts. Distribution runs through centralized kitchen networks feeding multi-unit retail footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
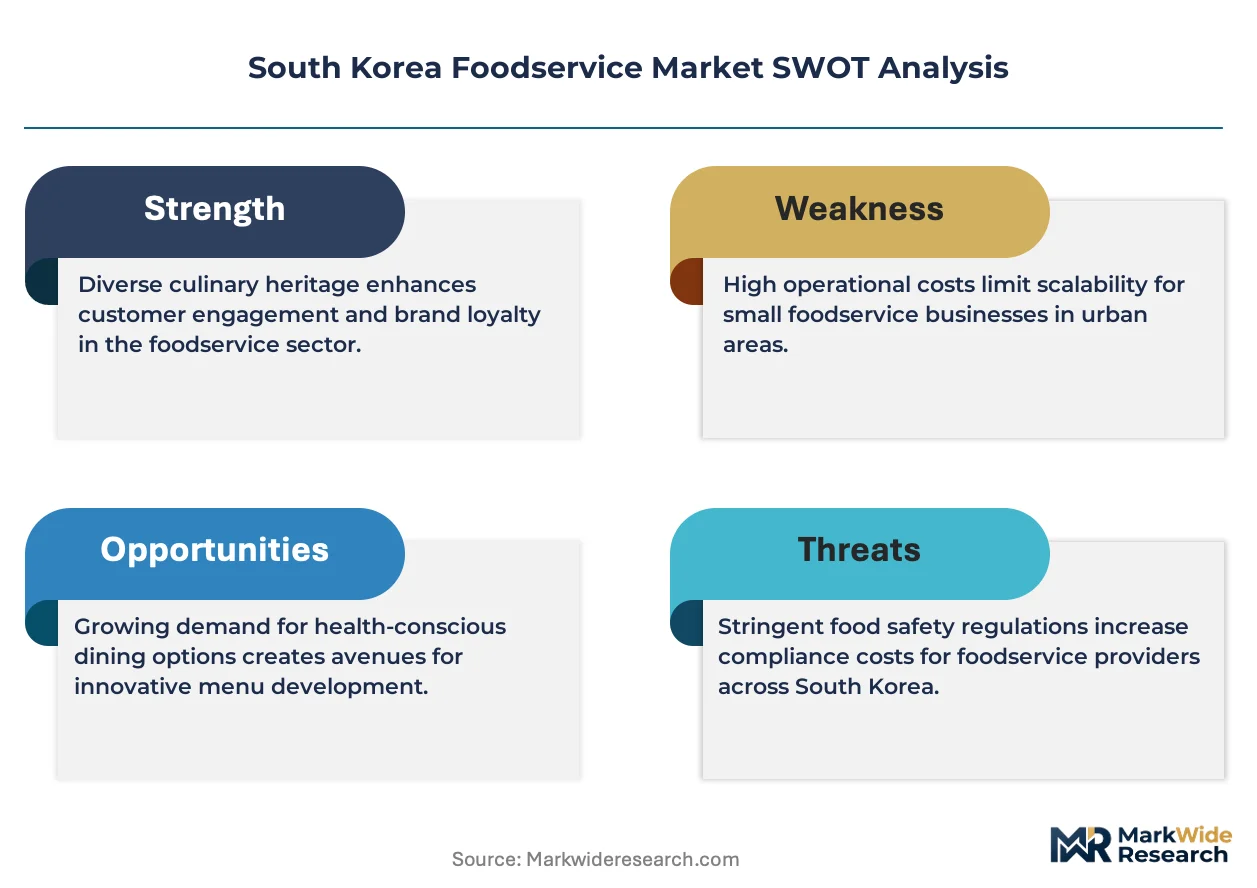
MFDS HACCP certification bottlenecks prop pricing power for compliant chains, creating supply-constrained tiering that favors incumbents with capital deployment capacity.
For Market Incumbents: Lock in cloud kitchen infrastructure in Mapo and Seongdong submarkets ahead of secondary-city platform saturation. Secure backward integration into domestic vegetable supply contracts to buffer climate-driven price swings. Platform commission concentration threatens independent competitors unable to negotiate volume discounts. For New Entrants and Emerging Players: Government workers in Sejong City represent an underserved buyer archetype with predictable weekday demand and limited format competition. Daegu university corridors offer white-space positioning for price-optimized quick-service concepts. Gwangju-Honam's income-penetration gap supports first-mover cloud kitchen deployment. Direct-to-consumer mobile app subscription models reduce platform fee exposure. For Investors and Strategic Acquirers: Re-rating potential sits with regional chains possessing central kitchen infrastructure given MFDS enforcement timeline compression. Five-to-ten-year viability favors operators with proprietary production networks over platform-dependent delivery-native concepts. Acquisition targets should demonstrate HACCP compliance progress and secondary-city footprint density. Watch for municipal food waste ordinance expansion as signal for procurement-specification inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Central Kitchen Certification Acceleration | MFDS HACCP compliance ahead of enforcement windows locks in supply chain access and procurement premiums. |
| Cloud Kitchen Cluster Expansion | High-rent metropolitan submarkets in Seoul enable delivery-only growth with reduced real estate exposure. |
| Subscription Model Deployment | Direct-to-consumer weekly meal plans in Gangnam and Yeouido reduce per-order platform commission burdens. |
| Secondary City Format Adaptation | Daegu, Daejeon, and Gwangju penetration gaps offer first-mover positioning for scaled entrants. |
| Agricultural Contract Backward Integration | Domestic vegetable supply agreements buffer climate-driven input cost volatility affecting spot-market competitors. |
Research Methodology
Multi-period observation of MFDS regulatory filing timelines, platform commission structures, and central kitchen deployment patterns anchored the trend analysis, supplemented by interviews with quick-service chain operations directors, MFDS compliance officers, agricultural procurement managers, and delivery platform account executives. Secondary validation drew from MFDS enforcement notices, Seoul and Busan municipal ordinance databases, Korea Agro-Fisheries & Food Trade Corporation agricultural price indices, and foodservice operator SEC filings. Bottom-up unit economics modeling triangulated against top-down metropolitan consumption estimates.
Input-output matrices mapped service format capital intensity, labor models, and regulatory exposure across customer and cuisine segments over the projection horizon. Segmentation dimensions modeled include service type velocity, customer occasion frequency, cuisine sodium-reduction compliance intensity, and distribution channel platform dependency. CAGRs derived from trend extrapolation of single-person household formation, cloud kitchen penetration curves, and subscription meal plan adoption rates.
Revisions become necessary when MFDS enforcement windows accelerate, platform commission structures shift materially, or climate-driven agricultural input disruptions exceed historical variance bands. Forecasts reflect documented assumptions about regulatory timeline adherence and metropolitan demand concentration. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Global Digital Food Delivery Market
Food Service
Commercial Air Fryer Oven Market
Food Service
Food Delivery Services Market
Food Service
Food Service Gloves Market
Food Service
Bangladesh Food Service Market
Food Service
United Kingdom Full Service Restaurants Market
Food Service
Beverage Coaster Market
Food Service
Europe Cloud Kitchen Market
Food Service
Singapore Food Service Market
Food Service
Pizza Foodservice Market
Food Service
Inflight Catering Market
Food Service
Oman Food Service Market
Food Service
Latin America Biodegradable Food Service Disposables Market
Food Service
Contract Blending Services Market
Food Service
Pizza Oven Market
Food Service
Europe Food Service Market