
 Undercounter Ice Makers Market | 2026-2036
Undercounter Ice Makers Market Size, Share, and Industry Trends Forecast 2026-2036
Undercounter Ice Makers Market Analytics
Stainless steel is hardening as the dominant enclosure material in premium undercounter ice maker lines, replacing lower-grade coated metals that corrode in high-humidity kitchen environments. Scotsman leverages its commercial refrigeration heritage to sustain specification-grade positioning across North American food service channels. Manitowoc anchors its portfolio with modular designs that allow field-configured ice production scaling. GE Profile competes on residential crossover appeal, bridging built-in kitchen aesthetics with commercial-grade output capacity.
An undercounter ice maker is a self-contained or modular refrigeration appliance engineered to produce and store ice cubes or nuggets within a cabinet dimensioned for installation beneath standard countertops, typically operating on compressor-driven vapor-compression cycles with integrated water filtration and automated harvest mechanisms. These units serve restaurants, bars, hotels, and healthcare facilities requiring continuous ice availability without floor-space allocation for standalone machines. Self-contained units dominate current volume due to simplified installation and maintenance, while modular configurations capture expanding share in high-throughput food service environments where separate storage bins extend production flexibility. The food service application segment leads absolute demand, though hospitality-driven replacement cycles are accelerating fastest as hotel renovation activity intensifies.
The U.S. Department of Energy enforces minimum efficiency standards for commercial ice-making equipment under federal appliance regulations, while NSF International certifies sanitation compliance for food zone materials and cleanability protocols. The EPA's ENERGY STAR program differentiates qualified models, creating procurement preference among institutional buyers and chain operators with sustainability mandates. Stakeholders must monitor evolving federal efficiency tier resets and state-level refrigerant phase-down schedules that will reshape compressor technology choices and manufacturing compliance costs.
Market Dynamics
Equipment refresh cycles across North American food service channels are compressing as the U.S. Department of Energy tightens commercial refrigeration efficiency standards, forcing operators to retire legacy units ahead of historical replacement timelines.
Growth Catalysts
- Sun Belt Hospitality Construction:Florida, Texas, and Arizona are experiencing elevated hotel and restaurant buildout activity, concentrating demand for compact ice production equipment in high-temperature climates where ice consumption per seat exceeds national averages.
- ENERGY STAR Procurement Mandates:Institutional buyers and multi-unit chain operators with sustainability commitments now require qualified equipment, creating specification advantages for manufacturers achieving EPA certification thresholds.
- Stainless Steel Enclosure Adoption:Premium food service operators are specifying corrosion-resistant cabinet materials that withstand high-humidity kitchen environments, extending equipment service life and reducing total cost of ownership.
Market Restraints
- Copper and Aluminum Input Volatility:Compressor manufacturing depends on conductive metals subject to commodity price swings, compressing margins for mid-tier equipment producers unable to pass through cost increases to price-sensitive buyers.
- Refrigerant Supply Concentration:Hydrofluorocarbon production concentrates among a limited supplier base in China, exposing North American manufacturers to import tariff exposure and phase-down schedule uncertainty.
- NSF Sanitation Certification Friction:Food zone material approval timelines extend product development cycles, delaying commercialization of design innovations and freezing smaller competitors out of specification-grade channels.
Strategic Opportunities
- Healthcare Facility Underpenetration:Hospital cafeterias and long-term care dining operations represent an underserved vertical with stringent sanitation requirements that favor premium equipment with automated cleaning protocols.
- Modular Configuration Expansion:High-throughput food service environments are adopting field-scalable production systems that separate ice generation from storage, enabling capacity expansion without full unit replacement.
- State-Level Refrigerant Incentives:California and New York are advancing early adoption credits for low-global-warming-potential equipment, creating procurement preference windows ahead of federal mandate timelines.
Industry Challenges
- EPA Certification Timeline Compression:Accelerated efficiency tier resets require engineering validation cycles that outpace traditional product development calendars, straining R&D resource allocation.
- Legacy Control System Integration:Smart connectivity features must interface with existing building management protocols, creating firmware compatibility burdens and field commissioning complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Undercounter Ice Makers Market |
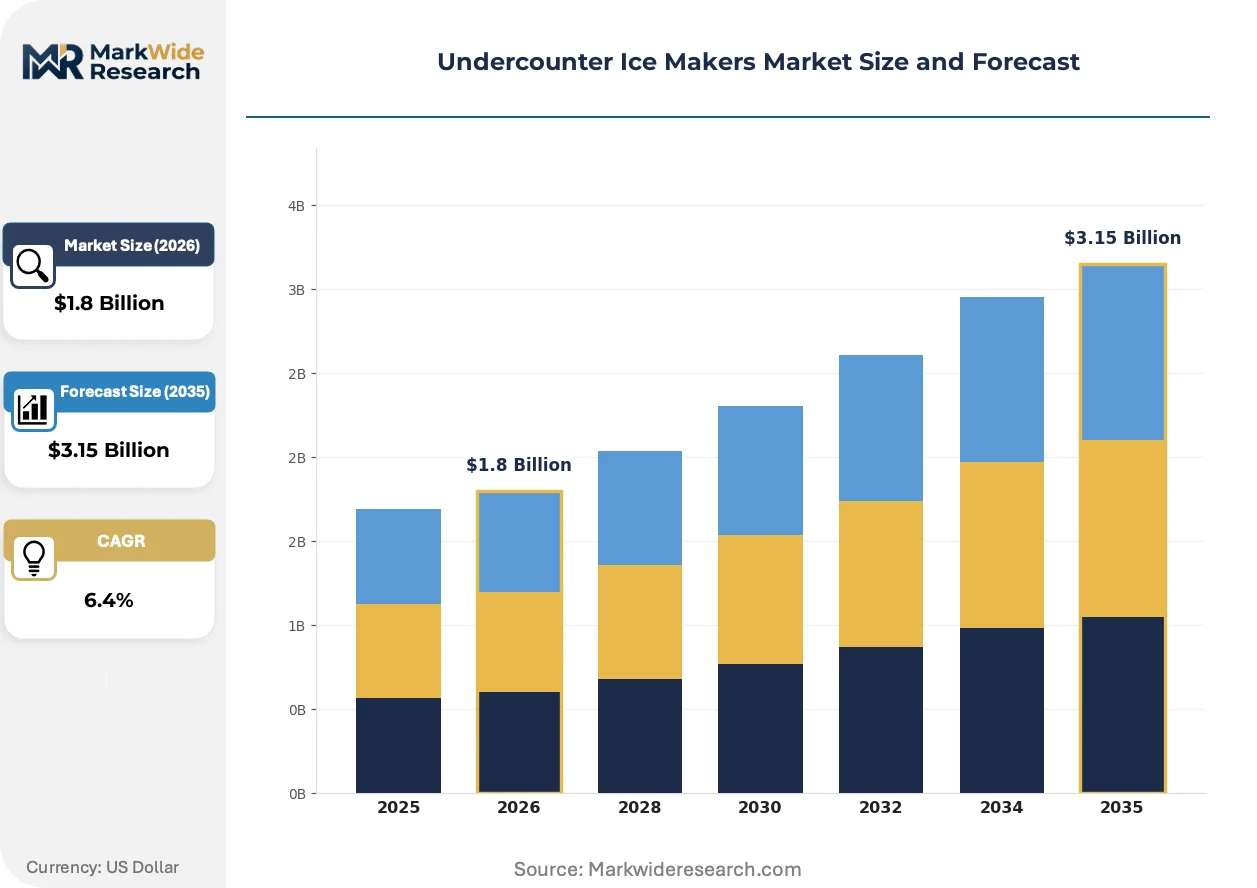
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular, Self-Contained, Countertop, Portable End User: Restaurants, Bars, Hotels, Healthcare Facilities Size: Small, Medium, Large, Extra Large Application: Food Service, Hospitality, Healthcare, Commercial Use |
| Companies Covered | Naixer, EUHOMY, Scotsman, NewAir, Frigidaire, Manitowoc, VEVOR, Kismile, GE Profile, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Undercounter Ice Makers Market Evolving Landscape
Active transformation in undercounter ice maker design centers on three vectors: compressor technology evolution, regulatory compliance architecture, and procurement model restructuring. These forces are reshaping how equipment is specified, purchased, and deployed across food service and hospitality verticals.
Variable-speed compressor technology is absorbing market share from fixed-speed alternatives by modulating ice production to match real-time demand rather than cycling on-off. Large-format restaurant operators with fluctuating service intensity are specifying these units to reduce energy consumption during low-traffic periods. The technology is absorbing specification priority in segments where utility rebates reward load-matching behavior, compressing demand for conventional compressor architectures.
The U.S. Department of Energy's amended commercial refrigeration standards are mandating minimum efficiency coefficients that legacy equipment cannot meet, forcing redesign of condenser coil geometry and insulation systems. Manufacturers are responding with vacuum-insulated panel integration and microchannel heat exchangers to achieve compliance thresholds. The regulation is absorbing engineering resources disproportionately among mid-tier producers lacking scale economies for rapid platform redevelopment.
Chain operators are consolidating procurement authority to corporate-level sustainability offices, displacing historically decentralized equipment purchasing by individual franchisees or property managers. This concentration is favoring manufacturers with national service networks and standardized maintenance protocols over regional specialists. The shift is most visible among quick-service restaurant brands with multi-state footprints and centralized capital planning functions.
Undercounter Ice Makers Market Segmentation
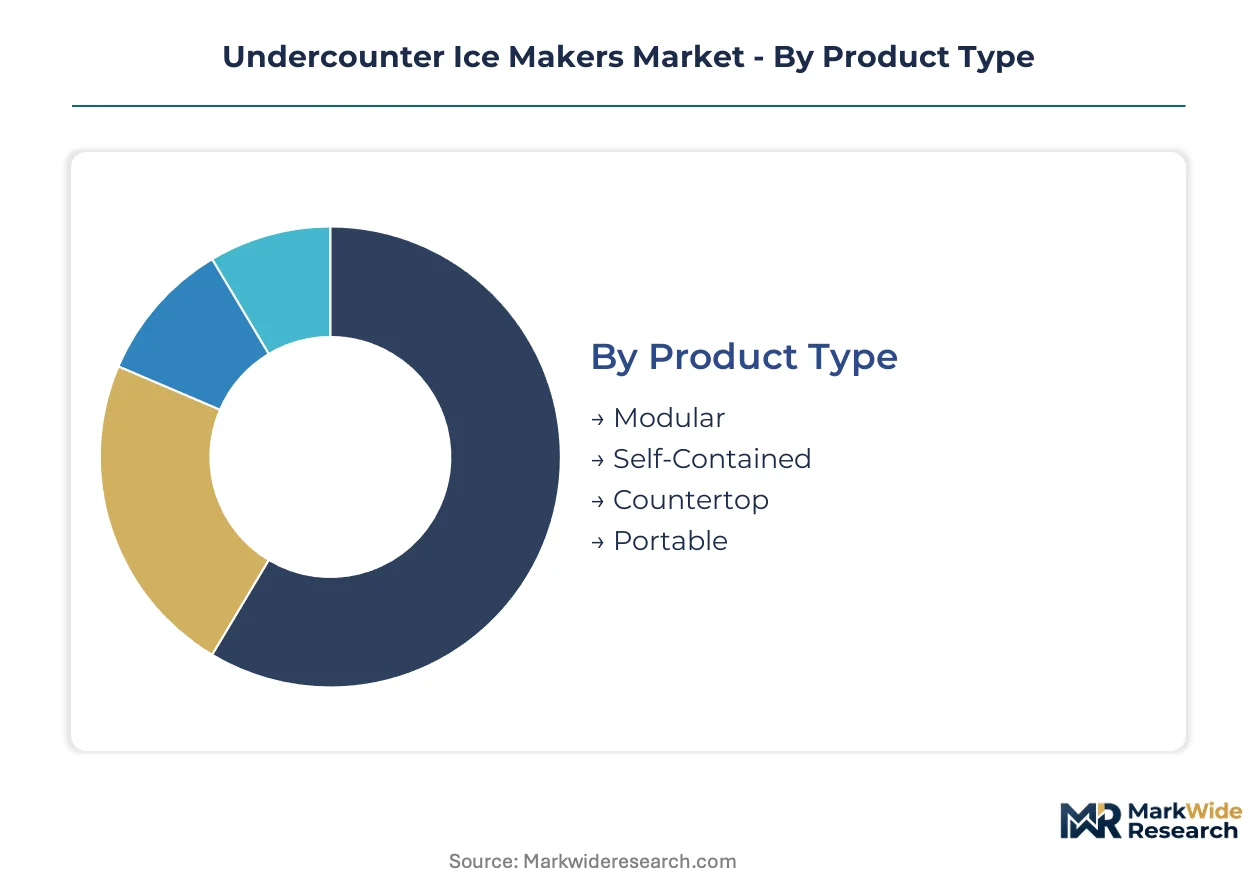
Undercounter ice maker purchasing decisions pivot on installation constraints and operational scale, with self-contained units dominating retrofit scenarios while modular configurations capture new construction. Segmentation reveals how equipment specification varies across food service density, building infrastructure age, and capital planning cycles.
Product Type:
Standalone units serve operators seeking plug-and-play deployment without contractor coordination, while embedded configurations demand deeper kitchen design integration during buildout phases.
- Modular:Field-separable ice generation heads and remote storage bins enable capacity scaling without full equipment replacement. Demand concentrates in high-throughput Florida and Texas restaurant buildouts where production flexibility outweighs initial cost premiums.
- Self-Contained:Integrated compressor, evaporator, and storage within a single cabinet dimensioned for standard undercounter cutouts. Hotel renovation cycles across Arizona and Nevada specify these units for accelerated installation timelines and reduced contractor coordination.
- Countertop:Compact units positioned above counter height for front-of-house beverage stations.
- Portable:Mobile castor-mounted configurations for catering and temporary food service operations.
Self-contained configurations lead volumes today; modular designs are gaining share fastest.
End User:
Capital availability and ice consumption intensity create tiered demand patterns, with high-volume operators prioritizing durability and low-volume settings emphasizing acquisition cost.
- Restaurants:Full-service and quick-service operators with continuous ice demand during service windows. Texas and Florida independent restaurants specify NSF-certified units with automated cleaning to reduce labor burden during peak staffing shortages.
- Hotels:Property-wide ice provisioning for guest floors, banquet facilities, and pool bars. Arizona resort construction is driving specification of stainless steel enclosures resistant to chlorinated humidity exposure.
- Bars:Cocktail-focused venues with premium ice shape requirements for craft beverage programs.
- Healthcare Facilities:Hospital cafeterias and long-term care dining with stringent sanitation protocols.
Restaurants dominate current procurement volumes; healthcare facilities are expanding most quickly as aging infrastructure triggers replacement cycles.
Size:
Physical envelope constraints in legacy buildings versus greenfield design freedom create divergent specification pathways across the dimensional spectrum.
- Small:Under-15-inch widths for coffee shops and compact bar installations.
- Medium:Standard 24-inch widths matching residential cabinetry modules.
- Large:30-inch and wider cabinets for high-volume food service. Arizona and Nevada casino-resort kitchens specify these units for banquet and buffet operations where ice consumption per seat exceeds national benchmarks.
- Extra Large:Custom-width configurations for institutional kitchens and central commissaries. Texas healthcare systems deploy these in regional food production facilities serving multiple satellite locations.
Medium sizes lead absolute shipments today; large formats are climbing the fastest as Sun Belt hospitality construction intensifies.
Application:
Regulatory exposure and sanitation liability create distinct procurement behaviors across use environments, with food-contact applications demanding certified materials and documentation.
- Food Service:Restaurants, cafeterias, and catering operations with direct ice-to-food contact. Florida and Texas operators face EPA ENERGY STAR procurement mandates from corporate sustainability offices, compressing demand toward certified models.
- Hospitality:Guest-facing hotel and resort applications where equipment aesthetics influence brand perception. Arizona luxury properties specify panel-ready units that integrate with millwork finishes.
- Healthcare:Patient and staff dining with Joint Commission sanitation oversight.
- Commercial Use:Office buildings, convenience stores, and non-food retail with intermittent demand patterns.
Food service anchors current demand; hospitality applications are expanding most quickly as hotel renovation activity accelerates across Sun Belt states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sun Belt hospitality construction clusters anchor demand geography for undercounter ice makers, with regulatory pressure and climate intensity concentrating procurement in specific metropolitan corridors.
United States
Florida and Texas hotel buildouts drive specification volume for stainless steel enclosures resistant to chlorinated humidity. The EPA's ENERGY STAR program mandates qualified equipment for institutional buyers, compressing demand toward certified models. Arizona casino-resort kitchens in Phoenix and Scottsdale deploy large-format units for banquet operations where ice consumption per seat exceeds national benchmarks.
Germany
Commercial kitchen renovation cycles accelerate replacement of legacy refrigeration equipment ahead of EU F-Gas Regulation phase-down schedules. The country's national energy efficiency regulator enforces minimum performance standards for commercial cooling appliances, forcing platform redesigns. Bavarian food service equipment distributors in Munich anchor specification-grade procurement for central European hospitality chains.
China
Urban hotel construction in Shanghai and Guangzhou concentrates demand for compact ice production systems in high-temperature climates. The Ministry of Ecology and Environment advances refrigerant phase-down timelines that reshape compressor technology choices. Pearl River Delta manufacturing clusters supply heat exchanger components to North American original equipment manufacturers facing tariff exposure.
Japan
Tokyo hospitality renovation activity intensifies replacement cycles for aging food service infrastructure in dense urban districts. METI efficiency standards for commercial refrigeration equipment mandate performance thresholds that legacy units cannot meet. Osaka-based restaurant operators specify automated cleaning protocols to reduce labor burden during persistent staffing shortages.
Australia
Queensland resort construction drives demand for corrosion-resistant cabinet materials in tropical coastal environments. The country's national standards body certifies sanitation compliance for food zone materials, extending product development timelines for imported equipment. Sydney and Melbourne hospitality clusters specify modular configurations enabling capacity scaling without full unit replacement.
Undercounter Ice Makers Market Competitive Landscape
Global majors compete with regional champions across specification-grade and price-accessible tiers, creating a bifurcated structure where heritage refrigeration brands anchor premium food service channels while Asian fabricators capture residential crossover volume. The vendor base stratifies across three archetypes: diversified appliance conglomerates with commercial refrigeration heritage, specialized food service equipment manufacturers with modular platform expertise, and direct-to-consumer brands leveraging e-commerce distribution. Capacity expansion and certification-driven product redesign represent dominant competitive moves as efficiency mandates compress development calendars.
Within the heritage refrigeration tier, Scotsman and Manitowoc exemplify specification-grade positioning through commercial heritage and modular design architecture. GE Profile occupies a position bridging residential kitchen aesthetics with food service output requirements. Among direct-to-consumer specialists, EUHOMY and VEVOR represent price-accessible alternatives capturing volume through e-commerce channels.
| Leading Market Players |
|---|
| Naixer |
| EUHOMY |
| Scotsman |
| NewAir |
| Frigidaire |
| Manitowoc |
| VEVOR |
| Kismile |
| GE Profile |
| Others |
Value Network & Pricing Analysis
Multi-unit chain operators with centralized procurement authority are consolidating specification-grade purchasing across North American food service channels, compressing pricing power toward manufacturers with national service networks and ENERGY STAR certification portfolios. This buyer concentration is reshaping how equipment tiers are positioned and how margin capture distributes across the value chain.
Pricing Analysis
Copper and aluminum commodity swings flow directly into compressor manufacturing costs, forcing mid-tier producers to absorb margin compression rather than risk volume loss to price-sensitive independent restaurants. Pricing stratifies across premium specification-grade, standard NSF-certified, and economy residential-crossover tiers, with stainless steel enclosure quality and automated cleaning protocols driving tier separation. Cost compression in the mid-tier is intensifying because Chinese refrigerant supply uncertainty and tariff exposure limit pass-through flexibility. Independent restaurants in Texas and Florida exhibit highest price sensitivity, while Arizona casino-resort operators prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Container freight rates from Pearl River Delta manufacturing clusters to North American distribution hubs remain elevated versus historical baselines, compressing landed costs for heat exchanger components and electronic control modules. Compressor production draws from China, Mexico, and the United States, with condenser coil fabrication concentrating in Guangdong and Baja California. Single-source vulnerability in hydrofluorocarbon refrigerant supply from Chinese chemical producers exposes North American OEMs to import tariff volatility and phase-down schedule uncertainty. Distribution runs through food service equipment distributors in Dallas, Atlanta, and Chicago, with direct-to-contractor e-commerce channels capturing residential crossover volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The undercounter ice maker market functions as a stable compounder anchored by mandatory equipment refresh cycles driven by federal efficiency standard tightening, creating predictable replacement demand irrespective of macroeconomic volatility.
For Market Incumbents: Anchor specification-grade positioning through accelerated ENERGY STAR certification investment ahead of federal tier resets, while deepening backward integration into compressor component supply to offset Chinese refrigerant tariff exposure. Defend against modular-system specialists by embedding field-scalable architecture into core platforms, preventing displacement in high-throughput Florida and Texas buildouts. For New Entrants and Emerging Players: Launch via direct-to-contractor e-commerce channels targeting price-sensitive independent restaurant operators in Sun Belt secondary markets underserved by national distributor networks. Healthcare facility food service represents the most penetrable vertical, with automated cleaning protocols and Joint Commission sanitation documentation serving as the critical go-to-market wedge against heritage brands. For Investors and Strategic Acquirers: Diversified commercial refrigeration conglomerates represent the most active acquirer category in this space, consolidating regional specialists to capture procurement centralization tailwinds. Targets with modular platform expertise and established NSF certification pipelines offer strongest long-term viability through the efficiency mandate cycle. Monitor EPA efficiency tier reset announcements as the primary inflection signal for accelerated replacement demand windows.| Strategic Initiative | Industry Significance |
|---|---|
| ENERGY STAR Certification Acceleration | EPA qualification thresholds create specification priority in institutional procurement channels. |
| Modular Platform Expansion | Field-separable ice generation heads capture high-throughput food service demand in Texas and Florida. |
| Stainless Steel Enclosure Standardization | Corrosion-resistant cabinets extend service life in chlorinated Arizona resort environments. |
| Automated Cleaning Protocol Development | Reduced labor burden addresses persistent staffing shortages in Osaka restaurant operations. |
| Refrigerant Technology Transition | Low-global-warming-potential compressors align with California and New York early adoption incentives. |
Research Methodology
Coverage spans the United States, Germany, China, Japan, and Australia, with primary inputs from each market informing demand pattern validation. The analysis combines structured interviews with food service equipment distributors, commercial kitchen design consultants, and chain operator procurement directors with secondary validation from EPA ENERGY STAR certification databases, DOE efficiency standard dockets, and NSF International sanitation compliance registries. Bottom-up equipment shipment modeling triangulates against top-down hospitality construction spending data across Sun Belt metropolitan corridors.
Granularity-level modeling disaggregates volume and value across product type, end user, size category, and application segments, with additional dimensional detail on regional regulatory framework clusters and refrigerant technology pathways. CAGRs derive from installed base replacement cycle analysis overlaid with new construction permit flows and efficiency mandate compliance deadlines. Compressor technology evolution curves and food service labor cost trajectories inform demand elasticity assumptions throughout the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EPA efficiency tier reset schedules or sustained copper price volatility. Forecasts reflect documented assumptions regarding hospitality construction permit sustainability and refrigerant phase-down implementation pacing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Takeout Dinner Market
Food Service
Breakfast Takeout Market
Food Service
Electric Tiffin Market
Food Service
Workplace Service Market
Food Service
Hospital Food Services Market
Food Service
Global Cafe and Bars Market
Food Service
Europe Out of Home (OOH) Delivery Market
Food Service
Commercial Sink Market
Food Service
Commercial Tandoor Oven Market
Food Service
Commercial Beverage Dispenser Market
Food Service
North America Cafes & Bars Market
Food Service
Global Combi Ovens Market
Food Service
Charbroiler Market
Food Service
International Food Subscription Box Service Market
Food Service
Global Digital Food Delivery Market
Food Service
Food Service Pasta Market