
 Food Service Gloves Market | 2026-2036
Food Service Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Food Service Gloves Market Intelligence
Foodservice kitchen labor availability is bifurcating procurement strategies across the industry. Top Glove Corporation Bhd dominates nitrile output capacity for North American distributors. Hartalega Holdings Berhad differentiates through thin-gauge polymer formulations that reduce material waste per unit. Superior Glove specializes in reusable cut-resistant lines that compete against disposables in high-turnover prep environments.
Food service gloves are single-use or multi-use hand coverings manufactured from latex, nitrile, vinyl, polyethylene, or thermoplastic elastomer, typically 3-8 mil in thickness, designed to prevent direct contact between bare skin and ready-to-eat food surfaces. Nitrile segments lead value contribution due to latex-allergy substitution and superior puncture resistance against grease and sharp utensils. Biodegradable product types represent the fastest-expanding structural category as municipal composting infrastructure matures and operators face waste-diversion mandates. Reusable glove demand concentrates in food processing facilities where extended-wear protocols and industrial laundering reduce per-use cost below disposable equivalents.
The FDA Food Code and state-level health department interpretations govern bare-hand contact prohibitions across restaurant and catering operations, directly mandating glove use during food preparation. Occupational Safety and Health Administration standards on latex sensitization and FDA registration requirements for medical-grade crossover products shape material selection and supplier qualification protocols. Stakeholders must monitor evolving state composting standards and polymer-recycling pilot programs that could redefine cost structures for biodegradable versus conventional glove categories.
Market Dynamics
The FDA's Food Code updates on bare-hand contact restrictions are tightening compliance requirements nationwide, forcing quick-service restaurants to expand glove procurement for frontline kitchen staff and reshaping distributor inventory priorities across the foodservice supply chain.
Growth Catalysts
- Regulatory Mandates:FDA Food Code interpretations in Texas and Florida now require glove use during ready-to-eat food preparation, eliminating bare-hand exemptions that previously reduced procurement volumes.
- Material Substitution:Nitrile formulations are displacing latex across hospital-adjacent foodservice operations where OSHA latex-sensitization protocols restrict natural rubber use.
- Labor Geography:Foodservice labor growth in southern United States states outpaces other regions, concentrating demand expansion in distributor networks serving Texas and Florida metropolitan clusters.
Market Restraints
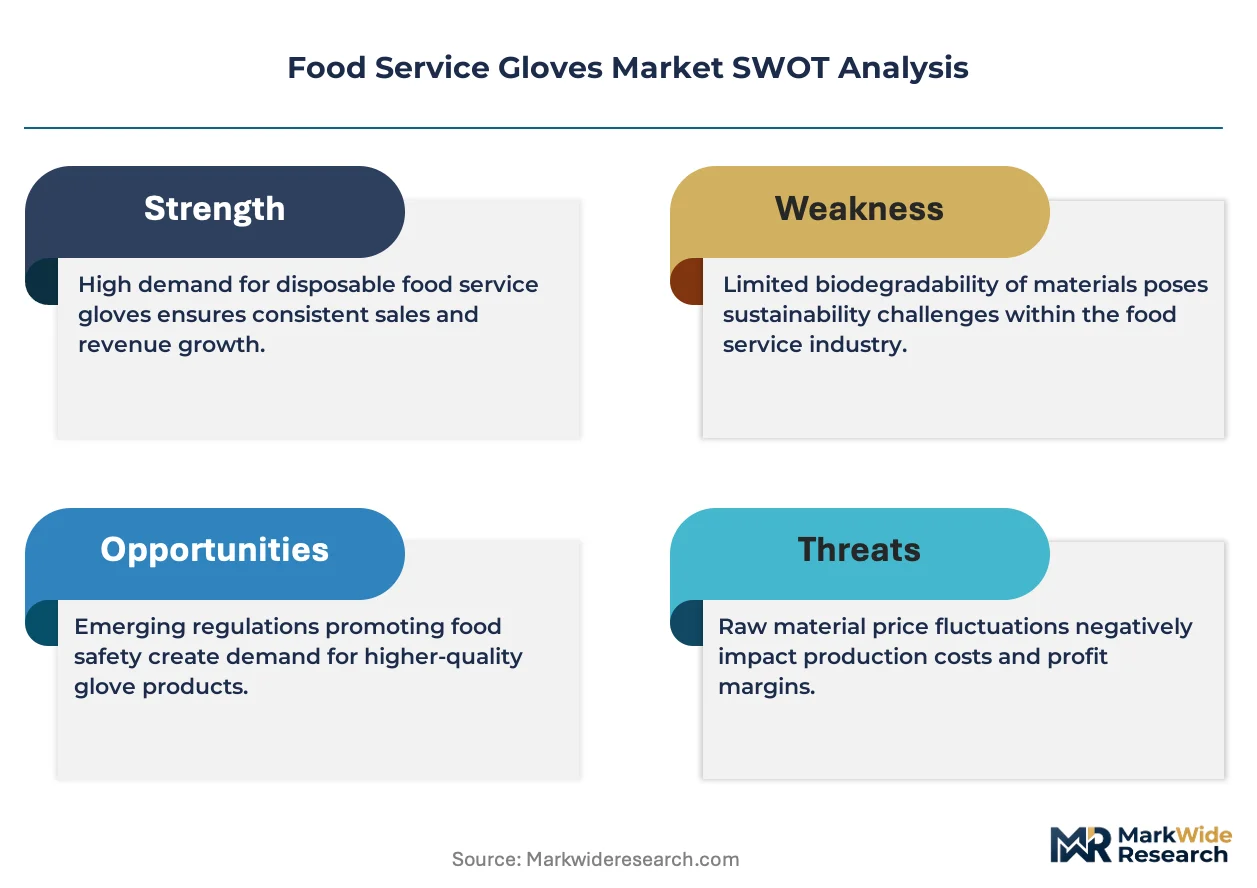
- Petrochemical Volatility:Acrylonitrile-butadiene feedstock prices fluctuate with crude oil benchmarks, compressing nitrile glove margins when energy markets spike.
- Supply Concentration:Malaysian nitrile production facilities dominate North American import volumes, creating geographic single-source risk during monsoon logistics disruptions.
- Competing Formats:Reusable cut-resistant glove lines from industrial laundering services compete against disposables in high-turnover prep environments where per-use cost calculations favor extended-wear protocols.
Strategic Opportunities
- Biodegradable Infrastructure:Municipal composting maturation in California and Washington creates regulatory tailwinds for thermoplastic elastomer gloves certified to ASTM D6400 standards.
- Crossover Medical-Grade:FDA registration for medical-grade glove production enables suppliers to pivot capacity between foodservice and healthcare during demand cycle mismatches.
- Direct-to-Operator Platforms:E-procurement portals are bypassing traditional broadline distributors, capturing margin from independent restaurants in Florida's Gulf Coast corridor.
Industry Challenges
- State Composting Standard Fragmentation:Divergent municipal certification requirements for biodegradable gloves force suppliers to maintain multiple product SKUs and testing regimens.
- Industrial Laundering Integration:Food processing facilities adopting reusable glove programs face reconfiguration friction with existing sanitation protocols and HACCP documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Service Gloves Market |
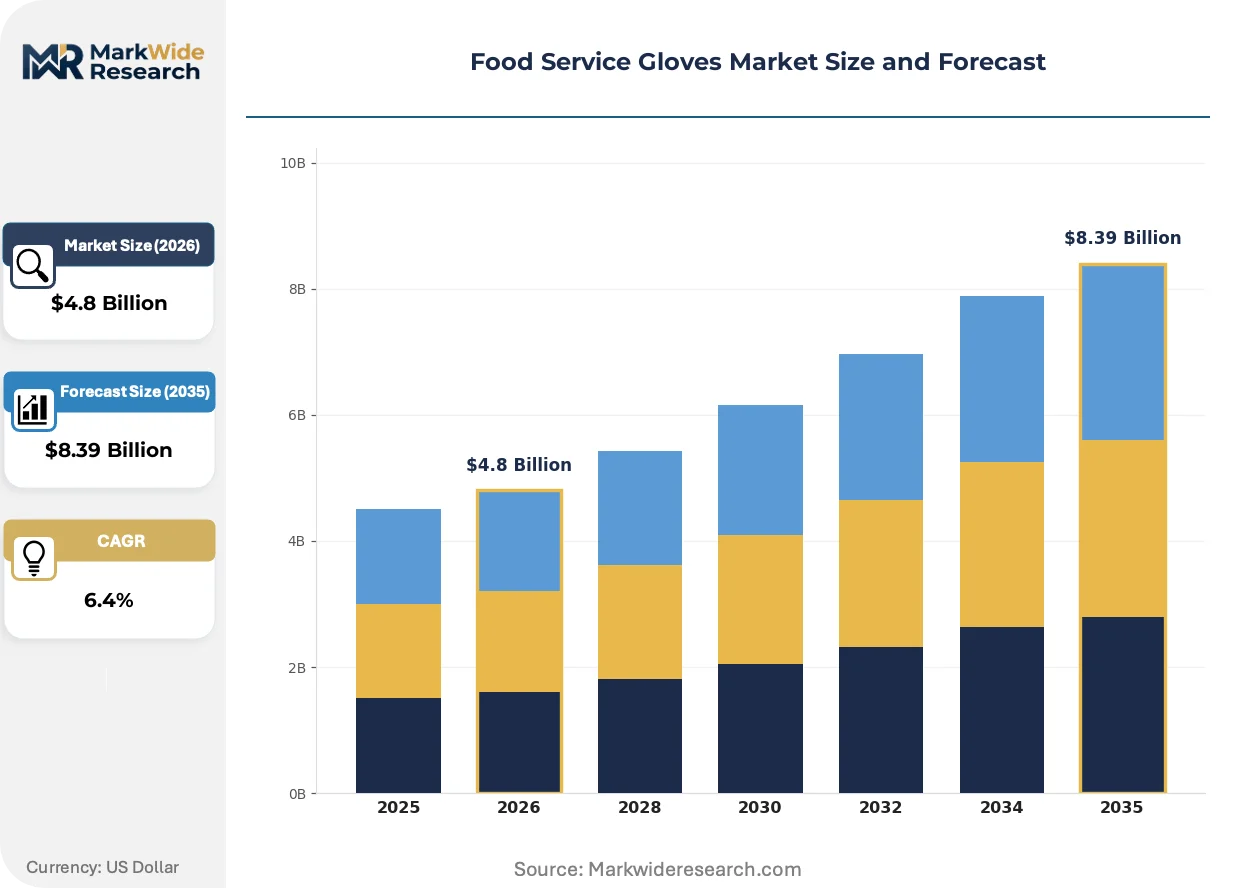
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Biodegradable, Nitrile Material: Latex, Vinyl, Polyethylene, TPE End User: Restaurants, Catering Services, Food Processing, Food Trucks Size: Small, Medium, Large, Extra Large |
| Companies Covered | Kossan Rubber Industries Bhd, Superior Glove, Top Glove Corporation Bhd, Rubberex Corporation (M) Berhad, Hartalega Holdings Berhad, Ansell Ltd., AMMEX, Sempermed, Supermax Corporation Berhad, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Service Gloves Market Strategic Shifts & Innovations
Thin-gauge polymer formulations are reducing material waste per unit while biodegradable alternatives reshape procurement criteria as waste-diversion mandates proliferate across municipal jurisdictions.
Advanced nitrile compounds with 3-mil thickness specifications are displacing standard 5-6 mil industrial gloves in quick-service restaurant prep lines. Chains with standardized kitchen protocols now specify these reduced-gauge products to cut per-unit polymer consumption without sacrificing puncture resistance against grease and sharp utensils. The structural consequence is compressing raw material demand per glove while maintaining equivalent barrier performance.
EPA and state-level environmental agencies are accelerating scrutiny of single-use plastic waste streams, with California's SB 54 implementation creating industrial consequence for conventional polyethylene glove disposal. Foodservice operators in the state now face procurement criteria that prioritize certified compostable alternatives, with distributors restructuring inventory mixes to maintain compliance eligibility for municipal and institutional contracts.
Buying committees at multi-unit restaurant chains are consolidating supplier relationships around integrated food-safety and hand-protection vendors. Independent operators historically served by fragmented local distributors now encounter bundled offerings from national broadliners that combine gloves with sanitation chemicals and disposable apparel. This pattern concentrates procurement decision-making in Texas and Florida corporate headquarters where volume leverage determines contract terms.
Food Service Gloves Market Segmentation
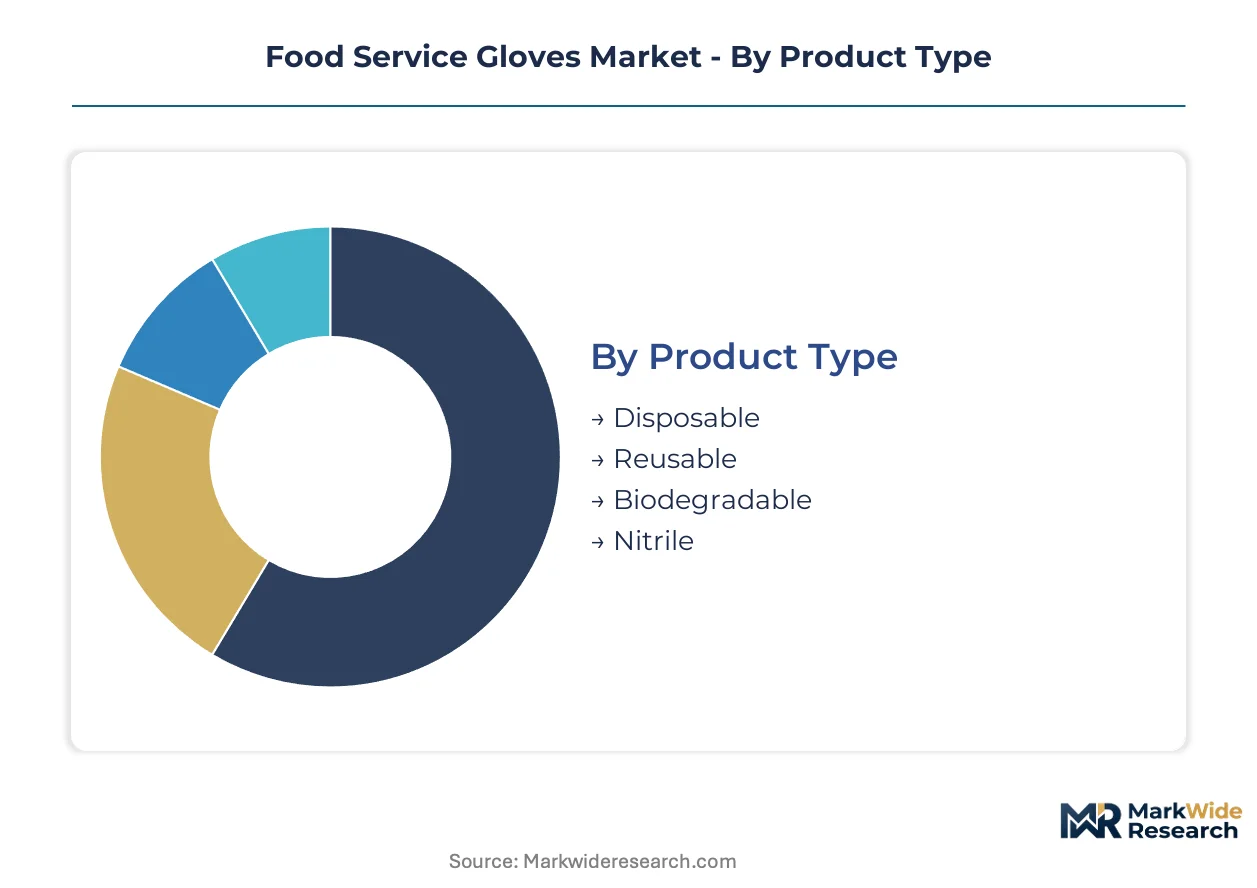
Segmentation in food service gloves determines procurement economics, regulatory compliance pathways, and supplier qualification criteria across distinct operational environments. Material chemistry and product format choices directly impact per-use cost calculations, waste disposal obligations, and worker safety protocols in commercial kitchens.
Product Type:
Disposable formats face intensifying substitution pressure from reusable industrial laundering programs in high-volume food processing facilities where extended-wear protocols reduce total cost of ownership below single-use equivalents.
- Nitrile:Synthetic rubber copolymers deliver superior puncture resistance against grease and sharp utensils while eliminating latex-allergy liability. Demand concentrates in hospital-adjacent foodservice operations across Texas and Florida where OSHA latex-sensitization protocols restrict natural rubber use.
- Biodegradable:Thermoplastic elastomer formulations certified to ASTM D6400 standards decompose in municipal composting facilities. California and Washington procurement criteria now prioritize these alternatives as SB 54 implementation creates industrial consequence for conventional polyethylene disposal.
- Disposable:Single-use polyethylene and vinyl gloves dominate quick-service restaurant prep lines where standardized kitchen protocols prioritize convenience over per-unit material optimization.
- Reusable:Cut-resistant lines with industrial laundering support compete in high-turnover prep environments where Superior Glove and similar specialists challenge disposable economics through extended-wear durability.
Disposable formats retain volume leadership; biodegradable alternatives hold the steepest expansion curve as municipal composting infrastructure matures.
Material:
Cost tier stratification separates premium nitrile formulations from economy polyethylene alternatives, with vinyl occupying a contracting middle position as allergy concerns and performance limitations erode procurement share.
- Latex:Natural rubber proteins deliver superior tactile sensitivity and elasticity for precision prep tasks. Hospital cafeterias and nursing home foodservice operations increasingly exclude this material under OSHA sensitization monitoring protocols.
- TPE:Thermoplastic elastomer compounds bridge performance and sustainability objectives with heat-sealable properties enabling thinner gauge production. Municipal composting certification in California creates procurement tailwinds unavailable to conventional petroleum-based alternatives.
- Vinyl:Polyvinyl chloride formulations offer lowest unit cost but exhibit reduced puncture resistance and plasticizer migration concerns under FDA food-contact scrutiny.
- Polyethylene:Cast and embossed film gloves serve minimal-barrier applications in deli counters and bakery displays where grease exposure remains limited and disposal frequency runs highest.
Nitrile commands the premium cost tier; TPE is climbing the fastest as sustainability mandates reshape procurement specifications.
End User:
Application environment dictates barrier performance requirements, with food processing facilities imposing extended-wear protocols that diverge sharply from quick-service restaurant convenience priorities.
- Restaurants:Frontline kitchen staff in quick-service chains drive standardized 3-mil nitrile procurement as FDA Food Code bare-hand contact restrictions eliminate previous exemption loopholes. Texas and Florida metropolitan clusters concentrate volume expansion.
- Food Processing:Industrial facilities with HACCP documentation systems adopt reusable cut-resistant programs through integrated laundering services, creating format competition against disposable suppliers.
- Catering Services:Mobile and temporary kitchen operations prioritize compact packaging and rapid donning features for event-based service cycles.
- Food Trucks:Space-constrained mobile operators favor pre-portioned dispenser boxes and color-coded sizing to minimize inventory footprint.
Restaurants retain volume leadership; food processing holds the steepest expansion curve as industrial laundering integration accelerates.
Size:
Volume distribution across size specifications reflects demographic labor composition and ergonomic litigation exposure in commercial kitchen employment.
- Medium:The most commonly specified dimension in standardized quick-service procurement contracts, matching average adult hand anthropometry in the US workforce.
- Large:Secondary volume concentration serving male-dominated kitchen labor pools in meat processing and institutional catering segments.
- Small:Concentrated demand in bakery and pastry operations with higher female labor participation and precision handling requirements.
- Extra Large:Niche specification for specialized equipment handling and cut-resistant liner accommodation in protein processing facilities.
Medium retains volume leadership; large holds the steepest expansion curve as foodservice labor demographics shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Food Code interpretations in the United States anchor regulatory momentum across the food service gloves sector, with bare-hand contact restrictions tightening procurement requirements nationwide. Demand concentrates in southern metropolitan clusters where foodservice labor expansion outpaces other regions.
United States
Texas and Florida metropolitan areas drive volume expansion as quick-service restaurant chains expand frontline kitchen staffing. FDA Food Code updates eliminate bare-hand contact exemptions during ready-to-eat food preparation. Dallas-Fort Worth and Miami-Dade distributor networks report accelerated nitrile procurement as compliance deadlines approach.
Malaysia
Malaysian production facilities dominate nitrile export capacity serving North American import channels. Monsoon logistics disruptions create seasonal supply vulnerability for acrylonitrile-butadiene glove output. Klang Valley manufacturing clusters maintain concentration of Top Glove Corporation Bhd and Hartalega Holdings Berhad production assets.
Canada
Hospital-adjacent foodservice operations in Ontario and Quebec accelerate latex substitution under Health Canada guidance on occupational sensitization. Provincial health authorities align procurement protocols with OSHA-equivalent latex restrictions. Toronto and Montreal metropolitan foodservice distributors prioritize nitrile inventory for institutional contract eligibility.
Germany
German industrial laundering services expand reusable glove programs competing against disposable formats in food processing facilities. ECHA chemical registration requirements shape thermoplastic elastomer formulation standards for EU market entry. Bavarian meat processing clusters adopt extended-wear protocols reducing per-use cost below single-use equivalents.
China
Domestic foodservice operators in Yangtze River Delta metropolitan areas standardize glove procurement as SAMR intensifies food-contact material scrutiny. GB standards for disposable plastics create compliance friction for conventional polyethylene glove suppliers. Shanghai and Hangzhou quick-service chains specify thinner-gauge nitrile to reduce polymer consumption per unit.
Food Service Gloves Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with Malaysian nitrile producers commanding upstream material supply and North American distributors controlling downstream channel access. Market structure reflects geographic concentration in Southeast Asian manufacturing paired with regional distribution fragmentation in target markets. Three archetypes dominate: scale-driven polymer compounders, thin-gauge formulation specialists, and reusable industrial laundering integrators. Competitive moves center on capacity expansion in biodegradable thermoplastic elastomer lines and backward integration into acrylonitrile-butadiene feedstock sourcing.
Within the Malaysian manufacturing tier, Top Glove Corporation Bhd and Hartalega Holdings Berhad exemplify scale-driven compounders with concentrated nitrile output capacity. Among North American specialists, Superior Glove occupies a position within the reusable cut-resistant segment challenging disposable economics in high-turnover prep environments. These three anchors illustrate the bifurcation between Southeast Asian supply concentration and regional service specialization.
| Leading Market Players |
|---|
| Kossan Rubber Industries Bhd |
| Superior Glove |
| Top Glove Corporation Bhd |
| Rubberex Corporation (M) Berhad |
| Hartalega Holdings Berhad |
| Ansell Ltd. |
| AMMEX |
| Sempermed |
| Supermax Corporation Berhad |
| Others |
Cost & Logistics Intelligence
FDA Food Code compliance certification gates supplier qualification while simultaneously stratifying price tiers across the food service gloves sector. Operators in Texas and Florida now face procurement criteria that separate premium nitrile formulations from economy polyethylene alternatives based on barrier performance validation and latex-allergy liability coverage.
Pricing Analysis
Geographic price spreads between Malaysian-manufactured nitrile and domestic vinyl alternatives compress distributor margins in southern US metropolitan clusters. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale leverage at multi-unit restaurant chains. Cost compression in the polyethylene tier is intensifying because California SB 54 waste-diversion mandates redirect procurement toward certified compostable alternatives. Quick-service restaurant chains exhibit highest price sensitivity through centralized buying committees, while hospital-adjacent foodservice operations prioritize barrier performance over unit cost.
Supply Chain Analysis
Port congestion at Klang Valley container terminals elevates inbound logistics costs for acrylonitrile-butadiene feedstock shipments reaching North American distributor networks. Malaysian production facilities draw from concentrated nitrile polymer supply anchored in Southeast Asian petrochemical complexes, with vinyl alternatives sourcing from Chinese PVC resin producers. Single-source vulnerability runs through monsoon-season logistics disruptions that delay glove container movements through the Strait of Malacca. Distribution runs through broadline foodservice distributors in Dallas-Fort Worth and Miami-Dade, with e-procurement portals capturing direct-to-operator volume along Florida's Gulf Coast corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through multi-unit restaurant chain consolidation, with standardized procurement protocols displacing fragmented independent operator purchasing across Texas and Florida metropolitan markets.
For Market Incumbents: Secure backward integration into acrylonitrile-butadiene feedstock sourcing to insulate margin compression from crude oil volatility. Expand biodegradable thermoplastic elastomer capacity in California-facing distribution nodes ahead of municipal composting infrastructure maturation. Channel control through exclusive broadline distributor relationships defends against e-procurement portal disintermediation threatening Florida's Gulf Coast corridor. For New Entrants and Emerging Players: Direct-to-operator platform under-service by incumbent broadliners creates entry pathways for specialized glove suppliers targeting independent restaurants with color-coded sizing and compact dispenser packaging. Food truck operators in space-constrained mobile kitchens represent the most penetrable segment, with rapid-donning features and minimal inventory footprint as the specific go-to-market angle. For Investors and Strategic Acquirers: FDA Food Code bare-hand contact restriction enforcement reshapes the acquisition landscape toward suppliers with medical-grade crossover registration enabling demand-cycle pivoting. Long-term viability centers on biodegradability certification and municipal composting partnership integration. Acquisition target archetype: thin-gauge formulation specialists with ASTM D6400-certified thermoplastic elastomer lines. The signal to watch is state-level composting standard harmonization reducing SKU fragmentation compliance burden.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Capacity Expansion | ASTM D6400 certification unlocks California and Washington municipal contract eligibility ahead of infrastructure maturation. |
| Medical-Grade Crossover Registration | FDA registration enables capacity pivoting between foodservice and healthcare during demand cycle mismatches. |
| Direct-to-Operator Platform Launch | E-procurement portals capture margin from independent restaurants in Florida's Gulf Coast corridor bypassing broadliners. |
| Backward Integration into Feedstock | Captive acrylonitrile-butadiene supply insulates nitrile margins from petrochemical price volatility spikes. |
| Industrial Laundering Partnership | Reusable cut-resistant programs challenge disposable economics in high-turnover food processing facilities with HACCP documentation. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with quick-service restaurant procurement directors, broadline distributor category managers, food processing facility HACCP coordinators, and industrial laundering service operators. Secondary validation drew from FDA Food Code regulatory filings, EPA waste-diversion mandate documentation, OSHA latex-sensitization guidance records, and customs import data tracking acrylonitrile-butadiene glove movements through US ports. Bottom-up volume estimates from end-user consumption patterns were triangulated against top-down capacity assessments from Malaysian manufacturing clusters.
Across the analysis window, the forecasting framework modeled demand trajectories through segmentation dimensions spanning material chemistry, product format, end-use environment, and geographic labor concentration. CAGRs were derived from regression analysis against foodservice employment growth indices and regulatory compliance deadline schedules. Industry-specific inputs included nitrile substitution rates in hospital-adjacent operations and municipal composting infrastructure deployment timelines in California and Washington.
Underlying assumptions cover sustained FDA Food Code enforcement momentum and Malaysian production continuity, with deviation risk concentrated in petrochemical feedstock price volatility and state-level composting standard fragmentation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Aquarium Protein Skimmers Market
Food Service
Latin America Online Grocery Market
Food Service
Food Service Utensils Market
Food Service
North America Online Grocery Delivery Market
Food Service
Saudi Arabia Cloud Kitchen Market
Food Service
Chained Consumer Foodservice Market
Food Service
United Arab Emirates Quick Service Restaurant Market
Food Service
Oman Food Service Market
Food Service
Commercial Air Fryer Market
Food Service
Commercial Bar Supplies Market
Food Service
Global Sushi Restaurants Market
Food Service
Countertop Pressure Fryer Market
Food Service
Malaysia Food Service Market
Food Service
Gourmet Street Food Market
Food Service
Commercial Rice Cooker Market
Food Service
Mobile Food Services Market