
 Saudi Arabia Foodservice Disposable Packaging Market | 2026-2036
Saudi Arabia Foodservice Disposable Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Foodservice Disposable Packaging Market Analytics
Modular container bundling is recalibrating buyer choice across Saudi foodservice procurement. Falcon Pack Industry LLC leverages its domestic manufacturing footprint to serve quick-service chains with standardized container-cup-lid combinations. Napco National Company anchors its position through integrated film and rigid packaging production serving catering operators. Hotpack Packaging Industries L.L.C differentiates via broad SKU depth across temperature-resistant formats for delivery-focused restaurants.
Saudi Arabia foodservice disposable packaging encompasses single-use containers, cups, trays, and cutlery engineered from plastic, paper, foam, or biodegradable substrates for prepared food containment and transport. Products typically specify heat tolerance thresholds, grease resistance ratings, and seal integrity parameters to maintain food safety during delivery and takeaway service. Containers dominate current volume flows due to entrenched use across rice-based meal formats and family-portion catering, while biodegradable materials represent the fastest-expanding segment as SFDA-aligned sustainability procurement criteria gain traction among chain operators. Cups capture concentrated margin pools through premium hot-beverage customization and branded print compatibility.
SFDA food-contact material standards and SASO technical regulations govern product safety, migration limits, and labeling requirements for all disposable packaging circulating in the Kingdom. The Saudi Green Initiative and circular economy policy signals are redirecting procurement specifications toward compostable substrates and recycled content thresholds. Stakeholders must monitor regulatory evolution around extended producer responsibility frameworks and substrate-specific bans to align capacity investments with compliance-bound demand trajectories.
Market Dynamics
Quick-service restaurant chains across Riyadh and Jeddah are accelerating off-premise dining formats, creating structural demand pull for temperature-engineered container solutions that maintain food integrity during extended delivery windows.
Growth Catalysts
- SFDA Food-Contact Material Standards:The Saudi Food and Drug Authority's tightening migration limits and labeling requirements are forcing domestic manufacturers to upgrade quality systems, creating compliance-driven replacement cycles across the installed base.
- Quick-Service Restaurant Expansion:Chains operating in Riyadh's foodservice cluster are standardizing container-cup-lid bundling specifications, generating volume commitments that amortize specialized tooling investments for qualified suppliers.
- Saudi Green Initiative Signals:Circular economy policy frameworks are redirecting procurement specifications toward compostable substrates, creating early-mover advantage windows for substrate converters with certified biodegradable production lines.
Market Restraints
- Petrochemical Feedstock Volatility:Polypropylene and polystyrene resin prices fluctuate with crude oil benchmarks, compressing margin predictability for rigid container manufacturers without backward integration into polymer supply.
- Central Region Supply Concentration:Manufacturing capacity clusters within Riyadh's industrial corridor, exposing buyers to single-point disruption risks from logistics bottlenecks or regional utility constraints.
- Biodegradable Performance Limitations:Current compostable formulations exhibit inferior grease resistance and heat tolerance versus conventional plastics, restricting deployment in rice-based meal formats with high oil content.
Strategic Opportunities
- Western Region Penetration:Jeddah's hospitality and pilgrimage foodservice infrastructure remains underdeveloped versus Riyadh, offering first-mover positioning for container suppliers with localized distribution partnerships.
- Extended Producer Responsibility Pre-Positioning:Anticipated SASO frameworks for packaging waste accountability will reward domestic manufacturers with integrated collection and recycling infrastructure.
- Smart Packaging Convergence:Integration of QR-coded traceability layers with temperature-sensitive substrates enables premium positioning for delivery-focused operators seeking real-time cold chain verification.
Industry Challenges
- SFDA Certification Timeline Compression:New product approvals require extended migration testing protocols, delaying commercialization schedules for innovative substrate formulations by 12-18 months versus conventional materials.
- Skilled Technical Workforce Scarcity:Polymer engineering and food-contact compliance expertise concentrates with established manufacturers, constraining capacity expansion for mid-scale entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Foodservice Disposable Packaging Market |
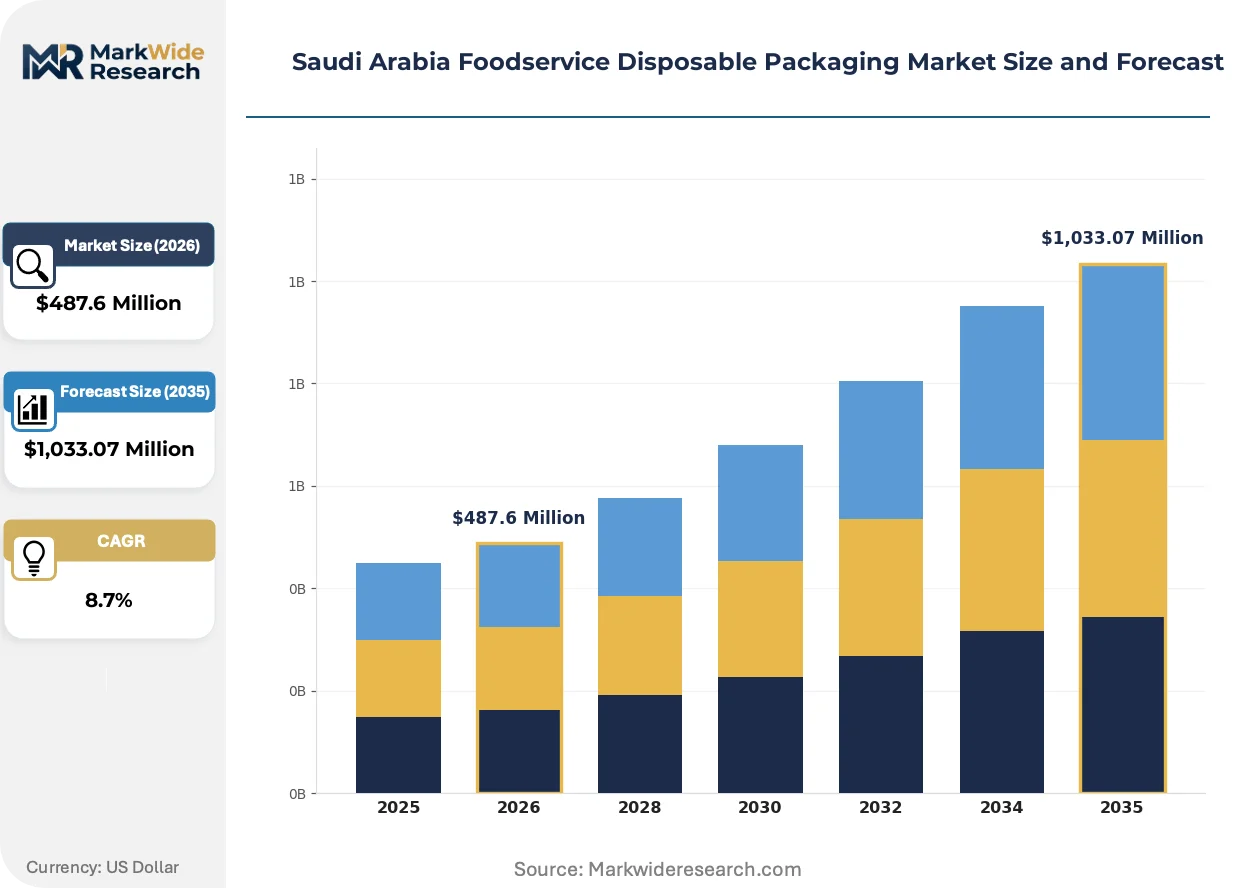
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Containers, Cutlery, Cups, Trays Material: Plastic, Paper, Biodegradable, Foam End User: Restaurants, Cafés, Catering Services, Fast Food Chains Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Falcon Pack Industry LLC, International Food Services LLC, Napco National Company, Emirates National Factory for Plastic Industries LLC, Prestige Packing Industry LLC, Hotpack Packaging Industries L.L.C, Arabian Plastic Industrial Co. Ltd., Detpak Middle East FZE, SAQR Pack Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Foodservice Disposable Packaging Market Evolving Landscape
Material science advances and regulatory pressure are converging to redefine performance specifications across Saudi foodservice packaging, with substrate selection becoming the primary battleground for supplier differentiation.
Multi-layer barrier films incorporating ethylene vinyl alcohol copolymers are consolidating technical leadership in hot-food container applications. Quick-service chains operating delivery-heavy formats are specifying these structures for rice-based meals requiring 45-minute heat retention. The technology is consolidating procurement decisions around film converters with co-extrusion capabilities, marginalizing single-layer suppliers.
SASO technical regulations governing recycled content thresholds are tightening compliance pathways for imported packaging materials. Domestic manufacturers with integrated recycling streams gain preferential positioning in institutional procurement tenders. Rigid container segments face the steepest adaptation requirements, with technical documentation demands increasing qualification burdens for offshore suppliers.
Chain operators are consolidating vendor relationships around full-bundle suppliers capable of container-cup-lid coordination. Independent restaurants in Jeddah's foodservice corridor are migrating from spot purchasing to annual framework agreements with standardized specifications. This concentration is most visible in the Central Region, where procurement departments at major quick-service chains have reduced qualified supplier pools by half over the past qualification cycle.
Saudi Arabia Foodservice Disposable Packaging Market Segmentation
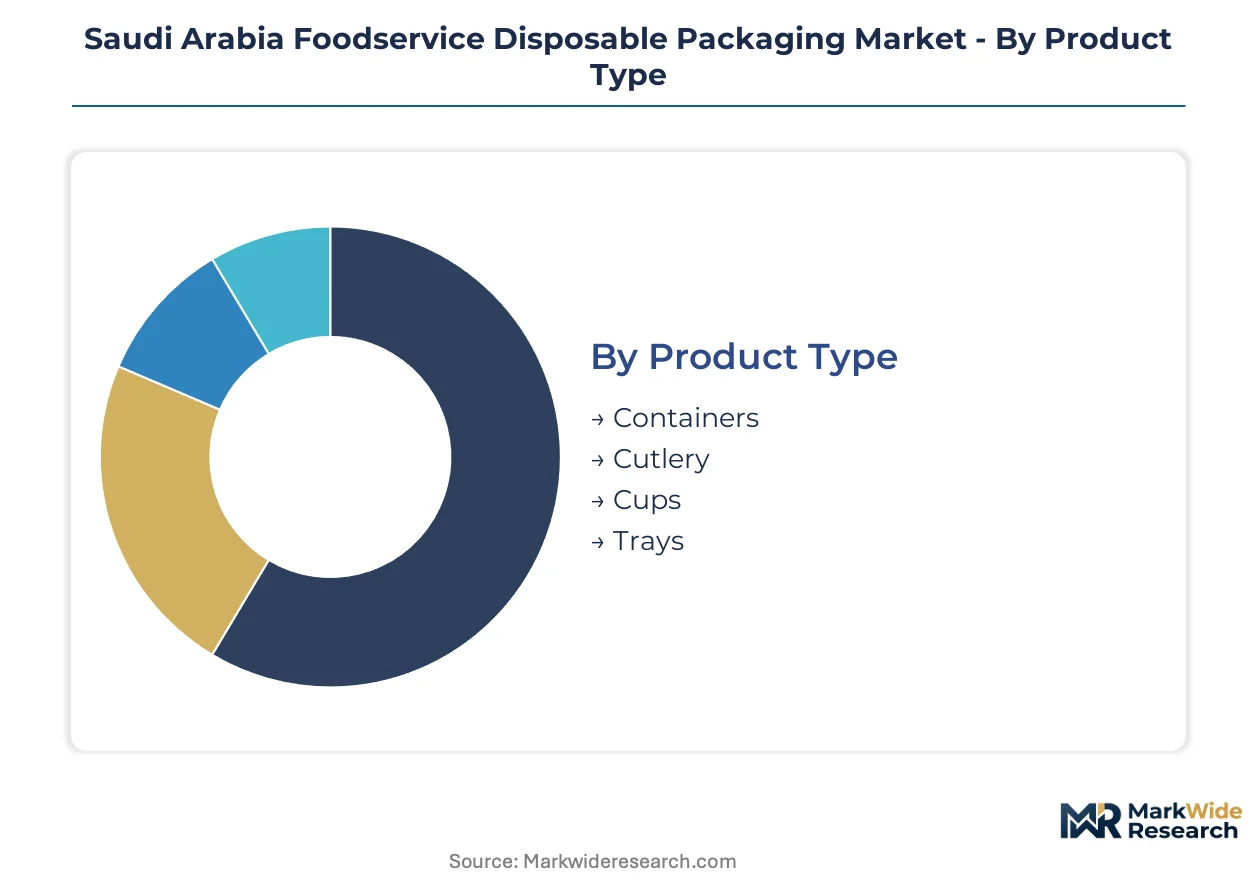
Segmentation in Saudi foodservice packaging reveals how procurement specifications diverge across buyer types, with Riyadh-based quick-service chains driving standardization while Jeddah hospitality operators prioritize customization. Material selection increasingly separates compliance-forward institutional buyers from cost-sensitive independents.
Product Type:
Buyers differentiate by meal format complexity and temperature retention requirements, with rice-based cuisine dictating container specifications and beverage programs driving cup customization.
- Containers:Multi-compartment polypropylene and bagasse structures dominate procurement for mandi and kabsa meals requiring 45-minute heat retention. Riyadh's quick-service chains specify leak-resistant latching systems for delivery-heavy operations, with Falcon Pack Industry LLC capturing volume through standardized bundling agreements.
- Cups:Double-wall paperboard with polyethylene barriers commands premium positioning across Saudi coffeehouse chains expanding iced beverage programs. Jeddah's café corridor drives demand for branded print compatibility and sip-through lid integration.
- Trays:Expanded polystyrene and molded fiber formats serve cafeteria-style service in pilgrimage catering infrastructure.
- Cutlery:Polypropylene spork and utensil kits accompany bundled container solutions for fast-food delivery formats.
Volume sits with Containers; growth tilts toward Cups.
Material:
Cost tiers separate buyers by regulatory exposure and brand positioning, with SFDA-aligned sustainability procurement creating premium substrate demand.
- Plastic:Polypropylene and polystyrene formulations retain technical leadership in grease resistance and heat tolerance for high-oil rice meals. Central Region manufacturing clusters supply rigid containers under SASO quality compliance, though petrochemical feedstock volatility compresses margin predictability for non-integrated converters.
- Biodegradable:Bagasse and PLA substrates are climbing the fastest as Saudi Green Initiative signals redirect chain procurement. Current formulations face performance limitations in extended delivery windows, restricting deployment to short-haul catering applications.
- Paper:PE-coated paperboard serves hot-beverage cups and limited food-contact applications with established recycling infrastructure.
- Foam:Expanded polystyrene retains position in institutional cost-sensitive procurement despite environmental pressure.
Plastic captures current volume; biodegradable substrates are expanding most quickly.
End User:
Scale and procurement sophistication separate buyer tiers, with national chains imposing bundling specifications versus fragmented independent operators.
- Fast Food Chains:Standardized container-cup-lid specifications dominate procurement across Riyadh's foodservice cluster, with annual framework agreements reducing qualified supplier pools. Temperature-engineered solutions for 30-minute delivery windows drive technical requirements.
- Catering Services:Pilgrimage and event hospitality in Makkah Province generates concentrated demand for large-format trays and bulk-portion containers with stackability specifications.
- Restaurants:Full-service operators in Jeddah's dining corridor prioritize presentation-grade packaging for premium takeaway positioning.
- Cafés:Beverage-focused establishments drive cup and lid customization with branded print requirements.
Fast Food Chains anchor procurement volume; Catering Services show steepest expansion trajectory from pilgrimage infrastructure investment.
Distribution Channel:
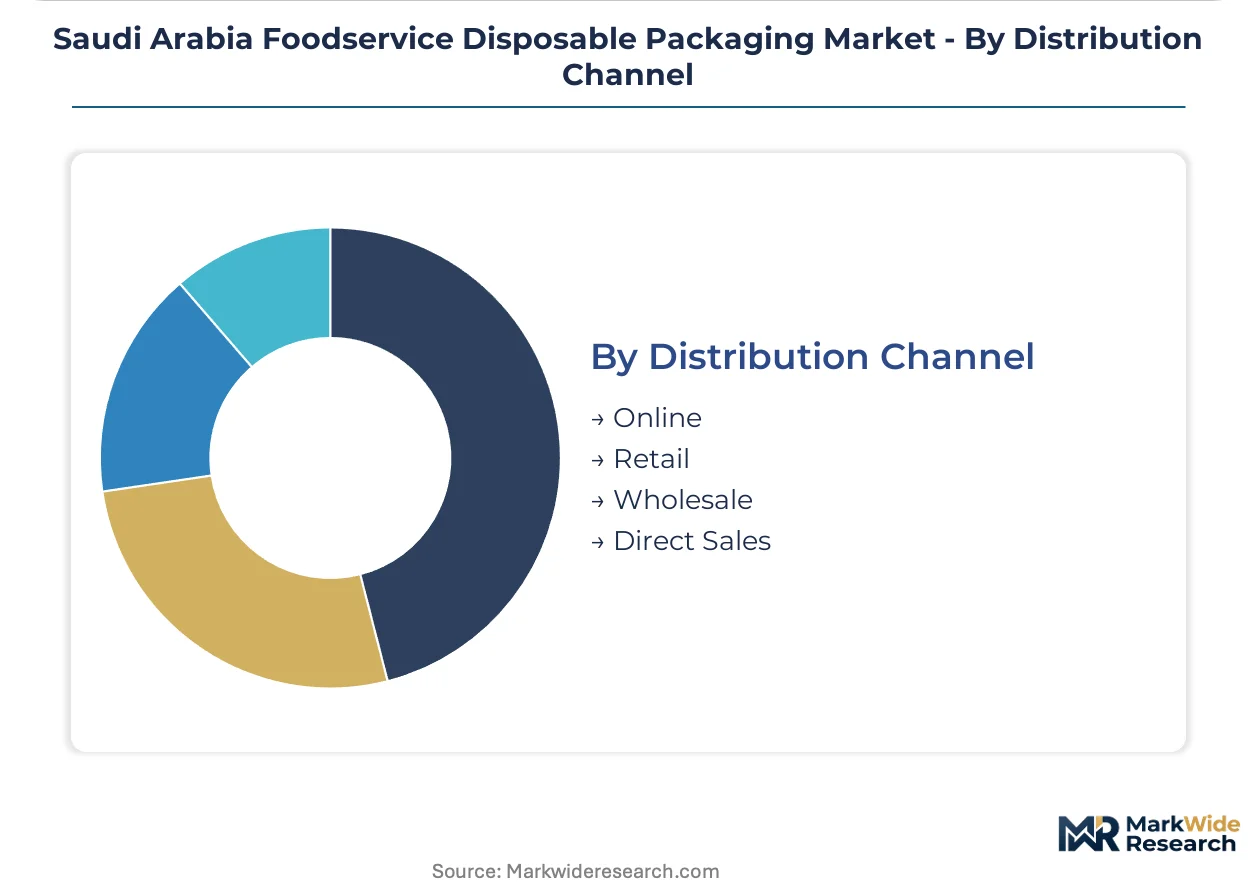
Geographic coverage and technical service capabilities separate channel performance, with centralized procurement favoring direct relationships.
- Direct Sales:National quick-service chains in the Central Region consolidate vendor relationships through dedicated account management and co-development programs for proprietary container designs.
- Wholesale:Riyadh-based distributors serve mid-scale restaurant clusters with inventory pooling and rapid replenishment for standardized SKUs.
- Online:E-procurement platforms gain traction among independent Jeddah operators seeking spot purchasing flexibility and transparent pricing.
- Retail:Cash-and-carry outlets serve small-format cafés and food trucks with immediate availability for emergency replenishment.
Direct Sales commands volume concentration; Online channels are gaining share fastest from procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modon Industrial City incentives and King Abdullah Economic City development zones are concentrating food-grade polymer conversion capacity within Saudi Arabia's Central and Western corridors. Domestic manufacturers cluster near Riyadh's logistics hub and Jeddah's Red Sea port infrastructure to serve quick-service restaurant procurement networks.
Riyadh
Central Region quick-service chains are standardizing container-cup-lid bundling specifications across their off-premise dining formats. SFDA food-contact material regulations require upgraded migration testing protocols for all domestic suppliers serving this cluster. Al-Kharj Road industrial corridor hosts Falcon Pack Industry LLC and Napco National Company production facilities supplying standardized polypropylene containers.
Jeddah
Western Region hospitality and pilgrimage foodservice infrastructure generates concentrated demand for large-format catering trays and temperature-resistant delivery containers. SASO quality standards govern recycled content thresholds for packaging materials circulating through King Abdulaziz Port import channels. King Abdullah Economic City manufacturing zones attract biodegradable substrate converters seeking proximity to Makkah Province event catering operators.
Eastern Province
Dammam industrial corridor leverages Jubail petrochemical feedstock integration for rigid container production serving Eastern Region quick-service expansion. Saudi Aramco downstream polymer supply chains support local polypropylene and polystyrene formulation capabilities. Dammam Second Industrial City hosts Hotpack Packaging Industries L.L.C distribution infrastructure for regional restaurant procurement networks.
NEOM Northwest
Saudi Green Initiative circular economy mandates are redirecting procurement specifications toward compostable packaging substrates within this planned development zone. Zero-carbon construction timelines accelerate demand for biodegradable foodservice disposables aligned with sustainability procurement criteria. Oxagon industrial zone planning documents specify extended producer responsibility frameworks for packaging waste accountability.
Saudi Arabia Foodservice Disposable Packaging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Saudi Arabia's foodservice disposable packaging sector. Market structure tilts toward consolidated supply relationships where national quick-service chains reduce qualified vendor pools through annual framework agreements. Three archetypes dominate: integrated polymer-to-packaging manufacturers with captive resin supply, specialized substrate converters with certified biodegradable production lines, and regional distributors with rapid replenishment capabilities. Competitive moves center on capacity expansion within Modon-sanctioned industrial zones and strategic partnerships with quick-service procurement departments for proprietary container co-development.
Among domestic manufacturers with Riyadh-based production footprints, Falcon Pack Industry LLC, Napco National Company, and Hotpack Packaging Industries L.L.C exemplify the integrated-to-specialized spectrum. Falcon Pack Industry LLC occupies a position representing standardized bundling agreements with quick-service chains. Napco National Company anchors the integrated film-and-rigid packaging archetype through multi-substrate production capabilities. Hotpack Packaging Industries L.L.C sits within the broad-SKU-depth tier serving delivery-focused restaurant operators with temperature-resistant format diversification.
| Leading Market Players |
|---|
| Falcon Pack Industry LLC |
| International Food Services LLC |
| Napco National Company |
| Emirates National Factory for Plastic Industries LLC |
| Prestige Packing Industry LLC |
| Hotpack Packaging Industries L.L.C |
| Arabian Plastic Industrial Co. Ltd. |
| Detpak Middle East FZE |
| SAQR Pack Company |
| Others |
Value Network & Pricing Analysis
Captive resin supply through Saudi Aramco's downstream polymer networks anchors both supply security and pricing power for domestic container manufacturers. This backward integration into petrochemical feedstock insulates qualified suppliers from the margin volatility that compresses non-integrated converters when crude benchmarks fluctuate.
Pricing Analysis
Short lead-time premiums structure procurement contracts across Riyadh's quick-service cluster, with annual framework agreements commanding discounts versus spot purchasing by independent Jeddah operators. Three-tier pricing structure across premium, standard, and economy levels separates SFDA-certified biodegradable substrates from conventional polypropylene and residual foam formats. Cost compression in economy-tier polystyrene is intensifying because of import competition from Gulf Cooperation Council suppliers. Fast-food chains with standardized bundling specifications show least price sensitivity; small-format cafés in retail channels exhibit highest.
Supply Chain Analysis
Returns and recycling flows remain nascent but anticipate SASO extended producer responsibility frameworks that will mandate post-consumer collection infrastructure. Manufacturing capacity clusters in Saudi Arabia, United Arab Emirates, and Turkey supply rigid containers and film formats to Kingdom buyers. Raw material draws from Jubail petrochemical complexes, imported EVOH barrier resins, and certified bagasse pulp shipments. Single-source vulnerability concentrates in specialized co-extrusion equipment for multi-layer films. Distribution runs through Modon-sanctioned industrial zones with direct sales to national chains and wholesale distributors serving mid-scale operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biodegradable substrate conversion is displacing conventional plastic formulations across procurement specifications, with bagasse and PLA production lines replacing legacy polystyrene capacity as Saudi Green Initiative compliance deadlines approach.
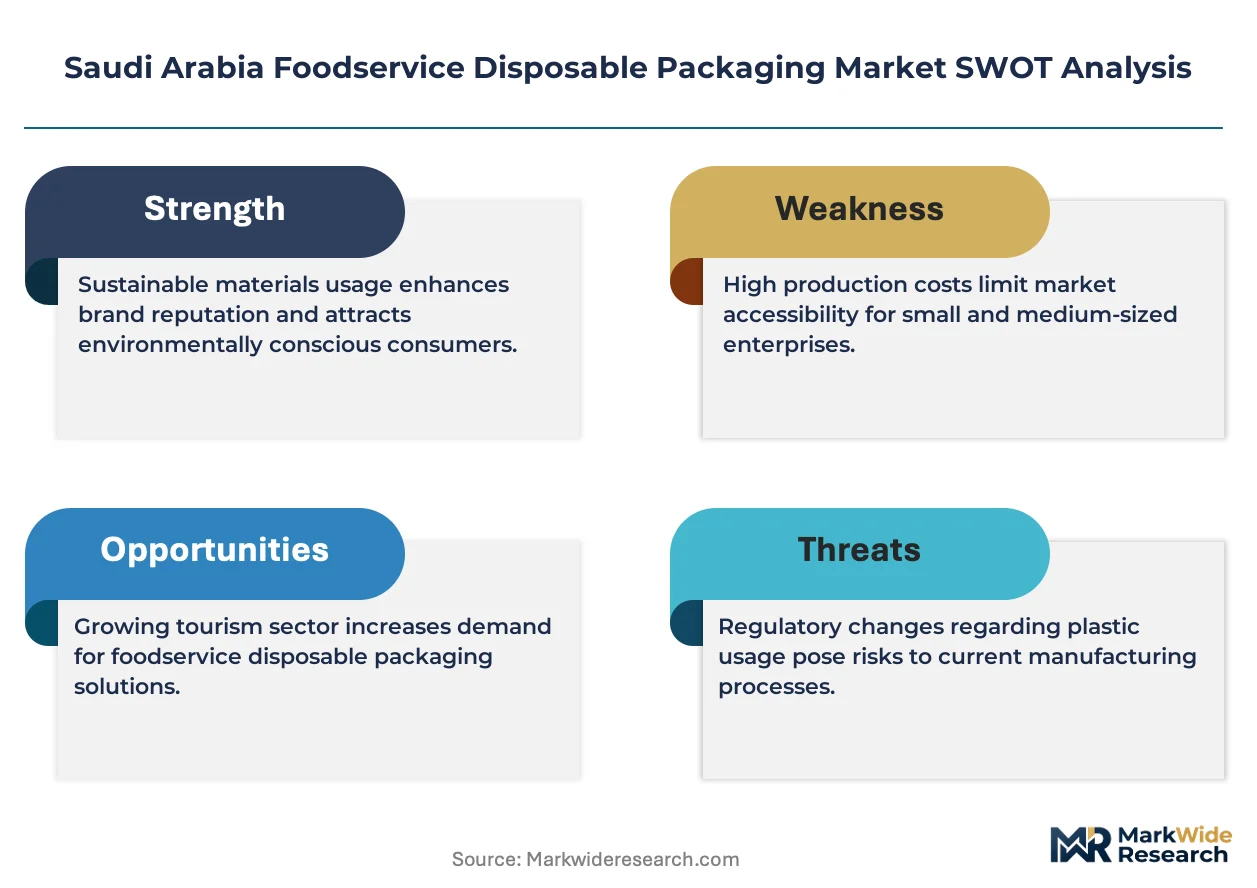
For Market Incumbents: Cement dominance in Riyadh's foodservice corridor by upgrading migration testing laboratories to compress SFDA certification timelines for innovative substrates. Add captive recycling collection infrastructure to pre-position for extended producer responsibility mandates. Bagasse performance limitations in high-oil rice meals represent the critical substitution threat requiring R&D investment. For New Entrants and Emerging Players: Enter via Jeddah's underdeveloped hospitality packaging infrastructure, where pilgrimage catering and café corridor expansion outpaces qualified local supply. Target biodegradable substrate production with SASO certification to capture premium positioning in Makkah Province event catering. Partner with King Abdullah Economic City development zones for zero-carbon alignment and preferential zoning access. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated polymer conglomerates seeking food-contact compliance capabilities and quick-service chain relationships. Five-to-ten-year viability favors substrate converters with certified biodegradable production lines and co-extrusion technical depth. Monitor SFDA substrate-specific ban announcements as inflection indicator for capacity stranding risk in conventional plastic assets.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Production Line Certification | SASO-aligned compostable capacity captures premium procurement from Saudi Green Initiative-compliant chains. |
| Co-Extrusion Capability Investment | Multi-layer EVOH barrier film production qualifies suppliers for 45-minute heat retention specifications in rice meal delivery. |
| Extended Producer Responsibility Pre-Positioning | Integrated collection infrastructure secures preferential positioning in anticipated packaging waste accountability frameworks. |
| Western Region Distribution Partnership | Jeddah and Makkah Province localization reduces logistics exposure from Central Region supply concentration. |
| Smart Packaging Technology Integration | QR-coded traceability layers enable premium positioning for delivery operators requiring cold chain verification. |
Research Methodology
SFDA regulatory filings, SASO technical documentation, and Saudi Customs trade statistics formed the secondary backbone for substrate flow and compliance pathway mapping. Primary interviews with quick-service procurement directors, polymer plant managers, and food-contact compliance consultants validated conversion capacity and certification timelines. Bottom-up modeling of container, cup, and tray shipments triangulated against top-down foodservice operator expansion data across Riyadh, Jeddah, and Dammam clusters.
Historical trendline analysis of foodservice disposable packaging consumption established baseline penetration rates across quick-service, catering, restaurant, and café segments. The analytical framework modeled product type, material substrate, end-user category, and distribution channel dimensions across the projection horizon. CAGRs derived from segment-specific growth drivers including off-premise dining format expansion, regulatory compliance replacement cycles, and sustainability procurement redirection. Forecast inputs incorporated pilgrimage infrastructure investment pipelines and NEOM development zone packaging specifications.
Revisions become necessary when SFDA substrate-specific bans accelerate, petrochemical feedstock volatility exceeds historical bands, or biodegradable formulation performance crosses threshold parity with conventional plastics. Forecasts reflect documented assumptions regarding regulatory timeline adherence and chain operator procurement consolidation trajectories. Practitioners should monitor SASO extended producer responsibility framework announcements and SFDA migration limit amendments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Ice Maker Market
Food Service Equipment
Refrigerated Counter Market
Food Service Equipment
North America Countertop Ice Makers Market
Food Service Equipment
Smart Food Scale Market
Food Service Equipment
Freestanding Large Cooking Appliance Market
Food Service Equipment
Food Thermos Market
Food Service Equipment
Global QSR Food Service Equipment Market
Food Service Equipment
Commercial Cookers Market
Food Service Equipment
Global Roti Maker Market
Food Service Equipment
Commercial Refrigerated Display Cabinet Market
Food Service Equipment
Asia-Pacific Commercial Dishwashers Market
Food Service Equipment
Draught Beer Chiller Market
Food Service Equipment
Global Refrigerated Display Cases and Chilled Rooms Market
Food Service Equipment
Food Trays and Bowls Market
Food Service Equipment
Commercial Microwaves Market
Food Service Equipment
Commercial Ice Equipment and Supplies Market