
 Plant Derived Proteins Market | 2026-2036
Plant Derived Proteins Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Derived Proteins Market Outlook
The EU Green Deal is repositioning procurement priorities across European food manufacturing, compelling ingredient suppliers to demonstrate carbon footprint reductions and deforestation-free sourcing. ADM leverages its North American crushing network to secure non-GMO soybean streams for European clients. Cargill competes through integrated supply chains spanning Brazilian origination to Dutch processing. Roquette Frères anchors its position via pea protein extraction capacity at its Vic-sur-Aisne facility, supplying isolates to plant-based meat formulators.
Plant derived proteins comprise proteinaceous fractions extracted from legumes, oilseeds, and grains through aqueous separation, enzymatic hydrolysis, or dry fractionation, typically achieving protein contents of 50-90% depending on processing intensity; these ingredients function as nutritional fortifiers, texturizing agents, and emulsion stabilizers across formulated foods. Pea protein isolates command premium positioning in meat alternative applications where gelation and water-binding properties determine finished product quality. Soy protein concentrates retain dominant volume across animal feed formulations, particularly in poultry and aquaculture diets where cost-per-unit-protein drives purchasing decisions. Rice protein occupies a specialized niche in allergen-free nutritional products, with limited suppliers constraining expansion.
EFSA novel food authorizations determine market access timelines for emerging protein sources such as hemp and single-cell ingredients, while REACH compliance governs chemical safety in processing aids and extraction solvents. The USDA Organic seal and Non-GMO Project verification create parallel premium channels in the United States, with certification costs filtering supplier participation. Stakeholders must monitor evolving protein quality scoring methodologies, as FAO digestibility-corrected amino acid scores replace crude protein metrics in nutrition labeling regimes.
Market Dynamics
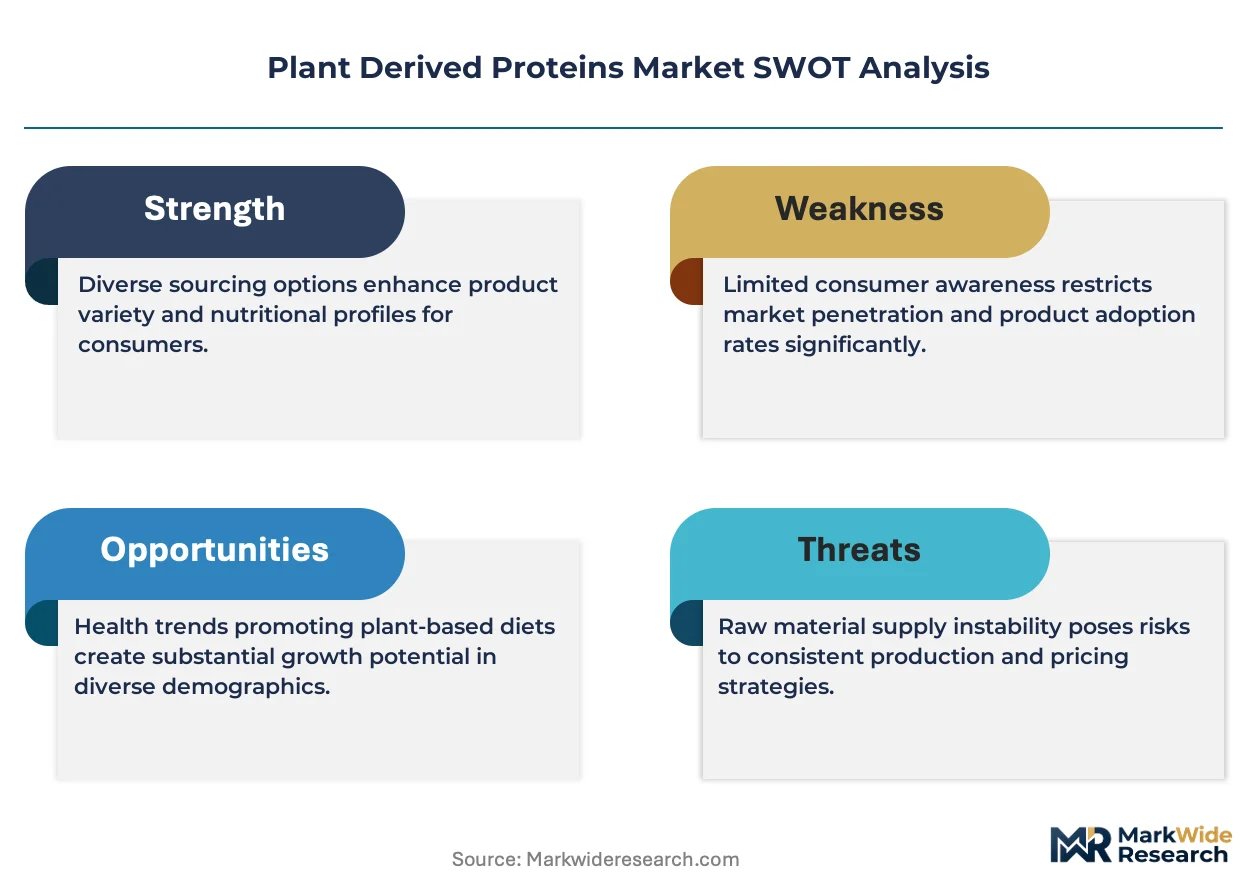
Ingredient processors face mounting pressure to demonstrate deforestation-free sourcing credentials under the EU Green Deal's Farm to Fork Strategy, forcing rapid supply chain reconfiguration and extrusion capacity expansion.
Growth Catalysts
- EU Green Deal procurement mandates:Food manufacturers across Germany, France, and the Netherlands must reformulate products to meet carbon footprint reduction targets, accelerating demand for pea and soy isolates.
- Meat analog production scaling:Extrusion technology advances enable texture replication that satisfies sensory requirements in plant-based burger and sausage applications.
- Poultry and aquaculture feed substitution:Soy protein concentrates displace fishmeal in salmon and shrimp diets as cost-per-unit-protein economics favor oilseed derivatives.
Market Restraints
- Pea protein isolate cost premiums:Aqueous extraction and enzymatic hydrolysis require energy-intensive processing that elevates unit costs above soy alternatives.
- Rice protein supply concentration:Limited extraction capacity in Asia-Pacific constrains expansion of allergen-free nutritional product lines.
- EFSA novel food authorization timelines:Hemp and single-cell protein sources face multi-year safety assessment delays before European market entry.
Strategic Opportunities
- Textured protein extrusion services:Dedicated capacity investments in Germany's Ruhr region position toll processors to capture meat industry outsourcing demand.
- Organic and Non-GMO Project certification channels:USDA Organic seal requirements create premium pricing tiers that filter out commodity competitors.
- Enzymatic hydrolysis-dry fractionation convergence:Combined processing routes yield functional isolates with enhanced gelation properties for bakery applications.
Industry Challenges
- Protein quality scoring methodology transitions:FAO digestibility-corrected amino acid score implementation demands reformulation expertise and analytical capability upgrades.
- REACH compliance for extraction solvents:Chemical safety documentation for hexane and ethanol recovery systems extends facility commissioning timelines.
- Extrusion operator skill scarcity:Textured protein production requires specialized knowledge of screw configuration and moisture control that outpaces vocational training output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Derived Proteins Market |
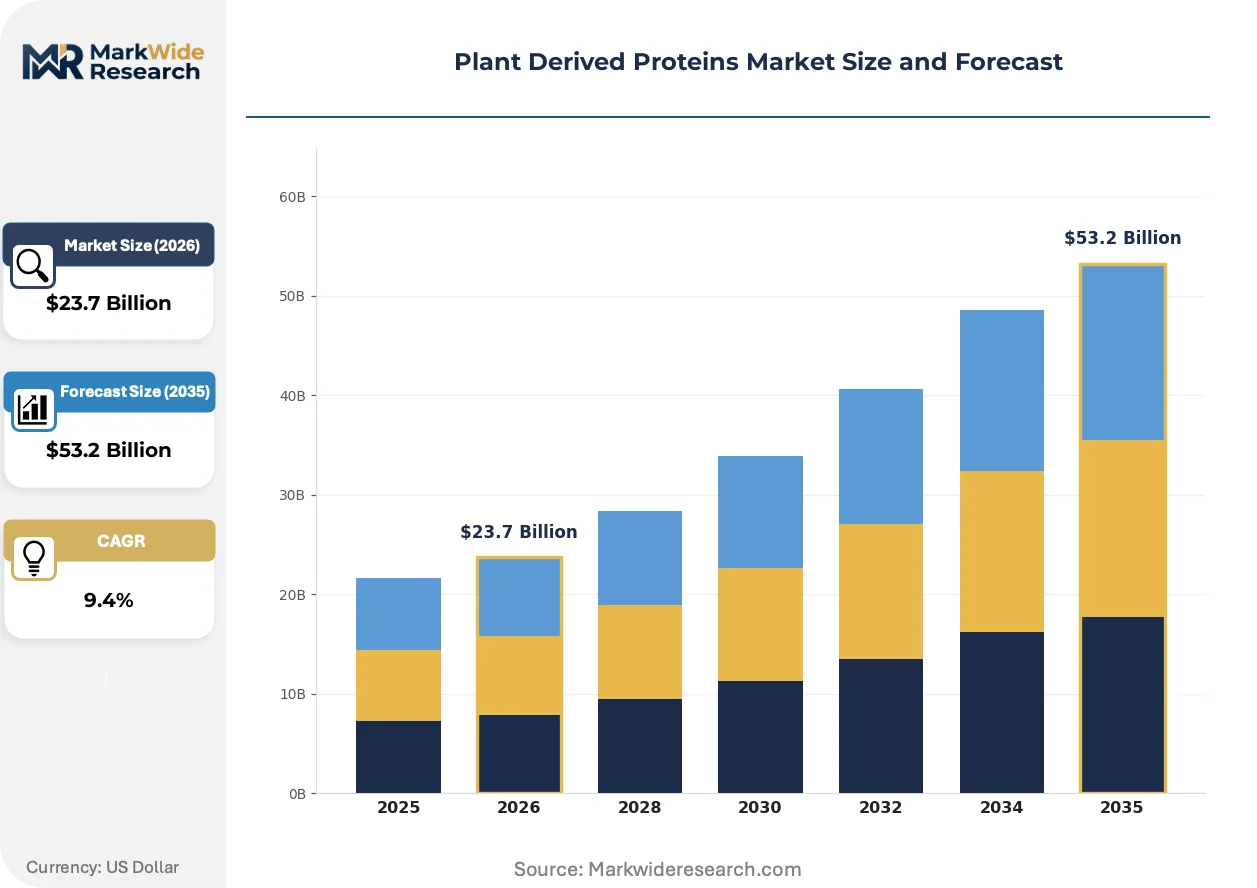
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $53.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pea Protein, Soy Protein, Rice Protein, Hemp Protein Application: Food & Beverage, Nutraceuticals, Animal Feed, Personal Care Form: Powder, Isolate, Concentrate, Textured End User: Restaurants, Food Manufacturers, Fitness Centers, Retail Consumers |
| Companies Covered | ADM, Cargill, Roquette Frères, Kerry Group, Ingredion, Glanbia, International Flavors & Fragrances, Wilmar International, Bunge Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Derived Proteins Market Strategic Shifts
Processing technology convergence and regulatory disclosure requirements are compressing competitive differentiation from raw material sourcing toward functional performance and carbon accounting transparency.
Dry fractionation combined with air classification is consolidating protein concentration economics for yellow pea and fava bean processors. Mid-scale ingredient suppliers in the American Midwest and Canadian prairies adopt these systems to bypass wet extraction capital intensity. The technology is consolidating regional supply bases around crushing-adjacent facilities rather than standalone isolate plants.
EFSA novel food authorizations for hemp seed protein and algae-derived ingredients are tightening documentation requirements for allergenicity and heavy metal content. European formulators now delay product launches pending positive safety opinions, compressing innovation cycle times. Pet food and sports nutrition categories absorb the longest approval delays due to consumption by vulnerable populations.
Carbon footprint labeling is redirecting procurement decisions toward geographically proximate crushing operations. German meat alternative manufacturers now specify rail-delivered Ukrainian or Baltic-region peas over transoceanic alternatives. Retail chains in Scandinavia and the Netherlands demand scope-three emissions disclosures that favor European-sourced isolates despite modest price premiums.
Plant Derived Proteins Market Segmentation
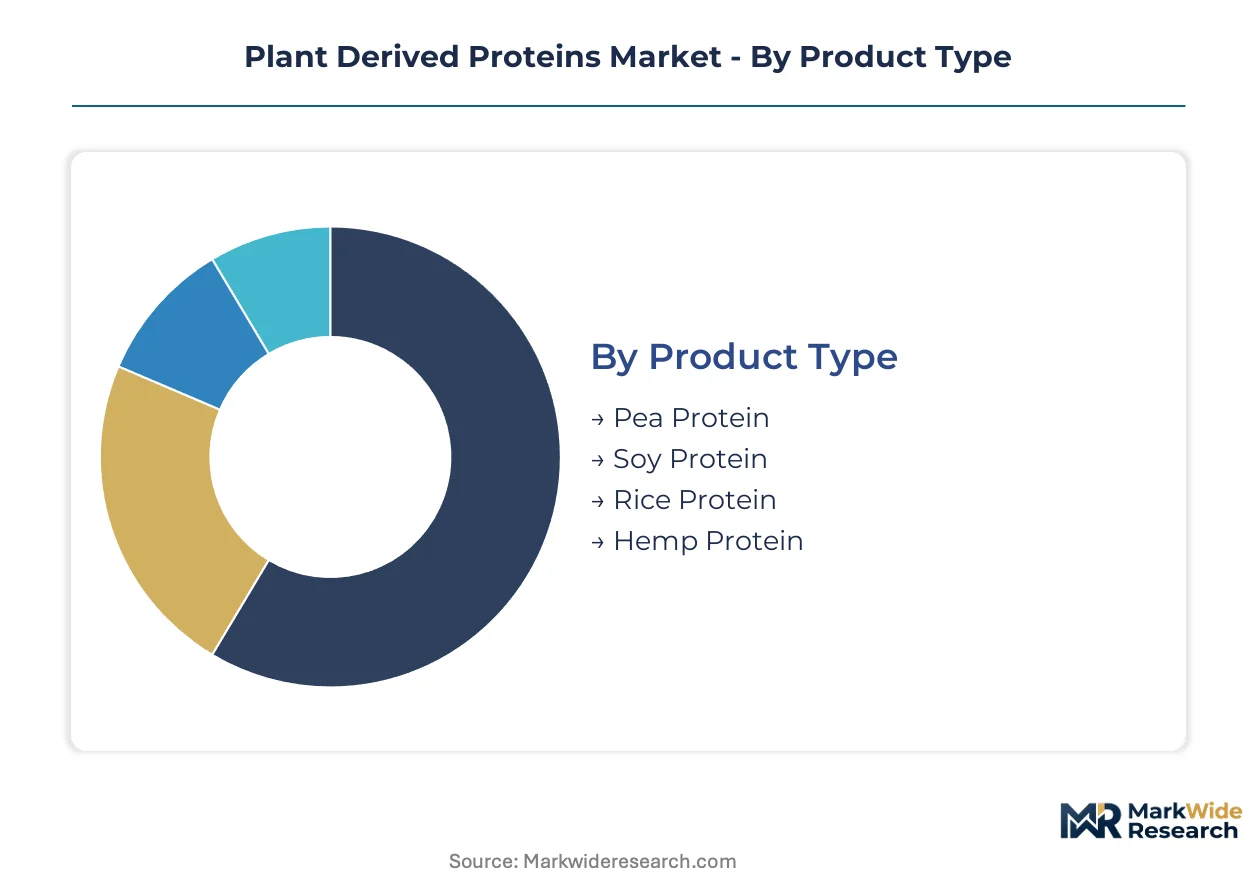
Ingredient buyers select plant derived proteins through layered filtering: functional performance determines technical suitability, then regulatory status gates market access, and finally carbon accounting tilts procurement toward specific geographies. These decision hierarchies fragment supplier strategies across multiple segmentation axes simultaneously.
Product Type:
Buyers prioritize gelation strength, emulsion stability, and amino acid completeness when selecting protein sources for formulated foods.
- Soy Protein:Concentrates and isolates achieve 65-90% protein content through aqueous extraction or alcohol washing. Poultry and aquaculture feed formulators in the United States specify soy protein concentrates for cost-per-unit-protein economics that undercut fishmeal alternatives. FDA GRAS status eliminates novel food authorization delays that constrain emerging sources.
- Pea Protein:Yellow pea isolates deliver gelation and water-binding properties critical to meat analog texture replication. German meat alternative manufacturers source pea protein from Roquette Frères' Vic-sur-Aisne facility to satisfy EU Green Deal carbon footprint disclosure requirements. EFSA's streamlined novel food opinions for established legume sources accelerate formulation timelines versus hemp or algae alternatives.
- Rice Protein:Hypoallergenic protein fractions extracted through enzymatic hydrolysis serve nutritional products targeting elimination diets. Limited extraction capacity in Asia-Pacific constrains supply expansion for allergen-free formulations.
- Hemp Protein:Cold-pressed cake fractions retain fiber and omega fatty acids alongside 50% protein content. EFSA novel food authorization timelines delay European market entry pending allergenicity and heavy metal safety assessments.
Soy protein leads on scale; pea protein leads on momentum.
Application:
End-use specifications diverge sharply: food manufacturing demands functional performance, while nutraceutical buyers prioritize digestibility scores and clean-label positioning.
- Food & Beverage:Plant-based meat formulators specify isolates with precise gelation temperatures and water-holding capacity for extrusion processing. USDA Organic and Non-GMO Project certification premiums filter supplier participation in premium retail channels.
- Nutraceuticals:Sports nutrition and meal replacement brands source rice and pea protein blends to achieve complete amino acid profiles without dairy or soy allergens. FAO digestibility-corrected amino acid score implementation demands reformulation expertise and analytical upgrades from contract manufacturers.
- Animal Feed:Salmon and shrimp aquaculture operations substitute soy protein concentrates for fishmeal as cost economics and sustainability certifications reshape procurement. REACH compliance for processing solvents extends commissioning timelines for new extraction facilities.
- Personal Care:Hydrolyzed wheat and soy proteins function as film-forming agents and humectants in hair and skin formulations. Cosmetic ingredient regulations vary by jurisdiction, fragmenting supplier qualification requirements.
Food and beverage commands volume concentration; nutraceuticals climb the fastest on premium positioning.
Form:
Processing intensity determines protein concentration, functional properties, and unit economics across the value chain.
- Isolate:90% protein content achieved through aqueous extraction and isoelectric precipitation delivers maximum functionality for meat analog applications. Energy-intensive processing elevates unit costs above concentrates, restricting use to premium formulations.
- Concentrate:65-80% protein fractions retain some fiber and carbohydrate content, balancing cost and performance for bakery and feed applications. Dry fractionation combined with air classification enables mid-scale processors to bypass wet extraction capital requirements.
- Powder:Spray-dried protein fractions serve beverage fortification and powder blend applications where solubility and dispersibility determine quality. Particle size distribution specifications vary by end-use, requiring customized milling protocols.
- Textured:Extruded protein structures replicate meat fiber orientation through controlled moisture, temperature, and shear. Specialized screw configuration knowledge and operator skill scarcity constrain capacity expansion despite meat industry outsourcing demand.
Concentrate leads on scale; textured forms gain share fastest on meat analog production scaling.
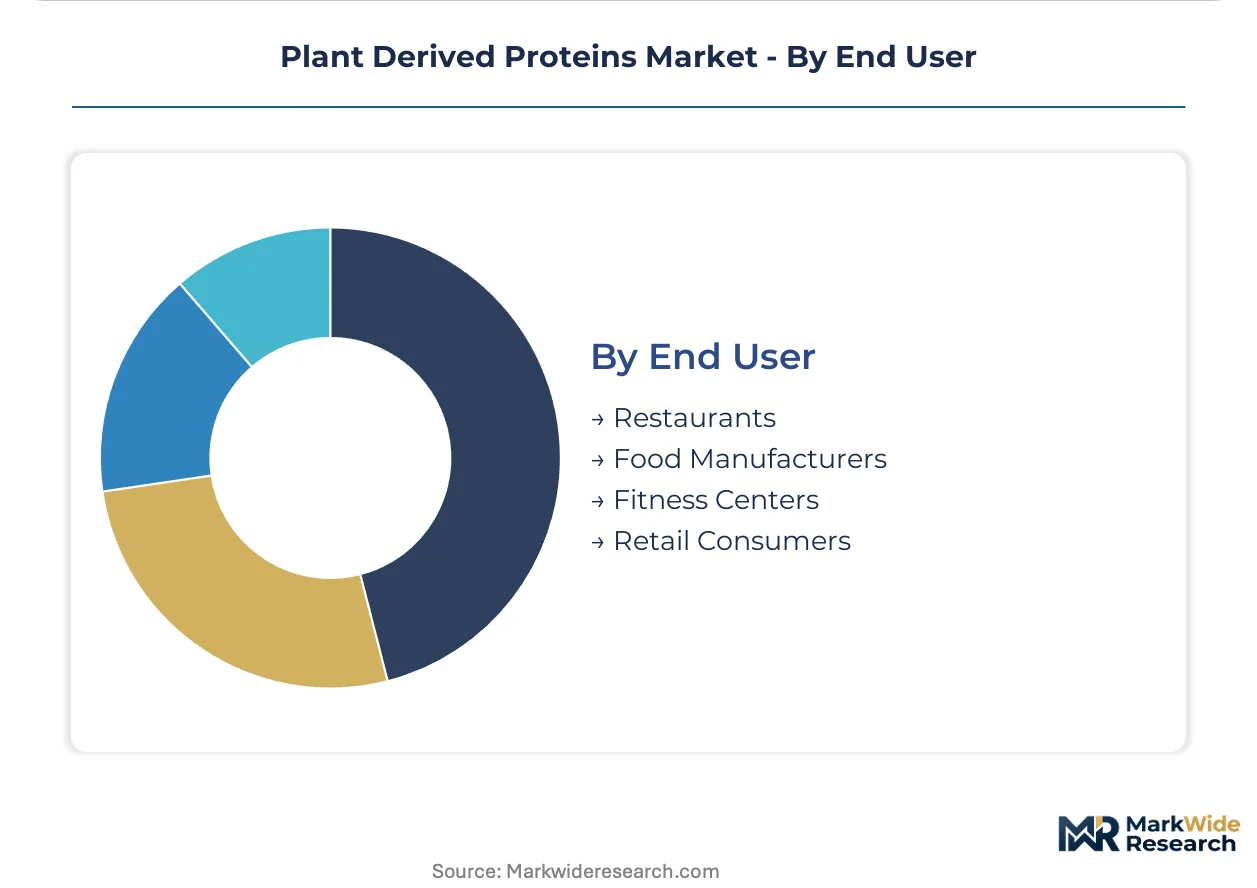
End User:
Procurement sophistication and volume scale separate institutional buyers from fragmented consumer channels.
- Food Manufacturers:Integrated procurement teams negotiate multi-year supply agreements with deforestation-free sourcing guarantees under EU Green Deal requirements. Rail-delivered Ukrainian and Baltic-region peas displace transoceanic alternatives for German processors prioritizing scope-three emissions reductions.
- Restaurants:Foodservice distributors specify textured vegetable protein for plant-based menu items where preparation simplicity and holding stability matter more than premium ingredient positioning.
- Fitness Centers:On-site retail and vending operations stock ready-to-drink protein beverages and powder sachets, capturing impulse purchases with convenience-oriented packaging formats.
- Retail Consumers:E-commerce direct-to-consumer brands compete on subscription pricing and flavor innovation, though certification premiums and shipping costs compress margins versus wholesale channels.
Food manufacturers lead on scale; fitness centers expand most quickly on convenience positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized extrusion technicians and protein chemists concentrate in Germany's Ruhr industrial corridor and the American Midwest, anchoring regional processing capabilities that suppliers struggle to replicate elsewhere.
United States
Poultry and aquaculture feed formulators in Iowa and Arkansas specify soy protein concentrates for cost-per-unit-protein economics. FDA GRAS status eliminates novel food authorization delays that constrain emerging sources. Crushing-adjacent facilities in the Midwest adopt dry fractionation to bypass wet extraction capital intensity.
Germany
Meat alternative manufacturers in Cologne and Hamburg source rail-delivered Ukrainian peas to satisfy EU Green Deal scope-three emissions disclosures. REACH compliance governs chemical safety in hexane and ethanol recovery systems. Dedicated extrusion capacity in the Ruhr region captures meat industry outsourcing demand.
France
Roquette Frères anchors pea protein extraction at its Vic-sur-Aisne facility supplying isolates to plant-based meat formulators. EFSA streamlined novel food opinions for established legume sources accelerate formulation timelines. Ingredient processors in Hauts-de-France build deforestation-free sourcing credentials under Farm to Fork mandates.
China
Wilmar International leverages integrated oilseed crushing networks to supply protein concentrates for domestic feed and food applications. SAMR food safety regulations govern protein fortification labeling. Processing clusters in Jiangsu and Shandong provinces consolidate around soybean origination infrastructure.
Netherlands
Rotterdam and Amsterdam serve as distribution hubs for European-sourced isolates demanded by Scandinavian retail chains. CSRD sustainability reporting requirements compress supplier qualification timelines. Toll processors in Brabant invest in textured protein capacity to serve German outsourcing contracts.
Plant Derived Proteins Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the plant derived proteins landscape, creating a tiered structure where integrated crushers hold feed-grade volume and specialized extractors capture food-grade premiums. The vendor base organizes around three strategic archetypes: multinational agribusinesses with origination-to-processing networks, mid-scale regional fractionators leveraging dry processing economics, and toll extrusion specialists selling texture-as-a-service. Dominant competitive moves include backward integration into seed crushing and strategic partnerships with meat alternative brands seeking captive isolate supply.
Among North American agribusinesses, ADM and Cargill exemplify the integrated archetype through crushing network control and non-GMO soybean stream segregation. Roquette Frères occupies a position within the European specialist tier, anchoring pea protein extraction capacity against transatlantic competitors. These three entities represent contrasting geographic and structural approaches to securing plant protein supply positions.
| Leading Market Players |
|---|
| ADM |
| Cargill |
| Roquette Frères |
| Kerry Group |
| Ingredion |
| Glanbia |
| International Flavors & Fragrances |
| Wilmar International |
| Bunge Global |
| Others |
Value Chain & Pricing Dynamics
The EU Green Deal's Farm to Fork Strategy gates both qualified supply and premium-tier pricing access, compelling ingredient processors to invest in deforestation-free sourcing credentials and carbon accounting transparency before European food manufacturers will award multi-year contracts at price premiums above commodity benchmarks.
Pricing Analysis
Bundled extrusion services command markups over unbundled isolate supply, with German toll processors in the Ruhr region pricing textured protein output on three-tier structure across premium, standard, and economy levels. Price differentiation hinges on Non-GMO Project verification and USDA Organic certification tiers, with rail-delivered Ukrainian peas carrying modest premiums over transoceanic alternatives. Cost compression in standard-grade concentrates is intensifying because dry fractionation adoption in the American Midwest bypasses wet extraction capital intensity. Animal feed formulators exhibit highest price sensitivity, while meat alternative manufacturers absorbing isolate premiums show lowest sensitivity due to finished-product positioning.
Supply Chain Analysis
Certification and qualification gating concentrates qualified supply around ADM's North American crushing network, Roquette Frères' Vic-sur-Aisne facility, and Cargill's Dutch processing operations. Supply chains draw from Brazilian soybean origination, Ukrainian and Baltic-region pea cultivation, and Canadian prairie dry fractionation capacity. Single-source vulnerability risks emerge from limited rice protein extraction capacity in Asia-Pacific constraining allergen-free formulation expansion. Distribution runs through Rotterdam and Amsterdam hubs serving Scandinavian retail chains demanding scope-three emissions disclosures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Plant Derived Proteins Market functions as a stable compounder, with EU Green Deal procurement mandates providing durable demand visibility that supports long-dated capacity investments and multi-year supply agreements.
For Market Incumbents: Extend deforestation-free sourcing credentials through backward integration into Ukrainian and Baltic-region crushing operations, capturing Farm to Fork Strategy procurement mandates before competitors complete supply chain reconfiguration. Add dedicated extrusion capacity in Germany's Ruhr region to capture meat industry outsourcing demand as extrusion operator skill scarcity constrains rival expansion. Certification investment in Non-GMO Project verification creates channel control against commodity competitors. For New Entrants and Emerging Players: Launch via toll extrusion partnerships serving mid-scale meat alternative brands seeking texture-as-a-service without capital intensity of in-house extrusion lines. Target organic and allergen-free nutritional product lines where rice protein supply concentration creates white-space opportunity for enzymatic hydrolysis specialists. Pet food and sports nutrition categories absorb longest EFSA novel food authorization delays, positioning established legume processors to capture formulation demand. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale dry fractionation specialists because capital-light processing technology enables geographic consolidation without wet extraction facility overhead. The five-to-ten year viability window favors processors with established EU Green Deal compliance infrastructure over commodity crushers lacking carbon accounting capabilities. Watch EFSA novel food authorization timelines for hemp and single-cell proteins as inflection indicator for next-generation ingredient platform viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Regional Crushing | Ukrainian and Baltic-region pea origination secures EU Green Deal-compliant supply for German meat alternative manufacturers. |
| Dedicated Extrusion Capacity Expansion | Ruhr region toll processors capture meat industry outsourcing demand amid extrusion operator skill scarcity. |
| Non-GMO Project Certification Investment | USDA Organic seal requirements filter commodity competitors from premium retail channel access. |
| Dry Fractionation Technology Adoption | Mid-scale Midwest processors bypass wet extraction capital intensity while achieving protein concentration economics. |
| EFSA Novel Food Authorization Pursuit | Hemp and algae protein safety opinions unlock European market entry for next-generation ingredient platforms. |
Study Parameters
Multiple input streams — executive interviews with ingredient procurement directors, technical discussions with extrusion equipment specialists, and regulatory consultations with EFSA compliance officers — were reconciled against customs records, EU Farm to Fork Strategy implementation documents, and SEC filings from listed agribusinesses. Bottom-up volume estimates from crushing capacity utilization and top-down demand calibration from food manufacturer formulation trends were triangulated to establish market sizing.
Historical capacity expansion patterns were cross-referenced against panel input from protein chemists and supply chain planners to build the analytical framework. Segmentation dimensions modeled include protein form (isolate, concentrate, textured), application (food and beverage, nutraceuticals, animal feed), and regional regulatory cluster (EU Green Deal compliance tier, FDA GRAS status, SAMR food safety alignment). CAGRs were derived from facility commissioning timelines and procurement contract duration analysis, with extrusion technology adoption curves and FAO protein quality scoring implementation treated as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA novel food authorization delays or REACH compliance extensions for extraction solvents. Forecasts reflect assumptions regarding EU Green Deal enforcement intensity and carbon accounting disclosure adoption rates across European retail chains. A model refresh is warranted upon material change in EFSA regulatory timelines or EU deforestation-free sourcing mandate implementation scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
North America Plant-Based Egg Market
Plant Based Food
Veggie Burger Market
Plant Based Food
Plant Based Meat Market
Plant Based Food
Rhubarb Root Extract Market
Plant Based Food
Soy- Based Food Market
Plant Based Food
Plant-Based Milk Alternatives Market
Plant Based Food
United States Rice Protein Market
Plant Based Food
Plant-Based Nuggets Market
Plant Based Food
Germany Plant Protein Market
Plant Based Food
Soy Food Products Market
Plant Based Food
Asia-Pacific Pea Protein Market
Plant Based Food
Asia Pacific Plant-Based Milk Market
Plant Based Food
Vegan Meat Alternatives Market
Plant Based Food
Global Tofu Market
Plant Based Food
Fermented Plant Extracts Market
Plant Based Food
Plant Based Breads Market