
 Global Digital Grocery Market | 2026-2036
Global Digital Grocery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Grocery Market Foresight
Single-source dependency on Instacart is decoupling as major retailers build proprietary fulfillment infrastructure. Walmart leverages its supercenter network to anchor same-day grocery delivery at scale. Amazon sustains Prime-integrated grocery access through Whole Foods and Amazon Fresh logistics. Kroger competes via Ocado Group's automated warehouse technology, positioning itself against vertically integrated rivals.
Digital grocery denotes food and household product transactions conducted through internet-connected platforms with automated inventory synchronization, cold-chain logistics protocols, and real-time order tracking systems. Mobile apps dominate platform-type engagement due to push-notification personalization and one-tap reordering interfaces. Home delivery captures the largest order-fulfillment volume, while subscription delivery locks recurring revenue from families seeking predictable replenishment. Fresh produce remains the highest-friction product category given perishability constraints and quality-verification demands.
FDA food-safety regulations and USDA organic-certification standards shape product-listing requirements and supplier eligibility across the United States. EU Green Deal packaging-waste directives and GDPR data-privacy frameworks constrain cross-border platform operations in Europe. Stakeholders must monitor evolving last-mile emissions regulations and data-localization mandates as these determine capital-deployment priorities for automated fulfillment networks.
Market Dynamics
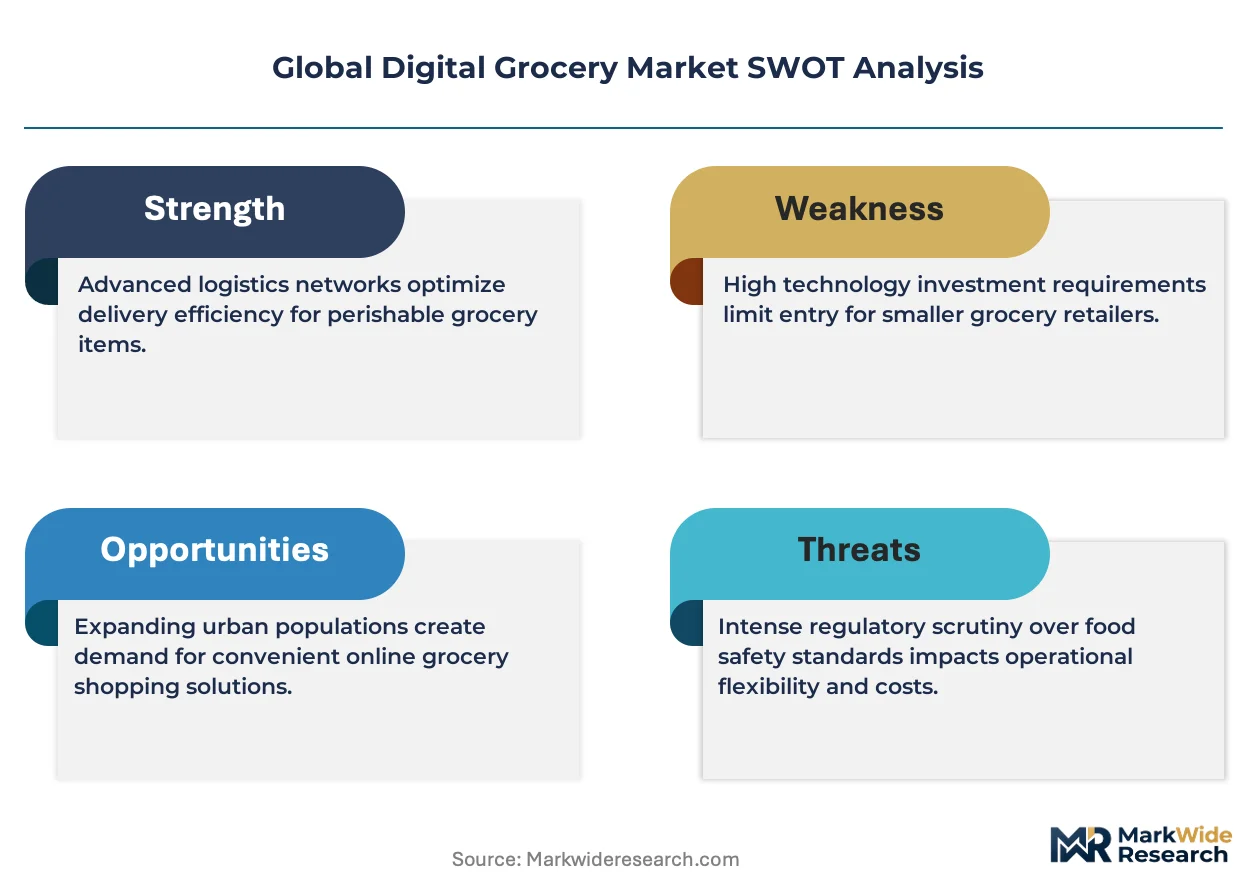
AI-powered demand forecasting and automated warehouse robotics are compressing fulfillment timelines while decoupling retailers from third-party delivery platforms. This structural shift is redrawing capital allocation toward proprietary infrastructure and cold-chain density.
Growth Catalysts
- Time-constrained household demand:Working parents represent a rapidly expanding buyer cohort as routine purchasing shifts online. Mobile apps with push-notification personalization and one-tap reordering interfaces dominate platform engagement.
- GDPR data-privacy frameworks:These European regulations, alongside EU Green Deal packaging-waste directives, are accelerating platform investment in compliant automated fulfillment networks and sustainable last-mile logistics.
- Automated warehouse robotics:Ocado Group's technology deployment by major retailers is enabling same-day fulfillment at scale. This technology compresses picking timelines and reduces labor dependency in high-volume operations.
Market Restraints
- Perishability constraints:Fresh produce remains the highest-friction product category given quality-verification demands and cold-chain integrity requirements throughout last-mile delivery.
- Last-mile emissions regulations:Evolving mandates in urban centers across Germany, France, and the United Kingdom are constraining fleet composition and delivery zone access for diesel-dependent operators.
- Data-localization mandates:Cross-border platform operations face fragmentation as jurisdictions including China, Russia, and Indonesia impose server-location requirements that duplicate infrastructure costs.
Strategic Opportunities
- Subscription delivery models:Families seeking predictable replenishment are locking recurring revenue streams. This channel innovation reduces customer acquisition costs and stabilizes demand forecasting accuracy.
- India's underpenetrated urban markets:Dense metropolitan corridors with rising smartphone penetration present white-space expansion for platforms that can navigate FSSAI food-safety regulations and local supply-chain partnerships.
- FDA food-safety regulations:Compliance with these standards creates supplier eligibility barriers that favor platforms with robust traceability systems, enabling premium positioning in the United States market.
Industry Challenges
- Cold-chain engineering talent scarcity:Platforms struggle to recruit specialists capable of designing temperature-controlled logistics networks that maintain USDA organic-certification integrity from warehouse to doorstep.
- Legacy inventory system integration:Real-time order tracking systems must synchronize with decades-old supermarket ERP architectures, creating data latency and stock-out risks during peak demand windows.
- Multi-jurisdiction certification timelines:Obtaining organic, halal, and allergen-free certifications across supplier bases in Brazil, Australia, and Canada extends product-listing lead times and complicates assortment planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Grocery Market |
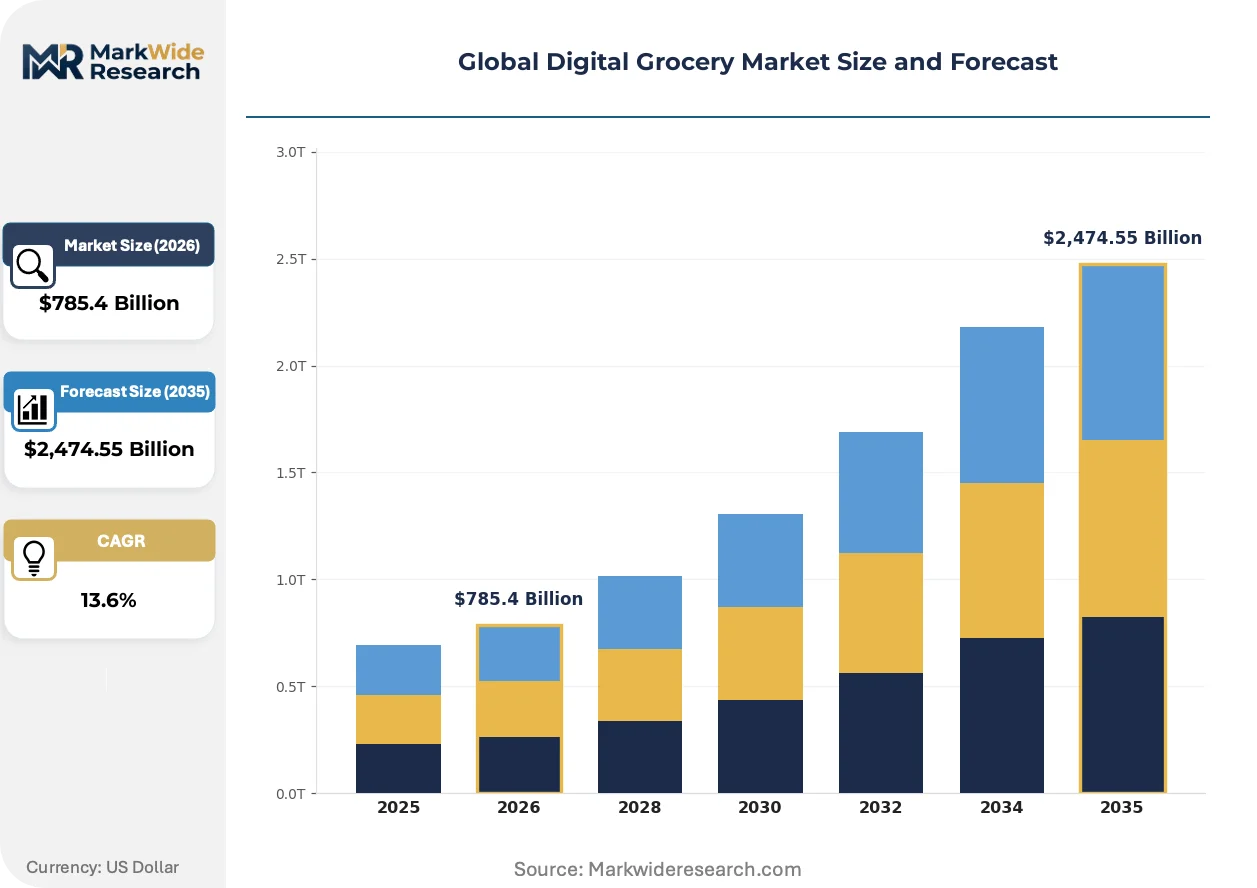
| Market Size in 2026 | $785.4 Billion |
| Market Size in 2035 | $2,474.55 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Mobile Apps, Websites, Voice Commerce, Social Media Channels, Automated Kiosks Product Category: Fresh Produce, Dairy Products, Beverages, Packaged Foods, Household Essentials Customer Type: Busy Professionals, Seniors, Families, Students, Health Enthusiasts Order Fulfillment Method: Home Delivery, Click & Collect, Locker Pickup, Subscription Delivery |
| Companies Covered | Walmart, Amazon, Instacart, Kroger, DoorDash, Uber Technologies, Ocado Group, Alibaba, JD.com, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Grocery Market Shifts & Advancements
Retailers are racing to unify fragmented fulfillment infrastructure while regulators tighten sustainability and data governance requirements. Three concurrent shifts are reshaping platform economics and competitive positioning.
Computer vision systems for produce quality assessment are unifying automated grading with customer-facing transparency. Walmart and Amazon Fresh deploy these systems to reduce refund rates on fresh categories. This technology is unifying supplier accountability with consumer trust, compressing the feedback loop between warehouse inspection and delivery acceptance.
EU Green Deal packaging-waste directives are mandating reusable container systems and extended producer responsibility frameworks. Retailers must redesign last-mile logistics to accommodate return-loop infrastructure for packaging recovery. Germany and France are most affected, with platforms piloting deposit schemes and reverse-logistics partnerships to maintain market access.
Replenishment behavior is shifting from episodic stock-up trips to continuous micro-fulfillment triggered by consumption-sensing devices. Smart refrigerator integrations and voice-assisted reordering are displacing traditional list-based shopping in United States and United Kingdom households with children. This pattern is most visible among dual-income families seeking to eliminate routine cognitive load from household management.
Global Digital Grocery Market Segmentation
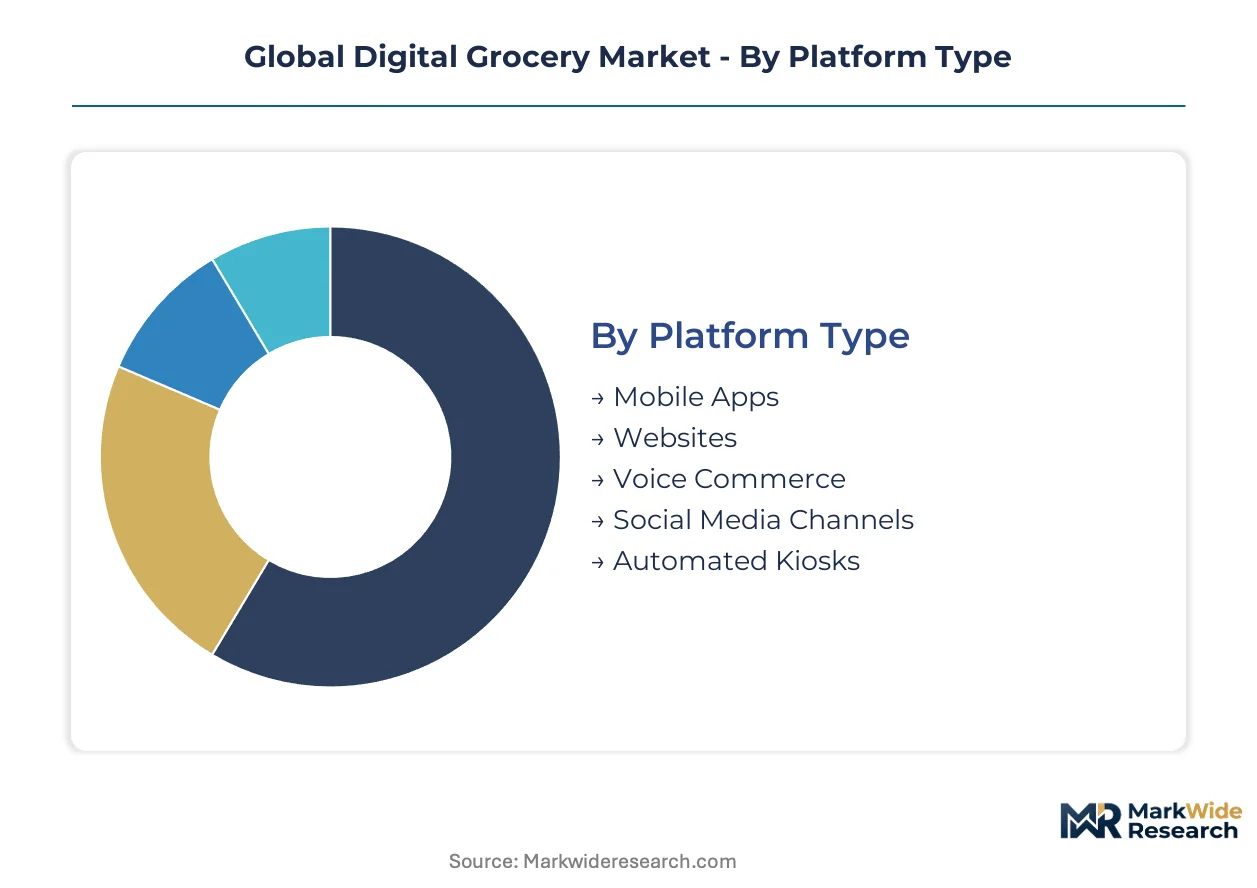
Platform architecture determines customer acquisition economics and retention mechanics in digital grocery. Product category mix shapes fulfillment infrastructure requirements and margin profiles. Customer segmentation drives personalization algorithm investment and loyalty program design.
Platform Type:
Volume concentrates in mobile-first interfaces while premium experimentation clusters in emerging interaction modes.
- Mobile Apps:Native applications dominate transaction volume through push-notification personalization and one-tap reordering interfaces. United States and United Kingdom working parents drive engagement as time-constrained households eliminate routine cognitive load from household management.
- Websites:Browser-based platforms retain significance for planned stock-up purchases and price comparison behavior. China and Germany show sustained desktop usage among seniors and multi-person household coordinators managing large basket sizes.
- Voice Commerce:Smart speaker integration enables hands-free reordering for recurring household staples.
- Social Media Channels:Live-stream commerce and influencer-curated shopping events convert discovery into immediate purchase.
- Automated Kiosks:Self-service terminals bridge digital ordering with physical pickup in transit hubs and office buildings.
Today's leader: Mobile Apps. Tomorrow's challenger: Voice Commerce.
Product Category:
Perishability gradients separate infrastructure-heavy fresh categories from shelf-stable assortment expansion.
- Fresh Produce:Highest-friction category requiring computer vision quality assessment and cold-chain integrity from warehouse to doorstep. Walmart and Amazon Fresh deploy automated grading systems to reduce refund rates and unify supplier accountability with consumer trust.
- Packaged Foods:Standardized handling characteristics enable automated warehouse robotics at scale. Ocado Group technology deployment by Kroger and European retailers compresses picking timelines for ambient and frozen packaged goods.
- Dairy Products:Temperature-controlled logistics networks maintain product integrity across last-mile delivery.
- Beverages:High-weight, low-margin category strains delivery economics without subscription bundling.
- Household Essentials:Predictable replenishment patterns support subscription delivery model economics.
Fresh Produce commands fulfillment investment. Packaged Foods delivers margin stability.
Customer Type:
Dual-income household density determines market prioritization for platform expansion capital.
- Families:Largest revenue cohort seeking predictable replenishment through subscription delivery models. United States and United Kingdom dual-income parents with children drive highest basket values and lowest churn rates.
- Busy Professionals:Time-constrained urban dwellers prioritize convenience over price comparison. India metropolitan corridors with rising smartphone penetration present expansion opportunity for platforms navigating FSSAI food-safety regulations.
- Seniors:Growing segment requiring simplified interfaces and assisted delivery protocols.
- Students:Price-sensitive cohort favoring discount platforms and group ordering features.
- Health Enthusiasts:USDA organic-certification and allergen-free requirements drive premium positioning.
Families anchor revenue today. Health Enthusiasts climb fastest on premium tier expansion.
Order Fulfillment Method:
Delivery speed expectations fragment across urban density and household composition variables.
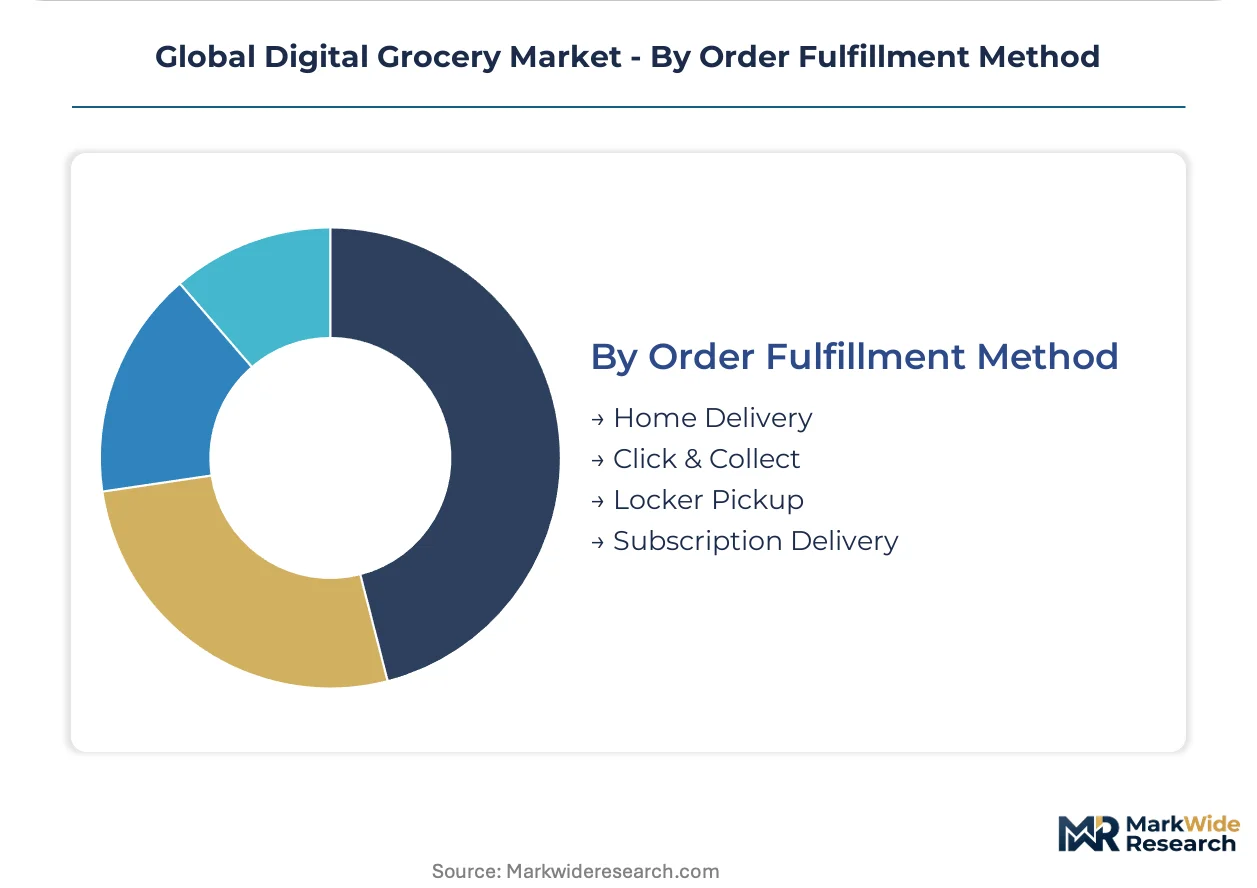
- Home Delivery:Captures largest order volume through same-day and scheduled slot offerings. Amazon Prime-integrated grocery access and Walmart supercenter network anchor scale economics in United States dense metropolitan markets.
- Subscription Delivery:Locks recurring revenue streams with demand forecasting accuracy benefits. Families seeking predictable replenishment reduce customer acquisition costs and stabilize inventory planning.
- Click & Collect:Curbside pickup reduces last-mile cost burden for planned purchases.
- Locker Pickup:Automated collection points serve apartment-dense urban zones and workplace delivery restrictions.
Home Delivery holds volume dominance. Subscription Delivery gains share fastest on retention economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The San Francisco Bay Area anchors digital grocery innovation through venture-backed fulfillment startups and established platform engineering centers. Dense metropolitan corridors across multiple continents now concentrate last-mile infrastructure investment and regulatory compliance expenditure.
United States
Walmart and Amazon deploy competing supercenter and Prime-integrated networks to capture working parent demand in Dallas-Fort Worth and Atlanta suburbs. FDA food-safety regulations and USDA organic-certification standards shape supplier eligibility and traceability system investments. Chicago's warehouse automation cluster hosts Ocado Group technology deployments by major retailers seeking same-day fulfillment scale.
China
Alibaba and JD.com leverage smartphone-saturated urban populations in Shanghai and Shenzhen for app-first grocery penetration. SAMR antitrust oversight and MIIT data-localization mandates constrain cross-border platform operations while accelerating domestic server infrastructure buildout. Beijing's cold-chain logistics corridor concentrates automated warehouse robotics deployment for fresh produce handling.
Germany
EU Green Deal packaging-waste directives and REACH chemical-compliance frameworks force platform redesign of last-mile container return systems. Berlin and Munich metropolitan zones pilot deposit schemes and reverse-logistics partnerships to maintain market access under tightening emissions regulations. Edeka and REWE compete through Ocado-licensed automated fulfillment against Amazon Fresh expansion.
United Kingdom
GDPR data-privacy enforcement and FSA food-hygiene standards create dual compliance burdens for Tesco and Sainsbury's platform operations. London's orbital motorway network supports same-day delivery density while Ocado's Hatfield automated warehouse anchors proprietary fulfillment infrastructure. Manchester and Birmingham corridors concentrate dark-store micro-fulfillment experimentation.
India
Smartphone penetration in Mumbai and Bengaluru corridors drives platform expansion into underpenetrated urban markets. FSSAI food-safety regulations and DGFT import licensing requirements complicate supplier onboarding and cold-chain certification timelines. Hyderabad's logistics technology cluster hosts demand-forecasting AI development for tropical produce handling protocols.
Global Digital Grocery Market Competitive Landscape
Established retailers occupy the standard tier; emerging entrants pursue specialized fulfillment technology and geographic white-space expansion. The market exhibits tiered concentration with vertically integrated supercenter operators, third-party platform intermediaries, and pure-play automation specialists competing through distinct capital-deployment models. Strategic archetypes include proprietary infrastructure builders, aggregator-dependent retailers, and warehouse robotics licensors. Dominant competitive moves encompass backward integration into cold-chain logistics and strategic licensing of automated picking systems.
Within the supercenter-anchored tier, Walmart exemplifies scale-driven fulfillment density through physical store network leverage. Among platform intermediaries, Instacart and DoorDash occupy positions dependent on retailer partnership structures rather than captive supply chains. Ocado Group represents the automation-licensor archetype, enabling same-day capabilities for retailers lacking in-house robotics engineering capacity.
| Leading Market Players |
|---|
| Walmart |
| Amazon |
| Instacart |
| Kroger |
| DoorDash |
| Uber Technologies |
| Ocado Group |
| Alibaba |
| JD.com |
| Others |
Supply & Pricing Matrix
Subscription-versus-transactional divergence separates stable-margin recurring revenue from volatile spot-market economics, with the former tethering supply chain investment to predictable demand corridors and the latter forcing dynamic inventory positioning around promotional calendars. Cold-chain density investments concentrate where subscription penetration locks in multi-year fulfillment commitments, while transactional markets fragment across competing last-mile networks.
Pricing Analysis
Input-cost pass-through from cold-chain logistics and automated warehouse robotics compresses margins for operators lacking proprietary fulfillment infrastructure. Three-tier pricing structure across premium organic-certified, standard national-brand, and economy private-label levels stratifies customer acquisition costs. Pricing pressure stems from Instacart-dependent retailers decoupling toward in-house delivery networks. Families with locked subscription commitments show lowest price sensitivity; students and single urban dwellers drive discount-platform traffic.
Supply Chain Analysis
Dual-sourcing requirements for fresh produce mandate multi-supplier qualification across California's Central Valley, Mexico's Sinaloa corridor, and Spain's Almería greenhouse cluster. Automated picking systems draw from German engineering, Chinese component manufacturing, and British software integration. Single-source vulnerability concentrates in Ocado Group's proprietary robotics licensing. Distribution runs through supercenter-anchored same-day networks and dark-store micro-fulfillment nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion hinges on subscription-model penetration compressing customer acquisition costs and shifting revenue toward predictable replenishment patterns with lower fulfillment volatility.
For Market Incumbents: Deepen proprietary cold-chain infrastructure to decouple from third-party platform dependency. Expand Ocado-licensed automated warehouse deployment in Chicago and Dallas-Fort Worth corridors. Lock supplier exclusivity through USDA organic-certification co-investment programs before emerging automation specialists capture tier-two retailer relationships. For New Entrants and Emerging Players: Begin with voice-commerce integration targeting dual-income United States households with children, where smart-speaker penetration outpaces platform saturation. India's underpenetrated Mumbai and Bengaluru metropolitan zones offer white-space expansion for platforms navigating FSSAI compliance through local supply-chain partnerships. Anchor go-to-market around tropical produce handling protocols developed for Hyderabad's logistics technology cluster. For Investors and Strategic Acquirers: Consolidation pressure builds where automated fulfillment capex requirements exceed mid-tier retailer standalone capacity. Long-term viability favors platforms with captive subscription bases and proprietary robotics engineering rather than aggregator-dependent intermediaries. Target acquisition archetype: regional automation specialists with FDA-traceability systems and dense last-mile networks in Sun Belt metropolitan corridors. Watch for inflection where working-parent subscription penetration crosses threshold triggering competitor exit.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Fulfillment Infrastructure Buildout | Walmart's supercenter network anchors same-day grocery delivery density against Amazon Prime-integrated Whole Foods logistics. |
| Automated Warehouse Robotics Licensing | Kroger's Ocado Group technology deployment compresses picking timelines and reduces labor dependency in high-volume operations. |
| Subscription Delivery Model Expansion | Family-focused predictable replenishment locks recurring revenue and stabilizes demand forecasting accuracy for inventory planning. |
| Computer Vision Quality Assessment Deployment | Amazon Fresh and Walmart reduce fresh produce refund rates through automated grading unifying supplier accountability with consumer trust. |
| EU Green Deal Packaging Compliance Investment | German and French platforms pilot deposit schemes and reverse-logistics partnerships to maintain market access under tightening emissions regulations. |
Research Methodology
Bottom-up household consumption modeling reconciled against top-down automated fulfillment capacity tracking forms the analytical core of this study. Primary interviews with grocery category managers, cold-chain logistics directors, platform engineering leads, and FSSAI compliance officers combined with secondary validation from FDA food-safety filings, USDA organic-certification databases, EU Green Deal directive documentation, and customs cold-chain equipment import records. Triangulation across demand-side behavioral data and supply-side infrastructure investment disclosures ensures segmentation accuracy.
Input-output matrix framing connects working-parent time-constraint indices to subscription-adoption curves across platform-type segments. Modeled dimensions span mobile app versus voice commerce engagement, fresh produce versus packaged goods category mix, and home delivery versus click-and-collect fulfillment methods. CAGRs derive from logistic curve fitting to smartphone penetration trajectories and automated warehouse robotics deployment schedules. Forecast inputs include last-mile emissions regulation timelines and data-localization mandate implementation across China, Russia, and Indonesia.
Several conditions sit outside the modeled scope, including pandemic-triggered demand spikes, tariff restructuring on Mexican produce imports, and breakthroughs in autonomous vehicle last-mile delivery. Forecasts reflect documented assumptions around regulatory stability and technology adoption curves. Deviation in FDA traceability requirement enforcement or EU packaging-waste directive penalty structures would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Thailand Food Service Market
Food Service
North America Food Service Market
Food Service
Food Away from Home Market
Food Service
United States Foodservice Market
Food Service
South America Free from Food Market
Food Service
Global Dark Store Market
Food Service
Saudi Arabia Quick Service Restaurants Market
Food Service
Takeout Dinner Market
Food Service
Vietnam Online Food Delivery Market
Food Service
Kuwait Food Service Market
Food Service
North America Food Platform-To-Consumer Delivery Market
Food Service
Smokeless Grill Market
Food Service
One-Off Chopsticks Market
Food Service
Contract Catering Market
Food Service
Singapore Food Service Market
Food Service
Saudi Arabia Foodservice Market