
 GCC Online Grocery Market | 2026-2036
GCC Online Grocery Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Online Grocery Market Intelligence
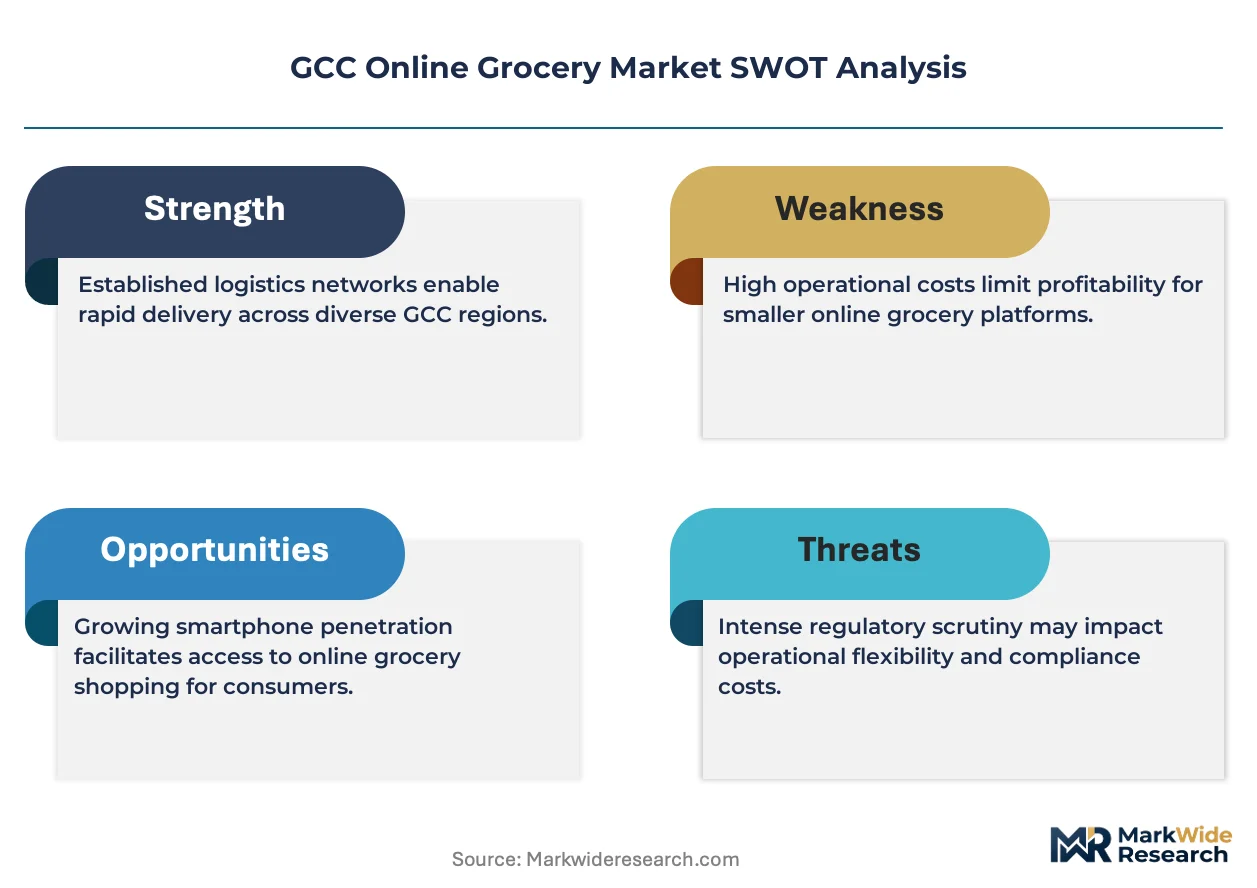
Asset-light dark-store leasing models are rewriting capital requirements for new entrants across the Gulf. Talabat leverages its existing food-delivery logistics backbone to anchor rapid grocery rollout in Dubai and Riyadh. Amazon Fresh competes through centralized inventory control and Prime-integrated subscription mechanics. Noon differentiates via localized assortment depth and Arabic-language interface optimization.
GCC online grocery encompasses perishable and packaged food products ordered through digital platforms for last-mile fulfillment, typically requiring cold-chain maintenance between two and eight degrees Celsius for dairy, meat, and fresh produce categories. The primary commercial purpose centers on replacing traditional supermarket visits with scheduled or on-demand delivery to residential and commercial addresses. Home delivery and same-day delivery dominate transaction volume, though click-and-collect is gaining traction among corporate buyers seeking predictable pickup windows. Individual consumers represent the deepest customer pool, while restaurant and retailer segments command higher average order values and more predictable demand patterns.
SAMR in Saudi Arabia and the UAE's consumer protection frameworks govern product labeling, refund policies, and food safety standards for digital grocery transactions. SAMR's e-commerce trustmark mandates vendor verification and transparent pricing disclosure, tightening market access for unregistered sellers. The Saudi Food and Drug Authority and Emirates Authority for Standardization and Metrology coordinate on imported fresh produce specifications, directly shaping cross-border supplier eligibility. Stakeholders must monitor evolving VAT enforcement on digital transactions and emerging data localization requirements that could fragment platform architecture across Gulf jurisdictions.
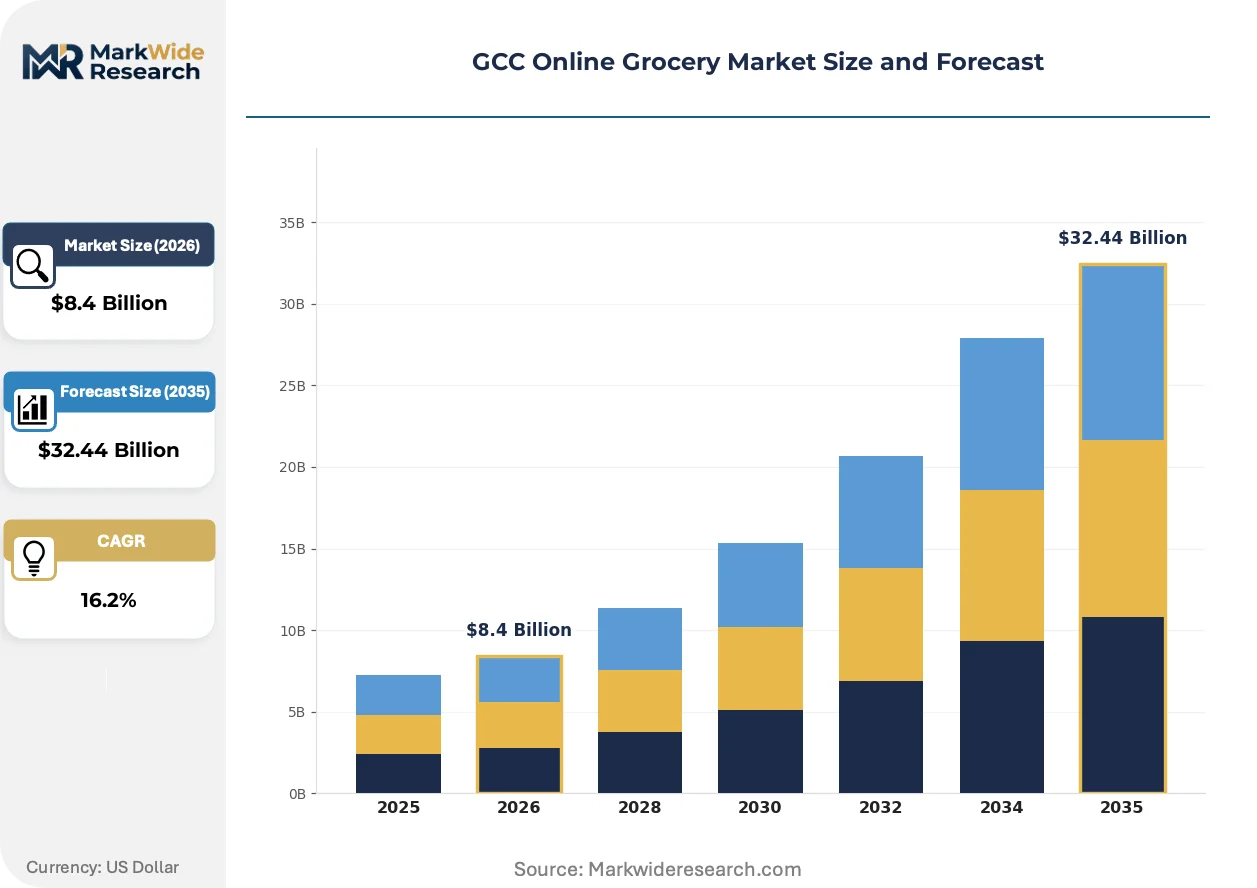
Market Dynamics
Dark-store leasing models are compressing capital requirements for new entrants while SAMR's e-commerce trustmark mandates and UAE digital wallet infrastructure tighten operational standards across Saudi Arabia and the Emirates.
Growth Catalysts
- Smartphone penetration thresholds:Young urban professionals in Riyadh and Dubai now complete weekly basket purchases through mobile-first interfaces, collapsing traditional supermarket visit frequency.
- SAMR trustmark enforcement:Saudi Arabia's vendor verification and transparent pricing disclosure requirements are filtering unregistered sellers, improving platform credibility for mainstream adoption.
- Cold-chain infrastructure expansion:Two-to-eight-degree Celsius maintenance capabilities for dairy, meat, and fresh produce categories are extending delivery radii beyond central business districts.
Market Restraints
- Last-mile fulfillment density requirements:Network economics favor Saudi Arabia and UAE metros where order concentration justifies refrigerated fleet deployment, marginalizing smaller Gulf states.
- Cross-border produce specifications:Saudi Food and Drug Authority and Emirates Authority for Standardization and Metrology coordination on imported fresh produce eligibility fragments supplier pools.
- VAT enforcement fragmentation:Emerging data localization requirements across Gulf jurisdictions threaten to splinter platform architecture and duplicate compliance costs.
Strategic Opportunities
- Corporate click-and-collect adoption:Restaurant and retailer segments with higher average order values seek predictable pickup windows, creating B2B revenue streams beyond individual consumers.
- Scheduled delivery optimization:Demand pattern predictability in commercial addresses enables route consolidation and capacity utilization improvements.
- Arabic-language interface depth:Localized assortment curation and native-language UX design capture segments underserved by English-default platforms.
Industry Challenges
- Refrigerated fleet capex intensity:Cold-chain maintenance between two and eight degrees Celsius requires specialized vehicle investment that strains balance sheets before density thresholds are reached.
- Refund policy standardization:Divergent consumer protection frameworks across Saudi Arabia and UAE create operational complexity for multi-market operators.
- Perishable inventory management:Fresh produce spoilage windows compress reorder cycles and demand forecasting accuracy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Online Grocery Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $32.44 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Dairy, Meat Delivery Model: Home Delivery, Click & Collect, Same-Day Delivery, Scheduled Delivery Customer Type: Individual Consumers, Corporates, Restaurants, Retailers Payment Mode: Credit Card, Debit Card, Cash on Delivery, Mobile Wallets |
| Companies Covered | Alibaba, Noon, Amazon Fresh, Instacart, Talabat, Walmart, JD.com, Ocado Group, Carrefour, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Online Grocery Market Strategic Shifts & Innovations
Mobile-first platform architectures are collapsing traditional grocery purchasing rhythms while regulatory frameworks and fulfillment models undergo parallel compression.
Automated dark-store picking systems are migrating from manual warehouse operations to robotic item retrieval in temperature-controlled micro-fulfillment centers. Grocery platforms in Dubai and Riyadh are deploying these systems to compress order preparation windows from hours to minutes. The technology is migrating from capital-intensive centralized distribution to asset-light leased facilities that reduce entry barriers for regional challengers.
SAMR's e-commerce trustmark mandates vendor verification, transparent pricing disclosure, and standardized refund protocols for digital grocery transactions. These requirements are disqualifying unregistered cross-border sellers and consolidating transaction volume toward compliant domestic platforms. Saudi Arabia's enforcement timeline is compressing faster than neighboring Emirates, creating temporary competitive asymmetries.
Scheduled delivery windows are displacing on-demand immediacy as the dominant preference among corporate buyers and family households. Restaurant and retailer segments prioritize predictable pickup and drop-off timing over sub-hour fulfillment. This behavioral pivot is most visible in Dubai's commercial districts where delivery density supports precise slot allocation without surge pricing volatility.
GCC Online Grocery Market Segmentation
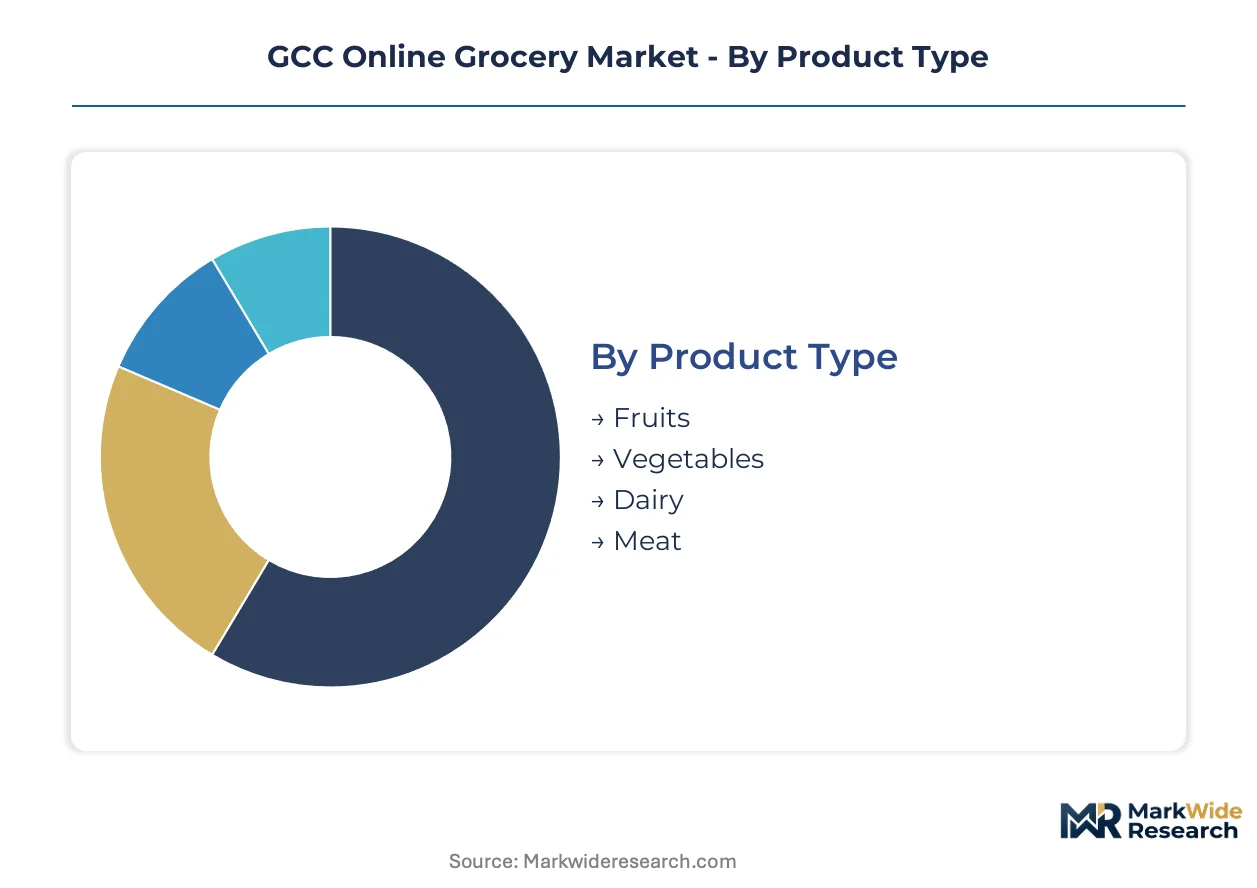
Segmentation in GCC online grocery reveals divergent margin profiles and operational requirements across product freshness windows and fulfillment velocity. Cold-chain intensity and delivery speed expectations create distinct competitive arenas that reward specialized infrastructure investments.
Product Type:
Inventory velocity varies dramatically across temperature requirements, with ambient categories turning weekly while fresh proteins and dairy demand daily replenishment cycles.
- Fruits:Imported produce from Egypt, India, and Turkey dominates assortment breadth. Dubai's restaurant procurement networks drive bulk ordering patterns that strain quality consistency during Gulf summer heat peaks.
- Vegetables:Leafy greens and herbs require strict two-to-eight-degree Celsius handling from farm gate to doorstep. Saudi Arabia's Al-Qassim region supplies domestic tomatoes and cucumbers, shortening lead times versus imported alternatives.
- Dairy:Ultra-high-temperature milk extends shelf stability, but fresh labneh and cheese varieties anchor repeat purchase frequency. UAE dairy processors leverage localized production to compress delivery windows against refrigerated import logistics.
- Meat:Halal certification requirements and chilled distribution constraints elevate supplier qualification barriers. Riyadh and Jeddah households show strongest preference for same-day fresh poultry and lamb cuts.
Dairy anchors the volume base while fresh produce categories gain share at the steepest rate.
Delivery Model:
Capital deployment intensity separates asset-heavy immediate fulfillment from leaner scheduled alternatives, with route density economics favoring concentrated metropolitan deployment.
- Home Delivery:Doorstep fulfillment remains the default expectation for household grocery replenishment. Saudi Arabia's SAMR trustmark requirements now mandate delivery confirmation protocols and temperature logging for perishable handoffs.
- Click & Collect:Corporate buyers and bulk purchasers prioritize predictable pickup windows over speed. Dubai's business district micro-fulfillment centers are adding dedicated collection bays to serve restaurant and retailer segments.
- Same-Day Delivery:Premium slot availability concentrates in Riyadh and Dubai where dark-store density supports sub-four-hour preparation cycles. Cold-chain maintenance through last-mile handoff consumes disproportionate operational cost.
- Scheduled Delivery:Fixed-window arrival preferences are displacing on-demand urgency among family households. Route consolidation across multiple orders improves vehicle utilization and reduces per-delivery cost.
Home delivery retains the dominant transaction share while scheduled delivery climbs fastest as operational sophistication matures.
Customer Type:
Order predictability and average basket value diverge sharply between fragmented household demand and concentrated commercial procurement.
- Individual Consumers:Weekly basket replenishment drives platform engagement frequency. Mobile-first interfaces and Arabic-language UX design determine retention in Saudi Arabia's price-sensitive segments.
- Corporates:Office pantry and staff meal programs generate recurring bulk orders with standardized specifications. Invoice-based payment terms and consolidated billing requirements favor established platforms with enterprise sales capabilities.
- Restaurants:Ingredient freshness specifications and delivery timing precision command premium tolerance. Dubai's F&B sector procurement increasingly shifts from wholesale markets to platform-mediated supply.
- Retailers:Small grocery stores and cafeterias source packaged goods and ambient categories through digital channels. Credit terms and return policies influence supplier selection more than consumer-facing platforms.
Individual consumers provide the deepest addressable pool while restaurant segments deliver the steepest expansion trajectory.
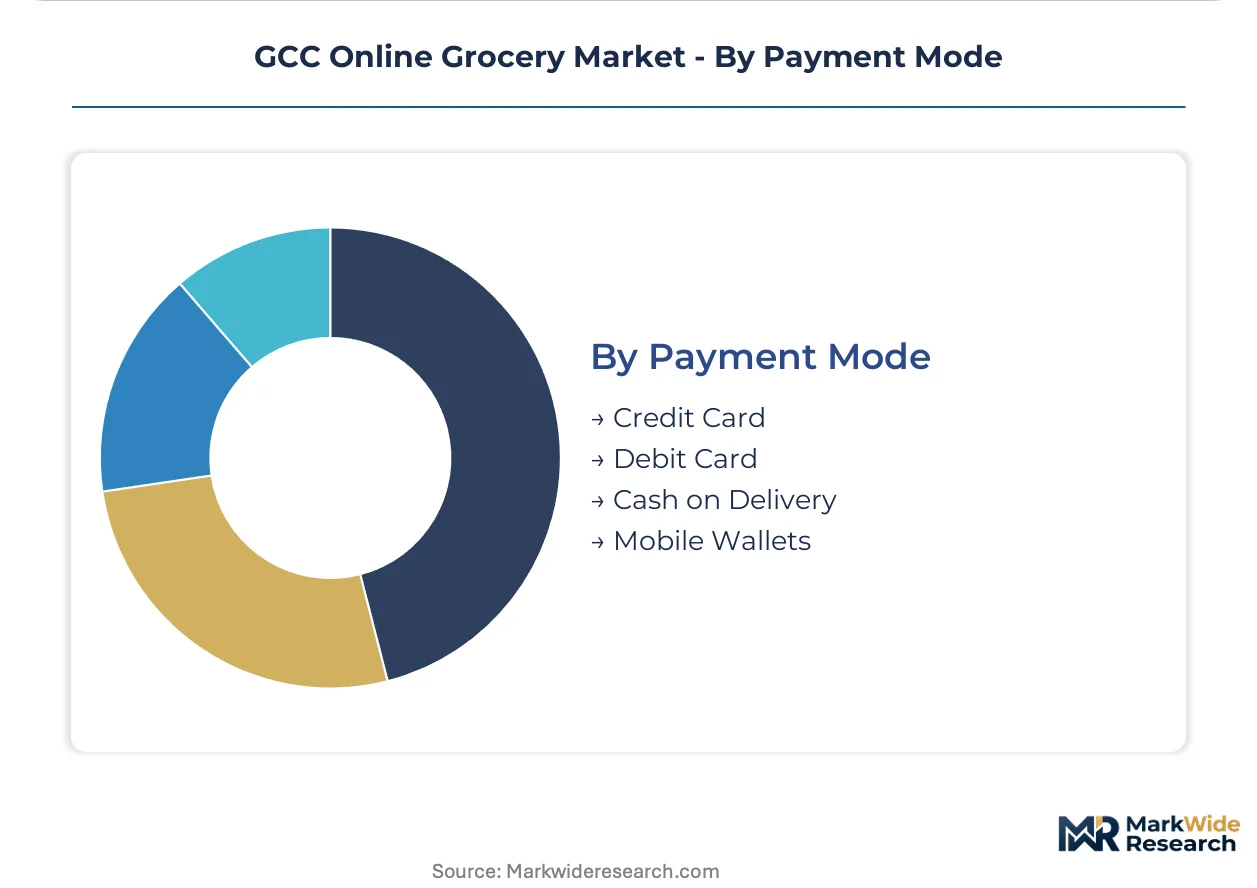
Payment Mode:
Trust infrastructure and regulatory momentum are accelerating digital payment migration while cash retention persists in specific demographic pockets.
- Credit Card:Rewards programs and purchase protection features dominate high-value transaction preference. UAE banking sector competition has reduced merchant discount rates, improving platform economics.
- Debit Card:Direct account linkage appeals to budget-conscious households monitoring expenditure in real time. SAMR pricing transparency mandates reinforce consumer confidence in pre-authorization amounts.
- Cash on Delivery:Remittance-dependent households and unbanked segments sustain demand despite fulfillment cost penalties. Last-mile carriers in Saudi Arabia's secondary cities maintain cash-handling infrastructure.
- Mobile Wallets:UAE government digital wallet infrastructure investments are accelerating adoption velocity. Apple Pay and Samsung Pay integration now standard among Dubai-based platform checkouts.
Card payments anchor transaction volume while mobile wallets expand most quickly amid infrastructure investment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Dubai and Riyadh metros where dark-store density justifies refrigerated fleet deployment, while secondary Gulf cities absorb cost penalties from sparse order concentration. SAMR trustmark enforcement and UAE digital wallet infrastructure widen the operational sophistication gap between Saudi-Emirati corridors and neighboring markets.
Saudi Arabia
Riyadh and Jeddah households drive weekly basket migration to mobile-first platforms, collapsing traditional hypermarket visit frequency. SAMR's e-commerce trustmark mandates vendor verification and transparent pricing disclosure, filtering unregistered cross-border sellers from transaction volume. The Eastern Province's industrial corridor anchors cold-chain warehouse expansion serving corporate restaurant procurement networks.
United Arab Emirates
Dubai's restaurant and retailer segments command premium average order values with predictable delivery timing requirements. MOHAP consumer protection frameworks govern refund policies and food safety standards for digital grocery transactions. Abu Dhabi's government digital wallet infrastructure investments accelerate mobile payment adoption velocity among unbanked demographic segments.
Qatar
Doha's concentrated high-income household base sustains premium-tier scheduled delivery preferences over on-demand urgency. The Qatar Central Bank's regulatory sandbox accommodates experimental payment integration for platform checkout optimization. Lusail City's planned logistics zones attract dark-store leasing interest from regional operators seeking Gulf expansion footholds.
Kuwait
Kuwait City's fragmented retail landscape creates whitespace for platform-mediated grocery consolidation among young professional households. The Ministry of Commerce and Industry coordinates with Gulf standardization bodies on imported fresh produce specifications. Hawalli Governorate's dense residential clustering supports pilot refrigerated last-mile networks before broader national rollout.
Oman
Muscat's lower smartphone penetration and banking access delays mobile-first grocery adoption relative to northern Gulf peers. The Consumer Protection Authority enforces product labeling requirements that elevate compliance costs for cross-border platform entry. Salalah's agricultural hinterland offers domestic sourcing potential for leafy greens and herbs shortening farm-to-doorstep lead times.
GCC Online Grocery Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in fulfillment infrastructure and payment rails. The vendor base compresses toward three archetypes: food-delivery incumbents repurposing logistics backbone, e-commerce giants leveraging centralized inventory control, and regional challengers optimizing Arabic-language interface depth. Consolidation pressure intensifies as SAMR trustmark requirements and cold-chain capex thresholds filter marginal operators. Dominant competitive moves include dark-store leasing partnerships and Prime-integrated subscription mechanics.
Among regional platform operators, Talabat and Noon occupy distinct positioning vectors within the Gulf grocery expansion. Talabat exemplifies the food-delivery incumbent archetype, leveraging existing logistics infrastructure to anchor rapid rollout in Dubai and Riyadh. Noon represents the localization-specialist tier, differentiating through Arabic-language interface optimization and curated assortment depth. Amazon Fresh anchors the global e-commerce giant archetype, competing through centralized inventory control and subscription-integrated customer mechanics. Each occupies a definable strategic space without direct functional overlap.
| Leading Market Players |
|---|
| Alibaba |
| Noon |
| Amazon Fresh |
| Instacart |
| Talabat |
| Walmart |
| JD.com |
| Ocado Group |
| Carrefour |
| Others |
Cost & Logistics Intelligence
Single-source dependency on Egyptian and Indian produce imports during Gulf summer heat peaks compresses margin buffers across freshness tiers while dictating cold-chain infrastructure placement between farm gate and doorstep. SAMR trustmark compliance costs and refrigerated fleet capex intensity stratify platform economics, forcing three-tier pricing separation between premium same-day, standard scheduled, and economy next-day fulfillment windows.
Pricing Analysis
Restaurant procurement managers anchor contract-based long-term offtake structures that lock in volume commitments against per-unit spot volatility. Price differentiation stems from halal certification grade and delivery velocity tier, with same-day chilled meat commanding substantial premiums over ambient-packaged alternatives. Pricing pressure intensifies in the standard scheduled tier as Talabat and Noon compress margins to capture household frequency. Individual consumers exhibit highest price sensitivity, while Dubai restaurant segments tolerate premium markups for timing precision.
Supply Chain Analysis
Tariff exposure between Turkey and Saudi Arabia dominates fresh produce landed cost variability during lira volatility periods. Supply concentrates in Egypt, India, and Turkey for fruits; the UAE and Saudi Arabia for localized dairy processing; and Brazil and Australia for chilled meat imports. Cold-chain dependencies rest on refrigerated container availability, last-mile fleet density, and dark-store temperature control systems. Single-source vulnerability persists in leafy greens during summer import disruptions. Distribution runs through platform-operated dark stores feeding both direct-to-consumer and click-and-collect nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SAMR trustmark enforcement and UAE digital wallet infrastructure represent concurrent regulatory and technological inflections reshaping competitive viability. Platforms that synchronize compliance architecture with payment rail integration capture disproportionate household wallet share.
For Market Incumbents: Build fulfillment density moats through leased dark-store networks in Riyadh and Dubai before secondary city saturation. Anchor defensive positioning against Amazon Fresh's Prime-integrated subscription mechanics by locking exclusive supplier agreements with Saudi Arabia's Al-Qassim vegetable growers and UAE dairy processors. Deepen Arabic-language interface personalization to raise switching costs among price-sensitive Saudi households.
For New Entrants and Emerging Players: Pursue corporate click-and-collect whitespace in Kuwait City's fragmented retail landscape and Oman's Muscat corridor where incumbent coverage remains thin. Target restaurant procurement segments in Doha and Hawalli Governorate with predictable bulk ordering patterns and invoice-based payment terms. Differentiate through halal certification tier specialization or scheduled delivery slot optimization rather than competing head-to-head on same-day velocity.
For Investors and Strategic Acquirers: SAMR trustmark compliance deadlines reshape the acquisition landscape toward platforms with verified vendor networks and transparent pricing infrastructure. Long-term viability centers on cold-chain asset-light models that scale across Gulf jurisdictions without duplicating refrigerated fleet investment. Prioritize targets with established corporate B2B revenue streams and localized Arabic UX depth. Watch Qatar Central Bank regulatory sandbox expansions as signal for payment integration arbitrage opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Dark-Store Leasing Partnership | Asset-light expansion into Riyadh and Dubai compresses capital requirements versus build-own-operate models. |
| Arabic-Language Interface Optimization | Native UX design captures Saudi price-sensitive segments underserved by English-default platforms. |
| Cold-Chain Infrastructure Investment | Two-to-eight-degree Celsius fleet density extends delivery radii beyond central business districts. |
| Corporate Click-and-Collect Launch | Dedicated collection bays serve Dubai restaurant and retailer segments with higher average order values. |
| Digital Wallet Integration | MOHAP and SAMR-aligned payment rails accelerate checkout velocity among UAE and Saudi households. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SAMR regulatory filings, UAE consumer protection frameworks, and GCC customs trade data. Primary interviews engaged grocery platform operations directors, cold-chain logistics providers, restaurant procurement managers, and retail category buyers. Secondary validation drew from Saudi Food and Drug Authority import specifications, Emirates Authority for Standardization and Metrology protocols, and digital payment infrastructure disclosures. Bottom-up order volume modeling triangulates against top-down market sizing across product type, delivery model, and customer segment dimensions.
Forecast inputs incorporate smartphone penetration trajectories, dark-store deployment pipelines, and regulatory enforcement timelines across the analysis window. Segmentation modeling spans product freshness tiers, fulfillment velocity categories, customer archetypes, and payment mode adoption curves. CAGRs derive from historical order growth patterns, platform capacity expansion announcements, and demographic shift projections. Cold-chain capex intensity and SAMR compliance cost curves inform margin compression assumptions.
Sensitivities concentrate around tariff volatility in Turkish and Indian produce imports, refrigerated fleet utilization thresholds in secondary Gulf cities, and divergent VAT enforcement timelines. Forecasts reflect assumptions about trustmark adoption velocity and digital wallet penetration without presuming uniform regulatory harmonization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Global Delivery Takeaway Food Market
Food Service
Europe Vending Machine Market
Food Service
Global Dark Store Market
Food Service
Virtual Kitchen Market
Food Service
Stirrers Market
Food Service
Vietnam Online Food Delivery Market
Food Service
United States Foodservice Market
Food Service
Commercial Grills Market
Food Service
United Kingdom Full Service Restaurants Market
Food Service
GCC Biodegradable Food Service Disposables Market
Food Service
Commercial Air Fryer Oven Market
Food Service
North America Food Service Disposable Market
Food Service
Integrated Stove Market
Food Service
Beverage Coaster Market
Food Service
Limited-Service Restaurants Market
Food Service
Rotisseries Market