
 Indonesia Foodservice Market | 2026-2036
Indonesia Foodservice Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Foodservice Market Outlook
BPJPH halal certification is redrawing competitive boundaries across Indonesia's foodservice landscape. PT Fast Food Indonesia Tbk leverages its KFC franchise network to sustain nationwide kitchen standardization. PT Sarimelati Kencana Tbk anchors the Pizza Hut system through controlled supply chain protocols. Jiwa Group differentiates via localized coffee formats that navigate Indonesia's diverse regional tastes.
Indonesia foodservice encompasses commercial meal preparation and delivery across full-service restaurants, quick-service outlets, cafés, and mobile food trucks, operating through centralized kitchens with cold-chain logistics maintaining temperatures below five degrees Celsius for protein-based menu items. Quick-service formats lead volume throughput due to standardized preparation cycles suited to dense urban traffic patterns. Full-service dining captures concentrated margin pools in Jakarta and Bali tourism corridors. Delivery channels are expanding fastest as digital platform integration reshapes last-mile fulfillment economics.
BPJPH, the National Halal Product Guarantee Agency, enforces mandatory halal labeling timelines that reshape procurement and kitchen segregation protocols for chains operating across the archipelago. Indonesia's Ministry of Health sanitation regulations and local Dinas Kesehatan inspection regimes govern operational licensing and facility compliance standards. Stakeholders must monitor certification backlog durations and provincial enforcement variance to calibrate expansion sequencing.
Market Dynamics
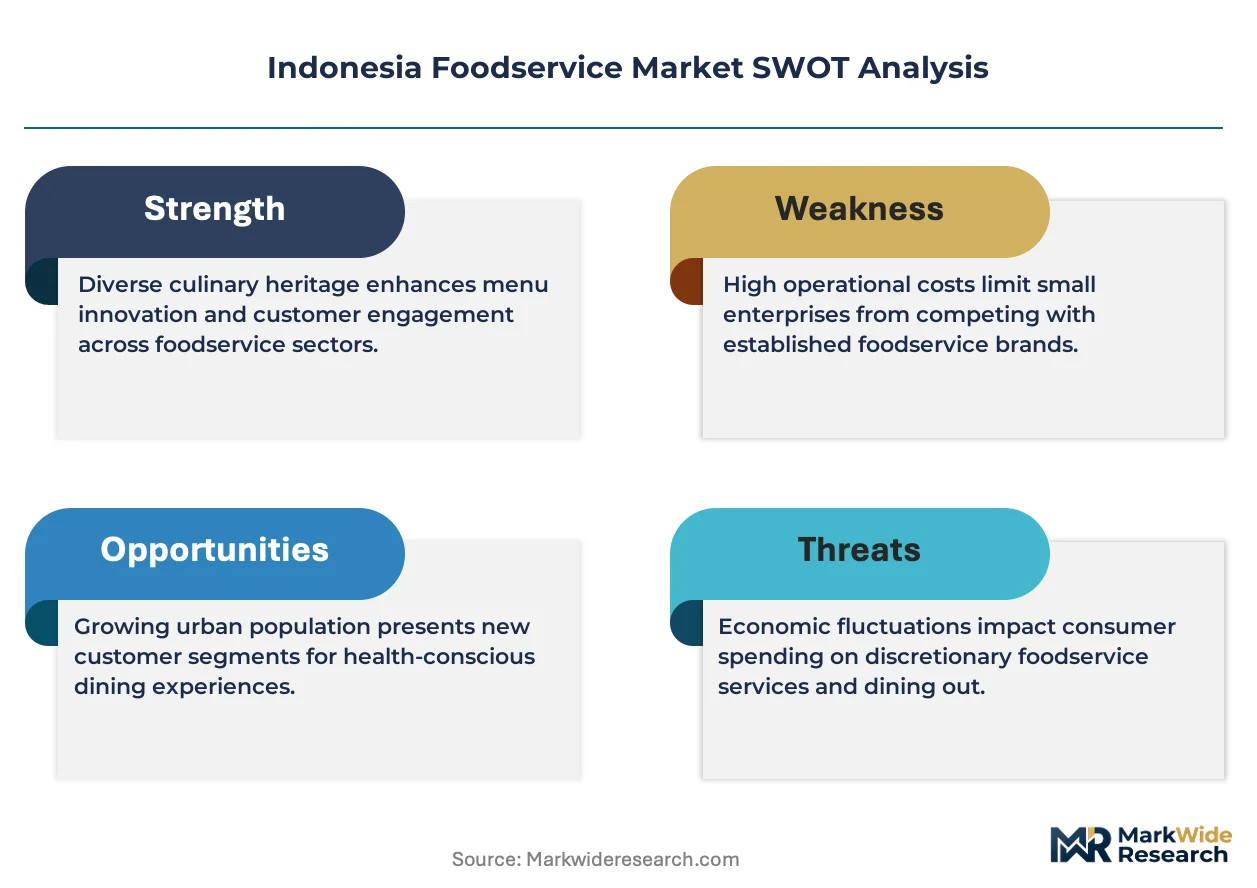
BPJPH halal certification mandates are forcing kitchen segregation protocols and supplier requalification across Indonesia's archipelago, compressing margins for operators lacking centralized procurement systems.
Growth Catalysts
- Urban Millennial Density:Jakarta and Surabaya metropolitan zones concentrate purchasing power for quick-service formats with standardized throughput cycles.
- BPJPH Regulatory Enforcement:Mandatory halal labeling timelines create compliance-driven demand for certified supply chain partners and segregated production facilities.
- Digital Platform Integration:Last-mile delivery apps are rewiring fulfillment economics for independent operators and chain franchises alike.
Market Restraints
- Protein Cold-Chain Costs:Maintaining sub-five-degree Celsius logistics across 17,000 islands imposes capital intensity on inter-island distribution.
- Provincial Enforcement Variance:Dinas Kesehatan inspection regimes differ across regencies, creating licensing friction for multi-location expansion.
- Certification Backlog Durations:BPJPH processing queues delay menu launches and supplier onboarding for new market entrants.
Strategic Opportunities
- Eastern Indonesia Penetration:Makassar and Manado corridors remain underdeveloped for branded quick-service relative to Java saturation.
- Mobile Food Truck Formats:Lower capex entry points suit secondary city deployment where permanent real estate costs exceed operator capital reserves.
- Tourism Corridor Premium Dining:Bali's international visitor recovery creates margin pools for full-service concepts with localized menu engineering.
Industry Challenges
- Kitchen Segregation Capex:Dual production lines for halal and non-halal items require facility redesigns that strain operator balance sheets.
- Halal Auditor Shortage:BPJPH-certified assessor scarcity extends compliance timelines and raises third-party verification costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Foodservice Market |
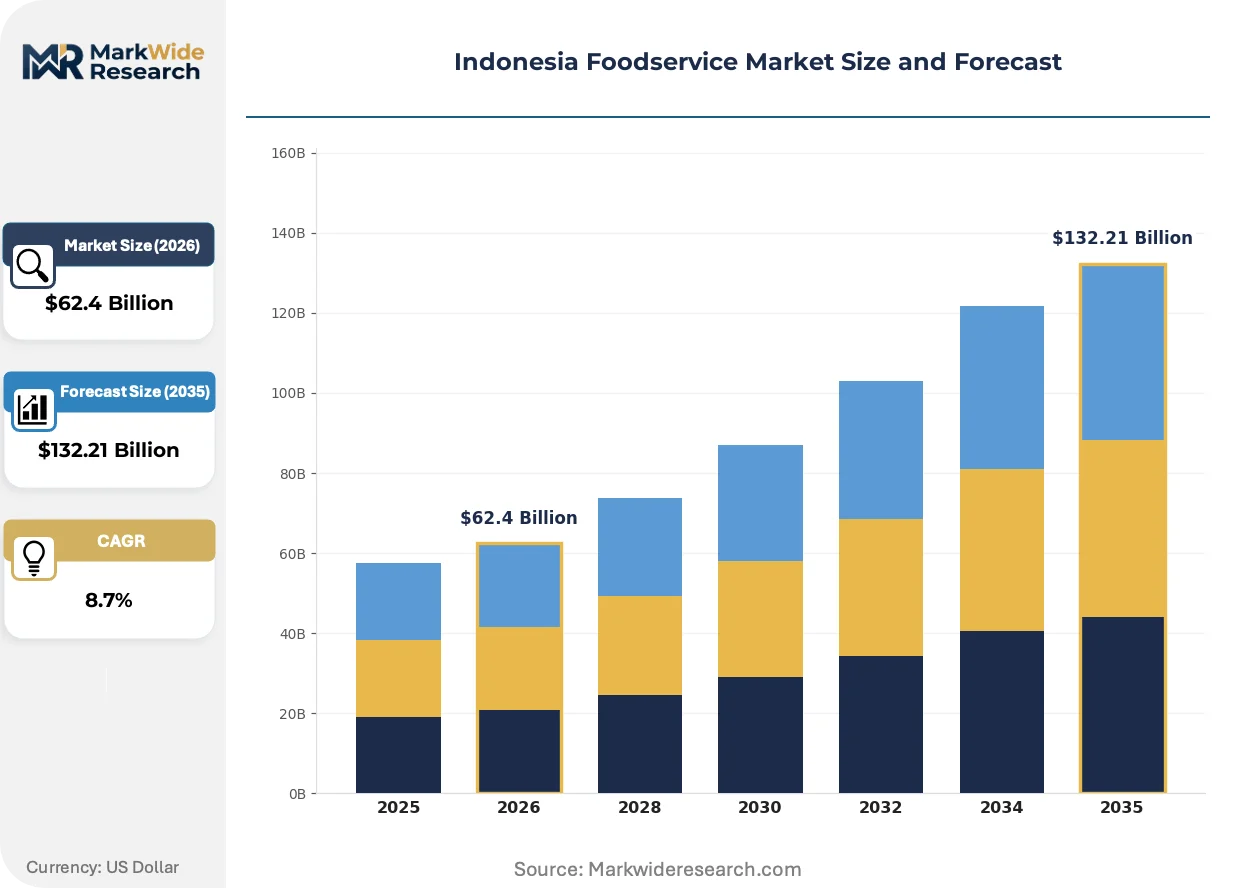
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $132.21 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service, Quick-Service, Cafés, Food Trucks End User: Restaurants, Hospitals, Educational Institutions, Corporate Offices Cuisine Type: Local, Asian, Western, Fusion Distribution Channel: Delivery, Dine-In, Takeaway, Catering |
| Companies Covered | PT Rekso Nasional Food, PT Map Boga Adiperkasa Tbk, PT Sarimelati Kencana Tbk, Inspire Brands, Inc., PT JCO Donut & Coffee, Jiwa Group, Solaria Indonesia, PT Fast Food Indonesia Tbk, Restaurant Brands Asia Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Foodservice Market Strategic Shifts
Centralized kitchen architecture and digital order-rail integration are compressing preparation cycle variability across Indonesia's quick-service segment. These shifts favor operators with capital to standardize production before geographic scaling.
Cloud-based kitchen management software is decomposing traditional site-level autonomy into remotely monitored production nodes. Quick-service chains with Java-centric footprints are adopting these systems fastest. The technology is decomposing franchisee operational discretion into headquarters-controlled throughput metrics.
Indonesia's Halal Product Assurance Law mandates BPJPH certification for all foodservice operators by statutory deadlines. This policy is forcing supplier requalification and ingredient traceability investments. Full-service restaurants in Greater Jakarta face the steepest compliance curves due to menu complexity and import dependency.
Delivery-aggregator dependence is restructuring customer acquisition economics for independent operators. Commission structures from Gojek and GrabFood platforms are displacing direct-order margin retention. This pattern concentrates most visibly in Surabaya's dense urban corridors where digital penetration outpaces parking infrastructure.
Indonesia Foodservice Market Segmentation
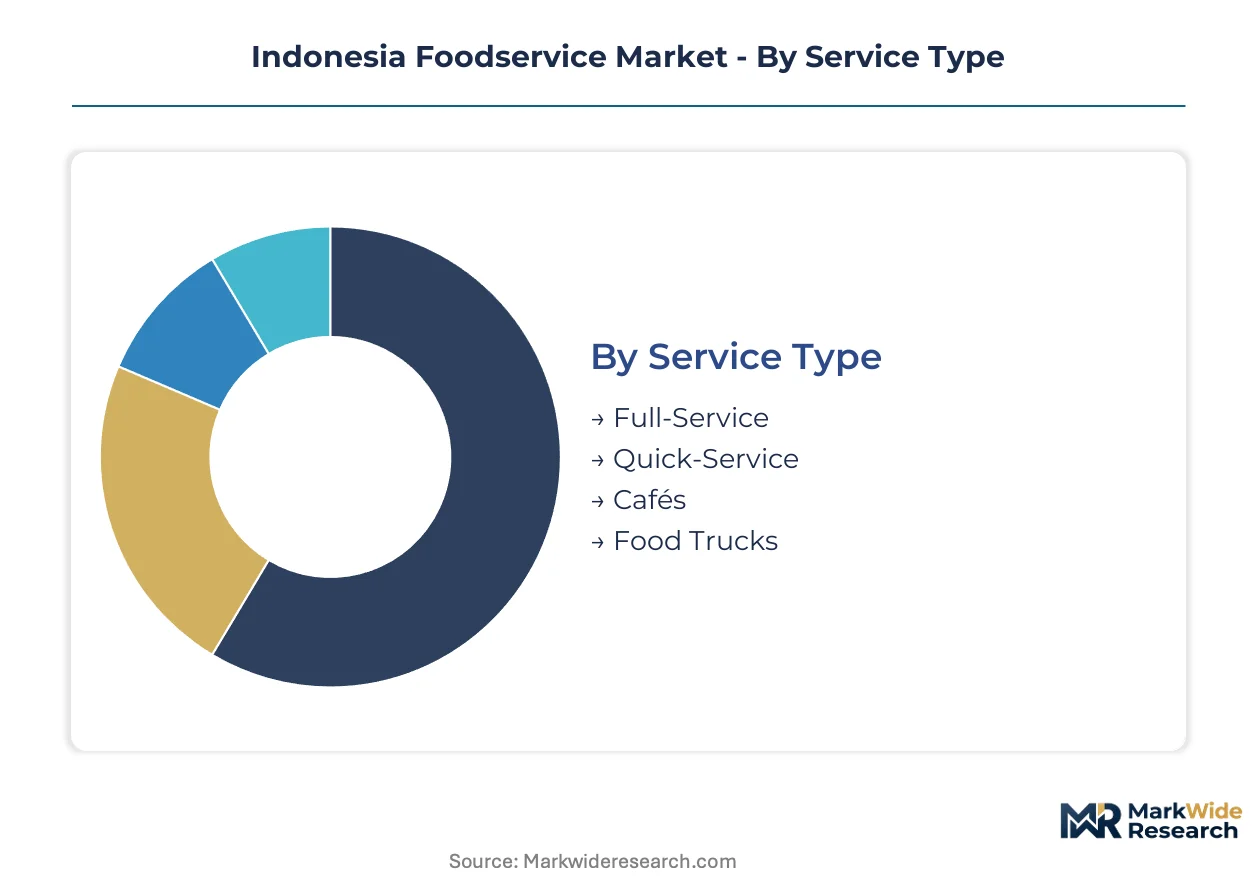
Segmentation reveals where capital is clustering across Indonesia's foodservice landscape. Service format and distribution channel choices determine compliance burden and margin durability under BPJPH mandates.
Service Type:
Margin pools concentrate in formats with throughput standardization and lower per-unit labor intensity.
- Quick-Service:Standardized preparation cycles with sub-three-minute service windows suit Jakarta and Surabaya's dense urban traffic. BPJPH kitchen segregation protocols favor chains with centralized procurement systems that can absorb compliance costs across volume.
- Full-Service:Higher check averages and extended dwell times capture premium spending in Bali tourism corridors and Jakarta's central business district. Menu complexity drives import dependency and steeper halal certification curves.
- Cafés:Localized beverage formats with lower equipment capex suit secondary city penetration where real estate costs strain operator reserves.
- Food Trucks:Mobile deployment bypasses permanent facility requirements, offering entry points in Makassar and Manado corridors with limited branded quick-service presence.
Quick-Service holds installed capacity. Food Trucks are rotating up the share rankings.
End User:
Contract stability varies sharply across institutional versus discretionary spending environments.
- Restaurants:Direct consumer-facing operations carry full BPJPH compliance burden and Dinas Kesehatan licensing exposure across every provincial jurisdiction.
- Hospitals:Mandatory halal requirements align with patient demographic composition; procurement runs through centralized tender processes with extended payment cycles.
- Educational Institutions:Volume contracts with state and private universities in Greater Jakarta concentrate demand for standardized meal plans with cost-per-meal constraints.
- Corporate Offices:Business district catering in Jakarta's SCBD and Thamrin corridors demands premium positioning with delivery reliability metrics.
Restaurants absorb the largest compliance overhead. Corporate Offices are expanding contract values fastest.
Cuisine Type:
Ingredient sourcing geography determines halal certification complexity and cold-chain capital requirements.
- Local:Domestic supply chains reduce import dependency and BPJPH traceability burden; regional taste variation demands kitchen-level adaptation across the archipelago.
- Asian:Cross-border ingredient flows from ASEAN trading partners require documented halal status at origin; demand concentrates in Surabaya's ethnic Chinese and Korean expatriate corridors.
- Western:Dairy and protein imports from Australia and New Zealand carry established halal credentials; premium positioning in Jakarta's Kemang and Senopati districts supports margin.
- Fusion:Menu engineering complexity multiplies supplier qualification requirements; experimental formats target Jakarta's affluent millennial demographic with disposable income for novelty.
Local cuisine commands volume leadership. Fusion concepts are gaining share fastest in metropolitan zones.
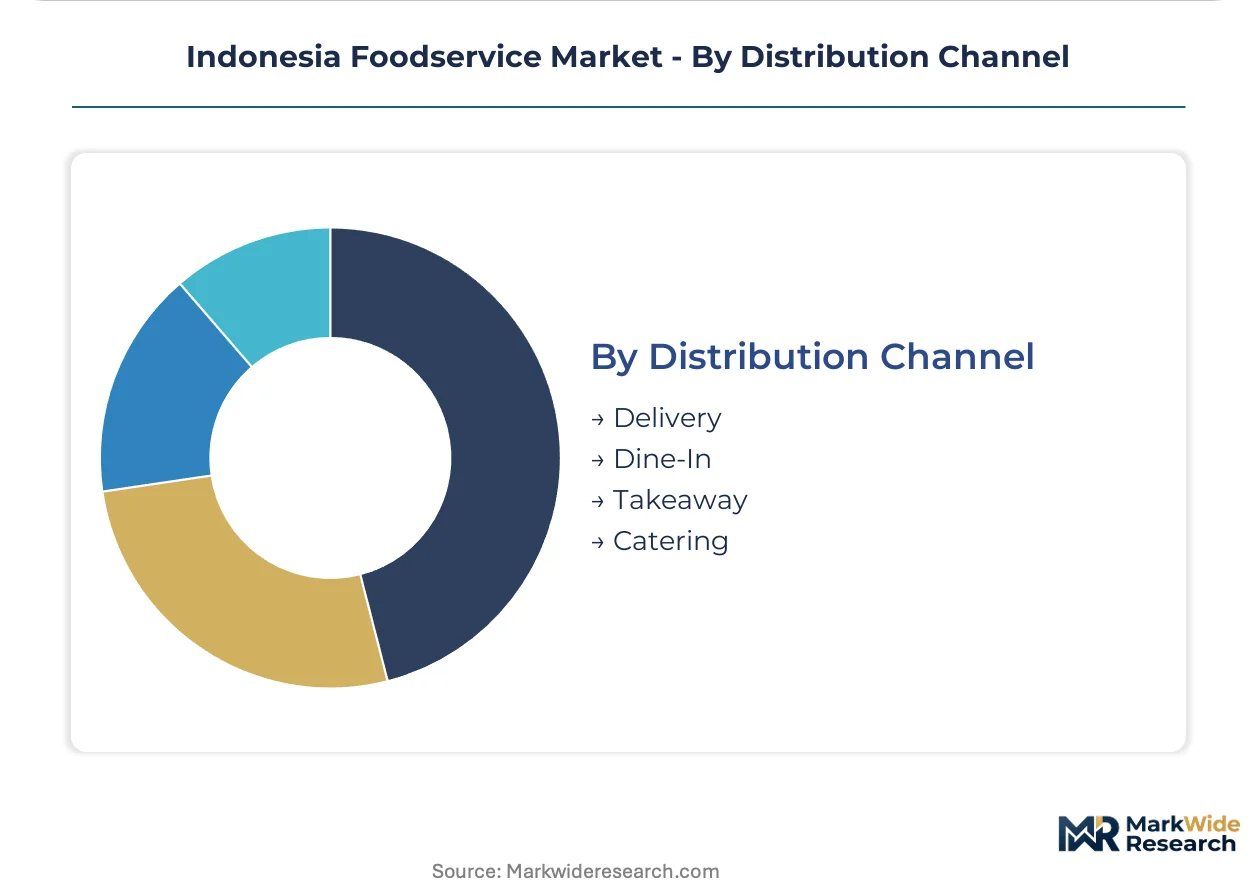
Distribution Channel:
Last-mile economics are restructuring as digital platforms capture customer relationships.
- Delivery:Gojek and GrabFood commission structures displace direct-order margin retention; aggregator dependence concentrates in Surabaya where parking infrastructure lags digital penetration.
- Dine-In:Facility capex and labor intensity weigh on returns; full-service concepts in Bali's Seminyak and Ubud rely on international visitor recovery for occupancy.
- Takeaway:Lower fulfillment cost than delivery with retained customer data; quick-service chains deploy dedicated pickup counters to defend margin.
- Catering:Event-based volume with advance ordering reduces kitchen throughput variability; corporate and wedding segments in Jakarta drive bulk procurement.
Dine-In retains the highest per-transaction value. Delivery is climbing the fastest as platform penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tanjung Priok Port's container throughput underwrites Greater Jakarta's dominance in Indonesia foodservice distribution, channeling imported proteins and dairy through cold-chain corridors that feed quick-service standardization across Java.
Greater Jakarta
Urban millennial density in Jabodetabek concentrates purchasing power for quick-service formats with sub-three-minute throughput cycles. BPJPH halal certification mandates reshape procurement protocols for chains operating across the metropolitan zone. Central Jakarta's SCBD and Thamrin corridors host premium full-service dining that captures corporate catering contracts and international business traffic.
East Java
Surabaya's port infrastructure enables protein import flows that sustain quick-service expansion with documented halal credentials from Australian and New Zealand origins. Dinas Kesehatan inspection variance across regencies creates licensing friction for multi-location operators. The metropolitan zone's dense urban traffic patterns favor standardized preparation cycles that delivery platforms amplify through digital penetration.
Bali
International visitor recovery in Seminyak and Ubud corridors drives premium full-service margin pools with localized menu engineering demands. Ministry of Health sanitation regulations govern operational licensing for tourism-dependent foodservice concepts. The island's limited cold-chain infrastructure concentrates branded quick-service presence in southern coastal zones near Ngurah Rai Airport logistics.
South Sulawesi
Makassar's underdeveloped branded quick-service presence relative to Java saturation creates whitespace for mobile food truck deployment with lower capex entry points. Provincial enforcement variance in halal certification timelines delays supplier onboarding for new market entrants. The city's port position as eastern Indonesia's logistics hub channels inter-island distribution for operators building archipelago-wide networks.
North Sumatra
Medan's ethnic Chinese and Korean expatriate corridors concentrate demand for Asian cuisine formats with cross-border ingredient flows from ASEAN trading partners. BPJPH processing queues extend compliance timelines for independent operators lacking centralized procurement systems. The city's position as Sumatra's western gateway shapes distribution economics for chains penetrating secondary metropolitan zones.
Indonesia Foodservice Market Competitive Environment
Listed leaders compete with private specialists across capital access and operational agility dimensions in Indonesia foodservice. PT Fast Food Indonesia Tbk and PT Sarimelati Kencana Tbk leverage public market funding to sustain nationwide kitchen standardization, while private operators deploy faster format experimentation. The market structures around three archetypes: franchise-heavy chains with centralized procurement, localized coffee specialists with regional taste adaptation, and diversified foodservice holding companies with portfolio breadth. Competitive moves concentrate on BPJPH compliance infrastructure and delivery platform integration rather than price-based rivalry.
Within the franchise-system tier, PT Fast Food Indonesia Tbk and PT Sarimelati Kencana Tbk occupy positions that exemplify centralized supply chain control, while Jiwa Group represents localized format specialists navigating Indonesia's diverse regional tastes. These three anchors illustrate how capital structure shapes strategic optionality under regulatory compression.
| Leading Market Players |
|---|
| PT Rekso Nasional Food |
| PT Map Boga Adiperkasa Tbk |
| PT Sarimelati Kencana Tbk |
| Inspire Brands, Inc. |
| PT JCO Donut & Coffee |
| Jiwa Group |
| Solaria Indonesia |
| PT Fast Food Indonesia Tbk |
| Restaurant Brands Asia Ltd |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty-day protein cold-chain lead times from Australian and New Zealand origins into Tanjung Priok Port concentrate purchasing power among quick-service chains with centralized procurement systems, compressing margin capture for independent operators lacking volume-scale negotiation leverage against import distributors.
Pricing Analysis
Volume-discount tiering structures separate national quick-service chains from regional independents and single-outlet operators across Indonesia's foodservice landscape. Price differentiation hinges on BPJPH halal certification grade and geographic delivery cost to outer-island provinces. Cost compression in the independent tier is intensifying because delivery-aggregator commission structures from Gojek and GrabFood displace direct-order margin retention. Corporate catering contracts in Jakarta's SCBD corridor exhibit least price sensitivity, while mobile food truck operators in secondary cities face acute margin pressure.
Supply Chain Analysis
Inventory cycles of seven to ten days for fresh protein inputs through Tanjung Priok Port anchor procurement scheduling for Greater Jakarta's quick-service density. Geographic supply concentration draws from Australia, New Zealand, and domestic Javanese poultry corridors. Raw material dependencies center on imported beef and dairy, domestic broiler chicken, and palm oil derivatives. Single-source vulnerability runs through Australia-New Zealand protein import lanes subject to shipping congestion. Distribution feeds from centralized kitchen nodes into last-mile delivery platform networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among delivery-aggregator platforms and corporate catering procurement committees, fragmenting price-setting autonomy for independent foodservice operators across Indonesia's metropolitan zones.
For Market Incumbents: Shield margin structures by deepening backward integration into captive poultry processing facilities in East Java and Central Java provinces. Accelerate BPJPH certification pipeline investments to preempt auditor shortage delays that threaten menu launch timelines. Prioritize direct-order channel development through proprietary mobile applications to reduce GrabFood and Gojek commission exposure. For New Entrants and Emerging Players: BPJPH certification fast-track through provincial agency relationships in South Sulawesi and North Sumatra opens whitespace corridors with lower competitive density than Java saturation. Target mobile food truck deployment in Makassar and Manado where permanent real estate costs exceed operator capital reserves. Pursue localized coffee format positioning that navigates Indonesia's diverse regional taste preferences without multinational franchise royalty burdens. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance-arbitrage play because BPJPH mandate enforcement timelines create acquisition windows for certified assets at distressed valuations. Target mid-scale quick-service operators with established halal supply chain protocols and Java-centric footprints. Monitor BPJPH auditor training program expansion rates as inflection indicator for certification backlog resolution and normalized compliance timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Centralized Kitchen Expansion | Standardized production nodes in Greater Jakarta absorb BPJPH segregation capex across volume throughput. |
| Halal Certification Fast-Track | Provincial BPJPH relationships compress supplier onboarding timelines for eastern Indonesia penetration. |
| Direct-Order Channel Development | Proprietary mobile applications defend margin retention against GrabFood and Gojek commission structures. |
| Backward Integration into Poultry | Captive processing facilities in East Java reduce import dependency and cold-chain cost exposure. |
| Mobile Food Truck Deployment | Lower capex entry points suit Makassar and Manado corridors with limited branded quick-service presence. |
Study Parameters
Cross-validation between executive interviews at quick-service franchise headquarters and Dinas Kesehatan licensing records anchors the qualitative findings. Primary fieldwork engaged supply chain directors at centralized kitchen operators, BPJPH certification consultants, procurement managers at institutional catering contractors, and platform partnership leads at delivery aggregators. Secondary validation drew from Ministry of Health sanitation regulation filings, BPJPH auditor deployment statistics, customs import records for protein and dairy, and provincial business licensing databases. Bottom-up outlet counting and top-down consumer expenditure estimates triangulate market sizing.
Sensitivity analysis around urban millennial population growth assumptions and BPJPH enforcement variance scenarios stress-tested projection outputs across the modeling period. Segmentation dimensions modeled include service format, end-user category, cuisine type, and distribution channel, with geographic cluster as the industry-specific overlay. CAGRs derive from trend extrapolation against base-year observed values, calibrated to documented quick-service outlet expansion rates and delivery platform transaction growth. Forecast inputs incorporate cold-chain infrastructure investment flows and provincial halal certification processing capacity.
Decision-makers should treat outputs as directional under assumptions of sustained BPJPH regulatory enforcement and continued delivery-aggregator platform penetration; material deviation in certification timeline resolution or macroeconomic consumption patterns would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Online Food Delivery Market
Food Service
Europe Vending Machine Market
Food Service
New Zealand Foodservice Market
Food Service
Mobile Food Services Market
Food Service
Commercial Bar Supplies Market
Food Service
Takeout Dinner Market
Food Service
Restaurant Takeout Market
Food Service
Instant Grocery Market
Food Service
Meal Kit Delivery Services Market
Food Service
Food & Beverage in Asia Market
Food Service
Commercial Beverage Dispenser Market
Food Service
GCC Food Service Market
Food Service
China Inflight Catering Market
Food Service
Bahrain Food Service Market
Food Service
Smokeless Grill Market
Food Service
South Korea Foodservice Market